
 Nesiritide Market | 2026-2036
Nesiritide Market Size, Share, and Industry Trends Forecast 2026-2036
Nesiritide Market Insights
Peptide synthesis capacity in Switzerland and China is hardening as specialized manufacturers scale recombinant production lines. Bachem leverages its long-standing peptide chemistry expertise to sustain supply of active pharmaceutical ingredients for cardiovascular therapies. Chengdu Kaijie Peptide anchors regional production with dedicated facilities serving domestic and export markets. BCN Peptides differentiates through European Union manufacturing standards and controlled-temperature logistics networks.
Nesiritide constitutes a recombinant human B-type natriuretic peptide (hBNP) produced through Escherichia coli fermentation, formulated for intravenous administration to patients with acutely decompensated heart failure requiring vasodilation and diuresis. Recombinant Nesiritide dominates value generation due to patent-protected manufacturing processes and stringent purity requirements exceeding 98% peptide content. Injectable Nesiritide captures the majority of hospital procurement volumes, while Lyophilized Nesiritide extends shelf stability for emergency department stockpiling. Cardiology Clinics represent the fastest-growing end-user channel as outpatient infusion protocols expand beyond traditional hospital settings.
FDA biologics licensing requirements and EMA centralized marketing authorization procedures govern manufacturing quality, clinical evidence standards, and post-market surveillance obligations for nesiritide suppliers. The European Pharmacopoeia monograph for recombinant peptides and United States Pharmacopeia Chapter 1055 define potency assays and endotoxin limits that directly determine batch release timelines. Stakeholders must monitor evolving biosimilar guidance from FDA and EMA, as abbreviated pathways for generic Nesiritide could restructure competitive dynamics without warning.
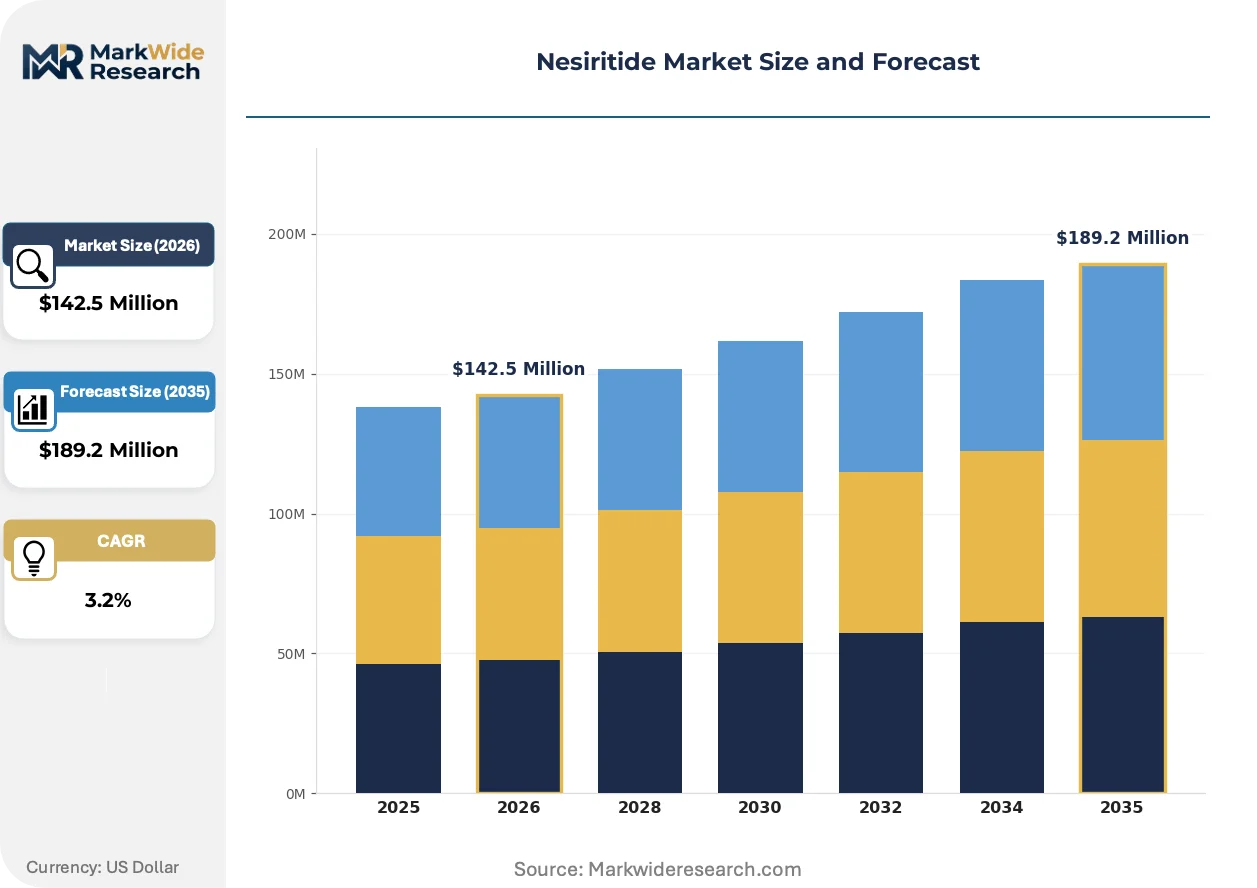
Market Dynamics
Recombinant peptide manufacturing concentration in Swiss and Chinese contract development organizations is compressing supply timelines while FDA biologics licensing requirements extend approval durations for new entrants.
Growth Catalysts
- Acute heart failure hospitalization protocols:Emergency departments in the United States, Germany, and Japan have standardized intravenous vasodilator therapy, creating institutional demand pull for recombinant B-type natriuretic peptide formulations.
- EMA centralized marketing authorization:Harmonized European manufacturing standards enable batch release reciprocity across member states, reducing regulatory friction for multi-country distribution.
- Escherichia coli fermentation yield improvements:Advances in recombinant protein expression systems have lowered per-gram production costs while maintaining the 98% purity threshold required for pharmaceutical-grade peptide.
Market Restraints
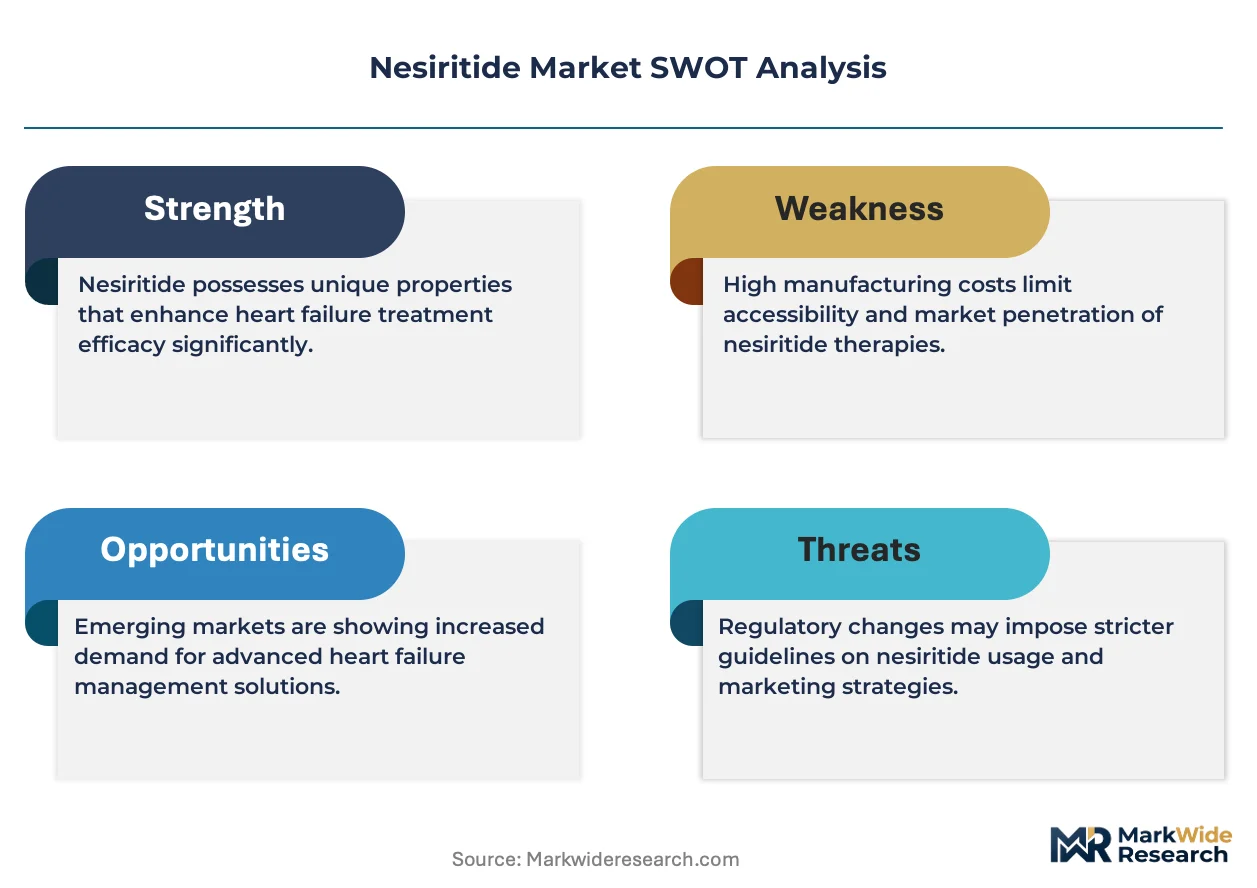
- Single-source API concentration:Active pharmaceutical ingredient synthesis clusters in Basel, Switzerland and Chengdu, China expose the supply base to regional logistics disruptions and geopolitical friction.
- Endotoxin testing bottlenecks:United States Pharmacopeia Chapter 1055 potency assay requirements add 4-6 weeks to batch release timelines, constraining working capital efficiency.
- Natriuretic peptide analog competition:Synthetic BNP mimetics and small-molecule vasodilators threaten therapeutic substitution in cost-sensitive hospital formularies.
Strategic Opportunities
- Outpatient cardiology clinic expansion:Ambulatory infusion centers in Florida, Texas, and California are piloting same-day discharge protocols for stabilized acute heart failure patients.
- Lyophilized formulation shelf-life extension:Freeze-dried peptide vials enable rural hospital stockpiling without cold-chain dependency, opening access in secondary care networks.
- Japanese PMDA orphan drug designation pathway:Expedited review timelines for refractory heart failure indications could accelerate market entry for refined dosing regimens.
Industry Challenges
- Peptide chemist talent scarcity:Recombinant protein purification and analytical method development expertise concentrates in Basel and Boston biotech clusters, limiting manufacturing scale-up capacity elsewhere.
- Biosimilar guidance uncertainty:FDA and EMA have not issued definitive abbreviated approval frameworks for generic nesiritide, freezing investment in follow-on biologic development programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nesiritide Market |
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $189.2 Million |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant Nesiritide, Generic Nesiritide, Injectable Nesiritide, Lyophilized Nesiritide End User: Hospitals, Cardiology Clinics, Emergency Departments, Rehabilitation Centers Administration Route: Intravenous, Subcutaneous, Inhalation, Infusion Packaging Type: Vials, Prefilled Syringes, Ampoules, Blister Packs |
| Companies Covered | Bachem, BCN Peptides, Chengdu Kaijie Peptide, China Medical System, Harbin Jixianglong Biotech, Hybio Pharmaceutical, LeapChem, Suzhou Tianma Pharma, Xiamen Bam Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nesiritide Market Trends and Innovations
Continuous manufacturing technologies and real-time release testing are compressing production cycles while regulatory agencies tighten post-market surveillance for biologic cardiac therapies.
Continuous bioprocessing is converging with single-use fermentation systems to eliminate batch-to-batch variability in recombinant peptide production. Large-scale CDMOs in Switzerland are retrofitting stainless-steel trains with perfusion bioreactors. This convergence is enabling real-time quality monitoring that reduces downstream purification bottlenecks.
EMA's Medical Device Regulation (MDR) companion diagnostic requirements are forcing co-development of biomarker assays for patient selection in nesiritide therapy. Cardiovascular device manufacturers must now synchronize PMA submissions with drug approval timelines. European hospital procurement committees are demanding integrated diagnostic-therapeutic bundles before adding new biologics to formularies.
Hospital buying consortia in the United States are consolidating pharmaceutical purchasing through group purchasing organizations, displacing traditional distributor relationships. Integrated delivery networks in Pennsylvania, Ohio, and Illinois now contract directly with peptide API manufacturers for multi-year supply agreements. This concentration is most visible in Medicare-dependent health systems seeking to cap episode-based reimbursement costs for heart failure readmissions.
Nesiritide Market Segmentation
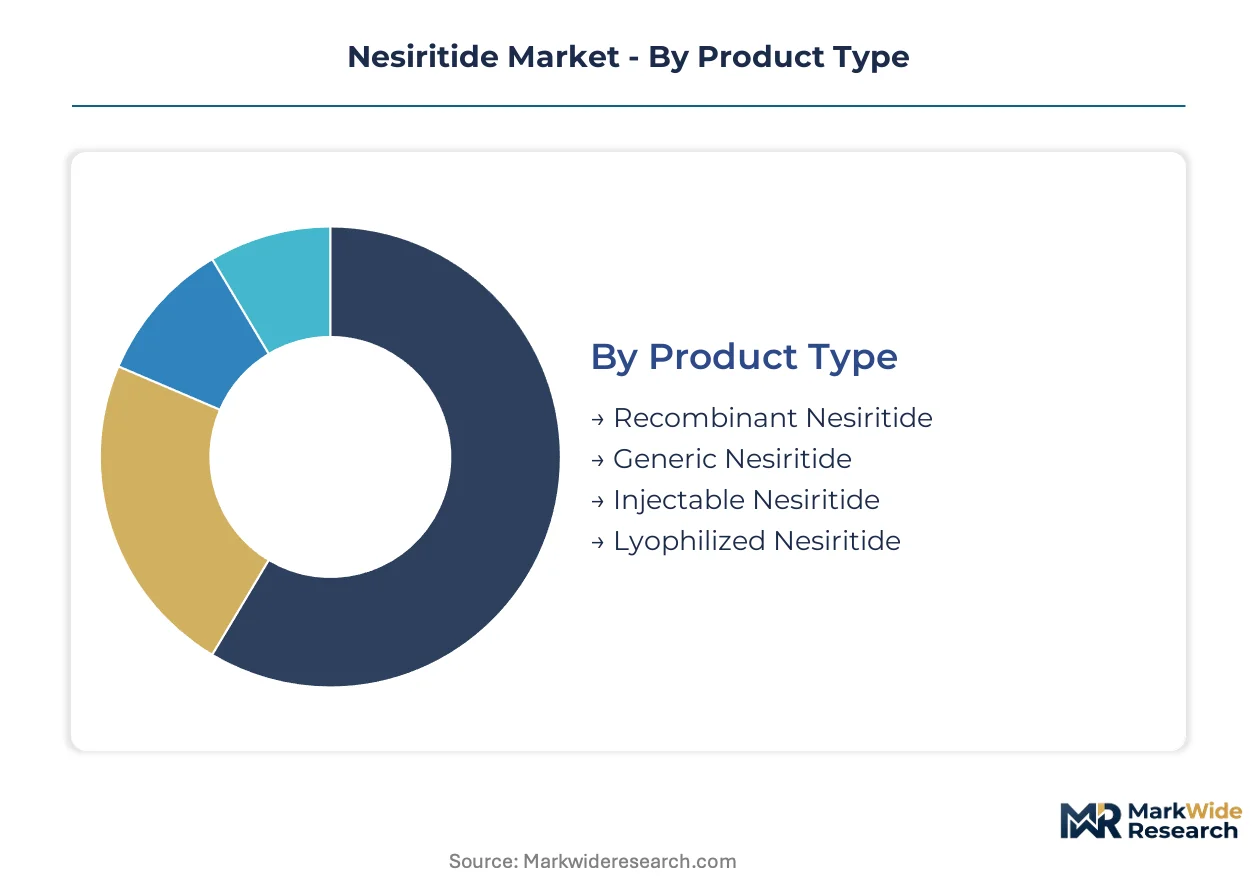
Hospital procurement committees evaluate nesiritide formulations through multiple technical dimensions. Product chemistry, administration logistics, and packaging integrity each determine formulary placement and reimbursement pathways for acute heart failure therapy.
Product Type:
Upgrade cycles in peptide manufacturing favor recombinant platforms over synthetic alternatives, with purity thresholds and patent status driving procurement decisions across acute care networks.
- Recombinant Nesiritide:Produced via Escherichia coli fermentation, this formulation achieves pharmaceutical-grade peptide content exceeding 98% purity. United States hospital systems prioritize recombinant sourcing for FDA biologics licensing compliance, particularly in Medicare-dependent integrated delivery networks seeking to standardize vasodilator therapy protocols.
- Injectable Nesiritide:Ready-to-use liquid formulations dominate emergency department procurement volumes due to elimination of reconstitution steps. German university hospitals favor injectable presentations for rapid deployment in acute decompensated heart failure protocols.
- Generic Nesiritide:Follow-on biologic candidates await definitive FDA and EMA abbreviated approval frameworks. The segment remains speculative pending regulatory clarity on biosimilar interchangeability standards.
- Lyophilized Nesiritide:Freeze-dried peptide extends shelf stability for rural hospital stockpiling without cold-chain dependency.
Volume placements concentrate in Injectable Nesiritide; the faster expansion belongs to Lyophilized Nesiritide.
End User:
Cost tier stratification separates high-acuity inpatient settings from emerging ambulatory channels, with reimbursement intensity declining across the care continuum.
- Hospitals:Tertiary cardiac centers in the United States, Germany, and Japan anchor institutional demand through standardized intravenous vasodilator protocols. Medicare episode-based reimbursement penalties for heart failure readmissions reinforce hospital investment in nesiritide formularies.
- Cardiology Clinics:Ambulatory infusion centers in Florida, Texas, and California pilot same-day discharge protocols for stabilized patients. Outpatient administration protocols are gaining share fastest as integrated delivery networks seek to decant inpatient volume.
- Emergency Departments:Urban academic medical centers deploy nesiritide within acute decompensated heart failure order sets.
- Rehabilitation Centers:Post-acute facilities utilize extended infusion protocols for hemodynamic stabilization prior to discharge.
Procurement volume clusters in Hospitals; Cardiology Clinics are climbing the fastest.
Administration Route:
Patient acuity and pharmacokinetic requirements dictate route selection, with intravenous delivery commanding premium positioning in acute settings.
- Intravenous:Direct venous administration enables precise titration of vasodilator effect in hemodynamically unstable patients. Japanese emergency medicine protocols specify intravenous nesiritide for acute pulmonary edema with systolic hypertension.
- Infusion:Continuous pump delivery supports extended hemodynamic monitoring in coronary care units. Swiss cardiology wards favor infusion protocols for refractory heart failure requiring sustained diuresis.
- Subcutaneous:Investigational routes target outpatient chronic heart failure management.
- Inhalation:Pulmonary delivery mechanisms remain preclinical for natriuretic peptide therapy.
Clinical utilization concentrates in Intravenous administration; Infusion protocols are expanding most quickly.
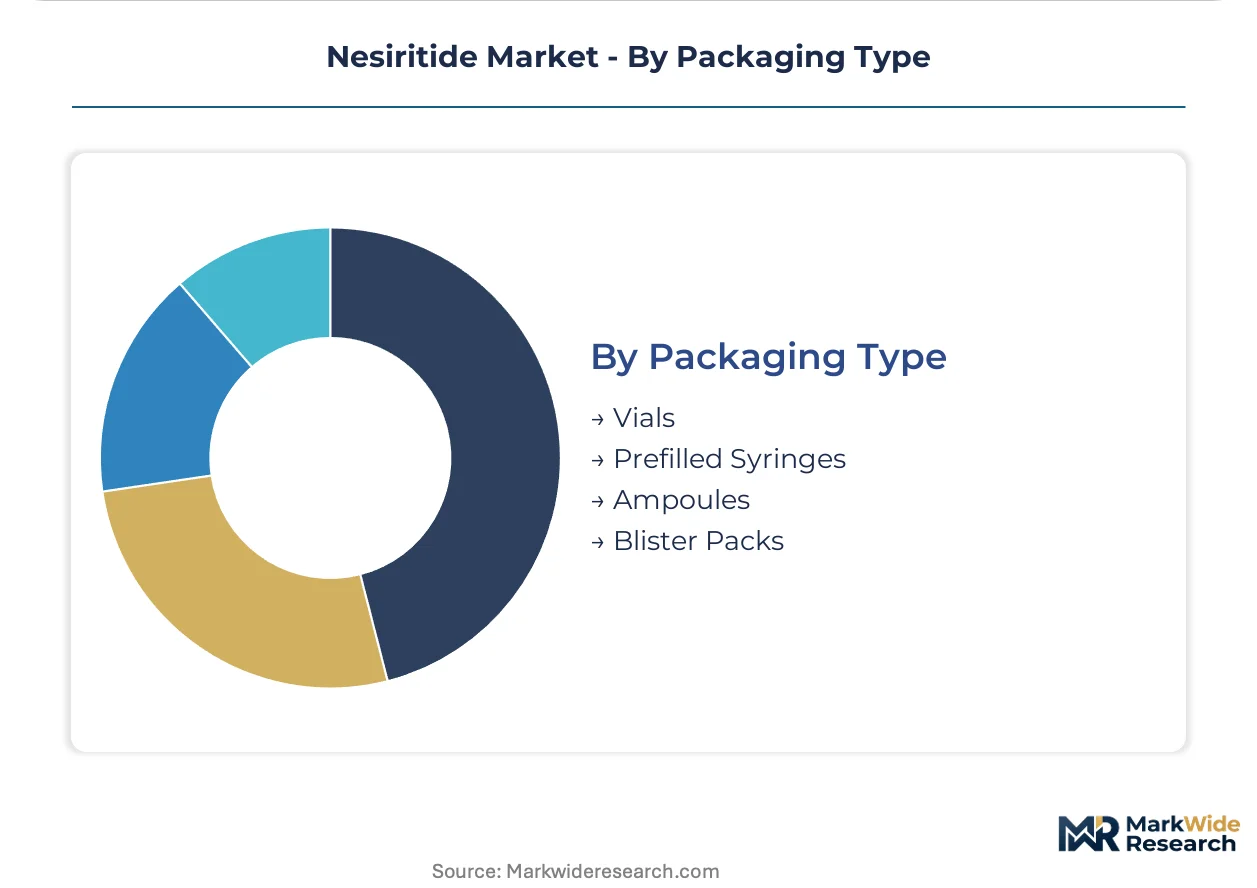
Packaging Type:
Supply chain resilience and point-of-care workflow efficiency drive packaging selection, with unit-dose presentations gaining preference in infection-control-conscious environments.
- Vials:Multi-dose glass containers serve high-volume hospital pharmacy compounding operations. Chengdu-based API manufacturers supply bulk peptide for vial filling across Asia-Pacific markets.
- Prefilled Syringes:Ready-to-administer units reduce medication error risk in emergency settings. German hospital buying consortia specify prefilled presentations for anesthesia and critical care formularies.
- Ampoules:Single-use glass containers support aseptic technique in resource-limited settings.
- Blister Packs:Unit-dose packaging enables automated dispensing cabinet integration.
Procurement volume centers on Vials; Prefilled Syringes are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peptide synthesis capacity clusters in Basel and Chengdu anchor supply-side geography for recombinant B-type natriuretic peptide production. Hospital procurement patterns diverge across acute care networks based on regulatory pathway maturity and cardiovascular infrastructure density.
United States
Medicare episode-based reimbursement penalties for heart failure readmissions drive hospital formulary investment in intravenous vasodilator protocols. FDA biologics licensing requirements govern manufacturing quality and post-market surveillance for recombinant peptide therapies. Integrated delivery networks in Pennsylvania, Ohio, and Illinois contract directly with API manufacturers for multi-year supply agreements.
Germany
University hospitals favor ready-to-use injectable presentations for rapid deployment in acute decompensated heart failure order sets. EMA centralized marketing authorization enables batch release reciprocity across member states, reducing regulatory friction for multi-country distribution. The Rhine-Main and Bavarian hospital consortia standardize procurement through group purchasing organizations.
Switzerland
Specialized contract development organizations concentrate recombinant protein expression expertise in the Basel biotech cluster. Swissmedic manufacturing standards and European Pharmacopoeia monographs define potency assays and endotoxin limits for peptide batch release. Bachem leverages long-standing peptide chemistry expertise to sustain active pharmaceutical ingredient supply for cardiovascular therapies.
Japan
Emergency medicine protocols specify intravenous nesiritide for acute pulmonary edema with systolic hypertension in tertiary cardiac centers. PMDA orphan drug designation pathways offer expedited review timelines for refractory heart failure indications. The Kanto and Kansai regions host advanced cardiovascular care infrastructure supporting intravenous administration.
China
Domestic peptide manufacturers scale dedicated facilities serving hospital pharmacy compounding operations across Asia-Pacific markets. NMPA biologics registration requirements shape approval timelines for recombinant peptide therapies. Chengdu anchors regional production with fermentation-based active pharmaceutical ingredient synthesis for export and domestic consumption.
Nesiritide Market Competitive Landscape
Global majors compete with regional champions across recombinant peptide synthesis capacity and cardiovascular therapy supply contracts. The vendor base stratifies between Swiss precision manufacturers, Chinese scale producers, and diversified pharmaceutical conglomerates. Three archetypes dominate: specialized peptide CDMOs with fermentation expertise, integrated API-to-finished-dose suppliers, and hospital-focused distribution platforms. Capacity expansion and strategic partnerships constitute the primary competitive moves as firms secure multi-year supply agreements with integrated delivery networks.
Within the specialized peptide synthesis tier, Bachem exemplifies European manufacturing standards and controlled-temperature logistics networks. Chengdu Kaijie Peptide occupies a position among Chinese scale producers with dedicated facilities serving domestic and export markets. BCN Peptides anchors the mid-tier segment with European Union manufacturing compliance and regional distribution reach.
| Leading Market Players |
|---|
| Bachem |
| BCN Peptides |
| Chengdu Kaijie Peptide |
| China Medical System |
| Harbin Jixianglong Biotech |
| Hybio Pharmaceutical |
| LeapChem |
| Suzhou Tianma Pharma |
| Xiamen Bam Biotech |
| Others |
Pricing and Supply Chain Analysis
Captive fermentation capacity in Basel and Chengdu anchors both supply security and pricing power for recombinant peptide manufacturers serving cardiovascular therapy markets. Swiss CDMOs leverage in-house Escherichia coli expression systems to command premium positioning, while Chinese scale producers compete on batch economics for hospital procurement tenders.
Pricing Analysis
Extended stability warranties and cold-chain integrity guarantees are bundled into premium nesiritide contracts for tertiary cardiac centers, while standard formulations ship without temperature-monitoring services. Three-tier pricing structure across premium, standard, and economy levels reflects endotoxin certification grades and FDA biologics licensing status. Cost compression in the economy tier is intensifying because hospital buying consortia are consolidating pharmaceutical purchasing through multi-year supply agreements. Medicare-dependent integrated delivery networks exhibit highest price sensitivity; Japanese tertiary cardiac centers show lowest sensitivity due to PMDA orphan drug reimbursement pathways.
Supply Chain Analysis
Batch recall and temperature excursion protocols define reverse-logistics requirements for recombinant peptide distribution, with Swissmedic and FDA pharmacovigilance systems mandating documented chain-of-custody records. Active pharmaceutical ingredient synthesis clusters in Switzerland, China, and the United States, with fermentation media and chromatography resins as critical inputs. Single-source vulnerability concentrates in Basel-based purification expertise and Chengdu fermentation capacity. Distribution runs through hospital buying consortia and group purchasing organizations that displace traditional wholesale relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into peptide fermentation and downstream purification capabilities is becoming the decisive competitive race, as manufacturers seek captive control over the 98% purity threshold that determines formulary placement.
For Market Incumbents: Hedge against biosimilar entry by locking multi-year supply agreements with integrated delivery networks in Pennsylvania, Ohio, and Illinois before FDA issues definitive abbreviated approval frameworks. Secure captive fermentation capacity in Basel or Chengdu to insulate against API supply disruptions. Invest in real-time release testing capabilities to compress batch release timelines constrained by United States Pharmacopeia Chapter 1055 potency assays. For New Entrants and Emerging Players: The premium-to-economy price gap in outpatient cardiology clinics offers fertile ground for lyophilized formulation specialists targeting ambulatory infusion centers in Florida, Texas, and California. Same-day discharge protocols for stabilized acute heart failure patients represent the most penetrable application segment. Pursue Japanese PMDA orphan drug designation pathway to accelerate market entry with expedited review timelines for refractory heart failure indications. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified pharmaceutical conglomerates seeking cardiovascular therapy portfolios, with Swiss precision manufacturers and Chinese scale producers as primary target archetypes. Long-term viability hinges on regulatory clarity for biosimilar interchangeability standards. Monitor FDA and EMA guidance publication timelines as the critical inflection indicator for follow-on biologic investment decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Perfusion bioreactor retrofitting in Basel CDMOs reduces downstream purification bottlenecks for hospital procurement. |
| Regulatory Approval Pathway | PMDA orphan drug designation accelerates review timelines for refractory heart failure dosing regimens in Japanese tertiary centers. |
| Long-term Supply Agreement | Multi-year contracts with Medicare-dependent health systems cap episode-based reimbursement costs for heart failure readmissions. |
| Pipeline Diversification | Lyophilized formulation development opens rural hospital access without cold-chain dependency. |
| Hospital System Partnership | Integrated diagnostic-therapeutic bundles satisfy European procurement committee demands under EMA MDR requirements. |
Research Methodology
FDA biologics licensing files, EMA centralized marketing authorization submissions, and ClinicalTrials.gov records formed the secondary backbone for supply-side and regulatory validation. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors at integrated delivery networks were cross-referenced against secondary sources. Bottom-up and top-down triangulation reconciled manufacturer production disclosures with hospital purchasing data.
Bottom-up modeling anchored volume and value outputs across the projection horizon. Segmentation dimensions included product chemistry, administration route, end-user channel, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to manufacturer capacity expansion announcements and hospital formulary adoption rates. Forecast inputs incorporated Medicare episode-based reimbursement penalty structures and EMA Medical Device Regulation companion diagnostic requirements.
Inputs from FDA and EMA regulatory filings were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around volume estimates. Forecasts reflect assumptions regarding biosimilar guidance timelines and peptide chemist talent availability in Basel and Boston clusters. Practitioners should monitor FDA abbreviated approval framework publication and Swissmedic manufacturing standard revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
Global Parkinson's Disease Drugs Market
Pharmaceuticals
Drug Delivery Market
Pharmaceuticals
Ebola Drug and Vaccine Market
Pharmaceuticals
Nucleic Acid Therapeutics Contract Development and Manufacturing Organization Market
Pharmaceuticals
Global Fondaparinux Market
Pharmaceuticals
Vaginal Ring Market
Pharmaceuticals
Obsessive Compulsive Disorder (OCD) Drug Market
Pharmaceuticals
Iceland Pharmaceutical Market
Pharmaceuticals
Dermatitis Drugs Market
Pharmaceuticals
Global Monoclonal Antibody Therapeutics Market
Pharmaceuticals
Global Desmopressin Market
Pharmaceuticals
Long-Acting Insulin Market
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
Ophthalmic Drugs Market
Pharmaceuticals
Respiratory Virus Infection Drug Market