
 Global Anti-Fungal Drugs Market | 2026-2036
Global Anti-Fungal Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Fungal Drugs Market Foresight
The EU Green Deal's pharmaceutical sustainability criteria is broadening procurement mandates across European hospital networks. Pfizer Inc. leverages its manufacturing scale to supply azole and echinocandin portfolios across multiple continents. Gilead Sciences, Inc. specializes in lipid-complex amphotericin formulations for severe invasive infections. Merck & Co., Inc. anchors hospital formulary contracts through its intravenous antifungal franchise.
Anti-fungal drugs comprise synthetic and natural compounds that inhibit ergosterol biosynthesis, disrupt fungal cell membrane integrity, or interfere with cell wall glucan synthesis at minimum inhibitory concentrations typically below 1 μg/mL for susceptible pathogens. These agents serve primarily to treat invasive candidiasis, aspergillosis, and dermatophyte infections in immunocompromised and transplant patient populations. Azoles retain the largest volume share due to generic fluconazole availability and prophylactic use in oncology wards. Echinocandins represent the fastest-expanding margin pool as first-line therapy for invasive candidiasis displaces polyenes in ICU protocols. The intravenous delivery mode commands premium pricing in hospital settings where bioavailability and therapeutic drug monitoring dictate outcomes.
The FDA's Qualified Infectious Disease Product program and EMA's adaptive pathways framework shape clinical trial design and accelerated review timelines for novel antifungal classes. WHO's fungal priority pathogens list concentrates R&D investment toward resistant Candida auris and Aspergillus fumigatus strains. Stakeholders must monitor regulatory divergence between the FDA's narrow-spectrum approval standards and EMA's broader combination-therapy endpoints as this determines portfolio prioritization for late-stage candidates.
Market Dynamics
Hospital formulary committees are consolidating procurement around intravenous echinocandins as first-line therapy for invasive candidiasis, compressing polyene utilization and reshaping manufacturer contracting structures across tertiary care networks.
Growth Catalysts
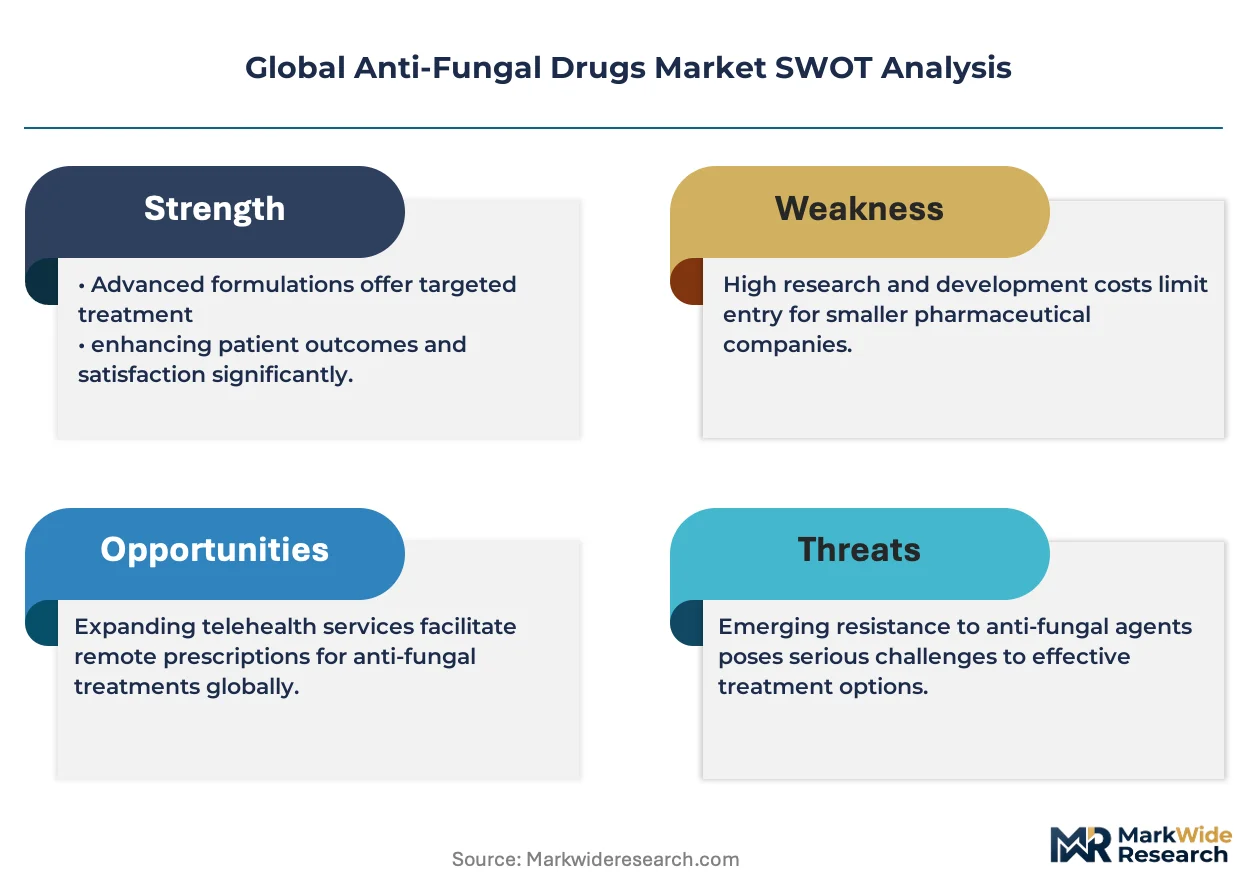
- FDA Qualified Infectious Disease Product designation:The program accelerates clinical trial timelines and extends market exclusivity for novel antifungal classes targeting resistant Candida auris strains.
- Immunocompromised patient expansion:Oncology and transplant ward censuses in the United States, India, and Germany drive prophylactic azole consumption and therapeutic drug monitoring protocols.
- IV-to-oral step-down protocols:Bioavailability improvements in next-generation triazoles enable earlier hospital discharge, reducing length-of-stay costs and expanding outpatient antifungal markets.
Market Restraints
- Active pharmaceutical ingredient concentration:Azole synthesis depends on Chinese and Indian bulk chemical suppliers, exposing formulators to price volatility and import tariff friction.
- Narrow-spectrum approval standards:FDA requirements for pathogen-specific endpoints limit label expansion opportunities and fragment addressable patient populations for novel agents.
- Generic fluconazole commoditization:Prophylactic volume pools face margin compression as hospital group purchasing organizations consolidate contracts around low-cost azole suppliers.
Strategic Opportunities
- Combination therapy endpoints:EMA's adaptive pathways framework permits broader approval criteria for azole-echinocandin regimens, opening differentiated positioning in European hospital networks.
- Therapeutic drug monitoring services:Integrated pharmacokinetic platforms create recurring revenue streams alongside voriconazole and posaconazole prescriptions in transplant centers.
- India's CDSCO fast-track pathway:Local manufacturing incentives and abbreviated review timelines attract investment in generic echinocandin production for domestic and export markets.
Industry Challenges
- Specialized mycology expertise scarcity:Clinical microbiology laboratories lack trained personnel for antifungal susceptibility testing, delaying appropriate therapy selection in community hospitals.
- Legacy IV infrastructure retrofitting:Echinocandin administration requires dedicated infusion lines and pharmacy compounding protocols that strain resource-constrained facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Fungal Drugs Market |
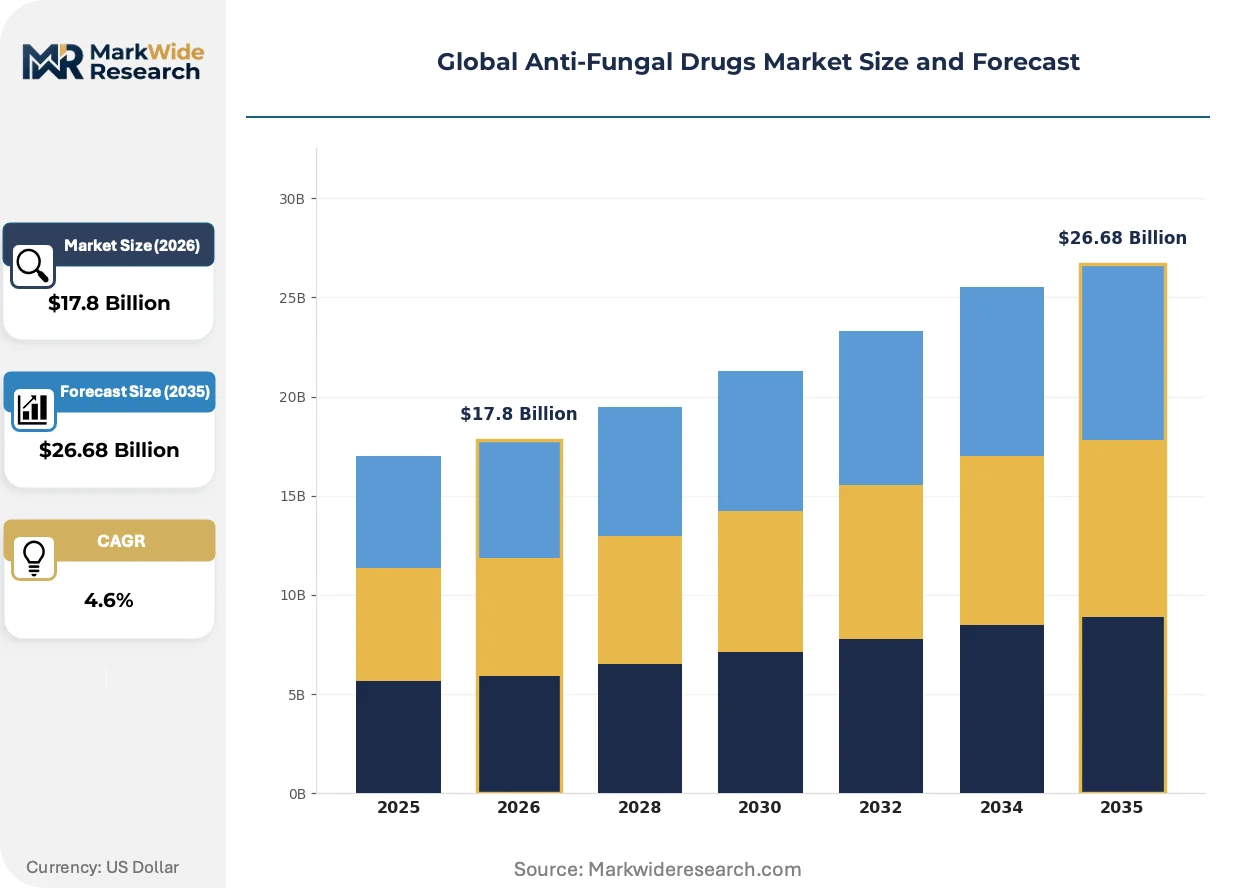
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Azoles, Echinocandins, Polyenes, Allylamines, Others Application: Invasive Infections, Superficial Infections, Systemic Infections, Opportunistic Infections End User: Hospitals, Clinics, Diagnostic Laboratories, Home Care Settings, Ambulatory Surgical Centers Delivery Mode: Oral, Topical, Intravenous, Intramuscular, Subcutaneous |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Novartis AG, GSK plc, Astellas Pharma Inc., Bayer AG, Sanofi, Gilead Sciences, Inc., Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Fungal Drugs Market Shifts & Advancements
Antifungal development is pivoting toward resistance-breaking mechanisms and delivery innovations that address the limitations of existing azole and polyene platforms in immunocompromised populations.
Liposomal amphotericin B formulations are overtaking conventional deoxycholate preparations in ICU protocols due to reduced nephrotoxicity profiles. Transplant centers in Germany and the United States have adopted liposomal products as standard of care for invasive aspergillosis, compressing polyene market share and elevating pricing power for manufacturers with complex formulation capabilities.
The EU Green Deal's pharmaceutical sustainability criteria mandate carbon footprint disclosure and waste reduction targets across European hospital supply chains. Procurement departments in France, Germany, and the Netherlands now embed environmental impact scoring alongside clinical efficacy in tender evaluations, favoring manufacturers with closed-loop manufacturing and reduced solvent utilization in API synthesis.
Hospital purchasing consortia are consolidating antifungal contracts under single-source agreements with price-volume guarantees and therapeutic interchange protocols. Group purchasing organizations in the United States negotiate multi-year echinocandin commitments that lock formulary access and displace competing agents, concentrating volume with established intravenous franchise holders and raising barriers for novel market entrants.
Global Anti-Fungal Drugs Market Segmentation
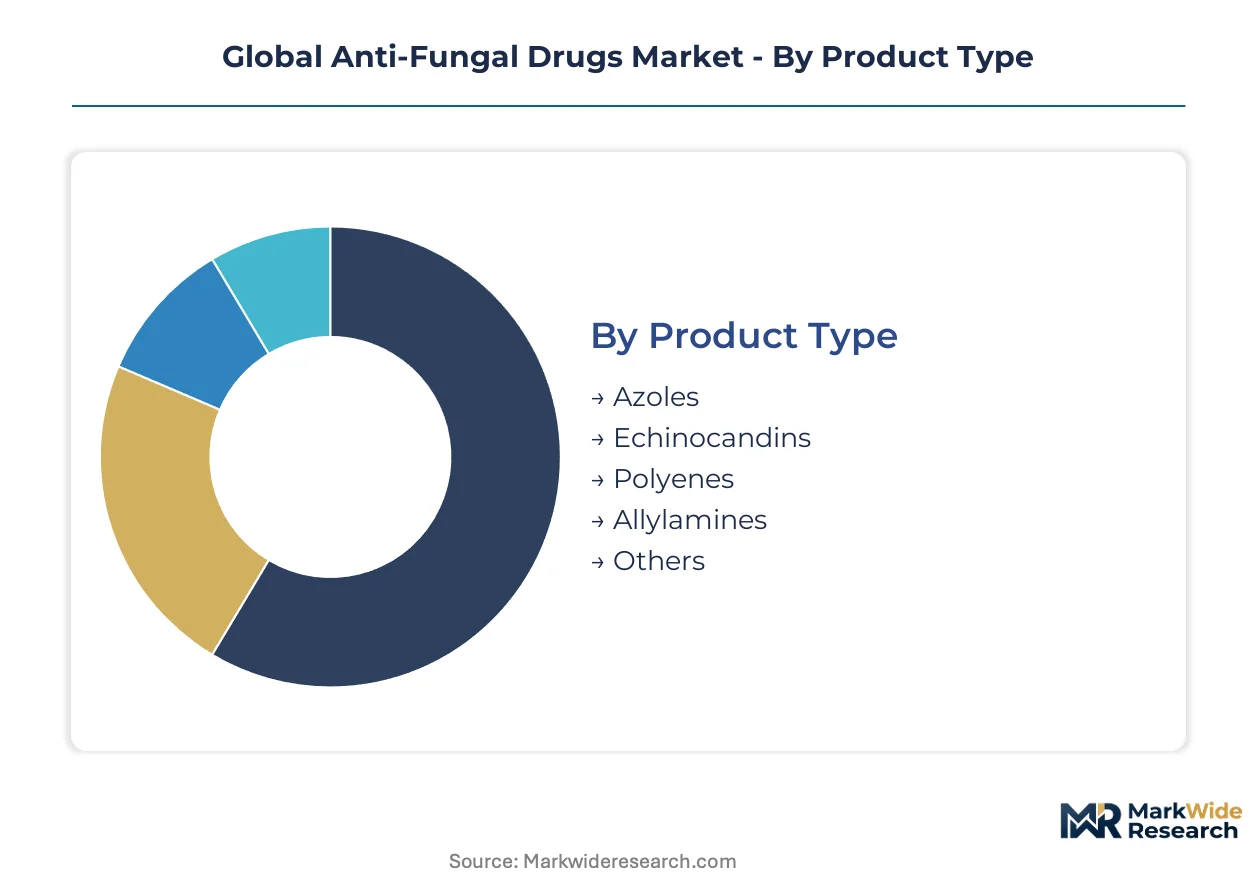
Antifungal market segmentation reveals distinct capital requirements, clinical workflows, and procurement patterns across therapeutic classes and care settings. Manufacturers align R&D portfolios and manufacturing investments to capture volume concentration in hospital-based intravenous therapies while addressing outpatient oral expansion.
Product Type:
Echinocandins demand the heaviest upfront capital commitment due to complex fermentation-based manufacturing and sterile lyophilization infrastructure, while azole chemistry offers lower barriers to generic entry.
- Echinocandins:Cyclic lipopeptides synthesized through fungal fermentation require dedicated bioreactor capacity and aseptic processing suites. Demand concentrates in United States and German ICU wards where invasive candidiasis protocols mandate first-line echinocandin therapy, supported by FDA Qualified Infectious Disease Product exclusivity incentives for novel agents.
- Azoles:Synthetic triazoles and imidazoles inhibit ergosterol biosynthesis through cytochrome P450-dependent lanosterol demethylation. Volume pools in Indian and United States oncology wards drive prophylactic fluconazole consumption, though generic commoditization compresses margins and consolidates procurement around high-volume suppliers.
- Polyenes:Macrolide antibiotics derived from Streptomyces species disrupt membrane integrity through ergosterol binding. Nephrotoxicity limitations restrict use to salvage therapy in resource-constrained settings.
- Allylamines:Squalene epoxidase inhibitors target dermatophyte infections with oral terbinafine dominating onychomycosis treatment in outpatient settings.
- Others:Pyrimidine analogs and morpholine derivatives occupy niche indications with limited manufacturing scale.
Most installed capacity flows through Azoles. Expansion is steepest in Echinocandins.
Application:
Clinical severity and reimbursement intensity separate segments, with invasive infections commanding premium pricing and therapeutic drug monitoring requirements that superficial infections cannot match.
- Invasive Infections:Bloodstream and deep-seated tissue infections in immunocompromised hosts require prolonged intravenous therapy with mortality-driven formulary prioritization. United States transplant centers and German hematology wards concentrate demand, with outcomes dictating procurement decisions above cost considerations.
- Opportunistic Infections:Pathogen emergence in HIV/AIDS and oncology populations creates prophylactic and preemptive treatment protocols. Indian public health programs and United States hospital systems drive volume through standardized guidelines for Pneumocystis and endemic mycoses prevention.
- Superficial Infections:Dermatophyte and yeast infections of skin, hair, and nails generate high prescription volumes with minimal monitoring requirements.
- Systemic Infections:Disseminated disease across multiple organ systems bridges inpatient and outpatient management with step-down oral therapy protocols.
Revenue concentrates in Invasive Infections. Volume expansion is broadest in Opportunistic Infections.
End User:
Procurement sophistication and reimbursement mechanisms create tiered access patterns, with tertiary hospitals capturing novel therapies and home settings absorbing step-down oral conversions.
- Hospitals:Tertiary care networks with oncology, transplant, and ICU services command intravenous echinocandin and liposomal amphotericin volumes through formulary contracts. Group purchasing organizations in the United States and hospital consortia in Germany consolidate procurement around multi-year agreements with therapeutic interchange clauses.
- Home Care Settings:Oral azole step-down therapy and patient-administered posaconazole suspension enable early discharge from United States and German transplant wards, creating recurring prescription flows outside institutional reimbursement.
- Clinics:Outpatient parenteral therapy programs and infusion centers bridge hospital and home care with intermediate supervision.
- Diagnostic Laboratories:Reference mycology services support susceptibility testing and pathogen identification, though trained personnel scarcity limits expansion.
- Ambulatory Surgical Centers:Prophylactic antifungal use in procedural settings generates limited but predictable volume.
Pricing power clusters in Hospitals. Patient volume is shifting fastest toward Home Care Settings.
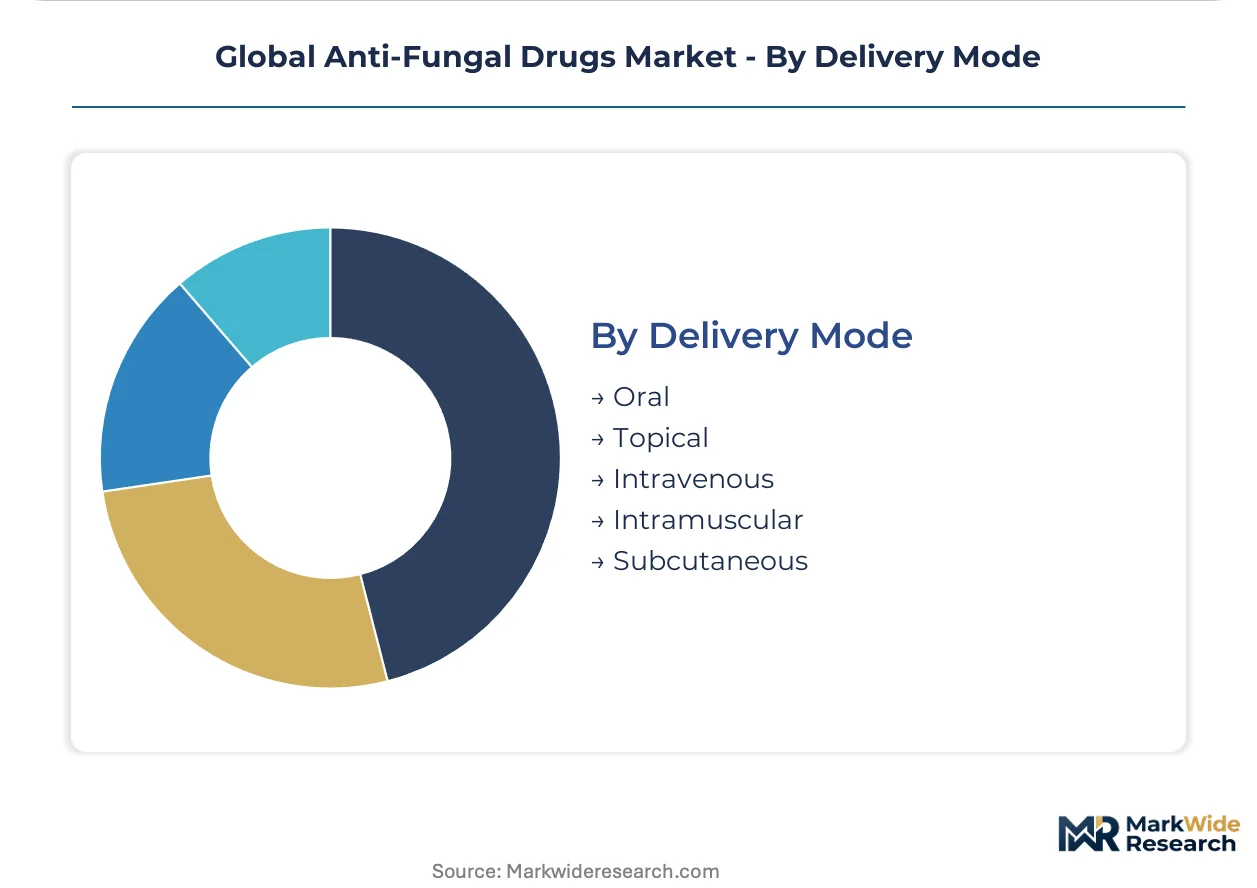
Delivery Mode:
Route selection determines manufacturing complexity, with intravenous formulations requiring sterile fill-finish capacity that oral solid dose facilities cannot replicate.
- Intravenous:Parenteral echinocandins and liposomal polyenes demand dedicated infusion lines, pharmacy compounding protocols, and therapeutic drug monitoring infrastructure. United States and German ICU adoption drives premium pricing, with bioavailability advantages justifying cost in critically ill populations.
- Oral:Tablet and suspension formulations enable outpatient conversion and prophylaxis continuation, with next-generation triazoles improving bioavailability to support earlier hospital discharge in United States oncology wards.
- Topical:Cream, gel, and shampoo formulations target superficial dermatophyte infections with minimal regulatory burden and commoditized pricing.
- Intramuscular:Limited application for depot formulations in specific endemic mycoses protocols.
- Subcutaneous:Emerging delivery route for investigational agents with pharmacokinetic advantages in outpatient settings.
Value capture concentrates in Intravenous. Growth is most rapid in Oral formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Systemic antifungal therapy originated in mid-20th century European pharmaceutical laboratories, with German and Swiss research institutions pioneering polyene chemistry before American biotechnology firms scaled echinocandin fermentation processes. Today, procurement patterns concentrate in tertiary hospital networks across five major pharmaceutical markets.
United States
Oncology and transplant ward censuses at Cleveland Clinic and MD Anderson drive intravenous echinocandin consumption. FDA Qualified Infectious Disease Product designation accelerates novel agent review timelines. Hospital purchasing consortia in the Northeast and Texas consolidate formulary contracts around multi-year volume commitments.
Germany
Hematology departments at Charité Berlin and University Hospital Heidelberg anchor liposomal amphotericin utilization for invasive aspergillosis. EU Green Deal pharmaceutical sustainability criteria mandate carbon footprint disclosure in tender evaluations. The Rhine-Main cluster concentrates sterile manufacturing capacity for parenteral antifungal formulations.
India
Public health programs for HIV/AIDS opportunistic infections generate high-volume fluconazole prophylaxis demand. CDSCO fast-track pathways attract investment in generic echinocandin production. Hyderabad and Ahmedabad host active pharmaceutical ingredient synthesis clusters serving domestic oncology wards and export markets.
Japan
Aging immunocompromised populations in Tokyo and Osaka metropolitan areas sustain therapeutic drug monitoring protocols for voriconazole. PMDA adaptive review frameworks accommodate combination therapy endpoints. The Kanto region concentrates hospital pharmacy compounding infrastructure for intravenous antifungal administration.
Switzerland
Basel-based pharmaceutical research centers anchor antifungal drug discovery pipelines targeting resistant Candida auris strains. Swissmedic maintains alignment with EMA approval standards while offering streamlined review for orphan indications. The Lake Geneva corridor hosts contract manufacturing organizations specializing in sterile lyophilization.
Global Anti-Fungal Drugs Market Competitive Landscape
Capital-heavy fermentation-based producers compete with asset-light formulation specialists for hospital formulary access. The market structure consolidates around three tiers: integrated pharmaceutical conglomerates with sterile manufacturing infrastructure, mid-size biotechnology firms with lipid-complex expertise, and generic manufacturers competing on azole commoditization. Strategic archetypes include echinocandin franchise holders, liposomal formulation innovators, and high-volume azole suppliers. Competitive dynamics center on hospital group purchasing organization contract consolidation and manufacturing capacity expansion in India.
Among integrated pharmaceutical conglomerates, Pfizer Inc. and Merck & Co., Inc. occupy positions reflecting scale-driven hospital contracting advantages, while Gilead Sciences, Inc. exemplifies the lipid-complex specialization archetype. These three entities represent distinct competitive vectors: fermentation capacity, formulary anchoring, and complex formulation expertise respectively.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Novartis AG |
| GSK plc |
| Astellas Pharma Inc. |
| Bayer AG |
| Sanofi |
| Gilead Sciences, Inc. |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
Fermentation scientists concentrated in the Basel-Zurich corridor and Hyderabad-Ahmedabad belt create labor-cost differentials that widen pricing spreads between originator echinocandins and generic azoles. Skilled bioprocess engineers command premiums in Swiss sterile manufacturing facilities, while Indian API synthesis operations leverage technical workforce density to undercut European cost structures across bulk triazole production.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates hospital procurement, separating liposomal amphotericin formulations from generic fluconazole tablets and commodity topical creams. Price differentiation rests on FDA QIDP exclusivity status and sterile manufacturing certification grades. Pricing pressure stems from Indian generic echinocandin entrants capturing CDSCO fast-track approvals. Oncology wards demonstrate lowest price sensitivity; community hospitals face acute budget constraints.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Mumbai, and Singapore anchor hub-and-spoke patterns for temperature-controlled antifungal shipments. Active pharmaceutical ingredient synthesis concentrates in India and China, with sterile fill-finish capacity clustering in Germany, Switzerland, and the United States. Raw material dependencies include fermentation media, specialized solvents, and lyophilization excipients. Single-source vulnerability for echinocandin fermentation strains creates supply chain risk. Distribution runs through hospital group purchasing organizations and European hospital consortia with multi-year contracting protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Anti-Fungal Drugs Market compounds steadily as immunocompromised patient censuses in oncology and transplant wards expand across tertiary hospital networks. FDA Qualified Infectious Disease Product designation provides predictable exclusivity incentives that anchor manufacturer R&D returns.
For Market Incumbents: Deploy therapeutic drug monitoring platform integration to lock formulary relationships beyond molecule patents. Echinocandin franchise holders should secure multi-year group purchasing organization contracts before Indian generic fermentation capacity reaches Western markets. Liposomal formulation specialists must invest in closed-loop manufacturing to satisfy EU Green Deal carbon disclosure mandates. Capacity addition in Swiss sterile lyophilization facilities preserves premium positioning against Asian cost competition. For New Entrants and Emerging Players: CDSCO fast-track pathways in India open a window for generic echinocandin production targeting domestic oncology wards and export markets. White-space concentration exists in therapeutic drug monitoring service bundling alongside voriconazole and posaconazole prescriptions. Home care settings for oral azole step-down therapy represent the most penetrable segment. Go-to-market positioning should emphasize bioavailability advantages enabling earlier hospital discharge protocols. For Investors and Strategic Acquirers: Integrated pharmaceutical conglomerates with sterile manufacturing infrastructure are the most active acquirers in this space, seeking lipid-complex formulation capabilities and hospital formulary anchoring positions. Long-term viability frames around fermentation-based manufacturing moats and regulatory exclusivity mechanics. Acquisition targets include mid-size biotechnology firms with QIDP-designated pipeline assets. Watch FDA breakthrough therapy designation grants to novel antifungal classes as inflection indicators for portfolio prioritization shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA QIDP designation accelerates review timelines for resistant Candida auris candidates. |
| Manufacturing Scale-Up | Fermentation capacity expansion in Hyderabad serves domestic Indian demand and export markets. |
| Regulatory Approval Pathway | EMA adaptive pathways enable broader combination-therapy endpoints for European hospital networks. |
| Licensing Agreement | Technology transfers for liposomal formulation expertise bridge capability gaps between regions. |
| Pipeline Diversification | Resistance-breaking mechanisms target WHO fungal priority pathogens beyond azole platforms. |
Research Methodology
Bottom-up hospital formulary modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors informed demand-side assumptions. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases. Triangulation between stakeholder input and trade data ensures segmentation integrity across therapeutic classes and delivery modes.
Historical trendline analysis of echinocandin and azole consumption patterns established baseline growth trajectories across the projection horizon. The forecast framework models segmentation across product type, application severity, end-user setting, delivery mode, and regional regulatory cluster. CAGRs derive from patient census projections in oncology and transplant wards, formulary adoption curves, and generic entry timing assumptions. Industry-specific inputs include immunocompromised population demographics, FDA QIDP designation velocity, and EU Green Deal procurement mandate implementation schedules.
Revisions become necessary when novel antifungal resistance mechanisms emerge, major API manufacturing facilities face regulatory action, or hospital reimbursement frameworks shift substantially. Forecasts reflect documented assumptions regarding patient population growth, regulatory exclusivity periods, and competitive entry timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
Global Diphtheria Vaccine Market
Pharmaceuticals
North America Meglitinide Market
Pharmaceuticals
RNA-Targeted Small Molecules Market
Pharmaceuticals
H1N1 Vaccination Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Sulfonylureas Market
Pharmaceuticals
Nasal Vaccines Market
Pharmaceuticals
Liver Fibrosis Drugs Market
Pharmaceuticals
Multiple Sclerosis Drugs Market
Pharmaceuticals
Pharma PLM Market
Pharmaceuticals
Global Human Rotavirus Vaccine Market
Pharmaceuticals
Bevacizumab Market
Pharmaceuticals
Europe Oral Anti-Diabetic Drug Market
Pharmaceuticals
Veterinary Pain Management Drugs Market