
 Asia-Pacific Biguanide Market | 2026-2036
Asia-Pacific Biguanide Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Biguanide Market Outlook
Market Context
China's NMPA bioequivalence requirements for generic metformin is recalibrating the cost-of-entry calculus for multinational entrants. Takeda Pharmaceutical Company Limited anchors its position through backward integration into active pharmaceutical ingredient sourcing across East Asian supply corridors. Glenmark Pharmaceuticals Ltd. competes on price in oral tablet generics while sustaining R&D intensity for extended-release formulations. Cipla Ltd. leverages its distribution density in South Asian hospital networks to dominate institutional procurement channels.
Technical Definition and Segment Structure
Biguanides comprise a class of oral hypoglycemic agents characterized by a guanide-derived core structure that suppresses hepatic gluconeogenesis and improves peripheral insulin sensitivity, with metformin hydrochloride serving as the dominant commercial compound due to its favorable safety profile and established efficacy in glycemic control. The primary commercial purpose centers on first-line pharmacological management of type 2 diabetes mellitus, with secondary applications in polycystic ovary syndrome and emerging cardiovascular risk reduction protocols. Metformin product lines capture the majority of volume across oral tablet and extended-release delivery modes, while injectable formulations represent a faster-growing niche driven by patient compliance imperatives in Japanese and Australian markets. Hospital end users concentrate procurement power through tender systems, whereas homecare channels expand as extended-release tablets enable reduced dosing frequency for outpatient populations.
Regulatory Framework and Outlook
India's CDSCO enforces stringent bioequivalence standards for generic biguanide approvals, while Australia's TGA maintains parallel pharmacovigilance protocols that shape post-market surveillance obligations across the region. Japan's PMDA reviews for metformin combination therapies create additional regulatory layers that filter market access for novel formulations. China's dual carbon goals are pressing domestic manufacturers toward greener synthesis routes for biguanide active pharmaceutical ingredients, altering capital allocation priorities. Stakeholders must monitor how Japan's METI pharmaceutical supply chain resilience initiatives interact with India's PLI scheme to reshape regional production geography.
Market Dynamics
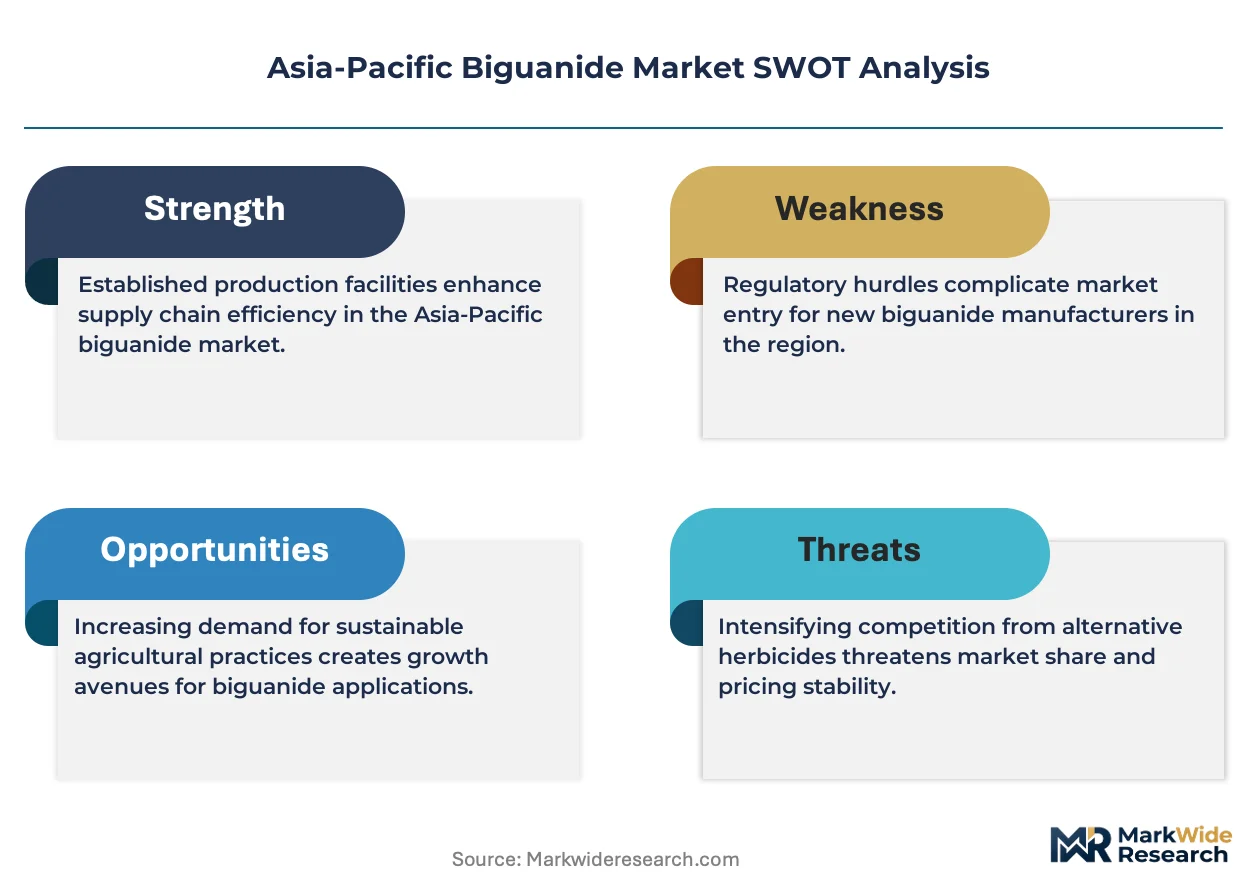
India's PLI scheme for active pharmaceutical ingredients is redrawing manufacturing economics across the Asia-Pacific Biguanide Market, forcing multinational formulators to reassess sourcing strategies and captive production ratios.
Growth Catalysts
- Extended-Release Formulation Demand:China's tier-one cities exhibit concentrated diabetes prevalence that drives uptake of once-daily metformin variants, compressing hospitalization rates and expanding outpatient prescription volumes.
- CDSCO Bioequivalence Standards:India's tightened generic approval protocols filter substandard entrants, elevating quality baselines that reward manufacturers with proven dissolution profile capabilities.
- Dual Carbon Goals:China's MEE mandates on green synthesis routes for biguanide APIs are accelerating capital flows toward enzymatic catalysis and solvent recovery systems in domestic production facilities.
Market Restraints
- API Supply Concentration:East Asian supply corridors dominate metformin hydrochloride precursor manufacturing, creating single-source vulnerability for formulators lacking backward integration into guanide derivative production.
- PMDA Combination Review Layers:Japan's incremental regulatory requirements for metformin-plus-SGLT2 inhibitor therapies extend approval timelines and inflate clinical trial expenditure for novel fixed-dose entrants.
- Insulin Analog Substitution:GLP-1 receptor agonists and basal insulin formulations capture treatment-naïve type 2 diabetes patients in Australian and Japanese reimbursement schemes, capping biguanide first-line share.
Strategic Opportunities
- Injectable Metformin Niche:Japanese and Australian markets show unmet demand for parenteral biguanide delivery among bariatric surgery patients with malabsorption, opening formulation development white space.
- South Asian Hospital Networks:Institutional procurement channels in Bangladesh, Vietnam, and Indonesia remain fragmented, enabling distributors with cold-chain capabilities to consolidate tender participation.
- METI Supply Chain Resilience Initiatives:Japan's pharmaceutical security programs offer co-funding for API inventory buffers, creating subsidy-eligible partnership structures for regional manufacturers.
Industry Challenges
- Bioanalytical Talent Scarcity:CDSCO and TGA pharmacovigilance requirements outpace the supply of chromatography specialists capable of executing complex dissolution studies for extended-release equivalence.
- Legacy Equipment Retrofit Costs:Batch processing infrastructure across Indian and Chinese contract manufacturers requires capital-intensive upgrades to meet continuous manufacturing guidelines under evolving ICH Q13 adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Biguanide Market |
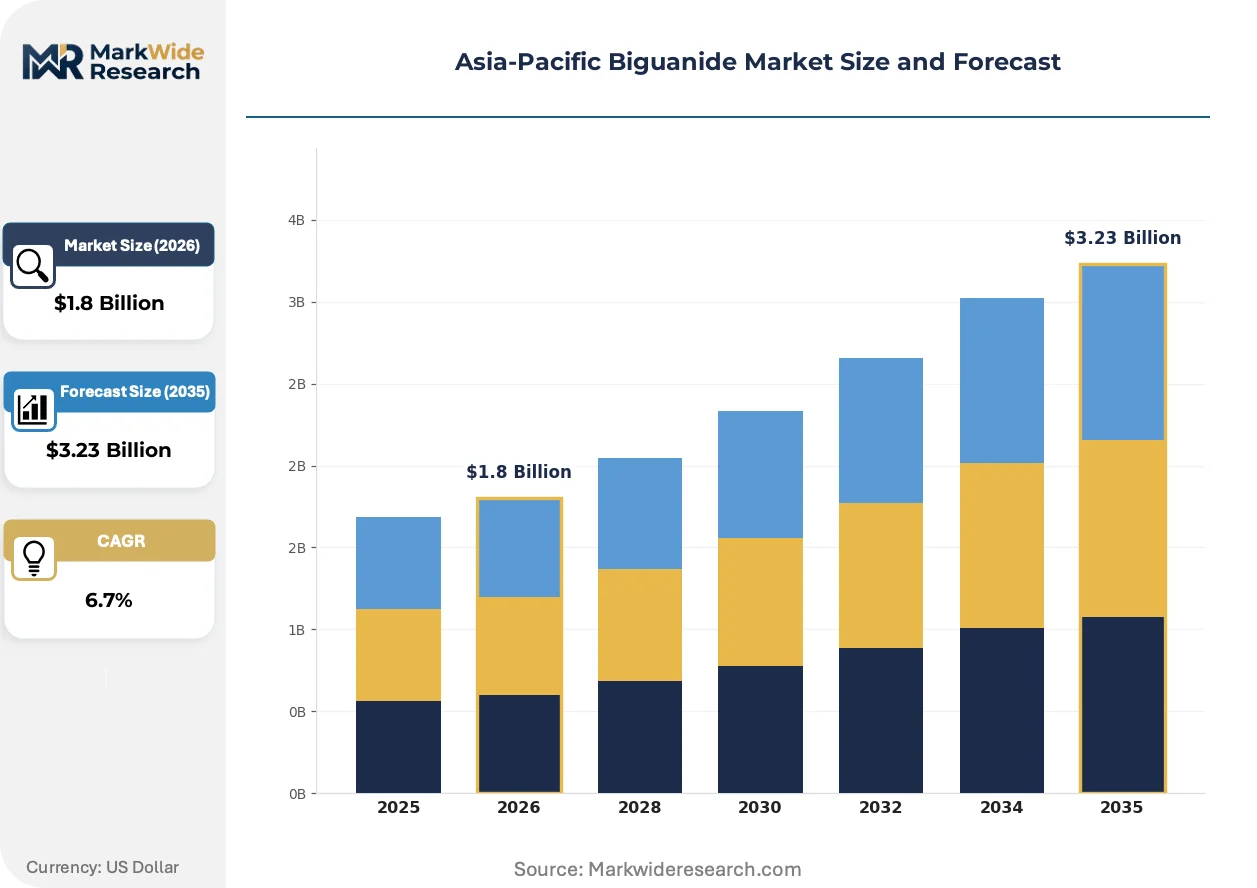
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metformin, Buformin, Phenformin, Others End User: Hospitals, Clinics, Homecare, Research Institutions Application: Type 2 Diabetes Treatment, Cardiovascular Benefits, Weight Management, Others Delivery Mode: Oral Tablets, Injectable, Extended-Release, Others |
| Companies Covered | Takeda Pharmaceutical Company Limited, Merck & Co., Inc., Sanofi, Bristol-Myers Squibb Company, GlaxoSmithKline plc, Boehringer Ingelheim International GmbH, Glenmark Pharmaceuticals Ltd., Cipla Ltd., Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Biguanide Market Strategic Shifts
Continuous processing technology and green chemistry mandates are converging to transform biguanide active pharmaceutical ingredient manufacturing across Asia-Pacific production corridors.
Enzymatic biocatalysis for metformin hydrochloride synthesis is electrifying cost structures in API manufacturing. Chinese producers under MEE emissions scrutiny are adopting immobilized enzyme reactors that halve organic solvent throughput. Takeda and domestic competitors are reallocating capex toward these biocatalytic platforms, compressing the cost gap between traditional chemical routes and sustainable alternatives.
Australia's TGA has tightened post-market surveillance obligations for biguanide generics through enhanced adverse event reporting mandates. The industrial consequence is elevated documentation burden for imported products, particularly from non-English-language manufacturing sites. Hospital procurement channels in Sydney and Melbourne are responding by privileging suppliers with established Australian pharmacovigilance infrastructure over price-focused alternatives.
Homecare channel expansion is displacing institutional volume across China's tier-two cities. Extended-release tablet formats enable reduced dosing frequency that supports outpatient adherence, with community pharmacy networks capturing prescription flow previously directed toward hospital dispensaries. This behavioral pivot is most visible in Chengdu and Wuhan, where diabetes management programs emphasize decentralized glycemic monitoring.
Asia-Pacific Biguanide Market Segmentation
Biguanide prescribing patterns diverge sharply across institutional versus ambulatory settings, with formulation choices driven by reimbursement bandwidth and patient adherence economics. Segment-level procurement strategies must account for CDSCO bioequivalence tiers, NMPA green synthesis mandates, and METI supply chain resilience programs that reshape competitive access.
Product Type:
Upgrade cycles in biguanide prescribing follow patent cliff dynamics and safety profile revisions that displace older molecular variants from first-line protocols.
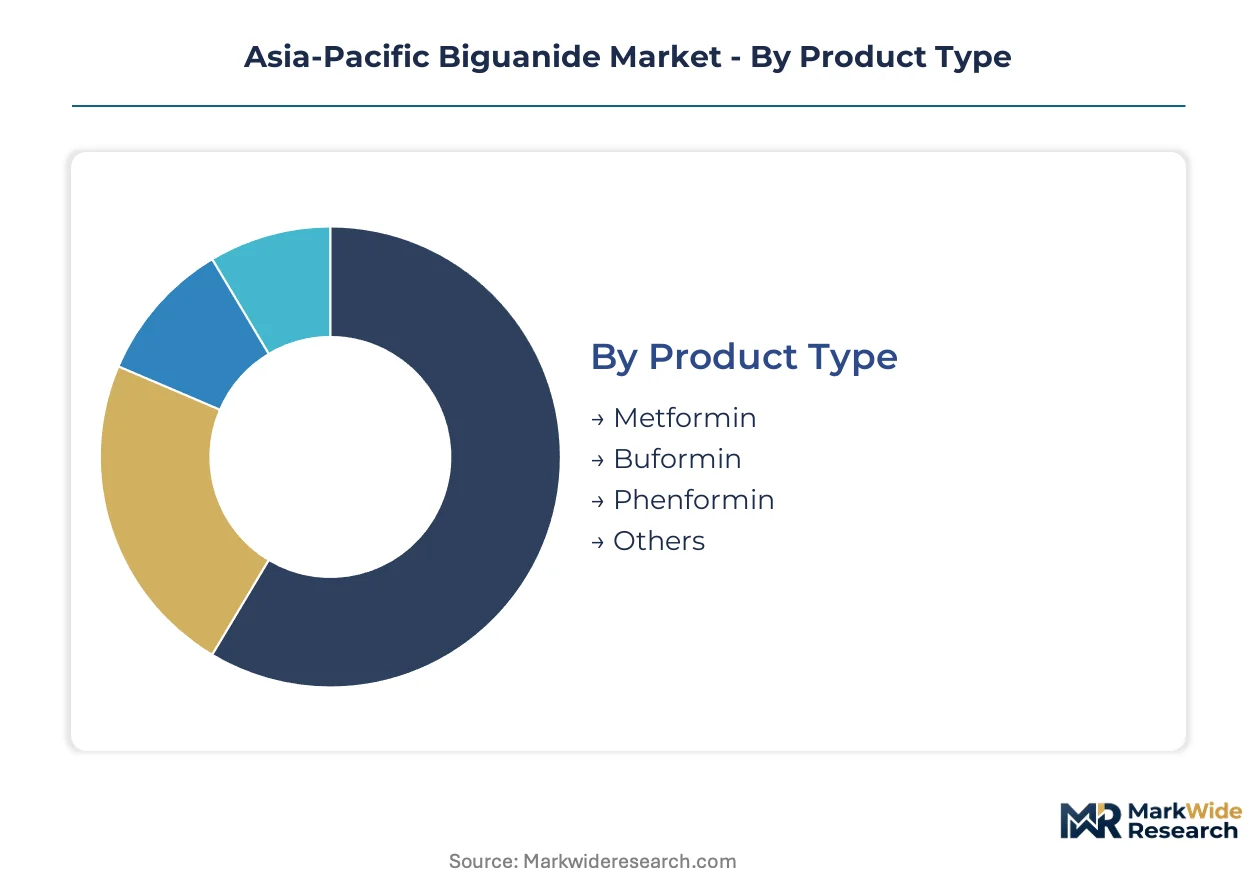
- Metformin:The hydrochloride salt dominates Asia-Pacific formularies through established hepatic gluconeogenesis suppression and peripheral insulin sensitivity improvement. China's tier-one cities and India's tertiary hospital networks concentrate procurement of this compound, with CDSCO dissolution profile requirements filtering substandard generic entrants from institutional tenders.
- Buformin:This butyl-substituted biguanide retains niche utilization in select Japanese and South Korean prescribing protocols where metformin intolerance manifests. Demand concentrates in specialized endocrinology clinics in Osaka and Seoul, constrained by PMDA pharmacovigilance alerts on lactic acidosis risk that limit expansion beyond refractory patient populations.
- Phenformin:Withdrawal from major Asia-Pacific markets following cardiovascular safety concerns relegates this segment to research applications and legacy protocol maintenance in isolated institutional settings.
- Others:Emerging guanide derivatives and combination precursors occupy preclinical and early-phase trial pipelines across Singapore and Australian research corridors.
Volume placements concentrate in Metformin; the faster expansion belongs to novel combination precursors in the Others category.
End User:
Cost tier stratification across reimbursement schemes divides procurement authority between centralized hospital tenders and decentralized pharmacy networks.
- Hospitals:Institutional procurement channels capture the majority of acute-phase biguanide dispensing through tender systems that privilege suppliers with proven bioequivalence documentation. India's AIIMS network and China's tier-one municipal hospitals anchor volume concentration, with Glenmark and Cipla dominating these channels through distribution density.
- Homecare:Extended-release tablet uptake enables outpatient adherence programs that shift prescription flow toward community pharmacy networks. Chengdu and Wuhan exhibit the most visible decentralization, where diabetes management programs emphasize reduced dosing frequency for glycemic control outside institutional settings.
- Clinics:Primary care and specialty endocrinology practices in Vietnam and Indonesia represent fragmented demand nodes with limited tender participation.
- Research Institutions:Academic medical centers in Singapore and Australia drive investigational use of biguanides for polycystic ovary syndrome and cardiovascular risk reduction protocols.
Revenue concentration sits with Hospitals; Homecare channels are climbing the fastest as extended-release formulations enable decentralized prescribing.
Application:
Margin structures vary across approved indications versus off-label protocols, with cardiovascular and metabolic applications commanding premium positioning.
- Type 2 Diabetes Treatment:First-line pharmacological management anchors the overwhelming majority of biguanide volume, with China's diabetes prevalence and India's expanding patient registry driving sustained demand. NMPA bioequivalence requirements for generic metformin elevate quality baselines that reward manufacturers with proven dissolution capabilities.
- Cardiovascular Benefits:Emerging protocols for risk reduction in prediabetic populations create expansion white space, particularly in Australian and Japanese reimbursement schemes where evidence-based guidelines increasingly recognize metformin's vascular protective effects.
- Weight Management:Off-label utilization for polycystic ovary syndrome and metabolic syndrome patients generates niche demand in specialized clinics across South Korea and Taiwan.
- Others:Investigational applications in oncology adjuvant therapy and longevity research occupy preclinical pipelines with limited commercial translation.
Prescription density peaks in Type 2 Diabetes Treatment; Cardiovascular Benefits applications show the steepest expansion trajectory as evidence protocols broaden.
Delivery Mode:
Supply concentration in oral solid dosage forms is displacing toward parenteral alternatives where malabsorption pathology creates unmet need.
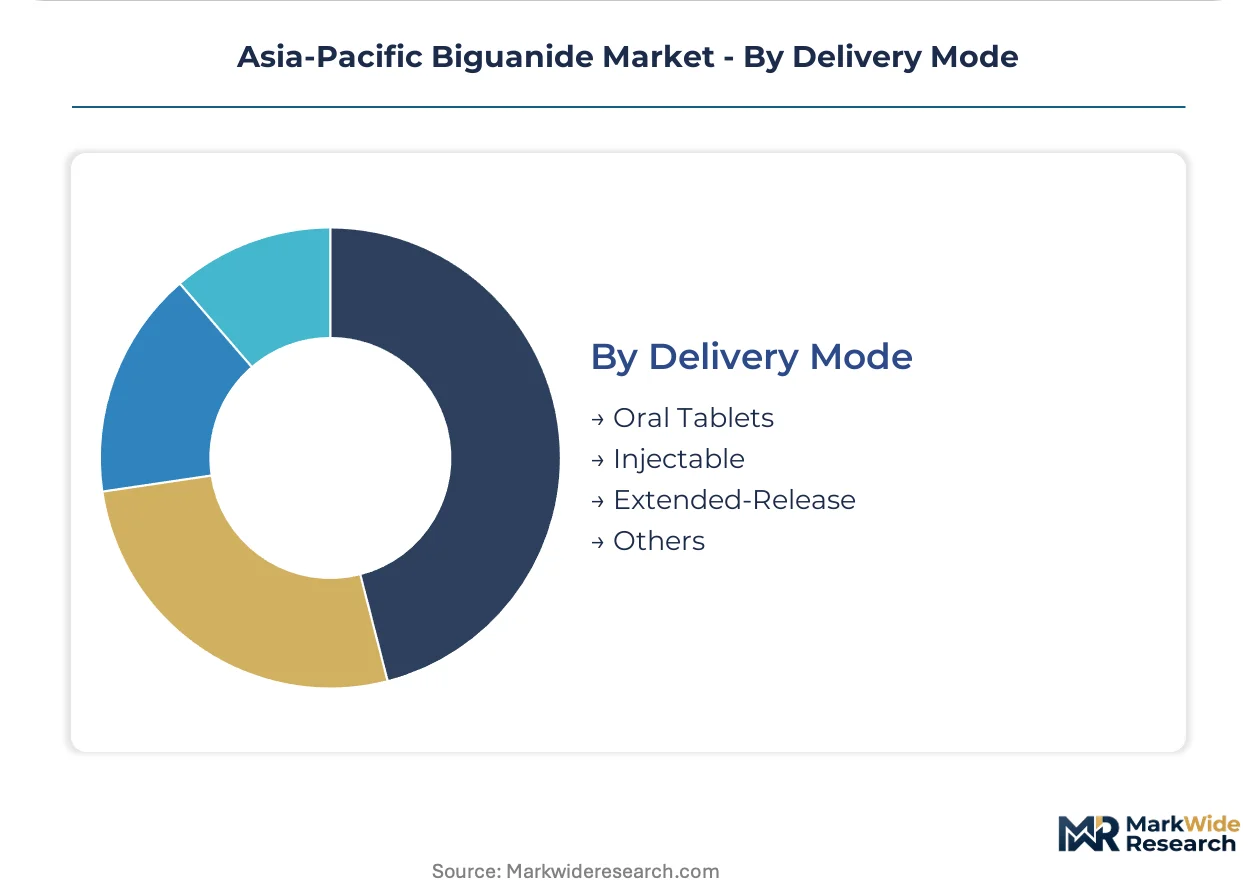
- Oral Tablets:Immediate-release formulations retain cost advantage in price-sensitive procurement environments, particularly across South Asian hospital networks where Glenmark competes on volume. India's PLI scheme for active pharmaceutical ingredients reinforces domestic manufacturing economics for these conventional dosage forms.
- Extended-Release:Once-daily metformin variants compress hospitalization rates and expand outpatient prescription volumes in China's tier-one cities, where patient adherence imperatives justify formulation premium. Takeda's backward integration into API sourcing supports competitive positioning in this higher-margin segment.
- Injectable:Parenteral delivery addresses bariatric surgery patients with malabsorption in Japanese and Australian markets, opening formulation development opportunities where oral bioavailability fails.
- Others:Transdermal patches and novel delivery mechanisms remain experimental with limited regulatory pathway clarity.
Unit volume concentrates in Oral Tablets; Injectable formats are gaining share fastest among surgical patient populations with absorption limitations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diabetes prevalence clusters in China's coastal megacities and India's urban corridors, concentrating procurement power in municipal hospital networks that favor extended-release metformin formulations.
China
Beijing and Shanghai municipal hospitals drive volume for once-daily metformin variants through centralized tender systems. NMPA bioequivalence requirements for generic approvals elevate manufacturing standards, filtering substandard entrants from procurement channels. Yangtze River Delta API producers are retrofitting facilities to meet MEE green synthesis mandates, accelerating capital flows toward enzymatic catalysis platforms.
India
Maharashtra and Gujarat anchor domestic biguanide production through API manufacturing clusters near Mumbai and Ahmedabad. CDSCO tightened bioequivalence protocols for generic metformin approvals, rewarding manufacturers with proven dissolution profile capabilities. The PLI scheme for active pharmaceutical ingredients is recalibrating cost structures for domestic formulators competing in South Asian hospital tenders.
Japan
Osaka and Tokyo endocrinology clinics sustain niche demand for buformin among metformin-intolerant patients. PMDA combination therapy reviews for metformin-plus-SGLT2 inhibitors extend approval timelines, inflating clinical expenditure for novel fixed-dose entrants. METI pharmaceutical supply chain resilience programs offer co-funding for API inventory buffers, creating subsidy-eligible partnerships for regional manufacturers.
Australia
Sydney and Melbourne hospital procurement channels privilege suppliers with established pharmacovigilance infrastructure over price-focused alternatives. TGA post-market surveillance mandates for biguanide generics elevate documentation burdens for imported products. Injectable metformin demand is emerging among bariatric surgery patients with malabsorption pathology in Queensland and Victoria surgical centers.
South Korea
Seoul Capital Area tertiary hospitals concentrate prescribing authority for biguanide combination therapies. MFDS pharmacovigilance protocols align with regional standards, shaping post-market obligations for domestic and imported formulations. Busan-Ulsan pharmaceutical manufacturing corridors are expanding capacity for extended-release tablet production to serve domestic and export markets.
Asia-Pacific Biguanide Market Competitive Environment
Japanese and European multinationals anchor the premium formulation tier; Indian and Israeli generic specialists hold volume positions in price-sensitive procurement channels. The market structure fragments across three tiers: backward-integrated API producers, formulation-focused generic houses, and research-oriented combination therapy developers. Two dominant competitive moves are reshaping positioning: strategic partnerships for green synthesis technology licensing and geographic expansion into fragmented Southeast Asian hospital networks.
Within the multinational tier, Takeda Pharmaceutical Company Limited and Merck & Co., Inc. occupy positions exemplifying backward-integrated supply chain architecture. Among generic specialists, Glenmark Pharmaceuticals Ltd. and Cipla Ltd. represent the Indian formulation-focused archetype competing on distribution density in institutional procurement channels. Teva Pharmaceutical Industries Ltd. sits within the mid-tier category, bridging research-oriented positioning with volume-scale manufacturing capabilities.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| Merck & Co., Inc. |
| Sanofi |
| Bristol-Myers Squibb Company |
| GlaxoSmithKline plc |
| Boehringer Ingelheim International GmbH |
| Glenmark Pharmaceuticals Ltd. |
| Cipla Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Chromatography specialist shortages across Mumbai and Ahmedabad widen spreads between CDSCO-certified premium tiers and uncertified economy supply. Labor-cost differentials between these Indian API clusters and Yangtze River Delta enzymatic catalysis facilities compress margins for traditional chemical synthesis routes.
Pricing Analysis
Volume concentrates in immediate-release oral tablets where Glenmark and Cipla compete on scale, while extended-release formulations capture margin premiums through once-daily adherence benefits. Pricing stratifies across premium, standard, and economy tiers based on bioequivalence certification grade and dissolution profile documentation. Cost compression in the economy tier intensifies as India's PLI scheme expands domestic API capacity. Hospital procurement channels show lowest price sensitivity due to tender-based volume commitments, whereas fragmented clinic networks in Vietnam and Indonesia drive hard bargaining.
Supply Chain Analysis
Workforce availability for biocatalysis engineering constrains expansion in Chinese MEE-compliant facilities beyond Shanghai and Jiangsu provinces. Active pharmaceutical ingredient supply concentrates in India, China, and selected Japanese backward-integrated operations. Metformin hydrochloride production draws from guanide derivative precursors and specialized enzyme immobilization substrates. Single-source vulnerability pervades East Asian supply corridors where precursor manufacturing lacks geographic diversification. Distribution runs through hospital tender systems in tier-one cities and distributor networks in fragmented Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where CDSCO bioequivalence standards erect barrier-to-entry moats favoring manufacturers with proven dissolution capabilities and established pharmacovigilance infrastructure.
For Market Incumbents: Anchor market position through backward integration into API sourcing across East Asian supply corridors, insulating against guanide derivative price volatility. Deepen captive production of extended-release formulations to defend margin structure against immediate-release commoditization. Prioritize enzymatic catalysis licensing to preempt MEE emissions compliance costs that will disadvantage chemical synthesis competitors. For New Entrants and Emerging Players: Injectable metformin formulation technology offers a technology-first wedge into Japanese and Australian bariatric surgery patient populations with malabsorption pathology. Target South Asian hospital networks in Bangladesh and Indonesia where institutional procurement remains fragmented and cold-chain capabilities enable tender consolidation. Pursue partnership structures with established distributors rather than direct sales infrastructure buildout. For Investors and Strategic Acquirers: Re-rating potential sits with CDSCO-certified API manufacturers given India's PLI scheme catalyzing cost structure advantages over import-dependent formulators. Long-term viability favors backward-integrated players with enzymatic platform investments and established hospital tender relationships. Monitor METI pharmaceutical supply chain resilience program funding announcements as inflection indicator for subsidy-eligible partnership opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Catalysis Platform Investment | MEE green synthesis mandates in China accelerate capital flows toward solvent-reducing biocatalytic production routes. |
| CDSCO Bioequivalence Certification | Tightened generic approval protocols filter substandard entrants and reward manufacturers with proven dissolution capabilities. |
| Extended-Release Formulation Development | Once-daily metformin variants capture outpatient prescription volume shifting from hospital to homecare channels. |
| Backward Integration into API Sourcing | East Asian supply corridor concentration creates vulnerability that captive guanide derivative production mitigates. |
| Injectable Metformin Development | Bariatric surgery patient populations in Japan and Australia present formulation white space where oral bioavailability fails. |
Study Parameters
Document review covered NMPA bioequivalence filings, CDSCO generic approval databases, and METI pharmaceutical supply chain program disclosures, complemented by interviews with API manufacturing executives, hospital procurement managers, regulatory affairs specialists, and endocrinology formulary directors. Secondary validation drew from clinical trial registries, customs trade data for biguanide precursor movements, and SEC filings of listed pharmaceutical manufacturers. Bottom-up volume estimates triangulated against top-down expenditure analysis across the projection horizon.
Cross-referencing historical prescription volume patterns against expert panel input on extended-release adoption trajectories shaped the analytical framework. Segmentation modeling incorporated product type, end-user channel, application indication, and delivery mode dimensions across regional regulatory clusters. CAGRs derived from iterative reconciliation of supply-side capacity expansion with demand-side epidemiological projections for diabetes prevalence. Industry-specific inputs included PLI scheme disbursement schedules and MEE emissions compliance timelines.
Several conditions sit outside the modeled scope, including unforeseen PMDA combination therapy approval accelerations, abrupt insulin analog substitution shifts in Australian reimbursement, and geopolitical disruptions to East Asian precursor trade corridors. Forecasts reflect documented assumptions regarding bioequivalence standard stability and green synthesis technology maturation curves. Material deviation in CDSCO enforcement intensity or METI subsidy allocation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
North America Meglitinide Market
Pharmaceuticals
Isoflurane Market
Pharmaceuticals
Japan Diabetes Drugs Market
Pharmaceuticals
Acetaminophen Market
Pharmaceuticals
Europe Pharmaceutical Market
Pharmaceuticals
Compound Potassium Hydrogen Phosphate Injection Market
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market
Pharmaceuticals
Lipid Injectable Market
Pharmaceuticals
Global Autism Spectrum Disorder Therapeutics Market
Pharmaceuticals
Cytomegalovirus Treatment Market
Pharmaceuticals
Ramipril Market
Pharmaceuticals
Contract Pharmaceutical Fermentation Services Market
Pharmaceuticals
Xanthine Oxidase Inhibitors Market
Pharmaceuticals
Prothrombin Complex Concentrate (PCC) Market
Pharmaceuticals
Iodine Deficiency Drug Market
Pharmaceuticals
Glucagon-Like Peptide-1 (GLP-1) Agonists Market