
 Metaxalone Market | 2026-2036
Metaxalone Market Size, Share, and Industry Trends Forecast 2026-2036
Metaxalone Market Foresight
FDA bioequivalence requirements for abbreviated new drug applications is decoupling small-scale API manufacturers from contract manufacturing opportunities. Pfizer Inc. leverages its established hospital formulary access to sustain branded metaxalone positioning against generic erosion. Biosynth anchors European supply chains through controlled-substance precursor sourcing capabilities. Chunghwa Chemical Synthesis & Biotech Co., Ltd. competes on cost-optimized fermentation-derived intermediate production for Asian pharmaceutical customers.
Metaxalone is a centrally acting skeletal muscle relaxant with the chemical designation 5-(3,5-dimethylphenoxy)-2-methyl-2-oxazolidinone, administered typically in 800 mg tablets for acute musculoskeletal pain relief through depression of central nervous system reflex arcs. The tablet segment dominates hospital dispensing protocols due to established insurance reimbursement codes and nursing staff familiarity with oral administration workflows. Extended release formulations within the formulation dimension are capturing margin pools as patents on immediate-release references expire and payers favor reduced dosing frequency for chronic pain patients.
FDA oversees bioequivalence validation and current Good Manufacturing Practice compliance for all domestic metaxalone finished dosage forms, while the Drug Enforcement Administration monitors precursor chemical movements under controlled substances analog provisions. The European Medicines Agency enforces International Council for Harmonisation Q3D elemental impurity guidelines that elevate analytical costs for API suppliers serving European Union markets. Stakeholders must monitor how pharmacovigilance databases flag sedation-related adverse event clusters that could trigger label restrictions or prescriber education mandates.
Market Dynamics
FDA bioequivalence standards for abbreviated new drug applications are decoupling small-scale API manufacturers from contract manufacturing opportunities, concentrating finished dosage form supply among vertically integrated pharmaceutical firms with established hospital formulary access.
Growth Catalysts
- Orthopedic surgery volume expansion:Rising procedural counts in US tertiary care centers are intensifying hospital procurement of muscle relaxants for postoperative pain management protocols.
- REACH compliance elevation:ECHA enforcement of International Council for Harmonisation Q3D elemental impurity guidelines is filtering out subscale API suppliers and rewarding analytical-capable manufacturers.
- Extended release formulation development:Patent expiration on immediate-release references is creating margin pools for reduced dosing frequency products favored by chronic pain patients and payers.
Market Restraints
- Precursor chemical control costs:DEA monitoring of controlled-substance analog movements under analog provisions is elevating compliance overhead for domestic formulation manufacturers.
- European supply chain concentration:Biosynth's dominance in controlled-substance precursor sourcing creates single-point vulnerability for EU market API availability.
- Sedation adverse event surveillance:Pharmacovigilance database flagging of central nervous system depression clusters risks triggering label restrictions or prescriber education mandates that constrain prescribing latitude.
Strategic Opportunities
- Asian fermentation-derived intermediate production:Chunghwa Chemical Synthesis & Biotech Co.'s cost-optimized manufacturing model demonstrates scalable pathways for API cost reduction serving price-sensitive pharmaceutical customers.
- Chronic pain protocol expansion:Extended release metaxalone aligns with evolving US payer preferences for reduced pill burden in long-term musculoskeletal condition management.
- Hospital formulary consolidation:Branded positioning through established GPO relationships creates defensive moats against generic erosion in institutional procurement channels.
Industry Challenges
- Bioequivalence study execution complexity:FDA tightening of purity benchmarks for abbreviated new drug applications demands specialized clinical pharmacology expertise that constrains generic sponsor pipelines.
- Multi-jurisdiction regulatory synchronization:Divergent EMA Q3D, FDA bioequivalence, and DEA precursor requirements force parallel compliance architectures that fragment quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metaxalone Market |
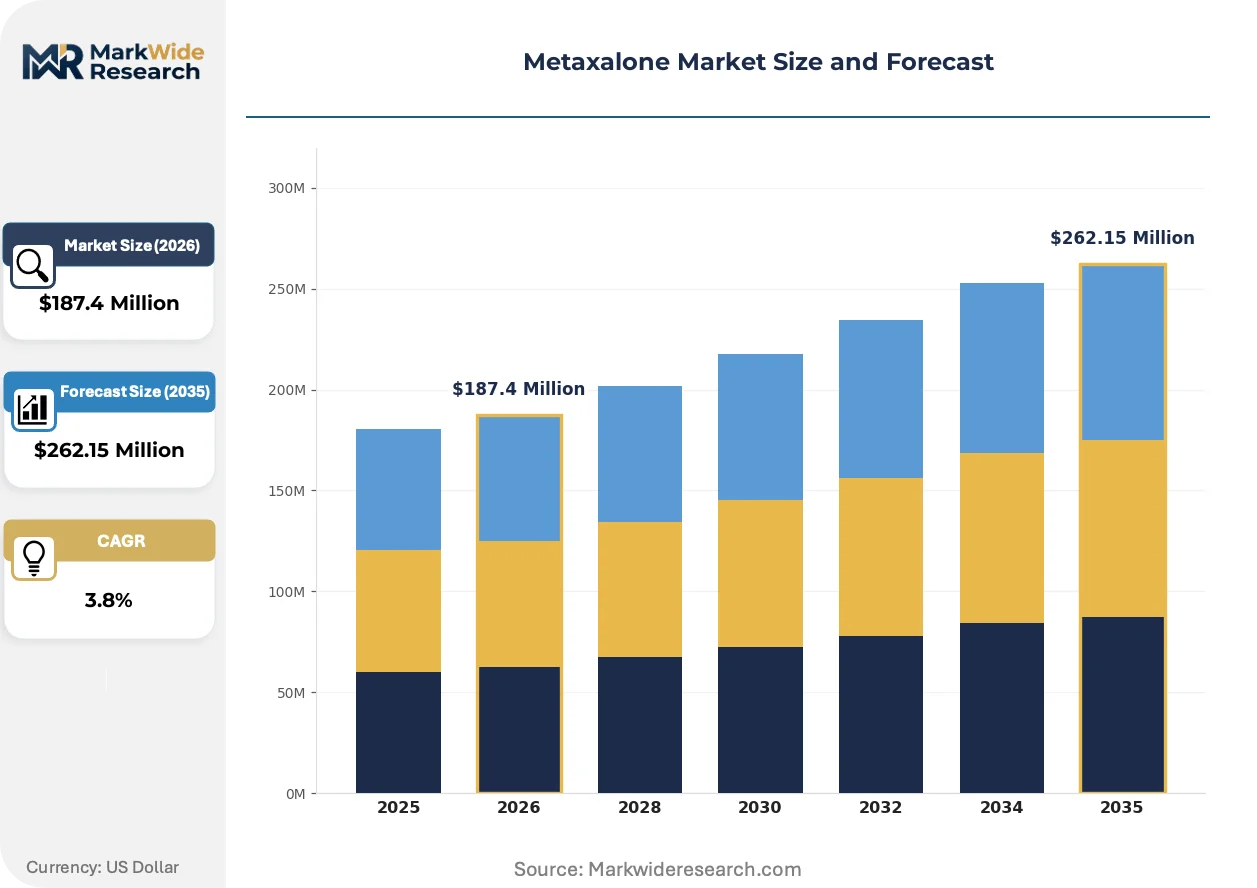
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Capsule, Liquid, Injectable End User: Hospitals, Clinics, Pharmacies, Homecare Distribution Channel: Online, Retail, Wholesalers, Distributors Formulation: Immediate Release, Extended Release, Combination, Others |
| Companies Covered | Biosynth, Chunghwa Chemical Synthesis & Biotech Co., Ltd., Sigma-Aldrich Co. LLC, CDI Technology, Angelini S.p.A., Pfizer Inc., Aurum Pharmatech LLC, Finetech Industry Limited, Biocore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metaxalone Market Shifts & Advancements
Formulation technology evolution and regulatory stringency are compressing competitive margins while rewarding manufacturers with integrated analytical and clinical capabilities.
Extended release oral solid dosage technology is consolidating market positioning around reduced dosing frequency products. Hospital formularies and chronic pain clinics are adopting these formulations at accelerating rates as immediate-release patents expire. This consolidation is compressing margins on commodity immediate-release tablets while concentrating value capture among manufacturers with modified-release platform expertise.
EMA enforcement of ICH Q3D elemental impurity guidelines is elevating analytical costs for API suppliers serving European Union markets. The industrial consequence is systematic exclusion of small-scale manufacturers lacking inductively coupled plasma mass spectrometry capabilities. Asian API suppliers are responding by investing in centralized analytical service centers or exiting EU-bound contract manufacturing.
Hospital procurement centralization through group purchasing organizations is displacing fragmented distributor relationships. Integrated delivery networks are consolidating muscle relaxant purchasing decisions, replacing independent pharmacy buyers with formulary committees. This concentration is most visible in United States tertiary care centers where orthopedic surgery volumes drive contract negotiation leverage.
Metaxalone Market Segmentation
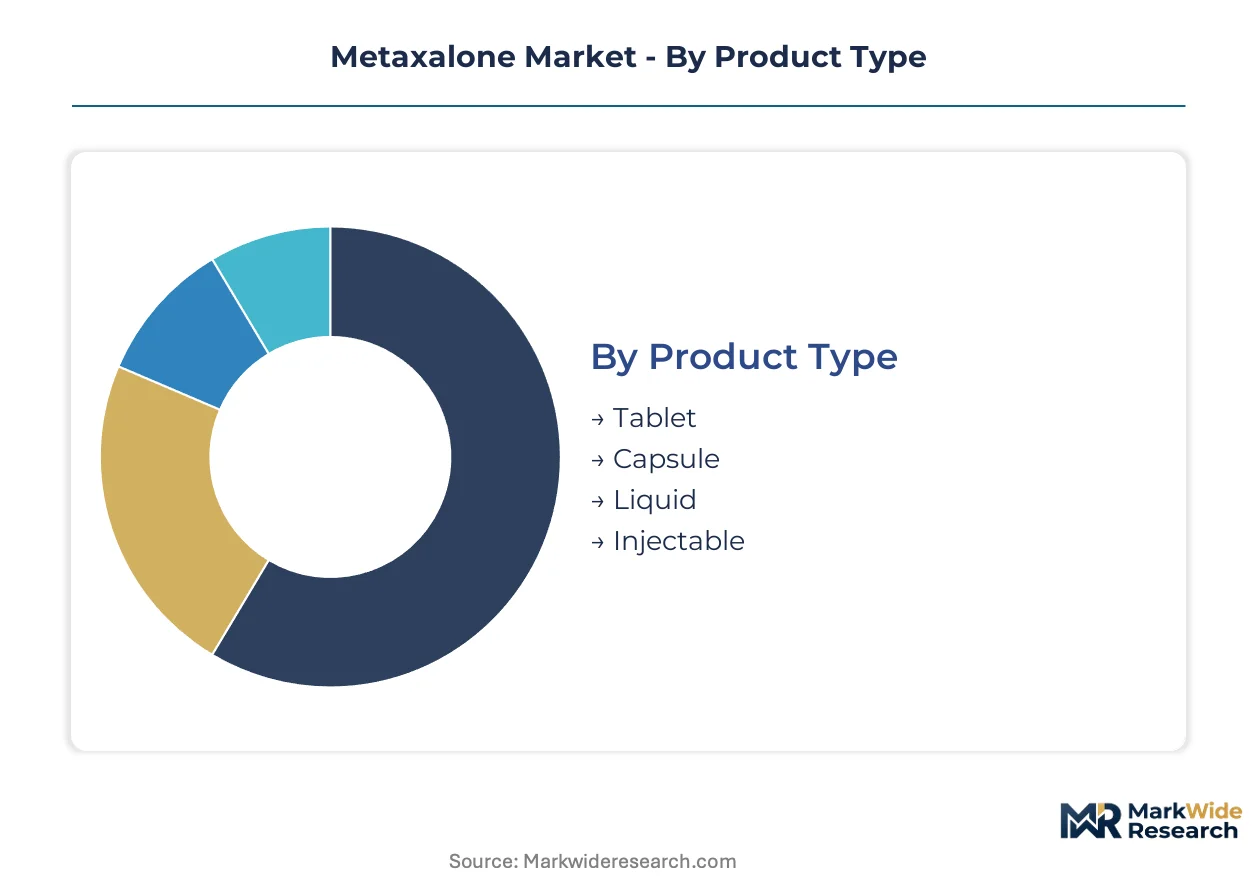
Metaxalone market segmentation reveals divergent competitive dynamics across dosage forms, patient settings, and supply channels. Hospital procurement centralization and chronic pain protocol evolution are reshaping volume concentration patterns.
Product Type:
Standardization dominates tablet manufacturing while liquid and injectable formats require specialized production infrastructure.
- Tablet:Oral solid dosage form containing 800 mg metaxalone compressed with standard excipients. Hospital formularies in US tertiary care centers concentrate procurement through group purchasing organizations, with established insurance reimbursement codes reinforcing nursing staff familiarity with oral administration workflows.
- Liquid:Suspension formulation enabling dose titration for patients with dysphagia or pediatric populations. Demand concentrates in homecare settings where caregiver administration flexibility outweighs stability and storage constraints of aqueous preparations.
- Capsule:Gelatin-encapsulated powder offering taste masking and moisture protection compared to tablets.
- Injectable:Parenteral formulation reserved for perioperative settings where oral route is contraindicated.
Most installed capacity flows through Tablet. Expansion is steepest in Liquid.
End User:
Volume concentration tracks orthopedic surgery procedural growth and chronic pain management protocol maturation.
- Hospitals:Institutional procurement of muscle relaxants for postoperative pain management in surgical wards and emergency departments. Integrated delivery networks in US tertiary care centers are consolidating purchasing decisions through formulary committees, displacing independent pharmacy buyer relationships.
- Clinics:Outpatient musculoskeletal and pain management specialty practices prescribing for acute injury and chronic condition flare-ups. Payer preferences for reduced pill burden in long-term management are accelerating extended release adoption.
- Pharmacies:Community and specialty retail dispensing for acute prescriptions and maintenance therapy refills.
- Homecare:Direct-to-patient distribution supporting post-discharge recovery and long-term chronic pain patients.
Procurement volume concentrates in Hospitals. Prescription growth is climbing fastest in Clinics.
Distribution Channel:
Channel margins compress where intermediaries multiply and expand where direct relationships reduce handling costs.
- Online:Direct-to-consumer and mail-order pharmacy platforms capturing chronic maintenance prescriptions. US patients managing long-term musculoskeletal conditions favor reduced dosing frequency products available through automated refill programs.
- Retail:Brick-and-mortar pharmacy chains handling acute prescriptions and same-day dispensing needs. Store locations near orthopedic surgery centers capture immediate post-discharge demand.
- Wholesalers:National and regional distributors managing inventory aggregation for institutional and retail customers.
- Distributors:Specialized pharmaceutical logistics providers handling controlled-substance precursor documentation under DEA monitoring requirements.
Transaction volume runs heaviest through Retail. Digital channel penetration is deepening most quickly in Online.
Formulation:
Technology maturity separates immediate-release commoditization from modified-release value capture.
- Immediate Release:Conventional oral solid dosage with rapid dissolution and absorption profiles. Patent expirations on reference products are compressing margins as generic sponsors navigate FDA bioequivalence study complexity.
- Extended Release:Matrix or reservoir-based modified release technology enabling reduced dosing frequency. Payers and chronic pain patients favor lower pill burden for long-term musculoskeletal condition management.
- Combination:Fixed-dose products pairing metaxalone with analgesic or anti-inflammatory agents.
- Others:Novel delivery technologies including orally disintegrating tablets and transdermal patches in development.
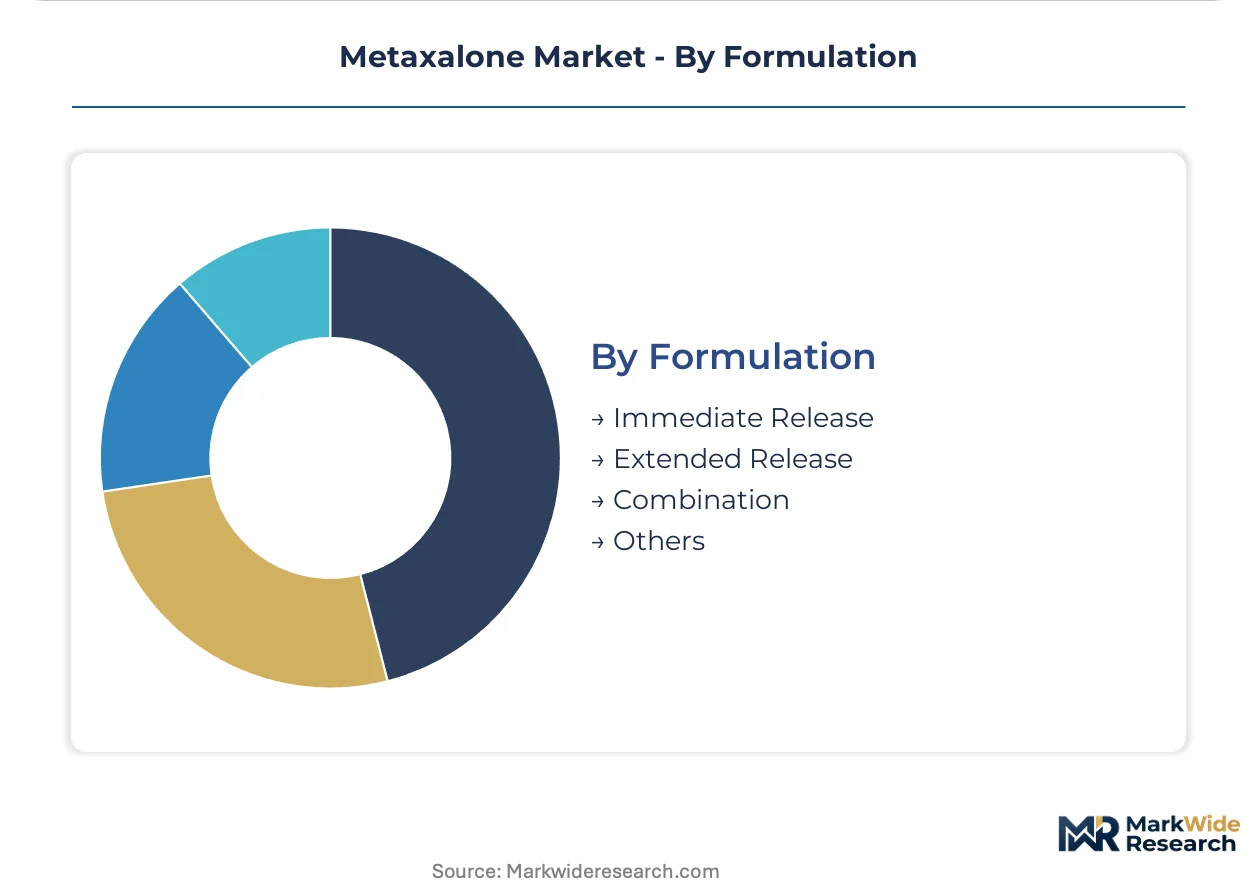
Prescription volume concentrates in Immediate Release. Value capture is shifting most rapidly toward Extended Release.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized pharmaceutical chemists and regulatory affairs professionals concentrate in jurisdictions with mature FDA and EMA oversight frameworks. Hospital procurement networks and API manufacturing clusters anchor demand in developed markets with established pain management protocols.
United States
Tertiary care centers in Texas and Florida drive orthopedic surgery volumes requiring postoperative muscle relaxant protocols. FDA bioequivalence standards for abbreviated new drug applications filter generic sponsor pipelines through specialized clinical pharmacology requirements. Hospital formulary committees in the Northeast Corridor consolidate procurement decisions through group purchasing organizations.
Germany
Specialized pain clinics in Bavaria and North Rhine-Westphalia prescribe extended release formulations for chronic musculoskeletal conditions. EMA enforcement of ICH Q3D elemental impurity guidelines elevates analytical costs for API suppliers serving European Union markets. Frankfurt and Basel-area logistics hubs manage controlled-substance precursor documentation under cross-border monitoring frameworks.
India
Contract research organizations in Maharashtra and Gujarat execute bioequivalence studies for generic sponsors targeting export markets. CDSCO oversight of active pharmaceutical ingredient manufacturing aligns with FDA inspection protocols for US-bound shipments. Hyderabad and Ahmedabad clusters specialize in cost-optimized fermentation-derived intermediate production.
Japan
Aging demographics in Kanto and Kansai regions expand chronic pain patient populations requiring long-term muscle relaxant therapy. PMDA pharmacovigilance systems monitor central nervous system depression adverse events for label restriction risks. Osaka-based pharmaceutical distributors manage hospital procurement through regional medical association networks.
United Kingdom
NHS Integrated Care Boards in London and the Midlands consolidate musculoskeletal pain management prescribing guidelines. MHRA post-Brexit regulatory autonomy maintains ICH Q3D alignment while diverging from EU batch testing requirements. Manchester and Cambridge research clusters develop novel formulation technologies for modified-release applications.
Metaxalone Market Competitive Landscape
The competitive structure tilts toward vertically integrated pharmaceutical firms with established hospital formulary access. Small-scale API manufacturers face systematic exclusion as FDA bioequivalence standards concentrate finished dosage form supply among analytical-capable sponsors. Three archetypes dominate: multinational branded incumbents defending formulary positioning, Asian fermentation specialists competing on intermediate cost, and European controlled-substance precursor suppliers anchoring supply security. Dominant competitive moves include strategic partnerships with group purchasing organizations and portfolio diversification into extended release platforms.
Among European-based chemical suppliers, Biosynth exemplifies the controlled-substance precursor archetype through its positioning in API supply chains. Pfizer Inc. represents the branded incumbent tier with established hospital access. Chunghwa Chemical Synthesis & Biotech Co., Ltd. anchors the Asian fermentation-derived intermediate segment serving price-sensitive pharmaceutical manufacturing customers.
| Leading Market Players |
|---|
| Biosynth |
| Chunghwa Chemical Synthesis & Biotech Co., Ltd. |
| Sigma-Aldrich Co. LLC |
| CDI Technology |
| Angelini S.p.A. |
| Pfizer Inc. |
| Aurum Pharmatech LLC |
| Finetech Industry Limited |
| Biocore |
| Others |
Supply & Pricing Matrix
Hospital formulary consolidation through group purchasing organizations in the United States is compressing margins on immediate-release metaxalone tablets while forcing API suppliers to absorb EMA Q3D elemental impurity compliance costs or exit European contract manufacturing entirely.
Pricing Analysis
Branded formulation bundles with established hospital access command premiums over unbundled generic tablet supplies. Three-tier pricing structure across premium extended-release, standard immediate-release, and economy generic tablet levels stratifies by bioequivalence certification tier and formulary positioning. Cost compression in immediate-release generics is intensifying because FDA purity benchmark tightening elevates clinical pharmacology study costs for abbreviated new drug application sponsors. Hospital procurement committees demonstrate lowest price sensitivity due to GPO-negotiated contracts, while retail pharmacy channels face acute price sensitivity from automated substitution policies.
Supply Chain Analysis
Reverse-logistics flows for expired or recalled metaxalone batches remain underdeveloped, creating compliance liability accumulation for distributors handling DEA-controlled precursor documentation. Active pharmaceutical ingredient supply concentrates in India, China, and selected European facilities. Fermentation-derived intermediate production draws from specialized chemical precursors and analytical-grade solvents. Single-source vulnerability in European controlled-substance precursor sourcing through Biosynth creates structural risk for EU-bound finished dosage form availability. Distribution runs through national wholesalers managing hospital GPO contracts and specialized pharmaceutical logistics providers handling DEA monitoring requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metaxalone market represents a late-cycle quality story as chronic pain management protocols shift toward extended-release specifications with superior bioequivalence profiles and reduced dosing frequency.
For Market Incumbents: Hedge against generic erosion by deepening backward integration into fermentation-derived intermediate production or securing captive supply through Asian API partnerships. Defensive moat construction through hospital GPO relationship exclusivity and extended-release platform patent portfolios counters immediate-release commodity price erosion. FDA bioequivalence study execution complexity constrains generic sponsor pipelines, protecting branded positioning. For New Entrants and Emerging Players: Modified-release formulation technology offers entry leverage into chronic pain clinic prescribing channels underserved by immediate-release generic saturation. Target liquid suspension formats for dysphagia and pediatric populations where caregiver administration flexibility commands pricing tolerance absent in tablet commoditization. Pursue contract manufacturing partnerships with Indian CROs executing bioequivalence studies for export-market abbreviated new drug applications. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated pharmaceutical firms combining hospital formulary access with extended-release platform expertise. Long-term viability over a multi-year horizon favors sponsors with demonstrated FDA bioequivalence validation capabilities and established GPO contracting relationships. Monitor pharmacovigilance database flagging of sedation-related adverse event clusters as early signal for potential label restriction risks constraining prescribing latitude.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Platform Development | Captures margin pools as immediate-release patents expire and chronic pain protocols favor reduced dosing frequency. |
| Hospital GPO Partnership Consolidation | Secures defensive procurement positioning against generic erosion in institutional channels with concentrated orthopedic surgery volumes. |
| Backward Integration into API Manufacturing | Absorbs EMA Q3D compliance costs in-house while filtering subscale competitors lacking inductively coupled plasma mass spectrometry capabilities. |
| Bioequivalence Study Capability Investment | Enables abbreviated new drug application pipeline execution as FDA tightening of purity benchmarks decouples small-scale sponsors. |
| Controlled-Substance Precursor Supply Security | Mitigates single-point vulnerability in European API availability through diversified sourcing or strategic inventory positioning. |
Research Methodology
Bottom-up orthopedic surgery volume modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with hospital formulary directors, regulatory affairs leads at generic sponsors, pain management clinicians, and pharmaceutical procurement managers combined with secondary validation against FDA abbreviated new drug application filings, EMA Q3D guidance documents, DEA controlled-substance movement reports, and hospital GPO contract databases. Triangulation between demand-side procedural growth and supply-side manufacturing capacity anchors volume estimates.
Historical trendline analysis of metaxalone prescription patterns across dosage forms, patient settings, and distribution channels established baseline trajectories. Segmentation modeling spanned formulation technology, end-user facility type, and regional regulatory cluster. CAGRs were derived through regression analysis of volume drivers including orthopedic surgery procedural growth, chronic pain protocol maturation, and generic entry timing. Forecast inputs incorporated extended-release adoption curves, FDA bioequivalence approval timelines, and hospital procurement centralization rates.
The model holds under stable regulatory enforcement intensity and continued hospital GPO consolidation; deviation in pharmacovigilance-triggered label restrictions or DEA precursor control escalation would shift volume trajectories. Forecasts reflect documented assumptions regarding bioequivalence study success rates and formulary access retention. Practitioners should monitor FDA adverse event database clustering and EMA inspection enforcement intensity for early signals of supply constraint or demand restriction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Opioid Analgesics Market
Pharmaceuticals
Norovirus Treatment Market
Pharmaceuticals
Injectable Targeted Therapy Market
Pharmaceuticals
Global Opioid Induced Constipation Market
Pharmaceuticals
Europe Veterinary Pharmaceuticals Market
Pharmaceuticals
Laxatives Market
Pharmaceuticals
Nimodipine Market
Pharmaceuticals
Europe Parenteral Lipid Emulsion Market
Pharmaceuticals
Soft Capsules Drugs Market
Pharmaceuticals
GCC Generic Injectables Market
Pharmaceuticals
United Kingdom OTC Drugs Market
Pharmaceuticals
Global Pharmacy Benefit Management (PBM) Market
Pharmaceuticals
APAC Pharmaceutical Warehousing Market
Pharmaceuticals
Topical Corticosteroids Market
Pharmaceuticals
Depression Drugs Market
Pharmaceuticals
US Pharmaceutical Warehousing Market