
 Candidiasis Therapeutics Market | 2026-2036
Candidiasis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Candidiasis Therapeutics Market Analysis
Hospital procurement of systemic antifungals is collapsing toward centralized formulary control while homecare infusion is gaining share among stable patients. Pfizer Inc. leverages its intravenous azole manufacturing scale to anchor hospital contracts across North America. Cidara Therapeutics Inc. differentiates through long-acting echinocandin conjugates designed for weekly dosing. SCYNEXIS, Inc. specializes in oral triterpenoid antifungals targeting refractory vulvovaginal cases.
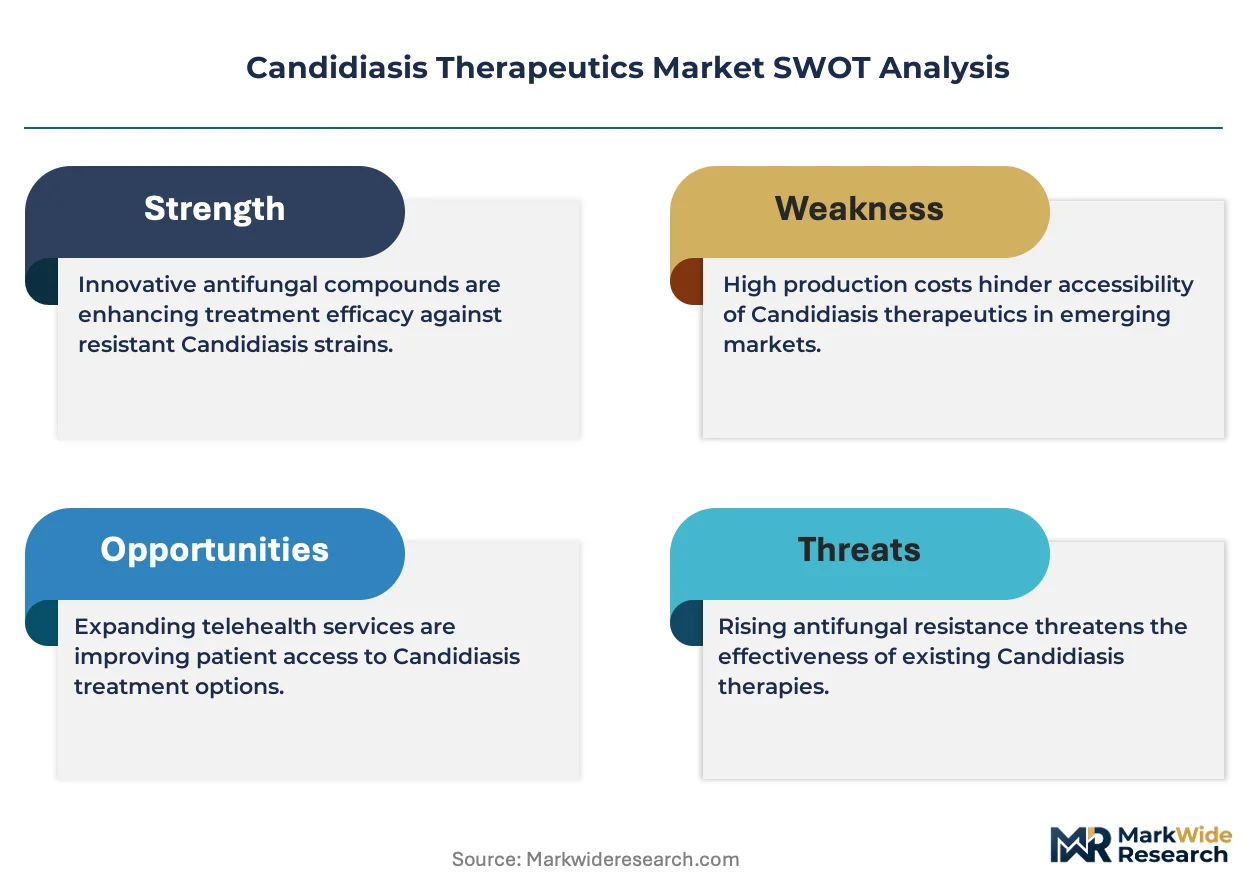
Candidiasis therapeutics comprise pharmaceutical agents that disrupt fungal cell membrane synthesis, cell wall integrity, or nucleic acid metabolism to eradicate Candida species infections. Echinocandins inhibit beta-1,3-D-glucan synthase with fungicidal activity against most Candida strains, serving as first-line therapy for invasive bloodstream infections. Azoles retain the largest revenue pool due to generic oral availability and prophylactic use, though resistance surveillance is intensifying. The invasive candidiasis therapy area commands premium pricing and intravenous administration routes, while vaginal indications drive volume through topical and oral azole generics.
FDA breakthrough therapy designation and EMA accelerated assessment pathways shape development timelines for novel antifungal classes. The FDA's Candida auris containment guidelines mandate reporting and infection control investments that expand diagnostic and therapeutic demand. EMA pharmacovigilance requirements for hepatotoxicity monitoring influence azole prescribing patterns across European hospitals. Stakeholders must monitor antifungal stewardship mandates and resistance surveillance networks to align pipeline investments with evolving standard-of-care protocols.
Market Dynamics
Hospital formulary consolidation is compressing vendor margins while immunocompromised patient volumes pull intravenous antifungal demand toward centralized procurement contracts.
Growth Catalysts
- FDA breakthrough therapy designation:Streamlined approval pathways accelerate novel echinocandin and triterpenoid candidates into clinical use, reducing development-to-commercialization timelines for resistant-strain therapies.
- Homecare infusion expansion:Stable candidemia patients transition from inpatient to ambulatory settings, creating pull-through demand for long-acting formulations and portable drug delivery systems.
- Candida auris containment protocols:Federal stockpiling mandates in outbreak clusters drive diagnostic and therapeutic procurement spikes across acute care networks.
Market Restraints
- Active pharmaceutical ingredient concentration:Azole precursor synthesis concentrates in Chinese and Indian contract manufacturers, exposing supply chains to geopolitical friction and export restriction risk.
- Echinocandin manufacturing complexity:Lipopeptide fermentation requires specialized bioreactor capacity that few CMOs maintain, limiting production elasticity during demand surges.
- Cross-resistance surveillance burden:EMA pharmacovigilance mandates for hepatotoxicity monitoring extend azole prescribing protocols, adding clinical workflow overhead that dampens utilization velocity.
Strategic Opportunities
- Weekly-dosing echinocandin conjugates:Long-acting formulations reduce infusion center visits and enable outpatient stewardship compliance in stable candidemia cases.
- Refractory vulvovaginal oral therapies:Triterpenoid antifungals address azole-resistant Candida glabrata isolates in ambulatory gynecology settings where topical generics fail.
- Antifungal stewardship mandates:Hospital accreditation requirements for resistance surveillance create attached demand for rapid diagnostic platforms and susceptibility testing services.
Industry Challenges
- Specialized mycology expertise scarcity:Clinical microbiology fellowship programs graduate fewer antifungal pharmacology specialists than hospital stewardship programs require.
- Legacy diagnostic platform integration:MALDI-TOF mass spectrometry systems require capital expenditure and workflow reconfiguration that smaller community hospitals defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Candidiasis Therapeutics Market |
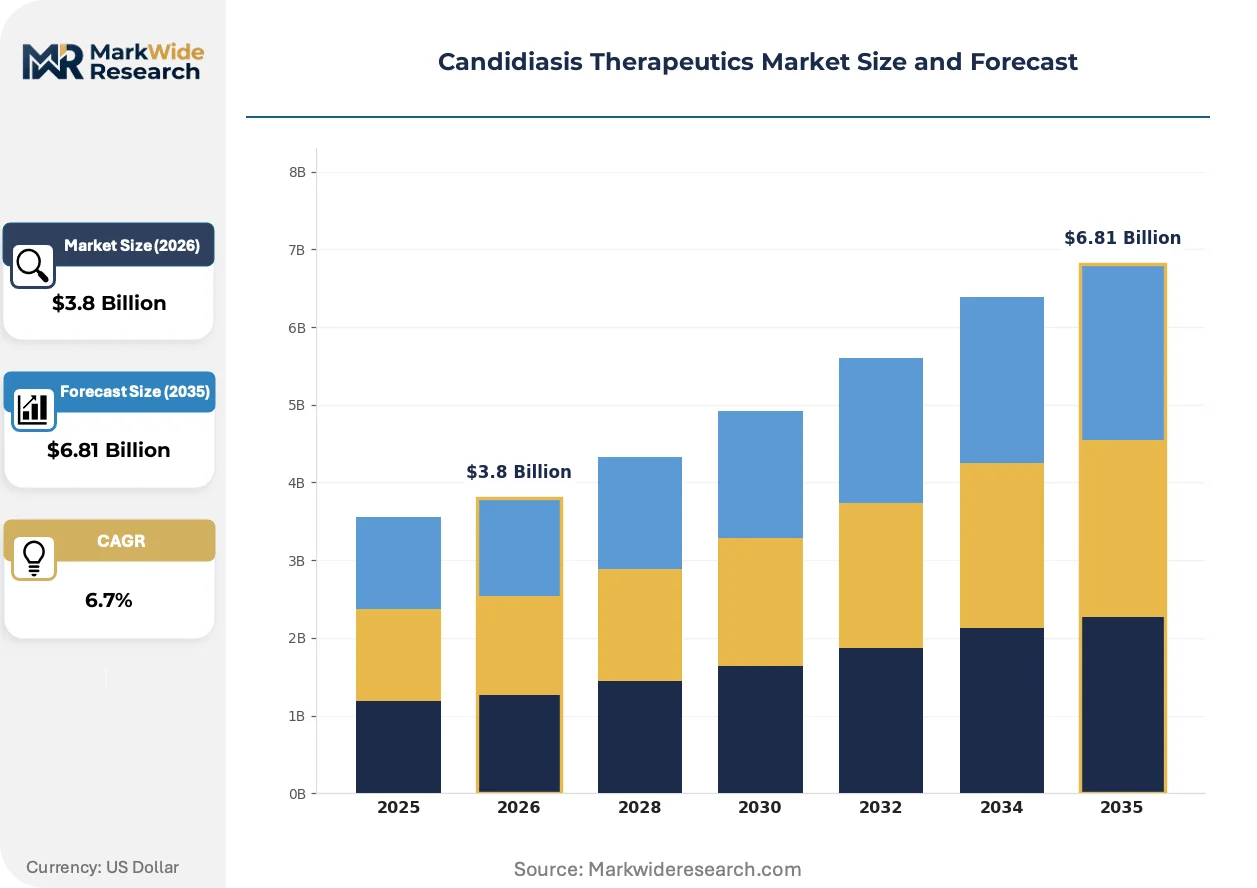
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Azoles, Echinocandins, Polyenes, Allylamines Therapy Area: Oropharyngeal, Esophageal, Invasive, Vaginal End User: Hospitals, Homecare, Laboratories, Clinics Administration Route: Oral, Intravenous, Topical, Inhalation |
| Companies Covered | Mycovia Pharmaceuticals, Inc., Cidara Therapeutics Inc., Pfizer Inc., Viatris Inc., Bayer AG, Astellas Pharma Inc., Basilea Pharmaceutica Ltd., Teva Pharmaceutical Industries Ltd., SCYNEXIS, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Candidiasis Therapeutics Market Emerging Trajectories
Antifungal development is pivoting toward resistance-agnostic mechanisms while hospital procurement models favor single-source contracts with manufacturing scale guarantees.
Long-acting echinocandin conjugates are displacing daily-dose intravenous caspofungin and micafungin in stable candidemia protocols. Oncology and transplant units at tertiary centers adopt weekly infusion regimens to reduce catheter-related complications and infusion center occupancy. This displacement compresses revenue per patient-day while expanding addressable patient volumes through outpatient eligibility.
EMA accelerated assessment pathways compress review timelines for novel antifungal classes addressing unmet resistance profiles. European hospital formularies prioritize agents with orphan drug designation for refractory invasive candidiasis, reshaping competitive positioning for developers with breakthrough-eligible pipelines. German and French reimbursement authorities now condition hospital tariff uplifts on antifungal stewardship compliance metrics.
Centralized hospital procurement is collapsing vendor relationships toward sole-source or dual-source contracts with volume guarantees. IDN pharmacy directors negotiate multi-year azole and echinocandin agreements that bundle diagnostic testing and susceptibility reporting. This concentration is most visible in United States health systems where Candida auris outbreak response funding ties procurement to federal stockpile replenishment cycles.
Candidiasis Therapeutics Market Segmentation
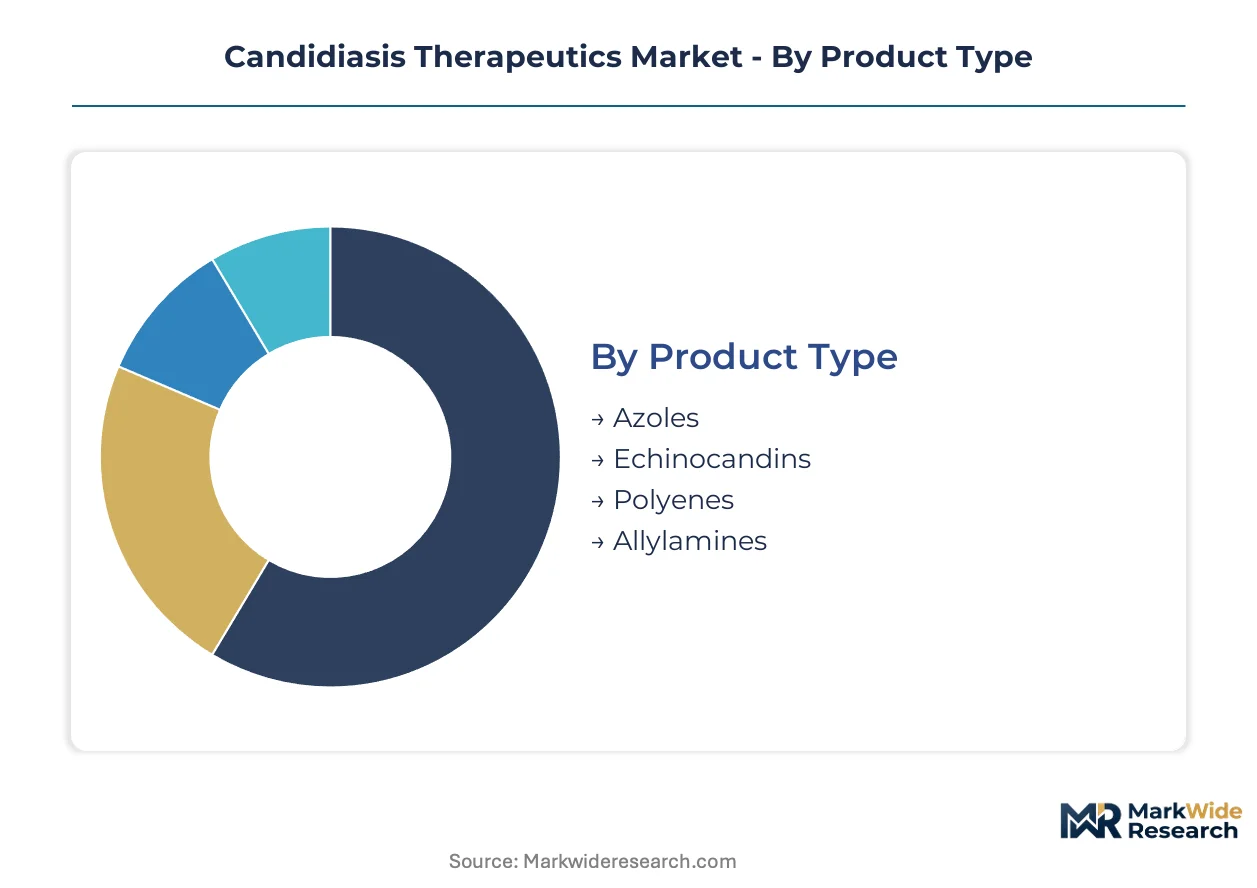
Therapeutic modality selection in candidiasis treatment hinges on infection site, resistance profile, and patient acuity. Segmentation reveals how hospital formulary consolidation and outpatient migration reshape demand concentration across administration routes and therapy areas.
Product Type:
FDA breakthrough therapy designation and EMA accelerated assessment pathways favor novel mechanisms, while generic azole availability sustains volume leadership in ambulatory settings.
- Azoles:Inhibit fungal CYP450-dependent ergosterol synthesis with broad-spectrum coverage. United States hospital procurement concentrates on fluconazole and voriconazole generics for prophylaxis, though Candida auris surveillance programs constrain empiric use.
- Echinocandins:Lipopeptide fermentation products that irreversibly inhibit beta-1,3-D-glucan synthase. Tertiary oncology centers in Germany and France prioritize caspofungin and micafungin for candidemia per EMA stewardship guidelines.
- Polyenes:Amphotericin B formulations retain niche use for azole-refractory mucormycosis coinfections.
- Allylamines:Terbinafine derivatives serve dermatophyte overlap cases with limited Candida-specific deployment.
Established volume favors azoles; emerging adoption favors echinocandins.
Therapy Area:
Site of infection determines reimbursement tiering and administration setting, with bloodstream involvement commanding premium intravenous protocols.
- Invasive:Candidemia and deep-seated candidiasis requiring intravenous echinocandin or liposomal amphotericin B. United States federal stockpiling mandates for Candida auris outbreak clusters concentrate demand in acute care networks with centralized procurement contracts.
- Vaginal:Recurrent vulvovaginal candidiasis drives oral fluconazole and topical azole volume. Ambulatory gynecology practices in Spain and Italy favor single-dose oral regimens for patient compliance.
- Oropharyngeal:HIV-associated and denture-related infections sustain topical nystatin and clotrimazole demand.
- Esophageal:Immunocompromised oncology patients require systemic therapy bridging oral and intravenous routes.
Revenue concentration sits with invasive indications; patient volume leadership belongs to vaginal therapy.
End User:
Care setting migration from inpatient to ambulatory channels reshapes distribution and service attachment requirements.
- Hospitals:Integrated delivery networks negotiate sole-source echinocandin contracts bundling susceptibility testing. German hospital tariff structures now condition reimbursement on antifungal stewardship compliance metrics.
- Homecare:Stable candidemia patients transition to ambulatory infusion centers. Long-acting formulations from Cidara Therapeutics enable weekly dosing protocols reducing catheter complications.
- Clinics:Community gynecology and infectious disease practices drive oral azole volume for uncomplicated infections.
- Laboratories:Reference labs and hospital microbiology units attach diagnostic and susceptibility testing services to therapeutic procurement.
Procurement authority concentrates in hospital pharmacy; growth velocity favors homecare expansion.
Administration Route:
Formulation technology and patient stability criteria determine route selection, with bioavailability and tissue penetration driving clinical preference.
- Intravenous:Echinocandins and liposomal amphotericin B require infusion center capacity. United States tertiary centers adopt weekly-dose echinocandin conjugates to reduce occupancy and catheter-related infections.
- Oral:Fluconazole and itraconazole bioavailability supports outpatient stewardship compliance. French and Italian reimbursement authorities favor oral step-down protocols reducing length-of-stay costs.
- Topical:Nystatin and clotrimazole formulations serve mucocutaneous indications with limited systemic absorption.
- Inhalation:Nebulized amphotericin B retains prophylactic use in lung transplant units with specialized aerosol delivery infrastructure.
Clinical standard favors intravenous initiation; cost pressure and patient preference drive oral conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical exports supply echinocandin formulations to French and Italian hospital networks, establishing a north-south trade corridor that shapes procurement patterns across continental Europe.
United States
Federal stockpiling mandates for Candida auris outbreak response concentrate hospital procurement in acute care networks. FDA breakthrough therapy designation accelerates novel antifungal approvals through streamlined review pathways. Tertiary oncology centers in Boston and Houston adopt weekly-dose echinocandin protocols to reduce catheter-related complications.
Germany
Hospital tariff structures condition reimbursement uplifts on antifungal stewardship compliance metrics, driving integrated delivery network consolidation. EMA pharmacovigilance requirements for hepatotoxicity monitoring reshape azole prescribing patterns. The Rhine-Ruhr pharmaceutical cluster anchors lipopeptide fermentation capacity for echinocandin manufacturing.
France
Reimbursement authorities favor oral step-down protocols that reduce length-of-stay costs for candidemia patients. ANSM oversight of hospital-acquired infection reporting intensifies diagnostic and therapeutic demand in outbreak clusters. Parisian academic medical centers pilot long-acting formulation protocols for stable ambulatory cases.
Japan
PMDA accelerated approval pathways for orphan-designated antifungals attract developers targeting refractory invasive candidiasis. METI industrial policy supports domestic bioreactor capacity expansion for lipopeptide production. The Kansai region's pharmaceutical manufacturing belt specializes in high-purity azole active pharmaceutical ingredient synthesis.
India
CDSCO regulatory harmonization with ICH guidelines accelerates clinical trial enrollment for novel antifungal classes. Contract manufacturing organizations in Hyderabad and Ahmedabad concentrate azole precursor production, exposing supply chains to export restriction risk. Domestic hospital networks expand immunocompromised patient volumes through oncology center expansion.
Candidiasis Therapeutics Market Vendor Landscape
Player mix skews toward diversified pharmaceutical conglomerates with intravenous manufacturing scale and specialized biotechnology developers with novel mechanism platforms. Market structure concentrates around hospital formulary contracts that bundle diagnostics, susceptibility testing, and therapeutic procurement. Two strategic archetypes dominate: scale-driven incumbents leveraging fermentation capacity and manufacturing scale, and mechanism innovators developing resistance-agnostic agents through long-acting or novel-target approaches. Competitive moves center on sole-source contract negotiation for integrated delivery networks and strategic partnerships bridging diagnostic platforms with therapeutic development.
Within the diversified pharmaceutical tier, Pfizer Inc. and Bayer AG exemplify scale-driven incumbents with intravenous azole and echinocandin manufacturing infrastructure. Among mechanism innovators, Cidara Therapeutics Inc. and SCYNEXIS, Inc. occupy positions anchored to long-acting lipopeptide conjugates and oral triterpenoid platforms respectively. These developers represent the resistance-agnostic archetype targeting refractory and ambulatory indications where generic azoles fail.
| Leading Market Players |
|---|
| Mycovia Pharmaceuticals, Inc. |
| Cidara Therapeutics Inc. |
| Pfizer Inc. |
| Viatris Inc. |
| Bayer AG |
| Astellas Pharma Inc. |
| Basilea Pharmaceutica Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| SCYNEXIS, Inc. |
| Others |
Supply Flow & Price Mechanics
Ninety-day safety stock requirements for lipopeptide fermentation feedstocks concentrate pricing power among echinocandin manufacturers with captive bioreactor capacity, while azole precursor volatility exposes formularies to spot-market swings. Hospital procurement officers negotiate multi-year contracts that bundle susceptibility testing to lock in volume guarantees against supply interruption.
Pricing Analysis
Next-generation weekly-dosing echinocandin conjugates command premium positioning against daily-dose caspofungin and micafungin, while generic fluconazole and voriconazole anchor economy tiers. Three-tier pricing structure across premium novel agents, standard-of-care echinocandins, and economy azole generics reflects FDA breakthrough designation status and manufacturing complexity. Pricing pressure stems from integrated delivery network formulary consolidation bundling diagnostics with therapeutic procurement. Community hospital systems exhibit highest price sensitivity due to capital constraints on MALDI-TOF mass spectrometry infrastructure.
Supply Chain Analysis
Seventy-five-day lead times for lipopeptide fermentation capacity constrain production elasticity during Candida auris outbreak surges. Active pharmaceutical ingredient synthesis concentrates in India and China for azole precursors, while Germany and Japan anchor echinocandin bioreactor infrastructure. Raw material dependencies include fermentation media, specialized resins for chromatographic purification, and high-purity solvents. Single-source vulnerability pervades lipopeptide contract manufacturing organization capacity. Distribution runs through hospital pharmacy and integrated delivery network procurement channels with attached diagnostic service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antifungal stewardship platform economics are shifting toward diagnostic-therapeutic interoperability, with rapid susceptibility testing integration creating ecosystem lock-in for integrated delivery networks that bundle procurement across formulary tiers.
For Market Incumbents: Fortify hospital formulary position through backward integration into lipopeptide fermentation capacity and diagnostic platform partnerships that bundle susceptibility testing with echinocandin contracts. Cidara Therapeutics' weekly-dosing conjugate architecture threatens daily-dose incumbents through outpatient eligibility expansion. Priority lever rests on securing sole-source agreements with oncology and transplant centers that condition accreditation compliance on bundled stewardship services. For New Entrants and Emerging Players: Lead with resistance-agnostic mechanisms targeting refractory vulvovaginal indications where azole generics fail, exploiting the white space between topical clotrimazole and systemic echinocandin therapy. Ambulatory gynecology practices in Southern Europe present lowest competitive density for oral triterpenoid penetration. Go-to-market angle centers on single-dose oral regimens that displace multi-day fluconazole compliance failures. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-pharma consolidation play because hospital formulary concentration favors scale-driven incumbents with manufacturing guarantees and diagnostic bundling capabilities. Acquisition target archetype includes biotechnology developers with FDA breakthrough-designated long-acting formulations and orphan drug positioning for refractory invasive candidiasis. Signal to watch is integrated delivery network pharmacy director turnover correlating with sole-source contract renegotiation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation accelerates novel echinocandin candidates past standard review timelines. |
| Manufacturing Scale-Up | Lipopeptide fermentation capacity expansion in German and Japanese bioreactor clusters secures outbreak response supply. |
| Hospital System Partnership | Sole-source formulary contracts bundle susceptibility testing with echinocandin procurement across oncology networks. |
| Pipeline Diversification | Resistance-agnostic triterpenoid platforms address azole-refractory Candida glabrata in ambulatory gynecology settings. |
| Reimbursement Strategy | EMA pharmacovigilance compliance metrics now condition German hospital tariff uplifts on stewardship adherence. |
Methodological Framework
A standing panel of hospital pharmacy directors, infectious disease clinicians, formulary procurement managers, and antifungal stewardship officers provided ongoing calibration across primary fieldwork and secondary validation. FDA filings, EMA assessment reports, ClinicalTrials.gov protocols, and hospital procurement database extracts supplied quantitative anchors. Bottom-up patient-volume modeling triangulated against top-down pharmaceutical revenue segmentation across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs before finalization. The analytical framework disaggregated demand by therapeutic modality, infection site severity, administration route, and regional regulatory cluster across the projection horizon. CAGRs derived from log-linear trend fitting adjusted for patent expiry curves and generic entry assumptions. Forecast inputs incorporated immunocompromised patient volume trajectories and Candida auris outbreak surveillance frequency.
The analysis sits within stated boundaries; outcomes outside sustained immunosuppression prevalence trends or stable regulatory approval pathways would require recalibration. Forecasts reflect documented assumptions regarding hospital formulary consolidation velocity and diagnostic platform adoption rates. Antifungal resistance surveillance network expansion or export restriction events on azole precursors could materially revise trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Parenteral Drugs Market
Pharmaceuticals
Calcimimetic Market
Pharmaceuticals
North America Meglitinide Market
Pharmaceuticals
Plasma-Derived Drugs Market
Pharmaceuticals
Sleeping Medications Market
Pharmaceuticals
Lipid-Lowering Drugs Market
Pharmaceuticals
Anti-Inflammatory Analgesic and Antipyretic Drugs Market
Pharmaceuticals
Oral Vaccines Market
Pharmaceuticals
Global Pharmaceuticals Market
Pharmaceuticals
GCC Generic Injectables Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Migraine Drugs Market
Pharmaceuticals
Middle East and Africa Adenomyosis Drugs Market
Pharmaceuticals
Unit-Dose Respiratory Medications Market
Pharmaceuticals
Global Prefilled Syringes Drug Molecules Market
Pharmaceuticals
Glucagon-Like Peptide-1 (GLP-1) Agonists Market