
 Global Immunomodulators Market | 2026-2036
Global Immunomodulators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Immunomodulators Market Foresight
The EU Green Deal's pharmaceutical sustainability criteria is restructuring procurement standards across European hospital networks. Bristol-Myers Squibb Company leverages its integrated biologics manufacturing footprint to supply checkpoint inhibitors at scale. Novartis AG anchors its position through cytokine engineering capabilities in Basel. F. Hoffmann-La Roche Ltd. dominates the monoclonal antibody segment with proprietary cell-line development platforms.
Immunomodulators are biologically active agents that amplify, suppress, or redirect immune responses through receptor binding, cytokine signaling, or pathway blockade, typically manufactured via mammalian cell culture with purity thresholds exceeding 95% for therapeutic-grade proteins. Their primary purpose is to treat autoimmune dysfunction, prevent graft rejection, or mobilize anti-tumor immunity in clinical settings. Monoclonal antibodies command the largest revenue pool due to established reimbursement and manufacturing maturity, while immune checkpoint inhibitors represent the fastest-expanding category as PD-1 and CTLA-4 mechanisms penetrate earlier lines of oncology therapy. The autoimmune disorders therapy area sustains the broadest prescriber base, though oncology applications generate the highest per-patient value.
The FDA's breakthrough therapy designation and the EMA's PRIME scheme together compress regulatory review timelines for novel immunomodulators, while WHO prequalification requirements shape access pathways in low-income markets. China's NMPA has aligned its biologics approval standards with ICH guidelines, accelerating multinational trial inclusion. Stakeholders must monitor evolving pharmacovigilance obligations for cytokine release syndrome as combination immunotherapy protocols expand beyond controlled trial settings.
Market Dynamics
The FDA's breakthrough therapy designation is compressing development timelines for novel immunomodulators while academic medical centers expand immuno-oncology protocols, creating simultaneous pull from regulatory acceleration and clinical infrastructure investment.
Growth Catalysts
- Regulatory Acceleration:The FDA's accelerated approval pathway and EMA's PRIME scheme compress review timelines for checkpoint inhibitors and cytokine therapies. Oncology departments at academic medical centers are expanding immunotherapy protocols in response.
- Clinical Infrastructure:The National Cancer Institute funds the majority of immuno-oncology clinical trials in the United States, concentrating demand for PD-1 and CTLA-4 mechanism drugs.
- Manufacturing Scale:Integrated biologics manufacturing footprints enable supply of therapeutic-grade proteins at purity thresholds exceeding 95% through mammalian cell culture expansion.
Market Restraints
- Input Cost Volatility:Cell culture media components and single-use bioreactor systems face supply concentration among German and Swiss specialty chemical suppliers.
- Technical Limitation:Cytokine release syndrome monitoring requirements constrain combination immunotherapy protocol expansion beyond controlled trial settings.
- Regulatory Friction:WHO prequalification requirements create separate compliance pathways for low-income market access, duplicating documentation burdens.
Strategic Opportunities
- Underpenetrated Geography:China's NMPA alignment with ICH guidelines accelerates multinational trial inclusion for biologics approval standards.
- Emerging Application:Earlier-line oncology therapy penetration for immune checkpoint inhibitors expands addressable patient populations beyond refractory settings.
- Technology Convergence:Cytokine engineering capabilities are integrating with proprietary cell-line development platforms to shorten therapeutic protein development cycles.
Industry Challenges
- Specialized Manufacturing Talent:Mammalian cell culture process development and analytical method validation for immunomodulators require scarce bioprocessing engineering expertise.
- Capex Intensity:GMP-compliant biologics manufacturing facilities demand substantial capital deployment for containment infrastructure and quality control systems.
- Pharmacovigilance Complexity:Evolving obligations for cytokine release syndrome reporting across combination therapy protocols strain post-market surveillance systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Immunomodulators Market |
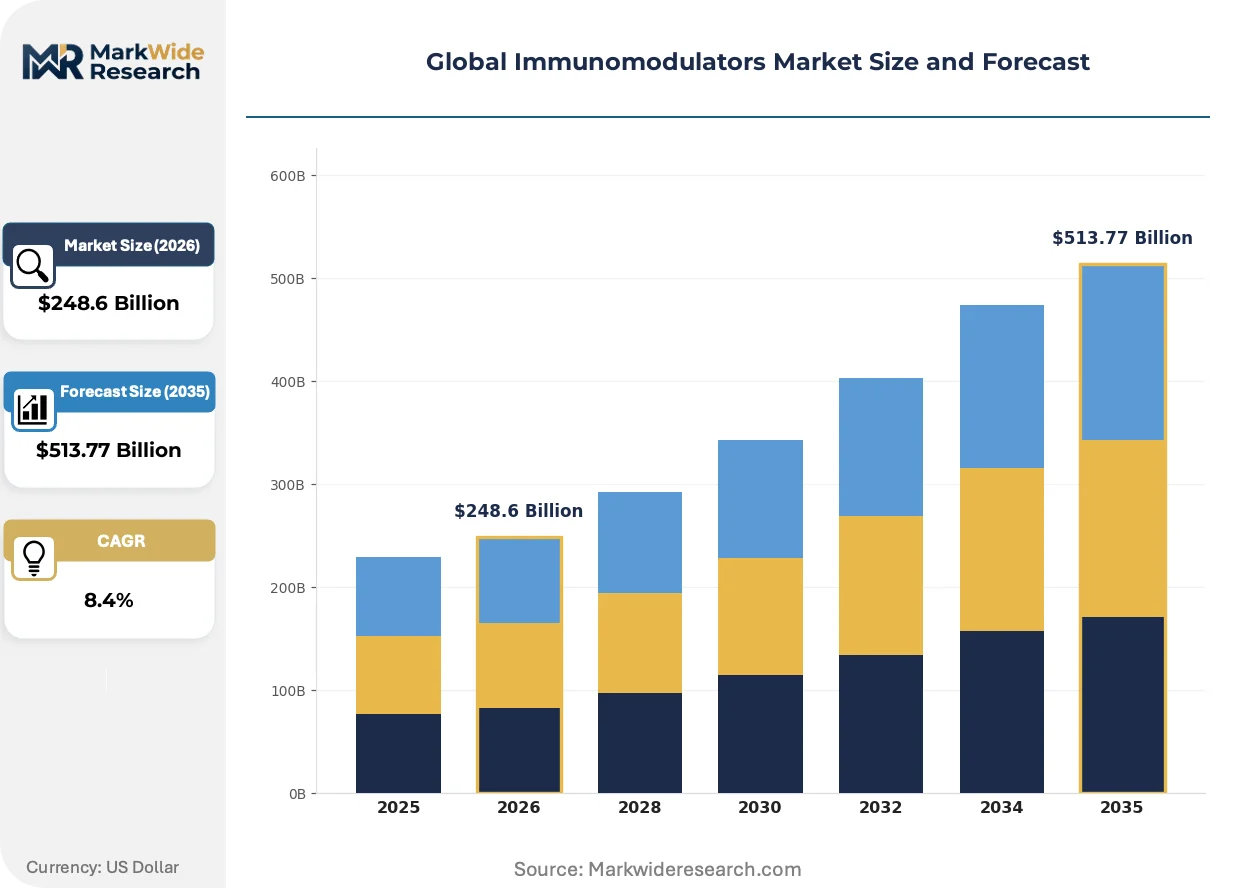
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $513.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Cytokines, Immunosuppressants, Immune Checkpoint Inhibitors, Vaccines Therapy Area: Autoimmune Disorders, Transplantation, Oncology, Infectious Diseases, Allergic Conditions End User: Specialty Clinics, Research Institutions, Dialysis Centers, Home Healthcare Providers, Diagnostic Labs Delivery Mode: Intravenous, Subcutaneous, Oral, Intramuscular, Topical |
| Companies Covered | F. Hoffmann-La Roche Ltd., Novartis AG, Biogen Inc., Teva Pharmaceutical Industries Ltd., Amgen Inc., Bristol-Myers Squibb Company, Merck Sharp & Dohme Corp., Eli Lilly and Company, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Immunomodulators Market Shifts & Advancements
Bi-specific antibody engineering and next-generation cytokine platforms are compressing the gap between discovery and clinical validation, while procurement criteria increasingly weight sustainability metrics alongside efficacy endpoints.
Multi-specific antibody formats are unifying target engagement strategies by simultaneously binding tumor antigens and T-cell receptors. Academic medical centers in the United States and university hospital networks in Germany are adopting these platforms for hematologic malignancy protocols. This convergence is unifying previously separate development tracks for CAR-T and checkpoint inhibitor programs into integrated immuno-oncology pipelines.
REACH regulation amendments and the EU Green Deal's pharmaceutical sustainability criteria are restructuring procurement standards across European hospital networks. Active pharmaceutical ingredient sourcing disclosures and carbon footprint thresholds now gate supplier qualification for monoclonal antibody contracts. German and French hospital purchasing consortia have advanced these requirements fastest, compressing supplier compliance timelines.
Academic medical center procurement departments are consolidating immunomodulator purchasing through centralized biologics tenders with outcome-linked pricing provisions. United States-based oncology networks and Swiss university hospitals have shifted from product-specific contracts to category-managed agreements with integrated distribution. This concentration is most visible in checkpoint inhibitor procurement, where three-tier pricing structures separate premium branded biologics from biosimilar alternatives and investigational access programs.
Global Immunomodulators Market Segmentation
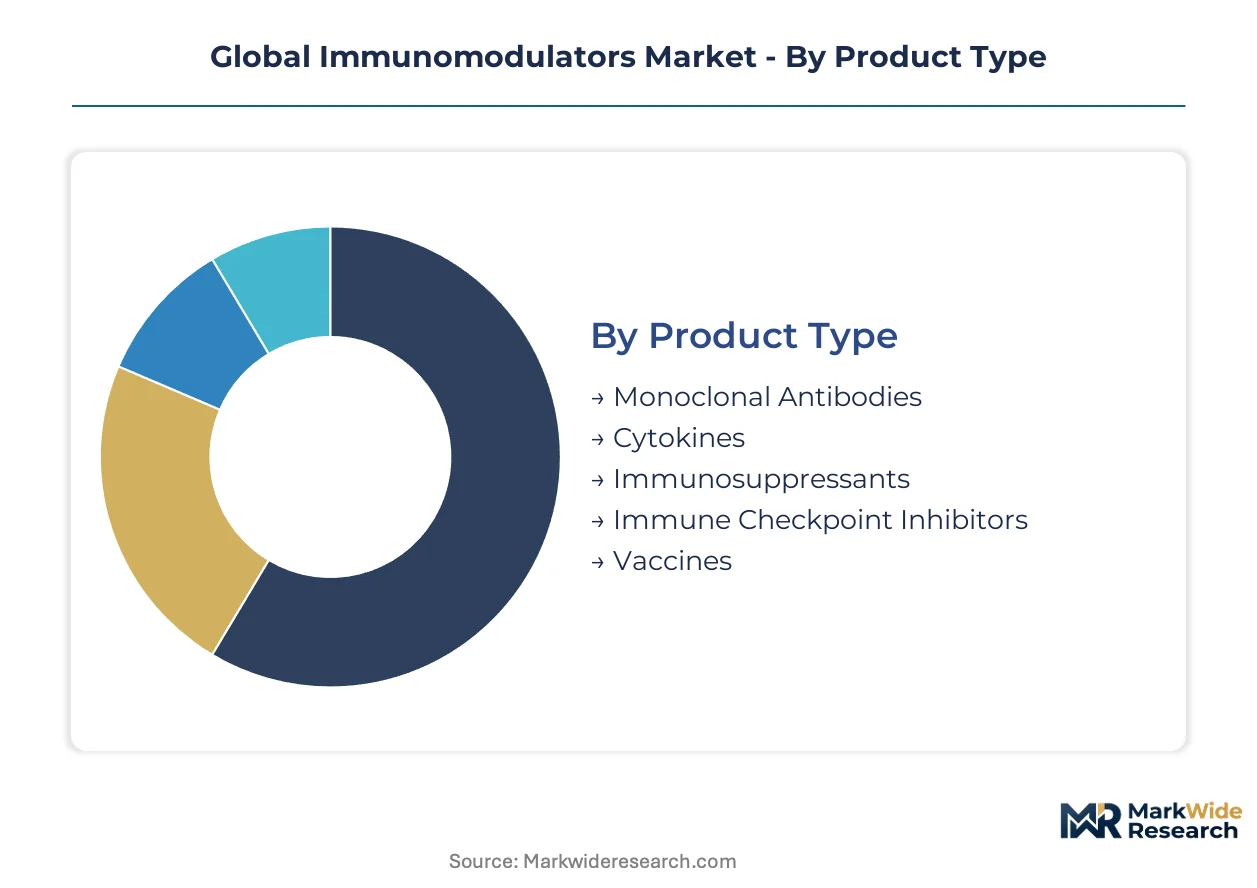
Immunomodulator segmentation reveals distinct manufacturing requirements, reimbursement pathways, and clinical deployment models across product architectures. Category boundaries increasingly blur as bi-specific formats and cytokine-antibody fusions enter development pipelines.
Product Type:
Standalone biologic platforms dominate high-value oncology applications while combination-ready formats embed into multi-agent protocols.
- Monoclonal Antibodies:These Y-shaped immunoglobulins bind single epitopes with high specificity, manufactured via Chinese hamster ovary cell culture at therapeutic-grade purity thresholds. Demand concentrates in United States academic medical centers where the National Cancer Institute funds the majority of immuno-oncology clinical trials, driven by established reimbursement codes and manufacturing maturity.
- Immune Checkpoint Inhibitors:PD-1 and CTLA-4 pathway blockers mobilize anti-tumor immunity by disrupting T-cell exhaustion signals. United States oncology departments are expanding earlier-line therapy protocols, compressing development timelines through the FDA's breakthrough therapy designation.
- Cytokines:Engineered interleukins and interferons amplify immune signaling through receptor binding cascades. Novartis AG anchors its position through cytokine engineering capabilities in Basel.
- Immunosuppressants:Small-molecule and biologic agents suppress graft rejection and autoimmune flare-ups. Transplantation protocols in German university hospital networks sustain procurement volume.
- Vaccines:Prophylactic and therapeutic immunomodulators prime adaptive immune responses. WHO prequalification requirements shape access pathways in low-income markets.
Volume placements concentrate in monoclonal antibodies; the faster expansion belongs to immune checkpoint inhibitors.
Therapy Area:
Cost tier stratification separates chronic management indications from acute intervention protocols.
- Oncology:Immuno-oncology applications generate the highest per-patient value through checkpoint inhibitor and CAR-T combination protocols. The FDA's accelerated approval pathway compresses regulatory review timelines for novel mechanisms.
- Autoimmune Disorders:Rheumatoid arthritis, multiple sclerosis, and inflammatory bowel disease sustain the broadest prescriber base through chronic administration models. United States specialty clinics and dialysis centers anchor demand.
- Transplantation:Graft-versus-host disease prophylaxis and rejection management require lifelong immunosuppression. Swissmedic and EMA pharmacovigilance frameworks govern post-market surveillance obligations.
- Infectious Diseases:Therapeutic vaccines and adjunct immunomodulators address persistent viral reservoirs. China's NMPA alignment with ICH guidelines accelerates multinational trial inclusion.
- Allergic Conditions:Desensitization protocols and IgE pathway modulation serve pediatric and adult populations. Home healthcare providers in France and Germany administer subcutaneous formulations.
Revenue concentration sits with oncology; autoimmune disorders deliver the most stable placement volume.
End User:
Customer type determines distribution infrastructure, cold-chain requirements, and outcome-linked contracting structures.
- Specialty Clinics:Outpatient infusion centers administer intravenous biologics under rheumatology, dermatology, and gastroenterology protocols. United States-based oncology networks have shifted to category-managed agreements with integrated distribution.
- Research Institutions:Academic medical centers conduct investigator-initiated trials and early-phase combination studies. The National Cancer Institute funds the majority of immuno-oncology clinical trials in the United States.
- Dialysis Centers:End-stage renal disease patients receive immunosuppressants and adjunct therapies during scheduled sessions. Procurement runs through hospital purchasing consortia.
- Home Healthcare Providers:Subcutaneous and oral immunomodulators enable self-administration outside clinical settings. German and French hospital purchasing consortia have advanced sustainability requirements fastest.
- Diagnostic Labs:Companion diagnostic testing guides patient selection for targeted immunotherapy. CDSCO and NMPA oversight governs test-kit approval pathways.
Procurement scale concentrates in specialty clinics; research institutions drive the steepest expansion trajectory for novel formats.
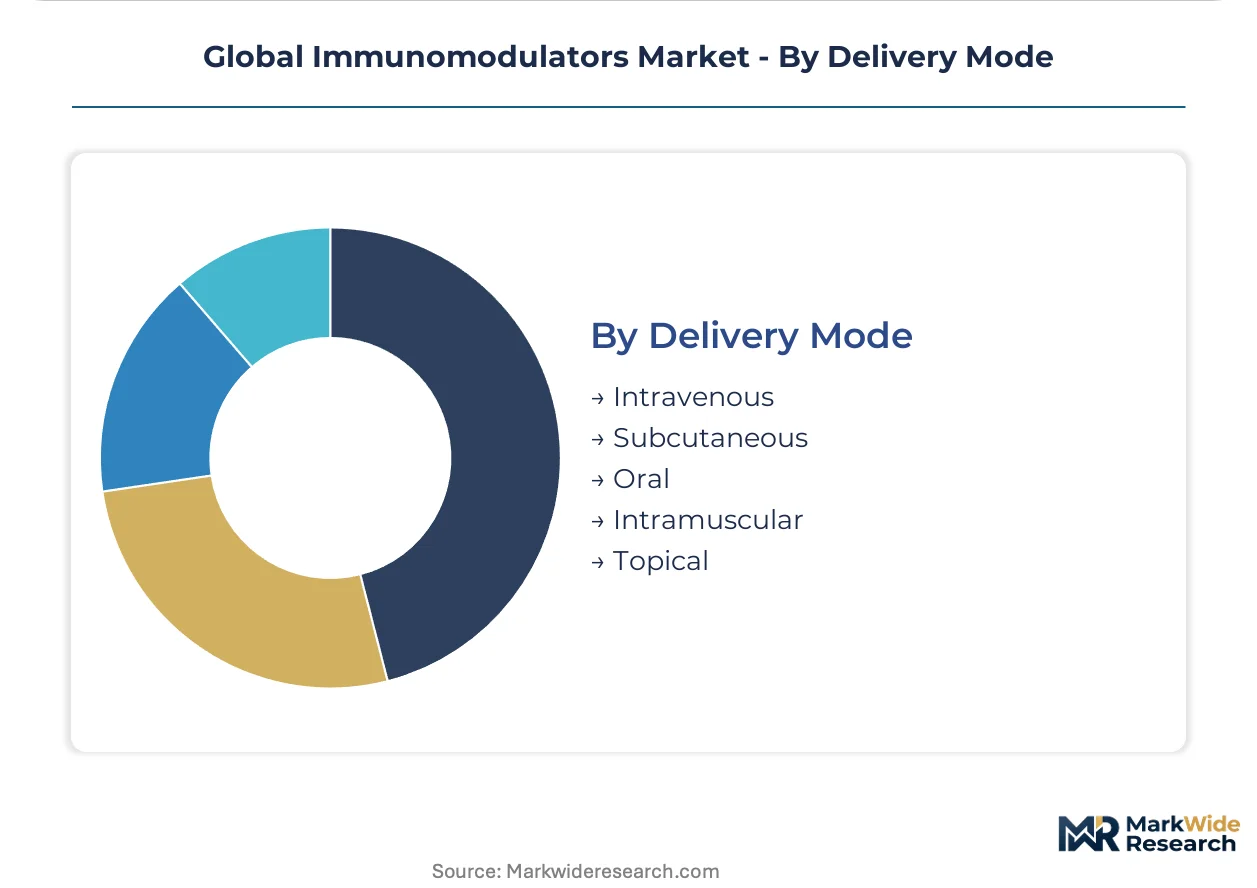
Delivery Mode:
Supply concentration in parenteral formats reflects manufacturing complexity and bioavailability constraints.
- Intravenous:Large-volume monoclonal antibody infusions require hospital-grade infusion infrastructure and nursing supervision. United States academic medical centers and university hospital networks in Germany anchor demand.
- Subcutaneous:Pre-filled syringes and auto-injectors enable outpatient and home administration. F. Hoffmann-La Roche Ltd. dominates this segment with proprietary cell-line development platforms.
- Oral:Small-molecule immunosuppressants offer patient convenience for chronic autoimmune management. Bristol-Myers Squibb Company leverages integrated manufacturing footprints for supply at scale.
- Intramuscular:Vaccine adjuvants and depot formulations sustain prolonged immune modulation. WHO prequalification requirements create separate compliance pathways for low-income market access.
- Topical:Localized immunomodulation for dermatologic conditions minimizes systemic exposure. EMA's PRIME scheme accelerates review for breakthrough topical biologics.
Manufacturing maturity concentrates in intravenous delivery; subcutaneous platforms are climbing the fastest as home administration expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area and Kendall Square biotechnology corridor concentrate the world's densest cluster of immuno-oncology clinical trial operations, anchoring demand for checkpoint inhibitors and cytokine engineering platforms across North America and beyond.
United States
The National Cancer Institute funds the majority of immuno-oncology clinical trials through academic medical centers in Boston, New York, and San Francisco. FDA breakthrough therapy designation compresses regulatory review timelines for PD-1 and CTLA-4 mechanism drugs. Maryland's I-270 biotechnology corridor houses concentrated analytical testing and companion diagnostic development facilities serving these protocols.
Germany
University hospital networks in Heidelberg, Munich, and Berlin sustain procurement volume for transplantation immunosuppressants and autoimmune biologics. EMA's PRIME scheme accelerates review for novel cytokine therapies originating from Basel-adjacent research operations. The Rhine-Main biopharma manufacturing belt hosts mammalian cell culture facilities supplying therapeutic-grade proteins at purity thresholds exceeding 95 percent.
Switzerland
Basel anchors cytokine engineering capabilities and proprietary cell-line development platforms serving global monoclonal antibody supply. Swissmedic pharmacovigilance frameworks govern post-market surveillance obligations for cytokine release syndrome reporting. The Greater Basel Area biologics manufacturing cluster integrates with German and French hospital purchasing consortia advancing EU Green Deal sustainability criteria.
China
Shanghai and Beijing academic medical centers expand investigator-initiated trials for combination immunotherapy protocols. NMPA alignment with ICH guidelines accelerates multinational trial inclusion for biologics approval standards. The Yangtze River Delta biopharma manufacturing zone scales mammalian cell culture capacity for domestic and export markets.
United Kingdom
London and Cambridge immuno-oncology research institutes drive early-phase combination studies for bi-specific antibody formats. MHRA operates under retained EU recognition agreements while developing independent pharmacovigilance frameworks. The Golden Triangle biotech cluster concentrates CAR-T and checkpoint inhibitor pipeline development across Oxford, Cambridge, and London.
Global Immunomodulators Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory sophistication and manufacturing scale, with integrated biologics footprints commanding pricing power over outsourced development models. The market structure concentrates around three strategic tiers: multinational pharmaceutical conglomerates with cell-line platforms, mid-cap specialists in cytokine engineering, and emerging biotechs licensing discovery assets. Consolidation pressures favor backward integration into mammalian cell culture capacity and captive supply of single-use bioreactor systems. Strategic partnerships between Basel-based engineering specialists and United States clinical trial networks compress development timelines.
Within the integrated multinational tier, F. Hoffmann-La Roche Ltd. and Novartis AG exemplify divergent platform strategies, with the former dominating monoclonal antibody cell-line development and the latter anchoring cytokine engineering capabilities. Bristol-Myers Squibb Company occupies a position at the intersection of immuno-oncology protocol expansion and manufacturing scale. These three entities represent distinct competitive archetypes: proprietary platform dominance, engineering specialization, and integrated supply chain control.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| Biogen Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Amgen Inc. |
| Bristol-Myers Squibb Company |
| Merck Sharp & Dohme Corp. |
| Eli Lilly and Company |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
Academic medical center procurement departments in the United States and German university hospital networks concentrate purchasing power through centralized biologics tenders, anchoring a value-based pricing model where reimbursement ties to progression-free survival endpoints in oncology protocols.
Pricing Analysis
Value-based pricing anchors the immunomodulator market through outcome-linked contracts that tie payment to patient response metrics in checkpoint inhibitor therapy. Three-tier pricing structure across premium branded biologics, biosimilar alternatives, and investigational access programs separates FDA breakthrough-designated therapies from follow-on entrants. Pricing pressure stems from biosimilar entry into monoclonal antibody categories as European hospital purchasing consortia consolidate volume. Research institutions demonstrate lowest price sensitivity due to grant-funded trial budgets, while dialysis centers face highest sensitivity from fixed reimbursement schedules.
Supply Chain Analysis
FDA and EMA GMP certification gates supplier qualification for therapeutic-grade proteins, with mammalian cell culture capacity concentrating in Switzerland, Germany, and the United States. Single-use bioreactor systems and cell culture media components draw from German and Swiss specialty chemical suppliers, creating concentrated input dependencies. Single-source vulnerability runs through Chinese heparin and Indian active pharmaceutical ingredient suppliers for immunosuppressant categories. Distribution runs through cold-chain logistics providers serving hospital networks and specialty infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mammalian cell culture capacity scarcity props pricing power for incumbent manufacturers, with GMP-compliant facility buildout timelines extending 4-6 years and constraining supply expansion.
For Market Incumbents: Extend cell-line platform dominance through captive supply of single-use bioreactor systems and backward integration into media component production. Consolidation of cytokine engineering capabilities in Basel-adjacent clusters defends against emerging biotech licensing threats. Capacity addition in the Yangtze River Delta addresses Chinese market access requirements. For New Entrants and Emerging Players: NMPA alignment with ICH guidelines in China opens a window for multinational trial inclusion without redundant regulatory filings. Target earlier-line oncology therapy penetration for immune checkpoint inhibitors where prescriber adoption curves remain steep. Partner with United States academic medical center networks for investigator-initiated trial sponsorship as go-to-market entry. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap cytokine engineering specialists with proprietary platform assets in Switzerland and Germany. Long-term viability hinges on manufacturing scale rather than discovery-stage pipelines alone. Watch FDA breakthrough therapy designation velocity as inflection indicator for portfolio rebalancing toward regulatory-accelerated assets.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | GMP-compliant biologics facilities in the Rhine-Main belt supply checkpoint inhibitors at 95% purity thresholds. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses review timelines for PD-1 mechanism drugs in earlier-line protocols. |
| Licensing Agreement | Strategic partnerships between Basel engineering specialists and Boston clinical trial networks accelerate development cycles. |
| Pipeline Diversification | Bi-specific antibody formats unify CAR-T and checkpoint inhibitor development tracks into integrated pipelines. |
| Clinical Trial Advancement | National Cancer Institute funding concentrates immuno-oncology trial operations in Longwood Medical Area and Kendall Square. |
Research Methodology
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from SEC 10-K disclosures, WHO prequalification registries, and EU Green Deal pharmaceutical sustainability criteria documentation. Bottom-up patient-flow modeling and top-down revenue triangulation anchored market size estimation.
Segment-level outputs across product type, therapy area, end user, and delivery mode dimensions fed into analytical frameworks spanning the projection horizon. CAGRs derived from patient population epidemiology, treatment penetration curves, and pricing trajectory assumptions. Forecast inputs incorporated cytokine release syndrome incidence rates and combination protocol expansion timelines.
The model assumes a particular technology adoption path for next-generation cytokine platforms; alternative pathways for CAR-T manufacturing automation would alter the capacity expansion outlook. Forecasts reflect documented assumptions regarding regulatory acceleration and reimbursement stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Zika Vaccines Market
Pharmaceuticals
Live Attenuated Vaccines Market
Pharmaceuticals
Europe Contraceptives Market
Pharmaceuticals
Global Acyclovir Market
Pharmaceuticals
Respiratory Virus Infection Drug Market
Pharmaceuticals
Middle East and Africa Adenomyosis Drugs Market
Pharmaceuticals
Contraceptive Drugs Market
Pharmaceuticals
Bipolar Disorder Drugs and Treatment Market
Pharmaceuticals
Europe Meglitinide Market
Pharmaceuticals
Gardasil (HPV Vaccine) Market
Pharmaceuticals
Bevacizumab Market
Pharmaceuticals
Calcineurin Inhibitor Drugs Market
Pharmaceuticals
Global Benzodiazepines Market
Pharmaceuticals
Cancer Therapeutics and Biotherapeutics Market
Pharmaceuticals
Small Volume Parenteral Market
Pharmaceuticals
Global Orphan Drugs Market