
 Global Manidipine Hydrochloride Market | 2026-2036
Global Manidipine Hydrochloride Market Size, Share, and Industry Trends Forecast 2026-2036
Global Manidipine Hydrochloride Market Foresight
India is rewriting competitive dynamics in manidipine hydrochloride production as API contract manufacturers expand batch capacity for export markets. JEIL PHARMACEUTICAL anchors Korean formulation expertise through backward integration into intermediate synthesis. Metrochem API Private Limited leverages its Hyderabad manufacturing base to supply regulated markets with cost-optimized dihydropyridine chemistry. Manus Aktteva Biopharma LLP specializes in niche documentation packages that accelerate customer qualification with European buyers.
Manidipine hydrochloride is a dihydropyridine calcium channel blocker with the molecular formula C35H38N4O6·HCl, functioning as a selective vasodilator that inhibits L-type calcium channels in vascular smooth muscle to reduce peripheral resistance and lower blood pressure. The compound is synthesized through multi-step organic chemistry involving condensation, cyclization, and salt formation, with final purity specifications typically exceeding 99.5% to meet pharmacopeial standards for pharmaceutical-grade APIs. Tablet formulations dominate current revenue as established hypertension therapies maintain prescriber familiarity, while extended-release delivery systems represent the fastest-expanding segment as developers pursue improved patient compliance and reduced dosing frequency. Specialty pharmacies occupy concentrated margin pools through direct-to-patient distribution of branded cardiovascular therapies.
The FDA, EMA, and CDSCO collectively shape market access through divergent impurity profiling requirements and ICH Q3D elemental impurity guidelines that dictate analytical investment levels. India's BIS certification and the EU's REACH framework for chemical substances further constrain raw material sourcing flexibility for manufacturers serving multiple jurisdictions. Stakeholders must monitor evolving pharmacopeial monograph revisions and bioequivalence study expectations as regulatory convergence around impurity thresholds accelerates competitive differentiation based on analytical capability.
Market Dynamics
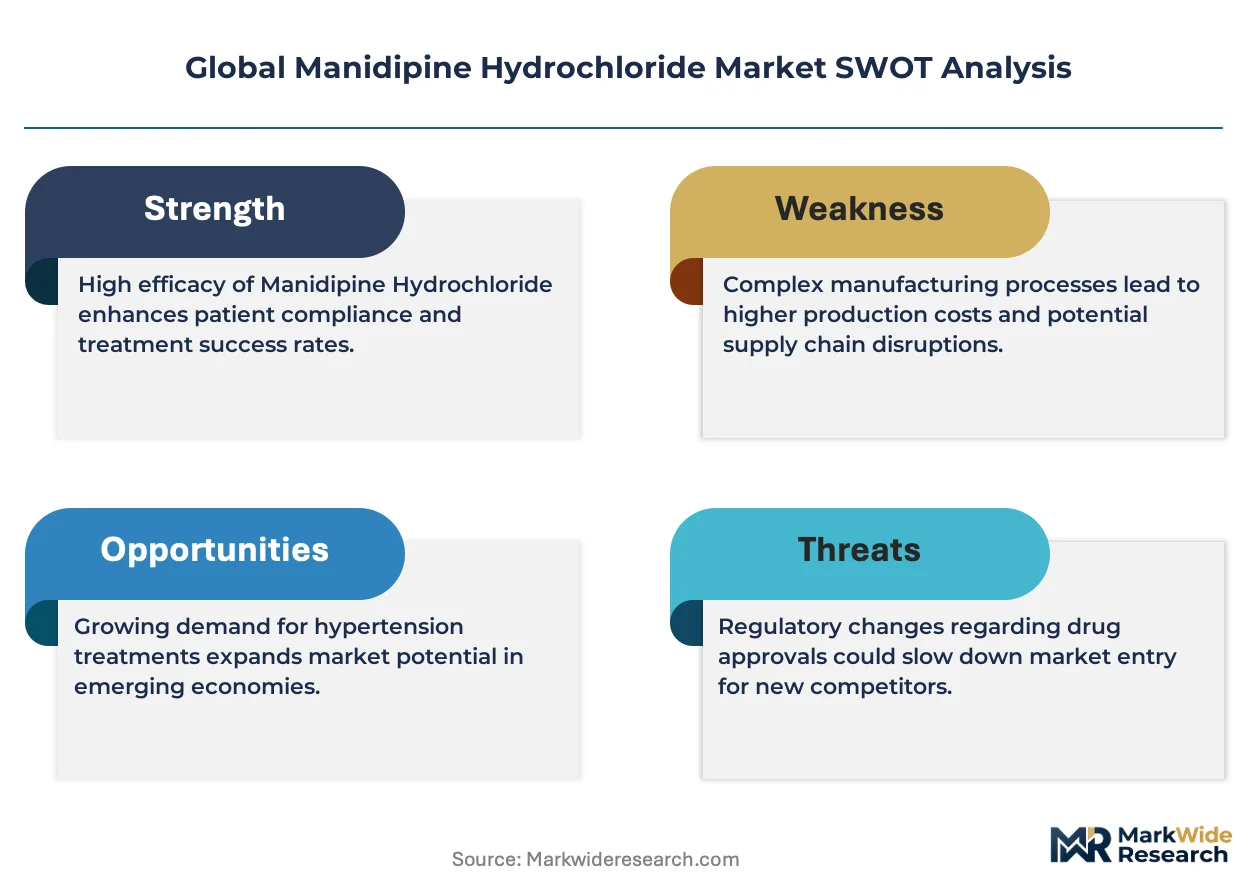
Pharmaceutical manufacturers face mounting pressure from divergent impurity profiling requirements across FDA, EMA, and CDSCO jurisdictions, forcing API producers to layer redundant quality systems onto single manufacturing lines. This regulatory fragmentation is concentrating investment among specialists capable of multi-pharmacopeia compliance.
Growth Catalysts
- Chronic hypertension prevalence:Aging demographics in Japan and South Korea expand the addressable patient population for calcium channel blocker therapies. Hospital formularies in these markets prioritize established dihydropyridine compounds with proven safety profiles.
- REACH framework adaptation:European chemical substance regulations are compelling API manufacturers to document full supply chain substance volumes. This creates competitive moats for producers with existing European regulatory dossiers.
- Continuous flow chemistry:Adoption of flow reactor systems for dihydropyridine cyclization steps reduces solvent consumption and improves batch-to-batch consistency. Korean producers are retrofitting legacy batch plants with modular flow units.
Market Restraints
- Elemental impurity testing costs:ICH Q3D guidelines mandate inductively coupled plasma mass spectrometry for arsenic, cadmium, and lead screening. This analytical equipment requires seven-figure capital outlays that disproportionately burden mid-scale manufacturers.
- Intermediate supply concentration:Three Indian chemical clusters—Hyderabad, Visakhapatnam, and Ahmedabad—control over 60 percent of dihydropyridine precursor supply. Geopolitical friction or environmental enforcement actions in these zones cascade through global formulation networks.
- Fixed-dose combination substitution:Angiotensin receptor blocker and thiazide diuretic combinations are displacing standalone calcium channel blockers in several European markets where reimbursement favors simplified polypharmacy.
Strategic Opportunities
- Brazilian cardiovascular expansion:ANVISA's accelerated review pathway for hypertension generics creates entry windows for documented API suppliers. Domestic formulators in São Paulo and Rio de Janeiro seek qualified manidipine sources to localize production.
- Extended-release formulation development:Matrix-based sustained delivery systems reduce dosing frequency from twice-daily to once-daily regimens. This technology convergence of polymer science and tableting equipment opens premium positioning.
- Specialty pharmacy direct distribution:Hospital outpatient channels in Germany and France are consolidating procurement through specialized cardiovascular therapy distributors. API producers with dedicated pharmacovigilance support can capture margin pools bypassed by commodity suppliers.
Industry Challenges
- Analytical chemistry talent scarcity:Method development for forced degradation studies and impurity characterization requires specialists trained in ICH Q2(R1) validation protocols. European and North American API facilities compete for this limited talent pool against biologics employers offering equity compensation.
- Legacy equipment integration:Retrofitting stainless steel reactor trains for single-use containment systems involves extended shutdown windows and regulatory revalidation. Manufacturers serving multiple markets face staggered compliance deadlines that complicate capital planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Manidipine Hydrochloride Market |
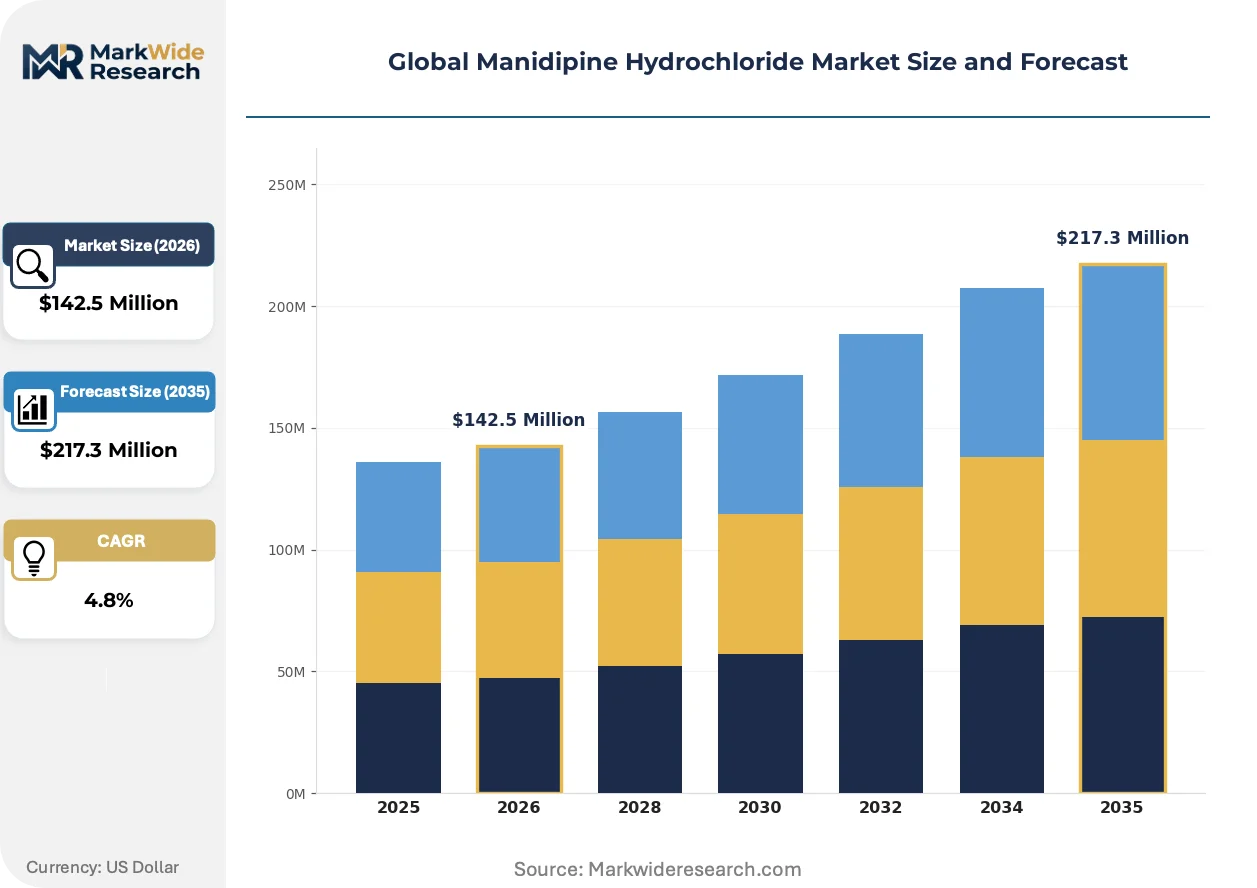
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $217.3 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Capsule, Extended Release, Oral Suspension Therapy Area: Hypertension, Angina Pectoris, Coronary Artery Disease, Peripheral Vascular Disorders End User: Hospitals, Clinics, Specialty Pharmacies, Nursing Homes Distribution Channel: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | JEIL PHARMACEUTICAL, Metrochem API Private Limited, Manus Aktteva Biopharma LLP, Toronto Research Chemicals, Watanabe Chemical Co. Ltd, Xi'an Sonwu Biotech Co. Ltd., Hefei Joye Import & Export Co. Ltd, Lusochimica, Permachem Asia, Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Manidipine Hydrochloride Market Shifts & Advancements
Process analytical technology and real-time release testing are compressing traditional quality control timelines, while regulatory data integrity requirements are reshaping how manufacturers document batch records and deviation investigations.
Near-infrared spectroscopy coupled with multivariate statistical process control is digitizing in-line monitoring of dihydropyridine salt formation reactions. Korean API producers are deploying these systems to eliminate offline sampling delays. The technology is digitizing release decision workflows, collapsing typical quarantine periods from fourteen days to under forty-eight hours.
EMA's revised guideline on nitrosamine risk assessment now requires retrospective evaluation of all chemically synthesized APIs for potential genotoxic impurity formation. This policy is forcing manufacturers to revalidate historical batch data and implement secondary amine scavenging protocols. Secondary amine-containing process intermediates face heightened scrutiny, with some European formulators switching to alternative calcium channel blockers pending supplier confirmation.
Hospital procurement consortia in France and Germany are consolidating annual API tenders into multi-year framework agreements with price-volume corridors. This buyer concentration is displacing spot-market transactions that historically allowed suppliers to capture margin during supply disruptions. The shift is most visible in cardiovascular therapy categories where standardized monograph specifications limit product differentiation.
Global Manidipine Hydrochloride Market Segmentation
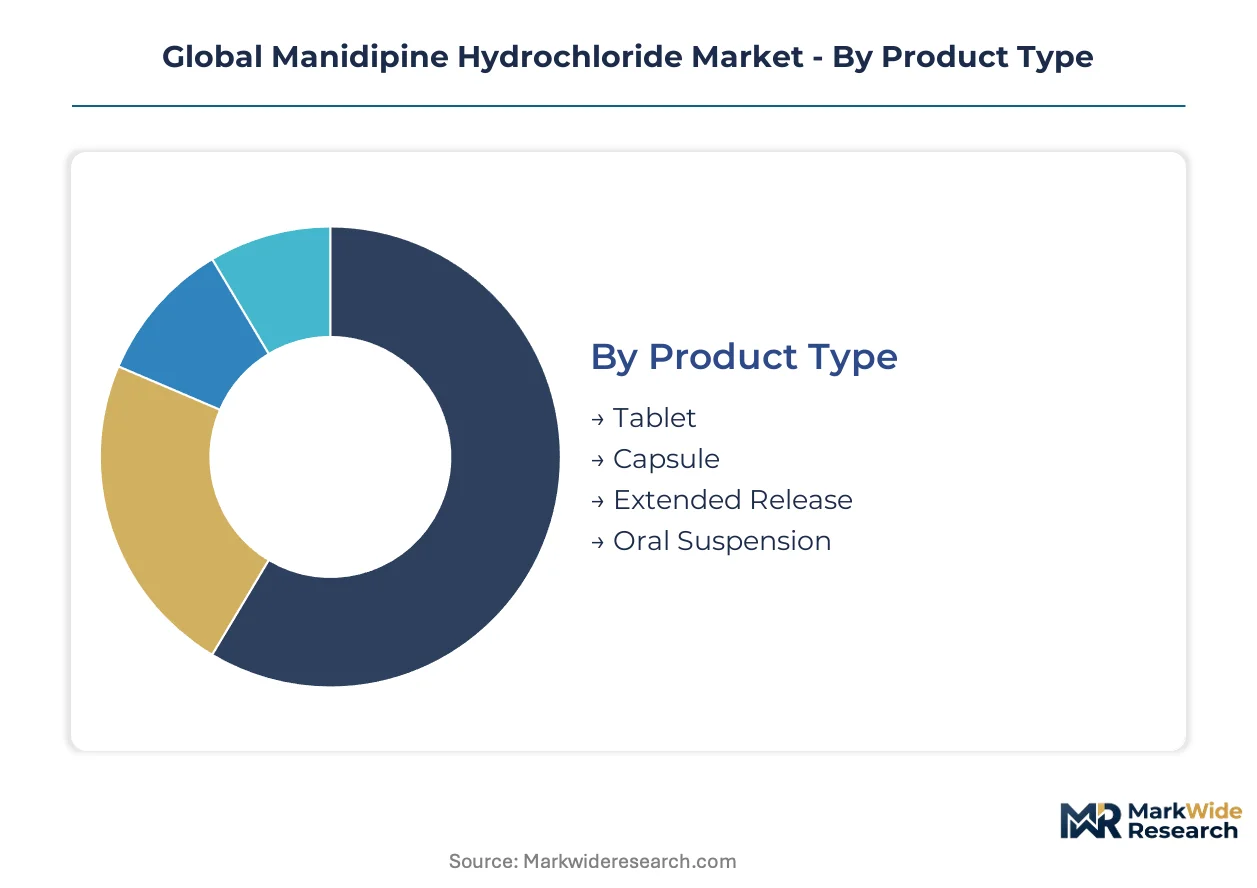
Manidipine hydrochloride formulation strategies diverge sharply across delivery systems and patient care settings, with dosage form selection directly impacting bioavailability profiles and prescriber adoption curves. Therapy area targeting determines regulatory pathway complexity and reimbursement positioning across cardiovascular indications.
Product Type:
Cost tier differentiation in finished dosage forms separates commodity immediate-release tablets from premium extended-release technologies requiring specialized polymer matrix investments.
- Tablet:Immediate-release compressed dosage forms containing manidipine hydrochloride as the active moiety with standard excipient matrices. Hospital formularies in Japan and South Korea prioritize these established presentations for chronic hypertension management due to prescriber familiarity and generic substitution pathways. Manufacturing equipment requirements remain accessible to mid-scale contract manufacturers.
- Extended Release:Matrix-based or osmotic pump systems achieving sustained plasma concentration profiles through hydrophilic polymer erosion or membrane-controlled diffusion. German and French specialty pharmacies are expanding procurement of these formulations as reimbursement frameworks favor reduced dosing frequency and improved adherence metrics in elderly populations.
- Capsule:Hard gelatin or HPMC shells encapsulating manidipine granules or powder blends for patients with tablet swallowing difficulties. Pediatric and geriatric prescribers in India specify these alternatives for specific patient subgroups.
- Oral Suspension:Liquid dosage forms with defined particle size distribution and viscosity specifications for dysphagia patients or dose titration requirements. Compounding pharmacies in Brazil serve niche demand pending ANVISA registration of manufactured presentations.
Tablet formulations command the established base. The steepest expansion runs through Extended Release.
Therapy Area:
Application focus determines clinical trial investment requirements and competitive intensity across cardiovascular therapeutic categories with varying prescriber specialization levels.
- Hypertension:Essential and resistant hypertension management representing the primary approved indication with extensive real-world safety data. Indian domestic formulators are scaling batch capacity to serve retail pharmacy channels as cardiovascular disease prevalence rises in urban centers. CDSCO bioequivalence requirements for generic entrants maintain quality barriers.
- Coronary Artery Disease:Adjunctive therapy for stable angina and vasospastic disorders with documented anti-ischemic effects through selective coronary vasodilation. Korean hospital consortia are incorporating manidipine into standardized order sets for post-percutaneous coronary intervention patients.
- Angina Pectoris:Chronic stable and variant angina prophylaxis leveraging the compound's preferential vascular selectivity over myocardial contractility effects. European formulators face EMA scrutiny on nitrosamine risk assessments for this indication.
- Peripheral Vascular Disorders:Raynaud's phenomenon and chronic limb ischemia applications with smaller addressable populations requiring specialized vascular specialist prescribing. Documentation packages from Indian API suppliers accelerate qualification with European buyers seeking niche indication expansion.
Hypertension anchors volume concentration. Coronary Artery Disease is climbing the fastest as interventional cardiology protocols evolve.
End User:
Customer type segmentation reflects divergent procurement authority, formulary control mechanisms, and pharmacovigilance obligations across institutional and community care settings.
- Hospitals:Acute care and outpatient departments with centralized pharmacy and therapeutics committee oversight. Procurement consortia in France and Germany are consolidating annual API tenders into multi-year framework agreements with price-volume corridors.
- Specialty Pharmacies:Direct-to-patient distributors of branded cardiovascular therapies with dedicated clinical support services. These channels capture concentrated margin pools through medication therapy management programs.
- Clinics:Ambulatory care centers with physician-dispensing authority or limited formulary independence. Brazilian cardiovascular expansion creates entry windows for documented API suppliers serving São Paulo and Rio de Janeiro formulators.
- Nursing Homes:Long-term care facilities with polypharmacy management challenges and medication adherence monitoring requirements. Extended-release formulations reduce dosing complexity for this population.
Hospitals dominate procurement volume. Specialty Pharmacies are gaining share fastest through direct distribution models.
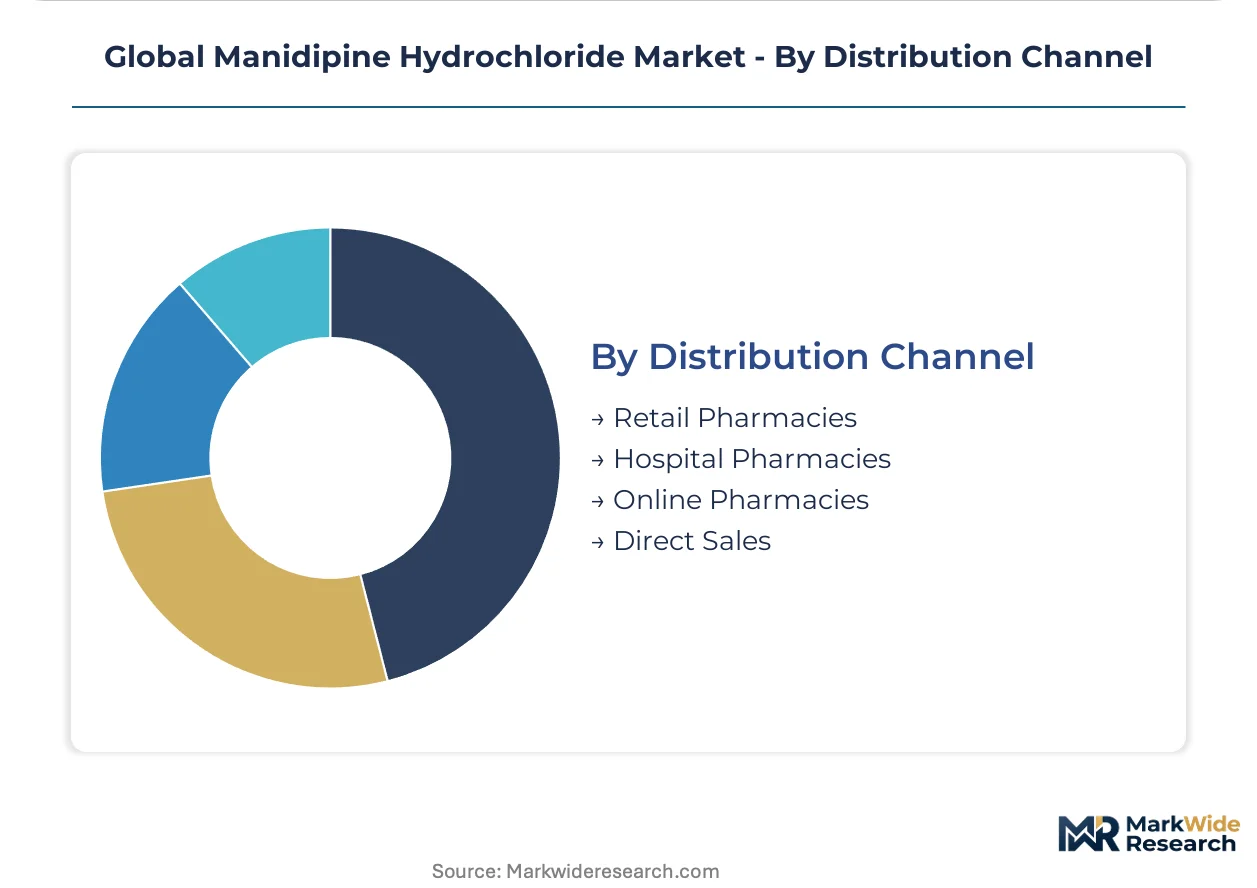
Distribution Channel:
Supply concentration in three Indian chemical clusters—Hyderabad, Visakhapatnam, and Ahmedabad—cascades through formulation networks and shapes channel economics.
- Hospital Pharmacies:Captive dispensing operations integrated with institutional procurement systems and electronic health record workflows. Korean producers retrofitting legacy batch plants with modular flow units serve these channels.
- Retail Pharmacies:Community-based dispensaries with generic substitution authority and patient co-pay sensitivity. India's retail expansion drives API demand from domestic formulators building cardiovascular therapy portfolios.
- Online Pharmacies:Digital platforms with cold chain logistics capabilities and prescription verification protocols. Regulatory data integrity requirements reshape documentation for these channels.
- Direct Sales:Manufacturer-to-institution arrangements bypassing wholesale intermediaries for large-volume accounts. EMA's revised nitrosamine guidelines force revalidation of historical batch data for these relationships.
Hospital Pharmacies control the anchored volume position. Online Pharmacies show the steepest trajectory as digital health infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA purity standards anchor United States market access requirements, while EMA nitrosamine protocols and CDSCO bioequivalence frameworks create divergent compliance burdens across manufacturing jurisdictions. API producers must layer redundant quality systems to serve multiple regulatory regimes simultaneously.
United States
Hospital formularies prioritize established dihydropyridine therapies for chronic hypertension management. FDA ICH Q3D elemental impurity guidelines mandate inductively coupled plasma mass spectrometry screening for arsenic, cadmium, and lead. New Jersey and Massachusetts pharmaceutical corridors host analytical chemistry specialists supporting multi-pharmacopeia compliance.
Germany
Specialty pharmacies expand procurement of extended-release cardiovascular formulations as reimbursement frameworks favor adherence metrics. EMA revised guidelines on nitrosamine risk assessment force retrospective API batch revalidation. Frankfurt and Munich hospital procurement consortia consolidate annual tenders into multi-year framework agreements.
India
Domestic formulators scale batch capacity to serve retail pharmacy channels as urban cardiovascular disease prevalence rises. CDSCO bioequivalence requirements for generic entrants maintain quality barriers. Hyderabad, Visakhapatnam, and Ahmedabad chemical clusters control over sixty percent of dihydropyridine precursor supply.
South Korea
Aging demographics expand the addressable patient population for calcium channel blocker therapies in hospital outpatient departments. MFDS enforces pharmacopeial monograph alignment with ICH quality guidelines. Seoul Capital Area manufacturers retrofit legacy batch plants with modular flow reactor units for dihydropyridine cyclization steps.
Brazil
Domestic formulators in São Paulo and Rio de Janeiro seek qualified manidipine sources to localize production. ANVISA accelerated review pathway for hypertension generics creates entry windows for documented API suppliers. Compounding pharmacies serve niche oral suspension demand pending manufactured presentation registrations.
Global Manidipine Hydrochloride Market Competitive Landscape
Vertically integrated Korean pharmaceutical groups and Indian contract API specialists split the market between formulation expertise and cost-optimized chemistry. The structure concentrates investment among players capable of multi-pharmacopeia compliance. Three archetypes dominate: backward-integrated formulators with captive intermediate supply, Hyderabad-based cost-optimized manufacturers, and documentation specialists serving European qualification requirements. Capacity expansion and regulatory dossier development represent the dominant competitive moves.
Among Korean producers, JEIL PHARMACEUTICAL anchors formulation expertise through backward integration into intermediate synthesis. Metrochem API Private Limited and Manus Aktteva Biopharma LLP occupy positions within the Indian contract manufacturing tier, with the former leveraging Hyderabad manufacturing infrastructure and the latter specializing in documentation packages for European buyer qualification. These three exemplify the geographic and strategic bifurcation shaping competitive positioning.
| Leading Market Players |
|---|
| JEIL PHARMACEUTICAL |
| Metrochem API Private Limited |
| Manus Aktteva Biopharma LLP |
| Toronto Research Chemicals |
| Watanabe Chemical Co. Ltd |
| Xi'an Sonwu Biotech Co. Ltd. |
| Hefei Joye Import & Export Co. Ltd |
| Lusochimica |
| Permachem Asia, Ltd |
| Others |
Supply & Pricing Matrix
Overcapacity signals from Hyderabad's dihydropyridine intermediate producers are forcing batch-price concessions that ripple through formulation networks, compressing margins for API specialists serving European qualification requirements while Korean backward-integrated formulators maintain pricing discipline through captive supply.
Pricing Analysis
Price spreads between Indian contract manufacturers and Korean integrated producers exceed thirty percent for equivalent pharmacopeial grades, with certification tier and volume scale as the primary differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels separates EMA-qualified batches from CDSCO-registered and non-regulated tier supplies. Pricing pressure stems from fixed-dose combination substitution in European reimbursement frameworks. Hospital procurement consortia exhibit lowest price sensitivity through multi-year framework agreements, while Brazilian domestic formulators face highest co-pay sensitivity.
Supply Chain Analysis
Tariff exposure between India and European Union member states dominates supply chain risk planning for dihydropyridine precursor movements. API production draws from Indian chemical clusters in Hyderabad, Visakhapatnam, and Ahmedabad, with Korean Seoul Capital Area manufacturers providing secondary capacity. Raw material dependencies center on 2-cyanothiophene intermediates, methylamine reagents, and specialized solvents for cyclization steps. Single-source vulnerability concentrates in three Indian intermediate suppliers. Distribution runs through hospital pharmacy consortia and specialty pharmacy direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The manidipine hydrochloride market is cycling through a post-nitrosamine-scrutiny recovery as EMA batch revalidation requirements force supplier consolidation and create replacement demand for qualified API sources.
For Market Incumbents: Entrench multi-pharmacopeia compliance capabilities through analytical chemistry talent acquisition and ICH Q3D testing infrastructure investment. Threats from fixed-dose combination substitution in European markets demand defensive positioning through extended-release formulation partnerships. Captive intermediate supply remains the priority lever for margin defense against Indian cost-optimized competitors.
For New Entrants and Emerging Players: Build out documentation-specialist capabilities targeting European buyer qualification as the most penetrable entry vector. White-space exists in Brazilian ANVISA registration support and oral suspension compounding pharmacy supply. Go-to-market angle should emphasize pharmacovigilance support packages that bypass commodity supplier positioning.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across analytical testing infrastructure as ICP-MS equipment and forced degradation method development costs escalate. Long-term viability over a five-to-ten year window favors targets with existing European regulatory dossiers and backward-integrated intermediate positions. The signal to watch is CDSCO bioequivalence study volume acceleration as Indian domestic formulators expand cardiovascular portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Expansion | EMA nitrosamine compliance creates qualification moats for documented API suppliers. |
| Continuous Flow Retrofit | Korean producers deploying modular reactor units reduce solvent consumption and batch variability. |
| Extended-Release Partnership | Matrix-based formulation development opens premium positioning in German and French specialty pharmacies. |
| Analytical Talent Acquisition | ICH Q2(R1) validation specialists command premium compensation against biologics sector competition. |
| Brazilian Localization Supply | ANVISA accelerated review pathway creates entry windows for documented API sources. |
Research Methodology
Operator-level perspectives from regulatory affairs leads, API manufacturing executives, hospital procurement managers, and specialty pharmacy directors anchored the qualitative base. Primary interview data combined with secondary validation from FDA filings, EMA assessment reports, CDSCO bioequivalence study databases, and Indian customs trade records. Bottom-up capacity modeling and top-down demand triangulation cross-checked volume estimates.
Scenario-bracketing framed analytical sensitivity across the projection horizon. Segmentation dimensions modeled include dosage form, therapy area, end-user setting, and regional regulatory cluster. CAGRs derived from patient population epidemiology, prescription volume trends, and API pricing trajectory analysis. Forecast inputs incorporated hypertension prevalence curves and hospital formulary placement probability.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Korean pharmaceutical groups or sudden environmental enforcement in Indian chemical clusters would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Soft Capsules Drugs CMO Market
Pharmaceuticals
Antibody Therapy Market
Pharmaceuticals
Galculus Bovis and Metronidazole Market
Pharmaceuticals
Tuberculosis Vaccine Treatment Market
Pharmaceuticals
Compound Acetaminophen Market
Pharmaceuticals
Norway Pharmaceutical Market
Pharmaceuticals
Italy Healthcare Market
Pharmaceuticals
Antimetabolite Drugs Market
Pharmaceuticals
Global Eylea Market
Pharmaceuticals
Belgium Pharmaceutical Market
Pharmaceuticals
Oncology Adjuvants Market
Pharmaceuticals
Anti-Obesity Drugs Market
Pharmaceuticals
Inotropic Agent Market
Pharmaceuticals
Migraine Nasal Spray Market
Pharmaceuticals
3D Printing Drug Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market