
 Propanil Market | 2026-2036
Propanil Market Size, Share, and Industry Trends Forecast 2026-2036
Propanil Market Analytics
Specialized formulation chemists is bifurcating the competitive landscape as complex emulsifiable concentrate recipes outpace generic manufacturing capacity. Bayer CropScience leverages its European regulatory expertise to sustain premium positioning in residue-sensitive export markets. ADAMA Agricultural Solutions anchors volume supply through backward integration into active ingredient production. Jiangsu Kuaida Agrochemical competes on cost-optimized suspended concentrate platforms for domestic Chinese rice growers.
Propanil is a selective acetanilide herbicide with the chemical formula C9H9Cl2NO, functioning as a photosystem II inhibitor that disrupts electron transport in weed chloroplasts to control broadleaf and grass species in flooded rice paddies. Liquid formulations dominate commercial volumes due to ease of tank-mixing with fertilizer and fungicide applications, while emulsifiable concentrates capture higher margin pools in precision agriculture systems where drift control commands price premiums. The application segment shows structural divergence: crops anchor baseline demand, yet vegetation management for irrigation canal maintenance represents the fastest-growing sub-area as water infrastructure investment expands.
The EPA governs propanil tolerances and ecological risk assessments under FIFRA, while India's CEA monitors groundwater contamination thresholds in rice-intensive districts. REACH compliance in Europe restricts certain co-formulant chemistries, pushing manufacturers toward bio-based surfactant alternatives. Stakeholders must track regulatory divergence between residue-limit jurisdictions to optimize formulation portfolios without duplicating registration costs.
Market Dynamics
Specialized formulation chemists is bifurcating the propanil landscape as complex emulsifiable concentrate recipes outpace generic manufacturing capacity, forcing suppliers to choose between premium residue-compliant systems and cost-optimized suspended concentrate platforms for domestic rice growers.
Growth Catalysts
- EPA Re-registration Review:The EPA's ongoing acetanilide herbicide review is accelerating product reformulation investments, pushing manufacturers toward next-generation co-formulant packages that preemptively address ecological risk findings.
- Southeast Asia Rice Expansion:Flooded paddy cultivation across Vietnam, Thailand, and Indonesia anchors formulation demand as mechanized transplanting spreads and weed control intensity rises.
- Water Infrastructure Investment:Vegetation management for irrigation canal maintenance represents emerging volume growth as governments fund canal clearing programs to reduce water loss.
Market Restraints
- Chloroaniline Input Volatility:3,4-dichloroaniline feedstock prices fluctuate with benzene derivatives markets, compressing margin predictability for non-integrated formulators.
- REACH Co-formulant Restrictions:ECHA classification of certain surfactant chemistries as substances of very high concern forces costly reformulation cycles for European-destined products.
- Glufosinate Substitution Pressure:Non-selective herbicide alternatives with simpler resistance management profiles capture share in precision-drilled rice systems where water control permits their use.
Strategic Opportunities
- India Eastern Rice Belt Underpenetration:West Bengal and Odisha districts show formulation intensity gaps relative to Punjab and Haryana, offering volume expansion through localized technical service networks.
- Bio-based Surfactant Convergence:Combination of microbial-derived adjuvants with conventional active ingredients opens premium positioning for residue-sensitive export markets.
- Direct-to-Cooperative Distribution:Bypassing traditional agrochemical dealer networks through farmer producer organization contracts reduces working capital requirements and captures price transparency gains.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in complex emulsion stability and drift-reduction polymer design concentrates at mid-sized specialists, constraining rapid product iteration at volume manufacturers.
- Groundwater Monitoring Compliance:India's CEA district-level contamination threshold enforcement requires granular batch tracking and field residue documentation that strains legacy quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Propanil Market |
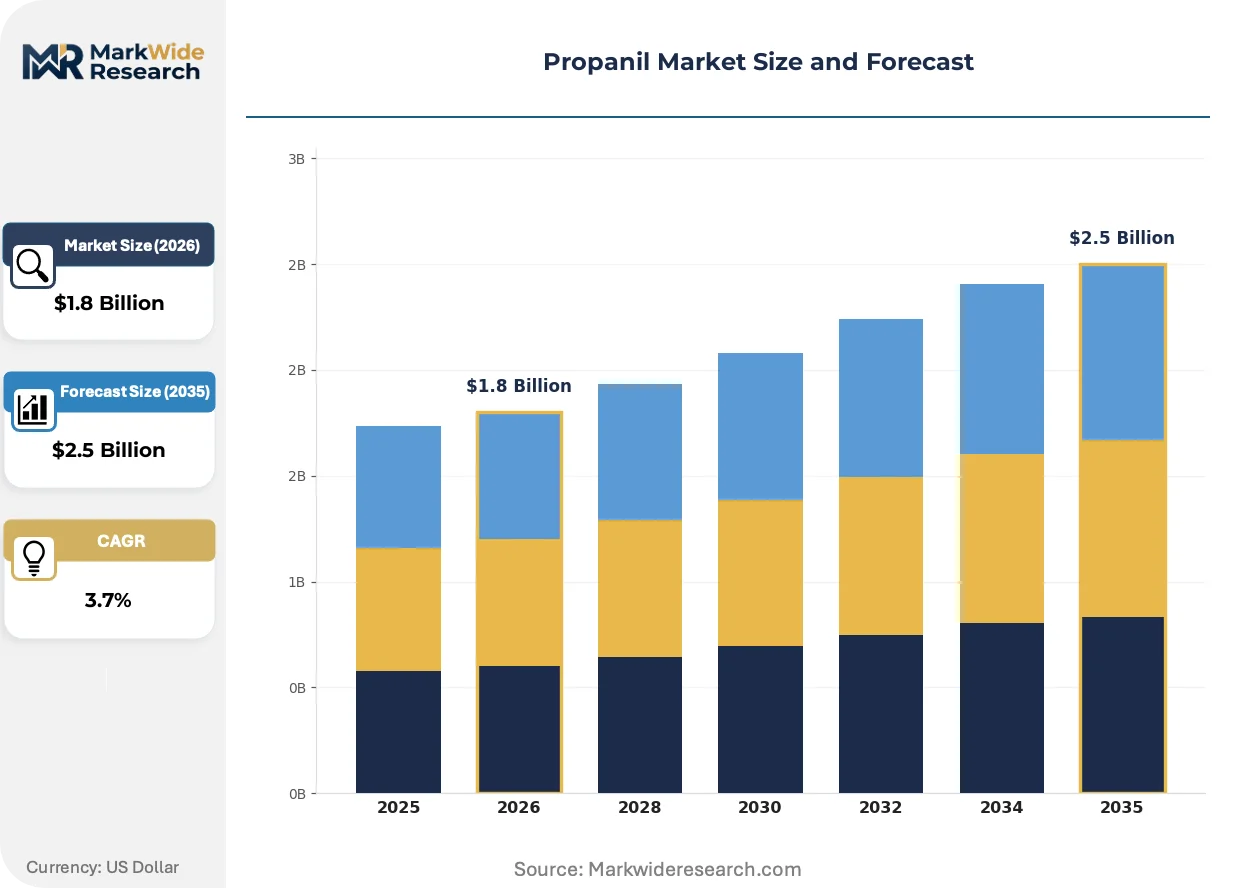
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Liquid, Suspended Concentrate, Emulsifiable Concentrate Application: Crops, Weeds, Aquatic, Vegetation Management End User: Agriculture, Landscaping, Government, Research Institutions Distribution Channel: Online Retail, Wholesalers, Agrochemical Stores, Direct Sales |
| Companies Covered | United Phosphorus, Willowood USA, Dow AgroSciences, Syngenta, Bharat Group, Bayer CropScience, Jiangsu Kuaida Agrochemical, ADAMA Agricultural Solutions, Shijiazhuang Lida Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Propanil Market Evolving Landscape
Formulation technology is actively reshaping competitive positioning in propanil markets, with drift control chemistry, regulatory pre-adaptation strategies, and channel restructuring emerging as the three dominant vectors of change.
Micro-encapsulation technology is bifurcating the propanil formulation landscape. This delivery system extends active ingredient release in flooded paddy conditions, improving weed control duration. Precision agriculture operators in Japan and South Korea are adopting encapsulated variants at accelerated rates. The technology is compressing generic emulsifiable concentrate margins while enabling premium pricing for manufacturers with polymer engineering capabilities.
REACH restriction proposals on nonylphenol ethoxylate surfactants are forcing co-formulant substitutions across European-registered propanil products. Manufacturers face reformulation timelines compressed by sunset date uncertainties. Suspended concentrate platforms using bio-based alternatives are capturing preference in residue-sensitive export supply chains serving EU-aligned markets.
Farmer producer organizations are consolidating procurement volumes across India's eastern rice belt. Traditional village-level agrochemical dealers face disintermediation as cooperatives negotiate direct supply contracts with formulators. This channel shift is most visible in West Bengal's Nadia and Murshidabad districts, where pooled procurement has reduced per-hectare herbicide costs and shifted technical service responsibility upstream to manufacturer field teams.
Propanil Market Segmentation
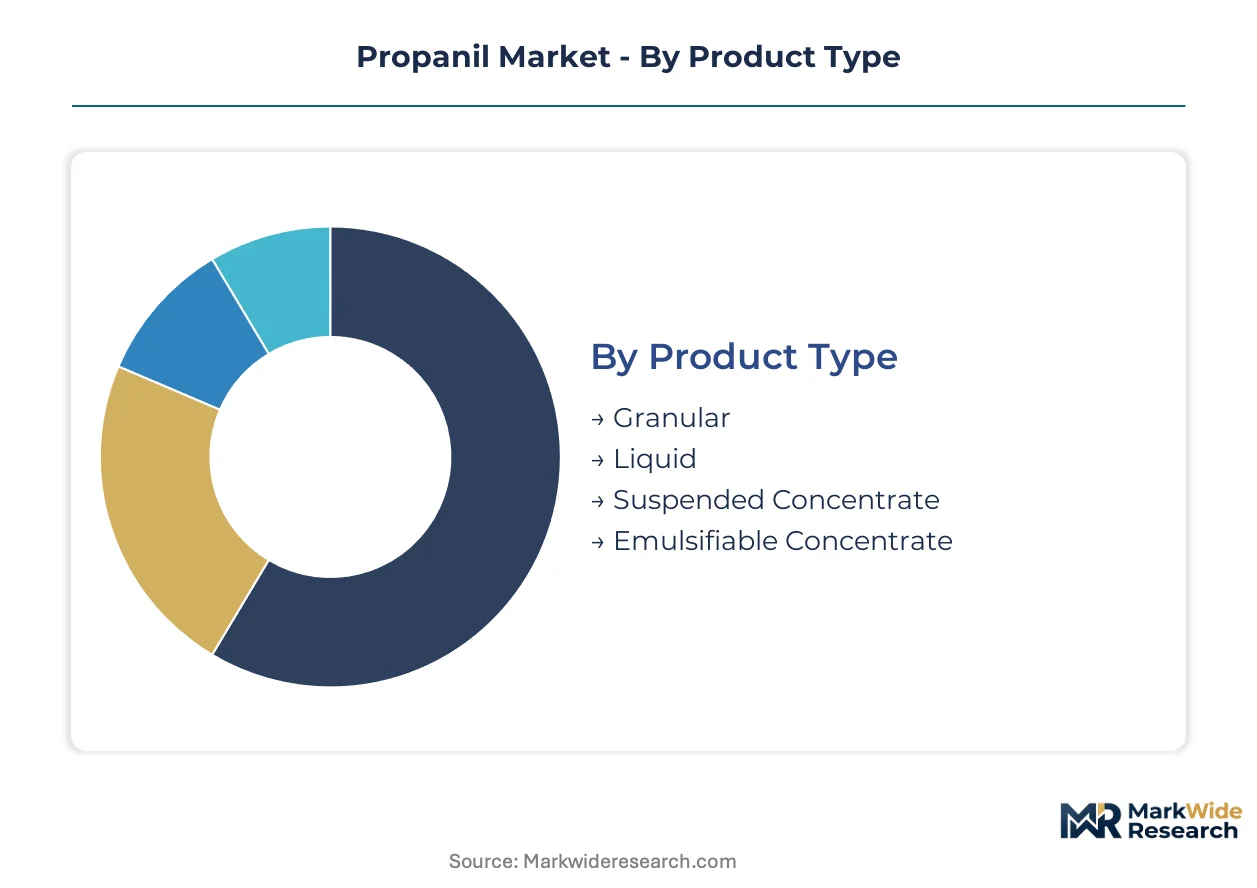
Propanil formulation diversity reflects divergent regulatory tolerances across export corridors. EPA residue limits, REACH co-formulant restrictions, and India's CEA groundwater thresholds each favor distinct physical delivery systems and channel structures.
Product Type:
Regulatory differentiation separates residue-compliant emulsion systems from cost-optimized aqueous platforms.
- Liquid:Aqueous solutions permit rapid tank-mixing with nitrogen fertilizers and fungicides in flooded paddy operations. Demand concentrates in Vietnam's Mekong Delta where mechanized spraying requires low-viscosity systems compatible with drone application equipment.
- Emulsifiable Concentrate:Oil-in-water emulsions incorporating drift-reduction polymers command premium positioning in Japan and South Korea's residue-sensitive export rice sectors. EPA ecological risk findings on acetanilide herbicides are accelerating reformulation investments in this category.
- Granular:Dry dispersible granules serve manual broadcasting in India's West Bengal smallholder plots where water access limits spray equipment deployment.
- Suspended Concentrate:Aqueous suspensions of micronized active ingredient compete on cost in China's domestic rice belt through simplified manufacturing processes.
Liquid formulations handle the majority of throughput; Emulsifiable Concentrate is expanding most quickly on share as precision agriculture spreads.
Application:
Cost tier separation distinguishes commodity crop protection from infrastructure maintenance contracts.
- Crops:Flooded rice paddies across Southeast Asia anchor baseline volume, with application timing synchronized to transplanting windows and weed emergence patterns.
- Vegetation Management:Canal bank and irrigation channel clearing represents the fastest-climbing application area as government water infrastructure investment accelerates in Indonesia and Thailand.
- Weeds:Broadleaf and grass species control in non-crop zones serves utility right-of-way maintenance programs.
- Aquatic:Submerged weed management in reservoir systems faces tightening EPA aquatic toxicity scrutiny.
Crops absorbs the dominant share of active ingredient volume; Vegetation Management is gaining share fastest as infrastructure budgets expand.
End User:
Customer type determines technical service intensity and formulation specification requirements.
- Agriculture:Smallholder cooperatives in India's eastern rice belt and commercial farming operations across Southeast Asia drive formulation demand through seasonal procurement cycles.
- Government:Public works departments managing irrigation canal systems purchase through tender processes with extended payment terms and residue documentation requirements.
- Landscaping:Golf course and ornamental turf applications in Japan favor micro-encapsulated variants for extended control duration.
- Research Institutions:Agricultural universities and extension services conduct resistance monitoring and efficacy trials that influence regional recommendation lists.
Agriculture commands the volume base; Government procurement is climbing fastest as canal maintenance programs scale.
Distribution Channel:
Channel restructuring is disintermediating traditional dealer networks in favor of direct cooperative relationships.
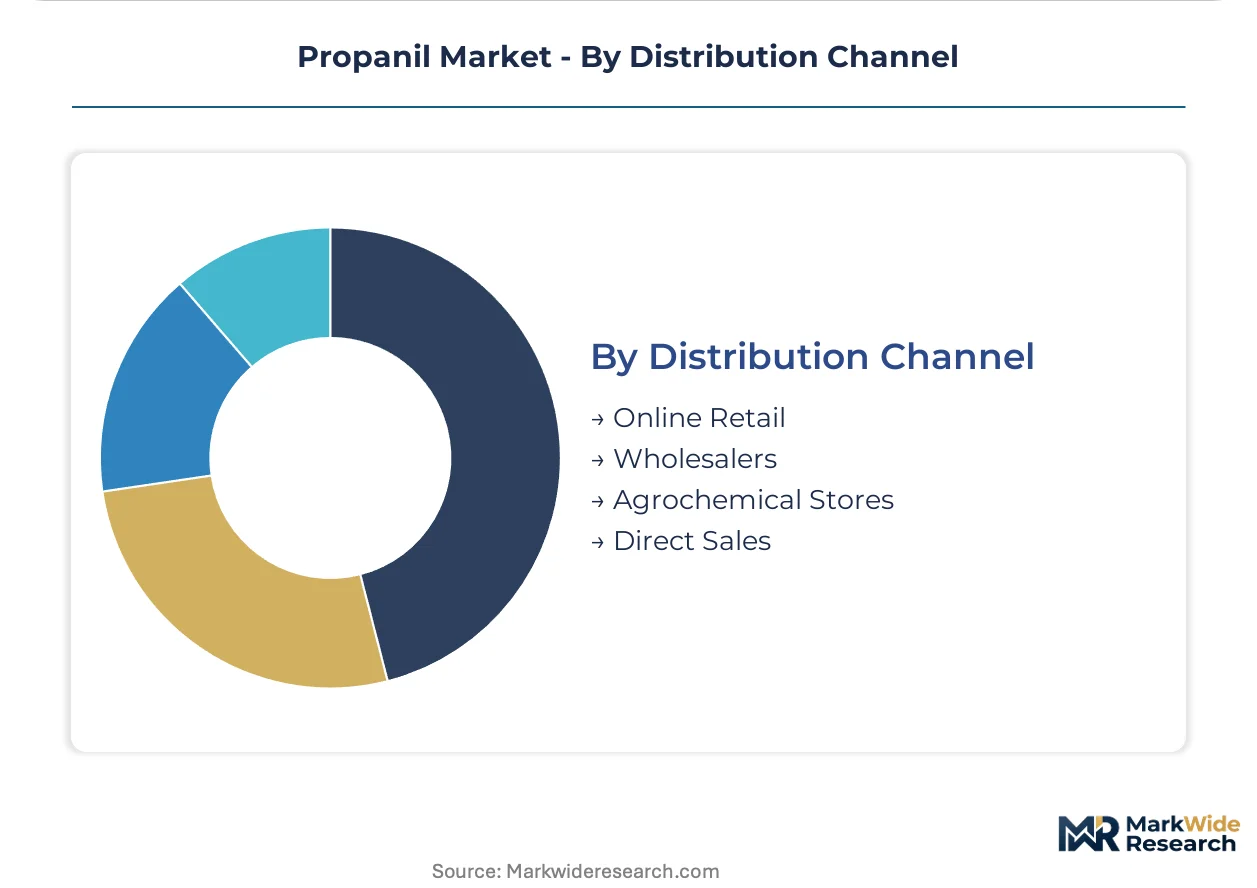
- Agrochemical Stores:Village-level retailers in India's Odisha and West Bengal districts face margin compression as farmer producer organizations consolidate procurement volumes.
- Direct Sales:Manufacturer contracts with cooperatives in West Bengal's Nadia and Murshidabad districts are reducing per-hectare herbicide costs and shifting technical service responsibility upstream.
- Wholesalers:Regional distributors serve fragmented smallholder markets in Vietnam and Indonesia where cooperative penetration remains limited.
- Online Retail:E-commerce platforms capture emerging share among precision agriculture operators in South Korea seeking specification transparency.
Agrochemical Stores still handles the majority of throughput; Direct Sales is the fastest mover on share as cooperative consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam consumes propanil formulations through mechanized drone spraying in the Mekong Delta, while India relies on manual broadcasting in smallholder plots; this application-method divergence shapes distinct formulation specifications across rice-growing geographies.
United States
The EPA's acetanilide herbicide re-registration review drives reformulation investments among rice growers in Arkansas and Louisiana. FIFRA-mandated ecological risk assessments are accelerating drift-reduction polymer adoption. The Mississippi Delta concentration of propanil application faces tightening tolerances for chloroaniline metabolite residues in export-bound grain.
India
West Bengal and Odisha districts anchor domestic formulation demand through flooded paddy cultivation across the eastern rice belt. The CEA monitors groundwater contamination thresholds in rice-intensive districts, requiring granular batch tracking from manufacturers. Kolkata-based formulators are expanding technical service networks into underpenetrated Murshidabad and Nadia districts.
Vietnam
Mechanized transplanting spreads across the Mekong Delta, intensifying weed control demand and favoring low-viscosity liquid formulations compatible with aerial application equipment. The Ministry of Agriculture and Rural Development regulates pesticide residue limits for export rice shipments. Can Tho and An Giang provinces concentrate formulation procurement through cooperative consolidation.
China
Jiangsu and Zhejiang provinces manufacture suspended concentrate platforms for domestic rice growers through cost-optimized aqueous suspension processes. The MEE enforces environmental compliance standards on chloroaniline intermediate production. Yangtze River Delta formulators are capturing share in Southeast Asian export markets through price-competitive supply contracts.
Thailand
Government-funded irrigation canal maintenance programs are expanding vegetation management applications beyond traditional crop protection. The Department of Agriculture regulates herbicide import tolerances for domestic rice consumption and re-export markets. Central Plains rice-growing provinces around Suphan Buri and Ayutthaya concentrate demand for both paddy and canal-clearing formulations.
Propanil Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in propanil manufacturing, with backward integration into active ingredient production separating margin-stable suppliers from price-exposed formulators. The competitive landscape segments into three strategic archetypes: multinational agrochemical conglomerates with regulatory expertise, mid-sized Asian manufacturers competing on cost-optimized platforms, and regional specialists serving localized distribution networks. Dominant competitive moves include capacity expansion in chloroaniline intermediate production and strategic partnerships with farmer producer organizations to bypass traditional dealer networks.
Within the integrated multinational tier, Bayer CropScience and ADAMA Agricultural Solutions exemplify divergent positioning strategies—Bayer leveraging European regulatory expertise for residue-sensitive export markets, ADAMA anchoring volume supply through captive active ingredient production. Jiangsu Kuaida Agrochemical occupies a position among cost-focused Asian formulators, representing the suspended concentrate platform specialists competing for domestic Chinese and Southeast Asian rice grower procurement.
| Leading Market Players |
|---|
| United Phosphorus |
| Willowood USA |
| Dow AgroSciences |
| Syngenta |
| Bharat Group |
| Bayer CropScience |
| Jiangsu Kuaida Agrochemical |
| ADAMA Agricultural Solutions |
| Shijiazhuang Lida Chemicals |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Indian formulators and chloroaniline intermediate producers lock in supply access and price visibility for propanil manufacturers serving Southeast Asia's rice belt, insulating integrated players from benzene derivative volatility that compresses margins at non-integrated competitors.
Pricing Analysis
Contract-based long-term offtake arrangements dominate procurement between integrated manufacturers and downstream cooperatives, while spot purchasing concentrates among smallholder-dependent dealers. Price differentiation rests on REACH compliance certification and drift-reduction polymer inclusion, with residue-sensitive export markets commanding substantial premia over domestic formulations. Cost compression in standard-grade emulsifiable concentrates is intensifying because glufosinate substitution pressure erodes pricing power in precision-drilled rice systems. Smallholder cooperatives in India's eastern districts exhibit the highest price sensitivity, whereas Japanese precision agriculture operators show minimal elasticity for micro-encapsulated variants.
Supply Chain Analysis
3,4-dichloroaniline feedstock production concentrates in China's Jiangsu and Zhejiang provinces, with Indian specialty chemical clusters around Ahmedabad and Mumbai serving secondary refining capacity. Manufacturing draws from benzene derivatives, chlorination reagents, and surfactant packages, with bio-based adjuvant alternatives emerging as substitution candidates. Single-source vulnerability characterizes European-bound products dependent on REACH-compliant co-formulant suppliers. Distribution runs through farmer producer organization contracts in West Bengal's Nadia district, bypassing traditional agrochemical dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Propanil markets are approaching a platform-economics inflection as cooperative procurement consolidation creates interoperability standards for batch tracking and residue documentation that favor integrated manufacturers over fragmented formulators.
For Market Incumbents: Shield margin stability through captive chloroaniline production and preemptive REACH co-formulant substitution investments. Glufosinate substitution pressure demands accelerated micro-encapsulation R&D to sustain premium positioning in residue-sensitive export corridors. Backward integration into active ingredient production remains the critical defensive lever against feedstock volatility. For New Entrants and Emerging Players: Differentiate on bio-based surfactant convergence combined with direct-to-cooperative distribution bypassing dealer networks. India's eastern rice belt presents the most penetrable geography, with West Bengal's Murshidabad district showing formulation intensity gaps relative to Punjab. Technical service partnerships with agricultural universities offer credible go-to-market positioning. For Investors and Strategic Acquirers: Capital is best deployed toward mid-sized specialists with polymer engineering capabilities and existing EPA registration dossiers. Long-term viability hinges on regulatory pre-adaptation capacity rather than volume scale alone. Watch for EPA ecological risk assessment publication timing as the definitive inflection signal for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chloroaniline Production | Captive supply of 3,4-dichloroaniline insulates margins from benzene derivative volatility. |
| Micro-Encapsulation Platform Development | Polymer engineering capabilities enable premium positioning in Japan's residue-sensitive export rice sector. |
| Bio-Based Surfactant Reformulation | REACH-compliant co-formulant substitution opens EU-aligned market access before sunset date enforcement. |
| Direct-to-Cooperative Distribution Contracts | Farmer producer organization partnerships in West Bengal reduce working capital requirements and capture price transparency. |
| EPA Pre-Registration Reformulation Investment | Next-generation co-formulant packages address anticipated ecological risk findings before mandatory compliance deadlines. |
Research Methodology
Initial hypotheses were tested against primary input from formulation chemists, agrochemical procurement managers at farmer cooperatives, regulatory affairs specialists, and chloroaniline plant managers, then refined through secondary validation against EPA re-registration documentation, REACH restriction proposals, India's CEA groundwater monitoring reports, and customs trade data. Bottom-up volume estimates from state-level rice cultivation statistics and top-down value projections from manufacturer revenue disclosures were triangulated to converge on segment-level outputs.
Variance decomposition across the projection horizon isolates drivers by formulation type, application segment, and regional regulatory cluster. The analytical framework models liquid, emulsifiable concentrate, granular, and suspended concentrate platforms separately, with drift-reduction polymer inclusion and REACH compliance status as cross-cutting modifiers. CAGRs were derived from regression-adjusted trend extrapolation incorporating mechanized transplanting adoption rates and canal maintenance program budget trajectories as industry-specific demand inputs.
The analysis sits within stated boundaries; outcomes outside sustained Southeast Asia rice expansion or accelerated EPA regulatory timelines would require recalibration. Forecasts reflect documented assumptions regarding cooperative consolidation velocity and chloroaniline supply continuity. Practitioners should keep alternative scenarios live as REACH sunset date enforcement and glufosinate substitution penetration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Coriolis Meters Market
Others
Nuclear Power Cables Market
Others
Profiling Floats Market
Others
Composite Copper Foil Production Equipment Market
Others
Aircraft Exterior Lighting Market
Others
APAC Smart Home Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
Middle East Paper Making Machine Market
Others
Industrial Gauges Market
Others
Metaverse Market
Others
Rope Market
Others
North America Forklift Truck Market
Others
Global Luxury High End Furniture Market
Others
High-End Servers Market
Others
North America Smart Homes Market
Others
Computer on Module Market