
 Triathlon Clothing Market | 2026-2036
Triathlon Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Triathlon Clothing Market Intelligence
Demand from committed amateur athletes is collapsing the distinction between professional-grade gear and accessible performance wear. This shift benefits brands that can deliver technical features at competitive price points. 2XU leverages its expertise in compression technology to serve this expanding consumer group. Meanwhile, specialist brands like HUUB differentiate through a focus on hydrodynamic and aerodynamic innovations specifically for triathlon disciplines.
Triathlon clothing consists of specialized garments designed for the swim, bike, and run disciplines of a triathlon. These garments utilize multi-functional fabrics, often polyester-spandex blends, that are quick-drying, chlorine-resistant, and offer muscle compression. All-in-one tri suits represent the largest product type, valued for efficiency during transitions. Material selection is a key differentiator, with advanced hydrophobic coatings and breathable textiles enabling higher performance and justifying premium pricing.
Product safety and material composition are governed by regulations like the EU's REACH directive, which restricts harmful chemicals in textiles. In the United States, the FTC enforces textile labeling requirements, ensuring transparency for consumers. Furthermore, ISO standards for textile performance testing provide benchmarks for durability and functional claims. The central challenge for manufacturers is balancing material innovation with the cost pressures inherent in a market with a broadening consumer base.
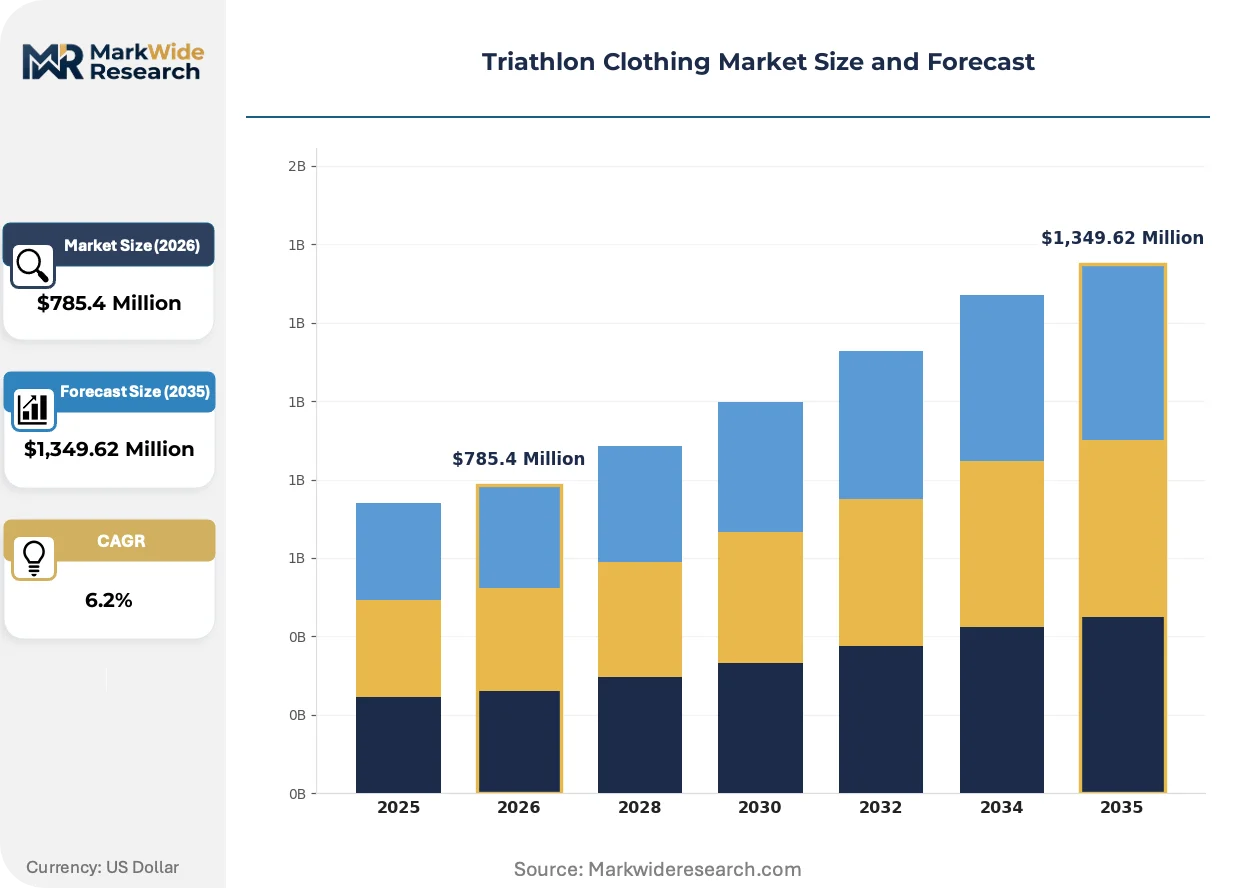
Market Dynamics
The central force shaping the triathlon clothing market is the democratization of performance technology. Demand from a growing base of dedicated amateur athletes is compelling brands to integrate elite-level material science, such as advanced compression and hydrophobic fabrics, into more accessible product tiers.
Growth Catalysts
- Expanding Event Participation:The rising number of sanctioned triathlon events and amateur participation, especially in endurance-focused nations like Australia and Germany, directly expands the core consumer base for specialized apparel.
- Material Science Innovation:Continuous development of high-performance textiles, including lighter polyester-spandex blends with enhanced chlorine resistance and aerodynamic properties, enables brands to offer tangible performance benefits that justify purchases.
- Health and Wellness Culture:A broader societal shift towards active lifestyles and personal fitness challenges serves as a powerful tailwind, drawing new entrants into triathlon and related multi-sport disciplines, thereby creating new demand for entry-level and mid-range gear.
Market Restraints
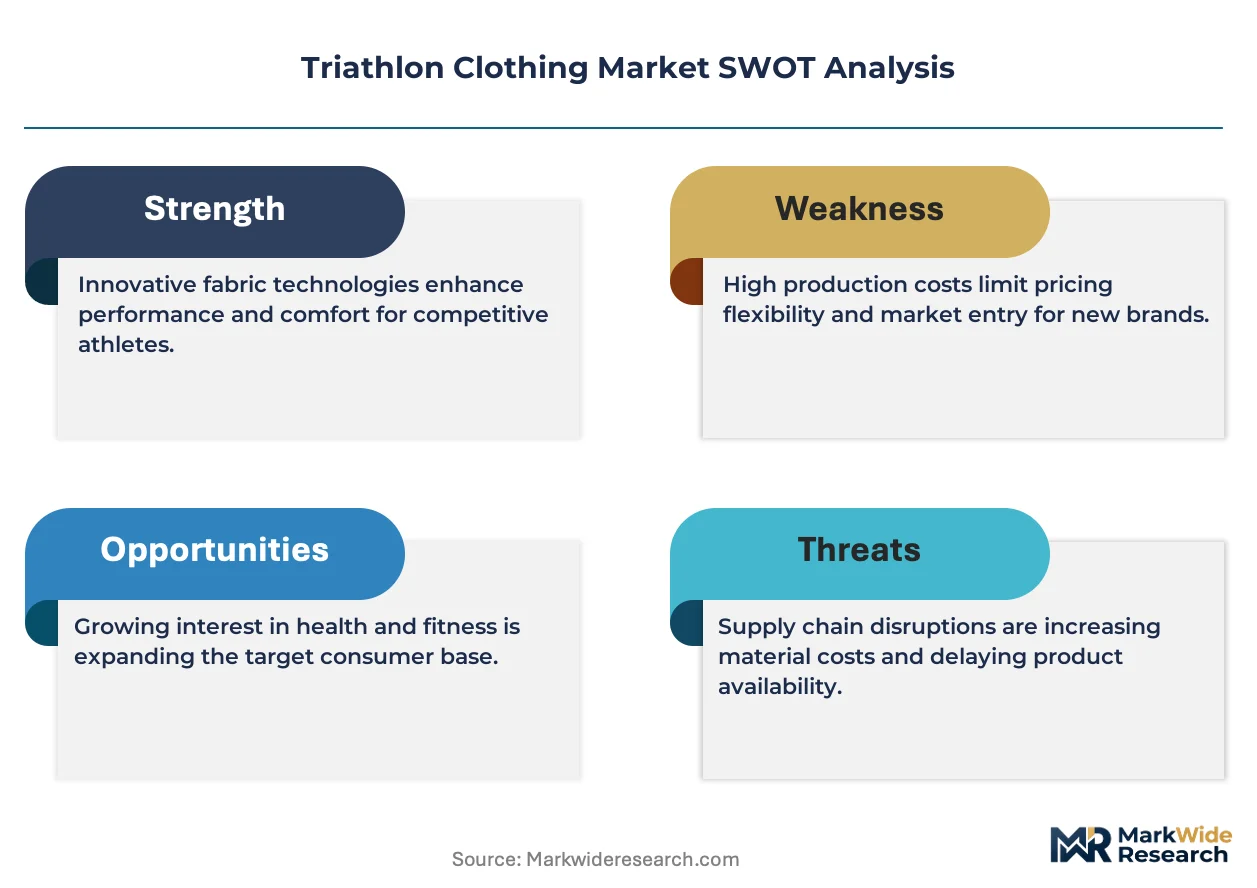
- High Input Costs:The specialized nature of performance fabrics, including proprietary compression textiles and hydrophobic coatings, leads to high raw material costs that can elevate final product prices beyond the reach of casual or beginner athletes.
- Substitution from General Sportswear:Entry-level participants often opt for general-purpose athletic wear, such as cycling shorts and running tops, which poses a significant substitution threat and can delay their investment in integrated tri suits.
- Supply Chain Concentration:A reliance on a limited number of specialized textile mills, primarily located in Asia, for the production of advanced synthetic fabrics creates potential vulnerabilities and price volatility in the supply chain.
Strategic Opportunities
- Geographic Expansion:There is significant opportunity in emerging triathlon markets, such as those in South America and Southeast Asia, where participation is growing but local availability of specialized apparel remains limited.
- Niche Product Development:Brands can target underserved segments by designing apparel for specific climate conditions, such as suits with enhanced UV protection for hot-weather races or thermal layers for cold-water swims.
- Direct-to-Consumer Channels:Building out direct-to-consumer (DTC) e-commerce platforms allows brands to control their messaging, capture higher margins, and build direct relationships with the core amateur athlete community, bypassing traditional retail intermediaries.
Industry Challenges
- Regulatory Compliance Burden:Adhering to a complex web of international chemical and textile regulations, such as the EU's REACH directive and the FTC's labeling laws in the United States, adds significant administrative and testing costs.
- Inventory Obsolescence Risk:The combination of fashion-driven colorway updates and rapid material technology cycles creates a high risk of inventory obsolescence, challenging manufacturers to accurately forecast demand for specific product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Triathlon Clothing Market |
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,349.62 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Swimwear, Cycling Shorts, Running Tights, Tri Suits Material: Nylon, Polyester, Spandex, Merino Wool End User: Amateur Athletes, Professional Athletes, Fitness Enthusiasts, Coaches Distribution Channel: Online Retail, Specialty Stores, Department Stores, Brand Outlets |
| Companies Covered | Nike, TYR Sport, 2XU, Castelli, Zone3, Pearl Izumi, Adidas, HUUB, Zoot Sports, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Triathlon Clothing Market Strategic Shifts & Innovations
Material science is converging with athlete-specific data to redefine performance benchmarks in triathlon apparel. Innovations are focused on delivering measurable gains in thermoregulation, hydrodynamics, and aerodynamics, meeting the technical expectations of an increasingly sophisticated consumer.
Bio-ceramic and graphene-infused textiles are emerging as a key innovation, designed to improve thermoregulation and far-infrared energy return to muscles. This technology is being rapidly adopted by competitive age-group athletes seeking an edge in performance and recovery. This new class of smart fabric is displacing traditional polyester blends by offering functional benefits that extend beyond basic moisture wicking and compression.
Sustainability mandates, particularly the EU Green Deal's framework for textiles, are forcing a lifecycle-based approach to design and manufacturing. This requires brands to increase transparency in sourcing and prove claims related to recycled content and chemical safety. The tri suit category, with its reliance on virgin synthetics, is heavily impacted, accelerating R&D into bio-based elastane and recycled nylon alternatives to meet future compliance.
A notable behavioral shift involves athletes prioritizing objective performance data over brand legacy when making purchasing decisions. This trend disrupts traditional marketing, as consumers now actively seek out wind-tunnel test results or comparative hydrodynamic data, often shared through online communities and product reviewers. This data-driven selection process is most pronounced in mature triathlon markets like the United States and the United Kingdom.
Triathlon Clothing Market Segmentation
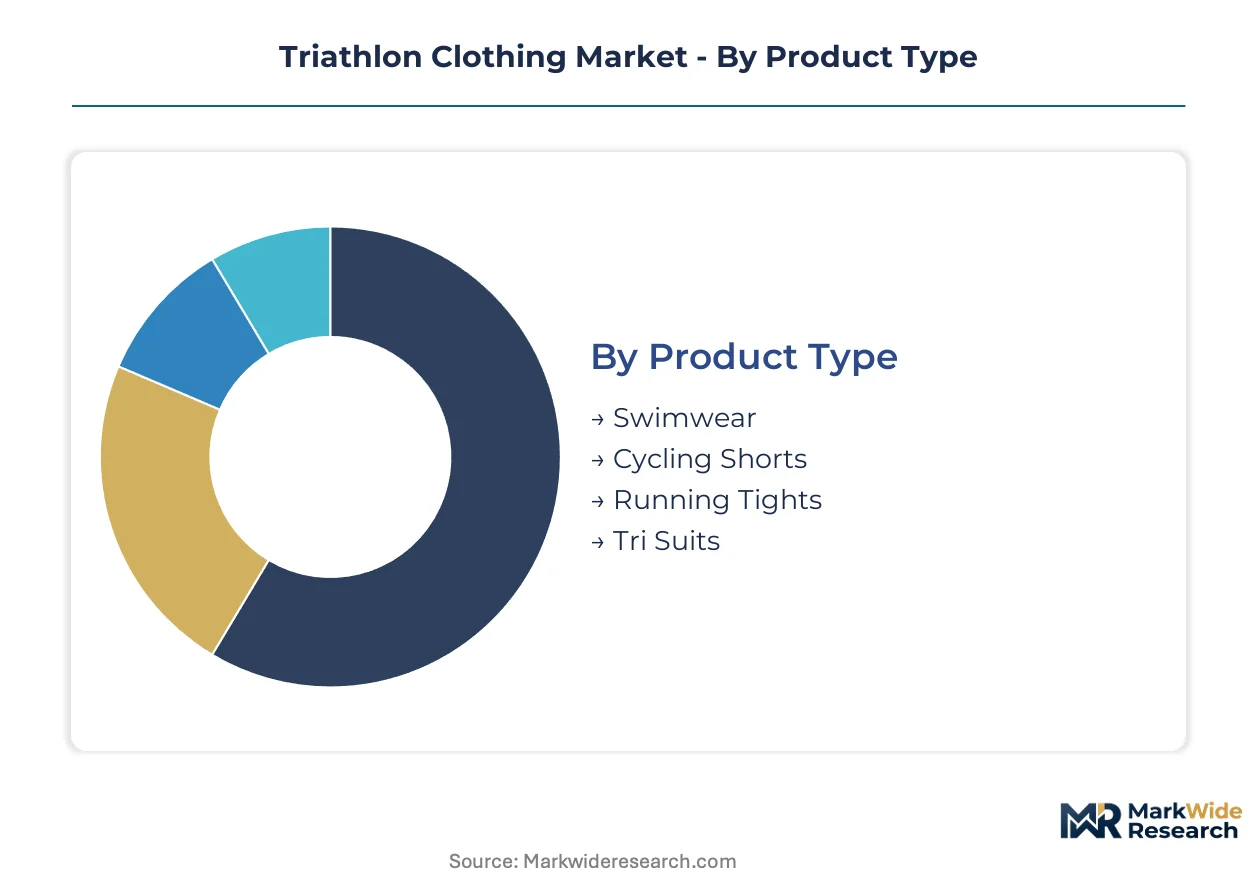
The triathlon clothing market segments across various dimensions, reflecting distinct performance needs and consumer preferences. Analyzing these segmentations provides a granular understanding of demand drivers and competitive landscapes. Manufacturers strategically align product development and distribution strategies with these defined market sub-groups.
Product Type:
Margin pools sit with high-performance integrated solutions within this category.
- Tri Suits:These all-in-one garments, typically constructed from hydrophobic polyester-spandex blends, integrate features for swimming, cycling, and running. Demand concentrates among committed amateur athletes in countries like Australia, seeking seamless transitions and aerodynamic benefits.
- Swimwear:Specialized triathlon swimwear includes jammers and speed suits, often featuring chlorine-resistant fabrics and hydrodynamic coatings for reduced drag. Professional athletes in the United Kingdom prioritize these garments for marginal gains in the swim leg.
- Cycling Shorts:Designed with integrated chamois padding, these shorts offer comfort and support during the bike leg of a triathlon. Entry-level participants often select these for training before investing in full tri suits.
- Running Tights:Compression running tights, made from moisture-wicking materials, support muscle recovery and improve blood circulation during the run. Fitness enthusiasts utilize these for general training and race day.
Tri Suits hold installed capacity. Swimwear is rotating up the share rankings.
Material:
Cost tier differentiates product offerings across this category.
- Spandex:This highly elastic synthetic fiber provides significant stretch and recovery, essential for muscle compression and unrestricted movement in triathlon apparel. Brands integrate spandex into blends for ergonomic fit, particularly in performance-oriented tri suits.
- Polyester:A durable and moisture-wicking synthetic, polyester forms the base for many triathlon garments, offering quick-drying properties and UV resistance. Its versatility makes it a staple for both entry-level and advanced clothing, especially in warmer climates.
- Nylon:Known for its strength and abrasion resistance, nylon is often blended with spandex to create resilient fabrics suitable for repeated use and harsh conditions. Technical swimwear frequently incorporates nylon for enhanced durability.
- Merino Wool:This natural fiber provides excellent thermoregulation and odor resistance, finding niche application in cooler climate triathlon apparel or recovery wear. Its premium cost limits widespread adoption in the core race-day segment.
Polyester-spandex blends command significant volume. Graphene-infused textiles are expanding most quickly.
End User:
Customer type drives demand for specific feature sets across this category.
- Amateur Athletes:This segment comprises the largest consumer base, seeking performance-oriented apparel that balances technical features with competitive pricing. Demand from amateur athletes drives innovation in accessible compression and quick-drying fabrics.
- Professional Athletes:Elite competitors demand the highest-performance, lightest, and most aerodynamic materials, often customized for specific race conditions. Their purchasing decisions heavily influence advanced material science developments like bio-ceramic infusions.
- Fitness Enthusiasts:Individuals engaged in multi-sport activities or general fitness, without specific triathlon race goals, purchase entry-level or versatile athletic wear. This group represents a funnel for future dedicated triathlon apparel consumers.
- Coaches:Triathlon coaches influence purchasing decisions through recommendations for training and race day gear. Their focus is on durability, comfort, and proven performance benefits for their athletes.
Amateur Athletes represent the largest consumer base. Professional Athletes are consistently demanding advanced material innovation.
Distribution Channel:
Volume flows through specific channels across this category.
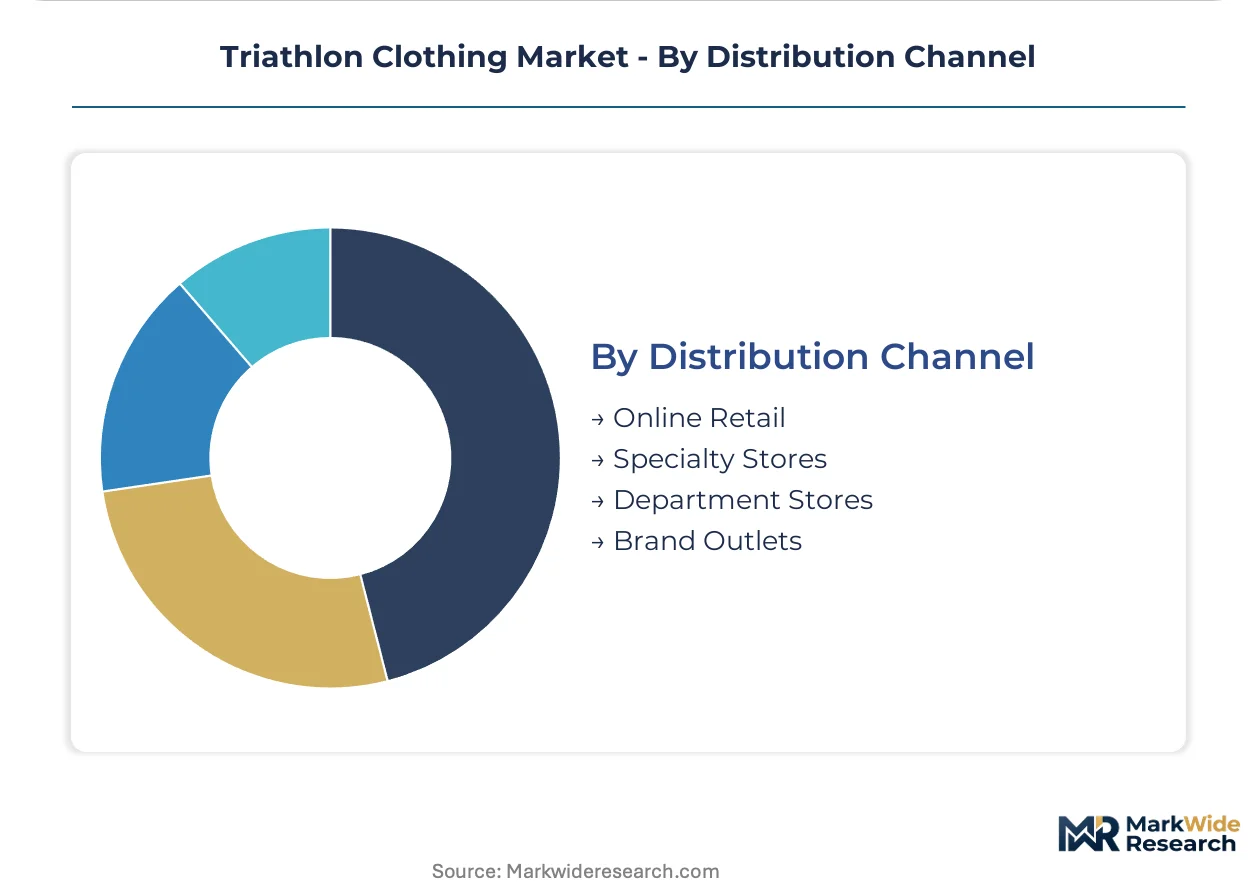
- Online Retail:E-commerce platforms offer a wide selection, price comparison, and direct-to-consumer access for triathlon clothing brands. This channel provides convenience and global reach for specialized apparel.
- Specialty Stores:Dedicated triathlon or multi-sport stores provide expert advice, fitting services, and a curated selection of high-performance gear. These stores cater to experienced athletes seeking personalized recommendations.
- Department Stores:Larger retail chains may carry a limited selection of general athletic or entry-level triathlon clothing. This channel appeals to casual fitness enthusiasts.
- Brand Outlets:Direct brand stores, both physical and online, allow manufacturers to control the customer experience and showcase their full product range. These outlets foster brand loyalty and offer exclusive products.
Online Retail represents the fastest-growing trajectory. Specialty Stores are gaining share through expert consultation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Committed amateur athletes drive significant demand across various global regions for specialized triathlon apparel. These consumers prioritize performance-oriented gear that offers both technical features and competitive pricing. This widespread interest shapes regional market dynamics.
United States
United States demand for triathlon clothing stems from a large base of amateur athletes and a strong health and wellness culture. The FTC enforces textile labeling requirements, ensuring product transparency for consumers. California's active lifestyle community, particularly around San Diego and San Francisco, drives significant sales of performance apparel.
Australia
Australia's robust triathlon culture and high participation rates create consistent demand for advanced apparel. The TGA may regulate certain performance-enhancing claims on specialized textiles. The Gold Coast region, known for its iconic triathlon events, acts as a hub for both training and retail activity.
Germany
Germany, an endurance-focused nation, exhibits strong demand for high-quality, technically advanced triathlon garments. The EU's REACH directive stringently restricts harmful chemicals in textiles, influencing material sourcing. Bavaria, with its numerous lakes and outdoor sports enthusiasts, represents a key consumer cluster for specialized gear.
United Kingdom
United Kingdom athletes increasingly prioritize objective performance data when selecting triathlon apparel. ISO standards for textile performance testing provide benchmarks for product durability and functional claims. London's vibrant urban athletic scene and surrounding national parks support a concentrated market for innovative sportswear.
Japan
Japanese consumers show growing interest in multi-sport disciplines, driving demand for innovative triathlon clothing. JIS standards ensure product quality and safety for textile imports and domestic manufacturing. The Tokyo metropolitan area, with its dense population and active lifestyle trends, represents a significant growth pocket.
Triathlon Clothing Market Key Industry Players
Player mix skews toward specialized performance brands alongside larger athletic apparel conglomerates. The market exhibits moderate fragmentation, with numerous smaller innovators competing against established players. Brands employ strategic partnerships for material science development and actively pursue geographic expansion into emerging triathlon markets. Portfolio diversification into related endurance sports apparel also defines competitive activity, aiming to capture a broader athlete base.
Within the performance-focused tier, Nike, a global sportswear giant, leverages extensive R&D capabilities to offer a broad range of athletic wear that includes triathlon-suitable options. Meanwhile, 2XU, known for its compression technology, exemplifies brands that specialize in technical apparel for endurance athletes. HUUB, a UK-based company, anchors the segment focused on hydrodynamic and aerodynamic innovations, catering to athletes seeking marginal gains in specific disciplines. These entities occupy distinct positions by emphasizing either broad market reach or deep specialization in material science.
| Leading Market Players |
|---|
| Nike |
| TYR Sport |
| 2XU |
| Castelli |
| Zone3 |
| Pearl Izumi |
| Adidas |
| HUUB |
| Zoot Sports |
| Others |
Cost & Logistics Intelligence
Capacity reservation agreements for specialized textile production lock in supply access and provide price visibility for brands in the triathlon clothing market, mitigating volatility for critical performance fabrics.
Pricing Analysis
Cost-plus contracts, often indexed to synthetic fiber prices, dominate agreements for specialized textile procurement in triathlon apparel. Brand premium and advanced material technology, such as hydrophobic coatings, drive significant price differentiation. Pricing softness stems from the increasing availability of mid-range performance wear for amateur athletes. Fitness enthusiasts show the highest price sensitivity, while professional athletes prioritize performance over cost.
Supply Chain Analysis
Increased inbound logistics costs, particularly for container availability from Asia, impact the profitability of triathlon clothing brands. Production of advanced synthetic fabrics concentrates in China, Vietnam, and Taiwan. The industry relies heavily on polyester-spandex blends and specialized hydrophobic chemicals, creating single-source vulnerability for niche performance textiles. Online retail represents the dominant downstream structure for specialized apparel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The triathlon clothing market is experiencing high-growth disruption, driven by the rapid adoption of bio-ceramic and graphene-infused textiles for performance gains. This technological inflection is redefining product benchmarks and consumer expectations.
For Market Incumbents:Consolidate market share by acquiring specialist brands focused on advanced material science, such as those innovating with bio-ceramic textiles. Deepen vertical integration into specialized fabric production to mitigate supply chain concentration risks from Asia. This counters the threat of inventory obsolescence and strengthens control over critical inputs. Invest in R&D to maintain a technological lead against emerging competitors.
For New Entrants and Emerging Players:Underserved climate-specific apparel needs present a significant white-space opportunity for new entrants. Target emerging triathlon markets in South America with apparel designed for enhanced UV protection in hot conditions. Focus on niche product development, like thermal layers for cold-water swims, to gain initial traction. Leverage direct-to-consumer e-commerce channels for efficient market entry and direct customer feedback.
For Investors and Strategic Acquirers:Capital is best deployed toward agile, R&D-intensive brands specializing in next-generation performance textiles. These companies offer long-term viability within the evolving triathlon apparel market over the next 5-10 years. Target acquisition profiles include innovators in graphene-infused or bio-based elastane fabrics. The continued expansion of global triathlon event participation serves as a key signal to watch for sustained market growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Material Science R&D Investment | Developing bio-ceramic and graphene-infused textiles provides a competitive edge in performance attributes for professional athletes. |
| Direct-to-Consumer Channel Expansion | Building e-commerce platforms strengthens brand relationships and captures higher margins from amateur athletes. |
| Sustainable Sourcing Integration | Adopting recycled nylon and bio-based elastane meets EU Green Deal mandates and attracts eco-conscious consumers. |
| Geographic Market Entry | Expanding into South America and Southeast Asia taps into growing participation rates in emerging triathlon markets. |
| Niche Product Line Development | Designing climate-specific apparel, like UV-protective suits, addresses underserved segments and diversifies revenue streams. |
Research Approach
Two parallel data streams informed the analysis: in-depth primary interviews and robust secondary research. Primary interviews engaged R&D directors, brand managers, procurement leads, and professional athletes across key regions. Secondary validation drew from textile industry reports, national sports federation data, customs records, and relevant regulatory filings like EU REACH documents. This approach ensured comprehensive bottom-up and top-down triangulation of market insights.
The forecasting boundary for this study extends across the analysis window, integrating a robust quantitative model. Segmentation dimensions modeled include product type, material, end user, distribution channel, and regional participation rates. Compound annual growth rates were derived from historical trends and projected participation increases. Key industry-specific forecast inputs included material science innovation timelines and new event sanctioning data.
Forecasts assume regulatory continuity in EU, US, and Australian regimes; material policy shifts would require re-modeling. The analysis accounts for potential supply chain disruptions and shifts in consumer preferences. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Italy 3D Printing Construction Market
Others
Global Smart Kitchen Market
Others
Hardwood Market
Others
Nuclear Power Cables Market
Others
Handheld Mobile Computers Market
Others
Finished Leather Market
Others
Egg and Egg Products Market
Others
Cloud Advertising Market
Others
Mexico Retail Market
Others
Composite Copper Foil Production Equipment Market
Others
Digital Audio Decoders Market
Others
Thailand Commercial Vehicles Lubricants Market
Others
Sprockets Market
Others
Semiconductor Gas Filters Market
Others
Bitcoin Mining Servers Market
Others
Latin America Smart Home Market