
 Global Solder Balls Market | 2026-2036
Global Solder Balls Market Size, Share, and Industry Trends Forecast 2026-2036
Global Solder Balls Market Foresight
Modular tape-and-reel packaging is pivoting how contract manufacturers manage solder ball inventory and feeding systems. Senju Metal Industry leverages its integrated melting-to-spheroidization capacity to sustain cost leadership across Asia-Pacific supply chains. Indium Corporation anchors North American demand through specialized alloy development for low-temperature reflow applications.
Solder balls are precision metal spheres, typically tin-based alloys with controlled diameters from 0.05 mm to 0.76 mm, manufactured through centrifugal atomization or micro-welding processes to achieve sphericity tolerances below 1%. These components function as interconnect elements in flip-chip, ball grid array, and chip-scale package assemblies, creating mechanical and electrical bonds between semiconductor dies and substrates. Lead-free formulations now dominate procurement volumes as RoHS-driven substitution has matured, though alloyed variants containing silver, copper, or bismuth command premium positioning for thermal cycling reliability. Electronics applications absorb the majority of output, with automotive-grade specifications emerging as the fastest-growing margin pool as advanced driver-assistance systems multiply joint-count requirements per vehicle.
EPA regulations in the United States restrict lead content in consumer electronics, while REACH and RoHS frameworks in Europe enforce substance restrictions and registration protocols that reshape supplier qualification pathways. Japan's METI promotes JIS standards for electronic materials that influence alloy composition specifications across export markets. Stakeholders must monitor evolving packaging form factors and regulatory substance lists to align alloy portfolios with next-generation interconnect demands.
Market Dynamics
Flip-chip packaging density requirements are compressing solder ball diameters below 0.15 mm while multiplying joint counts per die, forcing alloy suppliers to recalibrate spheroidization precision and thermal fatigue performance simultaneously.
Growth Catalysts
- Wafer-Level Packaging Expansion:Semiconductor foundries in Taiwan and South Korea are scaling 2.5D/3D integration, multiplying ball grid array joint density per substrate. This pulls demand for sub-200 micron spheres with enhanced coplanarity.
- RoHS-Driven Lead-Free Mandates:ECHA enforcement across Europe blocks tin-lead formulations from consumer electronics supply chains. Suppliers must qualify SAC305 and Sn-Ag-Cu-Bi variants to maintain market access.
- Automotive ADAS Proliferation:Advanced driver-assistance systems multiply sensor module counts per vehicle. Each radar and lidar unit requires ball grid array interconnects rated for -40°C to 150°C thermal cycling.
Market Restraints
- Tin Price Volatility:London Metal Exchange tin contracts fluctuate with Indonesian and Chinese smelter output disruptions. Alloy producers face margin compression when hedging fails to cover spot price spikes.
- Atomization Equipment Concentration:Centrifugal spheroidization systems with sub-1% tolerance capability concentrate among Japanese and German equipment builders. New entrants face 18-24 month lead times for precision melting infrastructure.
- SAC Alloy Brittleness:Silver-copper-tin formulations exhibit inferior drop-test performance versus legacy tin-lead. Handheld device manufacturers absorb higher warranty costs from solder joint fractures under mechanical shock.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor packaging attract Foxconn and Tata operations to Gujarat and Karnataka. Local solder ball production can bypass 15-20% import duties on precision alloys.
- Low-Temperature BiSn Formulations:Bismuth-tin eutectic alloys enable reflow below 140°C for flexible substrates and temperature-sensitive components. Wearable device assemblers adopt these for polymer-based circuit boards.
- Copper Pillar Bump Displacement:Fine-pitch flip-chip below 40 micron pitch favors copper pillar technology over solder balls. Alloy suppliers can pivot to cap-layer materials for hybrid interconnect schemes.
Industry Challenges
- Metallurgical Expertise Scarcity:Alloy development requires rare combinations of phase diagram modeling, surface oxidation control, and reliability testing. Foundries compete with battery and aerospace sectors for materials science PhDs.
- Dual-Certification Burden:Automotive-grade AEC-Q100 and consumer-grade JEDEC qualification run in parallel for 12-18 months. Smaller alloy houses lack capital to sustain dual-track testing programs.
- Spheroidization Yield Control:Satellite particle formation during centrifugal atomization wastes 8-12% of feedstock. Inline vision sorting adds capex without eliminating root-cause process variation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Solder Balls Market |
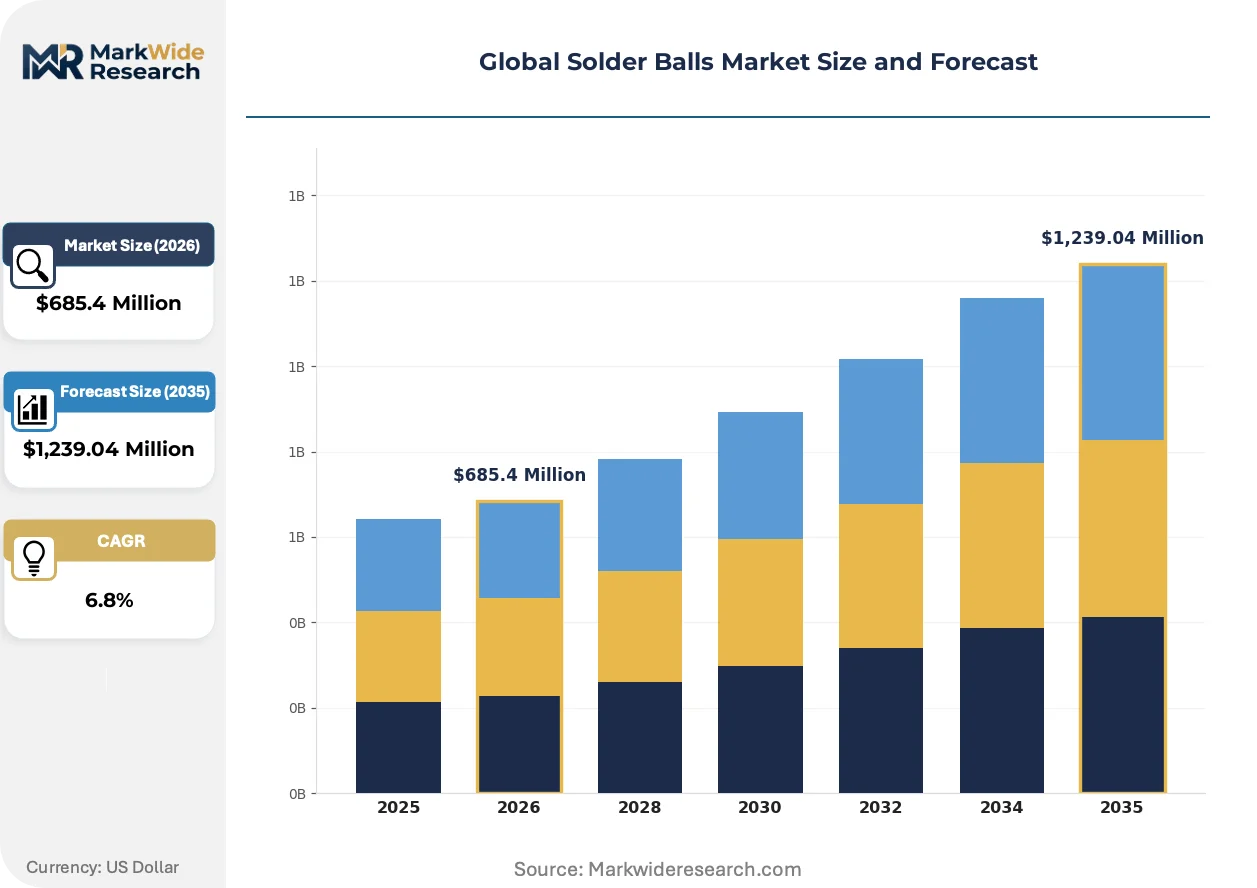
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Free, Leaded, Alloyed, Spherical Application: Electronics, Automotive, Aerospace, Industrial End User: OEMs, Contract Manufacturers, Retailers, Distributors Packaging Type: Bulk, Tapes, Trays, Foils |
| Companies Covered | Duksan Metal, Hitachi Metals Nanotech, Nippon Micrometal, Indium Corporation, Senju Metal Industry, DS HiMetal, Shenmao Technology, Accurus Scientific, Profound Material Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Solder Balls Market Shifts & Advancements
Alloy formulation roadmaps are diverging between high-reliability automotive specifications and cost-optimized consumer electronics grades, creating parallel supply chains with incompatible qualification protocols.
Micro-alloyed SAC compositions with deliberate germanium or nickel dopants are integrating into high-performance computing packages. AMD and NVIDIA datacenter GPUs adopt these variants for 1,000+ thermal cycle survival. The dopant additions suppress Kirkendall void formation at chip-package interfaces, extending mean-time-to-failure metrics that cloud infrastructure buyers demand.
REACH Annex XIV authorization procedures are expanding restricted substance lists to cover indium and bismuth precursors. European contract manufacturers must document supply chain due diligence for alloy additives above 0.1% weight thresholds. Medical device assemblers face the tightest compliance windows, with notified body reviews extending procurement lead times by 4-6 months.
Just-in-time consignment models are displacing bulk inventory ownership at EMS facilities. Foxconn and Jabil now require suppliers to maintain 2-4 weeks of finished goods within 50 kilometers of assembly plants. This compresses working capital cycles for alloy producers while transferring obsolescence risk from contract manufacturers to material vendors, with Taiwan and Mexico showing the fastest adoption velocity.
Global Solder Balls Market Segmentation
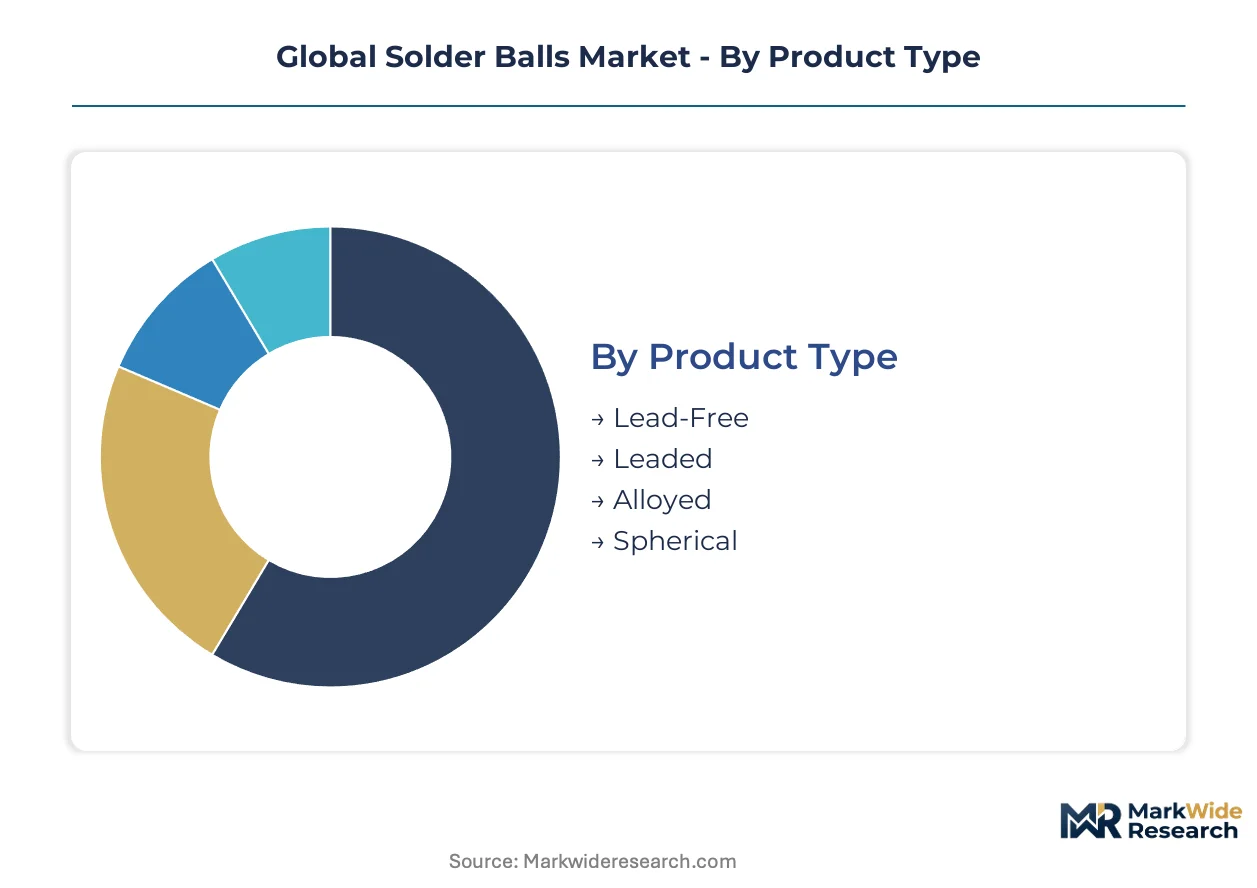
Solder ball procurement splits across incompatible qualification protocols that fragment supplier portfolios. Alloy composition and packaging format determine which certification tracks—automotive AEC-Q100, aerospace AS9100, or consumer JEDEC—vendors must navigate to access contract value.
Product Type:
Certification burden varies sharply: lead-free variants require RoHS documentation and REACH substance declarations, while leaded grades face EPA restrictions in US consumer electronics but retain military/aerospace exemptions through JEDEC J-STD-006B.
- Lead-Free:SAC305 and Sn-Ag-Cu-Bi formulations dominate volume as RoHS enforcement blocks tin-lead from European consumer supply chains. Taiwan semiconductor foundries specify sub-200 micron spheres for 2.5D packaging, forcing spheroidization precision upgrades.
- Leaded:Eutectic tin-lead retains niche positioning in aerospace and medical devices where JEDEC J-STD-006B grandfather clauses apply. US defense contractors absorb premium pricing for ITAR-controlled supply chains with full alloy traceability.
- Alloyed:Micro-doped compositions with germanium or nickel suppress Kirkendall voiding in datacenter GPU packages.
- Spherical:Centrifugal atomization achieves sub-1% sphericity tolerance for flip-chip coplanarity requirements.
Leading the category by volume: Lead-Free. Growing fastest: Alloyed.
Application:
Cost tier separation runs deepest here, with automotive-grade specifications commanding 40-60% premiums over consumer electronics grades for identical alloy compositions.
- Electronics:Smartphones and tablets absorb the majority of SAC305 volume. South Korean memory manufacturers specify tight diameter distributions for wafer-level packaging yield optimization.
- Automotive:ADAS sensor modules require -40°C to 150°C thermal cycling survival. Each radar unit multiplies ball grid array joint counts, pulling demand for high-reliability formulations through AEC-Q100 qualification tracks.
- Aerospace:AS9100 certification mandates lot traceability and vacuum packaging for high-altitude reliability.
- Industrial:Factory automation controllers specify tin-lead alternatives where RoHS exemptions for industrial equipment persist.
Highest margin capture: Automotive. Steepest expansion trajectory: Automotive.
End User:
Customer type determines inventory ownership models, with OEMs maintaining consignment stocks while contract manufacturers push vendor-managed inventory risk upstream.
- OEMs:Apple and Samsung direct procurement teams specify alloy compositions and audit spheroidization facilities. Their volume commitments justify dedicated production lines at Japanese suppliers.
- Contract Manufacturers:Foxconn and Jabil require 2-4 week finished goods buffers within 50 kilometers of assembly plants. This compresses working capital cycles for alloy producers.
- Retailers:Digi-Key and Mouser stock standard SAC305 grades for prototype and repair markets.
- Distributors:Arrow and Avnet manage allocation during tin price volatility spikes.
Dominant procurement volume: Contract Manufacturers. Fastest channel growth: OEM direct.
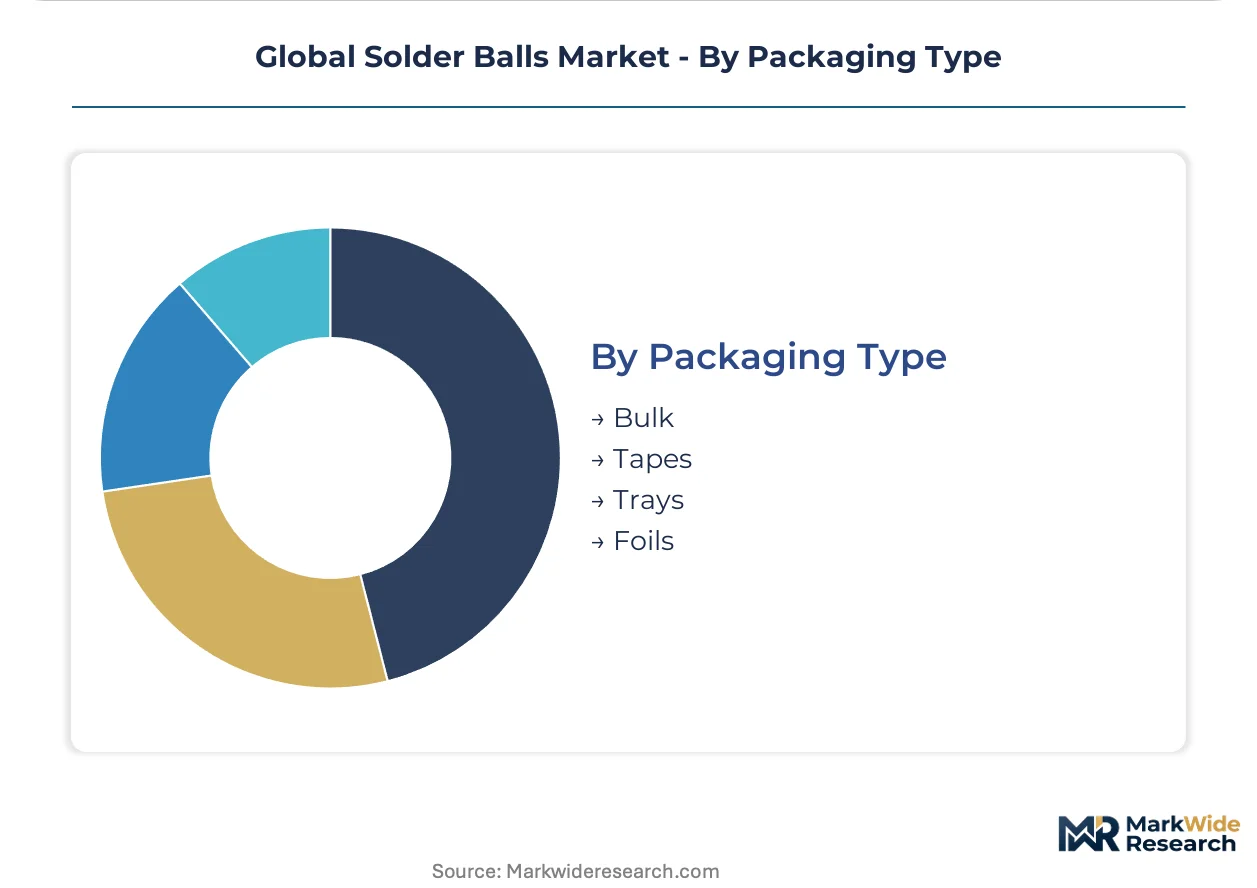
Packaging Type:
Supply concentration favors tape-and-reel formats where Japanese equipment builders control precision winding technology with 18-24 month lead times.
- Bulk:Foundries with in-house ball attach equipment purchase loose spheres in nitrogen-purged containers. This format minimizes per-unit packaging cost for high-volume consumers.
- Tapes:Modular tape-and-reel systems enable automated feeding at EMS lines. Japan's equipment builders dominate precision carrier tape production.
- Trays:JEDEC matrix trays protect coplanarity for large-diameter spheres in automotive module assembly.
- Foils:Preformed solder foil sheets serve niche rework and repair applications.
Widest adoption: Tapes. Gaining share fastest: Bulk for foundry direct.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian foundry clusters while consumption spreads across assembly operations in North America, Europe, and emerging Asian economies. Taiwan, South Korea, and Japan host the majority of flip-chip and wafer-level packaging capacity. This geographic split shapes alloy procurement patterns and regulatory compliance burdens.
Taiwan
Semiconductor foundries in Hsinchu Science Park and Taichung drive demand for sub-200 micron solder spheres with enhanced coplanarity. The island's EPA enforces hazardous substance reporting for electronic materials that exceeds RoHS baseline requirements. Tainan and Kaohsiung house precision spheroidization facilities serving TSMC and ASE Group packaging operations.
South Korea
Memory manufacturers in Icheon and Pyeongtaek specify tight diameter distributions for wafer-level packaging yield optimization. The Ministry of Environment operates a chemical substance registry that tracks alloy additives through supply chains. Samsung and SK Hynix packaging subsidiaries in Suwon and Yongin pull SAC305 volumes through consignment inventory models.
Japan
METI promotes JIS standards for electronic materials that influence alloy composition specifications across export markets. Senju Metal Industry leverages integrated melting-to-spheroidization capacity from its Akita and Ibaraki facilities. Osaka and Nagoya industrial clusters concentrate precision equipment builders with 18-24 month lead times for centrifugal atomization systems.
United States
Indium Corporation anchors North American demand through specialized alloy development for low-temperature reflow applications. EPA regulations restrict lead content in consumer electronics, creating compliance checkpoints for imported solder materials. Arizona and New Mexico host defense contractors absorbing premium pricing for ITAR-controlled tin-lead supply chains.
Germany
Automotive tier-one suppliers in Baden-Württemberg and Bavaria specify AEC-Q100 qualified alloys for ADAS sensor modules. ECHA enforcement of REACH Annex XIV authorization procedures blocks non-compliant formulations from European consumer supply chains. Stuttgart and Ingolstadt industrial corridors demand -40°C to 150°C thermal cycling survival for radar and lidar interconnects.
Global Solder Balls Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation, spheroidization, and packaging format vectors. The vendor base organizes around three strategic archetypes: integrated metal processors controlling upstream smelting, precision equipment operators with captive atomization capacity, and alloy designers specializing in thermal fatigue performance. Market access depends on dual-track qualification capabilities spanning automotive AEC-Q100 and consumer JEDEC protocols. Competitive moves concentrate on backward integration into tin smelting and geographic expansion into India's PLI-subsidized packaging corridors.
Within the integrated processing tier, Senju Metal Industry exemplifies the archetype of captive supply from melting through spheroidization. Among North American specialists, Indium Corporation occupies a position defined by low-temperature formulation expertise. DS HiMetal represents Korean fabricators with foundry-adjacent production positioning. These three anchors illustrate how geographic proximity to semiconductor packaging clusters determines procurement relationships and inventory ownership models.
| Leading Market Players |
|---|
| Duksan Metal |
| Hitachi Metals Nanotech |
| Nippon Micrometal |
| Indium Corporation |
| Senju Metal Industry |
| DS HiMetal |
| Shenmao Technology |
| Accurus Scientific |
| Profound Material Technology |
| Others |
Supply & Pricing Matrix
Semiconductor foundry procurement teams in Taiwan and South Korea command contract-based long-term offtake agreements that compress margin buffers for alloy suppliers during tin price spikes. Their volume concentration shifts pricing power toward buyers who consolidate SAC305 and Sn-Ag-Cu-Bi orders across multiple packaging facilities.
Pricing Analysis
Margin tightening in automotive-grade alloys reflects AEC-Q100 certification costs and lot-traceability documentation burdens that standard consumer electronics grades avoid. Pricing stratifies across automotive-certified, industrial-standard, and economy consumer tiers, with thermal cycling performance and alloy purity as the primary differentiation drivers. Cost-down pressure on SAC305 formulations accelerates because memory manufacturers in South Korea negotiate annual volume rebates exceeding foundry norms. Contract manufacturers exhibit the highest price sensitivity due to consignment inventory models that transfer working capital risk upstream, while defense contractors absorbing ITAR-controlled tin-lead supply chains show minimal elasticity.
Supply Chain Analysis
Direct-to-foundry channels handle hyperscale buyer demand from TSMC and Samsung packaging subsidiaries, bypassing distributor markups for sub-200 micron sphere orders. Raw material supply concentrates in Indonesia and China for tin smelting, with Japanese and German equipment builders controlling centrifugal spheroidization system production. Feedstock draws from London Metal Exchange contracts and captive mine operations, while the supply chain rests on single-source vulnerability for precision atomization equipment with 18-24 month procurement lead times. Distribution runs through just-in-time consignment hubs within 50 kilometers of major assembly plants in Taiwan, Mexico, and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Centrifugal spheroidization equipment scarcity props alloy pricing by constraining new entrant capacity additions. Foundry buyers absorb premium positioning for sub-150 micron spheres as qualified supplier lists remain short.
For Market Incumbents: Lock in backward integration into tin smelting to hedge London Metal Exchange volatility and secure feedstock during Indonesian export disruptions. Expand AEC-Q100 certification coverage ahead of automotive ADAS module proliferation that will disqualify consumer-grade suppliers. Defend against copper pillar bump displacement by developing cap-layer materials for hybrid interconnect schemes. For New Entrants and Emerging Players: Indian contract manufacturers assembling under PLI scheme incentives represent the most penetrable buyer archetype, with 15-20% import duty avoidance creating immediate cost positioning. Target Gujarat and Karnataka packaging corridors with local production of BiSn low-temperature formulations for wearable device assemblers. Pursue qualification partnerships with Foxconn and Tata operations before incumbent suppliers establish consignment inventory buffers. For Investors and Strategic Acquirers: The window for entry favors precision equipment operators with captive atomization capacity and existing JEDEC qualification tracks. Long-term viability centers on alloy houses serving dual automotive-consumer certification protocols that smaller competitors cannot sustain. Watch for tin price volatility spikes as inflection indicators that compress margins and trigger consolidation among undifferentiated suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tin Smelting | Captive feedstock supply hedges London Metal Exchange volatility for Senju Metal Industry and Korean fabricators. |
| AEC-Q100 Certification Investment | Automotive-grade qualification opens ADAS sensor module procurement from Bosch and Continental tier-one suppliers. |
| Low-Temperature BiSn Formulation Launch | Wearable device assemblers adopt sub-140°C reflow alloys for polymer-based flexible circuit boards. |
| Consignment Inventory Hub Expansion | Proximity buffers within 50 kilometers of Foxconn and Jabil plants satisfy just-in-time feeding requirements. |
| Cap-Layer Material Development | Hybrid copper pillar interconnect schemes preserve alloy supplier relevance as fine-pitch flip-chip displaces solder balls. |
Research Methodology
SEC 10-K filings, customs and trade databases, and semiconductor equipment shipment records formed the secondary backbone for this analysis. Primary interviews with alloy development directors, foundry procurement managers, and precision equipment sales engineers validated formulation roadmaps and capacity expansion timelines. Bottom-up triangulation across packaging format demand and top-down reconciliation with foundry capital expenditure disclosures ensured volume consistency.
Historical trendline analysis of wafer-level packaging adoption and thermal cycling reliability requirements established baseline growth patterns across the projection horizon. The analytical framework modeled alloy composition, application grade, end-user type, and packaging format as core segmentation dimensions. CAGRs derived from foundry capacity buildout schedules and automotive sensor module joint-count multipliers, with tin price scenario testing as a sensitivity input.
Revisions become necessary when Indonesian smelter export disruptions, REACH Annex XIV substance restrictions, or copper pillar technology adoption rates materially diverge from baseline assumptions. Forecasts reflect documented projections that semiconductor packaging form factor evolution and regulatory substance lists will proceed as modeled. Periodic stress-testing of base assumptions against equipment lead time extensions and qualification protocol changes is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Transparent Plastics Market
Others
Mobile Computer Cart Market
Others
Metal Ore Mining Market
Others
Augmented Reality (AR) in Warehousing and Logistics Market
Others
Hip Tendinitis Market
Others
Sound Reinforcement Market
Others
Asia-Pacific Agricultural Enzymes Market
Others
Global ESD Protection Devices Market
Others
Hopper Dryers Market
Others
Video Conferencing Hardware Market
Others
Indoor LBS Market
Others
Smartphone Gimbal Market
Others
Thiamethoxam Market
Others
Fire Sprinkler Market
Others
US Camping and Caravanning Market
Others
Italy Feed Additives Market