
 Tunnel Lighting Market | 2026-2036
Tunnel Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Tunnel Lighting Market Analysis
Software-defined adaptive control is restructuring tunnel lighting procurement, shifting capital expenditure toward recurring service contracts that bundle luminaire hardware with lifetime performance guarantees. Signify Holding leverages its Interact connected lighting platform to anchor long-term maintenance agreements across European alpine tunnel networks. Schréder competes through in-house photometric design capabilities that extend from fixture manufacturing to tunnel-specific glare modeling. Cree Lighting specializes in high-lumen-density LED engines that dominate North American DOT specifications for vehicular tunnel applications.
Tunnel lighting comprises engineered luminaire systems designed to maintain prescribed luminance levels measured in candelas per square meter across threshold, transition, interior, and exit zones, with critical emphasis on flicker-free operation below 200 Hz to prevent stroboscopic effects for drivers. LED product type now leads installed value due to lumen maintenance exceeding 100,000 hours and dimming granularity that fluorescent and HID sources cannot match. Smart lighting technology captures the fastest expansion as microwave and video-based traffic detection enables real-time lumen adjustment correlated to vehicle density. Road tunnels remain the dominant application segment, though mining tunnels in Australia and Chile generate premium pricing through explosion-proof certification requirements.
EU F-Gas Regulation and REACH chemical restrictions shape luminaire material selection across European tunnel projects, while CE marking under the Construction Products Regulation mandates photometric performance declarations. The US Federal Highway Administration's Roadway Lighting Handbook establishes luminance criteria that state DOTs adopt verbatim, creating a unified national specification landscape. China's GB standards for tunnel lighting, enforced by SAMR conformity assessment, require domestic project bids to source certified products. Stakeholders must monitor how evolving adaptive control protocols reshape supplier qualification criteria and long-term asset ownership models.
Market Dynamics
Adaptive control protocols are restructuring tunnel lighting procurement, converting capital-heavy luminaire sales into recurring service contracts that bundle hardware with lifetime performance guarantees and remote monitoring obligations.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of high-GWP refrigerants in tunnel climate systems forces simultaneous LED retrofits to reduce thermal load, accelerating luminaire replacement cycles across alpine corridor projects.
- China's Ministry of Transport mandate:Intelligent adaptive lighting becomes compulsory for new expressway tunnels, creating immediate specification demand for microwave detection and real-time dimming systems.
- Mountainous corridor density:Switzerland, Norway, and Japan maintain the world's highest tunnel density per kilometer of roadway, concentrating sustained maintenance and upgrade demand in geographically constrained markets.
Market Restraints
- Copper and aluminum price volatility:Luminaire housings and heat sinks depend on these base metals, with input cost swings compressing margin visibility for fixed-price installation contracts.
- Driver IC supply concentration:Tunable LED drivers for flicker-free operation below 200 Hz source predominantly from East Asian semiconductor foundries, creating single-point vulnerability for European and North American fixture assemblers.
- Legacy fluorescent infrastructure:Existing tunnel installations with magnetic ballast systems require complete rewiring for LED compatibility, extending payback periods and deferring municipal upgrade decisions.
Strategic Opportunities
- Mining tunnel explosion-proof certification:Australia's Bowen Basin and Chile's Atacama copper operations generate premium pricing for ATEX/IECEx certified luminaires with integrated gas detection interfaces.
- Photovoltaic-hybrid tunnel lighting:Convergence of bifacial solar panels with DC-native LED architectures enables off-grid threshold zone illumination in remote mountain tunnels, reducing grid connection costs.
- US IIJA infrastructure funding:Federal highway formula grants prioritize safety-critical tunnel modernization, directing capital toward states with highest vehicular tunnel inventory.
Industry Challenges
- Photometric design specialization scarcity:Tunnel-specific glare modeling and threshold zone luminance gradient calculation require expertise that outpaces current technical training pipeline output.
- CE marking documentation burden:Construction Products Regulation mandates for photometric performance declarations extend product qualification timelines by 8-14 months for non-European manufacturers.
- Interoperability fragmentation:Proprietary adaptive control protocols from competing connected lighting platforms prevent unified traffic management system integration, forcing redundant sensor deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tunnel Lighting Market |
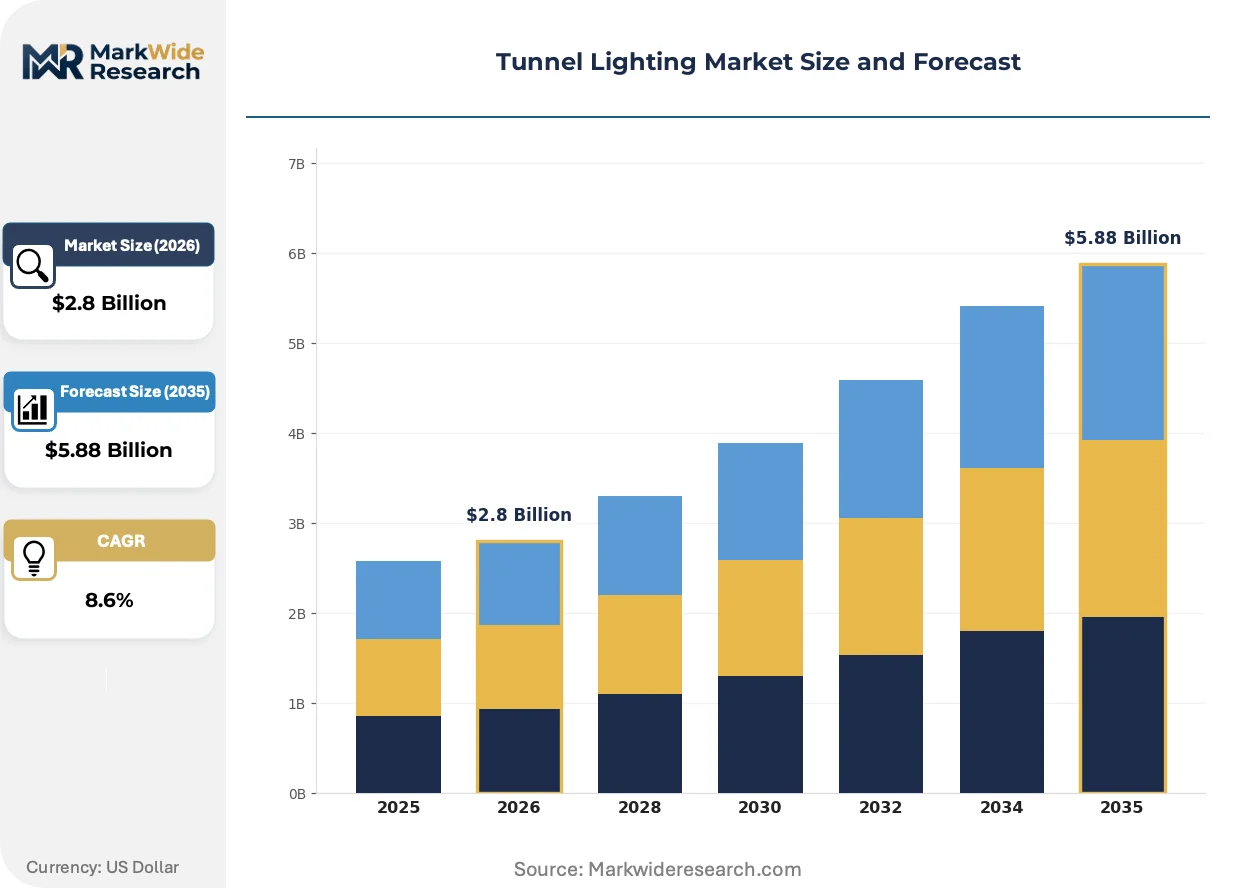
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, HID, Halogen Technology: Smart Lighting, Traditional Lighting, Solar Power, Energy-Efficient Systems Application: Road Tunnels, Railway Tunnels, Mining Tunnels, Waterway Tunnels End User: Government, Construction, Transportation, Utilities |
| Companies Covered | Signify Holding, Schréder, Cree Lighting, Acuity Brands, Zumtobel Group, Osram, General Electric, Thorlux Lighting, Aeon Lighting Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tunnel Lighting Market Emerging Trajectories
Control hardware separation from luminaire enclosures is enabling new procurement structures. Suppliers now unbundle intelligent nodes from optical engines, allowing infrastructure agencies to upgrade detection capabilities without fixture replacement.
Li-Fi optical wireless communication is modularizing tunnel connectivity architecture. This technology transmits traffic data and emergency signals through existing LED infrastructure. Alpine tunnel operators in Austria and Italy are piloting bidirectional light-based networks to eliminate redundant cabling runs. The approach is modularizing how tunnel communication backbones get deployed, compressing installation schedules by decoupling lighting and signaling contracts.
REACH chemical restrictions are forcing material substitutions in European luminaire manufacturing. ECHA substance of very high concern listings now cover specific flame retardants and coating chemistries previously standard in tunnel-rated housings. German and Swiss DOTs are responding with accelerated qualification programs for alternative polymer formulations, prioritizing suppliers with in-house materials testing laboratories.
Service contract unbundling is fragmenting traditional supplier relationships. Highway agencies now separately procure luminaire hardware, installation, and long-term performance guarantees through distinct RFP processes. This pattern is most visible in France and Spain, where concession-operated toll tunnels drive competitive separation of capital and operational expenditures to optimize lifecycle cost accounting.
Tunnel Lighting Market Segmentation
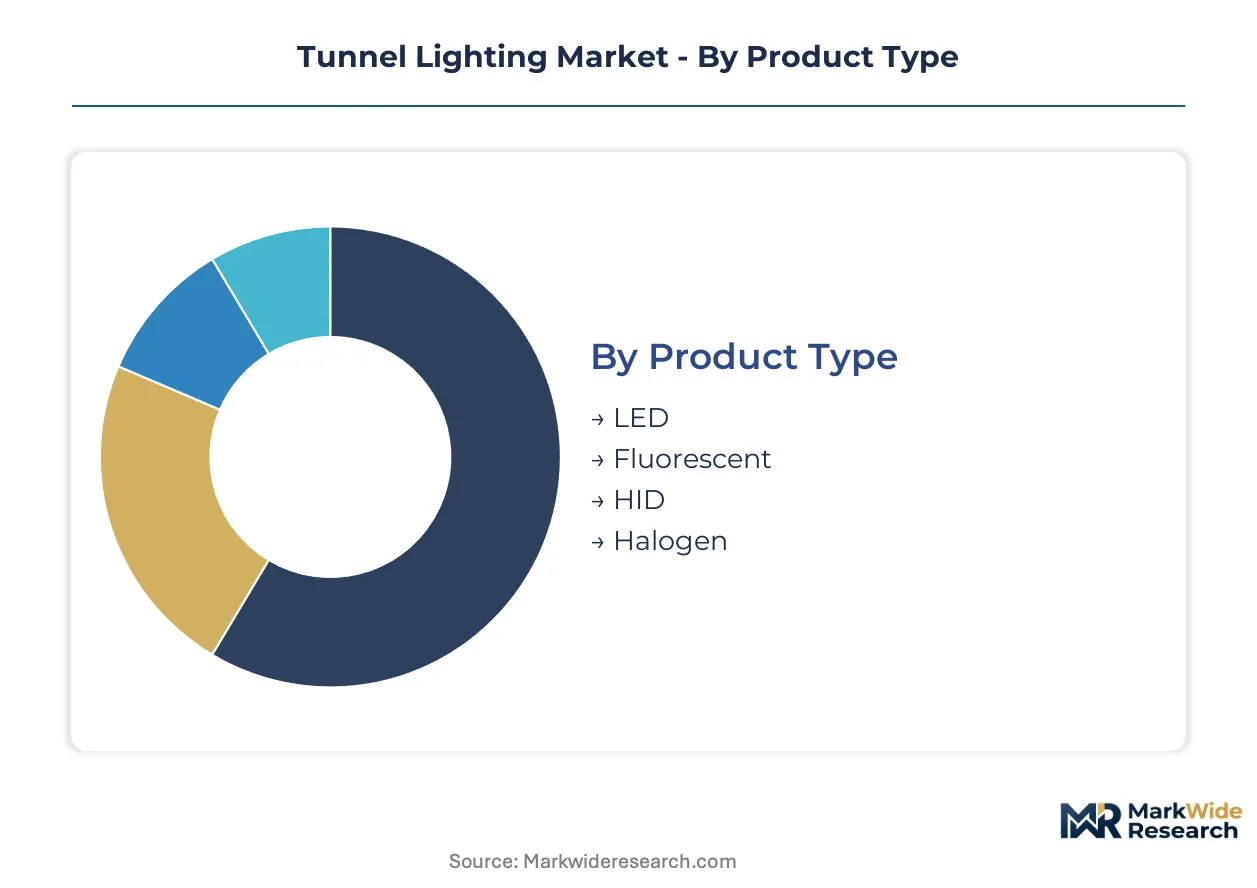
Tunnel lighting procurement diverges sharply between standalone fixture replacements and integrated adaptive control systems. Understanding these segment boundaries clarifies where capital expenditure concentrates versus where operational technology budgets flow.
Product Type:
Standalone luminaire sales dominate immediate replacement cycles, while embedded control modules reshape long-term procurement structures across highway agencies and mining operators.
- LED:Solid-state emitters delivering lumen maintenance exceeding 100,000 hours with dimming granularity down to 1% increments. Swiss and Norwegian alpine tunnel networks drive specification demand for flicker-free operation below 200 Hz under EU F-Gas Regulation compliance timelines.
- Fluorescent:Linear tube systems with magnetic ballast infrastructure requiring complete rewiring for LED retrofit compatibility. Municipal DOTs in Japan defer upgrade decisions where existing magnetic infrastructure extends payback periods beyond fiscal planning windows.
- HID:High-intensity discharge lamps including metal halide and high-pressure sodium variants. Mining tunnels in Chile's Atacama copper belt specify HID for explosion-proof fixture compatibility where LED certification gaps persist.
- Halogen:Tungsten-halogen incandescent sources with immediate full-output characteristics. Emergency backup systems in Swiss Gotthard Base Tunnel retain halogen for instantaneous threshold zone illumination during grid failure events.
LED leads volumes today; Smart Lighting integration is gaining share fastest.
Technology:
Cost tier separation distinguishes premium adaptive systems from commodity illumination, with solar-hybrid architectures emerging as a distinct mid-tier investment category.
- Smart Lighting:Microwave and video-based traffic detection enabling real-time lumen adjustment correlated to vehicle density. China's Ministry of Transport mandates intelligent adaptive lighting for new expressway tunnels, creating immediate specification pull through SAMR conformity assessment channels.
- Traditional Lighting:Fixed-output luminaires without detection integration or remote monitoring capabilities. Legacy installations across US state DOTs persist where IIJA funding prioritizes safety-critical modernization over efficiency upgrades.
- Solar Power:Bifacial photovoltaic panels paired with DC-native LED architectures for off-grid threshold zone operation. Remote mountain tunnels in Norway reduce grid connection costs through photovoltaic-hybrid deployment.
- Energy-Efficient Systems:High-efficacy luminaires meeting prescribed wattage-per-lumen thresholds without full adaptive control. Australian mining concessions specify energy-efficient fixtures for ATEX Zone 2 compliance where explosion-proof smart lighting remains cost-prohibitive.
Smart Lighting commands premium pricing; Solar Power is climbing the fastest as remote tunnel projects multiply.
Application:
Volume concentration in vehicular infrastructure contrasts with margin premium available in hazardous-environment certifications.
- Road Tunnels:Vehicular corridor illumination spanning threshold, transition, interior, and exit zones with prescribed luminance gradients measured in candelas per square meter. US Federal Highway Administration Roadway Lighting Handbook criteria create unified national specification adoption across state DOTs.
- Railway Tunnels:Electrified rail corridor lighting with electromagnetic interference shielding requirements. Swiss Federal Railways specify flicker-free operation synchronized to pantograph arcing frequencies in alpine tunnel segments.
- Mining Tunnels:Subterranean excavation lighting with ATEX/IECEx explosion-proof certification. Australia's Bowen Basin coal operations and Chile's copper mines generate premium pricing for integrated gas detection interfaces.
- Waterway Tunnels:Subaqueous conduit illumination with corrosion-resistant housing specifications. Japan's Seikan Tunnel and Channel Tunnel segments drive demand for pressure-rated luminaire enclosures.
Road Tunnels dominates installed base; Mining Tunnels shows steepest expansion trajectory on hazardous-environment pricing.
End User:
Customer type determines procurement modality, with government agencies favoring capital-heavy installation contracts and concession operators preferring service-based performance guarantees.
- Government:Highway infrastructure agencies and transport ministries specifying luminaires through public tender processes. France and Spain separate capital and operational expenditures across concession-operated toll tunnels to optimize lifecycle cost accounting.
- Construction:Engineering-procurement-construction contractors bundling lighting installation within broader civil works contracts. Alpine corridor projects in Switzerland concentrate demand for photometric design capabilities extending from fixture manufacturing to tunnel-specific glare modeling.
- Transportation:Railway operators and port authorities maintaining tunnel assets under performance-based maintenance agreements. Signify Holding anchors long-term service contracts through its Interact connected lighting platform across European networks.
- Utilities:Grid operators and energy distribution companies procuring tunnel lighting as grid-load management infrastructure. German and Swiss DOTs accelerate qualification programs for alternative polymer formulations under REACH chemical restrictions.
Government captures the largest contract value; Transportation is expanding most quickly through performance-based procurement conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland maintains the world's highest tunnel density per kilometer of roadway, while China's expressway construction program generates the largest absolute project pipeline for new tunnel installations.
United States
The Federal Highway Administration's Roadway Lighting Handbook establishes unified luminance criteria that state DOTs adopt verbatim, directing IIJA infrastructure funding toward safety-critical tunnel modernization. FHWA specifications create a coherent national procurement landscape across the Interstate highway system. California and Colorado mountain corridor projects concentrate demand for high-lumen-density LED engines in alpine tunnel networks.
China
The Ministry of Transport mandates intelligent adaptive lighting for all new expressway tunnels, creating immediate specification pull for microwave detection and real-time dimming systems. SAMR conformity assessment enforces GB standards that require domestic project bids to source certified products. Sichuan-Chongqing and Yunnan-Guizhou corridor projects drive volume concentration in mountainous western provinces.
Switzerland
Alpine tunnel density concentrates sustained maintenance and upgrade demand across the Gotthard and Lötschberg base tunnel networks. EU F-Gas Regulation compliance timelines accelerate LED retrofits to reduce thermal load in tunnel climate systems. The Swiss Federal Railways specify flicker-free operation synchronized to pantograph arcing frequencies in electrified rail segments.
Norway
Remote mountain tunnel projects reduce grid connection costs through photovoltaic-hybrid threshold zone illumination using bifacial solar panels with DC-native LED architectures. The Norwegian Public Roads Administration maintains strict photometric performance requirements for subsea tunnel installations. Western fjord corridor projects generate premium pricing for corrosion-resistant luminaire enclosures.
Japan
The Seikan Tunnel and metropolitan expressway networks drive demand for pressure-rated luminaire enclosures in subaqueous and high-traffic applications. METI energy efficiency standards accelerate fluorescent-to-LED conversion timelines across existing infrastructure. Honshu-Shikoku bridge-tunnel combinations concentrate specification demand for integrated emergency backup systems.
Tunnel Lighting Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with adaptive control platforms reshaping traditional fixture procurement relationships. The vendor base organizes around three archetypes: connected lighting platform operators, photometric design-integrated manufacturers, and high-lumen-density engine specialists. Competitive positioning depends on securing long-term service contracts versus winning discrete installation tenders. Geographic expansion through alpine corridor networks and technology licensing for smart detection protocols represent dominant competitive moves.
Within the connected lighting tier, Signify Holding anchors service-based positioning through platform-centric procurement models. Schréder and Cree Lighting exemplify contrasting specialization paths—one integrating photometric design capabilities from fixture manufacturing through tunnel-specific glare modeling, the other concentrating on vehicular tunnel specifications for North American DOT applications. These three companies represent the strategic archetype spectrum now dividing contract value between hardware sales and recurring performance guarantees.
| Leading Market Players |
|---|
| Signify Holding |
| Schréder |
| Cree Lighting |
| Acuity Brands |
| Zumtobel Group |
| Osram |
| General Electric |
| Thorlux Lighting |
| Aeon Lighting Technology |
| Others |
Supply Flow & Price Mechanics
Highway infrastructure agencies in North America and Europe concentrate procurement volume through multi-year framework agreements, anchoring contract-based pricing with performance guarantees and lifetime lumen maintenance clauses that bundle hardware with remote monitoring services.
Pricing Analysis
Capacity additions in China's LED component manufacturing base are reshaping price floors for commodity luminaires while premium adaptive systems retain margin insulation through proprietary control protocols. Three-tier pricing structure across premium smart-adaptive, standard LED retrofit, and economy fluorescent-replacement levels separates vendors by certification tier and after-sales bundling intensity. Price differentiation hinges on CE marking documentation completeness and SAMR conformity assessment status for Chinese project eligibility. Pricing pressure stems from copper and aluminum input cost volatility compressing margin visibility on fixed-price installation contracts. Municipal DOTs with constrained capital budgets exhibit highest price sensitivity, while mining operators in Australia and Chile prioritize ATEX certification over unit economics.
Supply Chain Analysis
ATEX/IECEx certification and CE marking under the Construction Products Regulation gate market access, extending qualification timelines by 8-14 months for non-European manufacturers and concentrating supply relationships with established testing laboratory networks. Manufacturing concentrates in China, Germany, and the United States, with Chinese foundries dominating tunable LED driver IC production for flicker-free operation below 200 Hz. Raw material dependencies span aluminum for luminaire housings, copper for thermal management components, and rare-earth phosphors for LED color rendering. Single-source vulnerability in East Asian semiconductor foundries creates supply chain risk for European and North American fixture assemblers. Distribution runs through engineering-procurement-construction contractors bundling lighting within broader civil works contracts and direct sales to concession-operated toll tunnel operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tunnel lighting market functions as a geographic-arbitrage play where EU F-Gas Regulation compliance timelines in alpine corridors accelerate premium retrofit demand while China's Ministry of Transport mandates create volume pull at lower price points.
For Market Incumbents: To counter proprietary adaptive control protocol fragmentation forcing redundant sensor deployment, anchor long-term service contracts through connected lighting platforms that bundle hardware with lifetime performance guarantees. Prioritize in-house photometric design capabilities extending from fixture manufacturing to tunnel-specific glare modeling to defend specification position in Swiss and Norwegian alpine corridor projects. Accelerate qualification programs for REACH-compliant alternative polymer formulations to maintain European market access.
For New Entrants and Emerging Players: The 40-60% price-point gap between premium smart-adaptive systems and economy LED retrofits in North American state DOT procurement creates entry space for mid-tier vendors offering microwave detection without full platform integration. Target mining tunnel applications in Australia's Bowen Basin and Chile's Atacama where explosion-proof certification gaps persist and premium pricing tolerates new supplier qualification timelines. Pursue photovoltaic-hybrid threshold zone architectures for remote Norwegian mountain tunnels as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: Connected lighting platform operators are the most active acquirer in this space, consolidating adaptive control capabilities to anchor recurring service contract revenue streams. Long-term viability over a 5-10 year horizon hinges on conversion of capital-heavy luminaire sales toward subscription-based performance guarantees. Acquisition targets should display in-house photometric design specialization and established CE marking documentation pathways. Watch for material shifts in IIJA infrastructure funding allocation across US state DOTs as an inflection indicator for North American demand trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Control Platform Integration | Signify Holding anchors long-term maintenance agreements through Interact platform deployment across European alpine networks. |
| Photometric Design Capability Buildout | Schréder extends from fixture manufacturing to tunnel-specific glare modeling for Swiss Gotthard corridor specifications. |
| Explosion-Proof Certification Investment | ATEX/IECEx qualification unlocks premium pricing in Australia's Bowen Basin coal operations and Chilean copper mines. |
| Photovoltaic-Hybrid Architecture Development | Bifacial solar-DC LED convergence reduces grid connection costs for Norwegian Public Roads Administration remote tunnel projects. |
| REACH-Compliant Material Substitution | German and Swiss DOTs accelerate alternative polymer qualification programs under ECHA substance restrictions. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with tunnel infrastructure agency procurement officers, lighting manufacturer product managers, and EPC contractor project directors alongside secondary validation through EU F-Gas Regulation implementation reports, US Federal Highway Administration Roadway Lighting Handbook specifications, and China SAMR conformity assessment databases. Bottom-up and top-down triangulation cross-validates luminaire shipment data against tunnel project completion records and adaptive control system installation permits.
Granularity-level framing models product type at LED-fluorescent-HID-halogen resolution, technology at smart-traditional-solar-energy-efficient tiering, and application at road-rail-mining-waterway segmentation, with end-user procurement modality distinguishing government capital expenditure from concession operator service contracts. CAGRs derive from installation base replacement cycle analysis and new expressway tunnel construction pipeline assessment across the projection horizon. Industry-specific forecast inputs include EU F-Gas Regulation compliance timeline adherence and China's Ministry of Transport mandate implementation velocity.
The model assumes a particular technology adoption path; alternative pathways for Li-Fi optical wireless communication or DC-native photovoltaic architectures would alter the outlook. Forecasts reflect assumptions regarding copper and aluminum price stability, East Asian semiconductor foundry capacity allocation, and REACH chemical restriction enforcement intensity. A model refresh is warranted upon material change in IIJA infrastructure funding disbursement patterns or SAMR conformity assessment protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Hybrid Switchgear Market
Others
Sprockets Market
Others
Industrial Hooters Market
Others
Industrial Air Purifiers Market
Others
Mini Personal Computer Market
Others
Czech Republic Market
Others
Subtilisin Market
Others
Toy Packaging Market
Others
Global Essential Oils and Plant Extracts for Livestock Market
Others
Process Spectroscopy Market
Others
Europe Astrology Market
Others
India Home Automation Market
Others
Connected Living Room Market
Others
Electric Chainsaw Market
Others
Coriolis Meters Market
Others
China 3D Printing Construction Market