
 Massive Machine Type Communication in Healthcare Market | 2026-2036
Massive Machine Type Communication in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Massive Machine Type Communication in Healthcare Market Foresight
Aftermarket service revenue for connected medical device platforms is fragmenting across hardware vendors, network operators, and software integrators. Huawei Technologies leverages its end-to-end 5G infrastructure stack to anchor large-scale hospital deployments in Asia. Nokia Corporation competes through specialized private wireless solutions that sustain high-reliability connectivity for critical care telemetry.
Massive Machine Type Communication in Healthcare denotes low-power, wide-area cellular connectivity enabling simultaneous transmission from thousands of medical endpoints with latency tolerances above one second and payload sizes below one kilobyte; its primary purpose is continuous, unattended physiological data collection without human-triggered session initiation. The Remote Patient Monitoring application segment leads current deployment volumes, while Smart Wearables concentrates fastest growth as consumer-grade biosensors achieve clinical validation. Telemetry Systems within the device type dimension commands premium margins due to stringent FDA 510(k) clearance requirements and hospital procurement cycles.
FDA cybersecurity guidance, EU MDR Annex I software requirements, and HIPAA security rule enforcement collectively elevate compliance costs for device manufacturers seeking multi-jurisdiction market access. EMA notified body capacity constraints in Europe are extending certification timelines, compressing first-mover advantages for early filers. Stakeholders must monitor spectrum allocation decisions by national regulators and prioritize modular architectures that accommodate evolving encryption mandates without hardware replacement.
Market Dynamics
5G network densification is compressing deployment timelines for cellular-enabled medical endpoints, while FDA and EU MDR cybersecurity mandates are forcing hardware redesign cycles that favor modular, firmware-upgradable architectures over fixed-function devices.
Growth Catalysts
- Hospital digitization mandates:Germany's Hospital Future Act allocates dedicated funding for connected care infrastructure, accelerating procurement of certified telemetry platforms.
- 5G standalone rollout:Network slicing capabilities enable guaranteed quality-of-service for critical patient data streams without contention from consumer traffic.
- EU MDR software classification:Annex I requirements for connected devices create compliance-driven replacement demand for legacy monitoring hardware lacking cybersecurity documentation.
Market Restraints
- Semiconductor supply concentration:Cellular modem fabrication concentrates among three foundry operators, exposing device manufacturers to allocation volatility.
- EMA notified body capacity:Certification backlog extends market entry timelines for novel connected medical devices by 8-14 months.
- Wi-Fi 6E substitution:Unlicensed spectrum alternatives erode addressable market for low-complexity cellular endpoints in controlled hospital environments.
Strategic Opportunities
- Home-based acute care expansion:Post-discharge monitoring protocols in the United States create demand for consumer-form-factor devices with clinical-grade validation.
- AI-at-the-edge convergence:On-device inference engines combined with mMTC radios enable anomaly detection without cloud round-trip latency.
- India's PLI scheme for telecom equipment:Domestic manufacturing incentives reduce landed cost for cellular modules serving price-sensitive diagnostic device makers.
Industry Challenges
- Firmware security engineering talent:Shortage of embedded systems specialists with medical device cybersecurity experience delays product validation.
- Legacy HIS integration:Hospital information systems built on proprietary protocols require costly middleware development for seamless data ingestion.
- Post-market surveillance compliance:FDA's 2023 cybersecurity guidance demands continuous vulnerability monitoring across deployed device fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Massive Machine Type Communication in Healthcare Market |
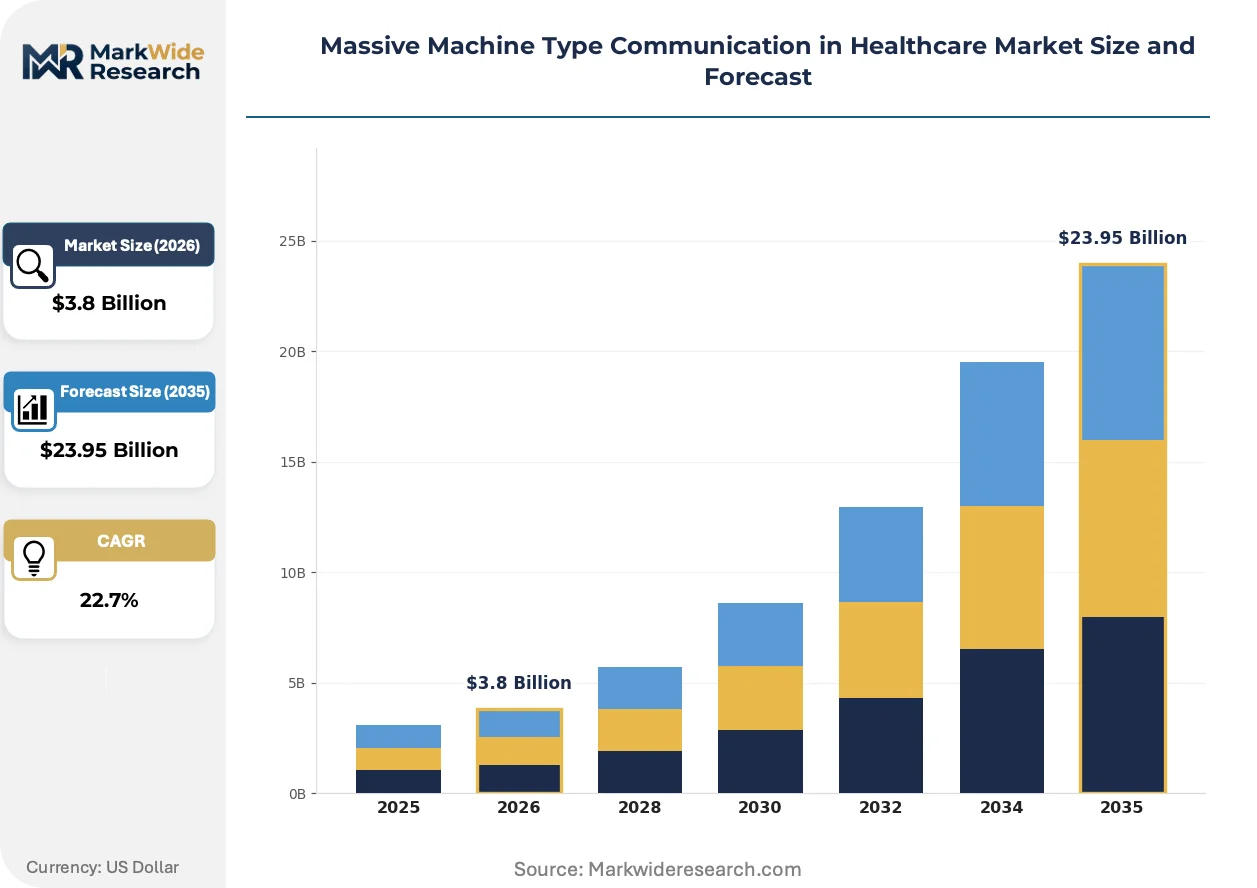
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.95 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Narrowband IoT, LTE-M, Sigfox, LoRaWAN Application: Remote Patient Monitoring, Asset Tracking, Smart Wearables, Telehealth Solutions End User: Hospitals, Clinics, Rehabilitation Centers, Home Healthcare Providers Device Type: Wearable Devices, Medical Sensors, Telemetry Systems, Diagnostic Equipment |
| Companies Covered | Huawei Technologies, Telefonaktiebolaget LM Ericsson, Nokia Corporation, Cisco Systems, Panasonic Holdings Corporation, Samsung Electronics, Qualcomm Incorporated, Intel Corporation, Vodafone Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Massive Machine Type Communication in Healthcare Market Shifts & Advancements
Three intersecting developments are restructuring how physiological data flows from patient to provider: radio technology evolution, regulatory software mandates, and procurement model transformation.
Reduced capability (RedCap) 5G is collapsing the power-performance tradeoff that previously forced device makers to choose between LTE-M battery life and 5G bandwidth. Chronic disease management platforms in Germany and Japan are piloting RedCap modules for continuous glucose monitors, enabling 10-year battery targets with megabit-per-second uplink speeds. This compression eliminates the need for dual-radio designs that combined narrowband-IoT fallback with high-power cellular burst modes.
EU MDR Annex I software requirements are forcing connected device manufacturers to document cybersecurity controls through the entire product lifecycle. The regulation treats patient data integrity as a safety-critical function equivalent to hardware failure modes, requiring threat modeling documentation for every firmware update. European hospital procurement committees now prioritize vendors with established software bill of materials practices, disadvantaging hardware-centric suppliers lacking in-house security engineering.
Subscription-based device provisioning is displacing capital purchase models for remote patient monitoring deployments. Health systems in the United States increasingly contract with platform operators who retain device ownership and bundle connectivity, cloud storage, and clinical decision support into per-patient-month fees. This shift transfers obsolescence risk from hospital IT departments to vendors, incentivizing modular hardware architectures that accommodate radio generation upgrades without full device replacement.
Massive Machine Type Communication in Healthcare Market Segmentation
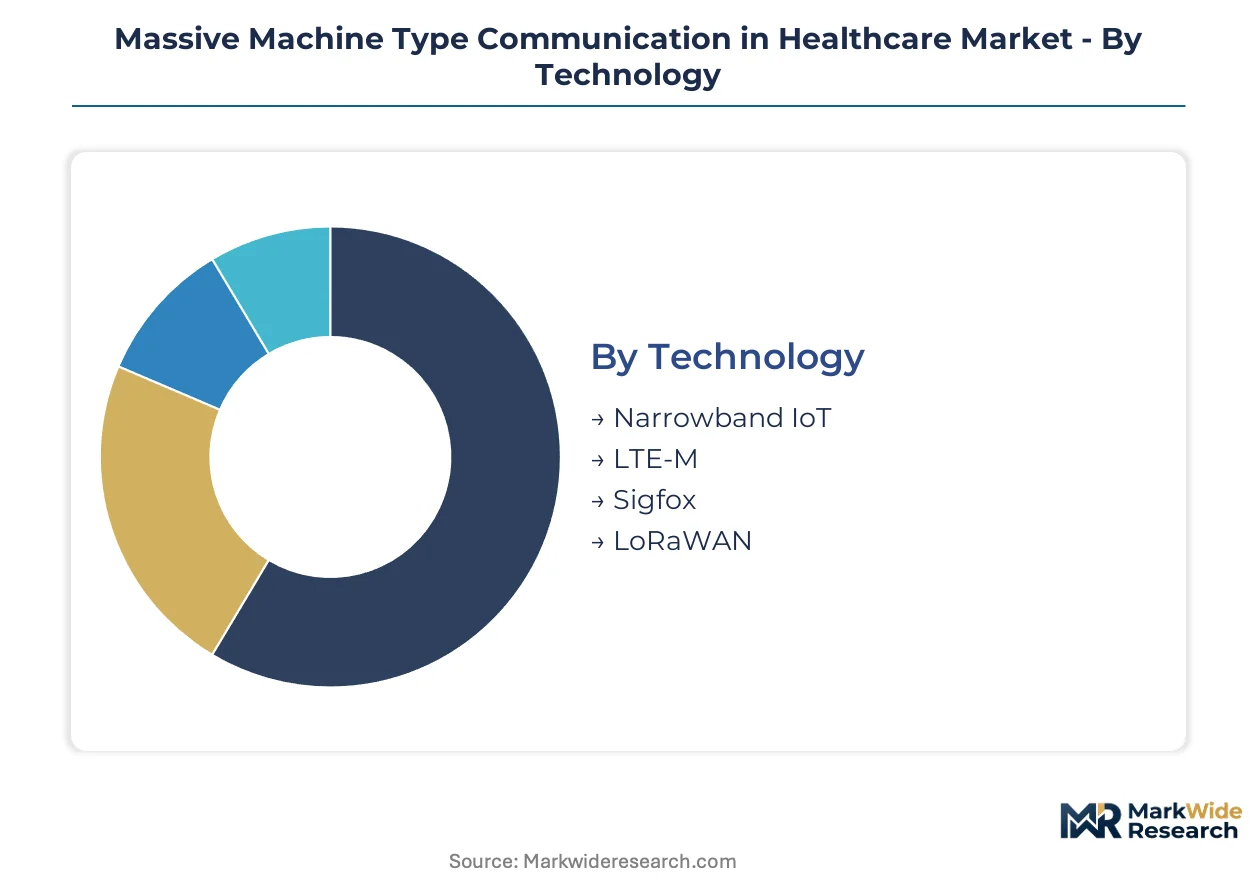
Massive Machine Type Communication in Healthcare segments diverge sharply in service intensity, with telemetry platforms demanding continuous firmware maintenance while disposable sensors require minimal post-deployment support. Procurement patterns across these segments reflect diverging regulatory burdens and hardware refresh cycles that reshape vendor economics.
Technology:
After-sales service intensity varies dramatically across connectivity standards, with cellular technologies locking manufacturers into multi-year carrier certification commitments while unlicensed alternatives shift support burdens to end-user IT departments.
- Narrowband IoT:Ultra-low-power cellular protocol optimized for intermittent data bursts from stationary medical endpoints. German hospital networks concentrate procurement for chronic disease monitoring where decade-long battery life outweighs bandwidth constraints.
- LTE-M:Enhanced machine-type communication standard delivering voice support and mobility management for ambulatory patient scenarios. United States health systems favor this technology for post-discharge monitoring programs where seamless handoffs between cell towers ensure data continuity during patient transport.
- Sigfox:Proprietary ultra-narrowband network operating in unlicensed spectrum with national coverage obligations varying by market. France and Spain host the densest public infrastructure deployments for low-cost asset tracking applications.
- LoRaWAN:Open-standard long-range radio enabling private network deployment within hospital campuses. Academic medical centers in the Netherlands and Switzerland leverage this flexibility for localized sensor grids without recurring carrier fees.
By volume, Narrowband IoT leads. By growth pace, LTE-M is ahead.
Application:
Cost tier stratification separates capital-intensive hospital infrastructure from consumer-accessible peripherals, with reimbursement codes determining viable price points across each application cluster.
- Remote Patient Monitoring:Continuous physiological surveillance for post-acute and chronic populations requiring clinical-grade data validation. United States Medicare reimbursement expansion for remote therapeutic monitoring concentrates demand among cardiology and pulmonology practices.
- Asset Tracking:Real-time location systems for mobile medical equipment reducing capital duplication and rental expenses. Japanese hospital networks prioritize these deployments to optimize utilization rates for infusion pumps and ventilators.
- Smart Wearables:Consumer-form-factor biosensors achieving clinical validation for prescribed therapeutic monitoring. South Korean digital health platforms drive fastest expansion through insurance-subsidized chronic disease management programs.
- Telehealth Solutions:Integrated audio-video and biometric transmission platforms enabling synchronous virtual consultations. India's national telemedicine guidelines accelerate procurement for rural primary care connectivity.
Remote Patient Monitoring captures the largest revenue pool. Smart Wearables climbs the fastest.
End User:
Customer type dictates purchasing authority complexity, with hospital procurement committees enforcing stringent cybersecurity documentation while home healthcare agencies prioritize plug-and-deploy simplicity.
- Hospitals:Acute care institutions with dedicated biomedical engineering departments managing fleet-scale device deployments. Germany's Hospital Future Act directs public funding toward certified telemetry infrastructure in university hospitals.
- Clinics:Outpatient facilities requiring streamlined integration with electronic health record systems. United States federally qualified health centers concentrate demand for cost-optimized remote monitoring bundles.
- Rehabilitation Centers:Post-acute facilities tracking functional recovery metrics through wearable motion sensors. Japan's aging population drives expansion in stroke and orthopedic rehabilitation monitoring.
- Home Healthcare Providers:Agencies managing dispersed patient populations through cellular-connected devices with minimal technical support. Brazil's expanding home care market prioritizes Portuguese-language device interfaces and local technical support.
Hospitals dominate absolute spending. Home Healthcare Providers expand most quickly.
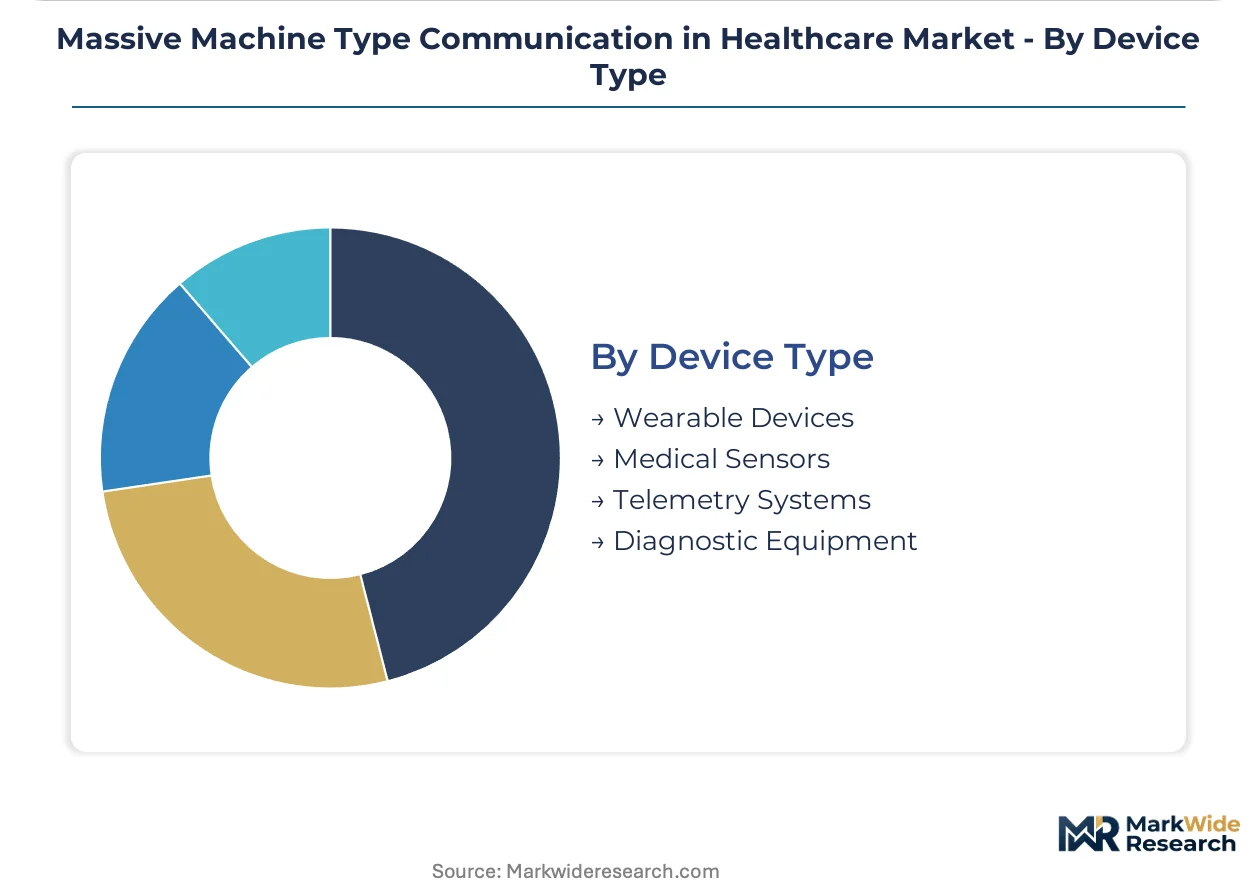
Device Type:
Margin structures correlate inversely with regulatory pathway complexity, with FDA 510(k) clearance requirements sustaining premium pricing for telemetry systems while commodity sensors compete on manufacturing scale.
- Wearable Devices:Body-worn biosensors measuring vital signs through optical, electrical, or mechanical transduction. Apple and Samsung consumer watch ecosystems pressure clinical-grade manufacturers to match form factors while maintaining FDA validation.
- Medical Sensors:Single-parameter measurement endpoints for glucose, blood pressure, or oxygen saturation. Chinese diagnostic device makers leverage domestic module supply to serve price-sensitive developing markets.
- Telemetry Systems:Multi-parameter patient monitors transmitting continuous data streams to central nursing stations. FDA cybersecurity guidance and EU MDR software requirements elevate engineering costs and extend development timelines for new entrants.
- Diagnostic Equipment:Connected imaging and laboratory instruments enabling remote quality control and predictive maintenance. Siemens Healthineers and GE Healthcare anchor this segment with integrated service contracts spanning hardware and connectivity.
Telemetry Systems command the highest unit margins. Wearable Devices gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cellular module fabrication concentrates among three foundry operators, exposing device manufacturers in Germany, the United States, Japan, and South Korea to allocation volatility. Hospital digitization programs and 5G infrastructure deployment timelines diverge sharply across these markets.
Germany
The Hospital Future Act allocates dedicated funding for connected care infrastructure, accelerating procurement of certified telemetry platforms. EU MDR Annex I software requirements elevate compliance costs for connected medical devices lacking cybersecurity documentation. Bavaria's university hospital networks concentrate pilot deployments of RedCap-enabled continuous glucose monitors.
United States
Medicare reimbursement expansion for remote therapeutic monitoring concentrates demand among cardiology and pulmonology practices. FDA's 2023 cybersecurity guidance mandates continuous vulnerability monitoring across deployed device fleets. Greater Boston's academic medical centers anchor early adoption of AI-at-the-edge inference engines for anomaly detection.
Japan
Post-acute facilities tracking functional recovery metrics drive expansion in stroke and orthopedic rehabilitation monitoring. METI's digital health investment programs subsidize private wireless network deployment in rural prefectures. Tokyo's hospital networks prioritize real-time location systems for mobile medical equipment to optimize utilization rates.
South Korea
Insurance-subsidized chronic disease management programs propel fastest expansion in consumer-form-factor biosensors achieving clinical validation. MFDS streamlined approval pathways for software-as-a-medical-device compress time-to-market for connected diagnostic platforms. Seoul Capital Area's digital health platforms anchor subscription-based device provisioning models.
India
The PLI scheme for telecom equipment reduces landed cost for cellular modules serving price-sensitive diagnostic device makers. CDSCO's evolving software medical device regulations create compliance uncertainty for first-generation connected monitors. Maharashtra's medical device manufacturing clusters concentrate domestic assembly of narrowband-IoT-enabled sensors.
Massive Machine Type Communication in Healthcare Market Competitive Landscape
Telecommunications infrastructure vendors and specialized medical device connectivity providers split the market along capability boundaries. Tier-one network equipment suppliers anchor large-scale hospital deployments through end-to-end 5G infrastructure stacks. Specialized private wireless solution providers sustain high-reliability connectivity for critical care telemetry. Dominant competitive moves include strategic partnerships between cellular module manufacturers and diagnostic device makers, plus geographic expansion through regulatory certification stacking across multiple jurisdictions.
Within the infrastructure-tier, Huawei Technologies and Nokia Corporation exemplify divergent strategic positioning. Huawei leverages its integrated 5G equipment portfolio to anchor deployments across Asian hospital networks. Nokia competes through specialized private wireless solutions that emphasize reliability engineering for life-critical data transmission. Telefonaktiebolaget LM Ericsson occupies a position between these archetypes, balancing macro-network infrastructure with enterprise-focused private cellular offerings. Samsung Electronics and Qualcomm Incorporated sit within the semiconductor-tier, supplying cellular modems and system-on-chip platforms that power third-party medical device integration.
| Leading Market Players |
|---|
| Huawei Technologies |
| Telefonaktiebolaget LM Ericsson |
| Nokia Corporation |
| Cisco Systems |
| Panasonic Holdings Corporation |
| Samsung Electronics |
| Qualcomm Incorporated |
| Intel Corporation |
| Vodafone Group |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor's freight rate volatility transmits directly into landed costs for cellular modem modules, amplifying margin pressure on device manufacturers while enabling pricing power for semiconductor foundries with captive logistics contracts. This dynamic concentrates cost differentiation between hospital-grade telemetry systems and consumer-form-factor wearables, as FDA and EU MDR compliance documentation requirements widen the procurement premium for certified endpoints.
Pricing Analysis
FDA 510(k) clearance pathways and EU MDR Annex I software documentation mandates dictate the pricing tier structure across connected medical device categories. Three-tier pricing stratifies across premium telemetry platforms with full cybersecurity validation, standard monitoring hardware with regional certification only, and economy sensor modules lacking clinical-grade documentation. Price differentiation centers on certification depth and after-sales firmware maintenance bundling. Cost compression in the economy tier intensifies because Chinese diagnostic device makers leverage domestic module supply. Home healthcare agencies exhibit highest price sensitivity, while German university hospital procurement committees prioritize compliance documentation over unit cost.
Supply Chain Analysis
Extended payment terms from Taiwan Semiconductor Manufacturing Company and supply-chain finance facilities at Samsung Foundry shape working capital requirements for cellular modem procurement. Module fabrication concentrates in Taiwan, South Korea, and mainland China. Raw material dependencies include silicon wafers, gallium arsenide substrates, and rare earth elements for RF front-end components. Single-source vulnerability in EUV lithography equipment exposes the entire supply base to geopolitical disruption. Distribution runs through authorized medical device distributors with regulatory compliance expertise rather than open electronic component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
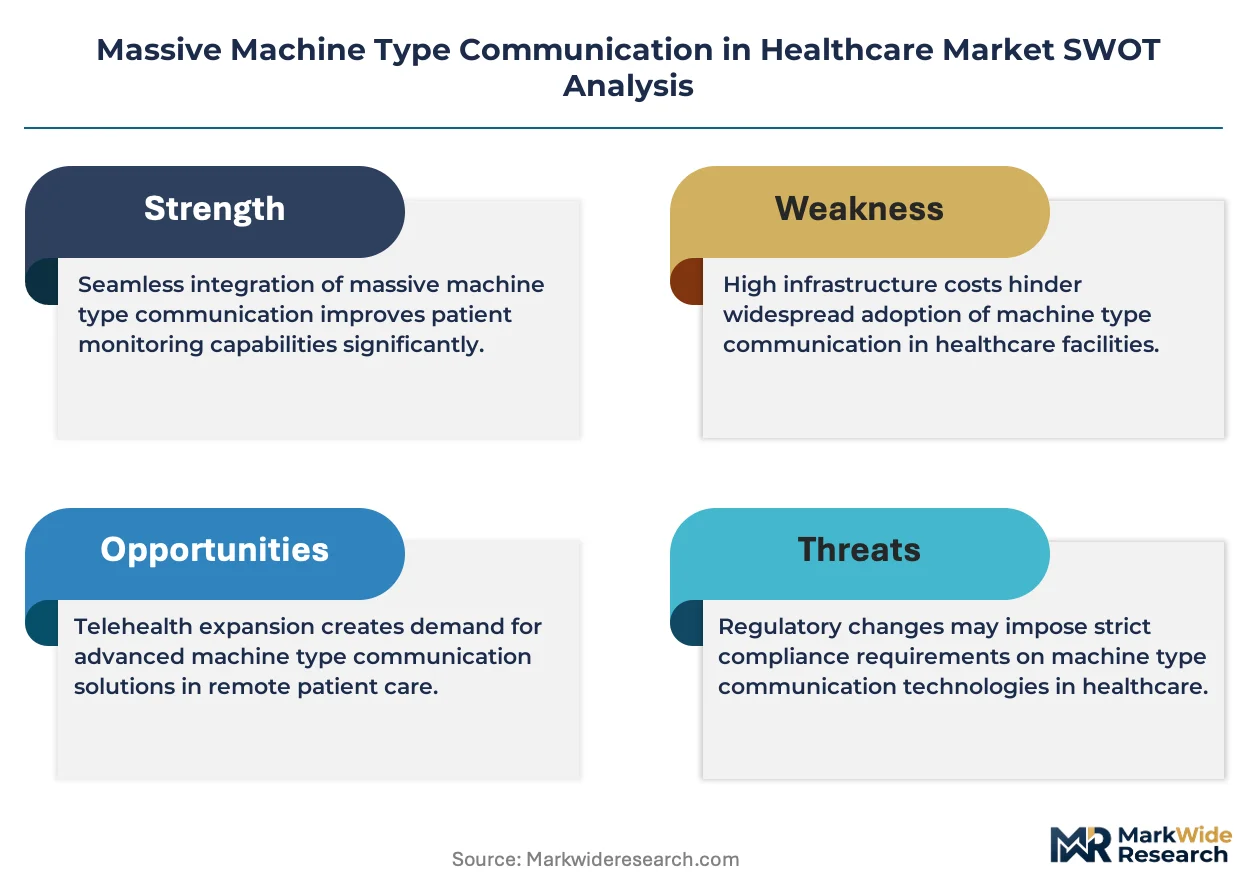
Wi-Fi 6E and private 5G network deployments present a credible substitution threat to cellular-enabled endpoints in controlled hospital environments, forcing incumbent connectivity providers to defend their installed base through service bundling rather than hardware margins alone.
For Market Incumbents: Insulate telemetry platform revenues by embedding AI-at-the-edge inference capabilities that require continuous firmware updates, creating switching costs that unlicensed alternatives cannot replicate. Deepen backward integration into RedCap module design to capture radio generation transitions without carrier recertification delays. Prioritize software bill of materials documentation to meet EU MDR procurement committee requirements and exclude hardware-centric competitors lacking security engineering depth. For New Entrants and Emerging Players: Pursue India's price-sensitive diagnostic device market where PLI scheme subsidies reduce cellular module landed costs and CDSCO regulatory pathways remain less mature than FDA or EMA channels. Target home healthcare providers in Brazil seeking Portuguese-language interfaces and local technical support, a segment incumbent global vendors underserve. Lead with subscription-based device provisioning models that transfer obsolescence risk from hospital IT departments to platform operators. For Investors and Strategic Acquirers: Specialized private wireless solution providers with FDA cybersecurity guidance compliance experience represent the most defensible acquisition targets as hospital digitization mandates accelerate. Long-term viability hinges on recurring revenue share from connectivity services rather than hardware shipment volumes. Monitor EMA notified body capacity expansion as the inflection signal for certification timeline compression and first-mover advantage restoration.| Strategic Initiative | Industry Significance |
|---|---|
| RedCap Module Integration | Enables 10-year battery targets for continuous glucose monitors while eliminating dual-radio design complexity. |
| Software Bill of Materials Implementation | Satisfies EU MDR Annex I procurement committee requirements and excludes hardware-centric competitors. |
| Private 5G Network Deployment | Delivers guaranteed quality-of-service for critical care telemetry without consumer traffic contention. |
| Subscription-Based Device Provisioning | Transfers obsolescence risk from hospital IT departments to platform operators per United States health system contracting trends. |
| AI-at-the-Edge Inference Development | Enables anomaly detection without cloud round-trip latency for post-discharge monitoring protocols. |
Research Methodology
A spread of perspectives from hospital procurement managers, biomedical engineers, cellular module product managers, and GPO contracts managers converged on the working assumptions underlying demand projections. Primary interviews combined with secondary validation against FDA 510(k) filings, EMA notified body capacity reports, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up endpoint shipment estimates triangulated against top-down health system IT spending surveys.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework. Segmentation dimensions modeled include connectivity technology, application type, end-user facility category, and device regulatory pathway complexity. CAGRs derived from historical shipment trajectories adjusted for 5G standalone rollout timelines and EU MDR software classification implementation phases. Forecast inputs incorporated German Hospital Future Act funding allocation schedules and United States remote therapeutic monitoring reimbursement expansion rates.
Sensitivities concentrate around EMA notified body capacity recovery, semiconductor foundry allocation volatility, and national spectrum allocation decisions. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and carrier network densification timelines. Macroeconomic contraction, cybersecurity incident disclosure mandates, or RedCap commercialization delays would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
AI In Government And Public Services Market
Others
Fresh Apples Market
Others
Drum Motor Market
Others
Global Molded Plastics Market
Others
5G Enabled Healthcare Services Market
Others
US Camping and Caravanning Market
Others
United States Indoor LBS Market
Others
Industrial Hooters Market
Others
Level Measuring Instrument Market
Others
Bakery Packaging Market
Others
Human Enhancement Technology Market
Others
Canada Feed Additives Market
Others
TWS Micro-Battery Market
Others
Belt Loader Market
Others
Binoculars and Mounting Solutions Market
Others
AI in Home Automation Market