
 Underwater Light Market | 2026-2036
Underwater Light Market Size, Share, and Industry Trends Forecast 2026-2036
Underwater Light Market Outlook
China is narrowing its LED component supply gap for marine-grade luminaires through dedicated coastal manufacturing zones. Ocean LED leverages vertical integration across die-casting and optical lens production to protect margin pools. Aqualuma LED Lighting anchors its position in Australia and Southeast Asia through channel control in premium marina networks. Signify Holding competes on manufacturing scale, sustaining cost advantages in high-volume pool lighting contracts.
Underwater lights are sealed luminaires engineered to operate at specified depths, typically employing marine-grade aluminum housings with IP68 ingress protection and tempered glass lenses to withstand hydrostatic pressure and chloride exposure. Their primary purpose spans functional illumination for vessel safety, aesthetic enhancement of aquatic environments, and photographic visibility in submerged conditions. LED product types dominate value contribution due to thermal management advances and lumen-per-watt efficiency gains, while halogen retains residual share in retrofit pool installations where legacy transformers constrain upgrades. Battery-operated power sources represent the fastest-expanding configuration, particularly for decorative and temporary installations where trenching costs deter wired alternatives.
The US Coast Guard and FCC regulate navigation light photometrics and electromagnetic emissions from vessel-mounted systems, while the EU RoHS and REACH frameworks restrict hazardous substances in housings and cable sheathing. These standards elevate compliance costs for smaller assemblers but create barriers that favor scaled manufacturers with in-house certification capabilities. Stakeholders must monitor divergence between IEC marine standards and emerging national codes as coastal states tighten ecological protections around sensitive reef ecosystems.
Market Dynamics
Marina infrastructure refurbishment cycles and superyacht new-build specifications are compressing replacement timelines for sealed luminaire systems. The EU Ecodesign Directive mandates minimum efficacy thresholds that disqualify legacy halogen architectures from coastal installations.
Growth Catalysts
- LED thermal management advances:Marine-grade aluminum housings with integrated heat sinks now sustain lumen output at depths exceeding 50 meters. Mediterranean superyacht builders specify these arrays for hull-mounted aesthetic illumination.
- EU RoHS compliance deadlines:Lead-free solder and cadmium-free phosphor formulations are mandatory for products entering EU marina supply chains. Manufacturers with in-house material certification capture specification authority.
- Battery-operated configuration expansion:Lithium-ion cell chemistry improvements eliminate trenching costs for temporary dockside installations. Australian premium marina networks deploy these for event lighting.
Market Restraints
- Marine-grade aluminum price volatility:Primary metal sourcing concentrates in Chinese smelters. Tariff exposure and energy input costs transmit directly to housing fabrication economics.
- IP68 certification timeline:Third-party pressure-testing for tempered glass lens assemblies requires 12-16 week validation cycles. Smaller assemblers lack capital reserves to carry inventory through certification.
- Halogen transformer lock-in:Legacy pool installations with magnetic transformers cannot support LED load characteristics without complete electrical reconfiguration. Residential retrofit demand fragments.
Strategic Opportunities
- Photographic visibility systems:Underwater cinematography for documentary production requires tunable color-temperature arrays. Broadcast equipment rental houses in California and Queensland represent untapped specification channels.
- Reef ecosystem protection mandates:Coastal states in the Florida Keys and Australia's Great Barrier Reef Marine Park restrict spectral output near sensitive coral habitats. Compliant narrow-band LED architectures command specification premiums.
- Smart marina integration:IoT-enabled luminaires with remote dimming and fault detection align with Singapore and Dubai port authority digitalization initiatives. System integrators bundle lighting into broader berth management platforms.
Industry Challenges
- Optical design talent scarcity:Compound lens geometry for controlled beam spread in turbid water conditions requires specialized illumination engineering. European technical universities produce limited graduates in this niche.
- Cable sheathing material qualification:REACH-compliant chlorosulfonated polyethylene alternatives exhibit accelerated degradation in high-salinity immersion. Formulation R&D demands sustained capex without guaranteed regulatory stability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underwater Light Market |
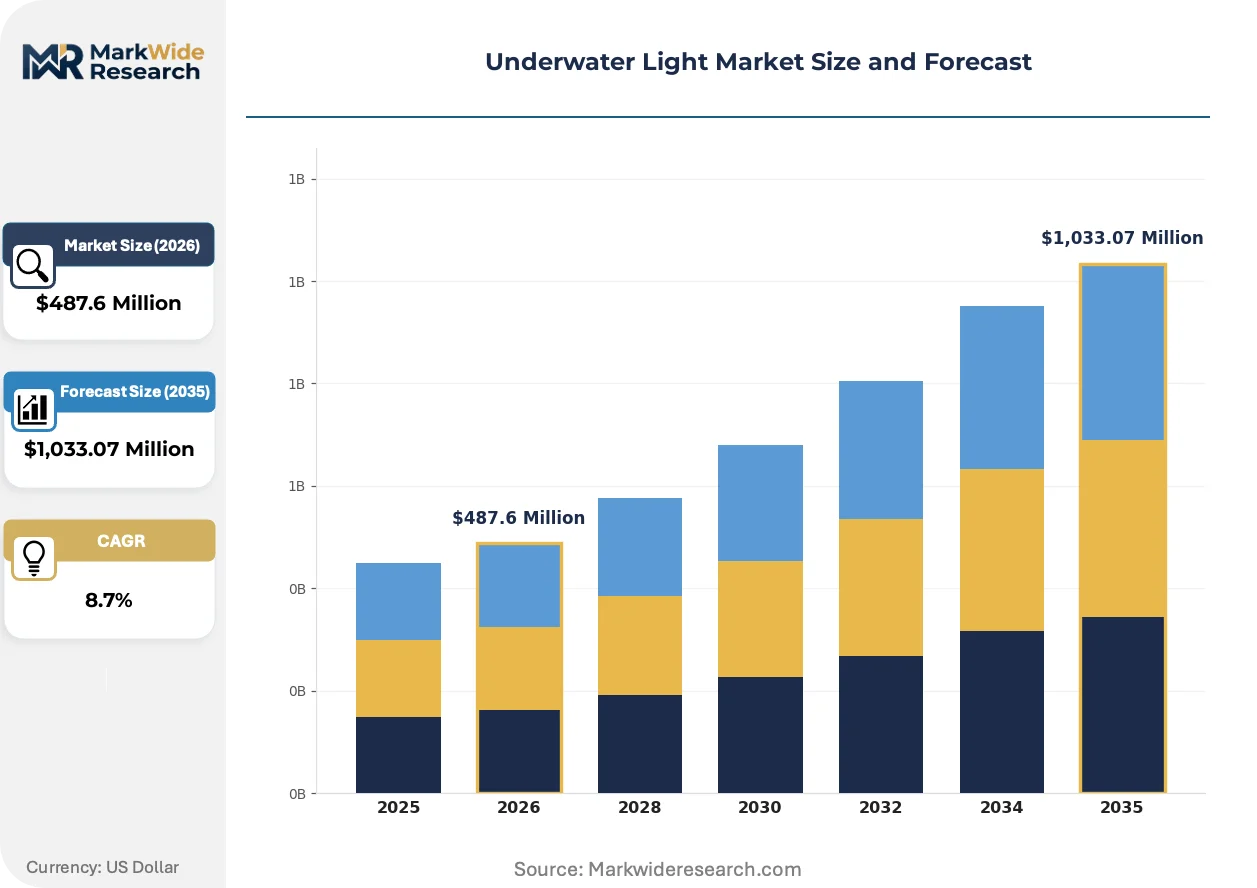
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Halogen, Xenon, Fluorescent Application: Swimming Pools, Aquariums, Decorative Lighting, Underwater Photography Power Source: Solar, Battery-operated, Wired, Hybrid Installation Type: Surface-mounted, Submersible, Floating, Integrated |
| Companies Covered | Ocean LED, Aqualuma LED Lighting, Hayward Industries Inc., Acuity Brands Inc., Shadow Caster Inc., Attwood Corporation, Signify Holding, Lumishore, Underwater Lights Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underwater Light Market Strategic Shifts
Digital control architectures and spectral tuning capabilities are redefining performance benchmarks for submerged illumination. Manufacturers now compete on software-defined light output rather than static lumen ratings alone.
Addressable LED driver electronics is digitizing fixture management across superyacht fleets. Captains and interior designers program circadian lighting sequences through tablet interfaces. The technology is digitizing how vessel aesthetic systems are specified, sold, and serviced, compressing traditional electrical contractor intermediation.
REACH substance restrictions on cable jacketing materials are forcing compound reformulation across European supply chains. ECHA authorization requirements for legacy plasticizers have triggered a 24-month qualification cycle for new sheathing grades. Italian and Spanish marina electrical contractors now stock only pre-certified cable bundles, eliminating field-splicing flexibility.
Specification authority has migrated from electrical wholesalers to marina management consortia. Procurement committees in Barcelona, Genoa, and Palma de Mallorca coordinate bulk purchasing for multiple berth facilities. Direct manufacturer relationships displace traditional distribution markups, with technical support bundled into multi-year service agreements rather than per-fixture transactions.
Underwater Light Market Segmentation
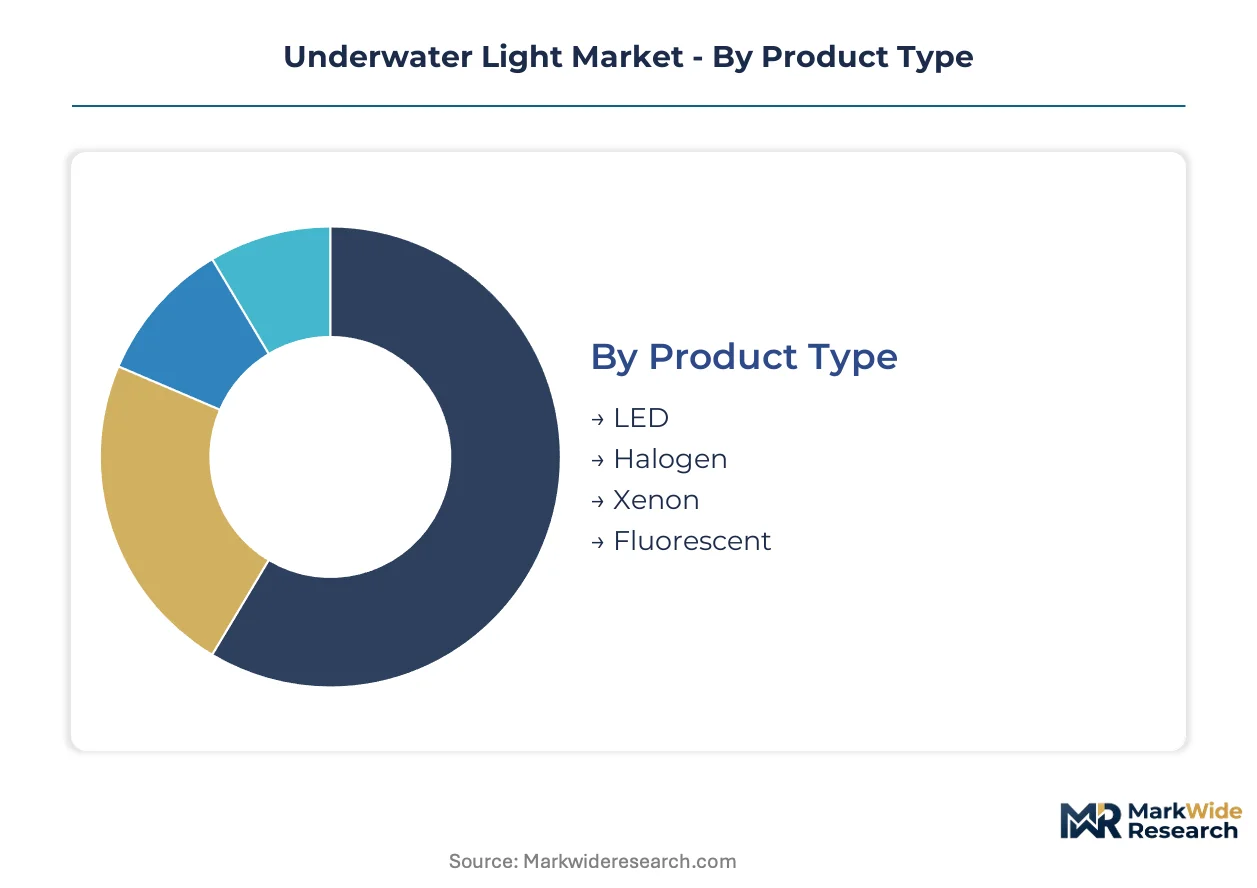
Underwater light segmentation reflects divergent technical requirements across vessel safety, aquatic aesthetics, and submerged imaging. Product architecture, power configuration, and mounting geometry each create distinct specification pathways that manufacturers must navigate.
Product Type:
Mature LED architectures now dominate commercial specifications while legacy technologies retain retrofit niches.
- LED:Marine-grade aluminum housings with integrated thermal management sustain lumen output beyond 50-meter depths. Mediterranean superyacht builders specify these arrays for hull-mounted aesthetic illumination.
- Halogen:Residual demand concentrates in residential pool retrofits where legacy magnetic transformers constrain electrical reconfiguration. Transformer lock-in fragments upgrade timelines across North American residential markets.
- Xenon:High-intensity discharge technology persists in deep-water cinematography applications requiring precise color rendering.
- Fluorescent:Limited to budget aquarium installations where spectral precision matters less than capital cost.
LED handles the majority of throughput; battery-compatible LED configurations are gaining share fastest.
Application:
End-use concentration follows coastal infrastructure investment cycles and luxury marine construction.
- Swimming Pools:Functional illumination for residential and commercial aquatics represents volume anchor. Australian and Southeast Asian premium marina networks drive specification upgrades.
- Underwater Photography:Tunable color-temperature arrays serve documentary production in California and Queensland broadcast equipment rental channels.
- Aquariums:Public and private aquatic displays require narrow-band spectral output for marine life compatibility.
- Decorative Lighting:Event and architectural applications favor temporary battery-operated installations eliminating trenching costs.
Swimming pool applications carry volume concentration; underwater photography commands the steepest expansion trajectory.
Power Source:
Cost tier stratification separates permanent infrastructure from flexible deployment models.
- Battery-operated:Lithium-ion chemistry improvements enable dockside event lighting without electrical trenching. Singapore and Dubai port authority digitalization initiatives favor these for temporary berth illumination.
- Wired:Permanent marina infrastructure and superyacht new-builds specify hardwired systems for reliability.
- Solar:Autonomous operation suits remote coastal installations with limited grid access.
- Hybrid:Dual-source configurations bridge reliability and flexibility for seasonal marina operations.
Wired systems anchor installed base value; battery-operated configurations climb the fastest on adoption.
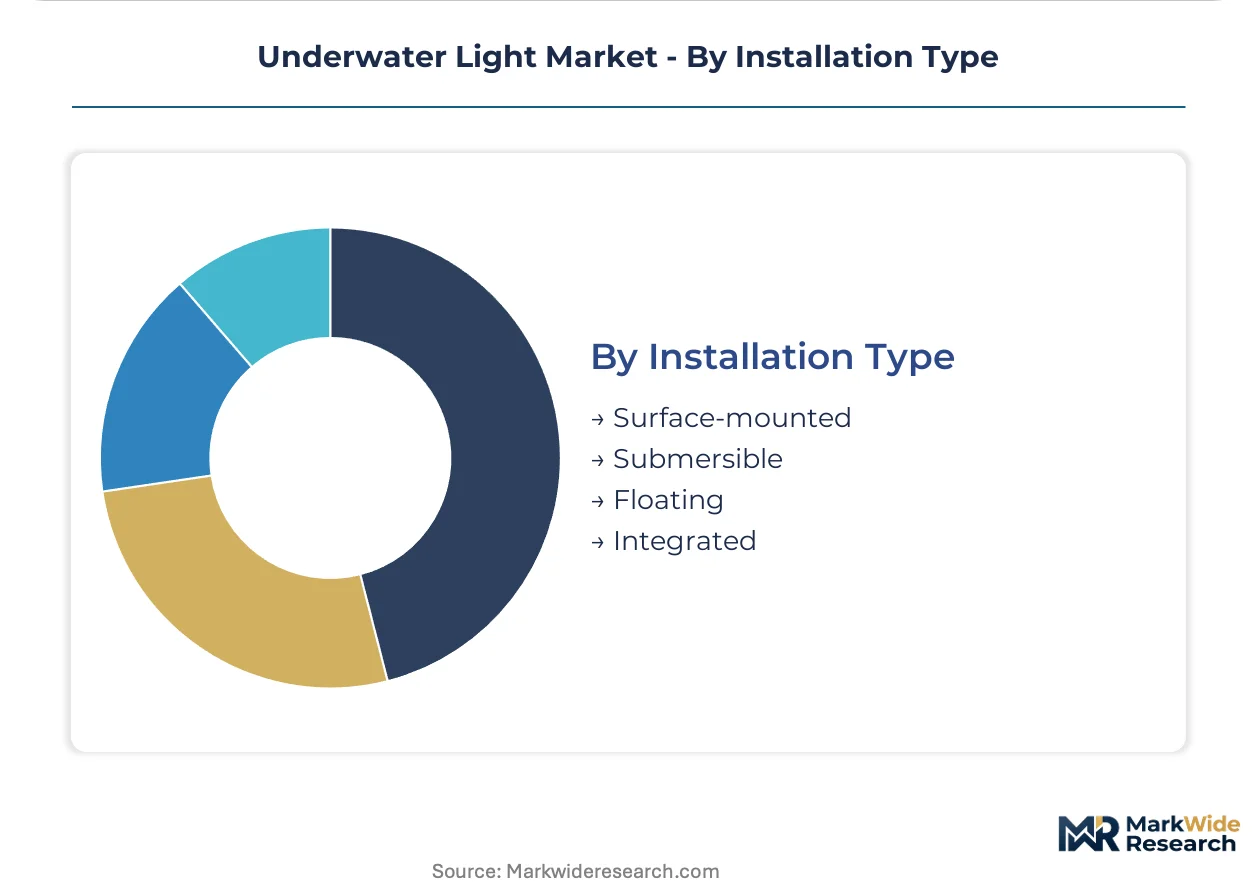
Installation Type:
Mounting geometry determines pressure rating requirements and maintenance accessibility.
- Submersible:IP68-rated sealed assemblies withstand hydrostatic pressure at specified depths. Florida Keys and Great Barrier Reef Marine Park restrictions on spectral output favor compliant narrow-band LED architectures.
- Surface-mounted:Hull and dock applications dominate superyacht aesthetic specifications.
- Floating:Temporary event lighting and marker applications favor rapid deployment.
- Integrated:Built-in vessel systems align with smart marina IoT platforms for remote dimming and fault detection.
Submersible fixtures command specification authority; integrated installations show the strongest forward momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU RoHS compliance deadlines anchor the dominant geography for sealed luminaire demand, with Mediterranean superyacht builders and marina operators driving specification upgrades across coastal economies.
United States
Florida Keys marina infrastructure and California broadcast equipment rental channels sustain demand for reef-compliant narrow-band LED architectures. The US Coast Guard regulates navigation light photometrics for vessel-mounted systems. Miami-Dade County and Fort Lauderdale clusters concentrate superyacht refit activity requiring IP68-rated hull illumination.
Italy
Genoa and Palma de Mallorca procurement committees coordinate bulk purchasing for multiple berth facilities across Ligurian and Tyrrhenian coastlines. The EU Ecodesign Directive mandates minimum efficacy thresholds that disqualify legacy halogen architectures. Lombardy-based manufacturers supply marine-grade aluminum housings with integrated thermal management for hull-mounted aesthetic arrays.
Australia
Queensland broadcast equipment rental houses and Great Barrier Reef Marine Park restrictions drive tunable color-temperature specifications for documentary production. The country's national environmental regulator restricts spectral output near sensitive coral habitats. Southeast Queensland premium marina networks deploy battery-operated lithium-ion configurations for event lighting.
Spain
Catalonia and Valencia coastal refurbishment cycles compress replacement timelines for sealed luminaire systems in Mediterranean berth facilities. REACH substance restrictions on cable jacketing materials force compound reformulation across Iberian supply chains. Barcelona procurement committees now stock only pre-certified cable bundles, eliminating field-splicing flexibility for electrical contractors.
China
Dedicated coastal manufacturing zones narrow the LED component supply gap for marine-grade luminaires serving export markets. The country's national standards administration oversees GB compliance for sealed assemblies. Yangtze River Delta die-casting and optical lens production clusters support backward integration strategies for margin protection.
Underwater Light Market Competitive Environment
Vertically integrated specialists and scale-driven lighting conglomerates split the market into distinct capability tiers. Consolidation pressure favors manufacturers with in-house certification capabilities to manage IP68 validation timelines. Three archetypes dominate: coastal manufacturing zone operators with captive component supply, premium marina channel controllers with specification authority, and diversified electronics assemblers competing on manufacturing scale. Competitive moves center on backward integration into die-casting operations and direct procurement relationships with marina management consortia.
Among vertically integrated specialists, Ocean LED exemplifies the coastal manufacturing archetype through control over optical lens production. Aqualuma LED Lighting occupies a position within the premium channel control tier, anchoring specification authority in Australian and Southeast Asian marina networks. Signify Holding sits within the scale-driven segment, sustaining cost advantages in high-volume contract manufacturing. These three represent the strategic positioning spectrum that defines competitive dynamics.
| Leading Market Players |
|---|
| Ocean LED |
| Aqualuma LED Lighting |
| Hayward Industries Inc. |
| Acuity Brands Inc. |
| Shadow Caster Inc. |
| Attwood Corporation |
| Signify Holding |
| Lumishore |
| Underwater Lights Limited |
| Others |
Value Chain & Pricing Dynamics
Chinese smelter concentration for primary marine-grade aluminum transmits directly to housing fabrication economics, concentrating margin pools with die-casting operations that have secured long-term metal offtake agreements. Mediterranean superyacht builders and Australian marina networks absorb these input cost movements through specification premiums on IP68-certified assemblies.
Pricing Analysis
Italian and Spanish procurement committees command 15-20% discounts against spot pricing through coordinated multi-berth bulk purchasing. Three-tier pricing structure across premium, standard, and economy levels separates OEM superyacht specifications from residential retrofit channels, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in economy-tier pool lighting is intensifying because Chinese coastal manufacturing zones have expanded LED component supply. Residential retrofit buyers with legacy transformer constraints exhibit highest price sensitivity, while superyacht builders prioritize thermal management performance over unit cost.
Supply Chain Analysis
Extended payment terms from Yangtze River Delta die-casting clusters to European assemblers now stretch 90-120 days, straining working capital for smaller fixture manufacturers. Component sourcing draws from China for aluminum housings and optical lenses, Italy for compound cable sheathing, and Australia for lithium-ion battery cells. Single-source vulnerability concentrates in tempered glass lens supply, where third-party IP68 certification creates 12-16 week validation bottlenecks. Distribution runs through direct manufacturer relationships with marina management consortia in Barcelona, Genoa, and Palma de Mallorca, displacing traditional electrical wholesaler markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a halogen-phaseout cyclical trough, with EU Ecodesign Directive compliance deadlines compressing replacement timelines across Mediterranean coastal infrastructure.
For Market Incumbents: Pre-empt margin erosion from Chinese coastal manufacturing zones by securing captive die-casting capacity in Yangtze River Delta clusters. Invest in in-house REACH-compliant cable sheathing formulation to eliminate 24-month qualification cycle exposure. Channel control through direct procurement relationships with Barcelona and Genoa marina consortia remains the priority defensive lever against emerging Asian competitors. For New Entrants and Emerging Players: Pursue underwater cinematography specification channels in California and Queensland broadcast equipment rental houses, where tunable color-temperature arrays face limited incumbent penetration. Battery-operated lithium-ion configurations for Australian premium marina event lighting represent the most penetrable white-space segment. A go-to-market angle bundling IoT-enabled remote dimming with Singapore and Dubai port authority digitalization initiatives bypasses traditional electrical contractor intermediation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed marine lighting specialists that consolidated regional marina networks but lack backward integration into optical lens production. Five-to-ten year viability hinges on regulatory compliance capability rather than manufacturing scale alone. The signal to watch is divergence between IEC marine standards and emerging national reef-protection codes in Florida and Queensland, which would trigger specification premium capture for narrow-band LED architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Die-Casting | Ocean LED's captive aluminum housing production protects margin pools against Chinese smelter price volatility. |
| REACH-Compliant Sheathing Reformulation | Italian cable manufacturers with ECHA-authorized compounds capture specification authority in EU marina supply chains. |
| Smart Marina IoT Integration | Singapore port authority digitalization initiatives bundle remote dimming capabilities into berth management platforms. |
| Battery-Operated Configuration Expansion | Australian premium marina networks deploy lithium-ion event lighting to eliminate trenching costs for temporary installations. |
| Reef-Compliant Spectral Architecture | Great Barrier Reef Marine Park restrictions command specification premiums for narrow-band LED arrays near sensitive coral habitats. |
Study Parameters
A spread of perspectives from superyacht build specification engineers, marina procurement committee directors, marine electrical contractors, and LED thermal management specialists converged on the working assumptions. Primary interview findings were validated against EU Ecodesign Directive implementation timelines, US Coast Guard navigation light photometric standards, ECHA substance authorization databases, and Australian Great Barrier Reef Marine Park spectral restriction guidelines. Bottom-up fixture shipment data from Mediterranean and Southeast Asian marina networks was triangulated with top-down coastal infrastructure investment forecasts.
Demand-supply balance modeling across the projection horizon incorporated LED efficacy thresholds, halogen transformer replacement cycles, and battery chemistry cost curves. Segmentation dimensions included product architecture, power configuration, mounting geometry, and regional regulatory cluster. CAGRs were derived from fitting observed replacement timelines and new-build specifications to projected coastal infrastructure refurbishment cycles. Industry-specific inputs encompassed IP68 certification pipeline durations and REACH-compliant material qualification timelines.
Sensitivities concentrate around EU RoHS enforcement intensity, Chinese aluminum export tariff adjustments, and divergence between IEC marine standards and emerging national reef-protection codes. Forecasts reflect documented assumptions regarding superyacht new-build rates and marina infrastructure investment cycles. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Insoluble Sulfur Market
Others
Vacuum Evaporators Market
Others
Global Thermally Conductive Grease Market
Others
Smart-Connected Power Plug Socket Market
Others
Augmented Reality (AR) in Warehousing and Logistics Market
Others
North America Smart Homes Market
Others
Africa Lime Market
Others
Nyerereite Market
Others
South America Halal Food and Beverages Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
Global Electroshock Weapons Market
Others
Asia-Pacific IVD Regulatory Affairs Outsourcing Market
Others
Rotary Union Market
Others
Smart Home Service Market
Others
APAC Machine Vision Systems Market
Others
Asia Pacific Contract Packaging Market