
 Liposomes Market | 2026-2036
Liposomes Market Size, Share, and Industry Trends Forecast 2026-2036
Liposomes Market Analysis
GMP-grade liposome manufacturing is reorganizing competitive dynamics across the pharmaceutical value chain. Pfizer leverages its lipid nanoparticle expertise developed through mRNA vaccine programs to sustain leadership in scalable formulation technology. Gilead Sciences anchors its position through deep specialization in liposomal oncology therapeutics, while Novartis competes on targeted delivery platforms for rare disease applications.
Liposomes are spherical phospholipid bilayer vesicles ranging from 25 nanometers to several micrometers in diameter, engineered to encapsulate hydrophilic or hydrophobic payloads for controlled release in biological environments. Their primary commercial purpose centers on improving drug bioavailability, reducing systemic toxicity, and enabling cell-specific targeting for therapeutic and diagnostic agents. Conventional liposomes retain dominant volume share in established generic applications, while stealth liposomes command premium positioning through PEGylation technologies that extend circulating half-life. Targeted liposomes represent the fastest-growing structural category as antibody-conjugated and ligand-directed formulations advance through clinical pipelines.
The FDA, EMA, and ISO 10993 biocompatibility standards collectively govern liposome characterization, sterility assurance, and batch-to-batch consistency requirements that determine market access timelines. These frameworks elevate barriers for emerging manufacturers while rewarding incumbents with validated quality management systems and prior regulatory approvals. Stakeholders must monitor evolving pharmacopeial monographs for lipid excipients and prepare for tightened endotoxin specifications as parenteral nanomedicine portfolios expand.
Market Dynamics
Precision nanomedicine manufacturing is compressing development timelines while fragmenting supply chains into specialized lipid excipient producers, formulation houses, and fill-finish contractors.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's breakthrough therapy and fast-track designations for nanomedicine candidates compress clinical-to-commercial timelines. Developers exploit these mechanisms for liposomal oncology assets.
- Oncology Drug Delivery Expansion:Tumor-targeted liposome platforms reduce off-tissue toxicity in chemotherapy regimens. Hospital systems prioritize these formulations for patient compliance advantages.
- Lipid Nanoparticle Platform Maturation:mRNA vaccine manufacturing infrastructure transfers directly to therapeutic liposome production. Contract manufacturers in the United States repurpose existing capacity.
Market Restraints
- Phospholipid Supply Concentration:High-purity hydrogenated soy phosphatidylcholine production concentrates among three European chemical suppliers. Price volatility in this input directly squeezes formulation margins.
- Regulatory Harmonization Gaps:Divergent EMA and FDA guidance on liposome characterization creates duplicate stability testing requirements. Developers absorb redundant analytical costs.
- Polymeric Nanoparticle Substitution:PLGA-PEG block copolymer carriers encroach on established liposome indications. These alternatives offer superior mechanical stability in certain depot formulations.
Strategic Opportunities
- Gene Therapy Vector Convergence:Lipid nanoparticle-siRNA combinations target liver-expressed genetic disorders. Developers in Massachusetts and California advance IND-enabling studies.
- Vaccine Adjuvant Repositioning:Cationic liposome formulations stimulate mucosal immunity in intranasal delivery. Manufacturers explore this route for respiratory pathogen candidates.
- PLI Scheme Manufacturing Incentives:India's production-linked incentive scheme for pharmaceuticals subsidizes domestic liposome API capacity. Multinationals evaluate contract manufacturing partnerships in Hyderabad and Ahmedabad clusters.
Industry Challenges
- Process Analytical Technology Integration:Real-time release testing for liposome size distribution and encapsulation efficiency demands specialized PAT expertise. Recruitment for these hybrid engineering-biology roles lags demand.
- Legacy Sterilization Validation:Terminal filtration and aseptic processing requirements for parenteral liposomes conflict with established small-molecule autoclave protocols. Facilities require dedicated isolator lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liposomes Market |
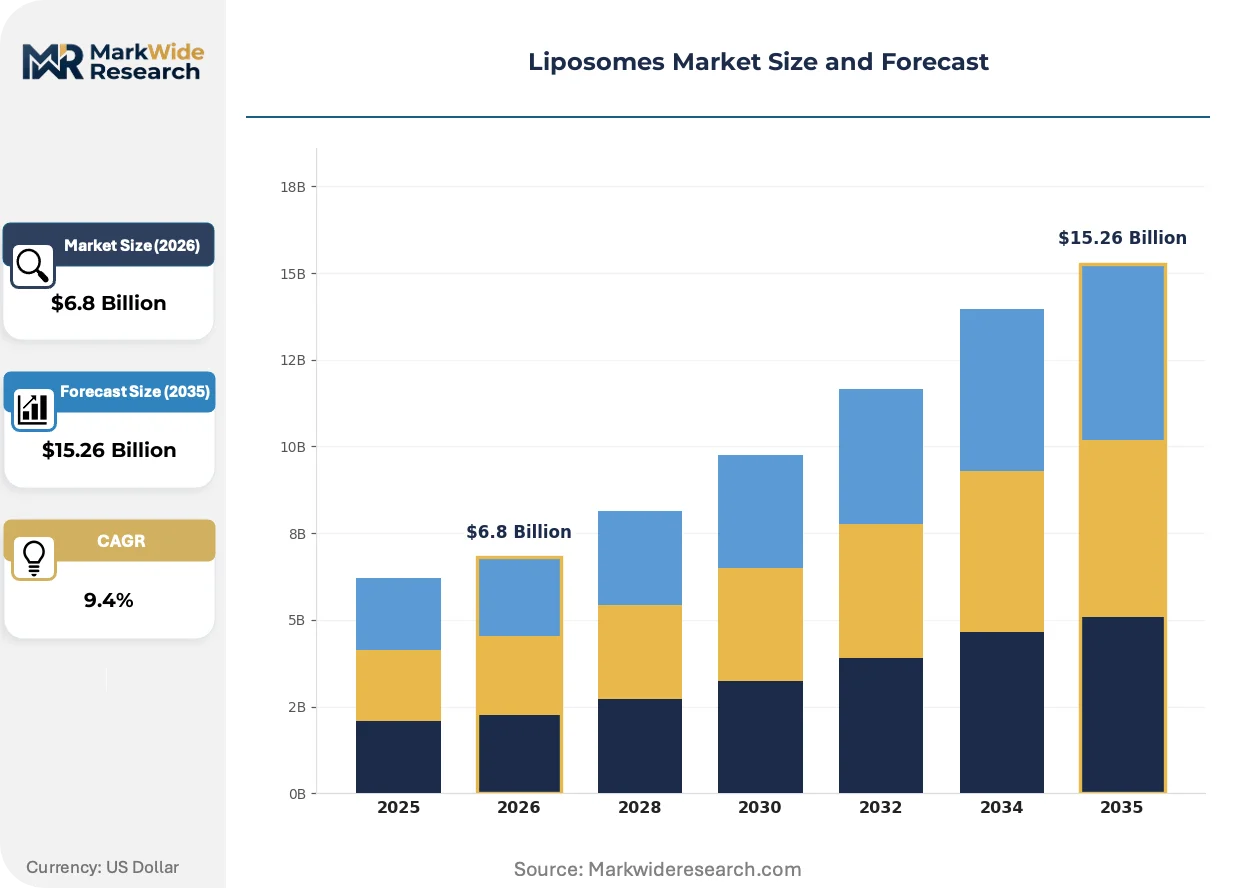
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Liposomes, Targeted Liposomes, Stealth Liposomes, Thermosensitive Liposomes Application: Drug Delivery, Vaccine Development, Gene Therapy, Diagnostic Imaging End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Hospitals Formulation Type: Solution, Powder, Emulsion, Gel |
| Companies Covered | Pfizer, Takeda Pharmaceutical Company Limited, Gilead Sciences, Inc., Abbott, Teva Pharmaceutical Industries Ltd, Johnson & Johnson, Novartis AG, Merck & Co., Pacira BioSciences, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liposomes Market Emerging Trajectories
Active targeting modalities and continuous manufacturing architectures are restructuring how liposome therapeutics advance from discovery to commercial scale.
Microfluidic mixing technology is supplanting traditional thin-film hydration and extrusion methods for liposome synthesis. Biopharmaceutical manufacturers in San Diego and Cambridge adopt these platforms for batch-to-batch consistency. The shift compresses process development timelines from months to weeks.
EMA's revised guideline on quality of nanomedicine products mandates extended physicochemical characterization for liposomal drug products. Developers must demonstrate in vitro-in vivo correlation for critical quality attributes. Oncology applications face the steepest compliance burden given their accelerated approval history.
Integrated development-manufacturing contracts displace fragmented outsourcing across formulation, analytical, and fill-finish stages. Large molecule CDMOs in Switzerland and Singapore capture these bundled engagements. Biotech sponsors prioritize single-source accountability for complex nanomedicine programs.
Liposomes Market Segmentation
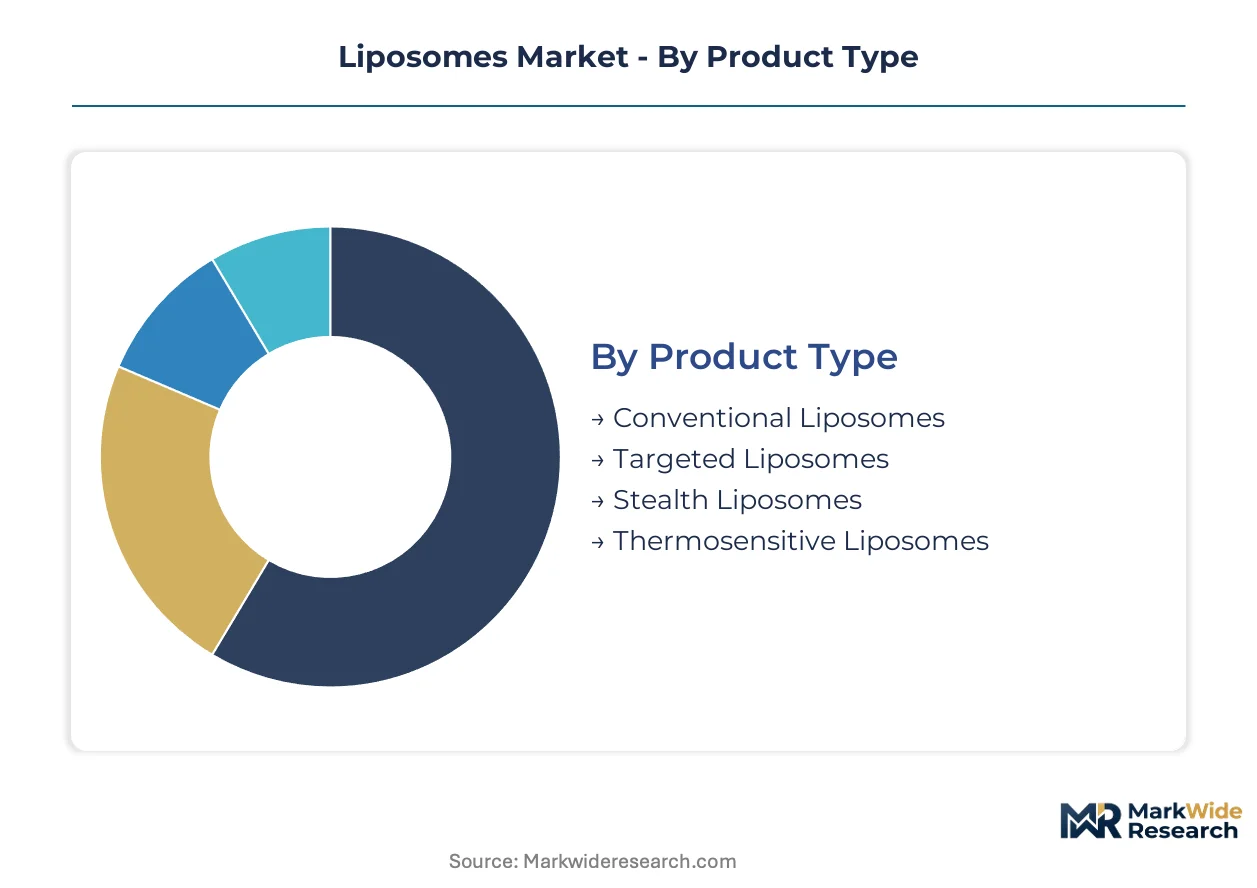
Liposome segmentation determines manufacturing scale, regulatory pathway, and pricing architecture. Formulation complexity varies dramatically across structural categories, while end-user concentration shapes commercial access strategies.
Product Type:
Polymeric nanoparticle alternatives exert substitution pressure most acutely on conventional formulations, while advanced structural variants defend position through functional differentiation.
- Conventional Liposomes:Simple phospholipid bilayers without surface modification dominate generic oncology and antifungal applications. Hospital procurement in the United States and Germany favors these formulations for established therapeutic indices and lower unit costs.
- Targeted Liposomes:Antibody-conjugated or ligand-directed surface engineering enables cell-specific payload delivery. Massachusetts and California developers advance IND-enabling studies for liver-expressed genetic disorders, driving the steepest clinical pipeline expansion.
- Stealth Liposomes:PEGylation extends circulating half-life through reduced reticuloendothelial clearance. EMA's nanomedicine quality guidelines elevate characterization requirements for these products.
- Thermosensitive Liposomes:Temperature-triggered release mechanisms enable localized drug deposition with external hyperthermia application. Academic medical centers in Japan evaluate these platforms for solid tumor ablation protocols.
Conventional liposomes anchor the volume base while targeted liposomes gain share at the steepest rate.
Application:
Clinical trial success rates and reimbursement complexity stratify this category into high-volume commercialized segments and emerging technology platforms.
- Drug Delivery:Encapsulation of hydrophilic and hydrophobic therapeutics improves bioavailability and reduces systemic toxicity. Oncology chemotherapy regimens in the United States and Switzerland represent the dominant demand concentration.
- Vaccine Development:Lipid nanoparticle mRNA platforms demonstrated scalable manufacturing through pandemic response infrastructure. Cationic formulations for intranasal respiratory pathogen candidates are advancing through preclinical stages in Massachusetts.
- Gene Therapy:Lipid nanoparticle-siRNA combinations target hepatocyte-expressed genetic disorders. IND-enabling studies concentrate among developers in Cambridge and San Diego.
- Diagnostic Imaging:Contrast agent encapsulation enables targeted visualization of pathological tissue. Research institutions in Germany and Japan evaluate these formulations for early-stage oncology detection.
Drug delivery commands the revenue base while gene therapy applications climb the fastest.
End User:
Procurement sophistication and technical capability requirements create distinct service models across customer categories.
- Pharmaceutical Companies:Integrated development-manufacturing contracts prioritize single-source accountability for complex nanomedicine programs. Swiss and Singapore CDMOs capture bundled engagements from large molecule sponsors.
- Biotechnology Firms:Venture-funded developers in California and Massachusetts outsource formulation and analytical stages to specialized contract manufacturers.
- Research Institutions:Academic medical centers evaluate novel liposome architectures through NIH and EU Horizon funding mechanisms.
- Hospitals:Hospital systems prioritize liposomal oncology formulations for patient compliance advantages in chemotherapy administration.
Pharmaceutical companies dominate contract value while biotechnology firms expand their share of development-stage engagements.
Formulation Type:
Stability requirements and administration routes determine manufacturing infrastructure investment across physical presentation formats.
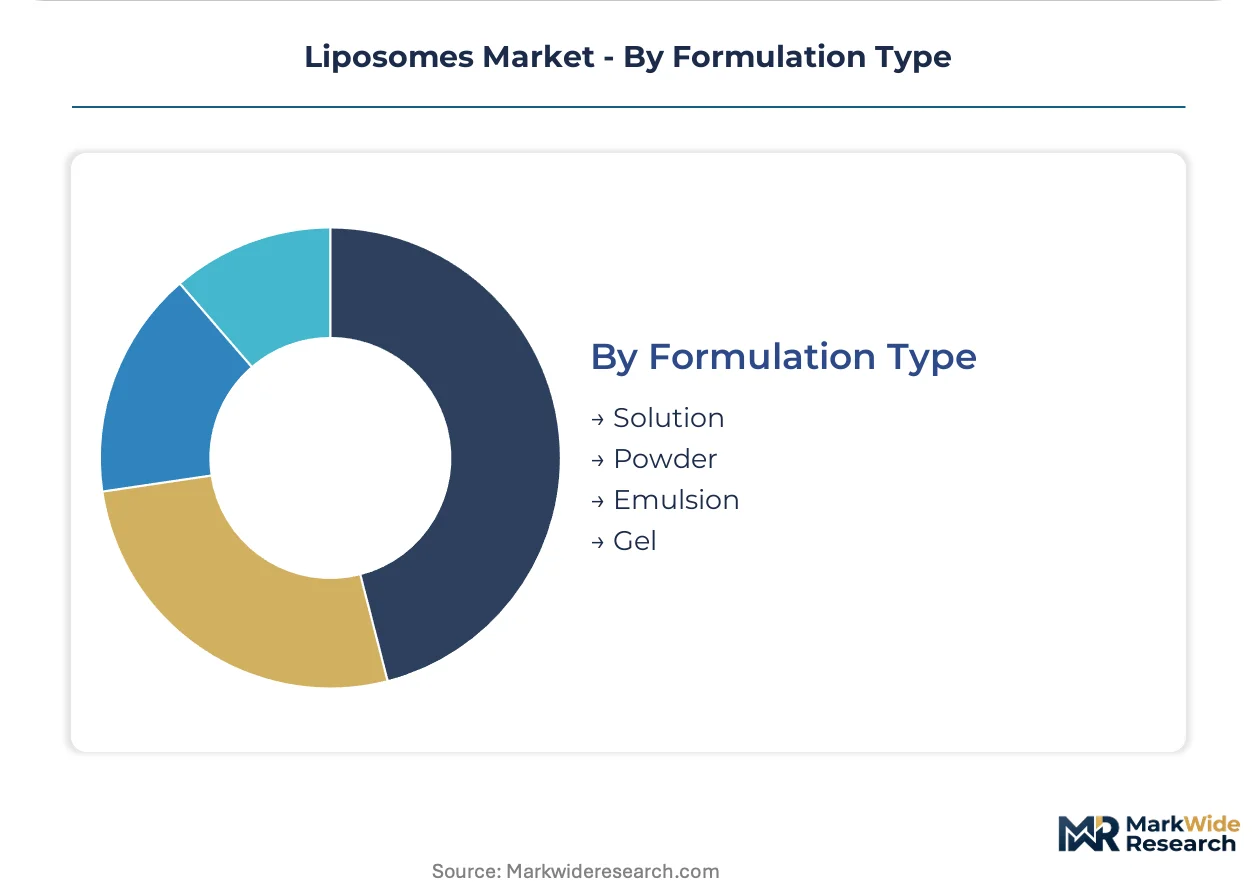
- Solution:Aqueous liposome dispersions for parenteral administration require cold chain distribution and terminal filtration validation. Fill-finish contractors in Switzerland maintain dedicated isolator lines for these products.
- Powder:Lyophilized formulations extend shelf stability for remote distribution. Hyderabad and Ahmedabad manufacturing clusters under India's PLI scheme evaluate spray-drying capacity for these products.
- Emulsion:Multiphase systems combine liposome encapsulation with lipid carrier phases for enhanced dermal penetration.
- Gel:Viscous matrices enable localized depot delivery for transdermal and mucosal applications.
Solution formulations retain the dominant volume position while powder presentations expand most quickly for distribution flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement teams in Germany negotiate aggressively on conventional liposome formulations, while United States buyers absorb premium pricing for targeted delivery platforms. Venture-funded developers in Massachusetts and California prioritize clinical velocity over unit economics. India's PLI scheme subsidized manufacturing attracts cost-sensitive contract manufacturing partnerships.
United States
FDA breakthrough therapy designations compress clinical-to-commercial timelines for liposomal oncology assets. The agency's nanomedicine guidance elevates characterization requirements for PEGylated formulations. Massachusetts and California clusters concentrate IND-enabling studies for lipid nanoparticle-siRNA combinations targeting hepatocyte-expressed disorders.
Germany
EMA's revised nanomedicine quality guidelines mandate extended physicochemical characterization for liposomal drug products. Hospital procurement systems in Bavaria and North Rhine-Westphalia prioritize established therapeutic indices for generic oncology applications. Academic medical centers in Heidelberg evaluate thermosensitive platforms for solid tumor ablation protocols.
Switzerland
Swissmedic's alignment with EMA standards accelerates parallel submission pathways for liposomal therapeutics. Large molecule CDMOs in Basel and Zurich capture integrated development-manufacturing contracts for complex nanomedicine programs. Fill-finish contractors maintain dedicated isolator lines for parenteral liposome solutions.
India
CDSCO's streamlined approval pathways for nanomedicine products attract multinational outsourcing partnerships. The PLI scheme for pharmaceuticals subsidizes domestic liposome API capacity in Hyderabad and Ahmedabad manufacturing clusters. Spray-drying infrastructure expands for lyophilized powder formulations targeting remote distribution.
Japan
PMDA's accelerated review pathways for orphan nanomedicine indications support targeted liposome development. METI funding mechanisms sustain academic medical center evaluation of novel architectures in Tokyo and Osaka. Thermosensitive platform research concentrates in Kansai region institutions for hyperthermia-triggered release applications.
Liposomes Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the liposome value chain. Large pharmaceutical incumbents with validated quality management systems capture premium positioning through prior regulatory approvals and scalable manufacturing infrastructure. Specialized biotechnology firms concentrate on novel targeting modalities and gene therapy vector applications. Contract development and manufacturing organizations compete on integrated service bundling across formulation, analytical, and fill-finish stages.
Among United States-based pharmaceutical developers, Pfizer exemplifies the technology leadership archetype through lipid nanoparticle platform maturation, while Gilead Sciences occupies a specialist position in liposomal oncology therapeutics. Novartis represents the diversified pharmaceutical model competing on targeted delivery platforms for rare disease applications. These three players anchor distinct strategic vectors within the competitive structure.
| Leading Market Players |
|---|
| Pfizer |
| Takeda Pharmaceutical Company Limited |
| Gilead Sciences, Inc. |
| Abbott |
| Teva Pharmaceutical Industries Ltd |
| Johnson & Johnson |
| Novartis AG |
| Merck & Co. |
| Pacira BioSciences, Inc. |
| Others |
Supply Flow & Price Mechanics
Ninety-day phospholipid inventory buffers in European hydrogenated soy phosphatidylcholine production concentrate pricing power among three chemical suppliers, while contract manufacturers absorb margin compression through formulation service bundling. This lead-time exposure concentrates buyer dependency on German and Dutch lipid excipient specialists, elevating spot-price volatility for GMP-grade inputs.
Pricing Analysis
After-sales analytical service contracts and stability testing packages drive lifetime value for CDMO relationships in this market. Three-tier pricing structure across premium, standard, and economy levels separates PEGylated targeted formulations from conventional generics and commodity phospholipid dispersions. Price differentiation hinges on FDA prior-approval supplement status and ISO 10993 biocompatibility certification tier. Cost compression in conventional liposome segments is intensifying because hospital procurement in Germany and the United States favors established therapeutic indices. Biotechnology sponsors in Massachusetts demonstrate least price sensitivity for IND-enabling formulation development.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp chemical corridors elevates inbound logistics costs for hydrogenated phospholipid shipments from European suppliers to Swiss and Singapore fill-finish contractors. Geographic supply concentration centers on Germany, the Netherlands, and India for high-purity lipid excipients, with formulation expertise clustering in Switzerland, Singapore, and the United States. Raw material dependencies rest on hydrogenated soy phosphatidylcholine, synthetic cholesterol, and PEG-lipid conjugates. Single-source vulnerability in phospholipid purification creates exposure to batch-release delays. Distribution runs through cold-chain logistics networks terminating at hospital pharmacy and clinical trial depot endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lipid nanoparticle platform maturation represents a high-growth disruption as FDA breakthrough therapy designations compress clinical-to-commercial timelines for nanomedicine candidates. This regulatory inflection accelerates capital deployment toward integrated manufacturing infrastructure.
For Market Incumbents: Compound manufacturing scale advantages through backward integration into phospholipid excipient production and captive supply of GMP-grade hydrogenated soy phosphatidylcholine. Defend against polymeric nanoparticle substitution by deepening PEGylation expertise and expanding dedicated isolator line capacity in Basel and Zurich clusters. Prioritize regulatory affairs investment for EMA-FDA parallel submission pathways. For New Entrants and Emerging Players: Anchor in gene therapy vector convergence opportunities targeting hepatocyte-expressed disorders, where lipid nanoparticle-siRNA combinations face limited established competition. Target India's PLI-subsidized manufacturing clusters in Hyderabad and Ahmedabad for cost-sensitive contract development partnerships. Pursue go-to-market positioning through integrated analytical-formulation service bundling for Massachusetts and California biotechnology sponsors. For Investors and Strategic Acquirers: Long-term, this sits as a platform-technology play because lipid nanoparticle infrastructure transfers across mRNA vaccines, gene therapies, and targeted oncology applications with minimal retooling. Acquisition targets should display microfluidic process development capabilities and validated FDA Type II drug master files. Watch CDSCO approval pathway streamlining as the signal indicating India-based manufacturing partnership viability.| Strategic Initiative | Industry Significance |
|---|---|
| Microfluidic Manufacturing Scale-Up | San Diego and Cambridge biopharmaceutical manufacturers adopt these platforms for batch-to-batch consistency. |
| EMA-FDA Parallel Submission Pathway | Swissmedic alignment accelerates market access timelines for PEGylated liposomal therapeutics. |
| Backward Integration into Phospholipid Supply | Captive hydrogenated soy phosphatidylcholine production defends margins against European supplier concentration. |
| India PLI Manufacturing Partnership | Hyderabad and Ahmedabad clusters subsidize domestic liposome API capacity for multinational sponsors. |
| Gene Therapy Vector IND Advancement | Massachusetts and California developers advance lipid nanoparticle-siRNA combinations for hepatocyte targets. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and ISO 10993 biocompatibility databases. Bottom-up triangulation across formulation type, application segment, and regional regulatory cluster anchored volume estimates, while top-down cross-checks against CDMO capacity disclosures refined value projections.
Across the analysis window, the forecasting framework modeled treatment line, dosage form, administration route, and regional regulatory cluster dimensions. CAGRs were derived from segment-level growth rate blending weighted by current revenue contribution. Industry-specific inputs included FDA breakthrough therapy designation velocity, EMA nanomedicine guideline compliance burden, and PLI scheme subsidy uptake rates in Indian manufacturing clusters.
Decision-makers should treat outputs as directional under assumptions of sustained FDA accelerated approval pathway utilization and stable phospholipid supply from European chemical suppliers; material deviation would warrant model refresh. Specific risk factors include EMA-FDA regulatory harmonization gaps, polymeric nanoparticle substitution acceleration, and phospholipid feedstock price volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Mobile MRI Services Market
Others
Cashew Kernel Market
Others
Advertising Intelligence Solution Market
Others
Global Supply Chain Risk Management Software Market
Others
AI In Government And Public Services Market
Others
Germany Smart Home Market
Others
Hot Air System Market
Others
Coloring Apps Market
Others
HPHT Diamond Cubic Press Market
Others
Cloud Broadcasting Solutions Market
Others
Middle East and Africa Cocoa Products Market
Others
Digital Audio Decoders Market
Others
Industrial Air Purifiers Market
Others
Massive Machine Type Communication in Healthcare Market
Others
Smart Home Service Market
Others
Digital Mortgage Software Market