
 China Automotive LED Lighting Market | 2026-2036
China Automotive LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
China Automotive LED Lighting Market Insights
Electric vehicle OEMs is reorganizing procurement priorities across the China automotive LED lighting supply base. Changzhou Xingyu Automotive Lighting System Co Ltd dominates domestic headlamp assembly capacity for indigenous brands. KOITO MANUFACTURING CO., LTD. sustains technical leadership in adaptive beam modules through its joint-venture footprint in China. Sanan Optoelectronics anchors upstream chip supply with captive epitaxial wafer production in Fujian and Hubei provinces.
China automotive LED lighting comprises solid-state semiconductor devices emitting visible light when electrical current passes through a gallium nitride junction, typically operating at forward voltages between 2.8 and 3.6 volts with luminous efficacy exceeding 130 lumens per watt for premium automotive grades. These devices replace halogen and xenon sources to reduce vehicle energy consumption and enable programmable beam patterns for adaptive driving functions. Headlights and taillights command the largest installed base while matrix LED technology captures expanding margin pools as domestic OEMs upgrade from standard LED configurations. Electric vehicles represent the fastest-growing end user category because NEV platforms prioritize energy-efficient electrical architectures across all auxiliary systems.
MIIT enforces GB standards for automotive lighting performance and electromagnetic compatibility, while SAMR administers compulsory certification for LED components entering vehicle supply chains. China's dual carbon goals from MEE are tightening embodied energy requirements in luminaire manufacturing, pushing suppliers toward localized chip production and reduced import dependency. Stakeholders must monitor how GB standard revisions for adaptive driving beam functionality reshape product qualification timelines and capital allocation across domestic versus import-dependent supply routes.
Market Dynamics
MIIT's tightening GB standards for luminaire efficiency are compressing qualification timelines and forcing domestic suppliers to accelerate backward integration into epitaxial wafer production, fundamentally restructuring procurement relationships across the Yangtze River Delta cluster.
Growth Catalysts
- NEV platform mandates:China's dual carbon goals from MEE require electric vehicle manufacturers to minimize auxiliary power consumption, directing procurement toward LED architectures that reduce energy draw versus halogen alternatives.
- Adaptive beam functionality:Domestic OEMs are upgrading headlamp assemblies to matrix LED configurations capable of programmable beam patterns for autonomous driving compatibility.
- Yangtze River Delta concentration:Manufacturing gravity in Shanghai, Jiangsu, and Zhejiang provinces creates dense supplier ecosystems that shorten development cycles and lower logistics costs for indigenous brands.
Market Restraints
- Gallium nitride substrate volatility:Epitaxial wafer production depends on specialized semiconductor materials subject to supply concentration in limited foundry locations, creating input cost instability for domestic chip fabricators.
- Import-dependent photonics:Premium adaptive beam modules still rely on foreign-sourced optical components, exposing assemblers to customs delays and currency fluctuation risks.
- GB standard revision friction:MIIT's evolving electromagnetic compatibility requirements force repeated recertification cycles that extend product launch timelines and consume engineering bandwidth.
Strategic Opportunities
- Western China manufacturing migration:Chongqing and Sichuan provinces offer underexploited production capacity with lower labor costs and proximity to emerging NEV assembly plants.
- Interior ambient lighting expansion:Cabin illumination systems represent an emerging application category as domestic OEMs differentiate through programmable color temperature and wellness-oriented lighting schemes.
- Localized chip fabrication incentives:Provincial industrial policies in Fujian and Hubei are subsidizing captive epitaxial growth capacity that reduces foreign exchange exposure for tier-one assemblers.
Industry Challenges
- Optical engineering talent scarcity:Adaptive beam algorithm development requires scarce expertise in computational optics and thermal management that concentrates in coastal technology hubs.
- Cleanroom capex intensity:Semiconductor-grade LED fabrication demands continuous capital reinvestment in particulate-controlled environments and MOCVD equipment upgrades.
- SAMR certification backlog:Compulsory product approval queues at the State Administration for Market Regulation are extending time-to-revenue for new luminaire introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Automotive LED Lighting Market |
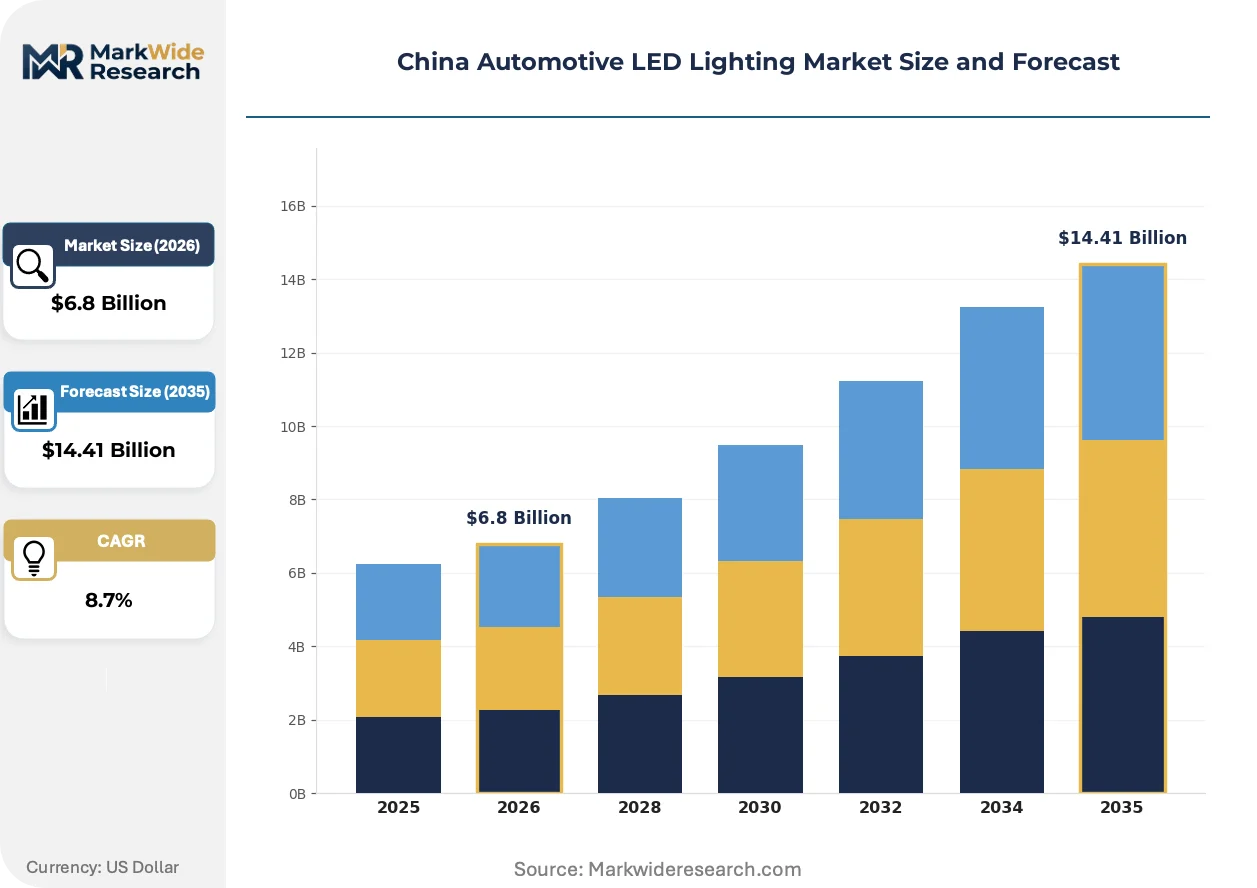
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headlights, Taillights, Fog Lights, Daytime Running Lights Technology: Standard LED, Adaptive LED, Matrix LED, Laser LED End User: Passenger Cars, Commercial Vehicles, Electric Vehicles, Luxury Cars Distribution Channel: OEMs, Aftermarket Dealers, Online Retail, Distributors |
| Companies Covered | Changzhou Xingyu Automotive Lighting System Co Ltd, Hasco Vision Technology Co Ltd, HELLA GmbH & Co. KGaA, KOITO MANUFACTURING CO., LTD., Valeo SE, Stanley Electric Co., Ltd., Sanan Optoelectronics, Refond Optoelectronics, Hyundai Mobis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Automotive LED Lighting Market Trends and Innovations
Matrix LED architectures are fragmenting the competitive landscape by separating optical hardware from software-defined beam control, enabling new entrants to compete on algorithmic differentiation rather than manufacturing scale alone.
Micro-LED pixel arrays are decomposing the traditional headlamp module into discrete addressable elements that enable real-time beam shaping without mechanical actuators. Domestic EV manufacturers are adopting these solid-state configurations faster than conventional ICE platforms. This technology is decomposing the established supplier hierarchy by allowing software specialists to capture margin previously retained by optical component fabricators.
MIIT's GB standard revisions for adaptive driving beam functionality are mandating precise luminous intensity distribution patterns that exceed legacy test protocols. Tier-one assemblers must retest entire product portfolios against updated electromagnetic compatibility thresholds. Indigenous brands with captive lighting divisions are responding faster than import-dependent suppliers, compressing the competitive window for foreign joint-venture participants.
Direct sourcing relationships between NEV OEMs and chip fabricators are displacing the traditional tiered supplier structure that intermediated component procurement. Aftermarket distributors and legacy lighting specialists are losing volume to factory-integrated supply chains. This behavioral shift is most visible among battery-electric vehicle startups in the Yangtze River Delta that prioritize vertical coordination over multi-source purchasing flexibility.
China Automotive LED Lighting Market Segmentation
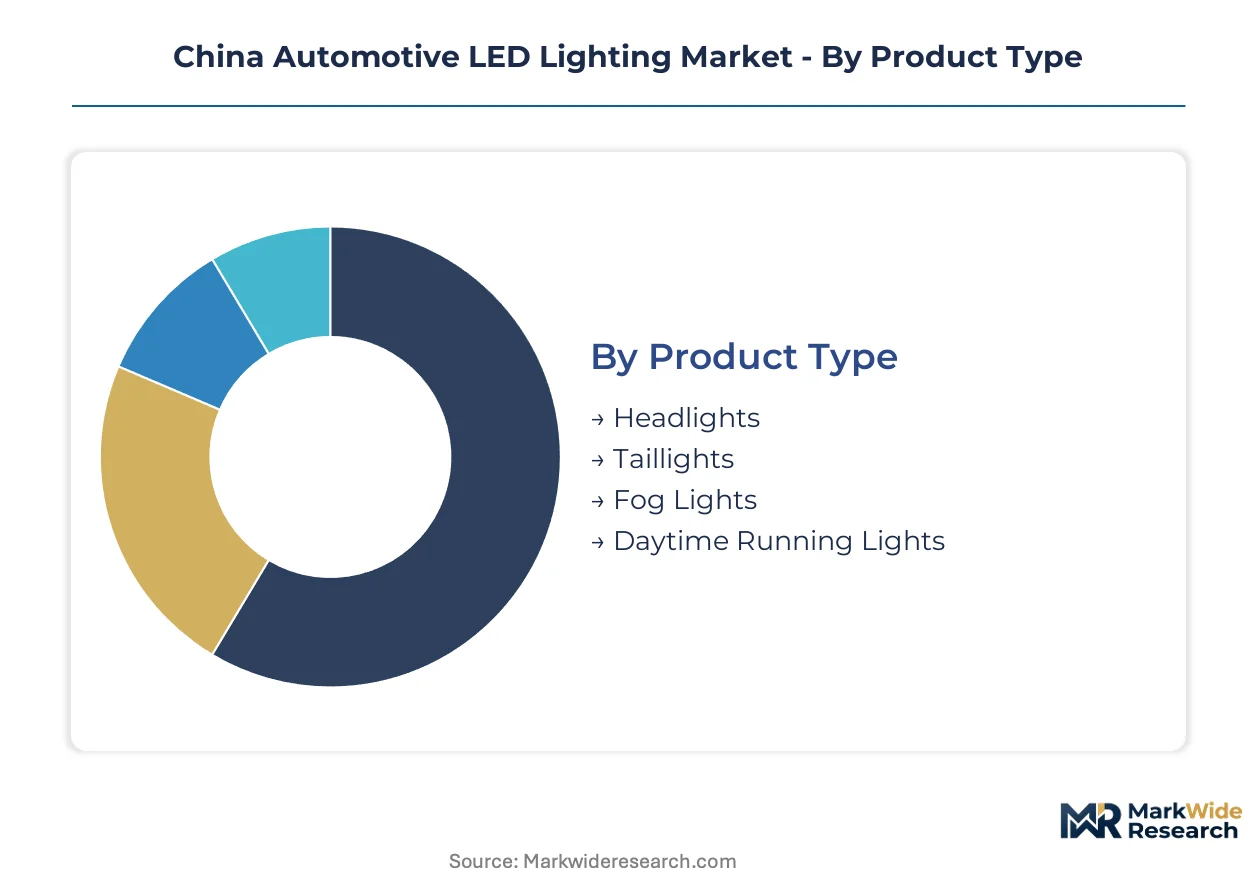
Segmentation in China's automotive LED lighting market reveals how procurement channels, technology tiers, and vehicle platforms intersect. MIIT efficiency mandates and NEV platform architectures are reshaping which segments capture capital allocation versus margin compression.
Product Type:
Headlamp and taillight assemblies flow through distinct channel economics, with OEM direct procurement dominating high-value front-end modules while aftermarket channels capture replacement demand for damaged rear assemblies.
- Headlights:Matrix LED and adaptive beam configurations operate at forward voltages between 2.8 and 3.6 volts with luminous efficacy exceeding 130 lumens per watt. Yangtze River Delta manufacturing clusters in Shanghai, Jiangsu, and Zhejiang provinces concentrate indigenous brand demand as domestic OEMs upgrade from standard LED configurations for autonomous driving compatibility.
- Taillights:Sequential and animated signal functions require programmable LED drivers with precise thermal management. Chongqing and Sichuan provinces are emerging as alternative production locations with lower labor costs and proximity to emerging NEV assembly plants.
- Fog Lights:Auxiliary beam modules face pricing pressure from integrated headlamp systems that absorb fog functionality into main assemblies.
- Daytime Running Lights:Mandated visibility requirements under GB standards sustain baseline volume despite margin compression from commoditized LED strip designs.
Headlights dominate installed base value concentration. Taillights are where supplier margin expansion concentrates through sequential animation and signature lighting differentiation.
Technology:
Technology tiers stratify by capital intensity and software content, with premium adaptive systems requiring cleanroom fabrication while standard LED packages compete on epitaxial wafer scale.
- Standard LED:Conventional gallium nitride junction devices with fixed beam patterns serve economy vehicle segments and replacement markets. Fujian and Hubei provincial subsidies for localized chip fabrication are reducing foreign exchange exposure for tier-one assemblers sourcing these commodity packages.
- Adaptive LED:Motorized beam leveling and cornering functions integrate mechanical actuators with thermal management systems. SAMR certification timelines extend product launch cycles for foreign joint-venture participants versus indigenous brands with captive lighting divisions.
- Matrix LED:Decomposing traditional modules into discrete addressable elements enables real-time beam shaping without mechanical components. Domestic EV manufacturers in the Yangtze River Delta are adopting these solid-state configurations faster than conventional ICE platforms.
- Laser LED:High-intensity supplementary sources extend throw distance for premium highway driving functions. Import-dependent photonics expose assemblers to customs delays and currency fluctuation risks.
Standard LED commands volume scale. Matrix LED is climbing the fastest as software-defined beam control separates optical hardware from algorithmic differentiation.
End User:
Vehicle platform electrification is redrawing segment boundaries, with NEV architectures prioritizing energy-efficient auxiliary systems that reduce battery drain.
- Passenger Cars:Indigenous brands with captive lighting divisions respond faster to MIIT GB standard revisions than import-dependent suppliers. Interior ambient lighting expansion represents an emerging application category as domestic OEMs differentiate through programmable color temperature.
- Commercial Vehicles:Fleet procurement emphasizes durability and standardized replacement protocols over adaptive beam functionality. Aftermarket distributors retain stronger position in this segment versus factory-integrated supply chains.
- Electric Vehicles:Battery-electric platforms prioritize LED architectures across all auxiliary systems to minimize energy draw. Direct sourcing relationships between NEV OEMs and chip fabricators are displacing traditional tiered supplier structures.
- Luxury Cars:Matrix LED and laser configurations capture premium positioning through programmable beam patterns and signature lighting animations. Optical engineering talent scarcity in computational optics and thermal management concentrates competitive advantage in coastal technology hubs.
Passenger cars anchor volume demand. Electric vehicles are gaining share fastest as NEV mandates from MEE redirect procurement toward energy-efficient electrical architectures.
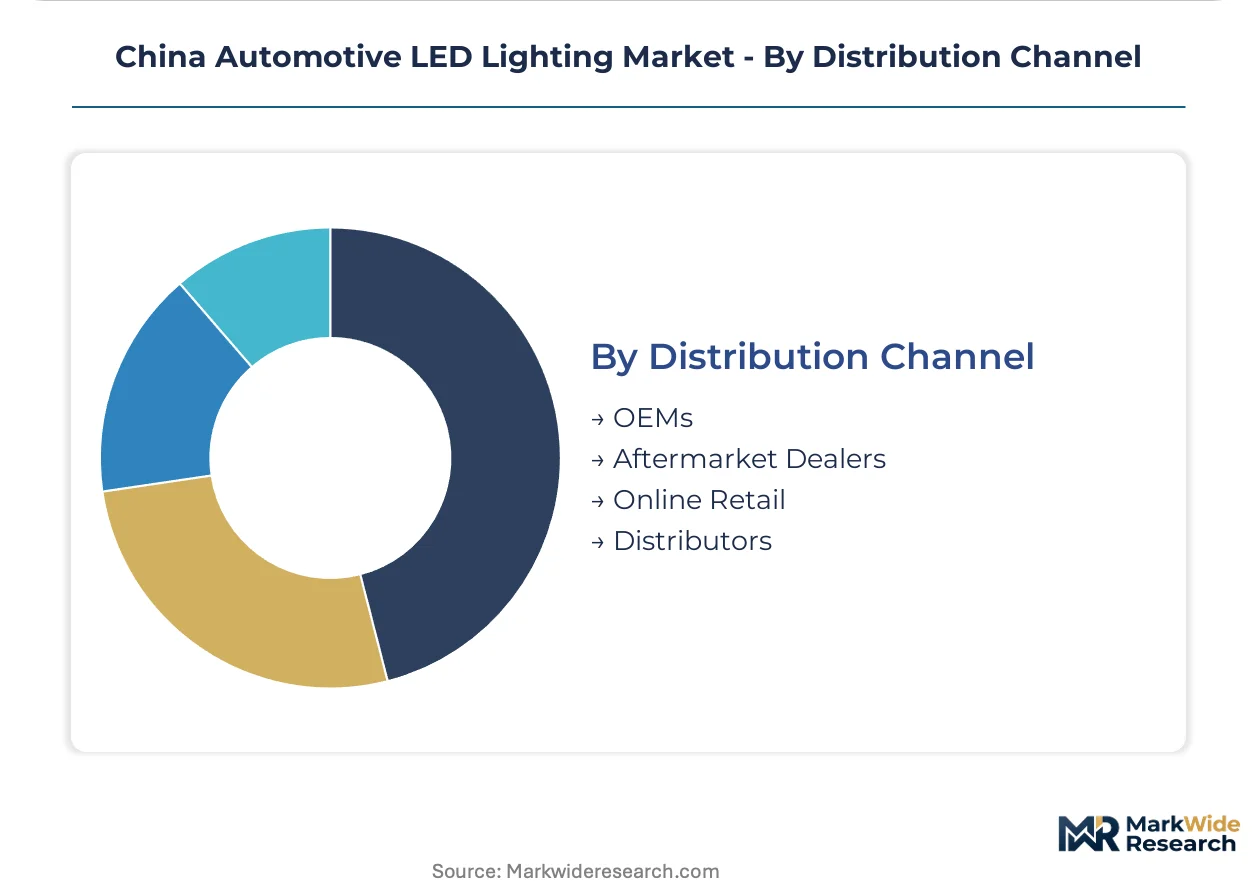
Distribution Channel:
Channel structure reflects the displacement of multi-source purchasing by vertical coordination, particularly visible among battery-electric vehicle startups.
- OEMs:Factory-integrated supply chains dominate headlamp and adaptive beam procurement. Changzhou Xingyu Automotive Lighting System Co Ltd anchors domestic headlamp assembly capacity for indigenous brands.
- Aftermarket Dealers:Replacement demand for damaged assemblies and upgrade retrofits sustains independent channel volume. Legacy lighting specialists are losing share to direct OEM relationships.
- Online Retail:E-commerce platforms capture accessory and retrofit demand from consumer vehicle owners. SAMR compulsory certification requirements create compliance barriers for unverified sellers.
- Distributors:Intermediary networks retain relevance in commercial vehicle fleets and regional repair chains. Western China manufacturing migration toward Chongqing and Sichuan is shortening logistics corridors for these channels.
OEMs dominate value capture. Online retail is where channel experimentation concentrates as direct-to-consumer accessory sales bypass traditional distribution layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
LED chip fabrication clusters in Fujian and Hubei provinces supply epitaxial wafers to Yangtze River Delta assemblers. MIIT's GB standards enforcement varies across provincial jurisdictions, creating differentiated qualification timelines.
Yangtze River Delta
Shanghai, Jiangsu, and Zhejiang provinces concentrate indigenous brand headlamp assembly capacity. MIIT fuel consumption standards drive LED adoption across NEV platforms manufactured in this cluster. Changzhou anchors domestic lighting system production for battery-electric vehicle startups prioritizing vertical coordination.
Pearl River Delta
Guangdong province hosts aftermarket distribution networks serving southern China's replacement demand. SAMR certification facilities in Shenzhen process compulsory product approvals for LED components. Dongguan manufacturers supply commoditized LED strip designs to economy vehicle segments.
Sichuan-Chongqing
Western China migration offers underexploited production capacity with lower labor costs. Provincial industrial policies subsidize manufacturing relocation from coastal clusters. Chongqing's emerging NEV assembly plants shorten logistics corridors for interior ambient lighting modules.
Fujian
Sanan Optoelectronics anchors captive epitaxial wafer production reducing foreign exchange exposure. Localized chip fabrication incentives from provincial authorities support backward integration into gallium nitride substrate processing. Xiamen facilities supply upstream semiconductor materials to tier-one assemblers nationwide.
Hubei
Wuhan's optoelectronics corridor concentrates MOCVD equipment installations for automotive-grade LED production. Dual carbon goals from MEE tighten embodied energy requirements in luminaire manufacturing. The province's cleanroom infrastructure supports semiconductor-grade fabrication for matrix LED configurations.
China Automotive LED Lighting Market Competitive Landscape
Concentration sits with domestic assemblers possessing captive lighting divisions and foreign joint-ventures holding technical leadership in adaptive beam modules. The vendor base stratifies across three tiers: indigenous brands with in-house production, multinational joint-ventures leveraging global technology portfolios, and specialized component fabricators supplying epitaxial wafers. Dominant competitive moves include backward integration into chip production and direct sourcing relationships displacing traditional tiered supplier structures.
Among domestic assemblers, Changzhou Xingyu Automotive Lighting System Co Ltd and Hasco Vision Technology Co Ltd exemplify the indigenous brand tier with integrated manufacturing footprints. KOITO MANUFACTURING CO., LTD. occupies a position representing foreign joint-venture technical leadership in adaptive beam functionality. Sanan Optoelectronics anchors the upstream component tier through captive epitaxial wafer production capabilities in Fujian and Hubei provinces.
| Leading Market Players |
|---|
| Changzhou Xingyu Automotive Lighting System Co Ltd |
| Hasco Vision Technology Co Ltd |
| HELLA GmbH & Co. KGaA |
| KOITO MANUFACTURING CO., LTD. |
| Valeo SE |
| Stanley Electric Co., Ltd. |
| Sanan Optoelectronics |
| Refond Optoelectronics |
| Hyundai Mobis |
| Others |
Pricing and Supply Chain Analysis
MIIT's GB standards enforcement gates both supplier qualification and price tier stratification, compressing margins for import-dependent assemblers while rewarding domestic participants with captive certification capabilities. SAMR compulsory product approvals create a dual-track market where certified indigenous brands command premium positioning against uncertified aftermarket alternatives.
Pricing Analysis
GB standard revisions dictate the pricing tier structure across headlamp and taillight assemblies. Three-tier pricing structure across premium, standard, and economy levels separates matrix LED configurations from adaptive systems and commodity LED packages. Price differentiation hinges on certification grade and volume scale, with Yangtze River Delta OEMs least sensitive due to direct sourcing relationships while aftermarket distributors face acute cost compression from SAMR compliance burdens.
Supply Chain Analysis
Inventory cycles for gallium nitride substrates extend lead times for epitaxial wafer procurement, forcing tier-one assemblers to buffer raw material positions. Supply concentrates in China, Taiwan, and South Korea for LED chip fabrication, with MOCVD equipment and specialized photonics drawing from concentrated foundry locations. Single-source vulnerability in premium optical components exposes assemblers to customs friction, while distribution runs through factory-integrated supply chains displacing traditional tiered intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical engineering talent scarcity in computational beam algorithms and thermal management systems constrains competitive expansion, favoring incumbents with established coastal R&D footprints over new entrants lacking cleanroom fabrication experience.
For Market Incumbents: Secure backward integration into epitaxial wafer production through provincial subsidy programs in Fujian and Hubei, insulating margin from gallium nitride substrate volatility. Lock in direct sourcing relationships with NEV OEMs in the Yangtze River Delta before emerging chip fabricators capture platform allocation.
For New Entrants and Emerging Players: SAMR certification fast-tracks for interior ambient lighting modules offer lower regulatory friction than headlamp assemblies, enabling market entry through cabin illumination differentiation. Target western China manufacturing migration to Chongqing and Sichuan, leveraging provincial industrial policies and proximity to emerging NEV assembly plants for logistics advantage.
For Investors and Strategic Acquirers: MIIT's evolving GB standards for adaptive driving beam functionality reshape the acquisition landscape toward indigenous brands with captive lighting divisions capable of rapid recertification. Prioritize tier-one assemblers with in-house epitaxial growth capacity and established SAMR approval pipelines. Watch for provincial subsidy exhaustion in Fujian and Hubei as an inflection signal for chip fabrication economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxial Wafer Production | Captive gallium nitride substrate supply reduces foreign exchange exposure and input cost instability for tier-one assemblers. |
| SAMR Certification Fast-Track Investment | Accelerated compulsory product approval timelines compress competitive windows for import-dependent joint-venture participants. |
| Western China Manufacturing Footprint Expansion | Chongqing and Sichuan relocation lowers labor costs and shortens logistics corridors for emerging NEV assembly plants. |
| Matrix LED Software-Defined Beam Development | Algorithmic differentiation separates optical hardware from beam control, enabling margin capture by computational optics specialists. |
| Direct OEM Sourcing Relationship Establishment | Factory-integrated supply chains displace traditional tiered intermediaries and lock in platform allocation with battery-electric startups. |
Research Methodology
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and SAMR certification specialists converged on the working assumptions. Primary interviews combined with secondary validation against MIIT regulatory filings, vehicle production databases, and provincial industrial policy disclosures. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled include vehicle propulsion architecture, luminaire technology tier, OEM brand tier, and regional production cluster concentration. CAGRs derived from installed base evolution and content-per-vehicle trajectories throughout the forecast period. Forecast inputs incorporated NEV mandate enforcement intensity from MEE and GB standard revision timelines from MIIT.
Decision-makers should treat outputs as directional under assumptions of sustained NEV platform growth and stable gallium nitride substrate supply; material deviation in provincial subsidy durability or SAMR certification velocity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Eye Balm Market
Others
Conditional Access System (CAS) Market
Others
Coriolis Meters Market
Others
France Location-Based Services Market
Others
8K Technology Market
Others
Latin America IT Device Market
Others
Spain Feed Additives Market
Others
Floor Cleaning and Mopping Machine Market
Others
Europe Battery Packaging Market
Others
Binoculars and Mounting Solutions Market
Others
Africa 3D Printing Construction Market
Others
Prunes Market
Others
Server Market
Others
Asia-Pacific Intercom Devices Market
Others
North America Flexographic Printing Market
Others
Digital Signage Media Player Market