
 South America Halal Food and Beverages Market | 2026-2036
South America Halal Food and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
South America Halal Food and Beverages Market Analytics
Buyer concentration among Brazilian supermarket chains is hardening as Carrefour and GPA consolidate halal procurement contracts across their banners. BRF S.A. anchors its position through captive slaughterhouse certification and direct retail partnerships. Nestlé S.A. competes in dairy-based halal beverages with reformulated whey processing lines. Unilever extends its reach via specialized sauces and dressings carrying Brazilian Islamic federation approval.
South America Halal Food and Beverages encompasses products manufactured under Islamic dietary law, requiring species-permissible sourcing, ritual slaughter (dhabihah for livestock), and exclusion of alcohol, porcine derivatives, and cross-contaminants throughout processing. The category serves both observant Muslim populations and export markets demanding traceable religious compliance, with cold-chain integrity and lot-level documentation as critical functional parameters. Meat dominates current volume due to Brazil's preeminence in beef and poultry exports to Middle Eastern buyers, while snack food represents the fastest-expanding margin pool as younger consumers seek portable, certified options. Dairy lags in certified innovation but carries latent premium potential where DSM's enzyme technologies enable rennet-free cheese production.
Brazil's MAPA (Ministério da Agricultura, Pecuária e Abastecimento) oversees federal halal inspection protocols alongside certifying bodies accredited by the country's Islamic federation, while Argentina's SENASA applies parallel standards for export-bound meat. These frameworks determine market access rather than domestic consumption alone, since much South American halal output ships to Gulf Cooperation Council states requiring third-party audit trails. Stakeholders must monitor whether Mercosur trade harmonization incorporates mutual recognition of halal standards or perpetuates bilateral certification costs.
Market Dynamics
Certification harmonization pressure between Brazil's MAPA protocols and Argentina's SENASA frameworks is restructuring competitive access across the Mercosur trade bloc, forcing processors to maintain dual audit trails for Gulf Cooperation Council export eligibility.
Growth Catalysts
- MAPA Federal Halal Protocols:Brazil's agricultural ministry streamlined slaughterhouse inspection standards, reducing certification timeline friction for meat processors seeking Middle Eastern market access.
- Slaughterhouse Cluster Concentration:São Paulo state's processing capacity around Santos port creates cold-chain efficiency that lowers per-unit compliance documentation costs for export-bound containers.
- DSM Enzyme Technologies:Rennet-free cheese production methods enable dairy processors to capture premium positioning previously blocked by traditional animal-derived coagulant restrictions.
Market Restraints
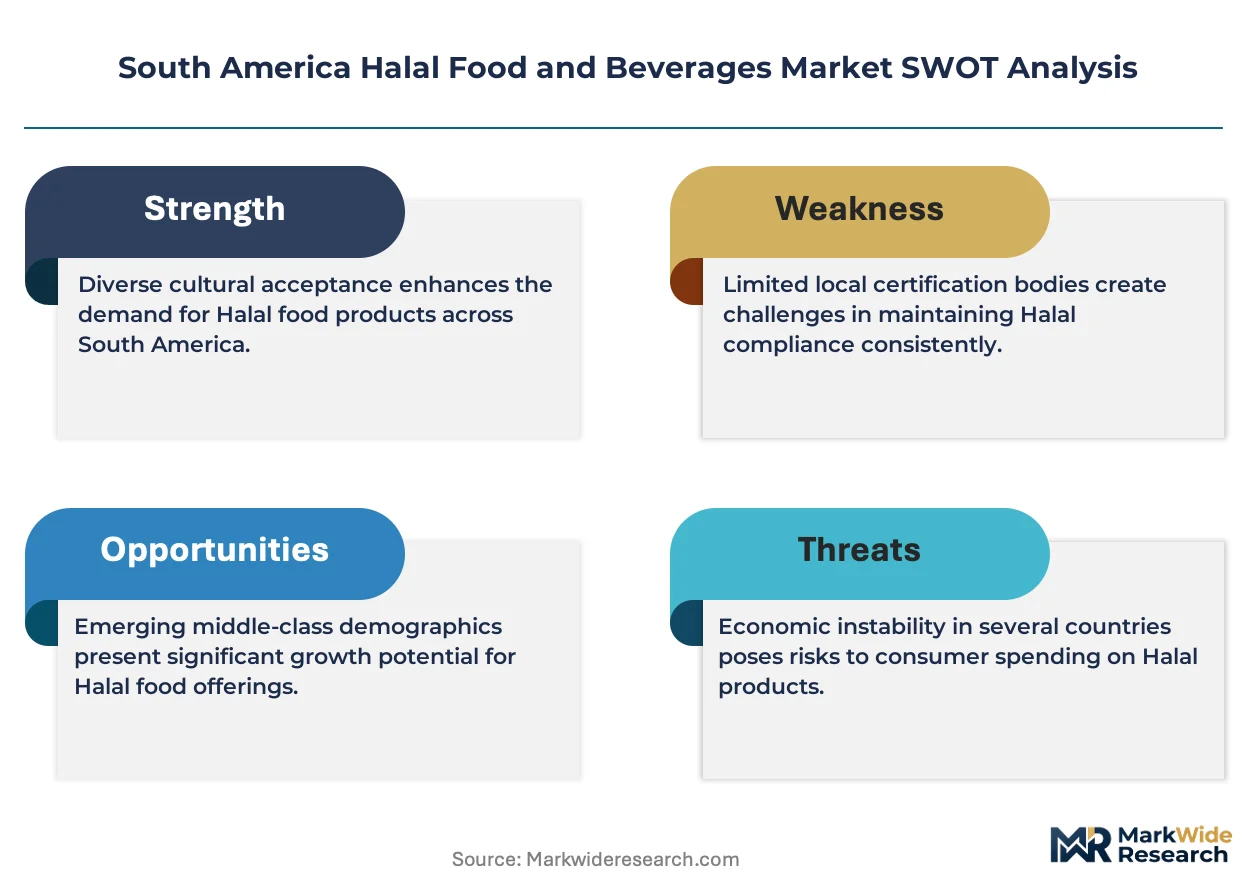
- Dual Certification Cost Structure:Processors serving both Brazilian Islamic federation standards and Gulf import requirements face redundant audit fees that compress margin on mid-volume production runs.
- Slaughterhouse Geographic Concentration:São Paulo state's dominance in certified capacity creates single-point vulnerability for cold-chain disruptions affecting export scheduling reliability.
- Rennet Substitution Technical Limitations:Microbial enzyme alternatives in hard cheese varieties fail to replicate traditional texture profiles, constraining product range expansion in premium dairy segments.
Strategic Opportunities
- Argentina's Underpenetrated Retail Shelf Space:Buenos Aires province supermarkets maintain minimal halal-dedicated inventory versus São Paulo benchmarks, creating first-mover positioning for branded protein lines.
- Specialized Sauce and Dressing Applications:Brazilian Islamic federation-approved condiment certification remains sparse, opening margin-rich positioning in meal-prep and foodservice channels.
- Mercosur Mutual Recognition Convergence:Pending trade harmonization protocols could eliminate bilateral certification redundancy, collapsing compliance cost structures for cross-border processors.
Industry Challenges
- Slaughter Ritual Skill Scarcity:Qualified dhabihah practitioners remain concentrated in legacy processing facilities, constraining capacity expansion at newer certified plants.
- Lot-Level Documentation Capex Intensity:Blockchain-enabled traceability systems required by Gulf buyers demand seven-figure infrastructure investment that excludes smaller cooperatives from premium export tiers.
- Cross-Contamination Protocol Integration:Separating halal and non-halal production lines within existing facilities requires physical plant reconfiguration that disrupts operational throughput during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Halal Food and Beverages Market |
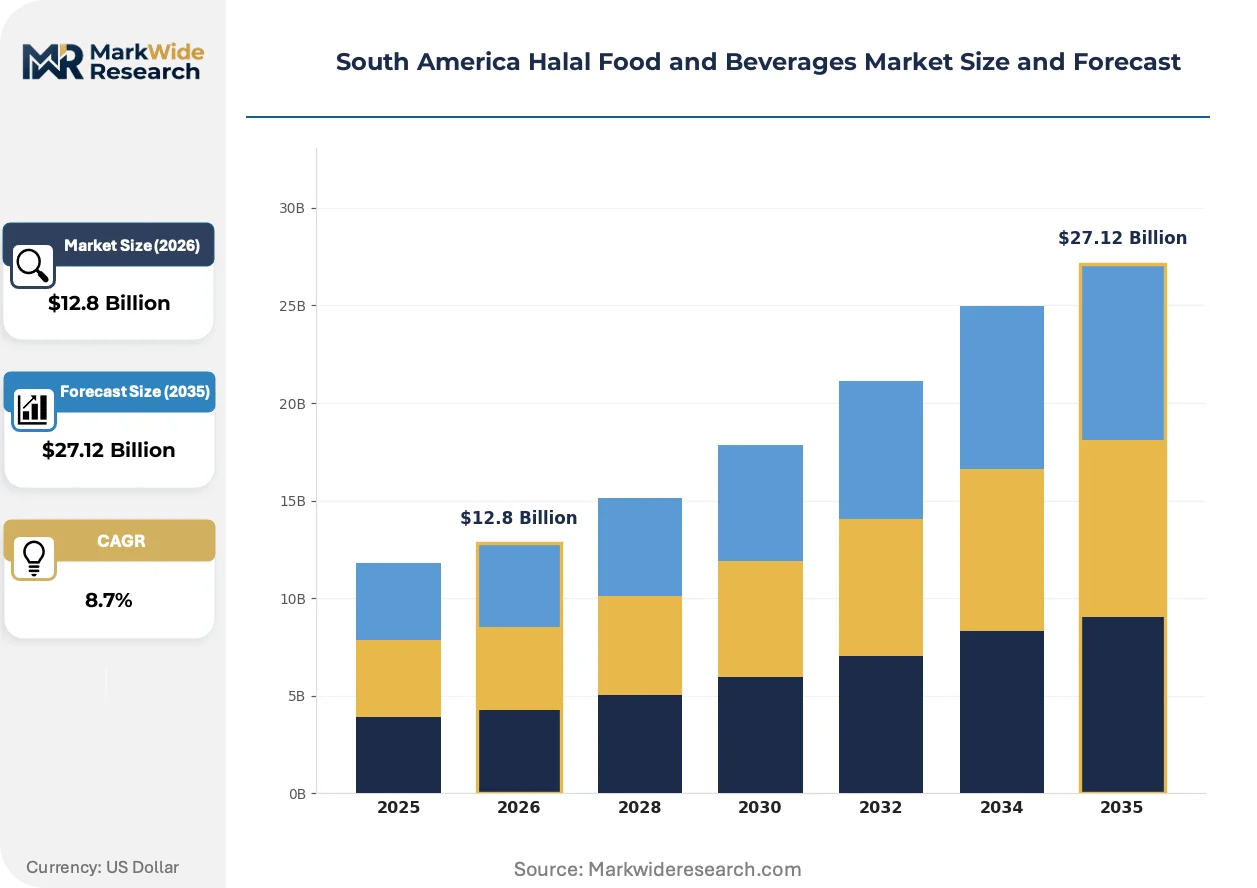
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat, Snack Food, Dairy, Beverages End User: Retail, Food Service, Online, Wholesale Packaging Type: Bottles, Cans, Boxes, Pouches Distribution Channel: Supermarkets, Grocery Stores, Specialty Stores, Online Retail |
| Companies Covered | Nestlé S.A., Cargill, Unilever, BRF S.A., PepsiCo, Kraft Heinz, Archer Daniels Midland Company, Koninklijke DSM N.V., Danone, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Halal Food and Beverages Market Evolving Landscape
Digital traceability infrastructure and enzyme-based ingredient substitution are compressing traditional compliance cost structures while opening new product formulation pathways previously blocked by ritual slaughter dependencies.
Blockchain-enabled lot tracking is consolidating supplier accountability standards across Brazilian beef and poultry export channels. Major Middle Eastern importers now mandate immutable chain-of-custody records from slaughter through container loading. This technology compression is eliminating paper-based audit trails that previously created week-long documentation delays at Gulf ports.
Argentina's SENASA revised its export-bound halal inspection framework to parallel Brazilian MAPA protocols, creating regulatory convergence pressure across the Southern Cone. Meat processors operating dual-country supply chains face streamlined but stricter documentation requirements. The reform most affects mid-sized cooperatives in Córdoba province that previously relied on informal certification pathways.
Health-conscious non-Muslim consumers in São Paulo and Buenos Aires metropolitan areas are driving certification-driven preference shifts in protein purchasing. Supermarket chains respond by expanding dedicated shelf space and private-label halal lines. This demand rotation is most visible in São Paulo state's upscale suburban districts where certified poultry commands price premiums over conventional alternatives.
South America Halal Food and Beverages Market Segmentation
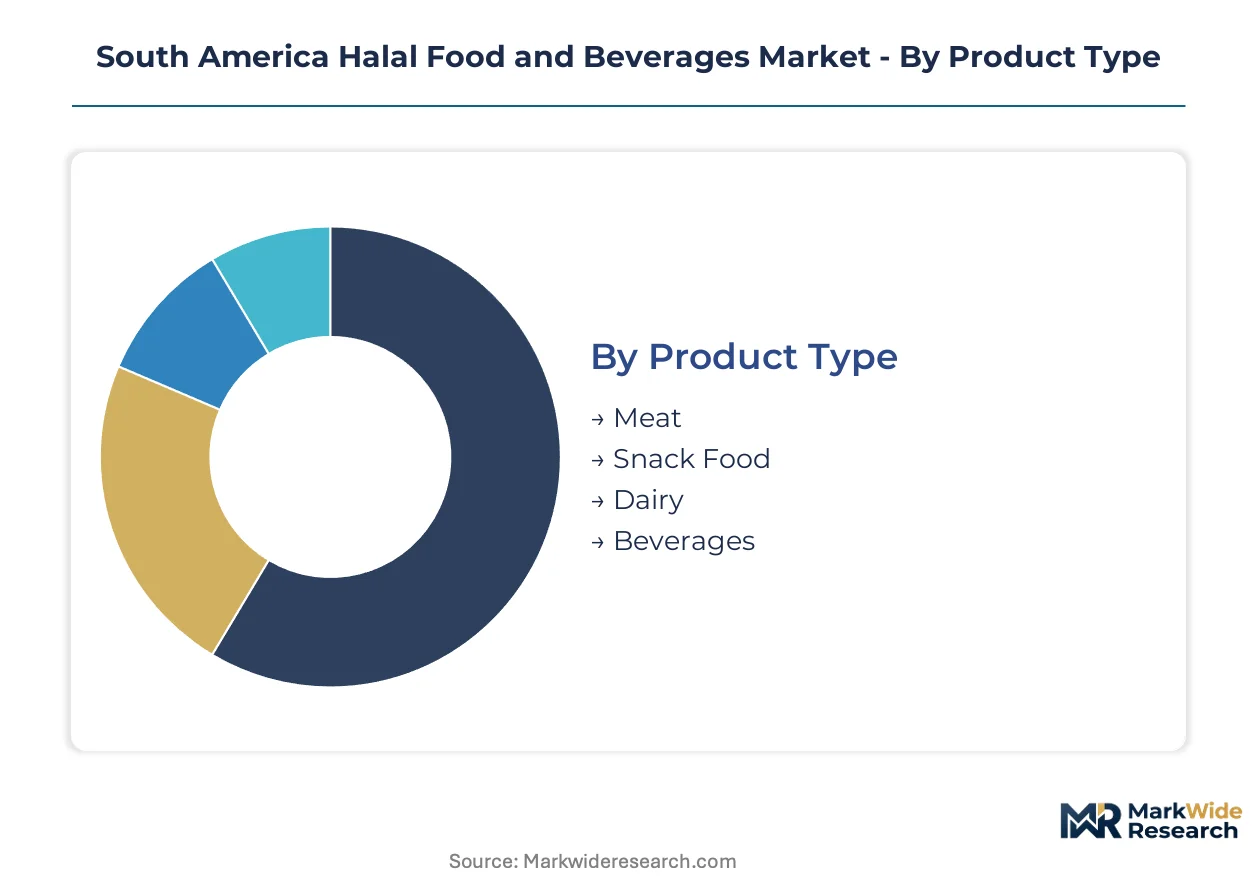
Halal food and beverage segmentation in South America reflects dual demand streams: observant Muslim communities requiring ritual compliance, and export markets demanding traceable certification. Category boundaries increasingly blur as health-conscious non-Muslim consumers adopt certified products for perceived quality assurance.
Product Type:
Upgrade cycles in halal product portfolios center on reformulation investments that unlock premium positioning and Gulf Cooperation Council market access.
- Meat:Beef and poultry products processed under dhabihah slaughter protocols with MAPA federal inspection oversight. São Paulo state slaughterhouses cluster around Santos port, leveraging cold-chain density to reduce per-unit compliance documentation costs for Middle Eastern export containers.
- Snack Food:Portable certified options including chips, nuts, and protein bars manufactured with halal-compliant flavoring systems and processing aids. Younger consumers across São Paulo and Buenos Aires metropolitan areas drive demand rotation toward convenience formats that carry Brazilian Islamic federation approval marks.
- Dairy:Milk, cheese, and yogurt products requiring rennet-free or microbial enzyme coagulation to satisfy religious restrictions.
- Beverages:Non-alcoholic drinks including dairy-based formulations and functional beverages with halal-certified ingredient sourcing.
Meat sits at the top of the volume ranking, with snack food climbing the fastest.
End User:
Cost tier stratification separates high-volume institutional buyers from premium-positioned retail channels seeking certification-driven margin capture.
- Retail:Supermarket chains and independent grocers serving Muslim communities and health-conscious non-Muslim shoppers. Carrefour and GPA in Brazil consolidate procurement contracts across banners, hardening buyer concentration and squeezing supplier margins on standardized halal SKUs.
- Food Service:Restaurants, cafeterias, and catering operations requiring bulk-certified ingredients with batch-level documentation.
- Online:E-commerce platforms and direct-to-consumer delivery services expanding halal product accessibility.
- Wholesale:Distributors supplying institutional buyers and regional retailers with volume-certified products.
Retail commands the dominant volume position, with food service gaining share fastest in urban corridor expansion.
Packaging Type:
Application-driven packaging selection balances shelf-life extension against certification visibility requirements and cold-chain compatibility.
- Bottles:Rigid containers for beverages and liquid dairy products requiring tamper-evident seals and lot-code traceability for Gulf import compliance.
- Cans:Metal containers for shelf-stable proteins and beverages, offering extended durability for export shipping to Middle Eastern markets.
- Boxes:Corrugated and folding carton formats for bulk protein shipments and retail-ready multipacks.
- Pouches:Flexible film structures for snack foods and portion-controlled protein products, enabling lightweight export logistics.
Bottles lead current volume deployment, with pouches expanding most quickly on snack food format innovation.
Distribution Channel:
Geographic concentration of certified consumption creates channel-specific investment priorities across metropolitan versus secondary markets.
- Supermarkets:Large-format retailers with dedicated halal shelf space and private-label certification programs. São Paulo state benchmarks exceed Buenos Aires province penetration, creating first-mover positioning opportunities for branded protein lines in underdeveloped Argentine retail networks.
- Grocery Stores:Neighborhood and ethnic-format retailers serving concentrated Muslim communities with curated certified assortments.
- Specialty Stores:Butcher shops and religious-goods retailers emphasizing ritual slaughter provenance and clerical certification authority.
- Online Retail:Digital platforms aggregating certified products across multiple suppliers for home delivery.
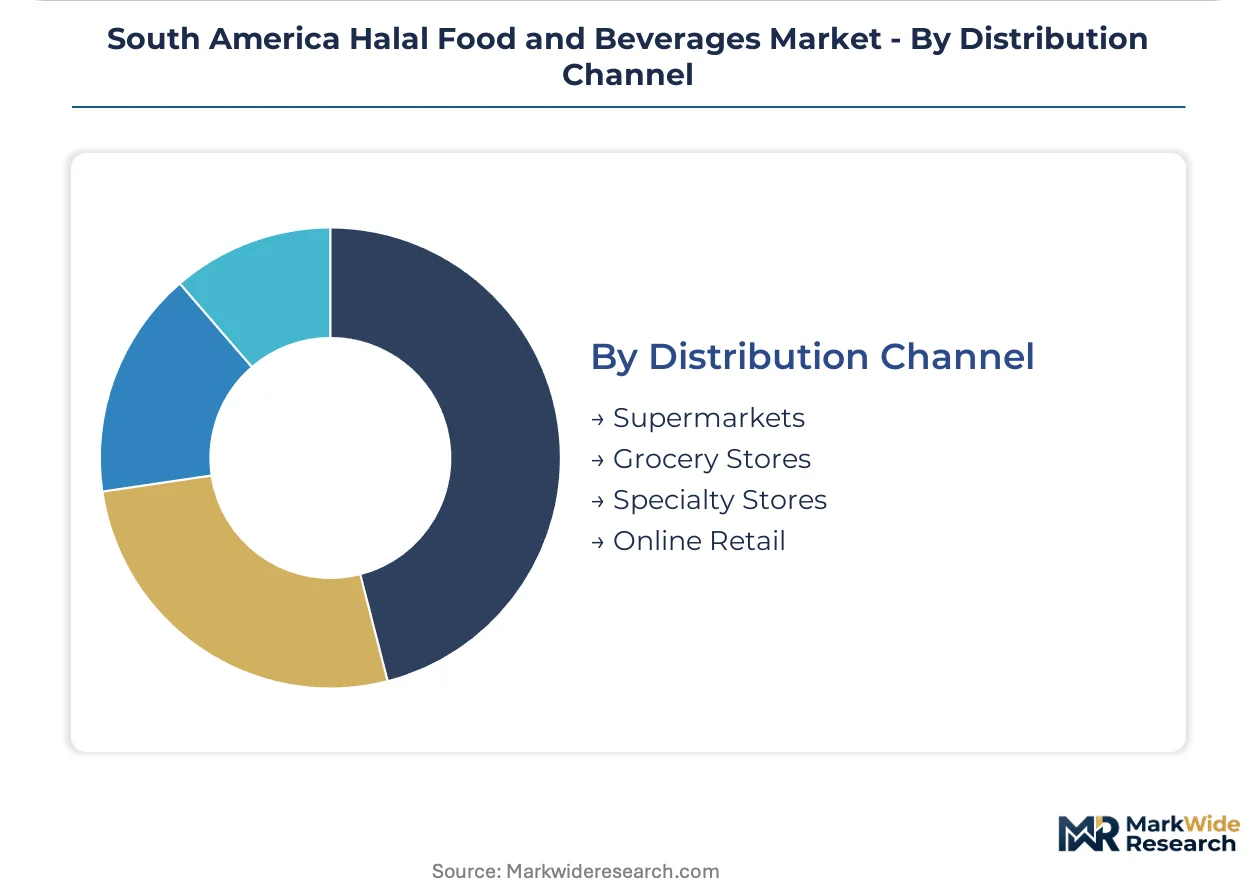
Supermarkets dominate volume throughput, with specialty stores capturing the steepest expansion trajectory on provenance-focused consumer preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands export volume leadership while Argentina cultivates underdeveloped retail penetration, creating divergent investment profiles across the Southern Cone.
Brazil
MAPA federal halal protocols and São Paulo slaughterhouse clusters drive Middle Eastern export dominance. The agricultural ministry's streamlined inspection standards compress certification timelines for Santos port-bound meat processors. Cold-chain density around the port reduces per-unit compliance documentation costs for Gulf Cooperation Council-bound containers.
Argentina
SENASA export inspection frameworks and Buenos Aires retail underpenetration create first-mover positioning opportunities. The national food safety agency's revised halal standards parallel Brazilian protocols, easing dual-country supply chain management. Córdoba province mid-sized cooperatives face stricter documentation requirements under reformed certification pathways.
Chile
Santiago metropolitan retail expansion and health-conscious consumer segments attract certified protein investment. The country's economic development agency promotes halal export diversification beyond traditional mining and agriculture. Valparaíso port logistics infrastructure supports emerging cold-chain capabilities for Pacific-rim halal trade routes.
Colombia
Bogotá urban corridor demand and Caribbean coastal Muslim communities anchor nascent retail development. The national standards body develops halal certification guidelines to reduce import dependency on Brazilian suppliers. Medellín food processing clusters experiment with certified snack food manufacturing for domestic and regional export markets.
Uruguay
Montevideo port beef exports and small-scale Muslim population concentration limit dedicated halal infrastructure investment. The ministry of livestock, agriculture and fisheries explores certification mutual recognition with Brazilian MAPA to access shared export channels. Punta del Este tourism corridor generates seasonal foodservice demand for certified protein sourcing.
South America Halal Food and Beverages Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification-heavy protein and convenience food segments. Market structure tilts toward consolidation as Brazilian retail buyer concentration hardens procurement leverage. Three archetypes dominate: integrated meat processors with captive slaughterhouse certification, multinational FMCG players with reformulated product lines, and specialty ingredient suppliers enabling dairy innovation. Competitive moves center on direct retail partnership formation and geographic certification expansion into underpenetrated Argentine and Chilean markets.
Among Swiss-based diversified nutrition conglomerates, Nestlé S.A. and Koninklijke DSM N.V. exemplify contrasting strategic positions—one occupying integrated consumer packaged goods territory, the other anchoring specialty enzyme and ingredient technology supply. Brazilian protein processor BRF S.A. represents the integrated slaughterhouse-certification archetype, while Netherlands-originated Unilever sits within the multinational FMCG tier leveraging Brazilian Islamic federation approval for condiment and dressing applications.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Cargill |
| Unilever |
| BRF S.A. |
| PepsiCo |
| Kraft Heinz |
| Archer Daniels Midland Company |
| Koninklijke DSM N.V. |
| Danone |
| Others |
Value Network & Pricing Analysis
Blockchain-enabled traceability infrastructure is compressing documentation cost economics while simultaneously redistributing pricing power toward slaughterhouse operators that have absorbed the seven-figure capex burden. São Paulo state processors with cold-chain density around Santos port now capture margin premiums that smaller cooperatives cannot match, creating a bifurcated supply structure where certification-grade capacity commands distinct pricing tiers.
Pricing Analysis
Capacity additions in São Paulo state are reshaping price floors for MAPA-certified meat exports to Gulf Cooperation Council markets. Three-tier pricing structure across premium, standard, and economy levels separates blockchain-traceable lot-level documentation from paper-based audit trails and informal certification pathways. Price differentiation hinges on cold-chain integrity guarantees and bilateral certification completeness. Pricing pressure stems from redundant audit fees compressing margins on mid-volume production runs. Foodservice buyers exhibit highest price sensitivity due to bulk procurement leverage, while retail chains with private-label programs absorb premium positioning for shelf-space access.
Supply Chain Analysis
Brazilian federal halal protocols and domestic-content mandates for MAPA-inspected slaughterhouses are reshaping sourcing patterns across the Southern Cone. Geographic supply concentration centers on Brazil, Argentina, and Uruguay, with São Paulo state anchoring cold-chain infrastructure. Raw material dependencies include live cattle and poultry stocks, ritual slaughter practitioner pools, and microbial enzyme inputs for dairy reformulation. Supply chain risk manifests as single-point vulnerability from São Paulo's dominance in certified slaughterhouse capacity. Distribution runs through Santos port export terminals for Middle Eastern markets, with emerging Valparaíso corridor development for Pacific-rim diversification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America Halal Food and Beverages Market functions as a stable compounder anchored by structural export demand from Gulf Cooperation Council states with limited alternative protein sourcing options. Certification-grade capacity scarcity perpetuates durable margin pools for compliant operators.
For Market Incumbents: Deepen captive slaughterhouse certification through MAPA federal protocol alignment and direct retail partnership formation with Carrefour and GPA banner consolidation. Threat substitution from Argentine SENASA-harmonized competitors demands preemptive certification investment in Córdoba province cooperatives. Channel control through cold-chain infrastructure ownership remains the critical defensive lever against margin compression from dual audit cost structures. For New Entrants and Emerging Players: E-commerce platform aggregation offers the lowest-friction entry vector for branded protein lines seeking Buenos Aires province retail penetration without incumbent buyer concentration leverage. White-space targets concentrate in Argentine supermarket halal shelf expansion and Brazilian Islamic federation-approved condiment certification. Foodservice direct distribution bypasses retail procurement consolidation while capturing institutional batch-documentation premiums. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized cooperatives facing SENASA documentation upgrades without capital reserves for blockchain traceability deployment. Long-term viability frames around certification mutual recognition convergence across Mercosur eliminating bilateral compliance redundancy. Acquisition target archetype: Argentine processors with SENASA alignment progress and underdeveloped retail channel relationships. The signal to watch is MAPA-ANVISA mutual recognition protocol advancement collapsing cross-border certification friction.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Mutual Recognition Pursuit | Mercosur harmonization would eliminate redundant audit fees for cross-border processors. |
| Blockchain Traceability Deployment | Seven-figure infrastructure investment secures Gulf Cooperation Council export tier access. |
| Rennet-Free Cheese Production Scale-Up | DSM enzyme technology unlocks premium dairy positioning previously blocked by ritual restrictions. |
| Argentine Retail Shelf Expansion | Buenos Aires province underpenetration creates first-mover positioning for branded protein lines. |
| Dhabihah Practitioner Training Programs | Qualified slaughter ritual skill scarcity constrains capacity expansion at newer certified plants. |
Research Methodology
Direct dialogue with MAPA compliance officers, SENASA inspection leads, supermarket category buyers, cold-chain logistics operators, and Brazilian Islamic federation certifiers grounded qualitative assessment. Secondary validation drew from customs export records, agricultural ministry inspection bulletins, Gulf Cooperation Council import documentation requirements, and refrigerated container shipping manifests. Bottom-up and top-down triangulation cross-checked slaughterhouse capacity estimates against port throughput data and retail shelf-space audits.
Bottom-up modeling segmented volume and value outputs across product type, end user, packaging format, and distribution channel dimensions throughout the forecast period. CAGRs derived from export trajectory analysis weighted by Middle Eastern import demand elasticity and domestic retail penetration curves. Industry-specific forecast inputs included MAPA certification timeline compression effects and DSM enzyme technology adoption curves in dairy processing.
The model assumes a particular technology adoption path; alternative pathways for blockchain traceability deployment would alter the outlook if Gulf buyers relax immutable documentation mandates or if paper-based audit trails regain acceptance. Forecasts reflect assumptions around Mercosur regulatory convergence timing and ritual slaughter practitioner pool expansion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Disposable Non Woven Sponge Market
Others
Europe Battery Packaging Market
Others
Europe Flow Battery Market
Others
ASEAN Agricultural Logistics Market
Others
Agitator Bead Mill Market
Others
Qatar Smartphone Market
Others
Global Wireless Asset Management Market
Others
Middle East Paper Making Machine Market
Others
Inorganic Tin Chemicals Market
Others
Latin America Automotive HVAC Market
Others
UK Automotive LED Lighting Market
Others
Double Card Mobile Phone Market
Others
Global Optical Coordinate Measuring Machine Market
Others
Paraffin Physical Therapy Market
Others
Idaas Market
Others
Handheld Mobile Computers Market