
 Asia Pacific Foodservice Paper Packaging Market | 2026-2036
Asia Pacific Foodservice Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Foodservice Paper Packaging Market Outlook
Aftermarket sustainability services is reconfiguring margin capture across the Asia Pacific foodservice paper packaging value chain. Huhtamaki Group leverages its regional manufacturing footprint to supply coated paper solutions for quick-service chains. Mondi Group anchors its position through kraft paper specialization and backward integration into pulp sourcing. Oji Holdings Corporation competes via high-volume containerboard production serving Japan's dense convenience store network.
Asia Pacific foodservice paper packaging comprises disposable containers, bags, wraps, and napkins engineered from kraft, coated, recycled, or specialty paper grades, typically featuring grease-resistant barriers formed through fluorochemical or bio-based coating processes, designed to safely contain prepared foods during transport and consumption. Containers command the largest volume share as delivery platforms standardize rigid packaging for hot meals, while specialty paper registers the fastest expansion as brands seek compostable alternatives to polyethylene-lined substrates. The wholesale distribution channel sustains the deepest margin pools through direct mill-to-chain contracts that lock in multi-year volume commitments.
China's SAMR enforces GB standards for food contact materials that restrict heavy metal migration and mandate labeling transparency, while India's FSSAI imposes parallel safety certifications on imported paper packaging that shape supplier qualification timelines. Japan's METI promotes bio-based material transitions through its Plastic Resource Circulation Strategy, redirecting R&D investment toward marine-degradable coatings. Stakeholders must weigh regulatory compliance costs against premium positioning in markets where single-use plastic bans are tightening faster than recycling infrastructure can scale.
Market Dynamics
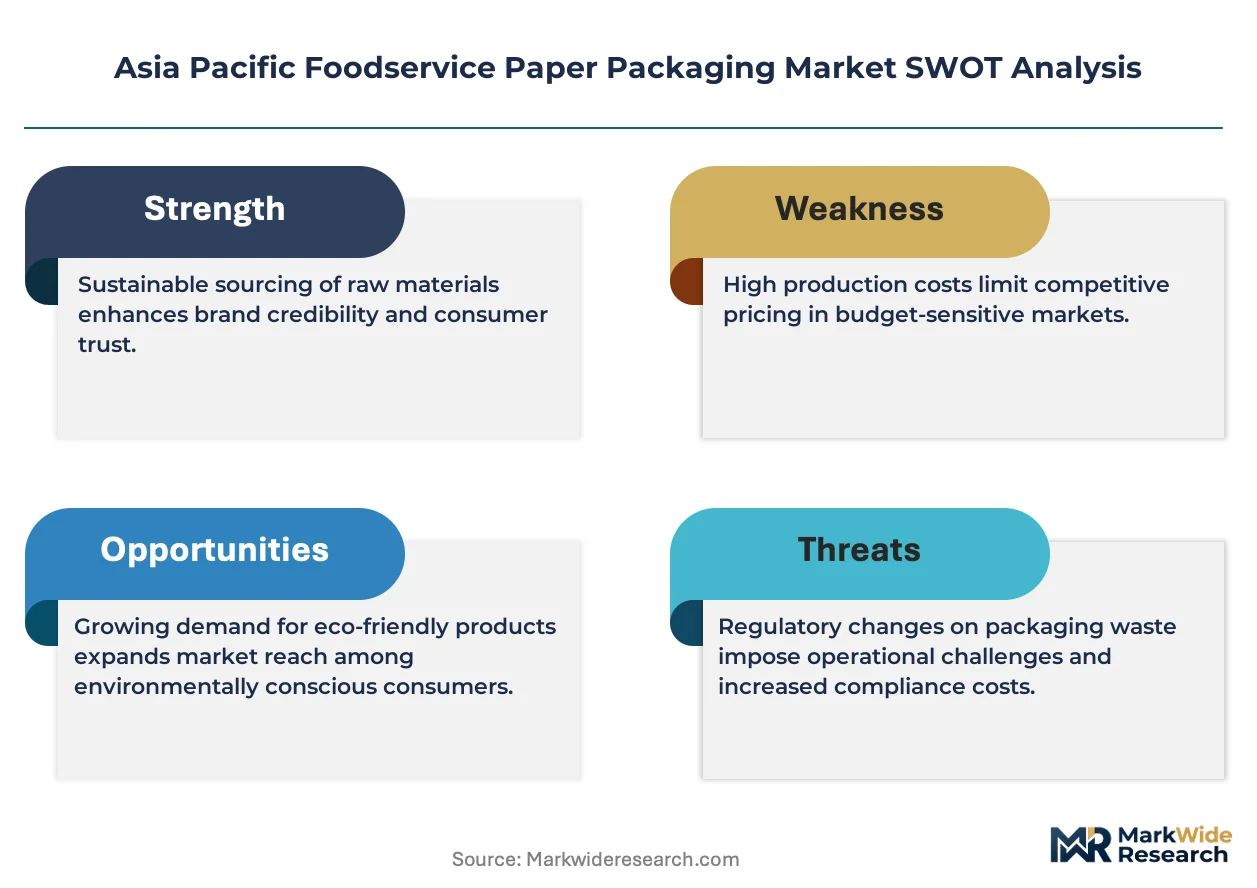
China's GB standards and national plastic restriction policies are accelerating material substitution across quick-service restaurant supply chains, forcing converters to requalify coating chemistries and migrate production lines from polyethylene-lined substrates to bio-based barrier systems.
Growth Catalysts
- Plastic Restriction Mandates:China's SAMR enforces GB standards that restrict single-use plastics in food contact applications, compelling quick-service chains to source paper-based alternatives. This regulatory pressure cascades through Southeast Asian markets as regional governments draft parallel legislation.
- Quick-Service Restaurant Expansion:Southeast Asian quick-service chains are replacing plastic with paper-based solutions at scale, driven by consumer-facing sustainability commitments and delivery platform packaging standardization requirements.
- Urban Delivery Corridor Density:India's urban food delivery corridors concentrate demand for rigid paper containers, with metropolitan logistics networks standardizing packaging formats to optimize thermal retention and stackability.
Market Restraints
- Pulp Input Cost Volatility:Kraft and containerboard grades face price pressure from softwood pulp supply fluctuations, squeezing converter margins when long-term contracts lock in fixed pricing to quick-service chains.
- Coating Chemistry Supply Concentration:Fluorochemical and bio-based barrier coatings remain concentrated among specialty chemical suppliers in East Asia, creating qualification bottlenecks for regional packaging converters.
- Recycling Infrastructure Mismatch:Compostable paper packaging requires industrial composting facilities that remain underdeveloped across South and Southeast Asia, limiting end-of-life value claims.
Strategic Opportunities
- Vietnam and Indonesia Underpenetration:Quick-service restaurant density in Vietnamese and Indonesian secondary cities lags metropolitan benchmarks, creating whitespace for coated paper container suppliers to establish mill-to-chain contracts ahead of competitor lock-in.
- Marine-Degradable Coating Convergence:Japan's METI Plastic Resource Circulation Strategy redirects R&D investment toward marine-degradable coatings, opening technology licensing opportunities for converters serving coastal tourism and island logistics markets.
- Direct Platform Integration:Food delivery platforms are consolidating procurement authority, enabling packaging suppliers to bypass traditional distributor networks and capture margin through direct volume commitments.
Industry Challenges
- Coating Migration Testing Capacity:India's FSSAI mandates parallel safety certifications on imported paper packaging that exceed domestic laboratory throughput, extending supplier qualification timelines by quarters.
- Legacy Equipment Retrofit Costs:Converters face capex intensity from extrusion coating line modifications required to handle water-based bio-barrier chemistries at production speeds matching solvent-based legacy systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Foodservice Paper Packaging Market |
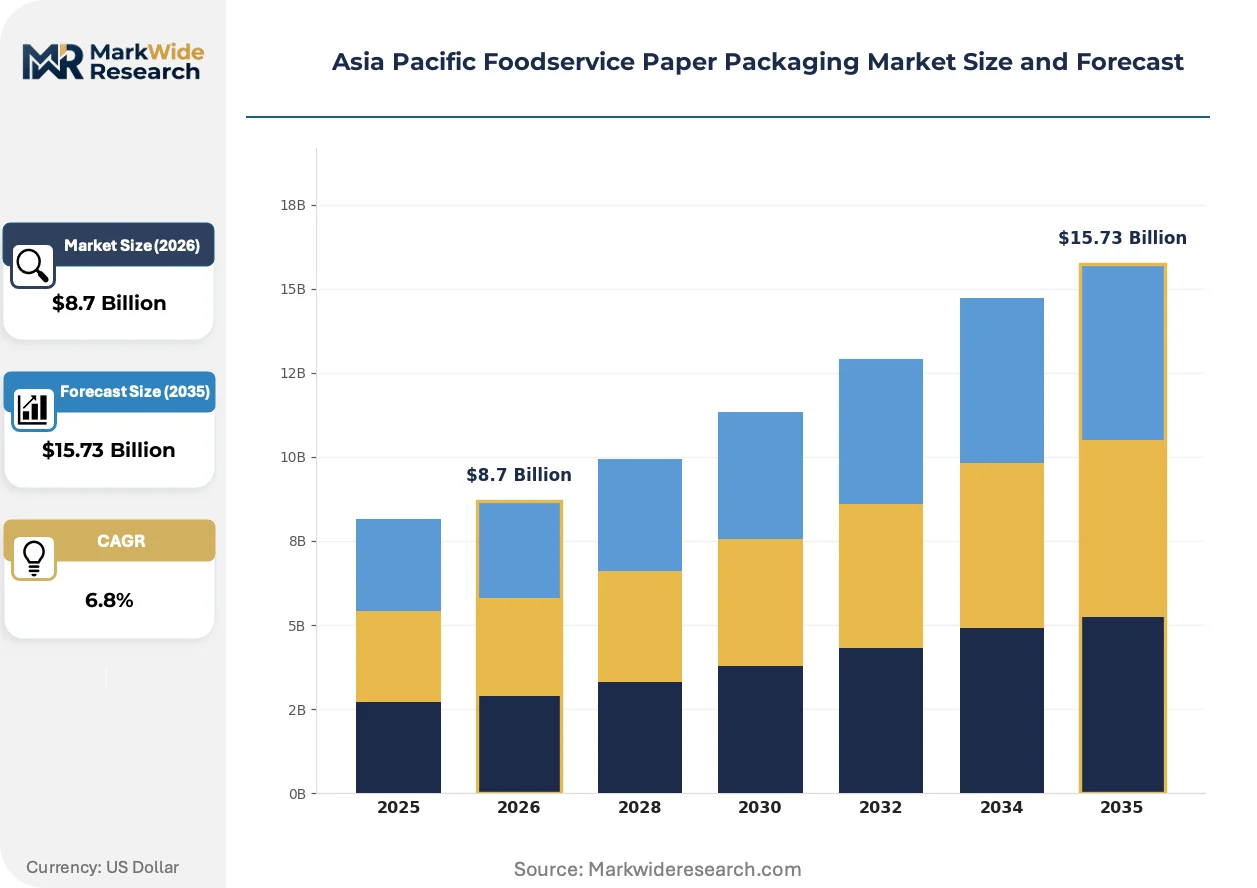
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Bags, Wraps, Napkins End User: Restaurants, Cafés, Food Trucks, Catering Services Material: Kraft Paper, Coated Paper, Recycled Paper, Specialty Paper Distribution Channel: Online, Offline, Wholesale, Retail |
| Companies Covered | SCG Packaging Co. Ltd., International Paper Company, Sarnti Packaging Co. Ltd., Huhtamaki Group, Tetra Pak Group, Amcor PLC, Oji Holdings Corporation, Mondi Group, Graphic Packaging International, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Foodservice Paper Packaging Market Strategic Shifts
Active reshaping in this market centers on coating chemistry transitions, regulatory harmonization pressures, and procurement authority consolidation among food delivery platforms that are standardizing packaging specifications across multi-brand portfolios.
Water-based bio-barrier coatings are migrating from niche specialty applications to mainstream quick-service container production. Major Southeast Asian quick-service chains have accelerated adoption timelines from pilot programs to chain-wide rollout within eighteen-month windows. This technology migration from fluorochemical to plant-derived barriers is compressing the addressable market for legacy polyethylene-lined substrates.
Japan's METI Plastic Resource Circulation Strategy establishes bio-based material transition timelines that redirect converter R&D investment toward marine-degradable formulations. The industrial consequence is a bifurcation in coating supplier qualification, with domestic Japanese converters gaining preferential access to METI-subsidized pilot facilities. Specialty paper grades featuring marine-degradable barriers are capturing premium positioning in Japan's dense convenience store network.
Food delivery platforms are consolidating packaging procurement authority previously dispersed across individual restaurant operators. Direct mill-to-platform contracts are displacing traditional wholesale distributor relationships in India's urban corridors. This concentration is most visible in Mumbai and Bangalore, where platform-standardized container specifications now govern supplier selection criteria.
Asia Pacific Foodservice Paper Packaging Market Segmentation
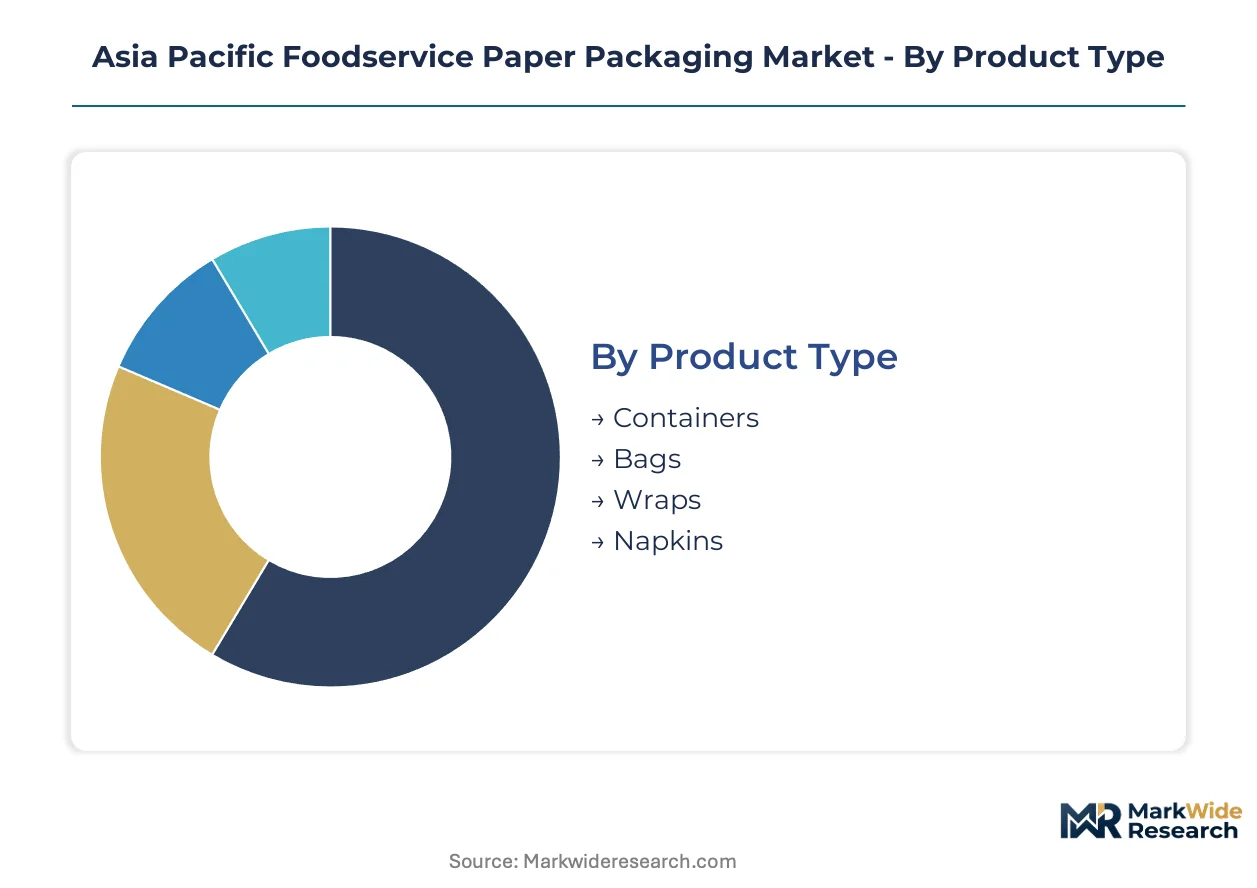
Segmentation in Asia Pacific foodservice paper packaging reveals how coating chemistry investments and delivery platform procurement authority concentrate value capture across distinct product-material combinations. Understanding these divisions exposes where converter margins compress against locked-in chain contracts versus where specialty barriers command premium positioning.
Product Type:
Aftermarket sustainability services intensity varies sharply across product formats, with rigid containers demanding liner retrofit programs and flexible wraps requiring coating requalification support.
- Containers:Rigid paperboard structures with extruded or laminated barrier layers designed for hot meal containment and stackable logistics. Demand concentrates in India's urban delivery corridors where platform-standardized formats optimize thermal retention for aggregator networks.
- Bags:Gusseted or flat configurations with reinforced bottoms for beverage and bulk item transport. Quick-service chains across Southeast Asia are replacing plastic carry bags with kraft alternatives at scale, driven by consumer-facing sustainability mandates.
- Wraps:Flexible sheets with grease-resistant coatings for sandwich and handheld food enclosure. Japan's convenience store network sustains volume through grab-and-go breakfast and lunch applications.
- Napkins:Single-ply to multi-ply tissue products for dining surface protection and hand cleaning. China's quick-service expansion drives bulk procurement through centralized distributor relationships.
By volume, Containers leads. By growth pace, Wraps with compostable barrier coatings is ahead.
End User:
Cost tier stratification separates premium full-service establishments sourcing custom-printed specialty grades from economy-focused operators purchasing standard kraft through wholesale channels.
- Restaurants:Full-service and limited-service dining establishments requiring branded packaging with customized print and barrier specifications. China's GB standards enforcement compels material requalification across mid-tier chains seeking polyethylene-free alternatives.
- Cafés:Beverage-forward outlets demanding cup sleeves, pastry bags, and cold-drink containers with moisture-resistant barriers. India's metropolitan café density in Bangalore and Mumbai sustains specialty coated paper procurement.
- Food Trucks:Mobile operators prioritizing lightweight, stackable containers for constrained preparation spaces. Vietnam's emerging street food formalization drives demand for cost-optimized kraft solutions.
- Catering Services:Event and institutional food providers sourcing bulk-format containers with transport durability. Indonesia's hospitality sector recovery concentrates procurement in Jakarta and Bali corridors.
Restaurants capture the deepest volume pools. Food Trucks is climbing the fastest as mobile formats proliferate across Southeast Asian secondary cities.
Material:
Application requirements dictate material selection, with hot-fill and greasy applications demanding coating performance that unbleached kraft cannot deliver without barrier augmentation.
- Kraft Paper:Unbleached virgin pulp grades prized for structural rigidity and natural aesthetic positioning. Quick-service chains in Thailand and Philippines favor kraft for visible sustainability signaling in consumer-facing packaging.
- Coated Paper:Substrates with extruded polyethylene or bio-based barrier layers enabling grease and moisture resistance. Japan's METI-subsidized pilot facilities accelerate domestic converter access to marine-degradable coating formulations.
- Recycled Paper:Post-consumer fiber grades with FDA and FSSAI-compliant food contact certifications. India's urban delivery platforms increasingly specify recycled content minimums in direct procurement contracts.
- Specialty Paper:Engineered grades including molded fiber, bamboo-based, and agricultural residue alternatives. Coastal tourism markets in Indonesia and Vietnam drive experimentation with marine-degradable substrates.
Kraft Paper dominates procurement tonnage. Specialty Paper gains share fastest as brand sustainability commitments outpace recycling infrastructure development.
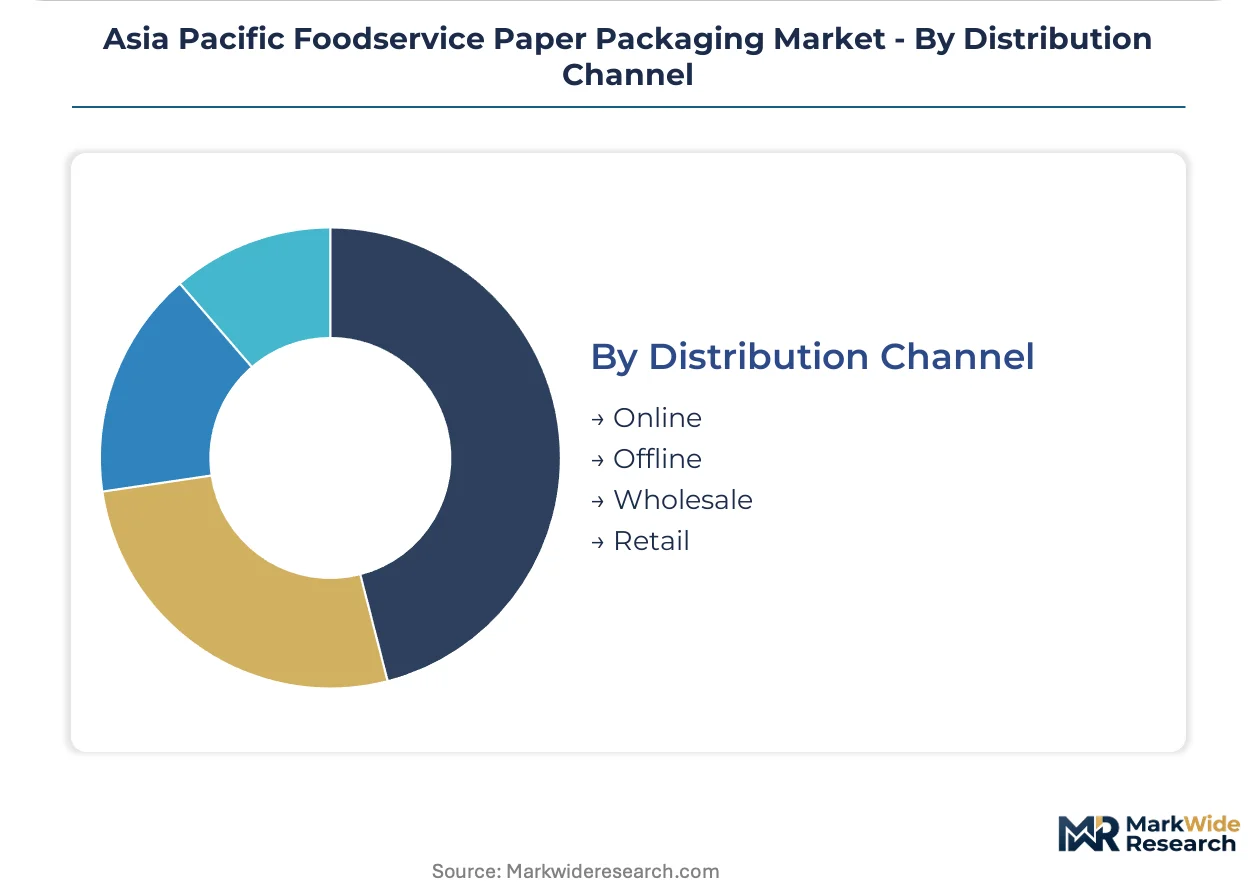
Distribution Channel:
Customer type concentration is restructuring channel economics, with food delivery platforms consolidating procurement authority previously dispersed across individual operator relationships.
- Online:E-commerce platforms and direct-to-operator digital procurement enabling small-batch customization and rapid specification changes. India's Swiggy and Zomato aggregator procurement teams now set packaging standards across thousands of restaurant partners.
- Offline:Traditional distributor relationships with physical inventory holding and route-based delivery. Secondary Indonesian cities retain offline dominance where platform penetration remains incomplete.
- Wholesale:Direct mill-to-chain contracts locking in multi-year volume commitments with fixed pricing. China's largest quick-service chains leverage wholesale scale to hedge pulp input volatility.
- Retail:Consumer-facing packaged goods outlets for home and small office food preparation. Japan's dense convenience store network sustains retail channel relevance for premium napkin and wrap formats.
Wholesale secures the largest contract values. Online is expanding most quickly as platform procurement authority consolidates across India and Southeast Asian metropolitan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the Asia Pacific foodservice paper packaging market. China's regulatory-driven substitution dominates volume, while Japan's premium positioning and India's platform-centralized procurement create distinct margin architectures.
China
Quick-service restaurant chains and delivery platforms drive container demand across tier-one and tier-two cities. SAMR enforces GB standards for food contact materials that restrict polyethylene-lined substrates and mandate labeling transparency. The Yangtze River Delta manufacturing corridor hosts converter clusters requalifying coating chemistries for bio-based barrier systems.
Japan
Dense convenience store networks sustain specialty wrap and napkin consumption through grab-and-go meal applications. METI's Plastic Resource Circulation Strategy subsidizes pilot facilities for marine-degradable coating development. The Kanto region around Tokyo concentrates domestic converter R&D investment toward bio-based material transitions.
India
Urban food delivery corridors in Mumbai and Bangalore concentrate rigid container demand as Swiggy and Zomato standardize packaging specifications. FSSAI imposes parallel safety certifications on imported paper packaging that extend supplier qualification timelines. Metropolitan logistics networks optimize thermal retention through platform-mandated container formats.
Vietnam
Quick-service restaurant density in Ho Chi Minh City and Hanoi lags regional benchmarks, creating whitespace for coated paper container suppliers. Street food formalization drives demand for cost-optimized kraft solutions in emerging urban centers. Secondary cities retain offline distribution dominance where platform penetration remains incomplete.
Indonesia
Hospitality sector recovery in Jakarta and Bali corridors concentrates catering procurement for bulk-format containers. National plastic restriction policies cascade from regional legislative templates, accelerating material substitution timelines. Coastal tourism markets in Bali drive experimentation with marine-degradable specialty substrates.
Asia Pacific Foodservice Paper Packaging Market Competitive Environment
Capability concentration sits with specialty coating developers; scale advantage sits with high-volume containerboard producers. The vendor base separates into three tiers: multinational integrated paper groups with captive pulp supply, regional converters serving quick-service chain contracts, and specialty chemical developers controlling barrier formulation IP. Dominant competitive moves include backward integration into pulp sourcing and direct mill-to-platform procurement relationships that bypass traditional distributor networks.
Among Asia Pacific-based integrated paper groups, Oji Holdings Corporation and SCG Packaging Co. Ltd. occupy positions emphasizing high-volume production scale. Mondi Group and Huhtamaki Group exemplify the multinational converter archetype with regional manufacturing footprints and direct chain relationships. These named entities anchor the competitive structure without exhausting the participant pool.
| Leading Market Players |
|---|
| SCG Packaging Co. Ltd. |
| International Paper Company |
| Sarnti Packaging Co. Ltd. |
| Huhtamaki Group |
| Tetra Pak Group |
| Amcor PLC |
| Oji Holdings Corporation |
| Mondi Group |
| Graphic Packaging International |
| Others |
Value Chain & Pricing Dynamics
Softwood pulp supply concentration in Southeast Asian plantation networks feeds directly into margin capture at the converter tier, where long-term mill-to-chain contracts lock in fixed pricing that insulates quick-service operators from raw material volatility while squeezing intermediary distributors.
Pricing Analysis
Long-term offtake contracts dominate procurement between major quick-service chains and integrated paper groups, with pricing stratifying across premium marine-degradable coatings, standard polyethylene-free barriers, and economy kraft grades. Price differentiation hinges on certification tier—FSSAI-compliant imports command premiums over domestic alternatives—and volume scale, with platform-direct agreements securing deepest discounts. Cost compression in the economy tier is intensifying as recycled fiber minimums become mandatory in Indian aggregator contracts. Small-format food trucks exhibit highest price sensitivity, while Japan's convenience store networks tolerate premium positioning for METI-subsidized bio-barrier formulations.
Supply Chain Analysis
Softwood pulp plantations in Indonesia, Malaysia, and Thailand anchor upstream feedstock availability for regional containerboard production. Coated paper converters draw from specialty chemical suppliers concentrated in East Asia for fluorochemical and bio-based barrier formulations. Single-source vulnerability around marine-degradable coating IP creates qualification bottlenecks for secondary-market entrants. Distribution runs through platform-procurement consolidation in Indian metropolitan corridors, with wholesale mill-to-chain relationships retaining dominance in Chinese tier-one and tier-two city networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping procurement authority in Asia Pacific foodservice packaging, as delivery aggregator standardization creates interoperability requirements that favor suppliers capable of direct volume commitments across multi-brand portfolios.
For Market Incumbents: Entrench platform-direct relationships before competitor lock-in solidifies, particularly in Indian urban delivery corridors where Swiggy and Zomato procurement teams consolidate specifications. Secure backward integration into pulp sourcing to hedge against Southeast Asian plantation supply disruptions. Prioritize FSSAI certification investment to preempt qualification timeline extensions that favor domestic competitors.
For New Entrants and Emerging Players: Build out coating chemistry capabilities targeting marine-degradable formulations, where Japanese METI subsidies have created technology licensing opportunities for coastal tourism markets in Indonesia and Vietnam. Target Vietnamese and Indonesian secondary cities where quick-service restaurant density lags metropolitan benchmarks and platform penetration remains incomplete. Pursue mill-to-chain contracts ahead of wholesale distributor consolidation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across specialty coating development, as water-based bio-barrier R&D requires pilot facility investment matching solvent-based legacy system throughput. Five-to-ten year viability favors converters with captive pulp supply and direct platform integration capabilities. Watch for FSSAI laboratory capacity expansion as signal that import qualification timelines may compress, altering competitive dynamics for foreign suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Sourcing | Captive softwood supply from Southeast Asian plantations hedges against price volatility in kraft and containerboard grades. |
| Direct Platform Procurement Relationships | Bypassing wholesale distributors captures margin through multi-year volume commitments with Swiggy and Zomato aggregator networks. |
| Marine-Degradable Coating Development | METI-subsidized pilot facility access positions Japanese converters for premium pricing in coastal tourism markets. |
| FSSAI Certification Pre-Qualification | Early investment in Indian food safety compliance shortens supplier onboarding timelines against import certification backlogs. |
| Secondary City Mill-to-Chain Contracts | Establishing coated paper container supply ahead of platform penetration locks in Vietnamese and Indonesian whitespace markets. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with quick-service chain procurement directors, packaging converter plant managers, food delivery platform supply chain leads, and specialty chemical R&D directors. Secondary validation drew from SAMR GB standards documentation, FSSAI food contact material certifications, METI Plastic Resource Circulation Strategy publications, and customs trade data for pulp and containerboard flows. Bottom-up volume modeling triangulated against top-down market sizing across coating chemistry transitions and platform procurement consolidation trends.
Calibration against historical substitution patterns in polyethylene-to-paper transitions anchored growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include product format, material grade tier, end-user category, distribution channel type, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating urban delivery corridor density metrics and quick-service restaurant expansion rates. Forecast inputs included pulp futures pricing volatility bands and laboratory certification throughput capacity for coating migration testing.
Sensitivities concentrate around FSSAI import certification timeline compression, METI subsidy program continuity for marine-degradable development, and platform procurement authority consolidation pace in Southeast Asian secondary cities. Forecasts embed assumptions about regulatory enforcement intensity and recycling infrastructure deployment that may require revision if national plastic restriction policies accelerate faster than industrial composting facility construction. Cross-checking against pulp futures market implied volatility and regional quick-service chain capex disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Bitcoin Mining Servers Market
Others
Astrology Market
Others
Europe Smart Homes Market
Others
Global Cigarette Packaging Market
Others
Advanced Combat Helmet Market
Others
Canada Feed Additives Market
Others
Dry Washer Market
Others
Buchner Funnels Market
Others
Cremation Furnace Market
Others
Connected Living Room Market
Others
Smart Home Controller Market
Others
Binoculars and Mounting Solutions Market
Others
Smart TV Platforms Market
Others
Stand-Up Pouch Valves Market
Others
Sprockets Market
Others
Sandbags Market