
 Printed Leather Market | 2026-2036
Printed Leather Market Size, Share, and Industry Trends Forecast 2026-2036
Printed Leather Market Outlook
Aftermarket refurbishment and pattern re-licensing is reshaping margin distribution across the printed leather value chain. Epson leverages its precision inkjet architecture to dominate high-resolution textile applications. Kuraray Co. Ltd. anchors synthetic substrate supply for automotive-grade printed surfaces. Agfa-Gevaert Group competes through UV-curable ink systems that reduce volatile compound emissions during curing.
Printed leather denotes hide or collagen-based substrates that receive pigmented, metallic, or photorealistic surface decoration through mechanical or digital transfer methods, typically achieving resolution thresholds of 600–1200 dpi in industrial configurations and serving aesthetic customization across fashion, mobility, and interior environments. Synthetic leather commands the broadest addressable volume base due to cost scalability and batch consistency, while genuine leather retains premium positioning where grain-specific printing and hand-finished patina justify unit economics. Digital printing technology leads growth velocity among process categories, displacing rotary systems in short-run luxury workflows where design turnover cycles compress below six weeks.
REACH restrictions on chromium VI compounds and ECHA classification of certain azo dyes are forcing tanneries toward water-based pigment systems and pre-tanned substrate certification. The EPA monitors perfluorinated compound discharge from coating facilities under Clean Water Act provisions, particularly affecting Michigan and Tennessee production zones. Stakeholders must monitor evolving chemical substitution timelines and pre-qualify alternative binder chemistries before regulatory phase-ins disrupt existing print formulations.
Market Dynamics
Digital inkjet printing is migrating from rotary screen systems across luxury fashion workflows, compressing design-to-production cycles below six weeks while forcing tanneries to retool for water-based pigment compatibility. This technological pivot restructures capital allocation across the value chain.
Growth Catalysts
- REACH chromium VI restrictions:European tanneries accelerate water-based pigment adoption, creating certified substrate demand that premium brands leverage for ESG positioning.
- Short-run luxury workflows:Fashion houses require sub-six-week design turnover, pulling digital print capacity expansion in Italy's Arzignano cluster.
- Automotive interior customization:OEM specification of printed leather for dashboard and seating surfaces drives synthetic substrate volume in tier-one supply chains.
Market Restraints
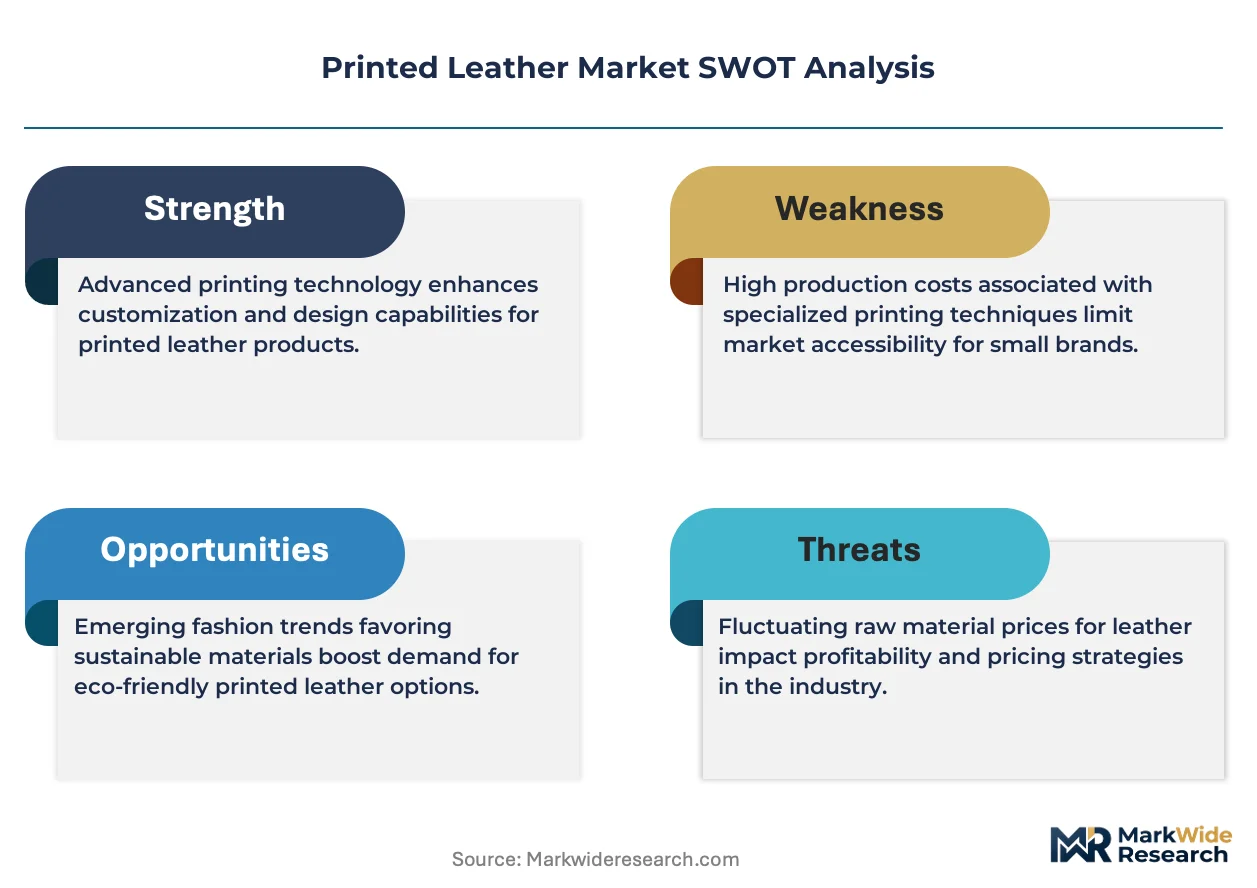
- Hide supply concentration:Premium calfskin availability tightens around French and Italian tanneries, constraining batch consistency for photorealistic print applications.
- Water-based pigment curing limitations:Extended drying cycles reduce throughput versus solvent-based systems, limiting cost competitiveness at industrial scale.
- Perfluorinated compound discharge monitoring:EPA Clean Water Act provisions in Michigan and Tennessee production zones impose treatment capex on coating facilities.
Strategic Opportunities
- Aftermarket pattern re-licensing:Archive designs from luxury houses generate recurring revenue streams through authenticated refurbishment services.
- UV-curable ink convergence:Reduced volatile compound emissions during curing align with EU Green Deal procurement criteria for public interior projects.
- India contract manufacturing:PLI scheme incentives for leather goods attract digital print infrastructure investment serving export markets.
Industry Challenges
- Artisanal print technician scarcity:Hand-finished patina specialization concentrates in aging workforce pools across Italian artisanal houses.
- Pre-tanned substrate certification timelines:ECHA azo dye classification updates disrupt existing formulation pipelines before alternative binder qualification completes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printed Leather Market |
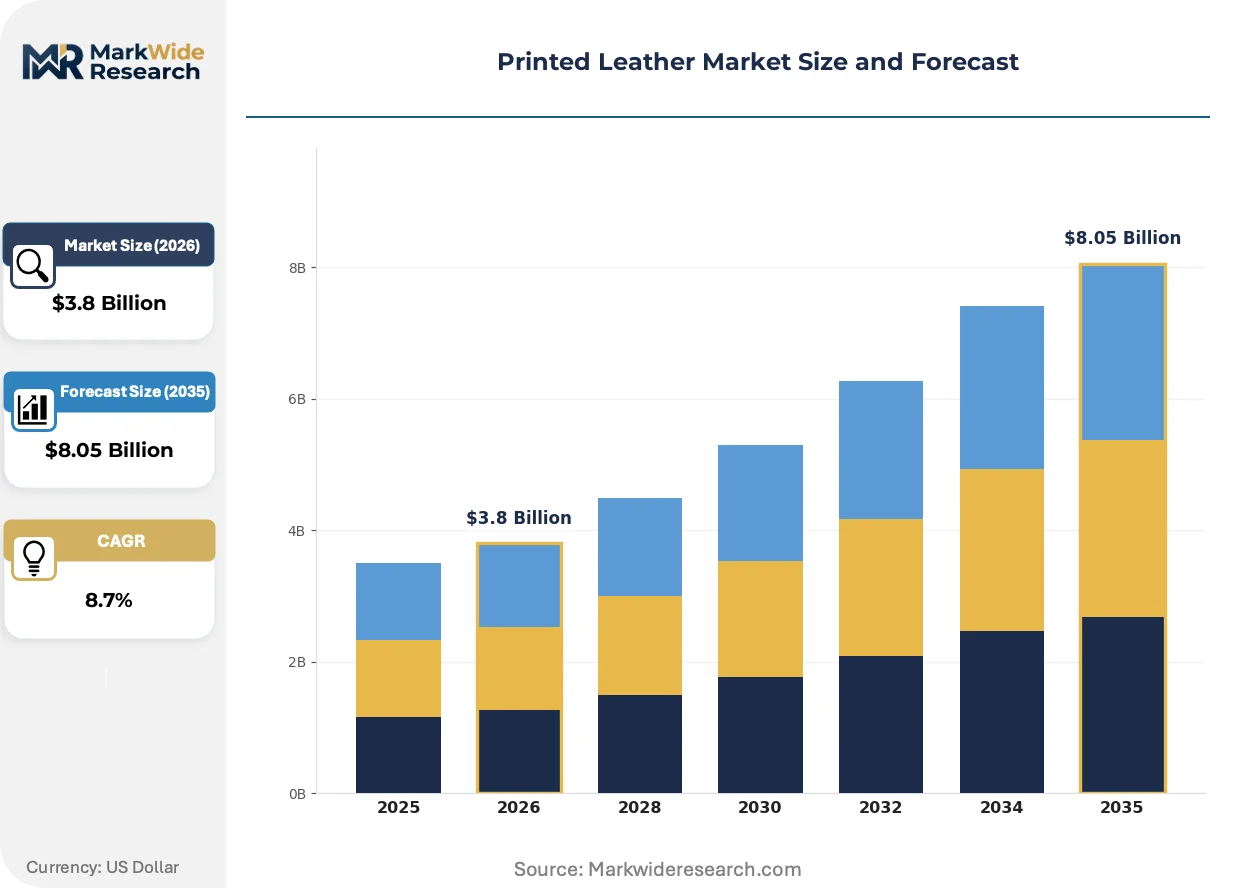
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genuine Leather, Synthetic Leather, Recycled Leather, Faux Leather Application: Footwear, Handbags, Automotive Interiors, Upholstery End User: Fashion Brands, Automotive Manufacturers, Furniture Retailers, Designers Technology: Digital Printing, Screen Printing, Rotary Printing, Hot Stamping |
| Companies Covered | Epson, Agfa-Gevaert Group, Kuraray Co. Ltd., Leather Hunte, CMYKing, Zünd, ISA TanTec, Hyphen Concord GmbH, Bags of Love, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printed Leather Market Strategic Shifts
Surface decoration technology is fragmenting across resolution tiers and curing chemistries, with regulatory pressure on volatile compounds accelerating hardware refresh cycles. Print houses now compete on certification breadth rather than equipment scale alone.
Single-pass inkjet architectures are migrating from multi-pass scanning systems in high-throughline tanneries serving automotive and contract furniture segments. Tier-one suppliers in Germany and Japan adopt these systems to maintain batch-to-batch color consistency across 1000-meter-plus production runs. The technology compresses capital recovery timelines while displacing rotary screen maintenance overhead.
EU F-Gas Regulation phase-down mandates are forcing solvent recovery system upgrades across coating facilities serving printed leather finishing. Industrial consequence includes accelerated water-based and UV-curable ink qualification programs. Italian and Spanish tanneries face the steepest compliance curves given their concentration of chrome-tanned substrate finishing.
Luxury brand procurement teams now specify blockchain-traceable hide sourcing alongside print resolution thresholds, unbundling quality assurance from traditional tannery relationships. Direct brand-to-print-house contracting fragments the historical merchant intermediary role. This pattern concentrates in French and Italian fashion houses with controlled distribution networks.
Printed Leather Market Segmentation
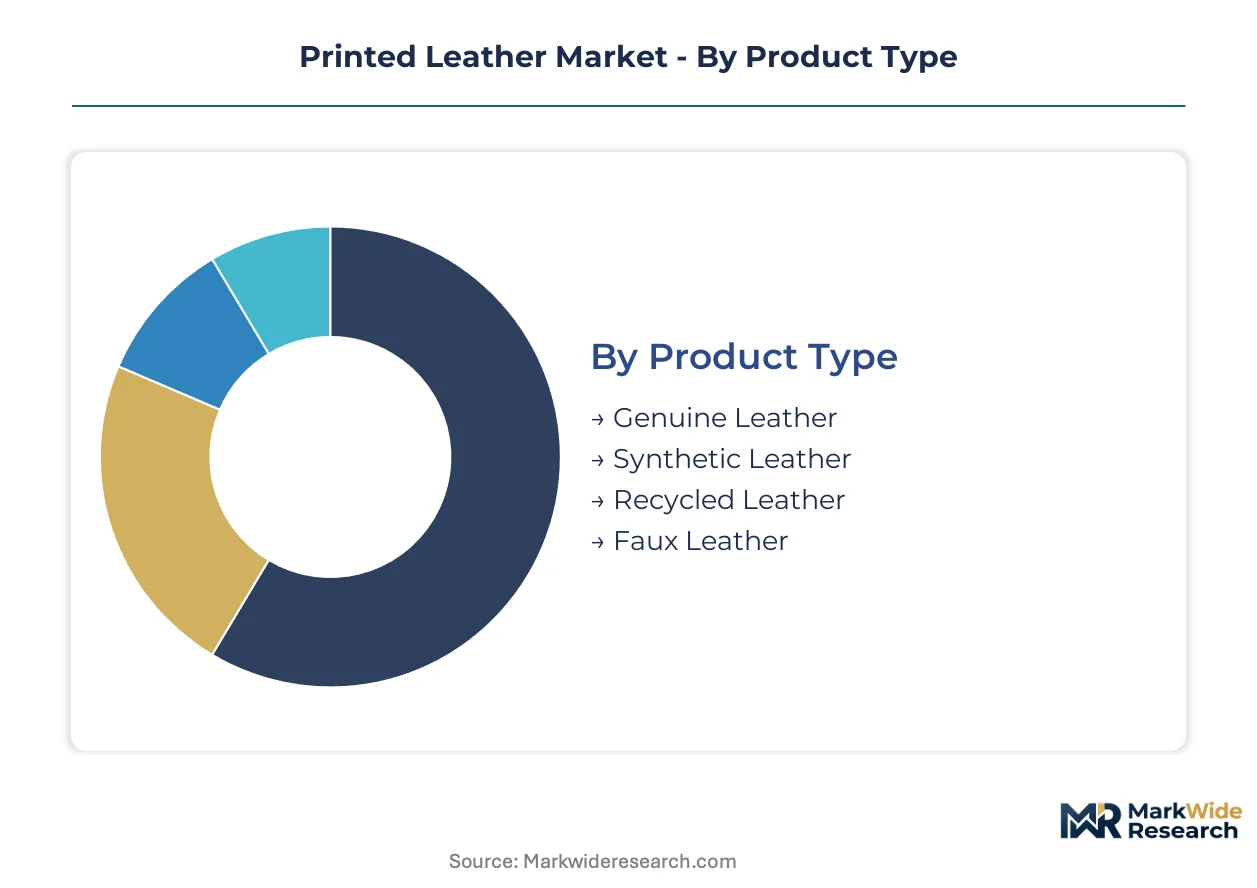
Segmentation in printed leather reveals divergent production economics across material grades and print technologies. Genuine leather commands extended batch cycles while synthetic substrates enable rapid design turnover, reshaping capital allocation across tanneries and print houses.
Product Type:
Cycle times stretch from hours for synthetic rolls to weeks for vegetable-tanned hides awaiting hand-finished patina, creating distinct inventory risk profiles across material tiers.
- Genuine Leather:Full-grain and top-grain hides receive surface decoration through pigment or aniline systems, with grain-specific printing requiring individual hide inspection. Italian tanneries in the Arzignano cluster dominate premium calfskin supply for French luxury houses, constrained by tight hide availability and extended curing protocols.
- Synthetic Leather:Polyurethane and polyvinyl chloride substrates achieve batch consistency across kilometer-scale production runs, enabling photorealistic print replication at industrial throughput. Kuraray Co. Ltd. anchors automotive-grade synthetic supply for tier-one seating manufacturers, driven by OEM specification of customizable dashboard surfaces.
- Recycled Leather:Reconstituted collagen fibers from leather scrap create lower-cost substrates suitable for accessory applications.
- Faux Leather:Entirely non-collagen alternatives serve vegan positioning requirements in fashion and furniture segments.
Synthetic leather anchors the volume base while genuine leather gains share at the steepest rate among premium positioning strategies.
Application:
Cost tiers separate commodity footwear from bespoke automotive interiors, with specification intensity determining margin capture across the value chain.
- Automotive Interiors:Dashboard, seating, and door panel applications demand fade-resistant pigments meeting OEM durability testing. German and Japanese tier-one suppliers specify single-pass inkjet systems for 1000-meter-plus production runs, compressing capital recovery timelines while displacing rotary screen maintenance.
- Handbags:Small leather goods require sub-six-week design turnover cycles, pulling digital print capacity expansion in Italy's artisanal print houses. Archive pattern re-licensing from luxury houses generates recurring revenue streams through authenticated refurbishment services.
- Footwear:High-volume production favors screen and rotary systems for consistent repeat patterns across thousands of units.
- Upholstery:Contract furniture and residential applications balance durability requirements with aesthetic customization breadth.
Footwear maintains the broadest installed equipment base while automotive interiors expand most quickly on OEM specification pull.
End User:
Customer type determines procurement sophistication, with controlled distribution networks demanding blockchain-traceable hide sourcing alongside print resolution thresholds.
- Fashion Brands:Luxury houses with direct-to-print-house contracting fragment traditional merchant intermediary roles, unbundling quality assurance from conventional tannery relationships. French and Italian labels specify REACH-compliant water-based pigments for ESG positioning in European markets.
- Automotive Manufacturers:OEM technical specifications drive synthetic substrate volume through tier-one supply chains, with color consistency requirements across 1000-meter-plus runs favoring single-pass inkjet adoption.
- Furniture Retailers:Contract and residential segments prioritize cost scalability over grain-specific customization.
- Designers:Independent creators access short-run digital print services for limited-edition collections and prototype development.
Fashion brands concentrate specification authority while automotive manufacturers drive standardization at the steepest volume trajectory.
Technology:
Process maturity separates established rotary systems from emerging digital architectures, with regulatory pressure on volatile compounds accelerating hardware refresh cycles.
- Digital Printing:Inkjet systems achieve 600–1200 dpi resolution thresholds with design-to-production cycles compressing below six weeks. Epson leverages precision inkjet architecture to dominate high-resolution textile applications, while water-based pigment compatibility requirements force tannery retooling.
- UV-Curable Ink Systems:Agfa-Gevaert Group competes through reduced volatile compound emissions during curing, aligning with EU Green Deal procurement criteria for public interior projects.
- Screen Printing:Established mesh-based systems maintain cost competitiveness for long-run commodity applications.
- Rotary Printing:Cylindrical screen systems face displacement in short-run luxury workflows but persist in high-volume footwear and upholstery segments.
- Hot Stamping:Foil transfer methods serve metallic and holographic effects in accessory applications.
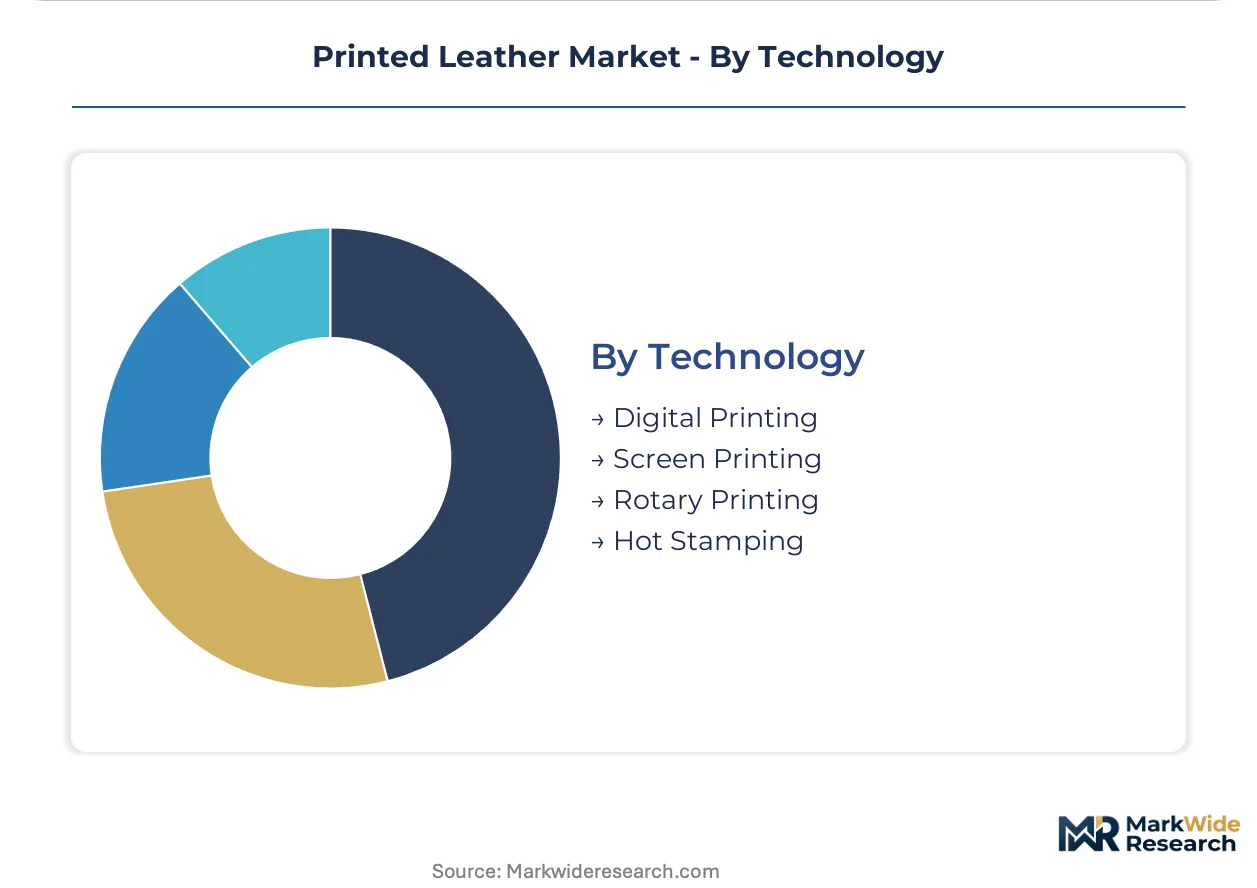
Rotary printing retains the largest installed base while digital printing climbs the fastest on luxury workflow migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and China demonstrate acute price sensitivity toward synthetic substrates, while French and Italian luxury houses absorb premium calfskin costs with minimal demand elasticity. This bifurcation shapes regional production strategies and regulatory compliance investments.
Italy
French luxury brands source premium calfskin through direct-to-print-house contracts, bypassing traditional merchant intermediaries. REACH chromium VI restrictions accelerate water-based pigment adoption across tanneries. The Arzignano tanning cluster concentrates artisanal print capacity serving sub-six-week design turnover cycles.
United States
Automotive OEMs specify printed leather for dashboard and seating surfaces, pulling synthetic substrate volume through tier-one supply chains. EPA Clean Water Act provisions in Michigan and Tennessee impose treatment capex on coating facilities monitoring perfluorinated compound discharge. Detroit-area automotive suppliers adopt single-pass inkjet systems for 1000-meter-plus production runs.
Germany
Tier-one automotive suppliers demand fade-resistant pigments meeting OEM durability testing protocols. EU F-Gas Regulation phase-down mandates force solvent recovery system upgrades across coating facilities. Bavarian industrial zones concentrate UV-curable ink qualification programs aligning with EU Green Deal procurement criteria.
India
Export-oriented contract manufacturers leverage PLI scheme incentives for leather goods to attract digital print infrastructure investment. BIS standards and DGFT export protocols govern chemical disclosure for tanning and printing processes. Tamil Nadu and Uttar Pradesh clusters expand capacity serving European and North American fashion brands.
China
Domestic automotive brands specify customizable printed surfaces for electric vehicle interiors, driving synthetic substrate demand. MIIT regulations and dual carbon goals pressure coating facilities toward water-based systems. Guangdong and Zhejiang provinces concentrate high-volume production for footwear and upholstery segments.
Printed Leather Market Competitive Environment
Capability concentration sits with precision inkjet and UV-curable ink specialists; scale advantage sits with synthetic substrate manufacturers and multi-process print houses. The market structures around three tiers: technology licensors dominating resolution thresholds, substrate suppliers anchoring automotive-grade volume, and regional print houses serving short-run luxury workflows. Dominant competitive moves include strategic partnerships between ink system developers and tannery equipment retrofitters, plus geographic expansion of certified substrate pre-tanning capacity.
Among technology-focused developers, Epson and Agfa-Gevaert Group exemplify divergent approaches to emission reduction and resolution performance. Epson occupies a position within precision inkjet architecture for high-resolution textile and leather applications. Agfa-Gevaert Group represents the UV-curable ink system archetype, with reduced volatile compound emissions during curing. Kuraray Co. Ltd. anchors synthetic substrate supply for automotive and industrial printed surface specifications.
| Leading Market Players |
|---|
| Epson |
| Agfa-Gevaert Group |
| Kuraray Co. Ltd. |
| Leather Hunte |
| CMYKing |
| Zünd |
| ISA TanTec |
| Hyphen Concord GmbH |
| Bags of Love |
| Others |
Value Chain & Pricing Dynamics
Arzignano's tanning cluster concentration in Italy funnels premium calfskin through a narrow supplier base, concentrating margin capture with French luxury houses that absorb elevated input costs with minimal demand elasticity. This upstream bottleneck shapes downstream pricing power across genuine leather tiers while synthetic substrate producers compete on batch consistency at industrial scale.
Pricing Analysis
Aftermarket pattern re-licensing and authenticated refurbishment services generate recurring lifetime value streams that reshape margin distribution across the value chain. Three-tier pricing structure across premium, standard, and economy levels separates grain-specific hand-finished patina from photorealistic digital prints and commodity rotary-screen outputs. Cost compression in synthetic substrates intensifies as Kuraray and competing substrate manufacturers scale polyurethane and PVC production for automotive OEM specifications. Price sensitivity concentrates among Indian and Chinese contract manufacturers serving export footwear and upholstery segments, while Italian artisanal print houses serving French luxury brands exhibit minimal elasticity.
Supply Chain Analysis
Export-control scrutiny on precision inkjet printheads and UV-curable ink formulations limits technology transfer to emerging print houses in India and China. Geographic supply concentration centers on Italy for premium calfskin finishing, Germany and Japan for tier-one automotive synthetic substrates, and China's Guangdong and Zhejiang provinces for high-volume footwear production. Raw material dependencies include chromium-tanned hides, water-based pigment systems, and perfluorinated coating chemistries. Single-source vulnerability sits with Epson's dominance in high-resolution inkjet architectures for sub-six-week luxury workflows. Distribution runs through direct brand-to-print-house contracting that fragments traditional merchant intermediary roles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chromium VI restrictions and EPA perfluorinated compound monitoring are forcing chemical substitution timelines that favor pre-qualified water-based and UV-curable ink systems. This regulatory inflection compresses competitive windows for tanneries still running solvent-based finishing lines.
For Market Incumbents: Pre-empt regulatory disruption by accelerating ECHA-compliant pre-tanned substrate certification ahead of azo dye classification phase-ins. Lock in direct-to-brand contracting with French and Italian luxury houses before blockchain-traceable sourcing requirements harden into procurement mandates. Capture artisanal print technician talent pools through apprenticeship programs addressing aging workforce concentration in Italian houses.
For New Entrants and Emerging Players: Build out digital print capacity in India's Tamil Nadu and Uttar Pradesh clusters, leveraging PLI scheme incentives to serve European and North American fashion brand export demand. Target short-run luxury workflows where sub-six-week design turnover cycles outpace incumbent rotary-screen retooling. Establish go-to-market positioning through authenticated archive pattern re-licensing partnerships with heritage luxury houses.
For Investors and Strategic Acquirers: Capital is best deployed toward UV-curable ink system developers and certified pre-tanning facilities aligned with EU Green Deal procurement criteria. Long-term viability over the next decade hinges on emission-reduction compliance breadth rather than equipment scale alone. Monitor ECHA binder chemistry substitution timelines as the critical inflection signal for formulation pipeline disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Pigment System Qualification | REACH compliance positions tanneries for ESG-driven luxury brand procurement. |
| Single-Pass Inkjet Capacity Expansion | German and Japanese tier-one suppliers achieve color consistency across 1000-meter-plus runs. |
| Blockchain-Traceable Hide Sourcing | French luxury houses unbundle quality assurance from traditional merchant relationships. |
| Artisanal Print Technician Apprenticeship Programs | Italian houses address aging workforce scarcity in hand-finished patina specialization. |
| UV-Curable Ink Convergence | Agfa-Gevaert emission profiles align with EU Green Deal public interior project criteria. |
Study Parameters
Cross-validation between primary interviews with tanning executives, print house technical directors, luxury brand procurement leads, and automotive tier-one supplier engineers anchors the qualitative findings against secondary sources including REACH regulatory filings, EPA Clean Water Act discharge monitoring data, SEC filings from ink system developers, and Italian tannery association production statistics. Bottom-up capacity assessments across the Arzignano cluster triangulate with top-down market sizing across synthetic substrate manufacturers.
Calibration against historical adoption curves for digital inkjet displacement of rotary systems informs the projection framework across the analysis window. Segmentation dimensions include material grade, print technology resolution tier, application durability specification, and regional regulatory compliance cluster. CAGRs derive from installed base migration rates and capital expenditure patterns across tannery equipment retrofit cycles. Industry-specific inputs capture OEM automotive interior specification timelines and luxury fashion house design turnover compression.
Stress conditions across hide supply availability, ECHA chemical classification timelines, and EPA enforcement intensity in Michigan and Tennessee production zones were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory phase-in schedules and technology adoption elasticities. Material shifts in EU F-Gas Regulation enforcement or single-pass inkjet cost curves would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Underwater Lighting Market
Others
US Cat Food Market
Others
Snus Market
Others
Coconut Activated Carbon Market
Others
Molecular Spectroscopy Market
Others
Edible Insects for Animal Feed Market
Others
Pediatric Measuring Devices Market
Others
Australia Content Services Platform Market
Others
Asia-Pacific Adtech Market
Others
Gym Wipes Market
Others
Global Cryogenic Tanks Market
Others
Wearable AI Market
Others
Mobile Computer Market
Others
Shisha Tobacco Market
Others
Asia Pacific Automotive LED Lighting Market
Others
Global Bio-Based Chemicals Market