
 Global Video Processing Platform Market | 2026-2036
Global Video Processing Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Video Processing Platform Market Foresight
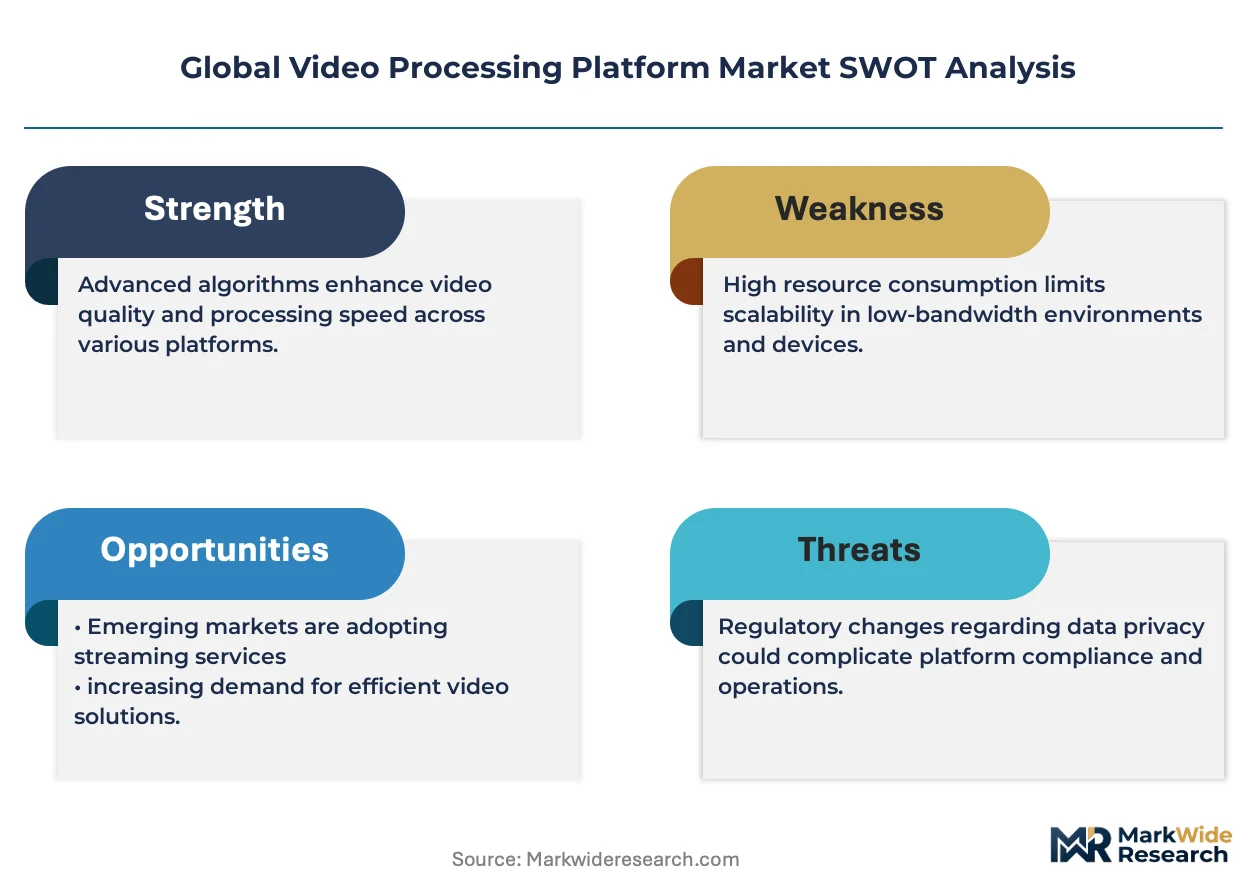
The gap between premium broadcast-grade processing and commodity cloud transcoding is realigning competitive strategy across the industry. Akamai Technologies leverages its edge-computing footprint to sustain low-latency delivery contracts with Tier-1 broadcasters. Harmonic specializes in converged cable and streaming infrastructure, while Amagi dominates cloud-native channel origination for FAST platforms.
A video processing platform is an integrated software-hardware system that ingests, transcodes, encrypts, and distributes video streams across multiple formats and bitrates, typically handling H.264, HEVC, and AV1 codecs with sub-200-millisecond latency targets for live applications. Its primary commercial purpose is to enable scalable, format-agnostic video delivery to heterogeneous endpoint devices while minimizing bandwidth expenditure. Cloud-based deployments are capturing the fastest expansion as media houses abandon capital-intensive on-premises infrastructure, though hybrid architectures retain strong positioning where content security mandates local encryption handling. AI-powered analytics represents the highest-margin technology segment, with real-time streaming compression commanding premium pricing in live sports and wagering applications.
The FCC enforces closed-captioning and emergency-alert standards that shape platform accessibility requirements in the United States, while the EU AI Act imposes risk-classification obligations on automated content recognition systems deployed across European broadcast networks. Japan's METI promotes 8K broadcasting standards that drive processing hardware refresh cycles among equipment vendors. Stakeholders must weigh regulatory compliance costs against localization advantages when selecting processing architecture for multi-territory deployments.
Market Dynamics
AI-powered compression algorithms are compressing latency budgets and displacing hardware-bound transcoding architectures across broadcast and streaming workflows.
Growth Catalysts
- EU AI Act compliance mandates:Automated content moderation systems in European broadcast networks must meet algorithmic transparency standards, forcing infrastructure upgrades that expand platform vendor addressable spend.
- Live sports wagering:Sub-200-millisecond latency requirements for real-time betting synchronization are driving premium processing contracts in the United States and South Korea.
- HEVC-to-AV1 codec migration:Royalty-free encoding standards are absorbing capital from patent-encumbered alternatives, reducing per-stream processing costs for OTT aggregators.
Market Restraints
- GPU supply concentration:Taiwan-based foundry capacity constraints limit real-time AI inference hardware availability for edge deployment.
- 8K broadcast hardware refresh cycles:Japan's METI standards mandate costly encoder replacements with limited content library compatibility.
- Cloud egress bandwidth pricing:Hyperscale providers in Germany and the United States impose egress fees that erode margin on high-bitrate live streams.
Strategic Opportunities
- FAST platform origination:Cloud-native channel creation for advertising-supported streaming remains underpenetrated in Brazil and Southeast Asian markets.
- Converged cable-streaming infrastructure:Hybrid QAM/IP architectures enable single-vendor consolidation for North American cable operators facing fiber competition.
- ISO/IEC 23009-5 compliance services:MPEG-DASH server-side ad insertion standards create certification-driven consulting revenue for platform vendors.
Industry Challenges
- Real-time ML engineering talent:Scarce expertise in neural video compression model optimization constrains R&D velocity across vendors.
- Multi-codec certification timelines:Device compatibility testing for H.264, HEVC, AV1, and VVC simultaneous support extends platform validation cycles.
- Legacy SDI integration:Hybrid environments require maintaining parallel baseband and IP signal paths, complicating operational workflows for broadcast engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Video Processing Platform Market |
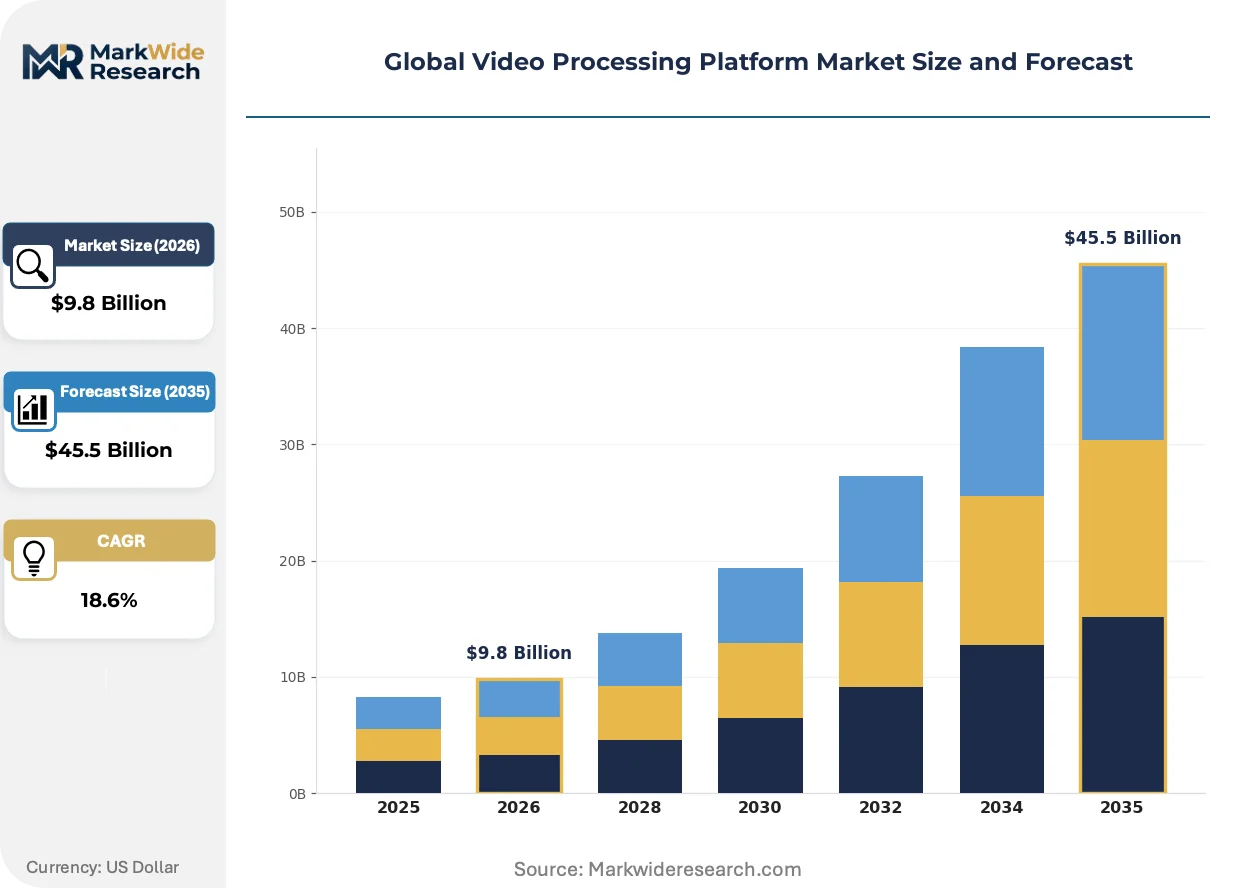
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $45.5 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Cloud-Based, On-Premises, Hybrid, Edge Computing Technology: AI-Powered Analytics, 4K & 8K Processing, HDR Enhancement, Real-Time Streaming, Compression Algorithms Application: Broadcast Media, Surveillance Systems, Content Delivery Networks, Telecommunication Networks, Digital Signage End User: Media Houses, Security Agencies, Telecom Operators, Advertising Firms, Educational Institutions |
| Companies Covered | Akamai Technologies, MediaKind, Harmonic, Synamedia, Brightcove, Kaltura, Amagi, ATEME, Imagine Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Video Processing Platform Market Shifts & Advancements
Neural processing units are embedding directly into encoding pipelines, collapsing the boundary between software-defined and hardware-accelerated transcoding. This architectural convergence is redrawing vendor specialization boundaries.
AV1 hardware encoding is absorbing development resources previously allocated to HEVC optimization. Broadcast equipment manufacturers in Germany and South Korea are shipping AV1-capable appliances eighteen months ahead of prior codec transition timelines. The technology is absorbing margin from patent-licensing-dependent business models, compressing royalty revenue pools for MPEG-LA licensors.
The EU AI Act risk-classification framework for automated content recognition is forcing algorithmic audit documentation into procurement specifications. European broadcast network CTOs now require explainability logs for AI-driven content moderation modules. This regulatory architecture is segmenting vendor qualification, excluding black-box inference engines from Tier-1 broadcaster approved vendor lists.
Subscription fatigue among streaming consumers is fragmenting content budgets across multiple free ad-supported television services. FAST platform operators in the United States are compressing channel launch timelines from months to weeks, demanding template-driven origination workflows from processing vendors. This procurement velocity is favoring cloud-native platform architectures over appliance-based deployments.
Global Video Processing Platform Market Segmentation
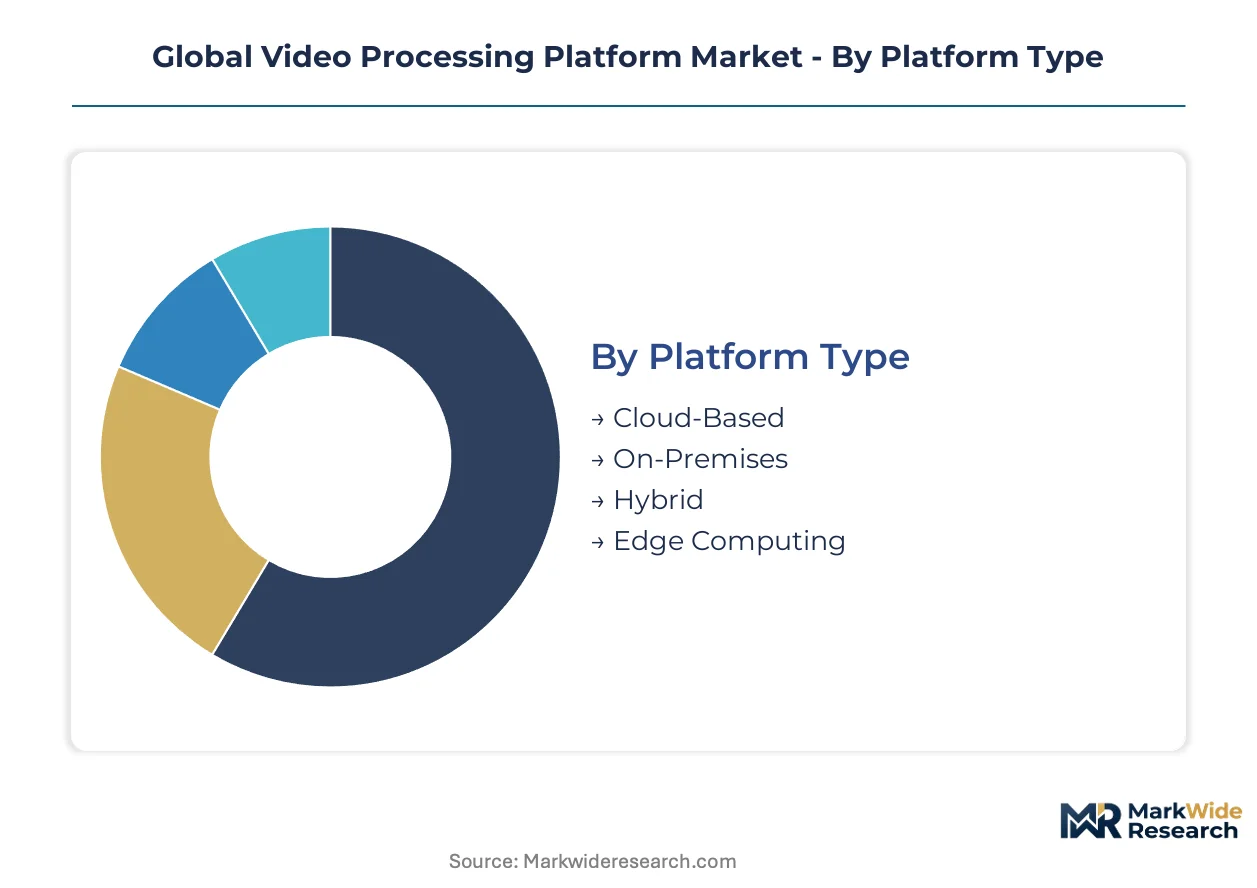
Video processing platforms fragment across deployment architectures, processing technologies, and use-case intensity. Each segment carries distinct margin profiles and capital requirements that reshape vendor specialization boundaries.
Platform Type:
Standalone cloud deployments dominate volume procurement, while edge and hybrid configurations embed into distributed infrastructure stacks where latency mandates override pure cost optimization.
- Cloud-Based:Fully virtualized transcoding and distribution infrastructure hosted on hyperscale provider networks. Media houses in the United States and South Korea are migrating capital expenditure to operational models, driven by OTT content volume surges and elastic scaling requirements.
- Hybrid:Split architectures retaining on-premises encryption and ingestion while leveraging cloud bursting for peak transcoding loads. German broadcasters facing EU AI Act compliance mandates favor this model for algorithmic audit trail control.
- On-Premises:Dedicated hardware appliances in owned data centers with fixed capacity ceilings. Security agencies and defense contractors in Japan maintain these deployments for air-gapped content handling.
- Edge Computing:Distributed processing nodes positioned within last-mile network infrastructure to collapse latency budgets. Live sports wagering operators in South Korea deploy these for sub-200-millisecond synchronization.
Volume placements concentrate in Cloud-Based; the faster expansion belongs to Edge Computing.
Technology:
Technology segments stratify by computational intensity and intellectual property exposure, with royalty-free standards absorbing development resources from patent-encumbered alternatives.
- AI-Powered Analytics:Neural inference engines for automated content recognition, moderation, and personalization. The EU AI Act risk-classification framework forces explainability documentation into procurement specifications, excluding black-box systems from Tier-1 broadcaster vendor lists.
- Compression Algorithms:Codec optimization across H.264, HEVC, AV1, and VVC standards. AV1 hardware encoding is compressing eighteen-month development cycles ahead of prior transitions, absorbing margin from MPEG-LA royalty pools.
- Real-Time Streaming:Sub-200-millisecond pipeline architectures for live event synchronization. Premium pricing commands this segment in United States sports wagering and Korean esports broadcasting.
- 4K & 8K Processing:Ultra-high-definition transcoding pipelines with expanded bitrate requirements. Japan's METI 8K broadcast standards drive hardware refresh cycles with limited backward compatibility.
- HDR Enhancement:Dynamic range mapping and tone curve optimization across delivery endpoints. Streaming services in Germany deploy these for cinematic content differentiation.
AI-Powered Analytics commands the steepest expansion trajectory; Compression Algorithms anchor current volume deployment.
Application:
Application segments diverge by content velocity requirements, with live broadcast workflows demanding fundamentally different architectural resilience than cached distribution systems.
- Broadcast Media:Linear and streaming channel origination with 99.999% availability targets. FAST platform operators in the United States compress launch timelines from months to weeks, forcing template-driven procurement.
- Content Delivery Networks:Distributed caching and adaptive bitrate streaming infrastructure. Edge-computing footprints from Akamai Technologies sustain low-latency contracts with Tier-1 broadcasters.
- Surveillance Systems:Multi-camera ingestion with forensic-grade timestamp integrity. Security agencies in Japan and Germany require local encryption handling that resists cloud migration.
- Telecommunication Networks:Carrier-grade video transport with SLA-backed quality metrics. South Korean operators integrate processing into 5G network slicing architectures.
- Digital Signage:Scheduled playlist distribution to heterogeneous endpoint displays. Retail networks in the United States favor this for advertising-supported in-venue content.
Broadcast Media absorbs the largest capital allocation; Content Delivery Networks are climbing fastest on streaming traffic expansion.
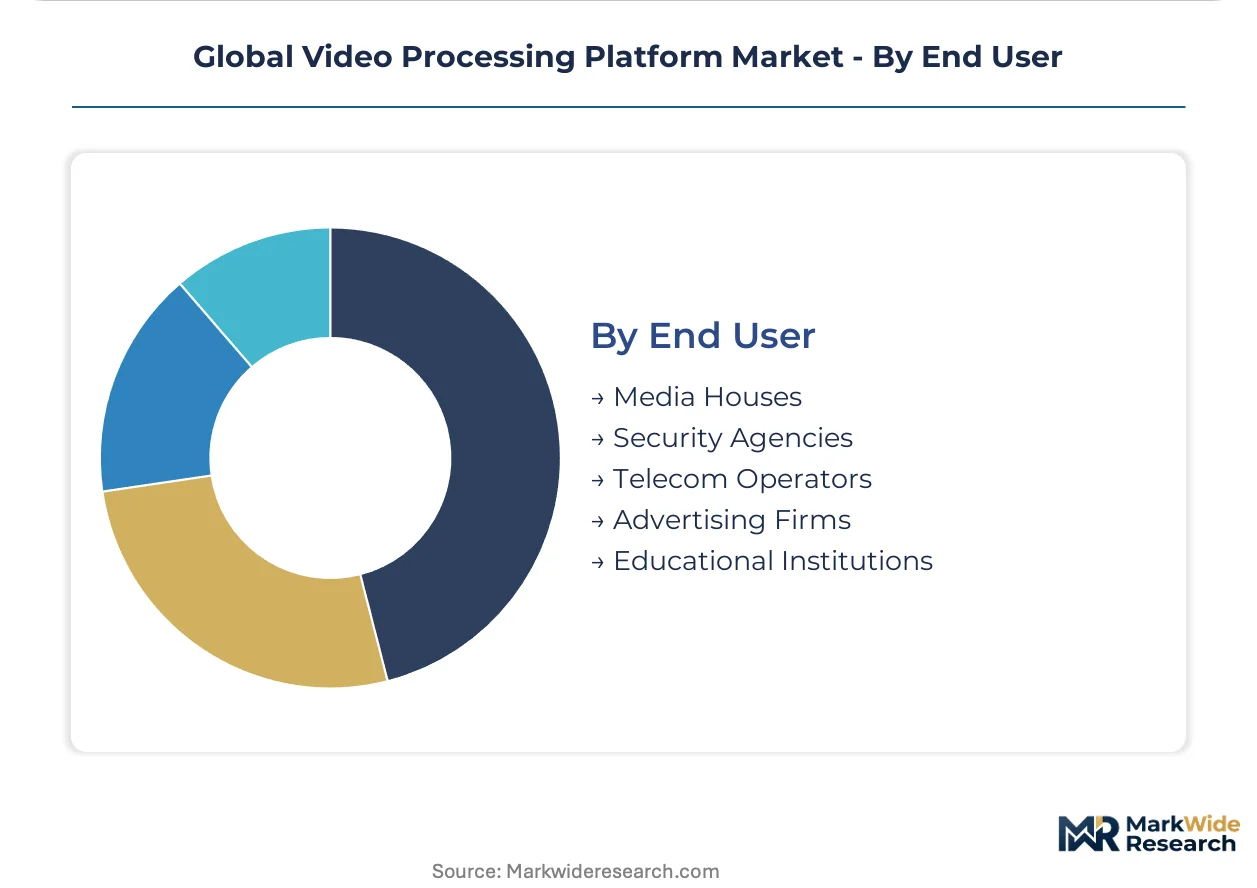
End User:
End-user categories separate by procurement sophistication, with media and telecom buyers driving standardization while security and education segments tolerate longer integration cycles.
- Media Houses:Broadcasters, streaming aggregators, and FAST platform operators with continuous 24/7 processing demands. Cloud-native channel origination from Amagi dominates this segment for advertising-supported streaming.
- Telecom Operators:Carriers bundling video services with connectivity subscriptions. Converged cable-streaming infrastructure from Harmonic enables single-vendor consolidation for North American operators.
- Security Agencies:Government and private surveillance operators with classified content handling requirements. On-premises deployments predominate due to air-gap mandates.
- Advertising Firms:Creative agencies and media buyers requiring dynamic ad insertion and personalization. ISO/IEC 23009-5 compliance services create certification-driven consulting revenue.
- Educational Institutions:Universities and K-12 districts with lecture capture and remote learning workflows. Budget constraints favor commodity cloud transcoding over broadcast-grade processing.
Media Houses represent the deepest procurement volume; Advertising Firms are expanding most quickly on addressable TV and programmatic video growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors the densest concentration of live sports wagering infrastructure, with sub-200-millisecond latency requirements driving edge-computing deployments across South Korean metropolitan networks.
United States
Live sports betting synchronization and FAST platform proliferation consume processing capacity across the Northeast corridor and California tech clusters. The FCC enforces closed-captioning and emergency-alert standards that shape platform accessibility requirements. New York and Los Angeles media hubs host hyperscale cloud infrastructure investments from Tier-1 broadcasters migrating from capital-intensive on-premises systems.
Germany
EU AI Act compliance mandates for algorithmic transparency are forcing infrastructure upgrades among broadcast networks in Bavaria and North Rhine-Westphalia. German regulators impose risk-classification obligations on automated content recognition systems. Berlin and Munich industrial corridors concentrate cloud egress bandwidth pricing negotiations that erode margin on high-bitrate live streams.
South Korea
Esports broadcasting and real-time wagering applications demand sub-200-millisecond pipeline architectures across the Seoul Capital Area. The country's national broadcasting regulator aligns with METI-influenced standards for next-generation encoding. Busan-Ulsan and Daejeon-Sejong technology zones integrate processing into 5G network slicing architectures for carrier-grade video transport.
Japan
METI-promoted 8K broadcasting standards drive costly encoder refresh cycles among equipment vendors in the Kanto and Kansai regions. Japan's industrial policy mandates hardware replacements with limited content library backward compatibility. Tokyo and Osaka broadcast engineering clusters maintain on-premises deployments for air-gapped content handling by security agencies.
United Kingdom
Advertising-supported streaming origination and ISO/IEC 23009-5 compliance services create certification-driven consulting revenue in London and the Southeast. The country's communications regulator enforces accessibility standards that intersect with EU AI Act risk frameworks. Manchester and Birmingham media production zones adopt hybrid architectures retaining local encryption handling for algorithmic audit trail control.
Global Video Processing Platform Market Competitive Landscape
Premium-margin players sit above commodity-margin players across latency-performance and AI-explainability dimensions. The vendor base stratifies into three tiers: edge-computing specialists commanding live sports contracts, cloud-native channel origination platforms capturing FAST growth, and converged infrastructure providers consolidating cable-streaming hybrid deployments. Consolidation pressure intensifies as neural processing units collapse boundaries between software-defined and hardware-accelerated transcoding. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and geographic expansion into underpenetrated Latin American and Southeast Asian markets.
Within the edge-computing tier, Akamai Technologies and Harmonic occupy positions reflecting divergent specialization strategies. Akamai exemplifies the distributed infrastructure archetype leveraging last-mile network positioning for low-latency delivery contracts. Harmonic represents converged cable-streaming consolidation, enabling single-vendor relationships with North American operators facing fiber competition. Amagi anchors the cloud-native origination segment, capturing advertising-supported streaming procurement velocity that favors template-driven workflows over appliance-based deployments.
| Leading Market Players |
|---|
| Akamai Technologies |
| MediaKind |
| Harmonic |
| Synamedia |
| Brightcove |
| Kaltura |
| Amagi |
| ATEME |
| Imagine Communications |
| Others |
Supply & Pricing Matrix
EU AI Act algorithmic transparency mandates gate qualified supply access and premium-tier pricing eligibility for automated content recognition modules deployed across European broadcast networks. Tier-1 broadcasters now require explainability documentation that excludes black-box inference engines from approved vendor lists, compressing margins for non-compliant suppliers while elevating pricing power for certified platform vendors.
Pricing Analysis
Throughput-based subscription tiers anchor pricing structures across cloud-native deployments, with per-stream processing fees scaling by latency performance and codec complexity. Price differentiation rests on certification grade for EU AI Act compliance and geographic delivery cost for edge-computing nodes. Cost compression in commodity cloud transcoding is intensifying because hyperscale providers are absorbing volume discounts into standard rate cards. FAST platform operators exhibit highest price sensitivity due to advertising-supported revenue models, while live sports wagering operators accept premium pricing for sub-200-millisecond guarantees.
Supply Chain Analysis
Dual-sourcing requirements for neural processing units are mandating multi-supplier qualification among broadcast equipment manufacturers to mitigate Taiwan-based foundry concentration. Hardware encoding capacity draws from Taiwan, South Korea, and Germany, with GPU accelerators and ASIC fabrication feeding from specialized semiconductor foundries. Single-source vulnerability concentrates in advanced node lithography for real-time AI inference chips. Distribution runs through hyperscale cloud provider marketplaces and direct OEM relationships with broadcast infrastructure vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over edge-computing infrastructure and neural compression IP determines margin capture. Players are pursuing downstream leverage through captive channel origination platforms to lock in recurring revenue streams.
For Market Incumbents: Acquire edge-computing real estate in metropolitan network hubs to defend against hyperscale cloud encroachment on low-latency live sports contracts. Consolidate converged cable-streaming infrastructure positions through certification investments for ISO/IEC 23009-5 server-side ad insertion standards, neutralizing emerging cloud-native competitors in North American cable markets. For New Entrants and Emerging Players: Capture FAST platform origination demand in Brazil and Southeast Asian markets where template-driven channel creation remains underpenetrated. Target advertising-supported streaming procurement velocity with cloud-native architectures that compress launch timelines from months to weeks, bypassing appliance-based incumbents. For Investors and Strategic Acquirers: AV1 hardware encoding availability eighteen months ahead of prior codec transitions is the leading indicator that royalty-free standards are absorbing margin from patent-licensing-dependent business models. Long-term viability favors platform vendors with captive neural compression R&D and multi-territory EU AI Act compliance certification. The signal to monitor is Tier-1 broadcaster vendor list exclusions of black-box AI systems.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Infrastructure Expansion | Akamai Technologies leverages last-mile positioning to sustain low-latency delivery contracts with Tier-1 broadcasters. |
| Cloud-Native Channel Origination Platform | Amagi captures FAST platform procurement velocity through template-driven workflows that compress launch timelines. |
| Converged Cable-Streaming Infrastructure | Harmonic enables single-vendor consolidation for North American operators facing fiber competition. |
| EU AI Act Compliance Certification | Algorithmic audit documentation requirements exclude black-box inference engines from Tier-1 broadcaster vendor lists. |
| AV1 Hardware Encoding Transition | German and South Korean manufacturers ship encoding appliances eighteen months ahead of prior codec transition timelines. |
Research Methodology
SEC filings from hyperscale cloud providers, ETSI technical specifications, and EU regulatory transparency databases formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with broadcast network CTOs, video platform engineering directors, and FAST channel operations executives validated deployment architecture preferences and procurement timelines. Bottom-up segment modeling triangulated against top-down industry expenditure analysis produced volume and value estimates across the analysis window.
Historical trendline analysis of capital expenditure patterns among Tier-1 broadcasters and OTT aggregators established baseline growth trajectories. The analytical framework segmented by deployment architecture, processing technology, application intensity, and end-user procurement sophistication throughout the forecast period. CAGRs derived from elasticity modeling of content volume growth against infrastructure cost curves, with neural processing unit penetration and codec transition timelines as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Taiwan foundry capacity constraints and EU AI Act enforcement variance across member states. Model outputs reflect assumptions regarding HEVC-to-AV1 migration velocity and live sports wagering regulatory expansion. A model refresh is warranted upon material change in GPU supply availability or automated content recognition risk-classification thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Construction Fabrics Market
Others
Programmatic Display Market
Others
Folding Smartphone Market
Others
Digital Tattoos Market
Others
Smart Home As a Service Market
Others
Vacuum Evaporators Market
Others
Europe Travel Retail Market
Others
Global Microcontroller Embedded Systems Market
Others
Bakery Packaging Market
Others
Finished Leather Market
Others
Digital Transformation of Maritime Freight Market
Others
Exosome Technologies Market
Others
Global Process Equipment Market
Others
Global Laser Defense Eyewear Market
Others
Ultra Mobile Devices (UMD) Market
Others
Europe Astrology Market