
 Underground Power Cable Partial Discharge and Fault Location Test Equipment Market | 2026-2036
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market Insights
The gap between laboratory-grade partial discharge analysis and handheld field diagnostics is repositioning procurement patterns across utility fleets. Megger sustains its heritage in insulation resistance testing through dedicated service networks across European distribution operators. HIOKI E.E. Corporation differentiates via compact electromagnetic sensors engineered for congested underground vault access in Japanese metropolitan grids. BAUR GmbH dominates the premium segment with very low frequency (VLF) test systems that integrate partial discharge measurement and fault location in single platforms.
Underground power cable partial discharge and fault location test equipment encompasses instruments that detect insulation degradation through electromagnetic pulse analysis and pinpoint cable defects using time domain reflectometry with spatial resolution typically below one percent of cable length. These systems serve primarily to prevent catastrophic failures in medium and high voltage distribution networks by identifying incipient faults before dielectric breakdown occurs. Partial discharge detectors command the largest revenue pool given their role in continuous asset monitoring programs, while time domain reflectometry is displacing traditional bridge methods for pre-location accuracy in long-distance transmission circuits. Fault locators attract focused R&D investment as utilities shift from time-based maintenance to predictive asset management protocols.
FERC reliability standards and IEEE 400.2 guide VLF testing procedures in US utility procurement specifications, while IEC 60502 and CENELEC HD 620 shape European product certification thresholds. The EU Green Deal's grid modernization funding is tightening diagnostic equipment mandates for interconnectors feeding renewable generation clusters. Stakeholders must weigh the trade-off between portable unit versatility and fixed monitoring system sensitivity as network digitalization accelerates.
Market Dynamics
VLF test systems are consolidating partial discharge detection and fault location into single-platform architectures, compressing procurement cycles for utility asset managers while raising technical certification barriers for field technicians.
Growth Catalysts
- IEEE 400.2 Standardization:US utilities now mandate VLF testing protocols for medium-voltage cable commissioning, forcing fleet upgrades across investor-owned and municipal operators.
- Urban Grid Density:Tokyo, London, and New York metropolitan distribution networks face acute failure risks from 1960s-era XLPE insulation, accelerating predictive diagnostic deployments.
- Time Domain Reflectometry:This pulse-based pre-location method is displacing traditional Murray loop bridge techniques in long-distance transmission circuits, cutting fault location times by half.
Market Restraints
- Copper and Rare Earth Volatility:Electromagnetic sensor cores depend on neodymium supply chains concentrated in Chinese processing facilities, creating input cost uncertainty for manufacturers.
- Calibration Infrastructure Gaps:Accredited laboratories capable of certifying partial discharge sensitivity below 1 pC remain concentrated in Germany, Japan, and the United States, limiting field deployment in secondary markets.
- Silicon Photonics Substitution:Distributed acoustic sensing using fiber-optic cables is emerging as an alternative for continuous cable monitoring in greenfield installations.
Strategic Opportunities
- India Smart City Mandates:The Ministry of Power's urban distribution modernization program creates first-mover advantages for compact, battery-operated fault locators suited to congested municipal rights-of-way.
- EU Green Deal Interconnectors:Offshore wind transmission corridors between Denmark and Germany require subsea cable diagnostic capabilities that integrate with existing VLF platforms.
- Cloud-Connected Fleet Management:Equipment vendors are embedding LTE modules to stream partial discharge data directly to utility SCADA systems, enabling subscription-based predictive maintenance revenue streams.
Industry Challenges
- High-Voltage Technician Scarcity:Utilities in France and Italy report 18-month backlogs for certified partial discharge analysts, constraining deployment of advanced diagnostic fleets.
- IEC 60502 Compliance Timelines:Type-test certification for new sensor architectures requires 14-24 months of accelerated aging validation, delaying product launches.
- Legacy Bridge Method Integration:Field crews trained on Wheatstone bridge techniques resist transitioning to TDR interfaces without parallel training investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underground Power Cable Partial Discharge and Fault Location Test Equipment Market |
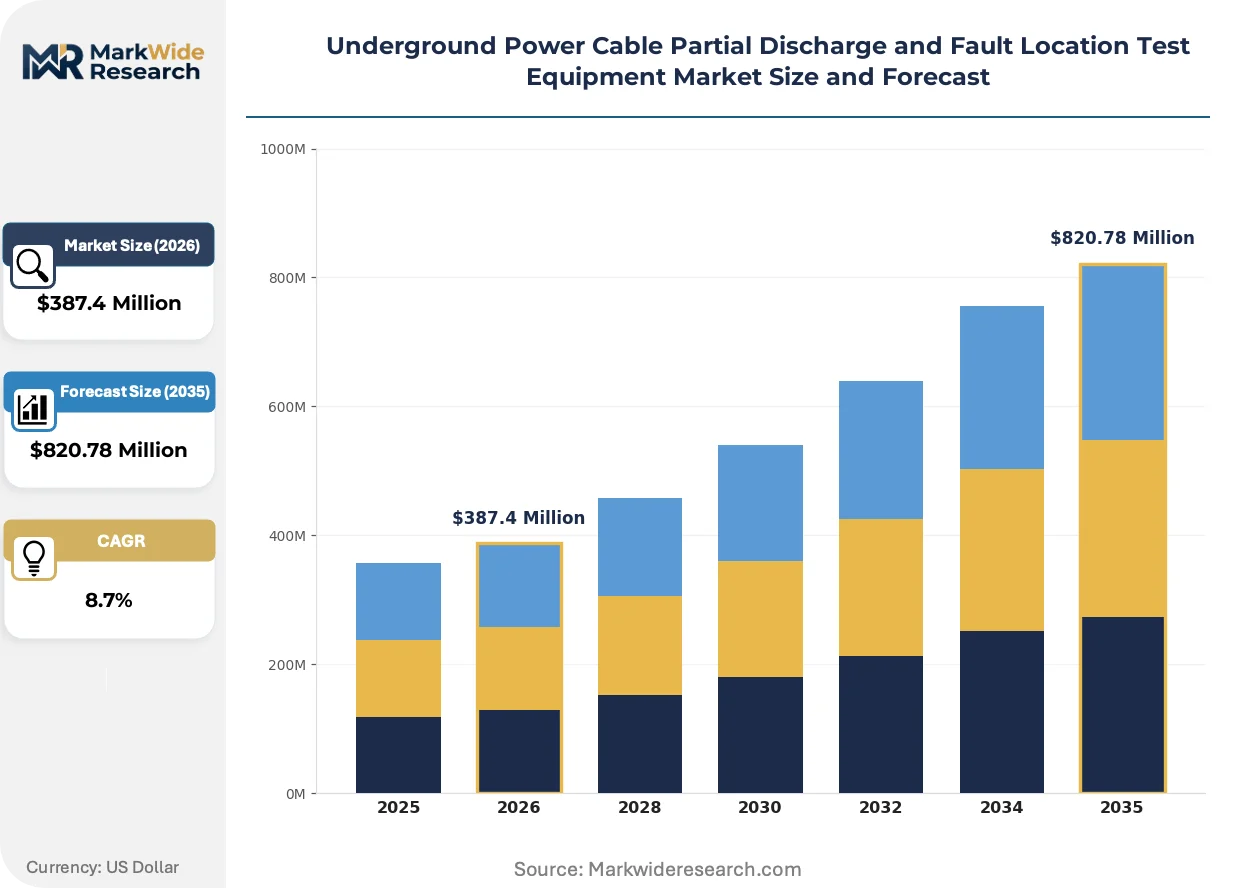
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $820.78 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Partial Discharge Detectors, Fault Locators, Cable Testing Instruments, Insulation Testers, Time Domain Reflectometers Technology: Ultrasound, Electromagnetic, Acoustic Emission, Transient Earth Voltage, Time Domain Reflectometry, Frequency Domain Reflectometry Application: Power Distribution Systems, Substation Maintenance, Cable Commissioning, Asset Condition Monitoring, Preventive Maintenance End User: Utility Companies, Electrical Contractors, Testing Laboratories, Industrial Facilities, Renewable Energy Firms |
| Companies Covered | 3M, Fluke Corporation, Megger, BAUR GmbH, Keysight Technologies, EA Technology, Radiodetection, HIOKI E.E. Corporation, HV Hipot Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market Trends and Innovations
Artificial intelligence inference at the edge is reshaping how partial discharge signals are classified, enabling real-time insulation degradation scoring without cloud dependency. This shift is compressing response windows for critical infrastructure protection.
Ultra-wideband electromagnetic sensors are electrifying defect detection in shielded medium-voltage cables by capturing transient pulses across 100 MHz bandwidths. German distribution operators are deploying these units for continuous monitoring of industrial corridor feeders. The technology is electrifying competitive positioning for vendors capable of manufacturing sub-picofarad resolution front-ends.
The EU Green Deal's grid modernization funding is tightening diagnostic equipment mandates for interconnectors feeding renewable generation clusters. CENELEC HD 620 certification thresholds are being revised to require traceable partial discharge measurement uncertainty budgets. European cable test houses are expanding calibration capacity to meet anticipated audit volumes.
Utility procurement departments are unbundling after-sales service contracts from equipment purchases, creating standalone calibration and training revenue pools. This restructuring favors vendors with captive service networks over pure-play manufacturers. The shift is most visible in UK and Netherlands distribution operators with centralized asset management functions.
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market Segmentation
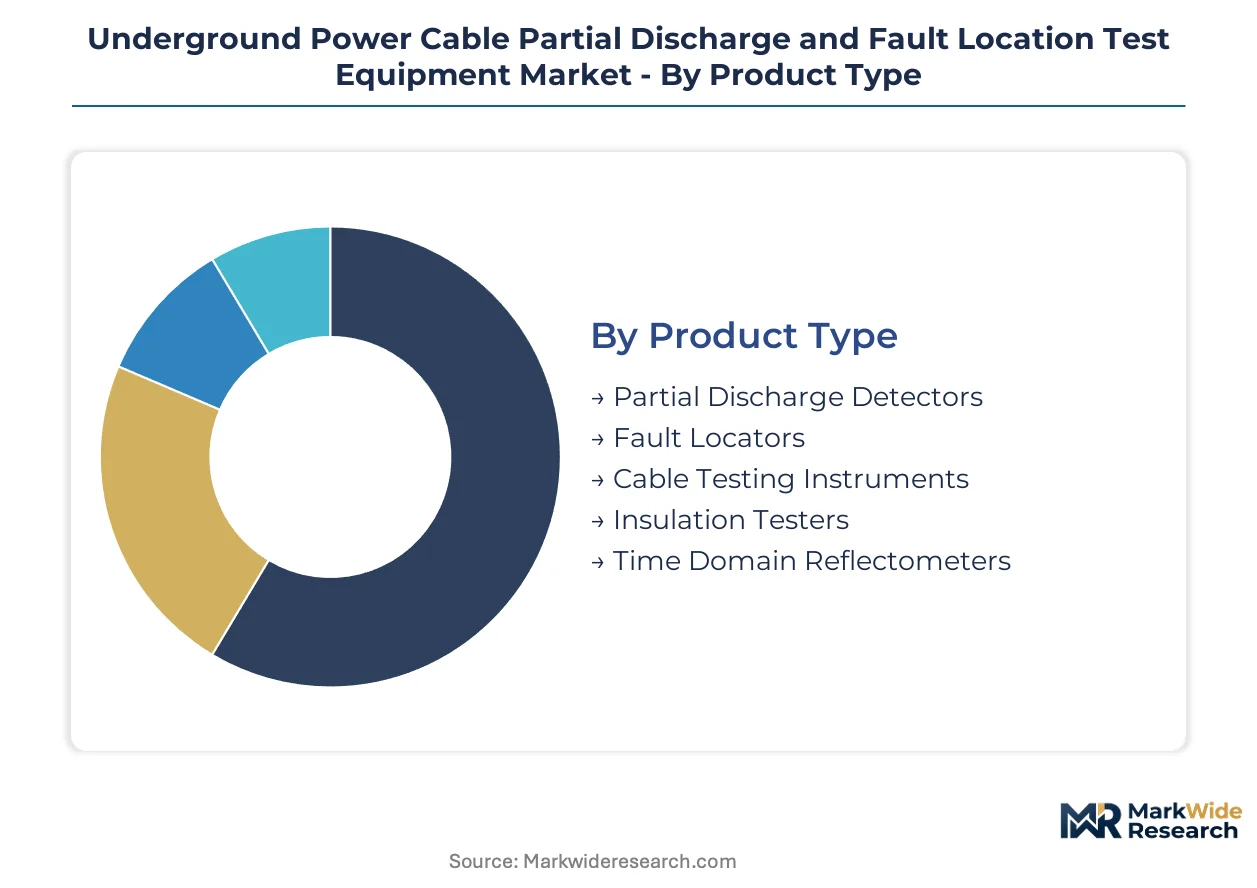
Equipment specifications diverge sharply between transmission-grade diagnostics and distribution-level portability. Procurement budgets allocate disproportionately toward platforms that consolidate multiple test modalities, reshaping how vendors structure product portfolios across voltage classes.
Product Type:
Capital intensity peaks with integrated VLF systems that combine partial discharge measurement, fault location, and dielectric withstand testing in single enclosures. Utility procurement cycles favor these multifunction platforms despite 40-60% higher upfront costs versus standalone units.
- Partial Discharge Detectors:Electromagnetic pulse analyzers detect insulation degradation through pico-coulomb sensitivity thresholds. German distribution operators deploy these for continuous monitoring of industrial corridor feeders where XLPE aging accelerates failure risk.
- Fault Locators:Time domain reflectometry units pinpoint cable defects with spatial resolution below one percent of cable length. Demand concentrates in Tokyo and London metropolitan grids where 1960s-era infrastructure requires precise pre-location before excavation.
- Cable Testing Instruments:VLF and DC withstand testers validate dielectric integrity during commissioning protocols.
- Insulation Testers:Megohm measurement devices perform baseline resistance verification before advanced diagnostic deployment.
- Time Domain Reflectometers:Pulse-based pre-location tools displace traditional bridge methods in long-distance transmission circuits.
Most installed capacity flows through Partial Discharge Detectors. Expansion is steepest in Fault Locators as predictive maintenance protocols displace time-based replacement schedules.
Technology:
Sensor architecture determines field deployment constraints, with electromagnetic and acoustic methods dominating congested underground vault access where physical probe insertion proves impractical.
- Electromagnetic:Wideband transient capture across 100 MHz bandwidths enables sub-picofarad resolution for shielded medium-voltage cables. Japanese metropolitan utilities specify these for dense urban distribution networks with limited maintenance windows.
- Time Domain Reflectometry:Pulse propagation analysis delivers precise fault distance measurement without cable de-energization in many configurations. US transmission operators favor TDR for cross-country circuit pre-location where excavation costs escalate dramatically.
- Ultrasound:Mechanical wave detection identifies surface discharge activity in terminations and joints.
- Acoustic Emission:Stress wave monitoring captures internal void discharge signatures in solid dielectric cables.
- Transient Earth Voltage:Surface potential measurement detects internal partial discharge through capacitive coupling in switchgear applications.
- Frequency Domain Reflectometry:Swept-frequency analysis identifies impedance discontinuities with enhanced sensitivity for branched network topologies.
Electromagnetic sensors command the dominant installed base. Frequency Domain Reflectometry is climbing the fastest as branched renewable interconnection networks proliferate.
Application:
Revenue concentration tracks utility capital expenditure cycles, with asset condition monitoring programs absorbing the largest diagnostic equipment allocations as regulatory pressure tightens reliability standards.
- Asset Condition Monitoring:Continuous or periodic insulation assessment programs transition utilities from time-based to predictive maintenance protocols. EU Green Deal grid modernization funding mandates these capabilities for interconnectors feeding offshore wind clusters between Denmark and Germany.
- Power Distribution Systems:Medium-voltage underground network testing dominates field deployment volumes across aging urban infrastructure. New York and Tokyo face acute replacement pressure from 1960s-era XLPE installations with elevated failure incidence.
- Substation Maintenance:Terminal and joint testing during outage windows verifies connection integrity.
- Cable Commissioning:Acceptance testing protocols validate new installation quality before energization.
- Preventive Maintenance:Scheduled diagnostic surveys identify degradation trends before catastrophic breakdown.
Asset Condition Monitoring absorbs the largest equipment budgets. Cable Commissioning is expanding most quickly as renewable generation interconnection volumes accelerate.
End User:
Procurement authority concentrates with entities owning cable asset portfolios, though electrical contractors capture significant equipment flow through service contract arrangements.
- Utility Companies:Investor-owned and municipal operators maintain captive diagnostic fleets for medium and high-voltage network maintenance. FERC reliability standards and IEEE 400.2 protocols mandate VLF testing capabilities across US transmission and distribution systems.
- Testing Laboratories:Accredited facilities perform type-testing and forensic analysis requiring laboratory-grade sensitivity below 1 pC. Calibration infrastructure gaps concentrate these capabilities in Germany, Japan, and the United States.
- Electrical Contractors:Service providers deploy portable units for third-party testing and emergency fault response.
- Industrial Facilities:Captive power systems in manufacturing and petrochemical complexes require dedicated diagnostic capabilities.
- Renewable Energy Firms:Wind and solar developers specify subsea and land cable testing for project commissioning and operational monitoring.
Utility Companies represent the dominant procurement channel. Renewable Energy Firms are gaining share fastest as offshore wind transmission corridors multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor outpaces Japanese metropolitan grids in diagnostic equipment density, while India's urban distribution networks accelerate procurement of compact fault locators for congested rights-of-way.
United States
FERC reliability standards and IEEE 400.2 protocols mandate VLF testing capabilities across investor-owned and municipal transmission operators. The Department of Energy's grid modernization funding tightens diagnostic requirements for aging urban infrastructure. New York metropolitan distribution networks face acute replacement pressure from 1960s-era XLPE installations with elevated failure incidence.
Germany
EU Green Deal grid modernization funding mandates asset condition monitoring capabilities for offshore wind interconnectors between Denmark and Germany. CENELEC HD 620 certification thresholds require traceable partial discharge measurement uncertainty budgets for equipment approval. The industrial corridor spanning North Rhine-Westphalia accelerates replacement cycles through predictive diagnostic deployments.
Japan
Tokyo metropolitan distribution networks face acute failure risks from 1960s-era XLPE insulation, accelerating predictive diagnostic deployments. METI's energy infrastructure resilience guidelines tighten cable testing protocols for dense urban grids. Japanese metropolitan utilities specify electromagnetic sensors for congested underground vault access with limited maintenance windows.
India
The Ministry of Power's urban distribution modernization program creates first-mover advantages for compact, battery-operated fault locators. Central Electricity Authority mandates strengthen diagnostic equipment requirements for smart city electrical infrastructure. Mumbai and Delhi municipal corporations accelerate procurement of portable units suited to congested rights-of-way.
United Kingdom
Ofgem's RIIO price control frameworks incentivize distribution network operators to shift from time-based to predictive maintenance protocols. UK distribution operators with centralized asset management functions unbundle after-sales service contracts from equipment purchases. London's aging underground cable networks drive adoption of time domain reflectometry for precise fault pre-location before excavation.
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market Competitive Landscape
Top-tier vendors anchor the premium segment, while mid-tier specialists and regional fabricators occupy distinct procurement channels. The market structure reflects consolidated capability at the high-performance end alongside fragmented supply for portable field units. Three archetypes dominate: heritage insulation testing houses, electromagnetic sensor specialists, and integrated VLF platform providers. Competitive moves concentrate on captive service network expansion and multifunction platform consolidation.
Among heritage European testing houses, Megger and BAUR GmbH exemplify contrasting strategic positions within the premium tier. Megger represents the established insulation resistance testing tradition through dedicated service networks, while BAUR GmbH occupies the integrated platform position combining VLF testing with partial discharge measurement. HIOKI E.E. Corporation anchors the compact sensor specialist archetype for dense metropolitan access constraints.
| Leading Market Players |
|---|
| 3M |
| Fluke Corporation |
| Megger |
| BAUR GmbH |
| Keysight Technologies |
| EA Technology |
| Radiodetection |
| HIOKI E.E. Corporation |
| HV Hipot Electric |
| Others |
Pricing and Supply Chain Analysis
Utility procurement departments unbundling after-sales service contracts from equipment purchases are forcing manufacturers to restructure revenue models and absorb upfront margin compression. This shift toward standalone calibration and training agreements concentrates pricing power with vendors possessing captive service networks across European distribution operators.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for VLF test systems as BAUR GmbH and domestic manufacturers expand sensor front-end production. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and after-sales bundling, with IEEE 400.2 compliance tiers commanding substantial premiums. Cost compression in the portable unit segment intensifies as Chinese manufacturers enter electromagnetic sensor markets. Municipal utilities in India exhibit highest price sensitivity due to constrained smart city budgets, while German industrial corridor operators prioritize sensitivity specifications over unit economics.
Supply Chain Analysis
High-voltage technician certification bottlenecks in France and Italy constrain final assembly throughput for precision-calibrated units. Electromagnetic sensor manufacturing concentrates in Germany, Japan, and China, with neodymium processing for sensor cores drawing from Chinese rare earth supply chains. Supply chain risk centers on single-source vulnerability for sub-picofarad resolution front-ends certified below 1 pC sensitivity. Distribution runs through authorized service networks rather than open channel partners, privileging incumbents with established calibration infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as grid modernization mandates across aging urban infrastructure create replacement cycle visibility. Regulatory tightening of IEEE 400.2 and IEC 60502 protocols sustains equipment refresh demand regardless of macroeconomic cycles.
For Market Incumbents: Cement service network density as the primary defensive moat against portable unit commoditization. Expand captive calibration laboratory capacity in secondary markets where accredited facilities remain scarce. Invest in cloud-connected fleet management platforms to capture recurring revenue streams as utilities unbundle procurement contracts. Counter silicon photonics substitution threats by integrating distributed acoustic sensing compatibility into VLF platform architectures. For New Entrants and Emerging Players: Electrical contractors seeking compact diagnostic capabilities represent an underserved buyer archetype distinct from utility fleet procurement. Target India's municipal corporations with battery-operated fault locators engineered for congested rights-of-way where maintenance windows are severely limited. Pursue white-label arrangements with European test houses requiring expanded calibration capacity under CENELEC HD 620 revisions. Differentiate through edge AI inference capabilities that reduce cloud dependency for real-time insulation scoring. For Investors and Strategic Acquirers: Asymmetric upside sits with electromagnetic sensor specialists possessing sub-picofarad manufacturing know-how and established relationships with Japanese metropolitan utilities. The five-to-ten year viability window favors acquisition targets with captive service networks over pure-play equipment manufacturers. Monitor IEC 60502 type-test certification backlogs as an inflection indicator for vendor capacity constraints and pricing power accumulation.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Fleet Integration | LTE module embedding enables subscription revenue streams from utility SCADA integration. |
| Calibration Infrastructure Expansion | Accredited laboratory buildout captures unbundled service contract flows from UK and Netherlands operators. |
| Edge AI Capability Acquisition | Real-time partial discharge classification without cloud dependency compresses critical infrastructure response windows. |
| Subsea Diagnostic Platform Extension | Offshore wind interconnector mandates between Denmark and Germany create specialized equipment demand. |
| Compact Sensor Miniaturization | Electromagnetic sensor footprint reduction opens congested underground vault access in Tokyo and London grids. |
Research Methodology
Bottom-up utility procurement modeling reconciled against top-down equipment shipment tracking forms the analytical core of this study. Primary interviews with utility asset managers, high-voltage test technicians, calibration laboratory directors, and diagnostic equipment procurement officers were validated against secondary sources including FERC reliability filings, IEC 60502 certification databases, IEEE standards documentation, and EU Green Deal grid modernization funding disclosures. Cross-referencing manufacturer service network maps with utility fleet deployment records enabled triangulation of installed base estimates.
Input-output matrices link partial discharge detector shipments, fault locator deployments, and VLF system installations to voltage class segmentation and end-user procurement channels across the projection horizon. Modeled dimensions span product type, sensor technology, application protocol, and end-user archetype, with CAGRs derived from regression analysis against utility capital expenditure cycles and regulatory compliance timelines. Forecast inputs incorporate cable replacement schedules for 1960s-era XLPE infrastructure and offshore wind interconnection buildout trajectories.
Inputs from utility procurement databases and equipment manufacturer service records were available through the study window; gaps in real-time partial discharge monitoring adoption rates introduce uncertainty bands around predictive maintenance transition timelines. Forecasts reflect documented assumptions regarding IEEE 400.2 mandate enforcement intensity and EU Green Deal funding continuity. Material deviation in neodymium supply chain stability or high-voltage technician certification throughput warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Mexico Wires and Cables Market
Cables
Smartphone Type-C Charging and Data Cable Market
Cables
Water Leak Sensing Cable Market
Cables
Usb Data Cable Market
Cables
Magnetic Charging Cable Market
Cables
Global Wires and Cables Market
Cables
Global Cable Gland Market
Cables
Cable Market
Cables
Wire and Cable Label Market
Cables
Cable Fault Locator Market
Cables
High Voltage Cables Market
Cables
EPR Cable Market
Cables
Low Voltage Cable Accessories Market
Cables
Network Cable Tester Market
Cables
Cable Flange Market
Cables
Asia-Pacific Cable Joints Market