
 EPR Cable Market | 2026-2036
EPR Cable Market Size, Share, and Industry Trends Forecast 2026-2036
EPR Cable Market Insights
The EU Green Deal is realigning procurement criteria for utility-scale cable contracts across European transmission networks. Prysmian Group leverages its submarine cable manufacturing footprint to capture offshore wind interconnection projects. Nexans sustains competitive positioning through backward integration into compound mixing operations. Sumitomo Electric Industries specializes in high-voltage EPR formulations for nuclear and thermal plant retrofits.
Ethylene propylene rubber cables employ a cross-linked insulation system rated for continuous conductor temperatures up to 90°C with short-circuit tolerance exceeding 250°C, serving critical functions in environments demanding thermal stability and moisture resistance. Power cables occupy the dominant value share given their deployment in renewable energy transmission and grid hardening investments. Low Smoke Zero Halogen grade material commands premium positioning as building codes tighten fire safety requirements in dense urban infrastructure projects. Flame Retardant grade competes on volume in industrial manufacturing settings where oil and chemical exposure risks persist.
FERC interconnection standards in the United States and EU CE marking under the Low Voltage Directive shape product certification requirements for cross-border cable shipments. China's GB standards and India's BIS certification create parallel compliance tracks that manufacturers must navigate for market access. Stakeholders should monitor evolving recyclability mandates and compound substitution timelines as regulatory pressure on halogen content and carbon intensity intensifies.
Market Dynamics
The EPR cable market is being fundamentally restructured by the EU Green Deal's recyclability mandates, which are forcing compound reformulation timelines and supplier qualification resets across European procurement frameworks.
Growth Catalysts
- Offshore wind procurement acceleration:Northern European developers are expanding medium-voltage array cable orders for North Sea projects. Germany's transmission system operators are consolidating specifications around EPR-insulated submarine designs.
- REACH compliance migration:The European Chemicals Agency's restrictions on halogenated flame retardants are redirecting specification sheets toward bio-based EPR formulations. Compound houses are scaling non-halogen additive packages.
- Grid hardening investment waves:China's State Grid Corporation is prioritizing moisture-resistant insulation for coastal province transmission corridors. Provincial utilities in Shandong and Jiangsu are issuing bundled cable tenders.
Market Restraints
- Ethylene and propylene feedstock volatility:Petrochemical input costs for EPR base polymer fluctuate with crude oil and natural gas liquid pricing. Compounders face margin compression during upstream spikes.
- Peroxide cross-linking agent concentration:Specialty chemical supply for the vulcanization process concentrates among a limited set of European and Japanese suppliers. Disruption risk elevates procurement costs.
- XLPE substitution in land-based transmission:Cross-linked polyethylene compounds compete for medium-voltage terrestrial applications where moisture resistance is less critical. EPR premiums face pressure in price-sensitive tenders.
Strategic Opportunities
- Floating offshore wind platform electrification:Dynamic cable systems for pre-commercial floating arrays in Portugal and Scotland require EPR's flexibility and fatigue resistance. Developers are qualifying new suppliers.
- India's coastal industrial corridor buildout:The Bureau of Indian Standards is revising cable specifications for humid subtropical environments. Gujarat and Tamil Nadu state utilities are expanding procurement frameworks.
- Digital twin integration with cable monitoring:Distributed temperature sensing and partial discharge detection systems are converging with EPR cable installations. Smart grid operators are bundling sensor infrastructure with cable orders.
Industry Challenges
- Compound formulation talent scarcity:Experienced rubber chemists capable of balancing electrical, mechanical, and fire-performance properties are retiring. Technical universities are not replenishing the specialist pipeline.
- Multi-standard certification timelines:Simultaneous pursuit of IEC, GB, and UL approvals for cross-border projects extends qualification cycles. Testing laboratory capacity constraints add quarters to product launches.
- Legacy XLPE infrastructure integration:Utilities with installed XLPE networks face technical and economic friction when specifying EPR for extensions or repairs. Joint compatibility and maintenance protocol divergence complicate fleet management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EPR Cable Market |
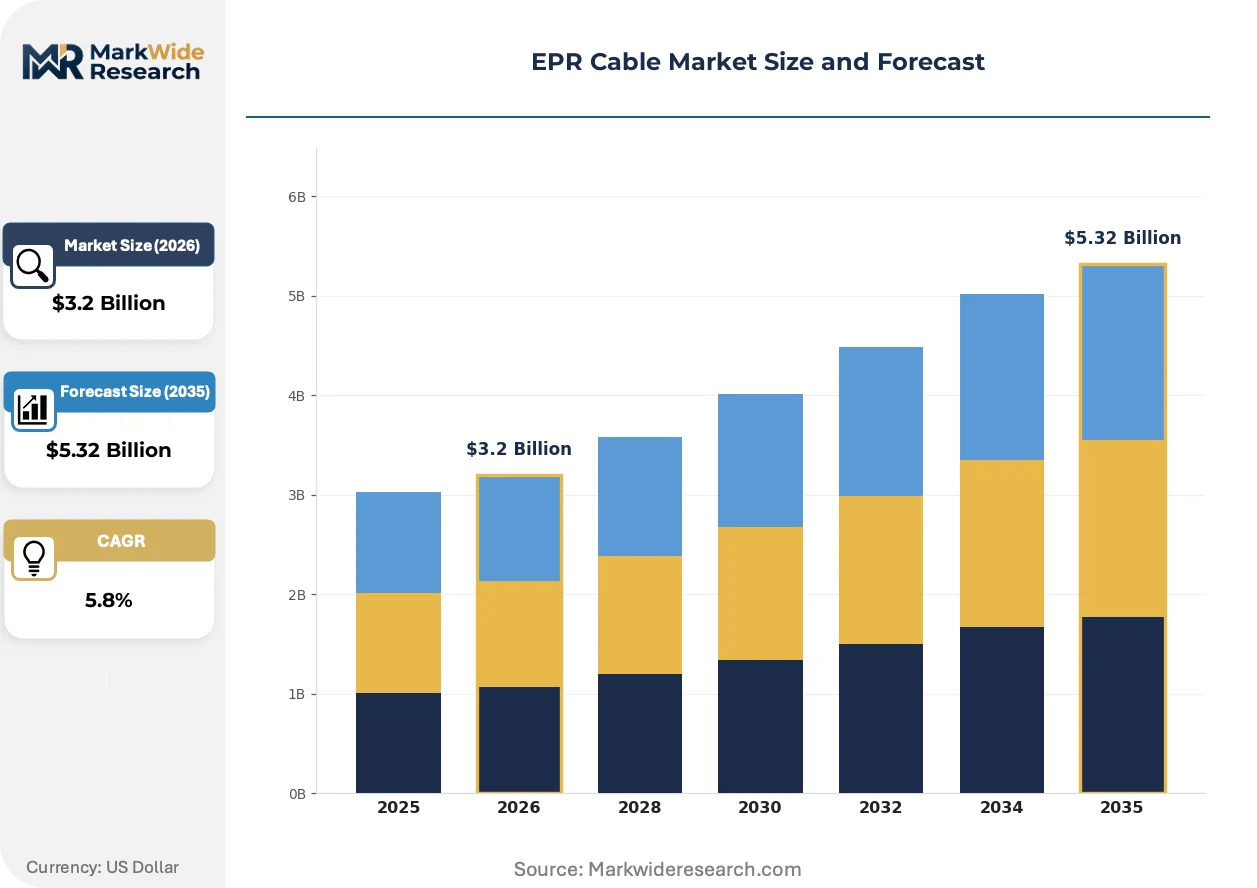
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.32 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Cables, Control Cables, Instrumentation Cables, Coaxial Cables, Fiber Optic Cables Material Grade: Standard Grade, High Temperature Grade, Flame Retardant Grade, Low Smoke Zero Halogen Grade, Weather Resistant Grade Application: Energy Transmission, Telecommunications, Industrial Manufacturing, Construction Projects, Electrical Distribution End User: Telecom Operators, Construction Firms, Manufacturing Plants, Power Distribution Companies, Data Centers |
| Companies Covered | Prysmian Group, Nexans, LS Cable & System, Sumitomo Electric Industries, Southwire Company, Furukawa Electric, NKT, KEI Industries, Hengtong Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EPR Cable Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are converging to redefine compound formulation priorities, while procurement digitization is compressing supplier-buyer coordination cycles across transmission project development.
Bio-based ethylene feedstocks derived from agricultural waste streams are integrating into EPR polymer production at pilot scale. Nordic cable manufacturers are qualifying these formulations for submarine applications where carbon intensity disclosures factor into tender scoring. The technology is integrating lifecycle assessment metrics directly into supplier selection criteria, compressing the competitive window for fossil-based compounders.
The EU Green Deal's cable recyclability mandates are compelling manufacturers to redesign insulation systems for end-of-life material recovery. Compounders must now demonstrate thermoplastic reprocessability or controlled depolymerization pathways to retain utility contract eligibility. Offshore wind developers in Germany and Denmark are embedding these requirements into 20-year service agreements, shifting specification power toward vertically integrated compound-cable producers.
Specification consolidation around digital tender platforms is compressing the supplier qualification cycle for transmission projects. European transmission system operators are migrating procurement to centralized e-procurement portals that standardize technical documentation and accelerate bid comparison. The shift is most visible in Germany's North Sea corridor, where TenneT and 50Hertz have harmonized EPR cable technical requirements across their joint offshore connection programs.
EPR Cable Market Segmentation
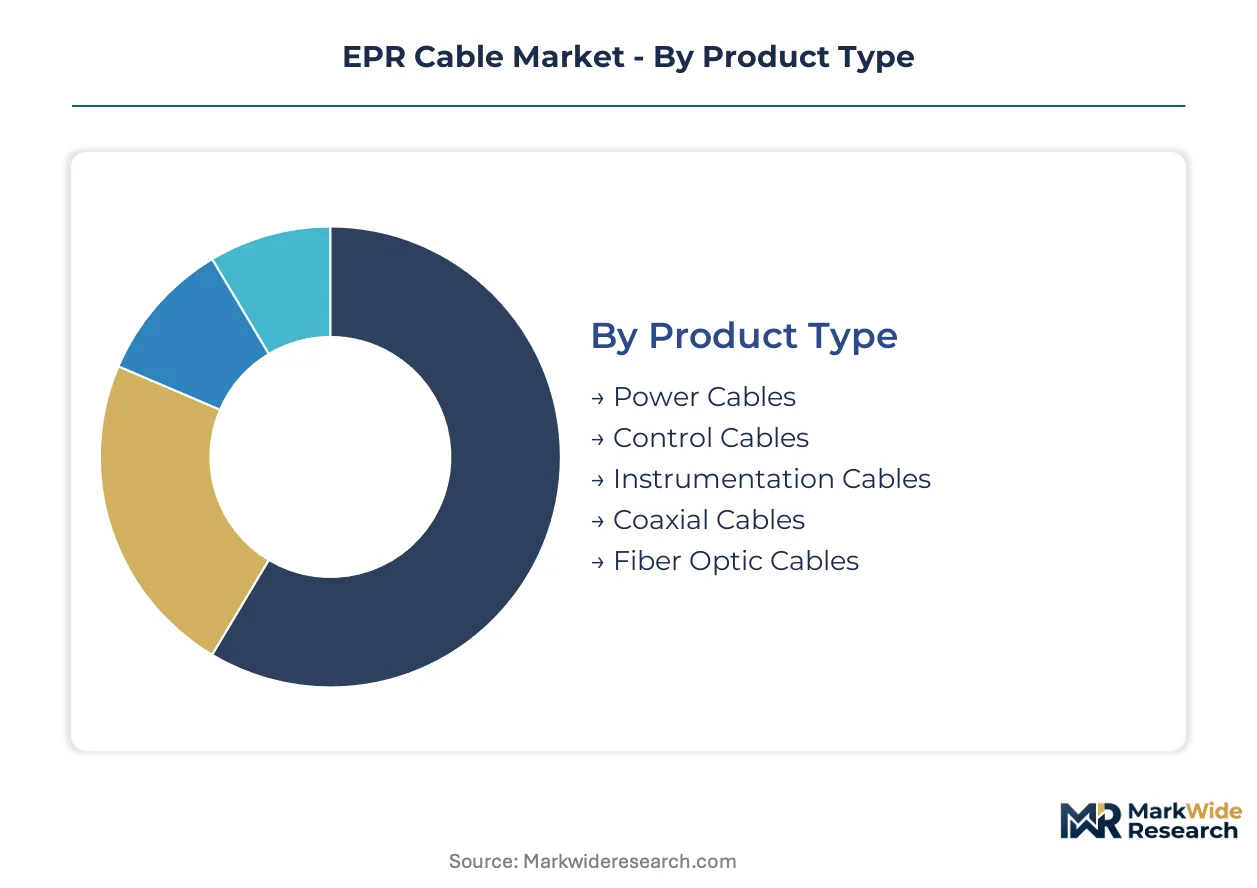
EPR cable procurement decisions hinge on thermal performance requirements and regulatory compliance tiers that vary sharply across installation environments. Specification sheets diverge based on whether cables face saltwater immersion, chemical exposure, or dense urban fire codes.
Product Type:
Replacement cycles for aging infrastructure are compressing procurement timelines for higher-performance cable categories.
- Power Cables:Medium-voltage designs rated up to 33kV dominate offshore wind array connections and grid intertie projects. Germany's North Sea corridor developers are consolidating specifications around EPR-insulated submarine power cable designs for 66kV collector systems.
- Control Cables:Multi-conductor configurations with individually screened pairs serve industrial automation and process control networks. Manufacturing plants in China's coastal provinces are specifying enhanced moisture barriers for humid subtropical environments.
- Instrumentation Cables:Low-capacitance designs with polyethylene bedding layers protect signal integrity in petrochemical facilities.
- Coaxial Cables:Semi-rigid constructions with EPR dielectric layers occupy niche RF transmission roles in marine and defense applications.
- Fiber Optic Cables:Composite power-fiber designs integrate EPR strength members for submarine and aerial deployments.
Power cables sit at the top of the volume ranking, with control cables climbing the fastest as industrial automation accelerates replacement schedules.
Material Grade:
Cost tiers separate commodity specifications from certified formulations required for regulated environments.
- Standard Grade:Peroxide-cross-linked EPR rated for 90°C continuous operation serves general-purpose industrial and utility applications. Provincial utilities in India are qualifying standard grade for humid coastal transmission corridors under revised BIS specifications.
- Low Smoke Zero Halogen Grade:Non-halogenated flame retardant packages eliminate toxic gas emissions during combustion. EU Green Deal mandates are forcing specification migration toward LSZH formulations in German and Danish offshore wind procurement frameworks.
- High Temperature Grade:Silicone-modified EPR compounds tolerate 150°C conductor temperatures in thermal power plant retrofits.
- Flame Retardant Grade:Halogenated additive systems compete on material cost in oil and chemical exposure settings where smoke toxicity is secondary.
- Weather Resistant Grade:Carbon black-loaded compounds with UV stabilizers serve aerial and direct-burial installations in high-solar regions.
Standard grade commands the largest procurement volumes, while LSZH grade is expanding most quickly as building codes and offshore wind mandates tighten.
Application:
Application selection tracks directly to the moisture, thermal, and mechanical stress profiles of each deployment environment.
- Energy Transmission:High-voltage EPR designs serve nuclear and thermal plant retrofits where thermal stability exceeds XLPE capabilities. Sumitomo Electric Industries specializes in formulations for these demanding replacement cycles.
- Industrial Manufacturing:Oil-resistant jacket compounds protect against chemical exposure in process industries. REACH compliance migration is redirecting specification sheets toward bio-based EPR formulations in European manufacturing procurement.
- Telecommunications:Hybrid power-fiber cables with EPR strength members serve submarine and rural broadband backhaul.
- Construction Projects:LSZH mandates in dense urban environments are compressing qualification timelines for fire-rated formulations.
- Electrical Distribution:Medium-voltage feeders with EPR insulation serve coastal and flood-prone utility territories.
Energy transmission anchors procurement volumes, with industrial manufacturing gaining share fastest as chemical resistance requirements intensify.
End User:
Customer type determines whether procurement emphasizes total cost of ownership or upfront capital minimization.
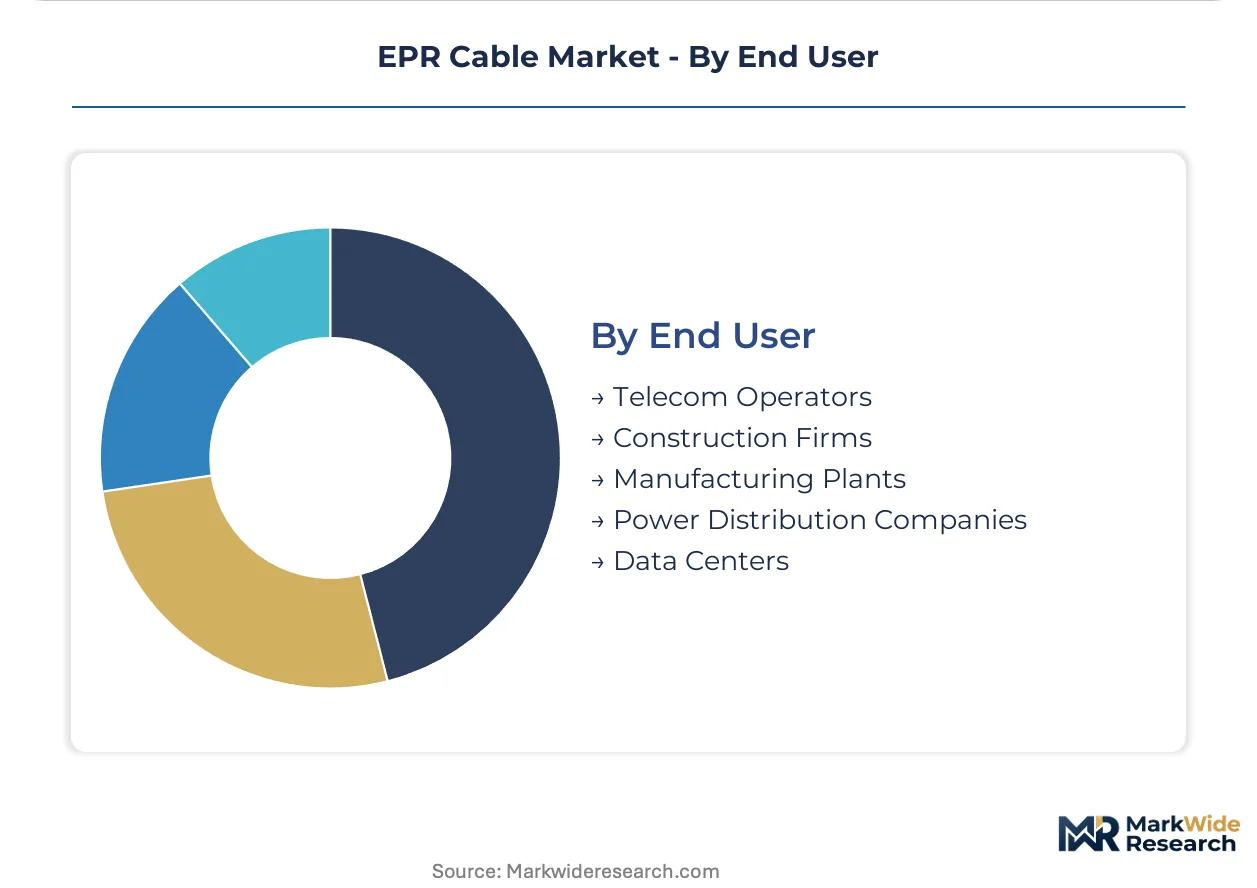
- Power Distribution Companies:Transmission system operators in Germany and China are bundling 20-year service agreements with cable orders that embed recyclability and digital monitoring requirements.
- Data Centers:Hyperscale operators specify LSZH grades for fire containment in densely cabled halls. FERC interconnection standards shape certification requirements for cross-border data center power feeds.
- Telecom Operators:Submarine cable consortiums prioritize fatigue resistance and moisture barriers for transoceanic routes.
- Construction Firms:Project-based procurement favors standard grades where code minimums permit.
- Manufacturing Plants:Process industries balance chemical resistance against peroxide cross-linking agent cost volatility.
Power distribution companies lead procurement volumes, with data centers climbing fastest as hyperscale construction accelerates fire-rated specification adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPR cable manufacturing originated in European industrial centers during the mid-20th century, with German and Italian compounders pioneering cross-linking technologies for high-voltage insulation systems.
Germany
Offshore wind developers in the North Sea corridor are consolidating procurement around 66kV submarine array specifications. The EU Green Deal's recyclability mandates are forcing compound reformulation timelines for cable suppliers serving TenneT and 50Hertz transmission projects. Hamburg and Bremen harbor clusters anchor submarine cable manufacturing and installation vessel staging operations.
China
State Grid Corporation is prioritizing moisture-resistant insulation for coastal province transmission corridors in Shandong and Jiangsu. GB standards revisions under MIIT oversight are tightening cable performance requirements for humid subtropical environments. Yangtze River Delta manufacturing bases are scaling EPR compound production to serve domestic and export demand.
United States
FERC interconnection standards are shaping certification requirements for cross-border transmission projects and data center power feeds. Grid hardening investments in hurricane-prone coastal utilities are elevating moisture-resistant cable specifications. Texas and Gulf Coast industrial corridors are expanding procurement for petrochemical and LNG facility electrification.
India
Bureau of Indian Standards is revising cable specifications for humid subtropical environments across Gujarat and Tamil Nadu state utilities. CEA-mandated transmission upgrades are accelerating coastal industrial corridor buildouts. Mumbai and Chennai manufacturing clusters are qualifying standard-grade formulations for revised BIS procurement frameworks.
Denmark
Offshore wind interconnection programs are embedding 20-year service agreements with recyclability and digital monitoring requirements. REACH compliance migration is redirecting specification sheets toward bio-based EPR formulations for Ørsted and Vattenfall projects. Esbjerg port infrastructure supports cable loadout and installation logistics for North Sea developments.
EPR Cable Market Competitive Landscape
Capital-heavy producers with captive compound mixing operations compete with asset-light cable assemblers sourcing insulation materials from third-party polymer houses. The vendor base stratifies across three tiers: integrated compound-cable manufacturers, specialized submarine cable fabricators, and regional utility cable suppliers. Strategic differentiation centers on backward integration into peroxide cross-linking agent supply and qualification for multi-standard certification regimes. Capacity expansion and strategic partnerships dominate competitive moves as players position for offshore wind procurement cycles.
Among European integrated manufacturers, Prysmian Group and Nexans exemplify the compound-cable vertical archetype. Sumitomo Electric Industries represents Japanese specialist positioning in high-voltage formulations. These three anchors illustrate how geographic origin and corporate structure map to strategic options: Milan-based and Paris-listed entities leverage submarine manufacturing footprints, while Osaka-headquartered operations concentrate on thermal stability applications for plant retrofits.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| LS Cable & System |
| Sumitomo Electric Industries |
| Southwire Company |
| Furukawa Electric |
| NKT |
| KEI Industries |
| Hengtong Group |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal recyclability mandates are compelling compound reformulation across European procurement frameworks, forcing suppliers to absorb certification and R&D costs while competing for utility-scale contracts. This demand-side specification shift compresses margins for non-integrated compounders and rewards backward integration into bio-based EPR production.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies EPR cable procurement, with LSZH-certified submarine grades commanding substantial premiums over standard industrial formulations. Price differentiation hinges on REACH compliance tier and peroxide cross-linking agent sourcing reliability. Pricing pressure stems from ethylene and propylene feedstock volatility linked to crude oil fluctuations. State utilities in India and Southeast Asia exhibit highest price sensitivity, while German and Danish offshore wind developers prioritize lifecycle cost and recyclability over unit economics.
Supply Chain Analysis
Specialist rubber chemist availability constrains compound innovation in Hamburg, Milan, and Osaka manufacturing clusters, where aging technical workforces face limited university pipeline replenishment. Raw material sourcing draws from Saudi ethylene crackers, Japanese propylene derivatives, and European peroxide vulcanization agents. Single-source vulnerability concentrates in specialty chemical supply for cross-linking processes. Distribution runs through transmission system operator e-procurement portals and direct OEM relationships for industrial automation customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where European regulatory stringency on halogen content and carbon intensity creates cost and compliance differentials against Asian manufacturing bases with looser environmental mandates.
For Market Incumbents: Hedge feedstock exposure through long-term offtake agreements with Saudi and Qatari ethylene producers, insulating margin structures from petrochemical volatility. Deepen backward integration into peroxide cross-linking agent production to reduce Japanese supplier concentration risk. Prioritize captive compound-mixing capacity in Bremen and Yangtze River Delta locations to defend positioning against emerging integrated competitors.
For New Entrants and Emerging Players: Floating offshore wind developers in Portugal and Scotland represent an underserved buyer archetype with unconsolidated supplier qualifications and urgent dynamic cable procurement needs. Target India's coastal industrial corridor buildout where BIS specification revisions create entry windows for standard-grade qualification. Pursue joint development agreements with floating platform engineering firms to embed EPR cable specifications early in project design cycles.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated compound-cable manufacturers possessing captive peroxide supply and multi-standard certification capabilities. Long-term viability favors entities with demonstrated thermoplastic reprocessability pathways aligned with EU end-of-life mandates. Monitor Ørsted and Vattenfall tender documentation for recyclability scoring methodology shifts as inflection indicators for supplier consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compound Mixing | Captive EPR formulation control insulates Prysmian and Nexans from peroxide supply disruptions. |
| Bio-Based Feedstock Qualification | Nordic manufacturers pilot agricultural waste-derived ethylene to meet EU Green Deal carbon intensity scoring. |
| Digital Twin Sensor Bundling | Smart grid operators at TenneT and State Grid converge distributed temperature sensing with cable procurement. |
| Multi-Standard Certification Investment | Simultaneous IEC, GB, and UL approvals compress product launch cycles for cross-border project participation. |
| Floating Wind Dynamic Cable Development | Pre-commercial arrays in Scotland and Portugal require EPR flexibility and fatigue resistance specifications. |
Research Methodology
Coverage spans Germany, China, India, Denmark, and the United States, with primary inputs from each market informing regional demand calibration. The research combines structured interviews with transmission system operators, compound house technical directors, offshore wind procurement leads, and utility cable engineering managers with secondary validation from customs trade data, SEC filings, IEC standard revision documentation, and FERC interconnection dockets. Bottom-up project pipeline aggregation and top-down macroeconomic elasticity modeling provide cross-check triangulation.
Segment-level granularity models product type, material grade, application environment, and end-user archetype across the projection horizon. CAGRs derive from elasticity-adjusted volume projections and value-per-unit trends by certification tier. Industry-specific forecast inputs include ethylene-propylene feedstock price scenarios, REACH restriction implementation timelines, and offshore wind capacity auction schedules.
Underlying measurement precision varies by segment; power cable and LSZH-grade volumes carry tighter precision than emerging floating wind dynamic cable categories. Forecasts reflect assumptions on regulatory enforcement consistency and petrochemical input cost stabilization. Practitioners should monitor ECHA substance restriction proposals, peroxide supplier capacity announcements, and floating wind platform commissioning dates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Flat Flexible Cables Market
Cables
US Cables Market
Cables
Power Cable Accessories Market
Cables
United States Cable Accessories Market
Cables
Power and Control Cable Market
Cables
Class 1E Electric Cables Market
Cables
Multi-Core Land High Voltage Underground Cable Market
Cables
Cable Fault Locator Market
Cables
Power and Signal Cables Market
Cables
Copper Cable Market
Cables
Anti-Static Space Wires Market
Cables
Mineral Insulated (MI) Cable Market
Cables
High-Temperature Superconducting Cables Market
Cables
Smartphone Type-C Charging and Data Cable Market
Cables
Military Cable Market
Cables
Europe Cable Accessories Market