
 Medical LED Headlight Market | 2026-2036
Medical LED Headlight Market Size, Share, and Industry Trends Forecast 2026-2036
Medical LED Headlight Market Insights
High-intensity white LEDs are repositioning xenon and halogen surgical lamps toward obsolescence across operating theaters. Karl Storz leverages its vertically integrated endoscope-illumination platform to bundle headlights with visualization systems. Enova Illumination specializes in lightweight, battery-powered designs that reduce surgeon fatigue during lengthy procedures. Integra LifeSciences anchors its position through hospital GPO contracts that lock in multi-year LED headlight supply agreements.
A medical LED headlight is a wearable, battery-powered or corded illumination device that mounts on a headband, surgical loupes, or integrated eyewear, typically delivering 50,000 to 100,000 lux at color temperatures between 4,000K and 6,500K to provide shadow-free, focused light during invasive procedures. Its primary purpose is to free surgeons' hands while maintaining consistent, high-fidelity tissue visualization across specialties from neurosurgery to dentistry. Wireless connectivity platforms represent the fastest-expanding technology segment as operating rooms prioritize cable-free mobility and reduced trip hazards. Portable configurations lead product-type demand due to their flexibility across outpatient clinics and field surgical units, while wall-mounted systems retain share in fixed-procedure suites where power reliability outweighs mobility needs.
The FDA's 510(k) clearance pathway governs device entry in the United States, while the EU MDR and CE marking requirements impose stricter clinical evidence standards on manufacturers selling into European hospitals. ISO 13485 quality management certification has become a baseline threshold for supplier qualification by procurement departments at major hospital networks. Stakeholders must monitor how battery chemistry regulations from the EPA and REACH substance restrictions reshape component sourcing for next-generation cordless platforms.
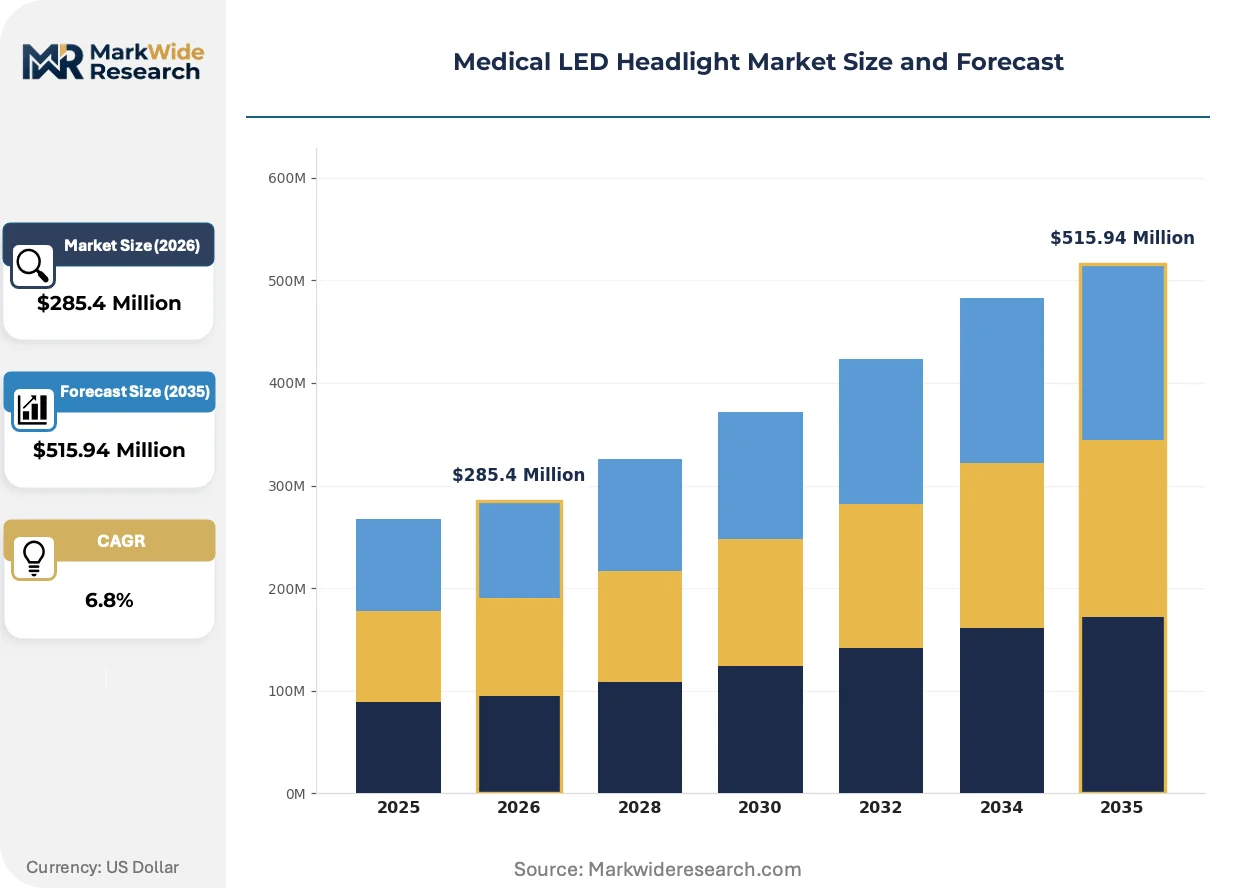
Market Dynamics
The EU MDR's tightened clinical evidence requirements are forcing manufacturers to consolidate wireless LED platforms around standardized battery architectures, compressing development cycles and reshaping supplier qualification protocols across hospital procurement departments.
Growth Catalysts
- EU MDR conformity mandates:Stricter CE marking requirements are accelerating hospital replacement of legacy corded systems with certified wireless platforms that streamline operating theater workflows.
- Surgical volume concentration:Ambulatory surgical centers are expanding LED headlight deployment as outpatient procedure volumes rise and facility budgets prioritize portable illumination.
- Lithium-polymer battery chemistry:Advances in energy density are enabling cordless designs that match wired output while eliminating trip hazards and sterilization constraints.
Market Restraints
- Cobalt supply concentration:Battery cell production depends on raw material sourcing from politically unstable regions, creating input cost volatility for cordless platform manufacturers.
- ISO 13485 certification timelines:Quality management audits impose 12-18 month lead times that delay market entry for new entrants seeking hospital network supplier status.
- Xenon lamp residual installed base:Capital-intensive surgical suites in budget-constrained facilities retain functional legacy systems, slowing replacement cycles despite LED performance advantages.
Strategic Opportunities
- Veterinary dentistry expansion:Companion animal surgical practices represent an underpenetrated channel where lightweight LED headlight adoption lags human medicine by approximately five years.
- FDA 510(k) predicate pathway:Streamlined clearance for devices demonstrating substantial equivalence to established wireless platforms reduces regulatory friction for iterative product improvements.
- Telemedicine-enabled remote surgery:Convergence of LED illumination with augmented reality visualization systems creates integrated platforms for telesurgical training and proctoring applications.
Industry Challenges
- Optical engineer talent scarcity:Specialized expertise in surgical-grade lens design and thermal management concentrates among a limited pool of professionals with medical device experience.
- Legacy integration complexity:Wireless headsets must interface with existing surgical loupe magnification systems from multiple manufacturers, requiring extensive mechanical compatibility testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical LED Headlight Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Wall-mounted, Corded, Wireless Technology: RGB, High Power, Adjustable Brightness, Wireless Connectivity End User: Hospitals, Clinics, Dental Practices, Veterinary Centers Application: Surgeon Illumination, Dental Procedures, Emergency Care, Diagnostics |
| Companies Covered | Karl Storz, Enova Illumination, Integra LifeSciences, Sunoptic Surgical, Stryker, SurgiTel, Excelitas Technologies, KLS Martin Group, Welch Allyn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical LED Headlight Market Trends and Innovations
Wireless connectivity architectures are fundamentally restructuring how surgical illumination integrates with broader operating theater ecosystems, creating new interface standards and procurement evaluation criteria.
LED driver electronics is modularizing around standardized power management chips that enable rapid customization across surgical specialty requirements. Hospital biomedical engineering departments are specifying hot-swappable battery modules to minimize procedure interruption risk. This standardization is modularizing supply chains, allowing original equipment manufacturers to source subassemblies from specialized contract manufacturers rather than maintaining captive production.
REACH substance restrictions are compelling battery pack redesigns to eliminate restricted cobalt compounds and fluorinated polymers from cordless LED headlight assemblies. Manufacturers serving European hospitals are accelerating qualification of alternative cathode chemistries ahead of 2027 enforcement deadlines. Surgical instrument distributors are prioritizing inventory positions that guarantee compliance across their EU MDR-certified product portfolios.
Group purchasing organization contract consolidation is compressing vendor rosters at major hospital networks, favoring suppliers offering full-spectrum surgical illumination portfolios. Independent distributors are losing share to direct manufacturer relationships as procurement departments centralize spend analytics and negotiate enterprise-wide pricing agreements. This concentration is most visible in Germany, where integrated delivery networks now control the majority of LED headlight acquisition decisions.
Medical LED Headlight Market Segmentation
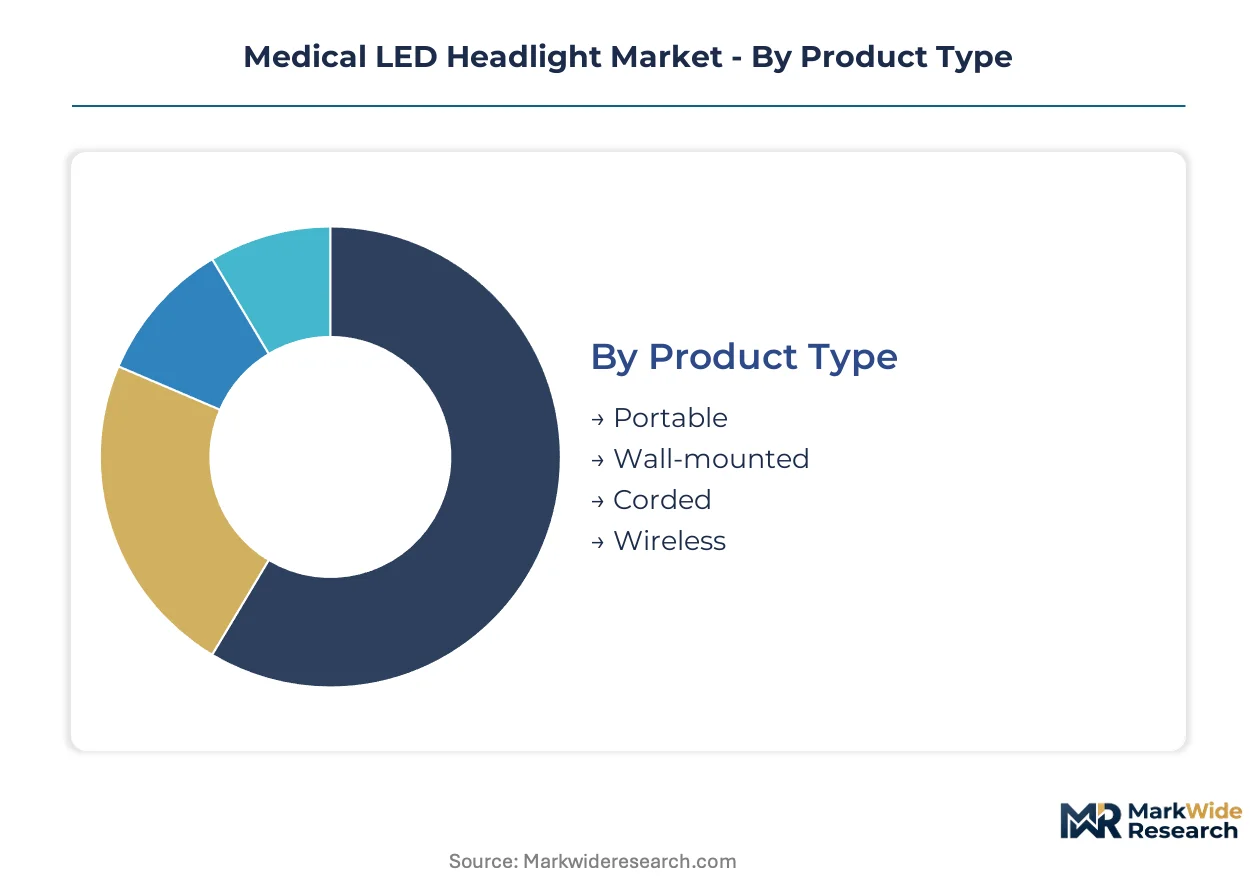
Segmentation in the medical LED headlight market reveals how capital deployment, clinical workflow requirements, and regulatory compliance reshape procurement decisions across surgical environments. Understanding these divisions exposes where manufacturers must concentrate R&D investment and which customer profiles offer the most defensible revenue streams.
Product Type:
Capital intensity varies sharply across these configurations, with wall-mounted systems requiring substantial infrastructure investment while portable units demand lighter upfront outlay but higher lifetime battery replacement costs.
- Portable:Battery-powered headlamps with detachable power packs dominate ambulatory surgical centers and field medical units where electrical infrastructure is unreliable or absent. Demand concentrates in Germany's dense network of outpatient clinics, driven by EU MDR compliance deadlines forcing replacement of non-certified legacy equipment. Lithium-polymer cell chemistry advances are compressing weight-to-output ratios, enabling surgical durations exceeding four hours without battery swap.
- Wireless:Fully cordless platforms eliminate cable sterilization protocols and trip hazards from operating theater floors. German hospital procurement departments are prioritizing these systems as integrated delivery networks consolidate vendor rosters around full-spectrum illumination portfolios. The segment absorbs disproportionate engineering talent as optical thermal management challenges intensify with power density gains.
- Wall-mounted:Fixed installations with dedicated power supplies retain presence in capital-intensive surgical suites where procedure volume justifies permanent infrastructure. These systems anchor major teaching hospital networks in the United States where FDA 510(k) predicate pathways streamline regulatory approval for iterative improvements.
- Corded:Traditional tethered designs persist in budget-constrained facilities with functional xenon lamp installed bases, though replacement cycles lengthen as wireless platforms achieve cost parity.
Portable configurations absorb the bulk of installed capacity; wireless platforms are expanding most quickly.
Technology:
Technology selection maps directly to surgical specialty requirements, with color rendering fidelity and thermal management specifications determining suitability for tissue differentiation tasks.
- High Power:Systems delivering 80,000 to 100,000 lux target neurosurgery and orthopedic procedures requiring deep cavity illumination without shadow interference. Demand clusters in German university hospitals where Karl Storz and KLS Martin Group anchor dense surgical instrument manufacturing ecosystems. Thermal dissipation engineering represents the primary development bottleneck as LED junction temperatures must remain below 85°C to preserve tissue safety margins.
- Wireless Connectivity:Bluetooth and proprietary RF protocols enable integration with operating room ecosystem management systems, including battery status monitoring and automated inventory tracking. United States hospital networks are specifying these capabilities in group purchasing organization contracts as biomedical engineering departments centralize device fleet management. The technology is reshaping supplier qualification protocols as cybersecurity validation becomes mandatory for FDA clearance.
- RGB:Multi-wavelength platforms allow spectral tuning for enhanced visualization of vascular structures and tissue perfusion states. These systems serve specialized applications in plastic surgery and dermatology where color discrimination affects procedural outcomes.
- Adjustable Brightness:Dimming circuits with continuous or stepped output control accommodate varying ambient lighting conditions and surgeon preference, representing baseline functionality across most certified platforms.
High Power technology commands the largest revenue share; Wireless Connectivity is climbing the fastest as operating room digitization accelerates.
End User:
End-user segmentation exposes divergent procurement authority structures, with hospital centralized purchasing contrasting against independent practitioner decision-making in smaller clinical settings.
- Hospitals:Integrated delivery networks and academic medical centers wield consolidated purchasing power through multi-year group purchasing organization agreements. German hospital procurement departments are prioritizing ISO 13485-certified suppliers with full EU MDR technical documentation as conformity assessment deadlines approach. These customers demand comprehensive service contracts covering preventive maintenance and rapid battery replacement logistics.
- Dental Practices:Oral surgery and endodontic applications require compact, lightweight headlamps compatible with surgical loupe magnification systems. Demand is expanding in the United States as dental service organizations aggregate practice acquisitions and standardize equipment procurement across regional footprints. Color temperature specifications between 5,000K and 6,500K predominate for accurate shade matching in restorative procedures.
- Clinics:Ambulatory surgery centers prioritize portable configurations with rapid sterilization turnaround capabilities, often operating outside hospital biomedical engineering support structures.
- Veterinary Centers:Companion animal surgical practices represent an underpenetrated channel where LED headlight adoption trails human medicine by approximately five years, creating expansion opportunity for lightweight battery-powered designs.
Hospitals absorb the bulk of installed capacity; Dental Practices are gaining share fastest as practice consolidation accelerates standardization.
Application:
Application segmentation aligns illumination specifications with procedural intensity, from continuous multi-hour surgeries to intermittent diagnostic examinations.
- Surgeon Illumination:General surgery, neurosurgery, and orthopedic procedures demand sustained high-output performance with shadow-free beam profiles. German operating theaters are upgrading these systems as EU MDR clinical evidence requirements render legacy corded platforms non-compliant. Battery hot-swap capability has become a mandatory specification for procurement departments managing high-utilization surgical schedules.
- Dental Procedures:Oral surgery, implantology, and endodontics require compact form factors integrating with loupe-mounted or headband configurations. United States dental schools are specifying these platforms for student training programs, creating downstream brand loyalty effects as graduates enter private practice.
- Emergency Care:Field surgical units and trauma bays prioritize ruggedized portable designs with rapid deployment protocols and compatibility with battery chemistries approved for air transport regulations.
- Diagnostics:Examination and minor procedure applications accept lower output specifications, with cost-sensitive procurement favoring corded or basic portable configurations over premium wireless platforms.
Surgeon Illumination retains the largest installed base; Dental Procedures are expanding most quickly as specialty practice volumes rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's medical technology free-trade zones around Tuttlingen and Berlin-Brandenburg concentrate surgical instrument manufacturing, attracting LED headlight suppliers seeking proximity to endoscope producers and hospital procurement networks.
Germany
University hospitals in Berlin and Munich are replacing legacy corded systems with EU MDR-certified wireless platforms ahead of conformity deadlines. The EU MDR's tightened clinical evidence requirements disqualify non-compliant legacy equipment from public hospital tenders. Tuttlingen's surgical instrument cluster hosts Karl Storz and KLS Martin Group, which bundle LED headlights with visualization systems for integrated operating theater contracts.
United States
Ambulatory surgical centers in Texas and Florida are expanding portable LED headlight deployment as outpatient procedure volumes rise. The FDA's 510(k) clearance pathway streamlines regulatory approval for wireless platforms demonstrating substantial equivalence to predicate devices. Minneapolis-St. Paul's medical device corridor anchors Enova Illumination's lightweight battery-powered design operations, serving dental service organizations consolidating regional equipment procurement.
Japan
Metropolitan Tokyo hospitals are specifying hot-swappable battery modules to minimize procedure interruption during high-utilization surgical schedules. METI's medical device quality standards align with ISO 13485 certification requirements that procurement departments mandate for supplier qualification. The Kansai region's precision optics manufacturing base supplies lens assemblies for high-intensity LED platforms targeting neurosurgery applications.
United Kingdom
NHS procurement frameworks are consolidating vendor rosters around full-spectrum surgical illumination portfolios, compressing independent distributor margins. MHRA's post-Brexit medical device regulations maintain alignment with EU MDR standards while establishing separate conformity assessment pathways. London's academic medical centers are upgrading surgeon illumination systems as integrated delivery networks centralize capital equipment acquisition decisions.
India
Corporate hospital chains in Maharashtra and Karnataka are importing ISO 13485-certified wireless platforms as domestic manufacturing capacity for surgical-grade LED drivers remains limited. CDSCO's medical device rules impose registration requirements that delay market entry for uncertified cordless platform manufacturers. Hyderabad's medical technology park is attracting contract manufacturers seeking to assemble battery packs for regional distribution.
Medical LED Headlight Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated endoscope-illumination platforms commanding premium positioning while standalone headlamp suppliers compete on weight-to-output ratios. The vendor base concentrates around three strategic archetypes: vertically integrated surgical visualization conglomerates, lightweight cordless specialists, and optical component contract manufacturers. M&A activity targets battery chemistry and wireless connectivity capabilities, while portfolio diversification into veterinary and dental channels extends addressable markets beyond hospital operating theaters.
Within the integrated visualization tier, Karl Storz anchors German market presence through captive production of endoscope-illumination bundles. Enova Illumination occupies a position among cordless specialists emphasizing surgeon ergonomics. Integra LifeSciences exemplifies the hospital GPO-contract archetype, securing multi-year supply agreements through enterprise-wide pricing structures.
| Leading Market Players |
|---|
| Karl Storz |
| Enova Illumination |
| Integra LifeSciences |
| Sunoptic Surgical |
| Stryker |
| SurgiTel |
| Excelitas Technologies |
| KLS Martin Group |
| Welch Allyn |
| Others |
Pricing and Supply Chain Analysis
Cobalt cathode chemistry costs cascade from Congolese mining concessions through Korean battery cell fabricators into German LED headlight manufacturer procurement tiers, compressing margins at the cordless platform segment while amplifying premium capture for ISO 13485-certified suppliers with captive cell supply.
Pricing Analysis
Lead-time-driven pricing stratification rewards German hospital procurement departments willing to accept 16-20 week delivery windows with standard-tier wireless platforms, while premium positioning commands 40-60% markups for FDA 510(k)-cleared systems available from domestic distributor inventory. Three-tier pricing structure across premium, standard, and economy levels separates EU MDR-certified wireless bundles from basic portable configurations and residual corded equipment. Pricing pressure stems from lithium-polymer cell cost volatility as cobalt concentrate benchmarks fluctuate, with ambulatory surgical centers exhibiting highest price sensitivity against academic medical centers prioritizing hot-swap battery reliability over unit economics.
Supply Chain Analysis
Freight cost absorption from Shenzhen battery pack assemblers through Rotterdam port clearance into Tuttlingen surgical instrument clusters adds 8-12% landed cost burden for cordless platform manufacturers lacking European contract manufacturing partnerships. Optical-grade polycarbonate lens housings concentrate in Japan's Kansai precision optics belt, while LED driver electronics fabrication anchors in South Korean semiconductor foundries. Single-source vulnerability permeates cobalt hydroxide refining capacity, with distribution running through specialized surgical instrument distributors in Germany and direct manufacturer relationships consolidating at United States hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical engineer talent scarcity across surgical-grade thermal management disciplines props pricing power for incumbent LED headlight manufacturers, constraining rapid capacity expansion regardless of demand signals from EU MDR compliance deadlines.
For Market Incumbents: Cement hospital GPO contract renewals through bundled visualization-illumination platform offerings that raise switching costs for Karl Storz and KLS Martin Group accounts. Defend against cordless specialist erosion by acquiring battery chemistry startups with solid-state electrolyte patents, or by backward integration into Korean cell assembly partnerships that secure cobalt offtake ahead of REACH 2027 enforcement. For New Entrants and Emerging Players: Veterinary dentistry practices in the United States represent the most penetrable buyer archetype, trailing human medical LED headlight adoption by five years with minimal incumbent sales presence. Target companion animal surgical centers through lightweight sub-200-gram portable designs with rapid sterilization protocols, leveraging FDA 510(k) predicate pathways for streamlined clearance against established wireless platforms. For Investors and Strategic Acquirers: METI's alignment of Japanese medical device quality standards with ISO 13485 certification requirements is the leading indicator that East Asian procurement consolidation will accelerate, favoring suppliers with multi-regional regulatory dossiers. Position for 5-10 year holding periods around mid-cap specialists with captive thermal management engineering teams and existing CE marking technical documentation, watching for EU MDR notified body capacity constraints as the inflection signal for regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | CE marking dossier completeness determines hospital tender eligibility across German procurement frameworks. |
| Hot-Swappable Battery Module Development | Minimizes procedure interruption risk for high-utilization surgical schedules in Tokyo metropolitan hospitals. |
| Veterinary Channel Distributor Partnership | Captures companion animal surgical practice upgrade cycles lagging human medicine by approximately five years. |
| Solid-State Battery Chemistry Qualification | Eliminates cobalt supply concentration risk ahead of REACH substance restriction enforcement deadlines. |
| Hospital GPO Enterprise Contract Negotiation | Locks in multi-year LED headlight supply agreements through integrated delivery network pricing structures. |
Research Methodology
Multi-period observation of surgical procedure volume trajectories, EU MDR notified body approval timelines, and lithium-polymer cell chemistry cost curves anchored the trend analysis, supplemented by interviews with hospital biomedical engineering directors, surgical instrument procurement managers, GPO contracts specialists, and LED driver electronics contract manufacturers. Secondary validation drew from FDA 510(k) clearance databases, EUDAMED medical device registration filings, Korean customs battery export statistics, and SEC 10-K disclosures from publicly traded surgical instrument conglomerates. Bottom-up installed base modeling triangulated against top-down healthcare capital expenditure forecasts.
Input-output matrices mapped LED junction temperature specifications, battery energy density thresholds, and optical thermal management engineering capacity constraints across the projection horizon. Segmentation dimensions spanned product configuration, power technology, surgical specialty application, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to wireless platform adoption patterns, incorporating lithium-cobalt oxide price elasticity coefficients and hospital infrastructure replacement cycle data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cobalt supply disruption scenarios, EU MDR notified body capacity bottlenecks, and solid-state battery chemistry commercialization timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bariatric Beds Market
Medical Devices
Asia-Pacific Arthroscopy Devices Market
Medical Devices
Cranial Implants Treatment Market
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
MRI Safe Neurostimulation Systems Market
Medical Devices
Coated Endotracheal Tube Market
Medical Devices
Global Medical Loupes Market
Medical Devices
Global Brachytherapy Devices Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
Catheter Systems Market
Medical Devices
Oxygenator Market
Medical Devices
United States Organ Preservation Market
Medical Devices
Biodegradable Stents Market
Medical Devices
Canada Minimally Invasive Surgery Devices Market
Medical Devices
Light Therapy Market
Medical Devices
Sleep Apnea Devices Market