
 Global IVF Devices Market | 2026-2036
Global IVF Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global IVF Devices Market Foresight
Specialty distributor networks serving fertility clinics is rewriting how IVF devices reach end users across mature and emerging markets. CooperSurgical leverages its direct-to-clinic model to control pricing and training attachment rates in North America. Vitrolife anchors European supply through its integrated media and consumables portfolio. Thermo Fisher Scientific competes by extending its analytical instrumentation expertise into embryology workflow automation.
In vitro fertilization devices encompass precision instruments and consumables engineered to maintain gamete and embryo viability outside the human body, with incubators typically holding temperature at 37 degrees Celsius and carbon dioxide at 5 to 6 percent to mimic physiological conditions. These systems enable fertilization, embryo culture, cryopreservation, and pre-implantation genetic screening in clinical reproductive medicine. Culture media commands the largest revenue pool among product types due to recurring purchase cycles and proprietary formulation premiums. Time-lapse imaging technology leads growth within the technology dimension as clinics invest in uninterrupted embryo monitoring to improve selection accuracy. Fertility clinics dominate end-user demand, though hospital-based reproductive centers are gaining share where public reimbursement structures favor integrated care delivery.
The FDA regulates IVF devices as Class II medical products requiring 510(k) clearance for incubators and embryo culture systems, while the EU MDR imposes stricter clinical evidence and post-market surveillance obligations on manufacturers seeking CE marking. ISO 13485 certification serves as a baseline quality management expectation for market access across both jurisdictions. Stakeholders must monitor how evolving single-embryo transfer guidelines and genetic testing reimbursement policies reshape capital equipment replacement cycles and consumables volume forecasts.
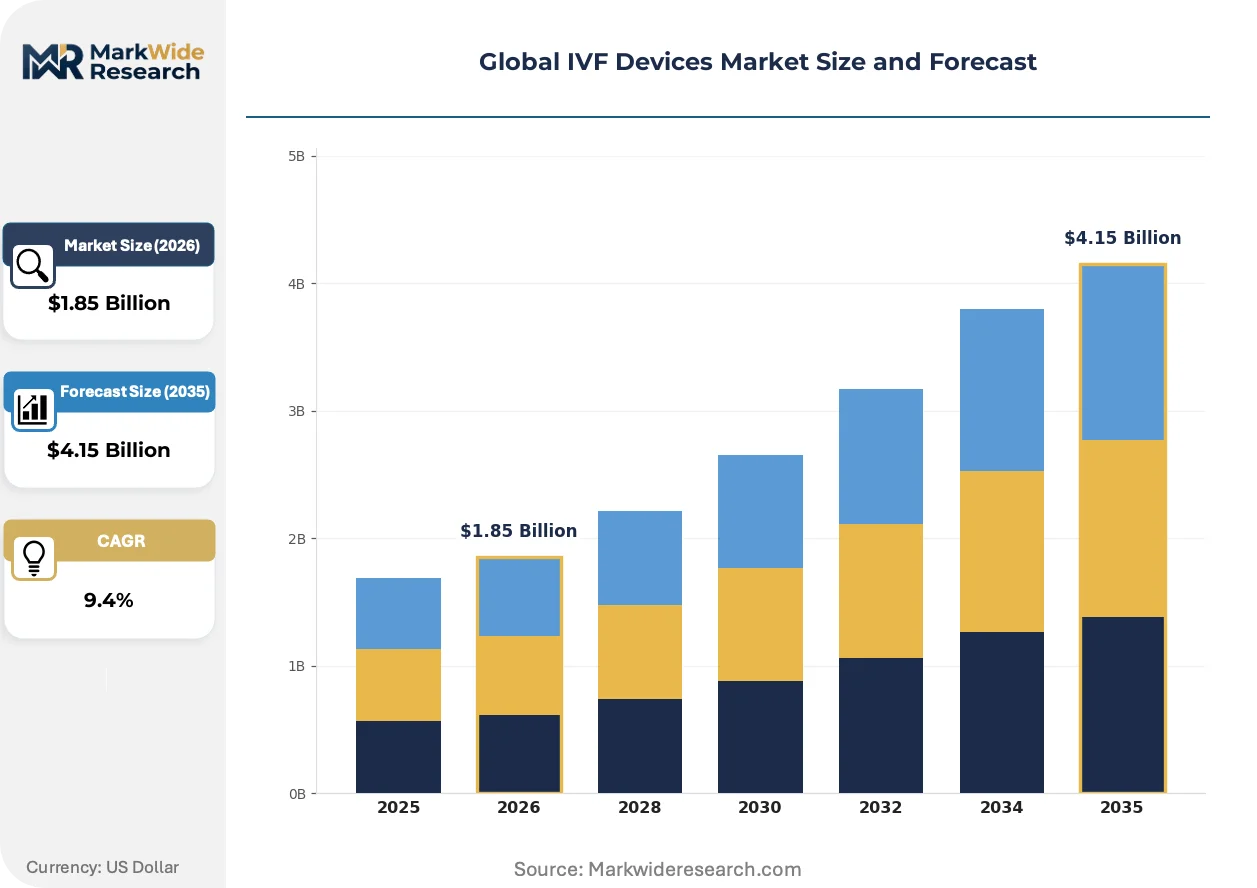
Market Dynamics
The EU MDR's tightened clinical evidence requirements for embryo monitoring equipment is compressing supplier margins while accelerating consolidation among culture media manufacturers seeking CE marking economies of scale.
Growth Catalysts
- Single-embryo transfer protocols:Clinical guidelines in the United States and United Kingdom now favor elective single-embryo transfer, driving demand for time-lapse incubators that improve selection confidence.
- Pre-implantation genetic testing expansion:Fertility clinics in Spain and Denmark are integrating PGT-A workflows into standard IVF cycles, expanding consumables attachment for biopsy tools and genetic analysis kits.
- Public reimbursement extension:France's national health insurance now covers three complete IVF cycles for women under forty-three, directly expanding procedure volumes and device utilization.
Market Restraints
- Culture media raw material concentration:Pharmaceutical-grade water for injection and recombinant albumin suppliers cluster in Germany and Switzerland, exposing manufacturers to single-source risk.
- Incubator energy cost volatility:Continuous 37-degree Celsius operation plus 5-6% carbon dioxide maintenance creates sustained electricity demand vulnerable to European industrial power pricing.
- Embryologist training pipeline constraints:The European Society of Human Reproduction and Embryology certifies fewer than four hundred new clinical embryologists annually, capping clinic expansion velocity.
Strategic Opportunities
- India's nascent fertility services:Mumbai and Delhi fertility centers currently operate below fifty percent utilization, presenting capital equipment placement opportunities as domestic reimbursement frameworks mature.
- Artificial intelligence embryo scoring:Deep learning algorithms analyzing time-lapse image sequences are converging with existing incubator hardware, creating software-as-a-service revenue streams.
- Direct-to-clinic consumables platforms:Specialty distributors in Brazil are building e-procurement portals that bypass traditional hospital supply chains, capturing margin previously allocated to intermediaries.
Industry Challenges
- ISO 13485 certification timelines:New market entrants face eighteen-to-twenty-four-month quality management system audits before obtaining CE marking or FDA 510(k) eligibility.
- Legacy incubator integration:Time-lapse imaging modules must interface with installed base incubators from multiple manufacturers, requiring proprietary adapter development and validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IVF Devices Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Incubators, Microscopes, Culture Media, Microinjection Systems, Cryopreservation Equipment, Embryo Monitoring Systems Technology: Time-Lapse Imaging, Laser-Assisted Hatching, Automated Culture Systems, Vitrification, Intracytoplasmic Sperm Injection Application: Female Infertility, Male Infertility, Unexplained Infertility, Pre-implantation Genetic Diagnosis, Fertility Preservation End User: Fertility Clinics, Hospitals, Reproductive Research Institutes, Diagnostic Laboratories |
| Companies Covered | CooperSurgical, Vitrolife, Cook Medical, Merck KGaA, Thermo Fisher Scientific, FUJIFILM Irvine Scientific, Esco Micro, Genea Biomedx, Ferring Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IVF Devices Market Shifts & Advancements
Digital embryo monitoring systems are displacing manual morphological assessment, while regulatory frameworks on both sides of the Atlantic force simultaneous compliance investments.
Time-lapse incubators equipped with continuous imaging is virtualizing the embryologist's workflow, replacing daily manual microscope checks with remote monitoring dashboards. Large clinic networks in the United States are deploying these systems across multiple locations to centralize embryology expertise. This virtualization is compressing the need for on-site senior embryologists at every satellite facility.
Europe's MDR now demands clinical performance studies for embryo culture media and monitoring devices seeking renewed CE marking, where previously technical documentation sufficed. Manufacturers must generate pregnancy outcome data from European clinics, extending product lifecycle management costs. German and Swedish suppliers are absorbing these costs through portfolio rationalization, discontinuing lower-volume SKUs.
Group purchasing organizations now dominate device selection for multi-site fertility networks in the United States, consolidating previously fragmented clinic-level procurement. Independent clinics in Texas and Florida are ceding vendor negotiation autonomy to GPOs in exchange for pricing concessions and standardized training protocols. This concentration is most visible in cryopreservation system purchases, where three GPOs now influence over sixty percent of domestic volume.
Global IVF Devices Market Segmentation
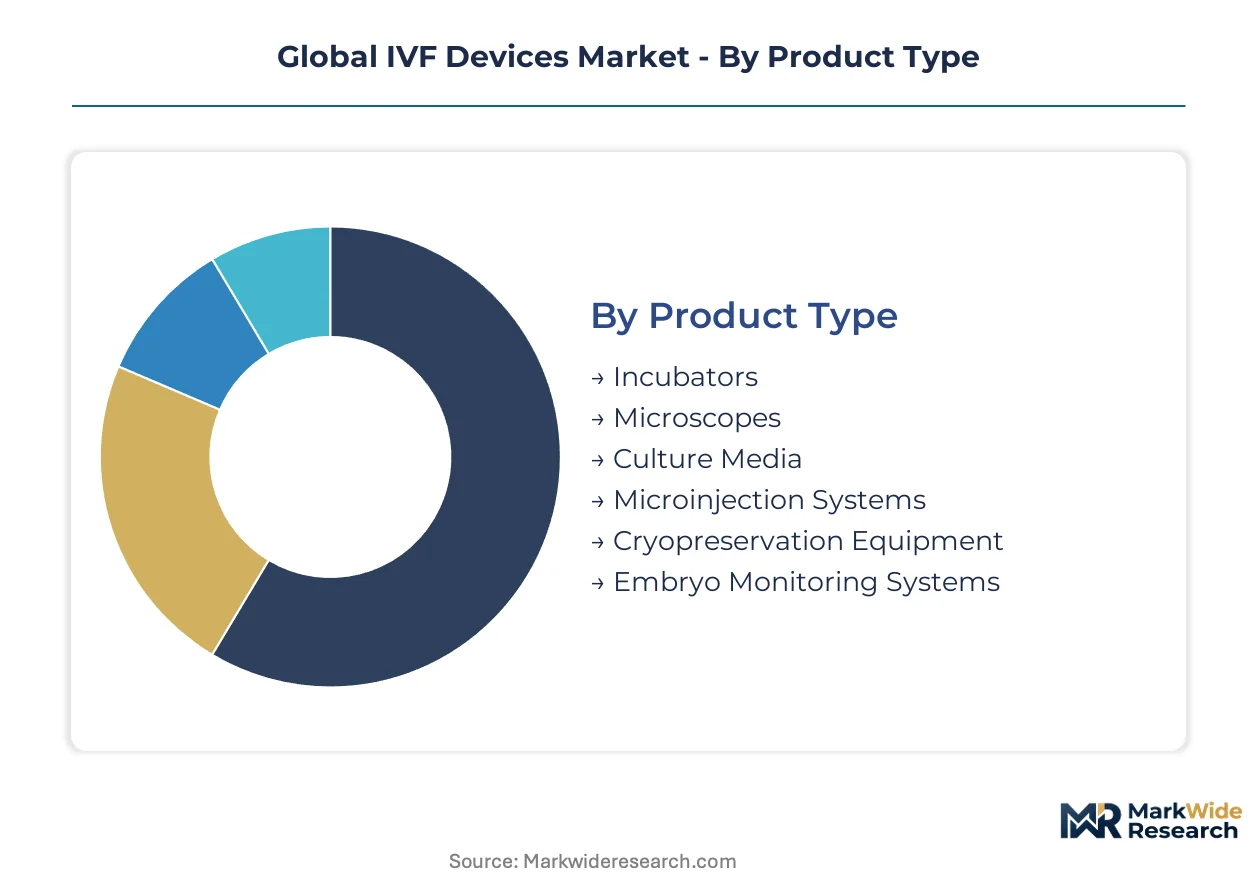
IVF device procurement patterns diverge sharply across product categories. Capital equipment cycles stretch seven to ten years while consumables reorder monthly. Understanding these turnover rhythms clarifies where manufacturers capture recurring revenue versus one-time placement gains.
Product Type:
Culture media turns over fastest with weekly to monthly replenishment cycles, while incubators and cryopreservation systems represent decade-long capital commitments.
- Culture Media:Proprietary formulations of amino acids, energy substrates, and protein supplements maintain gamete viability during extended culture. Fertility clinics in the United States negotiate multi-year supply contracts locking in formulation consistency and volume pricing. The recurring purchase pattern generates predictable revenue streams unmatched by capital equipment categories.
- Incubators:Precision thermal and gas control systems maintain 37 degrees Celsius and 5-6 percent carbon dioxide to mimic physiological conditions. Large clinic networks in Spain and Denmark prioritize uninterrupted imaging compatibility when selecting replacement units. Extended replacement cycles concentrate purchasing power among consolidated provider groups.
- Microscopes:Inverted optical systems with micromanipulation platforms enable embryo visualization and biopsy procedures.
- Microinjection Systems:Piezo-electric or hydraulic micromanipulators facilitate intracytoplasmic sperm injection procedures.
- Cryopreservation Equipment:Programmable freezers and liquid nitrogen storage systems preserve gamete and embryo viability.
- Embryo Monitoring Systems:Integrated hardware-software platforms capture developmental time-lapse sequences.
Culture media anchors the volume base while embryo monitoring systems gain share at the steepest rate.
Technology:
Cost tier stratification separates premium automated platforms from manual alternatives, with reimbursement eligibility determining adoption ceilings.
- Time-Lapse Imaging:Continuous embryo photography without culture dish disturbance enables morphokinetic assessment algorithms. Fertility clinics in the United Kingdom deploy these systems to support elective single-embryo transfer protocols mandated by national guidelines. The technology commands premium pricing justified by improved selection confidence.
- Vitrification:Ultra-rapid cooling protocols using high cryoprotectant concentrations achieve glass-like solidification without ice crystal formation. Spanish fertility centers have standardized this approach for oocyte and blastocyst preservation, driving consumables attachment for specialized cryoprotectant media and storage devices.
- Laser-Assisted Hatching:Pulsed infrared lasers create precise openings in the zona pellucida to facilitate embryo implantation.
- Automated Culture Systems:Robotic liquid handling platforms reduce manual intervention during media exchange protocols.
- Intracytoplasmic Sperm Injection:Micromanipulation technique delivering single sperm directly into ooplasm for severe male factor cases.
Vitrification dominates mature European markets while time-lapse imaging expands most quickly across newly consolidated clinic networks.
Application:
Customer type concentration varies by infertility etiology, with male factor cases clustering at specialized andrology centers.
- Female Infertility:Ovulatory dysfunction, tubal pathology, and advanced maternal age indications drive the majority of IVF cycles. Hospital-based reproductive centers in France handle complex endocrine cases requiring integrated gynecological surgery capabilities. Public reimbursement for three complete cycles directly expands device utilization in this category.
- Pre-implantation Genetic Diagnosis:Embryo biopsy and genetic screening workflows for monogenic disorders or chromosomal structural abnormalities. Danish fertility clinics have integrated PGT-M into standard care pathways for known carrier couples, expanding consumables demand for biopsy tools and genetic analysis reagents.
- Male Infertility:Severe oligospermia and azoospermia cases requiring surgical sperm retrieval and ICSI intervention.
- Unexplained Infertility:Diagnostic category applied when standard evaluations reveal no identifiable cause.
- Fertility Preservation:Oocyte and sperm cryopreservation for oncology patients or elective deferral of parenthood.
Female infertility anchors the volume base while pre-implantation genetic diagnosis climbs the fastest as screening protocols standardize.
End User:
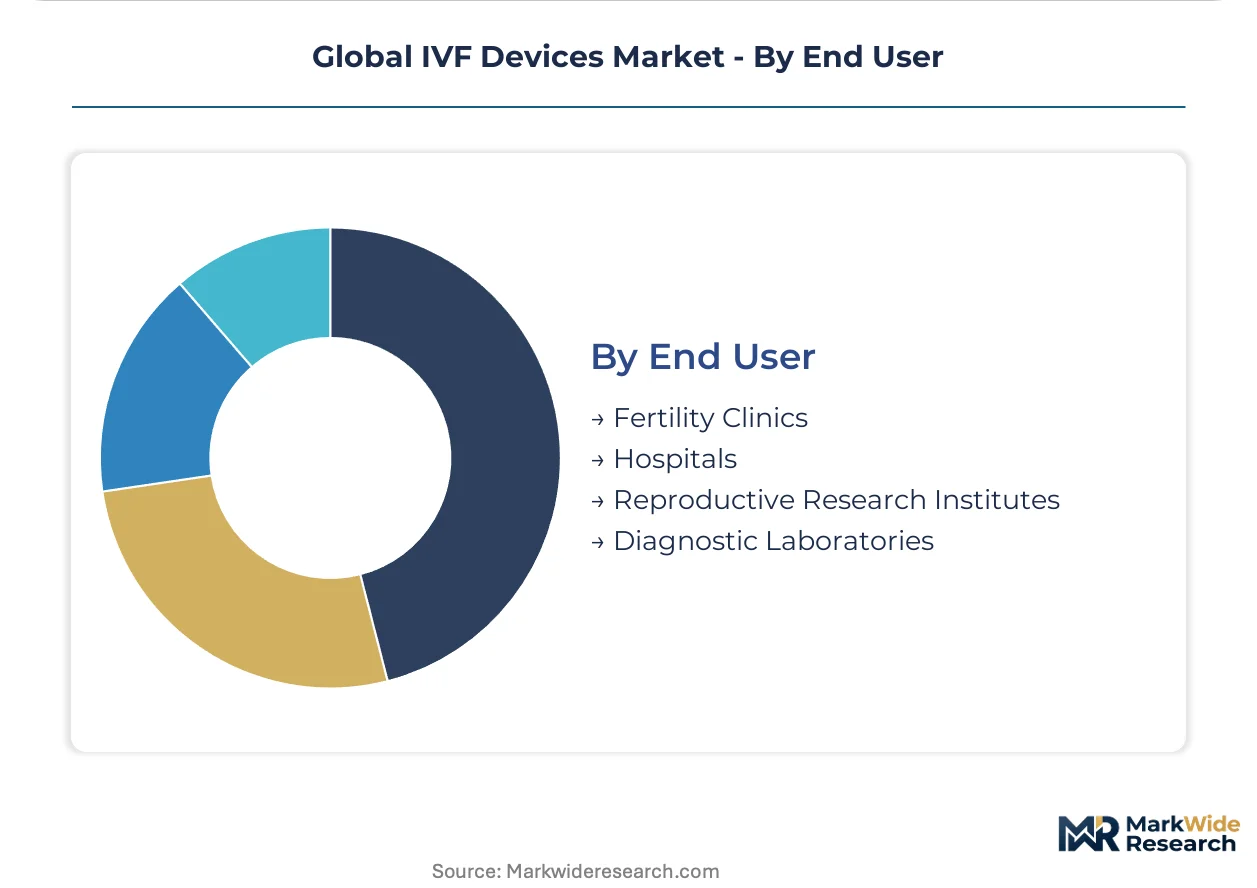
Supply concentration favors fertility clinics with dedicated embryology laboratories over general hospital infrastructure.
- Fertility Clinics:Specialized reproductive medicine centers with in-house embryology laboratories and procedure suites. Independent clinics in Texas and Florida increasingly delegate procurement decisions to group purchasing organizations in exchange for standardized training and pricing concessions. This concentration reshapes vendor negotiation dynamics across the United States.
- Hospitals:Academic medical centers and community hospitals integrating reproductive services within broader women's health departments. Public reimbursement structures in France favor hospital-based delivery where complex surgical interventions accompany fertility treatment.
- Reproductive Research Institutes:Academic and industry facilities conducting embryology protocol development and device validation studies.
- Diagnostic Laboratories:Independent facilities processing semen analysis and hormone panels supporting fertility treatment decisions.
Fertility clinics anchor the volume base while hospitals gain share where integrated care delivery attracts public reimbursement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure underwrites Europe's embryo culture media distribution network, connecting German chemical suppliers to fertility clinics across the continent.
United States
Fertility clinic consolidation into multi-site networks concentrates procurement decisions through group purchasing organizations. FDA 510(k) clearance requirements for incubators and embryo culture systems create regulatory moats for established manufacturers. The Dallas-Fort Worth metroplex anchors domestic demand growth, where independent clinics merge into regional chains to negotiate volume pricing on time-lapse imaging systems.
Germany
Pharmaceutical-grade water for injection and recombinant albumin suppliers cluster in Baden-Württemberg and Bavaria, exposing culture media manufacturers to concentrated raw material sourcing. The EU MDR imposes stricter clinical evidence obligations on embryo monitoring equipment seeking CE marking renewal. Frankfurt's specialized distributor networks serve as the logistics hub for pan-European media distribution.
France
Public reimbursement now covers three complete IVF cycles for women under forty-three, directly expanding procedure volumes and device utilization. ANSM enforces post-market surveillance requirements on embryo culture media manufacturers. The Île-de-France region concentrates hospital-based reproductive centers where integrated care delivery attracts state funding.
Spain
Fertility clinics in Barcelona and Madrid have standardized vitrification protocols for oocyte and blastocyst preservation, driving consumables attachment for specialized cryoprotectant media. National guidelines favor elective single-embryo transfer, accelerating time-lapse incubator adoption. The Catalan cluster leads PGT-A workflow integration into standard IVF cycles.
India
Mumbai and Delhi fertility centers currently operate below fifty percent utilization, presenting capital equipment placement opportunities as domestic reimbursement frameworks mature. CDSCO regulates IVF devices as medical products requiring import licensing for foreign manufacturers. Maharashtra's private clinic networks are building in-house embryology capabilities to shorten patient cycles and reduce outbound medical tourism.
Global IVF Devices Market Competitive Landscape
On the supply side, the industry is consolidating around integrated media-and-instrumentation portfolios, with culture media recurring revenue anchoring financial stability while capital equipment placement drives market share. Three archetypes dominate: full-spectrum reproductive health conglomerates, specialized embryology consumables pure-plays, and analytical instrumentation giants extending into workflow automation. Competitive moves center on direct-to-clinic distribution control and AI-enabled embryo scoring software licensing.
Within the integrated portfolio tier, CooperSurgical and Vitrolife exemplify divergent geographic anchoring strategies, with the former leveraging North American direct sales infrastructure and the latter consolidating European supply through media formulation expertise. Thermo Fisher Scientific occupies a position at the instrumentation-automation intersection, representing how analytical expertise migrates into embryology workflow design. These three entities illustrate how competitive positioning increasingly depends on controlling both consumables replenishment rhythms and capital equipment replacement cycles.
| Leading Market Players |
|---|
| CooperSurgical |
| Vitrolife |
| Cook Medical |
| Merck KGaA |
| Thermo Fisher Scientific |
| FUJIFILM Irvine Scientific |
| Esco Micro |
| Genea Biomedx |
| Ferring Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Fifty percent utilization at Mumbai and Delhi fertility centers signals acute overcapacity in India's emerging market, compressing capital equipment pricing while forcing suppliers to absorb extended payment terms and bundled training costs to secure placement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with time-lapse imaging systems commanding premium positioning against manual incubator alternatives. Price differentiation hinges on FDA 510(k) clearance tier and volume scale commitments from consolidated clinic networks. Cost compression in standard-tier consumables is intensifying because group purchasing organizations now aggregate demand across multi-site fertility chains. Independent fertility clinics in Texas and Florida exhibit highest price sensitivity, while large European clinic networks in Spain and Denmark prioritize uninterrupted imaging compatibility over unit cost.
Supply Chain Analysis
Pharmaceutical-grade water for injection and recombinant albumin feedstock draws from concentrated German and Swiss chemical suppliers, exposing culture media manufacturers to single-source vulnerability. Raw material dependencies center on amino acid formulations, energy substrates, and protein supplements formulated to proprietary specifications. Tariff exposure on cryoprotectant media imports threatens margin stability for manufacturers serving Latin American markets. Distribution runs through Frankfurt's specialized distributor networks for European fertility clinics, while North American procurement increasingly bypasses intermediaries via direct-to-clinic e-procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
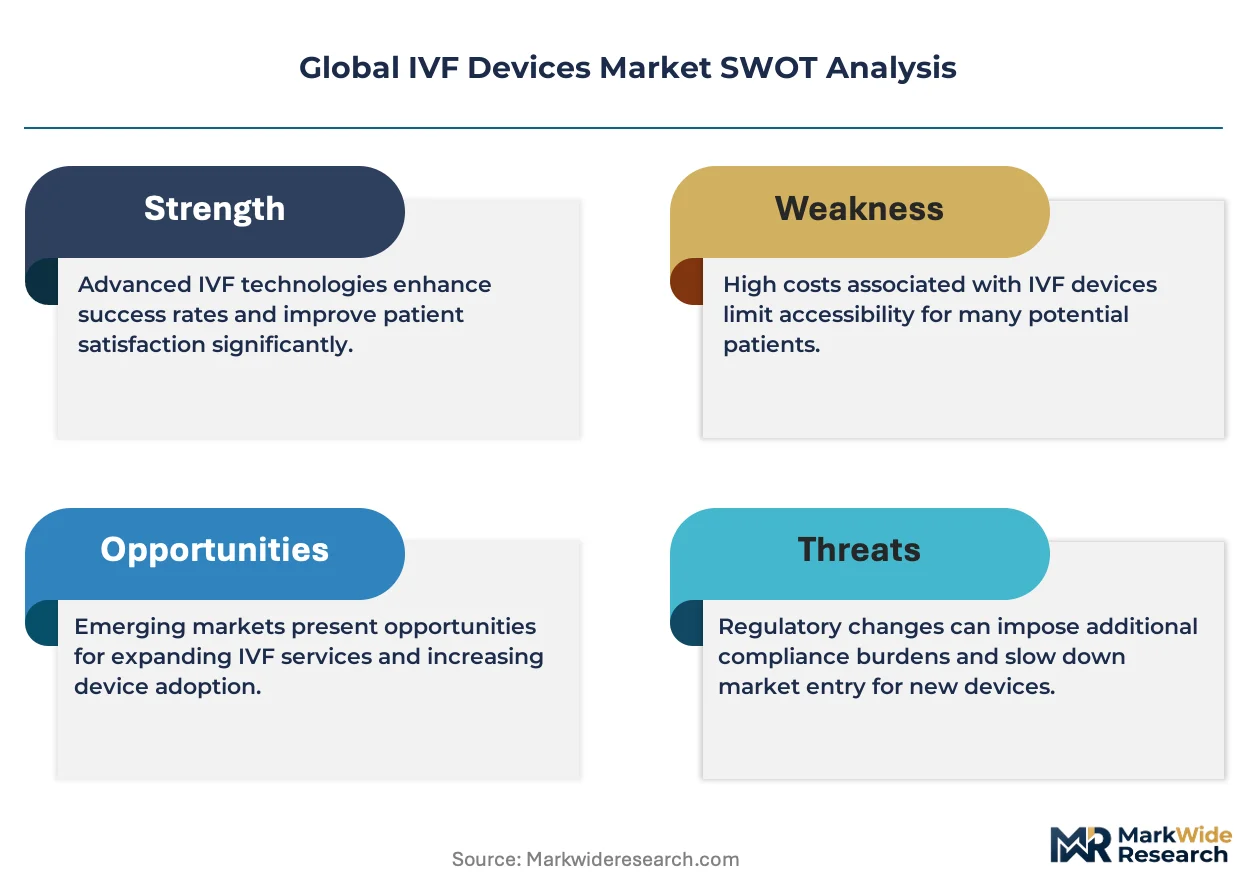
This market functions as a defensive-moat story anchored in regulatory entrenchment, where eighteen-to-twenty-four-month ISO 13485 certification timelines create formidable barriers against unvalidated competitors.
For Market Incumbents: Entrench market position by deepening backward integration into pharmaceutical-grade water for injection and recombinant albumin supply to neutralize German-Swiss raw material concentration risk. Accelerate CE marking renewal investments ahead of EU MDR's tightened clinical evidence requirements for embryo monitoring equipment, using pregnancy outcome data generation to lock out undercapitalized rivals. Channel control through direct-to-clinic training attachment programs represents the critical lever for pricing power preservation. For New Entrants and Emerging Players: India's sub-fifty percent fertility center utilization represents the most penetrable entry point for capital equipment placement, particularly as Maharashtra's private clinic networks build in-house embryology capabilities to capture outbound medical tourism revenue. Brazil's nascent e-procurement portal infrastructure offers a second white-space target, enabling margin capture previously allocated to traditional hospital supply chain intermediaries. A software-as-a-service go-to-market angle—embedding AI embryo scoring algorithms into existing incubator hardware—sidesteps capital-intensive manufacturing barriers while generating recurring revenue streams. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across embryo monitoring systems as EU MDR compliance costs force portfolio rationalization and SKU discontinuation among mid-tier manufacturers. Acquisition targets should profile specialized embryology consumables pure-plays with locked-in multi-year supply contracts and formulation consistency premiums that generate predictable replenishment revenue. The signal to watch is consolidation velocity among culture media manufacturers seeking CE marking economies of scale, which will indicate margin compression inflection points ahead.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR's tightened clinical evidence requirements force simultaneous compliance investments across embryo culture media and monitoring devices. |
| Backward Integration into Raw Materials | German and Swiss pharmaceutical-grade water for injection concentration creates single-source risk requiring captive supply development. |
| Software Companion Development | AI embryo scoring algorithms analyzing time-lapse sequences generate SaaS revenue streams attached to existing incubator hardware. |
| Hospital System Partnership | France's public reimbursement for three complete IVF cycles expands device utilization through hospital-based reproductive centers. |
| Direct-to-Clinic Distribution Control | CooperSurgical's North American model demonstrates pricing and training attachment rate capture bypassing traditional intermediaries. |
Research Methodology
Cross-validation between primary interviews with embryology laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs specialists anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR submission databases, hospital procurement records, and ESHRE certification statistics. Bottom-up demand modeling from fertility clinic procedure volumes and capital equipment replacement cycles triangulates with top-down analysis of manufacturer revenue disclosures and distributor shipment patterns.
Calibration against historical CAGRs from adjacent medical device categories and reproductive health segments informs the projection framework across product type, technology tier, application indication, and end-user facility category. Segmentation dimensions modeled encompass culture media formulation grade, incubator imaging capability level, infertility etiology, and procurement channel structure. Forecast inputs incorporate single-embryo transfer protocol adoption curves, PGT-A workflow integration rates, and public reimbursement expansion trajectories.
Macroeconomic conditions sit as an overlay; deviation in European industrial power pricing, healthcare reimbursement policy, or embryologist training pipeline throughput would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline stability and raw material supply continuity. Cross-checking against ESHRE annual certification statistics and national IVF registry data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
ePTFE Vascular Prosthesis Market
Medical Devices
Lactation Massager Market
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
X-Ray Positioning Devices Market
Medical Devices
Rapid Infuser Market
Medical Devices
Sweden Respiratory Devices Market
Medical Devices
Russia Viscosupplementation Market
Medical Devices
Global Cerebral Somatic Oximeters Market
Medical Devices
Sleep Apnea Implants Market
Medical Devices
Total Artificial Heart Market
Medical Devices
Australia Ultrasound Devices Market
Medical Devices
Atrial Appendage Occluder Market
Medical Devices
Argentina Aesthetic Devices Market
Medical Devices
Endodontic Devices Market
Medical Devices
Self-Injections Market
Medical Devices
Cellular Encapsulation Market