
 United Kingdom General Surgical Devices Market | 2026-2036
United Kingdom General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom General Surgical Devices Market Analytics
A capital-intensity divergence between robotic platform developers and conventional instrument manufacturers is bifurcating the United Kingdom General Surgical Devices Market. Smith & Nephew leverages its Leeds manufacturing base to sustain domestic supply of advanced wound closure and arthroscopy portfolios. CMR Surgical anchors British robotic surgery capabilities through its Cambridge-developed Versius system, competing directly with Intuitive Surgical's da Vinci installations across NHS trusts. B. Braun differentiates via integrated sterile supply chain control spanning German production and UK distribution networks.
General surgical devices encompass precision-engineered instruments manufactured from medical-grade stainless steel, titanium alloys, and polymer composites, designed to cut, grasp, coagulate, or retract tissue during open, laparoscopic, or robot-assisted procedures. Electrosurgery technology dominates hospital procurement budgets through reusable generator systems and disposable active electrodes that reduce operative blood loss. Robotics technology captures the fastest expansion trajectory as NHS England accelerates access to minimally invasive platforms in cardiac and gastrointestinal surgery. Orthopedic surgery application segments retain mature margin pools from high-volume hip and knee arthroplasty instrument sets.
The UK Medicines and Healthcare products Regulatory Agency enforces post-Brexit UKCA marking requirements that extend conformity assessment timelines for imported devices. NHS England's MedTech Funding Mandate selectively reimburses proven robotic and digital surgical technologies, redirecting capital expenditure toward innovation-qualified suppliers. Stakeholders must monitor MHRA alignment with future EU Medical Device Regulation amendments and NHS procurement framework shifts toward outcome-based contracting models.
Market Dynamics
NHS England's specialist surgical hub consolidation is concentrating capital equipment procurement into fewer purchasing authorities, intensifying vendor competition for multi-year framework agreements while elevating technical service requirements.
Growth Catalysts
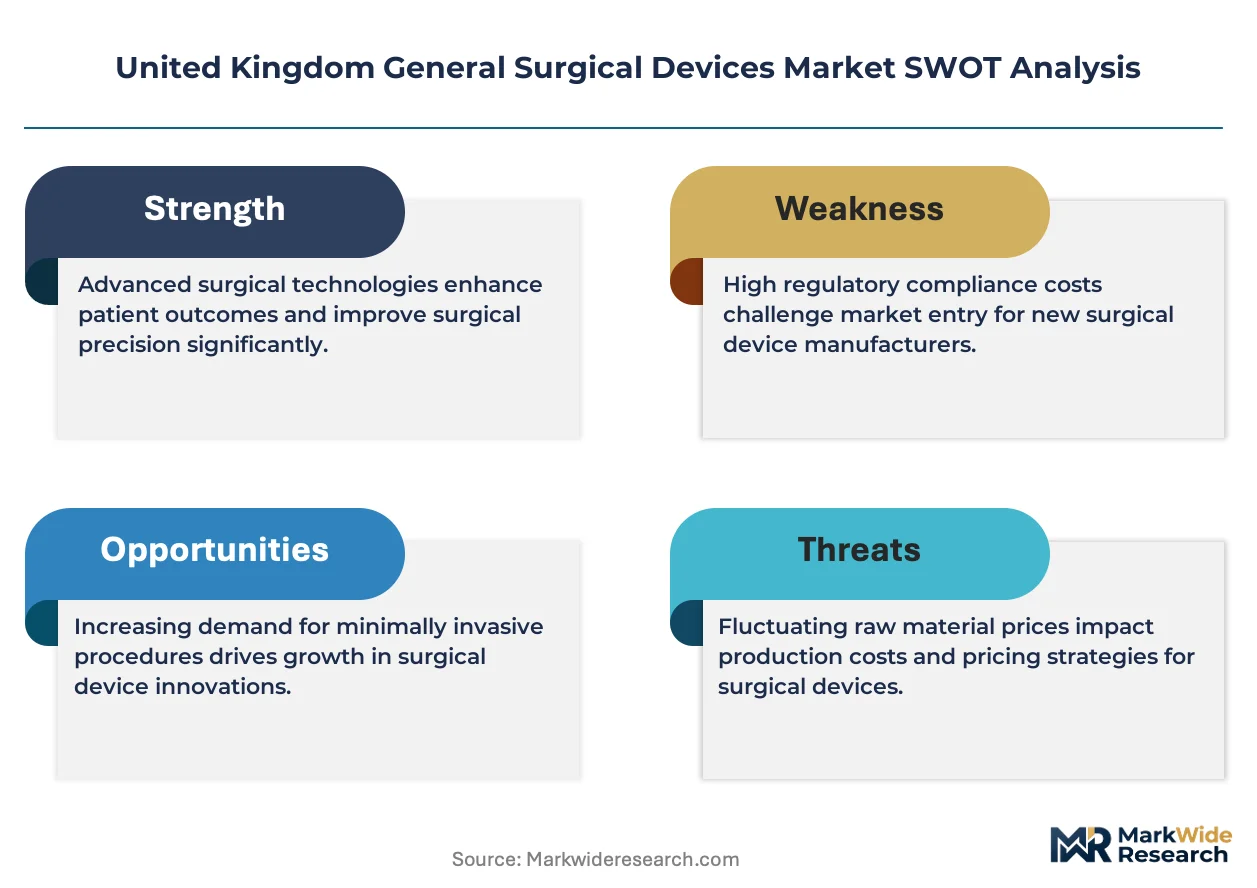
- MedTech Funding Mandate:NHS England's selective reimbursement mechanism accelerates hospital adoption of proven robotic platforms, directing capital flows toward innovation-qualified device suppliers.
- England:Specialist surgical hub networks in Manchester, Birmingham, and London concentrate high-volume procedures, creating demand density for advanced electrosurgical and laparoscopic instrument suites.
- Robot-assisted surgery:Minimally invasive platforms reduce patient recovery times and hospital bed days, aligning with NHS operational efficiency targets and elective surgery backlog reduction priorities.
Market Restraints
- UKCA marking timelines:Post-Brexit conformity assessment extensions delay market entry for imported devices, compressing revenue recognition windows for non-domestic manufacturers.
- Medical-grade stainless steel:Raw material price volatility and alloy supply concentration in German and Chinese mills squeeze instrument margin structures.
- Conventional open surgery:Established procedural workflows and surgeon training pathways slow substitution rates for advanced minimally invasive alternatives in district general hospitals.
Strategic Opportunities
- Wales and Northern Ireland:Underpenetrated peripheral regions present whitespace for mobile robotic surgery units and hub-and-spoke service delivery models.
- Digital surgery integration:Convergence of intraoperative imaging with AI-powered navigation creates premium positioning for next-generation instrument platforms.
- Outcome-based contracting:NHS procurement pilots reward demonstrated clinical outcomes, enabling vendors to capture value through risk-sharing arrangements rather than capital sales alone.
Industry Challenges
- Robotic surgery specialist training:Procedural complexity and credentialing requirements outpace NHS workforce development capacity, constraining installed base utilization rates.
- Legacy sterilization infrastructure:Compatibility gaps between advanced polymer-composite instruments and existing autoclave systems force capital reinvestment or hybrid supply chain management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom General Surgical Devices Market |
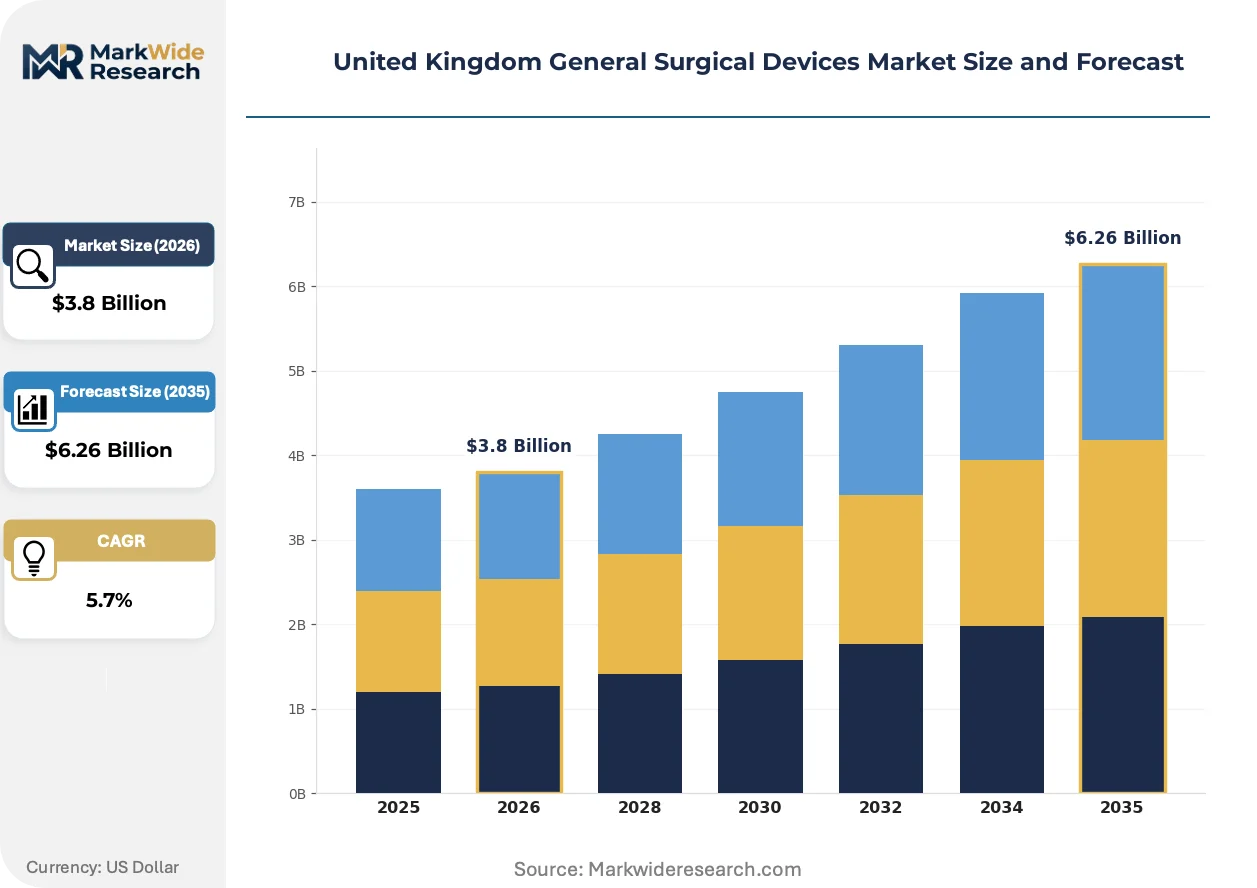
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
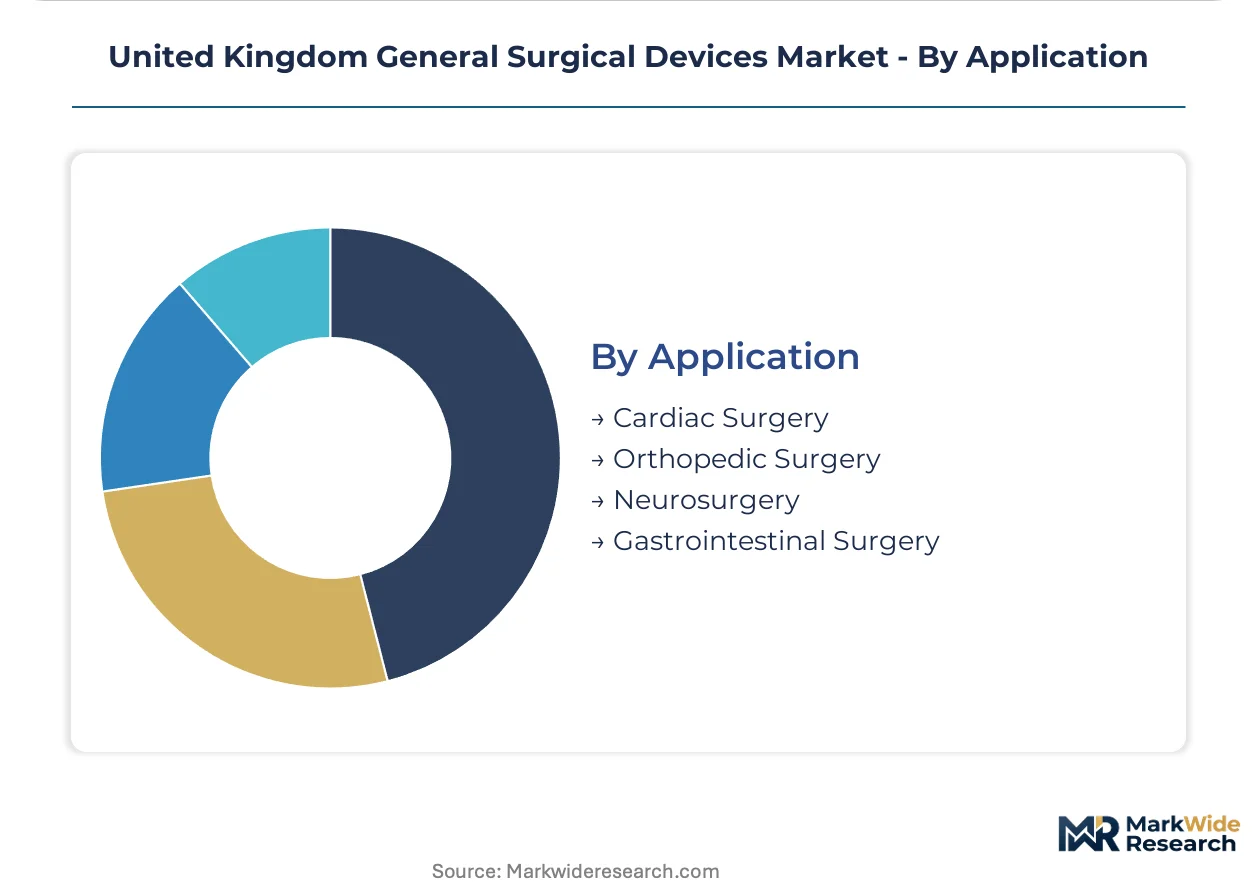
| Segmentation | Product Type: Scalpels, Forceps, Scissors, Hemostats Technology: Electrosurgery, Robotics, Ultrasonic, Laser End User: Hospitals, Ambulatory Surgical Centers, Clinics, Surgical Facilities Application: Cardiac Surgery, Orthopedic Surgery, Neurosurgery, Gastrointestinal Surgery |
| Companies Covered | Smith & Nephew, B. Braun, Intuitive Surgical, Boston Scientific, Johnson & Johnson, CMR Surgical, Medtronic, Olympus, Stryker, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom General Surgical Devices Market Evolving Landscape
Device architecture is fragmenting between premium robotic platforms and commoditized consumables, with software-defined functionality capturing disproportionate value in the surgical workflow.
Single-use polymer-composite instruments with embedded RFID traceability are bifurcating the reusable instrument market. NHS infection control mandates accelerate adoption in orthopedic and general surgery suites. This technology is compressing maintenance service revenue while expanding per-procedure consumable attach rates.
The UK Medicines and Healthcare products Regulatory Agency's phased UKCA implementation extends transitional provisions for CE-marked devices while tightening post-market surveillance requirements. Manufacturers must maintain dual conformity documentation, elevating regulatory affairs overhead. High-risk electrosurgical generators face the most stringent assessment timelines, favoring incumbents with established UK notified body relationships.
Hospital purchasing consortia are consolidating vendor panels and unbundling service contracts from equipment supply. NHS Supply Chain and regional procurement collaboratives in the Midlands and North West now negotiate multi-year total cost of ownership agreements. This behavior concentrates supplier relationships among integrated platform providers capable of delivering training, maintenance, and consumable logistics through single contracts.
United Kingdom General Surgical Devices Market Segmentation
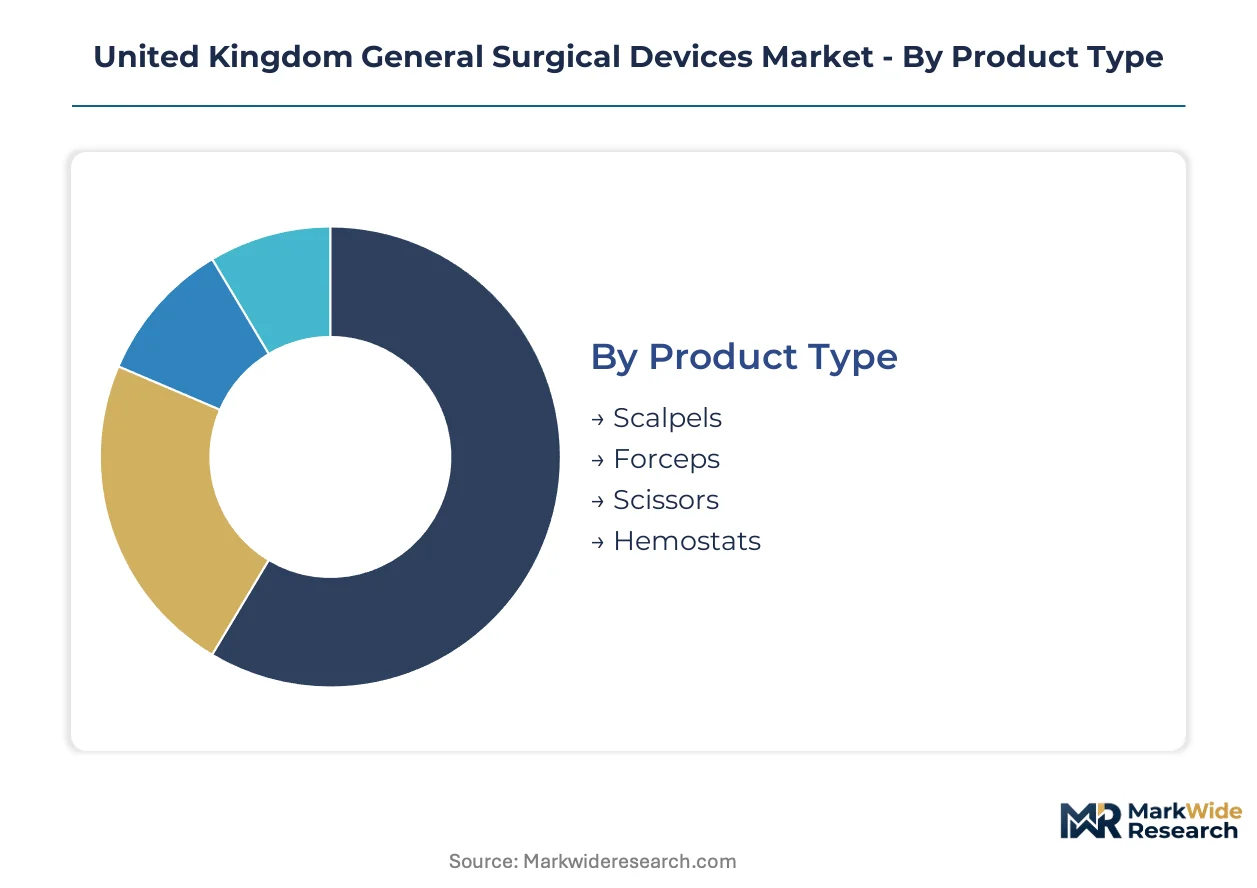
Segmentation in the United Kingdom General Surgical Devices Market reveals how procurement authority concentration and technology substitution pressures reshape competitive positioning. NHS England's hub consolidation and the MedTech Funding Mandate create divergent growth trajectories across product categories and end-use settings.
Product Type:
Scalpels face the most acute substitution threat from electrosurgical and ultrasonic alternatives, while forceps and hemostats retain irreplaceable roles in tissue manipulation. Material composition and reusability economics determine margin structures across these instrument classes.
- Scalpels:Manufactured from medical-grade stainless steel with carbon or ceramic blade coatings, these instruments dominate high-volume general surgery in England's district general hospitals. Disposable safety-engineered variants gain traction from NHS infection control mandates, though reusable handles with detachable blades persist in cost-constrained settings.
- Forceps:Precision-engineered grasping instruments span tissue, dressing, and hemostatic subtypes. Demand concentrates in Manchester and Birmingham surgical hubs for laparoscopic and open procedures, with polymer-composite variants displacing traditional steel in robotic-assisted workflows.
- Scissors:Metzenbaum and Mayo patterns serve dissection across general and specialty surgery.
- Hemostats:Kelly and mosquito clamps retain essential status in vascular control despite electrosurgical coagulation advances.
Forceps anchors the volume base while scalpels gain share at the steepest rate through single-use conversion.
Technology:
Cost tier stratification separates capital-intensive robotic platforms from consumable-heavy electrosurgical systems, with ultrasonic and laser technologies occupying intermediate positions. Procurement pathways diverge between NHS capital budgets and revenue-funded consumable streams.
- Electrosurgery:Generator systems and disposable active electrodes reduce operative blood loss across general, gynecologic, and urologic procedures. NHS trusts in London and the Midlands concentrate procurement of advanced bipolar vessel sealing systems.
- Robotics:Minimally invasive platforms command premium positioning through reduced patient recovery times. CMR Surgical's Versius system competes with Intuitive Surgical installations across NHS England specialist hubs.
- Ultrasonic:Harmonic scalpel technology offers precise cutting with minimal thermal spread.
- Laser:Selective application in ophthalmic and dermatologic procedures limits addressable market scope.
Electrosurgery anchors the volume base while robotics climbs the fastest on MedTech Funding Mandate qualification.
End User:
Customer type determines service intensity requirements, with hospitals demanding integrated training and maintenance contracts while ambulatory settings prioritize instrument portability and rapid turnover.
- Hospitals:NHS trusts and private hospital networks in England drive demand for complete instrument suites with sterilization compatibility and vendor-managed inventory. Multi-year framework agreements with Smith & Nephew and B. Braun consolidate supplier relationships.
- Ambulatory Surgical Centers:Standalone facilities in suburban London and regional cities favor single-use polymer instruments to eliminate reprocessing overhead and accelerate patient throughput.
- Clinics:Minor procedure settings require basic instrument sets with limited capital commitment.
- Surgical Facilities:Specialized ophthalmic and dental surgery centers drive niche demand for microsurgical instruments.
Hospitals anchor the volume base while ambulatory surgical centers expand most quickly on NHS efficiency targets.
Application:
Procedure complexity and reimbursement levels create tiered demand patterns, with cardiac and orthopedic surgery commanding premium instrument specifications and gastrointestinal surgery driving highest procedure volumes.
- Orthopedic Surgery:Arthroscopy and joint replacement instrument sets from Smith & Nephew's Leeds manufacturing base serve high-volume hip and knee arthroplasty. NHS England's elective surgery backlog reduction prioritizes orthopedic hub capacity expansion.
- Gastrointestinal Surgery:Laparoscopic cholecystectomy and colorectal resections generate sustained demand for graspers, staplers, and energy devices across England's specialist surgical networks.
- Cardiac Surgery:Sternotomy and minimally invasive valve repair procedures require specialized retractors and stabilizers.
- Neurosurgery:Cranial and spinal instrumentation demands highest precision specifications with limited addressable volume.
Gastrointestinal surgery anchors the volume base while orthopedic surgery captures premium positioning through arthroplasty instrument set economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
England commands premium pricing leverage over Scotland and Wales through NHS England's consolidated procurement authority and specialist surgical hub concentration. Scotland and Northern Ireland operate under devolved health budgets with fragmented purchasing power. Regional disparities in regulatory compliance costs and infrastructure investment deepen this asymmetry.
London and the Southeast
London's specialist surgical hubs in Chelsea, Westminster, and the Royal Free network drive demand for robotic platforms and advanced electrosurgical systems. NHS England's MedTech Funding Mandate prioritizes capital allocation to these centers. The concentration of private hospital networks in Harley Street and Canary Wharf creates dual-track procurement channels.
Midlands
Birmingham and Manchester surgical hubs concentrate high-volume orthopedic and gastrointestinal procedures, generating dense demand for arthroscopy and laparoscopic instrument suites. The Midlands regional procurement collaborative negotiates multi-year framework agreements with integrated suppliers. University Hospital Birmingham anchors training networks for robotic surgery credentialing.
Scotland
NHS Scotland's devolved procurement operates through National Services Scotland with longer assessment timelines for novel devices. Edinburgh and Glasgow maintain tertiary referral centers for cardiac and neurosurgical instrumentation. The Scottish Health Technologies Group evaluates cost-effectiveness before national adoption.
Wales
Underpenetrated relative to England, Wales presents whitespace for mobile robotic surgery units and hub-and-spoke service models. NHS Wales procures through Shared Services Partnership with limited capital budgets for advanced platforms. Cardiff and Swansea university health boards concentrate specialist capacity.
Northern Ireland
The smallest UK market by volume, Northern Ireland sources devices through NHS Supply Chain with extended lead times. Belfast City Hospital and Royal Victoria Hospital maintain core general surgery capacity. Regulatory alignment with GB standards post-Protocol creates compliance complexity for cross-border suppliers.
United Kingdom General Surgical Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the United Kingdom General Surgical Devices Market. Robotic platform developers capture premium positioning through software-defined functionality and training ecosystems, while conventional instrument manufacturers defend share through sterile supply chain scale and reprocessing service contracts. The market structure bifurcates between integrated platform providers and specialized component suppliers. Dominant competitive moves include multi-year NHS framework agreements and outcome-based contracting pilots.
Among UK-based developers, CMR Surgical occupies a position exemplifying domestic robotic surgery capabilities through its Cambridge-developed Versius system. Smith & Nephew anchors the conventional instrument tier with its Leeds manufacturing base sustaining domestic supply chains. B. Braun sits within the integrated supply chain archetype, spanning German production and UK distribution networks.
| Leading Market Players |
|---|
| Smith & Nephew |
| B. Braun |
| Intuitive Surgical |
| Boston Scientific |
| Johnson & Johnson |
| CMR Surgical |
| Medtronic |
| Olympus |
| Stryker |
| Others |
Value Network & Pricing Analysis
Single-use polymer-composite instruments displacing reusable stainless steel sets are rerouting supply chains from German and Chinese alloy mills toward medical-grade polymer extrusion facilities in Ireland and the Netherlands while compressing per-procedure pricing through eliminated reprocessing labor.
Pricing Analysis
Configured-to-order pricing for robotic instrument arms carries a 40-60% premium over standard electrosurgical generator configurations. The dominant structure runs through multi-year total cost of ownership contracts bundling capital equipment, consumables, and training services. Price differentiation rests on MHRA UKCA certification tier and after-sales service intensity. Cost compression in conventional reusable instruments is intensifying because NHS Supply Chain consolidates vendor panels. District general hospitals exhibit highest price sensitivity; London specialist hubs prioritize clinical outcome metrics over unit cost.
Supply Chain Analysis
Inventory lead times for electrosurgical generators extend 8-14 weeks due to semiconductor component constraints in German and Taiwanese fabrication facilities. Geographic supply concentration centers on Germany for precision-engineered instruments, China for medical-grade stainless steel feedstock, and Ireland for polymer-composite consumables. Raw material dependencies include cobalt-chromium alloys, medical-grade polycarbonates, and rare-earth elements for electrosurgical electrodes. Single-source vulnerability in bipolar vessel sealing chipsets creates procurement risk. Distribution runs through NHS Supply Chain regional distribution centers and private hospital group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom General Surgical Devices Market represents a high-growth disruption as NHS England's MedTech Funding Mandate redirects capital flows toward robotics-qualified suppliers, creating winner-take-most dynamics in specialist surgical hubs.
For Market Incumbents: Consolidate sterile supply chain control through backward integration into polymer-composite manufacturing or captive reprocessing service contracts. Lock in multi-year NHS framework agreements before 2025 procurement cycle renewals. Threat: CMR Surgical's domestic Versius installations erode Intuitive Surgical's installed base. Lever: certification investment in UKCA-marked instrument variants.
For New Entrants and Emerging Players: Anchor in Wales and Northern Ireland's underpenetrated peripheral regions with mobile robotic surgery units and hub-and-spoke service delivery models. Most penetrable segment: ambulatory surgical centers seeking single-use instrument solutions to eliminate reprocessing overhead. Go-to-market angle: AI-powered intraoperative navigation bundled with disposable instrument platforms.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-cap electrosurgical manufacturers lacking robotics portfolios. Long-term viability favors platform-integrated suppliers capable of software-defined functionality capture. Acquisition target archetype: sterile supply chain operators with NHS logistics contracts. Signal to watch: MHRA alignment with EU MDR amendments accelerating conformity assessment consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| UKCA Certification Pathway | Accelerates market access for high-risk electrosurgical generators through established notified body relationships. |
| Hospital System Partnership | Locks in multi-year framework agreements with NHS England specialist hubs in Manchester and Birmingham. |
| Software Companion Development | Enables AI-powered navigation integration with CMR Surgical Versius and competing robotic platforms. |
| Reimbursement Strategy | Qualifies platforms for NHS MedTech Funding Mandate selective reimbursement accelerating capital adoption. |
| Backward Integration | Captures polymer-composite instrument margin through in-house medical-grade polycarbonate extrusion. |
Research Methodology
Desk research of MHRA regulatory filings, NHS procurement databases, and GPO contract disclosures preceded structured interviews with hospital purchasing committee chairs, biomedical engineering directors, and robotic surgery program coordinators. Primary fieldwork combined with secondary validation from trade customs data and medical device registration records. Bottom-up procedure volume modeling and top-down capital expenditure estimates were triangulated against manufacturer shipment disclosures.
Variance decomposition across product type, technology tier, end-user setting, and application specialty shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated NHS elective surgery backlog reduction targets and specialist surgical hub capacity expansion timelines.
Material uncertainties — MHRA regulatory timeline extensions, NHS procurement framework restructuring, and robotic surgery workforce training bottlenecks — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Soft Tissue Market
Medical Devices
Middle East and Africa Electroencephalography Devices Market
Medical Devices
Europe Insulin Pumps Market
Medical Devices
Micro Balloon Catheter Market
Medical Devices
Global Retinoscopes Market
Medical Devices
Global Surgical/Operating Microscopes Market
Medical Devices
Pediatric Home-Use Medical Devices Market
Medical Devices
Chordal Suture Systems Market
Medical Devices
Directed Energy Based Surgical Systems Market
Medical Devices
Chile Respiratory Devices Market
Medical Devices
Posterior Chamber Lens Market
Medical Devices
Mhealth (Mobile Health) Devices Market
Medical Devices
Automated CPR Devices Market
Medical Devices
Diabetic Eye Disease Devices Market
Medical Devices
Global Handheld Bladder Scanner Market
Medical Devices
Chile Ultrasound Devices Market