
 Ultrafiltration Membrane Market | 2026-2036
Ultrafiltration Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrafiltration Membrane Market Intelligence
Market Dynamics
Aftermarket membrane replacement and technical service revenue is rewriting profit structures across the value chain, pulling margin pools away from initial equipment sales toward recurring consumables and field support. DuPont leverages its integrated polymer science capabilities to control critical raw material inputs for hollow-fiber modules. Toray Industries anchors Asian demand through its dominance in precision-engineered PVDF membranes for semiconductor ultrapure water. Veolia competes by bundling membrane assets with long-term operating contracts across European municipal frameworks.
Technology and Segmentation
Ultrafiltration membranes are pressure-driven separation barriers with pore sizes typically ranging from 1 to 100 nanometers, fabricated from polymers such as polyethersulfone and polyacrylonitrile or from sintered ceramic oxides like alumina and zirconia, and they retain macromolecules, colloids, and microorganisms while passing water and dissolved salts. The polymer segment occupies the largest installed base due to lower capital cost and module flexibility, though ceramic variants are capturing high-temperature and aggressive-chemistry applications in food processing and pharmaceutical manufacturing where thermal sterilization is mandatory. Water treatment leads application demand, but biotechnology is recording the fastest specification escalation as single-use bioreactor adoption drives integrity-testing standards.
Regulatory Environment
The EPA enforces membrane performance under the Safe Drinking Water Act and Clean Water Act, while the EU's Drinking Water Directive and REACH chemical registration framework shape product compliance across European supply chains. China's MEE implements stricter effluent limits for industrial zones, directly mandating tertiary membrane treatment for semiconductor and pharmaceutical discharge. Stakeholders must monitor how tightening per- and polyfluoroalkyl substance restrictions in the EU and US will alter fluoropolymer membrane chemistries and supplier qualification pathways.
Market Dynamics
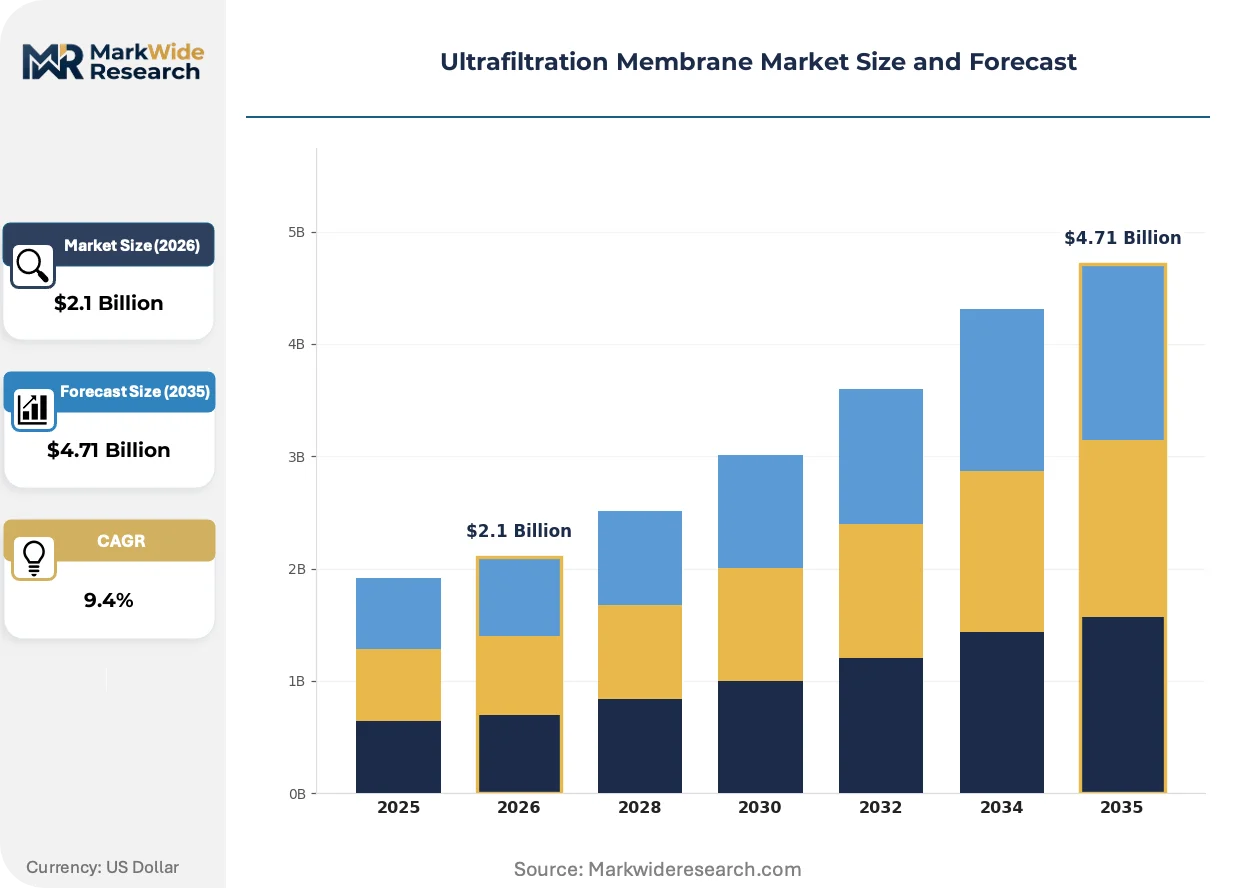
The ultrafiltration membrane market is pivoting toward recurring revenue models as hollow-fiber module lifespans extend and municipal utilities in Germany and the United States prioritize retrofit programs over greenfield installations.
Growth Catalysts
- EU Urban Wastewater Treatment Directive:German utilities are accelerating membrane replacements to meet tightening tertiary treatment mandates for phosphorus and nitrogen removal.
- Semiconductor ultrapure water specifications:fabs in China's Jiangsu province and South Korea's Gyeonggi region are specifying 0.01-micron absolute-rated membranes for advanced node production.
- Polyvinylidene fluoride chemistry advances:modified PVDF surface coatings are reducing irreversible fouling by 40 percent in biopharma protein concentration applications.
Market Restraints
- Fluoropolymer feedstock concentration:three Japanese chemical conglomerates control 70 percent of high-purity PVDF resin supply, creating price volatility exposure for membrane fabricators.
- Thermal sterilization incompatibility:polyethersulfone membranes degrade above 80°C, excluding them from pharmaceutical SIP/CIP protocols where ceramic is mandatory.
- REACH perfluorinated substance restrictions:ECHA's proposed PFAS ban threatens fluoropolymer membrane chemistries and forces qualification of polysulfone alternatives.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO's tightening water-for-injectables standards create first-mover advantage for membrane vendors with USP validation packages.
- Single-use bioreactor convergence:integration of gamma-stable ultrafiltration cassettes with disposable fermentation systems eliminates stainless steel validation costs.
- Direct-to-utility digital channels:membrane manufacturers are bypassing regional distributors to sell replacement modules through e-procurement portals to German municipal purchasing cooperatives.
Industry Challenges
- Integrity testing technician shortage:bubble-point and diffusion-test certification programs are backlogged 12-18 months, delaying biopharma facility startups.
- Legacy SCADA integration:1990s-era municipal plants lack digital protocols for real-time transmembrane pressure monitoring, forcing expensive control system overhauls.
- Patent thickets around surface modification:grafting chemistry IP held by university licensors complicates commercialization of low-fouling membrane variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrafiltration Membrane Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.71 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer, Ceramic, Composite, Others Application: Water Treatment, Food Processing, Pharmaceutical, Biotechnology End User: Municipal, Industrial, Residential, Commercial Technology: Microfiltration, Reverse Osmosis, Membrane Bioreactor, Electrodialysis |
| Companies Covered | DuPont, Toray Industries, Veolia, Pall Corporation, Asahi Kasei Corporation, Kovalus Separation Solutions, Pentair, Mann+Hummel, Hydranautics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrafiltration Membrane Market Strategic Shifts & Innovations
Membrane manufacturing is converging with advanced polymer synthesis and digital monitoring, compressing product lifecycles while elevating performance thresholds for critical separations.
Graphene oxide-polymer composite membranes are rendering obsolete conventional polyethersulfone microfiltration pretreatment in semiconductor ultrapure water trains. Samsung and TSMC fabs in South Korea and Taiwan are piloting these 2-nm-channel structures for particle removal below 10 nanometers. The technology is rendering obsolete multi-stage cartridge filtration and reducing capital footprint by 60 percent in polishing loops.
REACH chemical registration requirements are forcing membrane suppliers to disclose full polymer additive compositions to ECHA, including plasticizers and pore-forming agents previously treated as trade secrets. This transparency mandate is accelerating substitution of legacy phthalate-based additives with bio-derived alternatives in European-sourced modules. German and French pharmaceutical manufacturers are now requiring full material disclosure as a procurement gate.
Buyers are unbundling membrane replacement from OEM service contracts, sourcing third-party validated modules through specialized distributors. This disintermediation is compressing margins for integrated system vendors while expanding addressable market for standalone membrane suppliers with ISO 9001 and NSF 61 certifications. The pattern is most pronounced in North American municipal markets where procurement officers prioritize unit cost over single-source accountability.
Ultrafiltration Membrane Market Segmentation
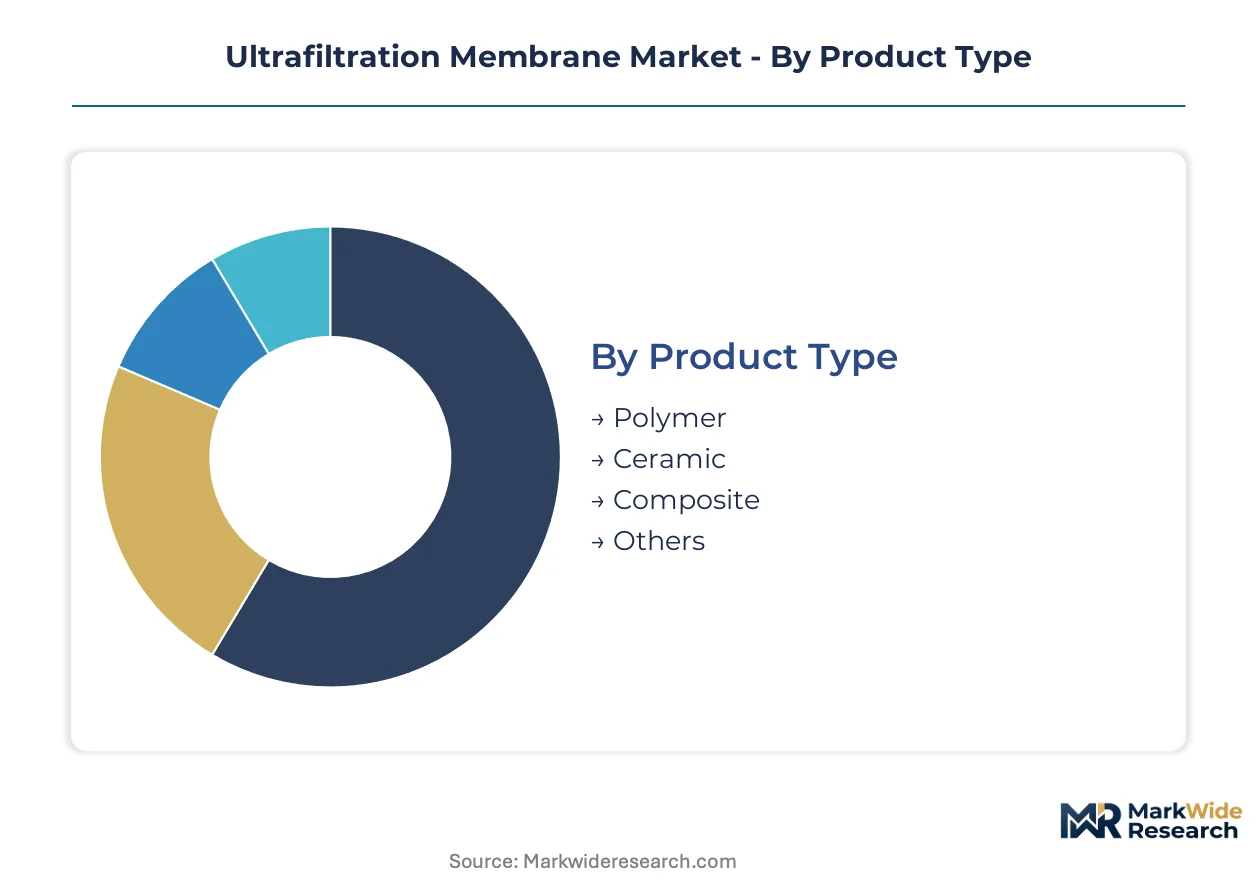
Membrane replacement cycles vary dramatically across material chemistries and end-use applications, creating distinct margin profiles and customer retention dynamics for suppliers. Understanding these turnover patterns allows vendors to calibrate inventory, service contracts, and R&D prioritization against predictable demand pulses.
Product Type:
Polymer membranes turn over fastest in biopharma protein concentration where surface fouling accelerates replacement schedules, while ceramic modules persist for years in food sterilization loops.
- Polymer:Fabricated from polyethersulfone, polyvinylidene fluoride, and polyacrylonitrile, these hollow-fiber and spiral-wound modules dominate municipal retrofit programs in Germany and the United States where capital constraints favor lower first-cost solutions. Replacement intervals compress to 3-5 years in high-fouling surface water feeds.
- Ceramic:Sintered alumina and zirconia structures withstand thermal sterilization above 120°C, anchoring demand from pharmaceutical manufacturers in France and Switzerland requiring SIP/CIP compatibility. Extended 10-15 year lifespans offset 3-4x capital premiums.
- Composite:Graphene oxide-polymer hybrids are displacing conventional pretreatment in South Korean semiconductor fabs.
- Others:Metal-organic framework membranes remain experimental for gas separation crossover applications.
Polymer anchors the volume base while composite gains share at the steepest rate.
Application:
Water treatment commands the largest installed base by unit volume, though biotechnology applications are driving the most rapid specification escalation as single-use systems proliferate.
- Water Treatment:Municipal utilities in the United States deploy hollow-fiber modules for tertiary phosphorus removal under EPA Clean Water Act mandates. German utilities under the EU Urban Wastewater Treatment Directive are accelerating membrane replacements ahead of tightened effluent standards.
- Biotechnology:Single-use bioreactor adoption is forcing gamma-stable ultrafiltration cassette integration with disposable fermentation systems. Integrity-testing protocols now demand 0.1-micron absolute ratings for viral clearance validation.
- Pharmaceutical:Water-for-injectables production in India requires USP-validated modules as CDSCO tightens standards.
- Food Processing:Thermal sterilization requirements favor ceramic membranes for dairy and beverage pasteurization.
Water treatment generates the replacement volume while biotechnology commands the steepest expansion trajectory.
End User:
Industrial customers concentrate procurement authority at headquarters level, compressing sales cycles, whereas municipal purchasing cooperatives fragment decision-making across German Länder and US state boundaries.
- Industrial:Semiconductor fabs in China's Jiangsu province and South Korea's Gyeonggi region specify 0.01-micron absolute-rated membranes for advanced node ultrapure water systems. Procurement teams bundle membrane replacement with long-term operating contracts.
- Municipal:German utilities prioritize retrofit programs over greenfield installations, sourcing replacement modules through e-procurement portals that bypass traditional distributors.
- Commercial:Hospitals and data centers require point-of-use ultrafiltration for critical process water.
- Residential:Point-of-entry systems remain a niche in developed markets with robust municipal infrastructure.
Industrial anchors the premium pricing tier while municipal expands most quickly through retrofit mandates.
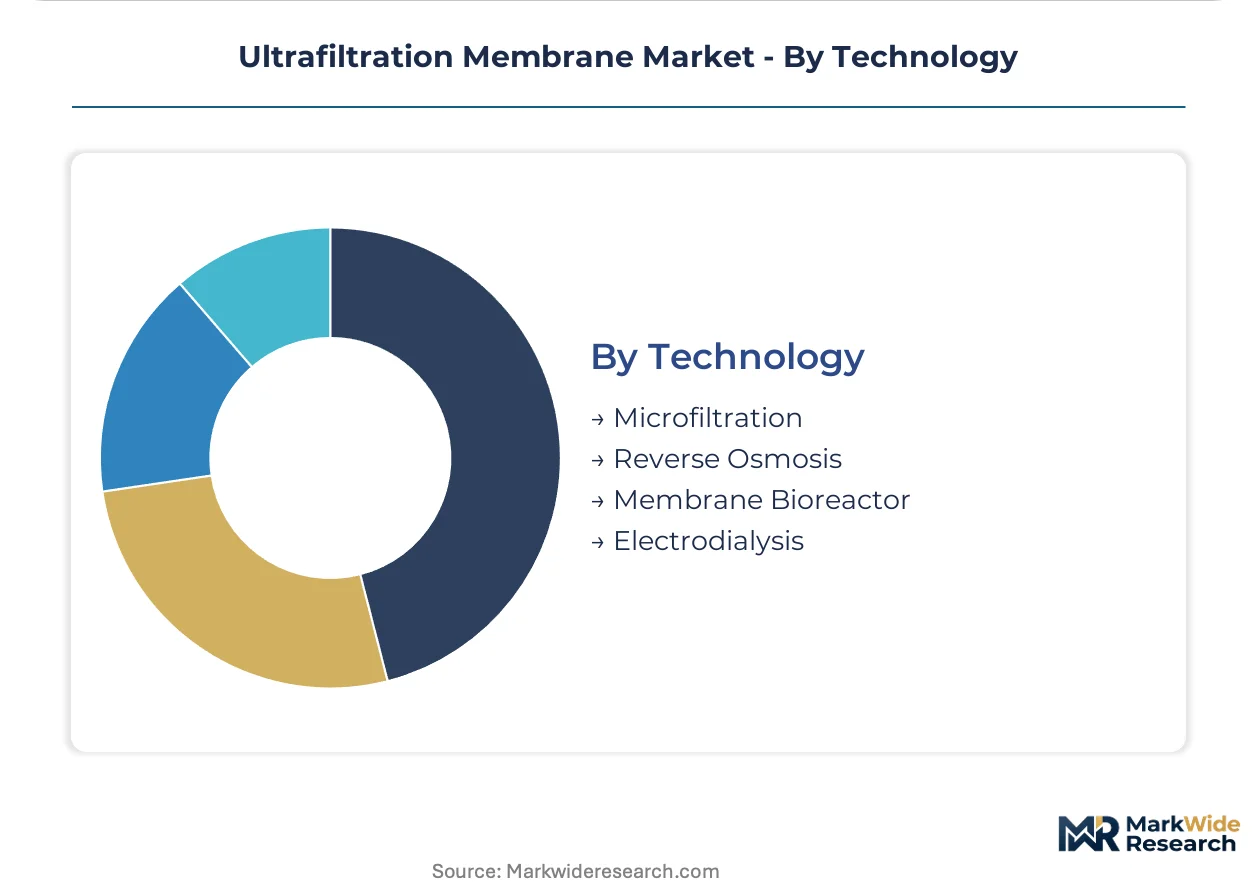
Technology:
Membrane bioreactor integration is displacing conventional activated sludge in space-constrained European plants, while reverse osmosis pretreatment specifications are tightening as feedwater quality degrades.
- Membrane Bioreactor:Combined biological-physical treatment systems achieve tertiary effluent quality in footprint-constrained German municipal plants. Hollow-fiber modules integrate directly into aeration basins, eliminating secondary clarifiers.
- Reverse Osmosis:Seawater desalination pretreatment trains increasingly specify ultrafiltration ahead of RO membranes to reduce particulate fouling in Middle Eastern facilities.
- Microfiltration:Larger pore-size systems serve as cost-effective pretreatment for ultrafiltration polishing loops.
- Electrodialysis:Ion-exchange membrane electrodialysis complements ultrafiltration in specialized brackish water desalination.
Membrane bioreactor anchors the municipal retrofit volume while reverse osmosis pretreatment gains share fastest in industrial desalination.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Membrane consumption patterns diverge sharply across geographies: German utilities prioritize municipal retrofit programs, while Chinese semiconductor fabs drive specification escalation for ultrapure water systems.
United States
EPA Clean Water Act mandates are accelerating membrane replacements at tertiary treatment facilities. Municipal utilities in the Midwest and Southeast are sourcing hollow-fiber modules through e-procurement portals that disintermediate traditional distributors. Procurement officers prioritize unit cost over single-source accountability, compressing margins for integrated system vendors.
Germany
The EU Urban Wastewater Treatment Directive is forcing utilities in North Rhine-Westphalia and Bavaria to upgrade phosphorus and nitrogen removal capabilities ahead of tightened 2027 effluent deadlines. ECHA's proposed PFAS restrictions are simultaneously threatening fluoropolymer membrane chemistries and accelerating qualification of polysulfone alternatives. German pharmaceutical manufacturers now require full material disclosure as a procurement gate.
China
MEE effluent limits for industrial zones directly mandate tertiary membrane treatment for semiconductor and pharmaceutical discharge. Jiangsu province fabs are specifying 0.01-micron absolute-rated membranes for advanced node production. The Yangtze River Delta concentration of biopharma plants is driving demand for gamma-stable ultrafiltration cassettes.
South Korea
Semiconductor ultrapure water specifications are tightening fastest in Gyeonggi region fabs serving Samsung and SK Hynix. Graphene oxide-polymer composite membranes are piloting for particle removal below 10 nanometers. MFDS pharmaceutical water standards are converging with USP validation protocols.
India
CDSCO tightening of water-for-injectables standards is creating first-mover advantage for membrane vendors with USP validation packages. Maharashtra and Gujarat pharmaceutical clusters are upgrading from conventional filtration to integrity-tested ultrafiltration systems. BIS certification requirements are raising barriers for unvalidated imports.
Ultrafiltration Membrane Market Key Industry Players
Capability concentration sits with integrated polymer science specialists; scale advantage sits with diversified environmental engineering conglomerates. The market structures around three tiers: hollow-fiber module fabricators controlling critical raw material inputs, precision-engineered membrane specialists serving semiconductor ultrapure water, and bundled service providers anchoring European municipal frameworks. Dominant competitive moves include backward integration into high-purity resin supply and bypass of regional distributors through direct e-procurement channels.
Within the integrated materials tier, DuPont exemplifies captive control over polymer inputs for hollow-fiber production. Toray Industries occupies a position as the precision-engineered PVDF specialist anchoring Asian semiconductor demand. Veolia represents the bundled service archetype, competing through long-term operating contracts across European municipal frameworks rather than standalone module sales.
| Leading Market Players |
|---|
| DuPont |
| Toray Industries |
| Veolia |
| Pall Corporation |
| Asahi Kasei Corporation |
| Kovalus Separation Solutions |
| Pentair |
| Mann+Hummel |
| Hydranautics |
| Others |
Cost & Logistics Intelligence
PVDF resin concentration among three Japanese chemical conglomerates creates price volatility exposure that compresses margin spreads between premium ceramic modules and economy polymer alternatives while forcing membrane fabricators toward backward integration or polysulfone substitution strategies.
Pricing Analysis
Long-term offtake contracts dominate municipal procurement in Germany and the United States, with hollow-fiber module pricing stratifying across USP-validated premium tiers, ISO-certified standard tiers, and economy grades for non-critical applications. Price differentiation rests on certification level and after-sales service bundling rather than raw membrane performance alone. Cost compression in the economy tier intensifies because procurement officers prioritize unit cost over single-source accountability. Municipal buyers exhibit highest price sensitivity, while semiconductor fabs in South Korea and China demonstrate lowest sensitivity due to ultrapure water specification non-negotiability.
Supply Chain Analysis
High-purity PVDF resin production concentrates in Japan, China, and Germany, with membrane fabrication drawing from polyethersulfone feedstocks anchored in Belgian and U.S. polymer science clusters. Raw material dependencies include fluoropolymer resins, sintered alumina powders, and graphene oxide precursors for emerging composite variants. Single-source vulnerability runs through Japanese resin supply for hollow-fiber module fabricators lacking captive polymer capabilities. Distribution runs through specialized technical distributors for biopharma and semiconductor accounts, while municipal procurement increasingly bypasses intermediaries via direct e-procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as the primary defensive moat, with REACH chemical registration and USP validation protocols creating switching costs that lock in incumbent positions across European and North American pharmaceutical supply chains.
For Market Incumbents: Build certification moats by accelerating USP and NSF 61 validation investments ahead of CDSCO tightening in India and MFDS convergence in South Korea. Backward integration into high-purity resin supply insulates margin pressure from Japanese feedstock concentration. Channel control through direct e-procurement portal development captures German municipal replacement demand migrating away from traditional distributors. For New Entrants and Emerging Players: Establish a beachhead in India's pharmaceutical water-for-injectables segment where CDSCO standards are upgrading but incumbent validation packages remain sparse. Target gamma-stable ultrafiltration cassette integration with single-use bioreactor systems as the most penetrable biotechnology application. Pursue distributor partnerships with ISO 9001-certified membrane specialists rather than competing head-to-head against integrated system vendors in municipal retrofit programs. For Investors and Strategic Acquirers: ECHA's proposed PFAS ban reshapes the acquisition landscape toward polysulfone membrane specialists with qualified alternatives to fluoropolymer chemistries. Long-term viability centers on materials science capabilities rather than equipment integration scale. Watch for integrity testing technician certification backlog resolution as the signal indicating biopharma facility startup acceleration and membrane demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Resin Supply | Captive PVDF feedstock insulates Japanese supply concentration risk for hollow-fiber fabricators. |
| USP Validation Package Expansion | CDSCO tightening in India and MFDS convergence in South Korea create first-mover certification advantages. |
| Direct E-Procurement Channel Development | Bypassing regional distributors captures German municipal purchasing cooperative demand migrating online. |
| Gamma-Stable Cassette Integration | Single-use bioreactor convergence eliminates stainless steel validation costs for biotechnology manufacturers. |
| Polysulfone Alternative Qualification | ECHA PFAS restrictions threaten fluoropolymer chemistries and force substitution pathway preparation. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with membrane R&D directors, municipal procurement officers, biopharma process engineers, and semiconductor facilities managers; and secondary validation through EPA enforcement databases, ECHA chemical registration filings, MEE effluent limit notices, and customs trade data for polymer resin imports. Bottom-up module shipment estimates triangulated against top-down water treatment capital expenditure forecasts across the analysis window.
Forecast inputs considered membrane replacement cycle dynamics by material chemistry, regulatory deadline clustering in Germany and the United States, and specification escalation trajectories in semiconductor ultrapure water systems. Segmentation dimensions modeled include product type, application vertical, end-user procurement authority structure, and regional regulatory framework intensity. CAGRs were derived from installed base turnover rates and specification upgrade elasticities rather than greenfield capacity assumptions.
Stress conditions across PVDF resin price volatility, REACH PFAS restriction implementation timing, and semiconductor capital expenditure cyclicality were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and technology substitution rates. Cross-checking against EIA water treatment expenditure benchmarks and SEMI fab equipment forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Membrane Touch Switch Material Market
Membrane Materials
Global Track Etched Membrane Market
Membrane Materials
Global Transfer Membrane Market
Membrane Materials
Microporous Materials Market
Membrane Materials
Membrane Bioreactor Market
Membrane Materials
PVDF Membrane Market
Membrane Materials
Inorganic Ion Exchange Materials Market
Membrane Materials
Bitumen Membrane Sheets Market
Membrane Materials
Global Microfiltration Membranes Market
Membrane Materials
Membranes Market
Membrane Materials
Global Membrane Water and Wastewater Treatment Market
Membrane Materials
Global Polymer Nanomembrane Market
Membrane Materials
Global Chemical Separation Membranes Market
Membrane Materials
Middle East and Africa Ceramic Membranes Market
Membrane Materials
Expansion Vessel Membrane Market
Membrane Materials
Liquid Roofing Market