
 Global Ultrafiltration Market | 2026-2036
Global Ultrafiltration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ultrafiltration Market Foresight
Aftermarket membrane replacement revenue is reshaping profit pools across the ultrafiltration value chain. DuPont leverages its polymer science heritage to dominate hollow fiber chemistry. Toray Industries anchors Asian supply through integrated spinning and module assembly. Pall Corporation specializes in validated pharmaceutical-grade systems that command premium positioning.
Ultrafiltration separates macromolecules and colloids via semipermeable membranes with typical molecular weight cutoffs between 1,000 and 500,000 Daltons, operating at transmembrane pressures below 100 psi to retain proteins while passing salts and solvents. Spiral wound modules lead municipal water treatment for their packing density and low energy footprint, while ceramic membranes capture expanding share in food and beverage processing where thermal sterilization and aggressive cleaning cycles degrade polymers. Hollow fiber modules represent the fastest-growing configuration in biotech and life sciences, driven by single-use adoption and reduced validation burden.
EPA drinking water regulations, FDA process validation requirements under 21 CFR Part 211, and EU MDR device classification standards collectively elevate barrier-to-entry for membrane suppliers serving regulated end users. REACH chemical restrictions and ISO 10993 biocompatibility testing further constrain material selection and supplier qualification pathways. Stakeholders must monitor evolving PFAS treatment mandates and corresponding membrane performance specifications.
Market Dynamics
Single-use membrane systems are compressing validation timelines and redrawing competitive boundaries across pharmaceutical and biotech filtration workflows. This shift is virtualizing capital deployment patterns as drug producers trade stainless steel assets for disposable process trains.
Growth Catalysts
- EU MDR Device Classification:Tighter validation frameworks for biotech filtration systems are mandating documented membrane performance, expanding demand for pre-qualified pharmaceutical-grade modules.
- PFAS Treatment Mandates:EPA drinking water regulations are forcing municipal utilities to retrofit treatment trains with advanced membrane barriers capable of capturing per- and polyfluoroalkyl substances.
- Ceramic Membrane Chemistry:Food and beverage processors in thermal sterilization environments are adopting aluminum oxide and zirconia membranes that withstand aggressive cleaning cycles.
Market Restraints
- Polymer Feedstock Volatility:Specialized polysulfone and polyethersulfone resins face price instability tied to benzene derivative markets, squeezing hollow fiber module margins.
- Asian Supply Concentration:Integrated spinning and module assembly capabilities cluster in Japan and China, creating vulnerability to regional logistics disruptions or trade policy shifts.
- Membrane Fouling Limits:Irreversible protein binding and biofilm formation on polymeric surfaces constrain operational lifespans in high-concentration bioprocessing streams.
Strategic Opportunities
- India Biopharma Expansion:CDSCO regulatory harmonization and PLI scheme incentives are attracting contract manufacturing investment, driving demand for single-use filtration skids.
- Continuous Bioprocessing Convergence:Integration of perfusion cell culture with inline ultrafiltration is virtualizing batch boundaries and enabling real-time release paradigms.
- REACH Chemical Restrictions:Phased limitations on legacy solvent systems are creating openings for aqueous-based membrane cleaning protocols and biodegradable surfactant formulations.
Industry Challenges
- ISO 10993 Biocompatibility Testing:Extended cytotoxicity and sensitization study timelines delay product launches for pharmaceutical membrane suppliers.
- Legacy System Integration:Retrofitting single-use modules into existing stainless steel infrastructure requires custom manifold design and validation protocol redevelopment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ultrafiltration Market |
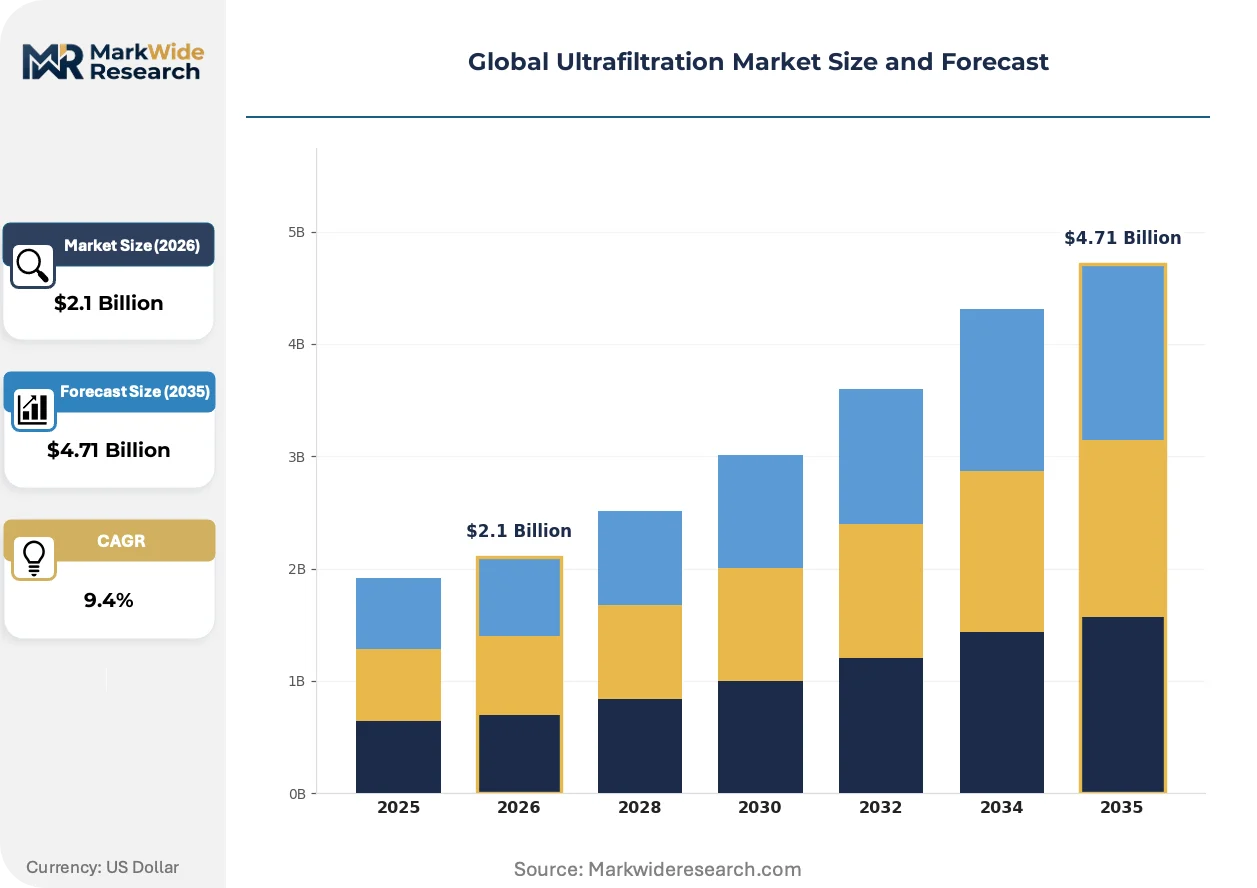
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.71 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Filters, Spiral Wound Modules, Hollow Fiber Modules, Tubular Modules, Ceramic Membranes Technology: Pressure-Driven, Crossflow Filtration, Dead-End Filtration, Dynamic Filtration, Integrated Membrane Systems Application: Water Treatment, Food & Beverage Processing, Pharmaceutical Purification, Chemical Processing, Biotech & Life Sciences End User: Municipal Plants, Beverage Manufacturers, Drug Producers, Chemical Plants, Research Laboratories |
| Companies Covered | SUEZ, Pentair, DuPont, Evoqua Water Technologies, Koch Membrane Systems, Toray Industries, Veolia, Asahi Kasei, Pall Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ultrafiltration Market Shifts & Advancements
Digital process analytics and predictive membrane life modeling are compressing maintenance cycles and enabling condition-based replacement strategies. These capabilities are virtualizing traditional time-based preventive maintenance paradigms.
Tangential flow filtration (TFF) skids equipped with integrated UV-C sterilization are penetrating viral clearance applications previously reserved for nanofiltration or chromatography. Biotech contract manufacturers in Germany and Massachusetts are standardizing on these hybrid systems for monoclonal antibody processes. This convergence is virtualizing the boundary between ultrafiltration and dedicated viral inactivation steps, reducing capital footprint and buffer consumption.
REACH authorization requirements for persistent organic pollutants are constraining perfluorinated membrane chemistries in European medical device applications. Manufacturers are accelerating development of hydrocarbon-based alternatives with comparable hydrophobicity profiles. Germany's chemical processing corridor around Ludwigshafen is emerging as the primary testbed for these next-generation materials.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-sized pharmaceutical firms. Dutch and Swiss biotech clusters are piloting per-liter processing fee structures that bundle membrane modules, technical support, and predictive analytics. This shift transfers operational risk to suppliers while locking in multi-year consumable revenue streams.
Global Ultrafiltration Market Segmentation
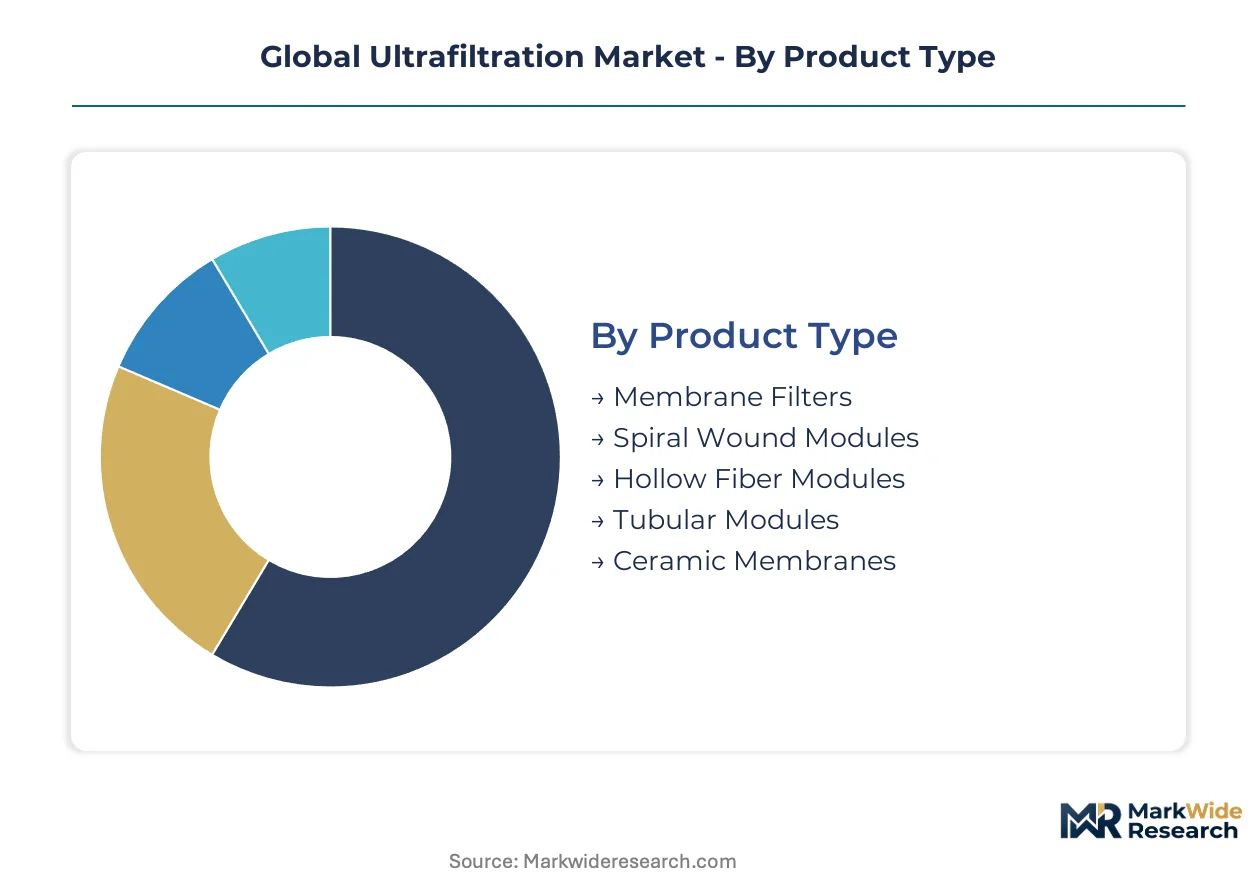
Ultrafiltration technology spans radically different performance requirements across municipal infrastructure, pharmaceutical cleanrooms, and food sterilization environments. Segmentation reveals how membrane chemistry, module geometry, and operating pressure regimes align with specific contamination challenges and regulatory validation burdens.
Product Type:
Spiral wound modules and hollow fiber systems anchor opposite ends of the use-case spectrum, from high-volume desalination pre-treatment to single-use bioprocessing.
- Membrane Filters:Flat-sheet or pleated configurations in polyethersulfone or regenerated cellulose deliver precise molecular weight cutoffs for laboratory-scale separations. Research laboratories in Massachusetts and Basel drive demand for validated, extractables-tested formats.
- Spiral Wound Modules:Polyamide thin-film composites wound around permeate collection tubes achieve the highest packing density in the industry. Municipal plants in California and Singapore specify these for low-energy reverse osmosis pretreatment and surface water polishing.
- Hollow Fiber Modules:Thousands of hair-thin capillaries potted at both ends create inside-out or outside-in flow paths with exceptional surface-area-to-volume ratios. Single-use adoption by drug producers in Germany and Switzerland is compressing validation timelines and displacing reusable stainless steel systems.
- Tubular Modules:Wide-bore ceramic or polymer tubes handle high-solids feeds that would clog narrower channels. Food and beverage processors in Italy and Spain deploy these for wine clarification and whey protein concentration where particulate loading is severe.
- Ceramic Membranes:Sintered aluminum oxide or zirconia structures withstand steam sterilization, aggressive caustic cleaning, and thermal cycling that degrades polymers. Chemical plants along Germany's Ludwigshafen corridor specify these for solvent recovery and catalyst retention.
The dominant share belongs to spiral wound modules, while hollow fiber systems are closing the gap fastest.
Technology:
Cost tiers separate legacy dead-end formats from advanced crossflow and integrated systems that reduce energy and membrane replacement spend.
- Pressure-Driven:Transmembrane pressure as the sole driving force remains the baseline for simple liquid-liquid separations. Small beverage manufacturers in Mexico and Brazil favor these for cost-constrained juice clarification and brewing applications.
- Crossflow Filtration:Tangential flow across the membrane surface shears away fouling layers and sustains flux over extended operation. Biotech contract manufacturers in India and South Korea standardize on these for perfusion cell culture and continuous downstream processing.
- Dead-End Filtration:Perpendicular flow deposits all retained material on the membrane, limiting these to low-solids or batch applications. Research laboratories use disposable capsules for small-volume sterile filtration where throughput is secondary to convenience.
- Dynamic Filtration:Rotating disks or vibrating membranes generate secondary flows that suppress concentration polarization without high crossflow velocities. Food processors in France pilot these for viscous dairy concentrates where pump energy costs dominate.
- Integrated Membrane Systems:Ultrafiltration cascaded with nanofiltration, reverse osmosis, or chromatography in single skid designs. Municipal utilities in Australia and Japan deploy these for advanced water reuse schemes meeting EPA and WHO potable reuse guidelines.
Crossflow filtration commands the largest installed base, though integrated membrane systems are expanding most quickly as water stress intensifies.
Application:
Application segmentation tracks how membrane performance specifications diverge across drinking water safety, pharmaceutical purity, and industrial chemical recovery.
- Water Treatment:Surface water filtration, wastewater tertiary treatment, and seawater reverse osmosis pretreatment constitute the volume foundation. Municipal plants in the US and Singapore size systems for EPA and WHO pathogen log reduction targets.
- Food & Beverage Processing:Protein concentration, enzyme recovery, and beverage clarification demand sanitary design and FDA or EFSA food contact compliance. Dairy cooperatives in the Netherlands and New Zealand specify hygienic modules for whey and lactose fractionation.
- Pharmaceutical Purification:Final formulation filtration, virus clearance, and active pharmaceutical ingredient concentration require documented validation and extractables profiles. Drug producers in Switzerland and Ireland adopt single-use systems to eliminate cleaning validation burden.
- Chemical Processing:Catalyst recovery, solvent purification, and product concentration in aggressive organic media. Petrochemical complexes in Saudi Arabia and Belgium deploy ceramic systems for high-temperature hydrocarbon separations.
- Biotech & Life Sciences:Monoclonal antibody concentration, vaccine purification, and gene therapy vector processing. CDSCO-registered contract manufacturers in India source pre-qualified single-use skids for export-oriented production.
Water treatment retains the dominant share, while biotech and life sciences are climbing the fastest on single-use penetration.
End User:
Customer type determines procurement patterns, with municipal plants prioritizing lifecycle cost and drug producers emphasizing validation documentation and supply security.
- Municipal Plants:Public utilities operating under EPA, EU Drinking Water Directive, or WHO guidelines specify durable systems with 10-15 year membrane life. Procurement in Germany and Japan favors established suppliers with local service networks.
- Beverage Manufacturers:Breweries, wineries, and soft drink bottlers prioritize taste neutrality and sanitary design over absolute retention ratings. Italian and Spanish producers lead adoption of ceramic systems for traditional method sparkling wine.
- Drug Producers:FDA and EMA compliance mandates drive demand for pre-validated, extractables-documented modules. Swiss and German biotech clusters specify equipment-as-a-service contracts bundling consumables and predictive analytics.
- Chemical Plants:Petrochemical and specialty chemical operators balance chemical compatibility against module replacement economics. BASF-Leverkusen and Bayer sites anchor demand for high-temperature ceramic systems.
- Research Laboratories:Academic and government research facilities prioritize flexibility and low capital commitment over scale. NIH-funded labs in Maryland and Cambridge biotech clusters drive demand for disposable capsule formats.
Municipal plants represent the largest revenue pool, though drug producers are gaining share fastest on single-use conversion and premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across geographies. Municipal utilities in developed economies prioritize lifecycle cost and validation documentation, while emerging-market buyers emphasize upfront capital efficiency and local service availability.
United States
EPA drinking water regulations and PFAS treatment mandates are driving municipal retrofit investments. The agency's maximum contaminant level proposals for per- and polyfluoroalkyl substances force utilities toward advanced membrane barriers. Massachusetts biotech clusters around Cambridge standardize on single-use tangential flow filtration for monoclonal antibody production.
Germany
EU MDR device classification tightens validation requirements for pharmaceutical-grade systems. The country's national pharmaceutical regulator enforces documented membrane performance under harmonized European frameworks. BASF-Leverkusen and Bayer sites in the Ludwigshafen chemical corridor anchor demand for high-temperature ceramic membranes in solvent recovery applications.
China
Dual carbon goals and water stress intensification accelerate membrane adoption in industrial wastewater reuse. The Ministry of Ecology and Environment enforces discharge standards that favor advanced treatment trains. Yangtze River Delta municipalities deploy integrated membrane systems for advanced water reuse schemes meeting WHO potable reuse guidelines.
India
CDSCO regulatory harmonization and PLI scheme incentives attract contract manufacturing investment. The national pharmaceutical regulator aligns with FDA and EMA standards for export-oriented production. CDSCO-registered contract manufacturers in Hyderabad and Bangalore source pre-qualified single-use filtration skids for biopharma export growth.
Japan
METI industrial policy supports domestic membrane manufacturing capacity for strategic autonomy. The national standards body maintains JIS specifications for water treatment equipment that exceed baseline ISO requirements. Integrated spinning and module assembly capabilities cluster in Osaka and Nagoya, supplying Asian pharmaceutical and electronics markets.
Global Ultrafiltration Market Competitive Landscape
Capability concentration sits with specialized membrane chemists; scale advantage sits with diversified filtration conglomerates. The market structures around three tiers: integrated polymer science specialists, water infrastructure multinationals, and single-use bioprocessing pure-plays. Strategic moves center on backward integration into polymer resin production and equipment-as-a-service contracting models that lock in consumable revenue streams.
Among water infrastructure multinationals, SUEZ and Veolia exemplify the integrated service-contracting archetype, bundling membrane modules with long-term operational agreements. DuPont and Toray Industries occupy positions on the materials-science vector, leveraging polymer heritage for hollow fiber chemistry control. Pall Corporation sits within the pharmaceutical-grade validation tier, where extractables documentation and pre-qualified formats command premium positioning. These three archetypes—service-integrated, materials-led, and validation-focused—capture distinct profit pools across municipal, industrial, and life science end uses.
| Leading Market Players |
|---|
| SUEZ |
| Pentair |
| DuPont |
| Evoqua Water Technologies |
| Koch Membrane Systems |
| Toray Industries |
| Veolia |
| Asahi Kasei |
| Pall Corporation |
| Others |
Supply & Pricing Matrix
Japan and China hold captive spinning and module assembly capacity for polysulfone and polyethersulfone hollow fibers, concentrating margin capture with integrated polymer science specialists who command premium positioning in pharmaceutical-grade validation tiers.
Pricing Analysis
Aftermarket membrane replacement revenue drives lifetime value across the ultrafiltration value chain. Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and municipal-grade levels separates validated extractables-documented modules from commodity spiral wound systems. Cost compression in hollow fiber modules is intensifying because benzene derivative feedstock volatility squeezes specialized resin margins. Municipal utilities in Germany and Japan exhibit highest price sensitivity due to lifecycle cost procurement mandates, while Swiss and Massachusetts biotech clusters accept premium positioning for single-use validation documentation.
Supply Chain Analysis
Toray Industries and Asahi Kasei anchor contract-manufacturing concentration for integrated spinning and module assembly in Osaka and Nagoya. Ceramic membrane supply draws from Germany's Ludwigshafen corridor and Japan's Nagoya industrial zone, while hollow fiber polymer resins feed from US Gulf Coast and European benzene derivative production. Single-source vulnerability concentrates in Asian logistics corridors serving pharmaceutical contract manufacturers. Distribution runs through authorized distributor networks for municipal infrastructure and direct equipment-as-a-service contracting for biotech clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
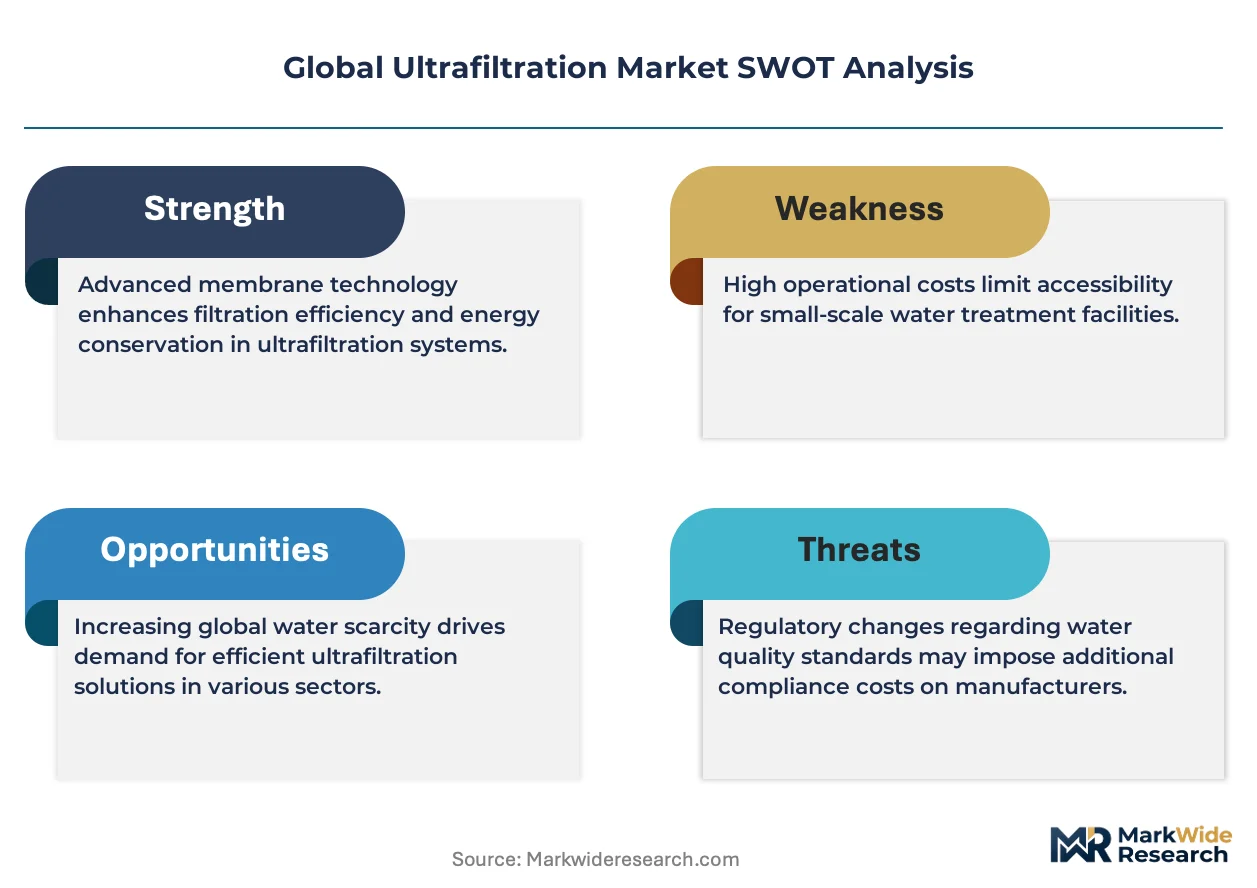
Single-use membrane adoption in biopharma represents early-cycle expansion, with perfusion cell culture convergence and real-time release paradigms accelerating penetration beyond traditional batch processing workflows.
For Market Incumbents: Entrench polymer science leadership by backward integration into specialized polysulfone resin production and captive hollow fiber spinning capacity. Defend against emerging equipment-as-a-service pure-plays by bundling predictive analytics with multi-year consumable contracts. Prioritize ISO 10993 biocompatibility certification investment to extend validation documentation moats around pharmaceutical-grade modules.
For New Entrants and Emerging Players: Build out aqueous-based membrane cleaning protocols and biodegradable surfactant formulations to capture REACH-driven solvent substitution demand in European medical device applications. Target India's CDSCO-registered contract manufacturing clusters with pre-qualified single-use skid offerings. Lead with equipment-as-a-service contracting to bypass capital purchase barriers among mid-sized pharmaceutical firms.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed water infrastructure conglomerates seeking membrane technology tuck-ins to complete service-contracting bundles. Five-to-ten year viability hinges on ceramic membrane chemistry substitution for perfluorinated materials constrained by REACH authorization. Watch PFAS treatment mandate enforcement velocity as inflection indicator for municipal retrofit capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Production | Captive polysulfone supply secures margin control against benzene derivative volatility for hollow fiber manufacturers. |
| Equipment-as-a-Service Contracting Model | Per-liter processing fees lock in multi-year consumable revenue with Dutch and Swiss biotech clusters. |
| Ceramic Membrane Chemistry Substitution | Hydrocarbon-based alternatives replace perfluorinated materials constrained by REACH authorization in German medical device testbeds. |
| Predictive Analytics Platform Development | Condition-based replacement strategies virtualize time-based maintenance for Massachusetts monoclonal antibody producers. |
| India Biopharma Manufacturing Partnership | CDSCO-aligned pre-qualified skids capture PLI scheme-driven contract manufacturing investment in Hyderabad and Bangalore. |
Research Methodology
Operator-level perspectives from membrane module procurement managers, biotech process engineers, municipal utility planning officers, and pharmaceutical regulatory affairs leads anchored the qualitative base. Primary interviews combined with secondary validation from FDA 21 CFR Part 211 filings, EPA drinking water regulation dockets, EU MDR technical documentation, and REACH authorization lists. Customs data on polysulfone resin trade flows and SEC filings from diversified filtration conglomerates provided demand-side triangulation. Bottom-up module shipment tracking and top-down end-use market sizing were cross-referenced for convergence.
Scenario-bracketing framed analytical approach across the analysis window, with segmentation modeled by membrane configuration, technology type, application vertical, and end-user procurement archetype. CAGRs derived from installed base replacement cycles and penetration curve analysis for single-use adoption in bioprocessing. Forecast inputs incorporated EU MDR implementation timelines, PFAS maximum contaminant level proposal trajectories, and CDSCO regulatory harmonization milestones.
Sensitivities concentrate around benzene derivative price volatility, Asian logistics disruption scenarios, and REACH chemical restriction phase-in schedules. Cross-checking against WHO potable reuse guideline adoption rates and IEA water stress intensity indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Membrane Separation Materials Market
Membrane Materials
Asia Pacific Waterproofing Membrane Market
Membrane Materials
Middle East and Africa Ceramic Membranes Market
Membrane Materials
Oxygen Barrier Materials Market
Membrane Materials
Expansion Vessel Membrane Market
Membrane Materials
Ultrafiltration Membrane Market
Membrane Materials
Europe Gas Barrier Membrane Market
Membrane Materials
Liquid Applied Membranes Market
Membrane Materials
TPO Roofing Membrane Market
Membrane Materials
Hollow Fibers Membrane Market
Membrane Materials
Global Waterproofing Membrane Market
Membrane Materials
Oxygen Barrier Films Market
Membrane Materials
US Commercial Restoration Waterproofing Membranes Market
Membrane Materials
Global Ion Exchange Membrane Market
Membrane Materials
PVDF Membrane Market
Membrane Materials
Global Track Etched Membrane Market