
 Europe Membrane Bioreactor (MBR) Market | 2026-2036
Europe Membrane Bioreactor (MBR) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Membrane Bioreactor (MBR) Market Intelligence
Hollow fiber membrane geometries is reshaping how European utilities configure compact wastewater treatment trains for nutrient-sensitive catchments. Veolia Water Solutions & Technologies anchors its position through integrated system design capabilities spanning membrane supply to plant commissioning. Kubota Corporation differentiates via specialized flat sheet membrane manufacturing with roots in Japanese industrial process refinement. Alfa Laval AB leverages its heat transfer heritage to optimize thermal management in high-strength industrial MBR applications.
Membrane bioreactor technology combines suspended growth biological treatment with membrane filtration, typically operating at mixed liquor suspended solids concentrations of 8-15 g/L and employing pore sizes of 0.01-0.4 microns to deliver pathogen-free effluent suitable for direct reuse. Its primary purpose is to eliminate secondary clarifiers while achieving superior treated water quality in footprint-constrained installations. Hollow fiber configurations lead European municipal procurement due to lower specific aeration demands and modular replacement economics, whereas flat sheet membranes occupy premium industrial niches where chemical cleaning tolerance determines lifecycle cost. Integrated systems technology is accelerating fastest as utilities seek single-contractor accountability for performance guarantees.
EMA and ECHA frameworks govern chemical safety in membrane manufacturing supply chains, while the EU Urban Wastewater Treatment Directive and F-Gas Regulation shape operational compliance thresholds for effluent quality and aeration energy intensity respectively. REACH compliance requirements for per- and polyfluoroalkyl substances are forcing membrane suppliers to reformulate coating chemistries and validate alternatives. Stakeholders must monitor how the EU Green Deal's carbon border adjustment mechanism restructures competitive economics for imported membrane modules versus European-manufactured equivalents.
Market Dynamics
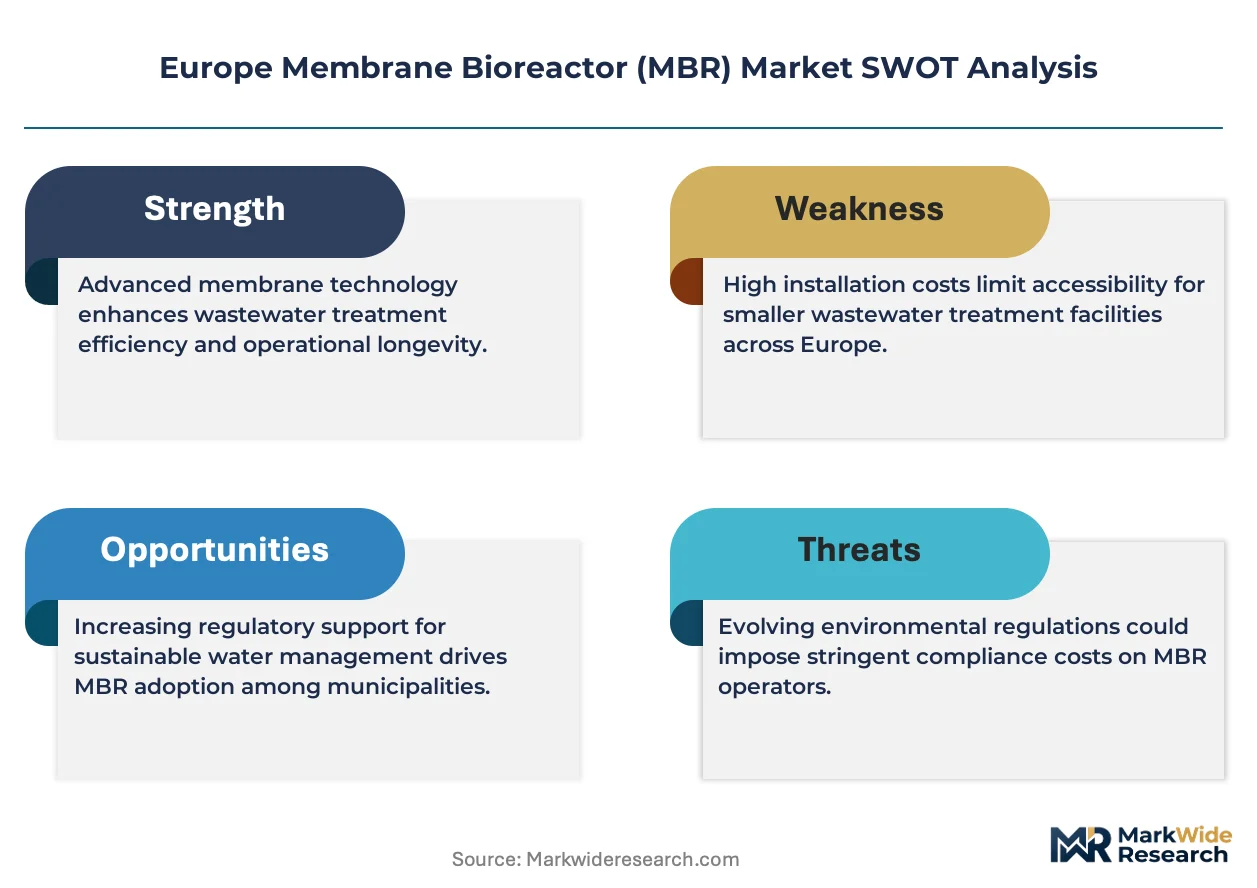
EU Urban Wastewater Treatment Directive revisions are compressing effluent quality timelines across municipal utilities, forcing treatment plant operators to abandon conventional activated sludge trains for membrane-based alternatives that guarantee pathogen removal without secondary clarifiers.
Growth Catalysts
- REACH PFAS restrictions:Membrane suppliers are accelerating coating chemistry reformulation to eliminate per- and polyfluoroalkyl substances, creating replacement demand for compliant module configurations across German and French procurement channels.
- Industrial water reuse mandates:Food and beverage processors in the Netherlands and Belgium face tightening discharge limits that MBR technology satisfies through direct effluent recycling loops.
- Flat sheet membrane durability:Chemical cleaning tolerance advantages in high-strength industrial streams are displacing hollow fiber dominance in pharmaceutical and petrochemical wastewater niches.
Market Restraints
- PVDF resin supply concentration:Polyvinylidene fluoride polymer feedstock for membrane casting concentrates among Asian chemical producers, exposing European module fabricators to shipping cost volatility and tariff exposure.
- Energy intensity thresholds:F-Gas Regulation aeration efficiency standards penalize legacy blower configurations, requiring capital-intensive blower replacement alongside membrane upgrades.
- Conventional SBR substitution:Sequencing batch reactor systems with tertiary filtration offer lower capital outlays for utilities with land availability, constraining MBR penetration in rural catchments.
Strategic Opportunities
- Polish municipal infrastructure:EU cohesion fund allocations for wastewater network completion create first-mover positioning for integrated MBR system contractors in secondary cities lacking treatment capacity.
- CSRD water stress disclosure:Corporate Sustainability Reporting Directive mandates for water consumption transparency are pushing industrial facility managers toward closed-loop MBR installations that eliminate discharge volumes.
- Digital twin integration:Real-time membrane fouling prediction algorithms layered atop SCADA systems are enabling predictive maintenance contracts that extend module replacement intervals.
Industry Challenges
- Membrane integrity testing certification:Pressure decay test protocols for hollow fiber module qualification lack harmonized EU standards, forcing operators to navigate national approval timelines that delay commissioning.
- Specialized process engineering scarcity:Mixed liquor suspended solids optimization for nutrient removal requires expertise spanning biological process design and membrane hydraulics that utilities struggle to staff internally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Membrane Bioreactor (MBR) Market |
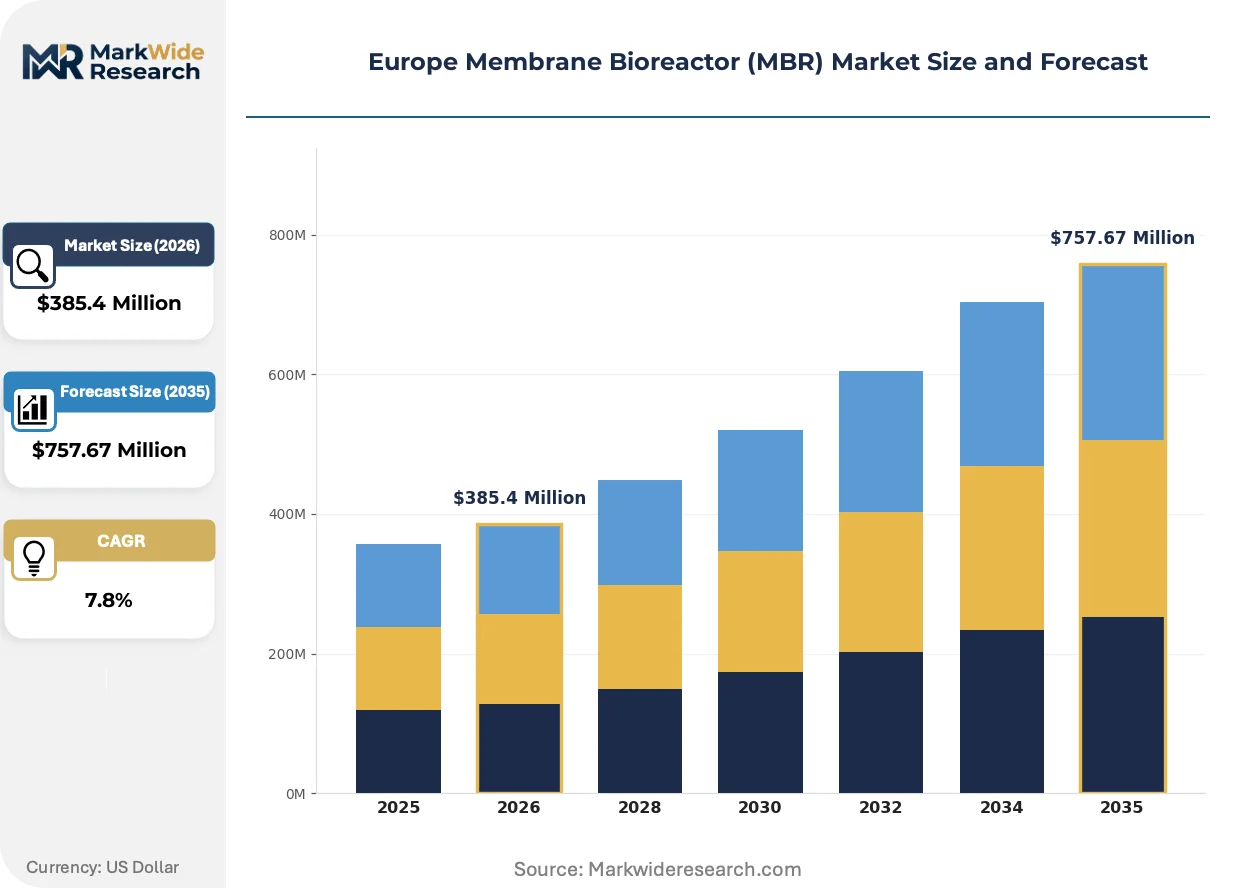
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $757.67 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Sheet, Hollow Fiber, Capillary, Tubular End User: Municipal, Industrial, Hospitality, Residential Application: Wastewater Treatment, Water Reuse, Sludge Management, Nutrient Removal Technology: Crossflow Filtration, Batch System, Continuous Flow, Integrated Systems |
| Companies Covered | Mitsubishi Chemical Corporation, Evoqua Water Technologies LLC, Veolia Water Solutions & Technologies, Asahi Kasei Corporation, Koch Membrane Systems, Inc., SUEZ Water Technologies & Solutions, TORAY INDUSTRIES, INC., Alfa Laval AB, Kubota Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Membrane Bioreactor (MBR) Market Strategic Shifts & Innovations
Membrane bioreactor technology is converging with digital process control and advanced materials science, compressing the traditional separation between biological treatment and filtration engineering disciplines.
Ceramic membrane substrates are migrating from niche industrial applications into municipal pilot installations. Dutch water authorities in Limburg and Brabant are testing alumina and silicon carbide configurations that withstand aggressive chemical cleaning regimes. This material shift is enabling higher mixed liquor concentrations that shrink biological tank volumes by one-third compared to polymeric alternatives.
EU Green Deal carbon border adjustment mechanisms are restructuring competitive economics for imported membrane modules. Chinese and Japanese suppliers face embedded emissions documentation requirements that European fabricators with renewable electricity contracts can satisfy more readily. German engineering procurement offices are now weighting lifecycle carbon intensity alongside unit membrane cost in tender evaluations.
Single-contractor performance guarantees are displacing component-by-component procurement for large municipal projects. French and Italian utilities now require membrane supply, biological process design, and commissioning accountability from unified vendors. This bundling compresses vendor margins while shifting operational risk toward integrated system providers with balance sheet capacity to underwrite long-term effluent quality commitments.
Europe Membrane Bioreactor (MBR) Market Segmentation
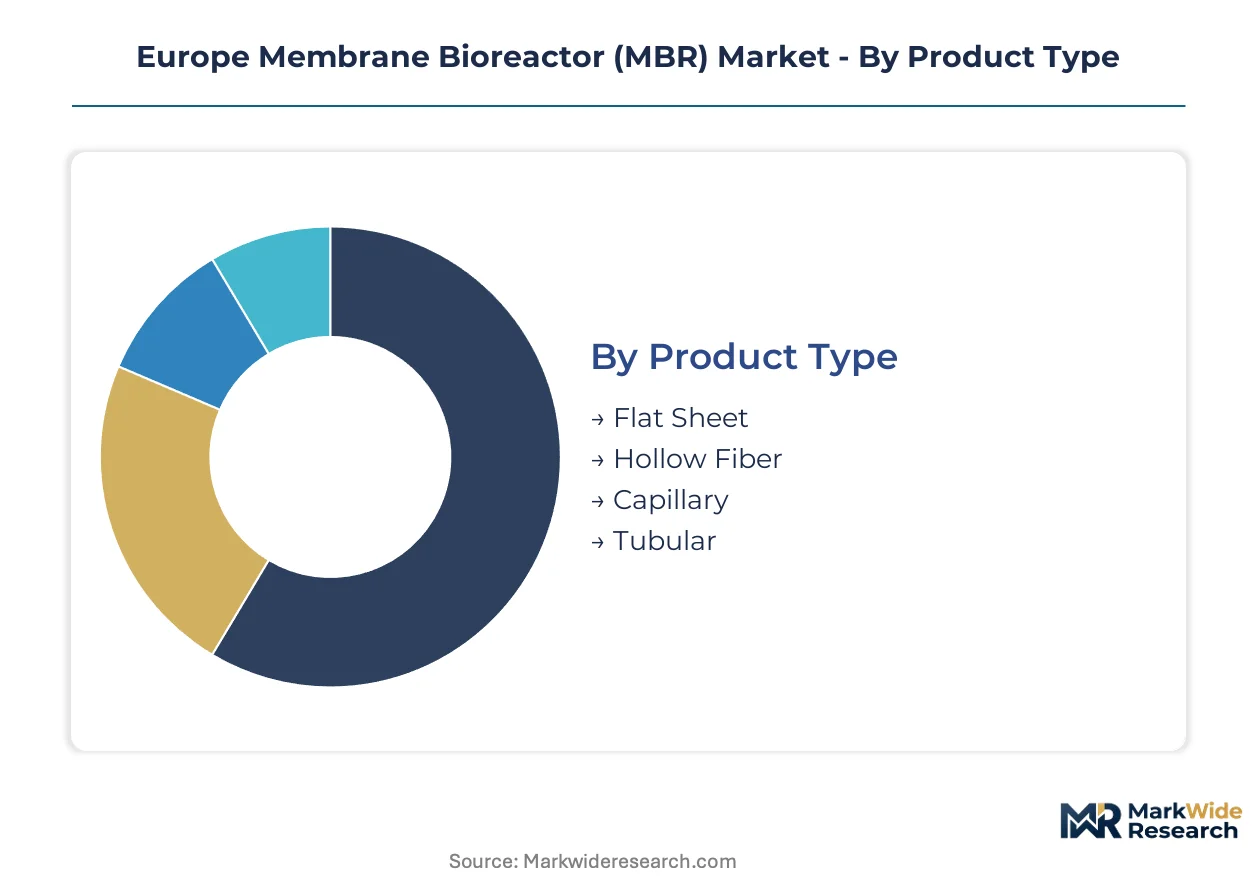
MBR procurement patterns diverge sharply across membrane geometries and operational configurations, with replacement cycles spanning 3-7 years for polymeric modules versus 10-15 years for ceramic alternatives. Understanding these temporal rhythms helps suppliers align inventory and service contract structures with actual utility capital planning horizons.
Product Type:
Hollow fiber geometries turn over fastest in municipal fleets due to fiber breakage accumulation, while flat sheet and ceramic substrates persist longer in industrial settings with aggressive cleaning protocols.
- Flat Sheet:Rigid plate-and-frame construction with membrane sheets bonded to support plates, typically cast from chlorinated polyethylene or modified PVDF. German pharmaceutical manufacturers and Dutch food processors specify flat sheet trains for high-strength wastewater with frequent caustic cleaning cycles.
- Hollow Fiber:Bundles of hair-thin filaments potted at both ends, offering the highest packing density and lowest specific aeration demand per unit permeate. French and Italian municipal utilities dominate procurement, driven by EU Urban Wastewater Treatment Directive nutrient limits and footprint constraints in dense urban catchments.
- Capillary:Intermediate diameter tubes bridging hollow fiber and tubular geometries, suited to moderate suspended solids applications.
- Tubular:Large-bore channels handling high solids without pre-screening, common in Italian olive oil processing and Spanish winery effluent.
Hollow fiber anchors the volume base while integrated ceramic-hybrid configurations gain share at the steepest rate in Limburg and Brabant pilot programs.
End User:
Capital allocation intensity varies threefold across user categories, with industrial facilities prioritizing water reuse payback periods under 4 years versus municipal operators accepting 8-12 year amortization horizons.
- Municipal:City-scale wastewater treatment plants serving 10,000-500,000 population equivalents, procuring through framework agreements with 10-15 year service concessions. Polish secondary cities and German Ruhrgebiet utilities are expanding MBR capacity fastest under EU cohesion fund and state-level climate investment programs.
- Industrial:Food and beverage, pharmaceutical, and petrochemical processors with discharge consent limits or internal water stress targets. Belgian brewing conglomerates and Dutch dairy cooperatives are retrofitting conventional activated sludge with MBR trains to eliminate discharge volumes entirely.
- Hospitality:Resort and hotel complexes in water-scarce Mediterranean coastlines, often combining MBR with reverse osmosis for irrigation-grade output.
- Residential:Cluster-scale developments and eco-districts in Scandinavian countries, typically sub-500 person equivalent decentralized systems.
Municipal procurement dominates installed base value while industrial closed-loop retrofits expand most quickly under CSRD water stress disclosure mandates.
Application:
Technical specifications diverge by application, with nutrient removal demanding anoxic zone integration and sludge management requiring thickened mixed liquor handling capabilities absent from standard water reuse configurations.
- Wastewater Treatment:Core biological oxidation and solids separation function, achieving BOD5 and TSS below 5 mg/L without secondary clarifiers. German utilities along the Rhine and Elbe basins are upgrading to MBR to meet tightened ammonia and phosphorus discharge limits.
- Water Reuse:Direct recycling of treated effluent for cooling towers, irrigation, or process water, requiring disinfection credit from membrane barrier. Spanish agricultural districts and Italian industrial parks are leading adoption where aquifer depletion threatens operational continuity.
- Sludge Management:Membrane thickening and solids retention time extension for reduced biosolids volume.
- Nutrient Removal:Biological phosphorus and nitrogen removal through anaerobic-anoxic-oxic zone sequencing, increasingly specified in Baltic Sea and North Sea catchments under HELCOM and OSPAR commitments.
Wastewater treatment anchors the volume base while water reuse climbs the fastest as drought frequency reshapes industrial facility planning across Mediterranean Europe.
Technology:
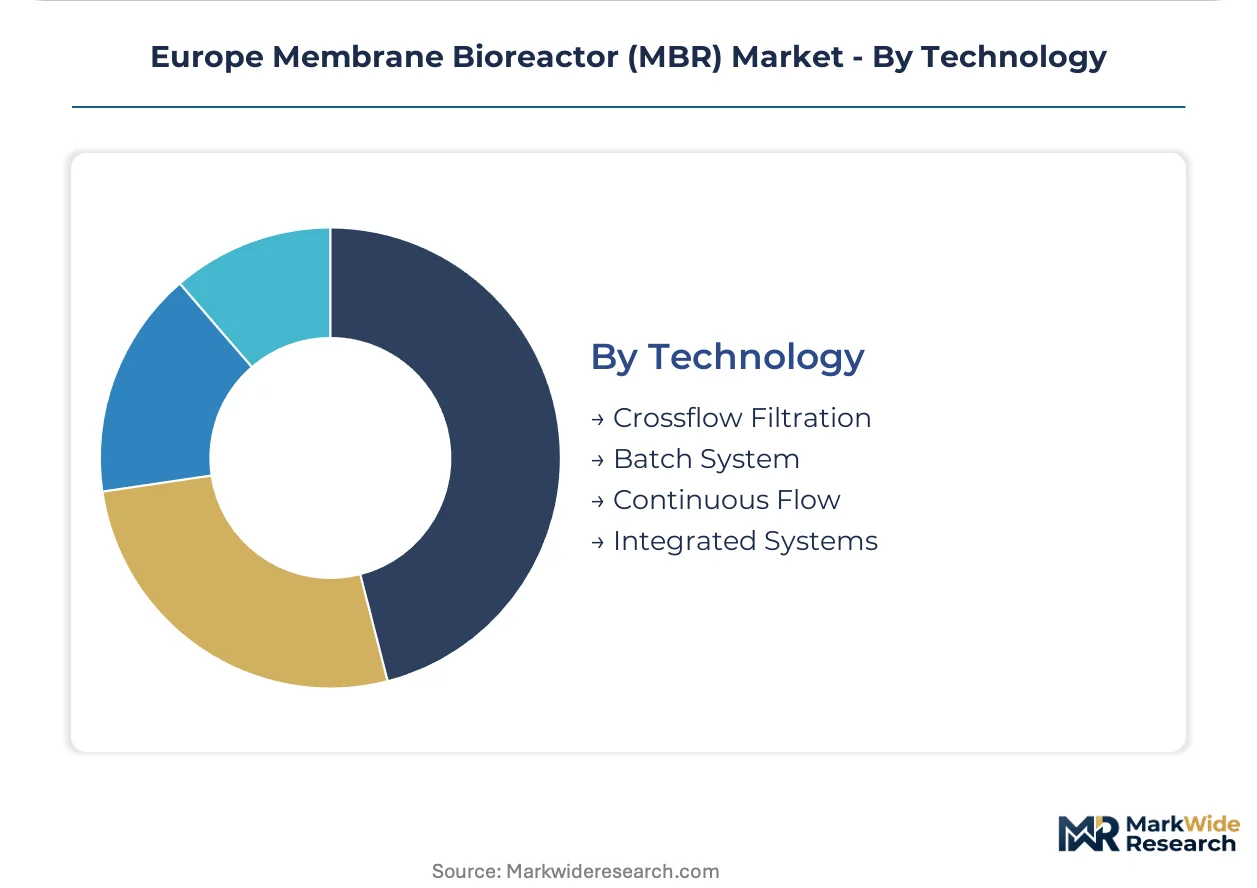
Operational mode selection determines blower energy intensity and cleaning chemical consumption, with integrated systems bundling process control and membrane supply under single-vendor accountability.
- Crossflow Filtration:Tangential flow across membrane surface at 2-4 m/s velocity, shear-dependent fouling control suited to high-solids industrial streams with abrasive or viscous characteristics.
- Batch System:Sequenced fill-react-settle-draw cycles with intermittent membrane operation, offering operational flexibility for variable flows but requiring larger tankage.
- Continuous Flow:Steady-state operation with constant permeate withdrawal, standard for large municipal baseload plants with diurnal flow equalization upstream.
- Integrated Systems:Single-contractor supply of membranes, biological process design, SCADA integration, and commissioning with performance guarantees. French and Italian utilities now mandate this procurement mode for projects exceeding 50,000 population equivalent, compressing vendor margins while transferring operational risk.
Continuous flow configurations anchor the volume base while integrated systems capture share fastest as procurement offices prioritize single-point accountability for effluent quality compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German membrane module fabricators export hollow fiber configurations to Polish and Czech municipal utilities expanding treatment capacity under EU cohesion fund programs. This trade corridor channels engineering expertise eastward while sourcing PVDF resin feedstock from Asian chemical producers.
Germany
Ruhrgebiet utilities are retrofitting conventional activated sludge trains with MBR technology to meet tightened ammonia discharge limits under the EU Urban Wastewater Treatment Directive. The F-Gas Regulation is forcing blower replacement alongside membrane upgrades. Engineering procurement offices in Düsseldorf and Essen now weight lifecycle carbon intensity in tender evaluations.
France
Municipal utilities in the Île-de-France region dominate hollow fiber procurement for footprint-constrained urban catchments. The EU Green Deal's carbon border adjustment mechanism is restructuring competitive economics for imported versus European-manufactured modules. Paris-area water authorities require single-contractor performance guarantees for projects exceeding 50,000 population equivalent.
Poland
EU cohesion fund allocations are driving first-mover positioning for integrated MBR system contractors in secondary cities lacking treatment capacity. REACH PFAS restrictions are accelerating coating chemistry reformulation across procurement channels. Municipal infrastructure projects in Kraków and Wrocław are expanding fastest under national climate investment programs.
Netherlands
Food and beverage processors in Brabant and Limburg are testing ceramic membrane substrates that withstand aggressive chemical cleaning regimes. CSRD water stress disclosure mandates are pushing industrial facility managers toward closed-loop installations. Dutch dairy cooperatives are retrofitting conventional systems to eliminate discharge volumes entirely.
Italy
Spanish agricultural districts and Italian industrial parks are leading water reuse adoption where aquifer depletion threatens operational continuity. The EU Urban Wastewater Treatment Directive is compressing effluent quality timelines across municipal utilities. Olive oil processing clusters in Puglia and winery effluent facilities in Tuscany specify tubular membrane configurations.
Europe Membrane Bioreactor (MBR) Market Key Industry Players
Channel-controlling players compete with product-specialist players across procurement modes ranging from component supply to integrated system delivery. The vendor base organizes around three strategic archetypes: diversified environmental services conglomerates with balance sheet capacity for performance guarantees, specialized membrane fabricators with materials science heritage, and regional engineering contractors bundling third-party modules with local commissioning expertise. Competitive moves concentrate on single-contractor accountability structures and digital twin integration for predictive maintenance contracts.
Within the diversified environmental services tier, Veolia Water Solutions & Technologies and SUEZ Water Technologies & Solutions exemplify channel-controlling players capable of underwriting long-term effluent quality commitments. Among membrane fabricators with materials specialization, Kubota Corporation and TORAY INDUSTRIES, INC. occupy positions reflecting distinct substrate geometries. Alfa Laval AB sits within the industrial application specialist archetype, leveraging heat transfer heritage for thermal management optimization. These named entities anchor competitive dynamics without implying specific market share positions or strategic actions beyond their visible procurement presence.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| Evoqua Water Technologies LLC |
| Veolia Water Solutions & Technologies |
| Asahi Kasei Corporation |
| Koch Membrane Systems, Inc. |
| SUEZ Water Technologies & Solutions |
| TORAY INDUSTRIES, INC. |
| Alfa Laval AB |
| Kubota Corporation |
| Others |
Cost & Logistics Intelligence
The Rotterdam-Antwerp barge corridor channels PVDF resin feedstock from Asian chemical producers to German membrane fabricators, with freight cost volatility compressing margins at module assembly plants while amplifying price spreads between premium ceramic configurations and commodity hollow fiber alternatives.
Pricing Analysis
Current-generation hollow fiber modules command substantial premiums over prior-generation flat sheet trains due to lower specific aeration demands, while next-generation ceramic-hybrid configurations price at a further elevation reflecting extended replacement intervals. Three-tier pricing structure across premium, standard, and economy levels separates integrated system packages with performance guarantees from component-only procurement and refurbished module alternatives. Cost compression in standard-tier hollow fiber trains is intensifying because Chinese and Japanese suppliers face embedded emissions documentation burdens under EU carbon border adjustment mechanisms. Municipal utilities in France and Italy exhibit the greatest price sensitivity due to framework agreement constraints, whereas Dutch food processors prioritize lifecycle cost over upfront capital outlay.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for membrane module procurement, with supply-chain finance facilities emerging as a competitive differentiator for integrated system contractors underwriting long-term performance guarantees. PVDF resin production concentrates in China, Japan, and South Korea, while membrane casting and module assembly anchor in Germany, France, and the Netherlands. European fabricators draw from fluoropolymer feedstock, non-woven support substrates, and precision potting adhesives. Single-source vulnerability in PVDF precursor supply exposes module producers to shipping cost volatility and tariff exposure. Distribution runs through engineering-procurement-construction contractors and direct municipal framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe MBR market sustains defensive moats through regulatory entrenchment: EU Urban Wastewater Treatment Directive compliance timelines create switching costs that lock utilities into proven membrane configurations for 10-15 year concession periods.
For Market Incumbents: Insulate integrated system capabilities by deepening captive supply of membrane casting capacity and predictive maintenance algorithms. Sequencing batch reactor systems with tertiary filtration threaten rural catchment penetration, necessitating backward integration into blower manufacturing to capture F-Gas Regulation upgrade cycles. Certification investment in harmonized EU membrane integrity testing protocols preserves first-mover positioning in Polish municipal infrastructure expansion. For New Entrants and Emerging Players: Establish a beachhead in ceramic membrane substrates for Dutch industrial closed-loop retrofits, where chemical cleaning tolerance demands exceed incumbent polymeric expertise. Polish secondary cities lacking treatment capacity represent the most penetrable geography, with EU cohesion fund allocations creating procurement windows for contractors offering single-point accountability. A go-to-market angle bundling digital twin integration with SCADA-layered fouling prediction algorithms differentiates against legacy component suppliers. For Investors and Strategic Acquirers: Regional engineering contractors with local commissioning expertise and established utility relationships represent the most attractive acquisition archetype, offering channel control without balance sheet exposure for performance guarantees. Long-term viability hinges on positioning for CSRD water stress disclosure mandates accelerating industrial closed-loop adoption. The signal to watch is REACH PFAS restriction implementation timelines, which will force coating chemistry reformulation and create replacement demand for compliant module configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVDF Resin Supply | Mitigates Asian feedstock concentration risk for German membrane fabricators facing carbon border adjustment documentation burdens. |
| Ceramic Membrane Substrate Scale-Up | Captures Dutch industrial pilot program demand for chemical-cleaning-tolerant configurations in Brabant and Limburg. |
| Digital Twin SCADA Integration | Enables predictive maintenance contracts extending module replacement intervals for French and Italian municipal utilities. |
| Single-Contractor Performance Guarantee Expansion | Aligns procurement office requirements in Paris-area water authorities exceeding 50,000 population equivalent projects. |
| REACH PFAS-Compliant Coating Development | Secures German and French procurement channel access as per- and polyfluoroalkyl substance restrictions accelerate. |
Research Approach
Cross-validation between regulatory filing analysis and procurement database tracking anchors the qualitative findings in this study. Primary interviews with municipal wastewater treatment plant operators, membrane module procurement managers, EPC contractors, and industrial facility environmental compliance officers combined with secondary validation from ECHA REACH registrations, EU Urban Wastewater Treatment Directive implementation reports, F-Gas Regulation compliance disclosures, and national tender databases. Bottom-up module shipment tracking and top-down utility capital expenditure surveys enable triangulation across independent data streams.
Calibration against historical membrane replacement cycles and announced municipal infrastructure investments shapes the projection framework across the analysis window. Segmentation dimensions modeled include membrane geometry, end-user category, application type, and operational technology mode, with regional regulatory cluster differentiation for EU cohesion fund eligibility zones. CAGRs derive from installed base turnover analysis and announced project pipelines. Forecast inputs incorporate mixed liquor suspended solids concentration trends and aeration energy intensity thresholds under evolving F-Gas Regulation standards.
Sensitivities concentrate around EU Green Deal carbon border adjustment mechanism implementation timelines and REACH PFAS restriction enforcement dates. Forecasts reflect assumptions regarding membrane integrity testing protocol harmonization and ceramic substrate manufacturing scale-up feasibility. Macroeconomic contraction affecting municipal infrastructure budgets, regulatory deviation on effluent quality timelines, or breakthrough ceramic membrane cost reductions would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Drinking Water Adsorbents Market
Water & Sludge Treatment
Global Water Treatment Technology Market
Water & Sludge Treatment
United Kingdom Water Treatment Chemicals Market
Water & Sludge Treatment
North America Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Deionized Water Systems Market
Water & Sludge Treatment
Global Sodium Hypochlorite Market
Water & Sludge Treatment
Global Naphthalene Water Reducers Market
Water & Sludge Treatment
United States Water Treatment Chemicals Market
Water & Sludge Treatment
Water Purification Systems Market
Water & Sludge Treatment
Industrial Wastewater Treatment Market
Water & Sludge Treatment
India Water Treatment Market
Water & Sludge Treatment
Polish Water Treatment Chemicals Market
Water & Sludge Treatment
Mexico Water Treatment Chemicals Market
Water & Sludge Treatment
US Water and Wastewater Treatment Market
Water & Sludge Treatment
Asia-Pacific Water Treatment Chemicals Market
Water & Sludge Treatment
Swimming Pool Treatment Chemicals Market