
 Global Metal-Organic Framework Market | 2026-2036
Global Metal-Organic Framework Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metal-Organic Framework Market Foresight
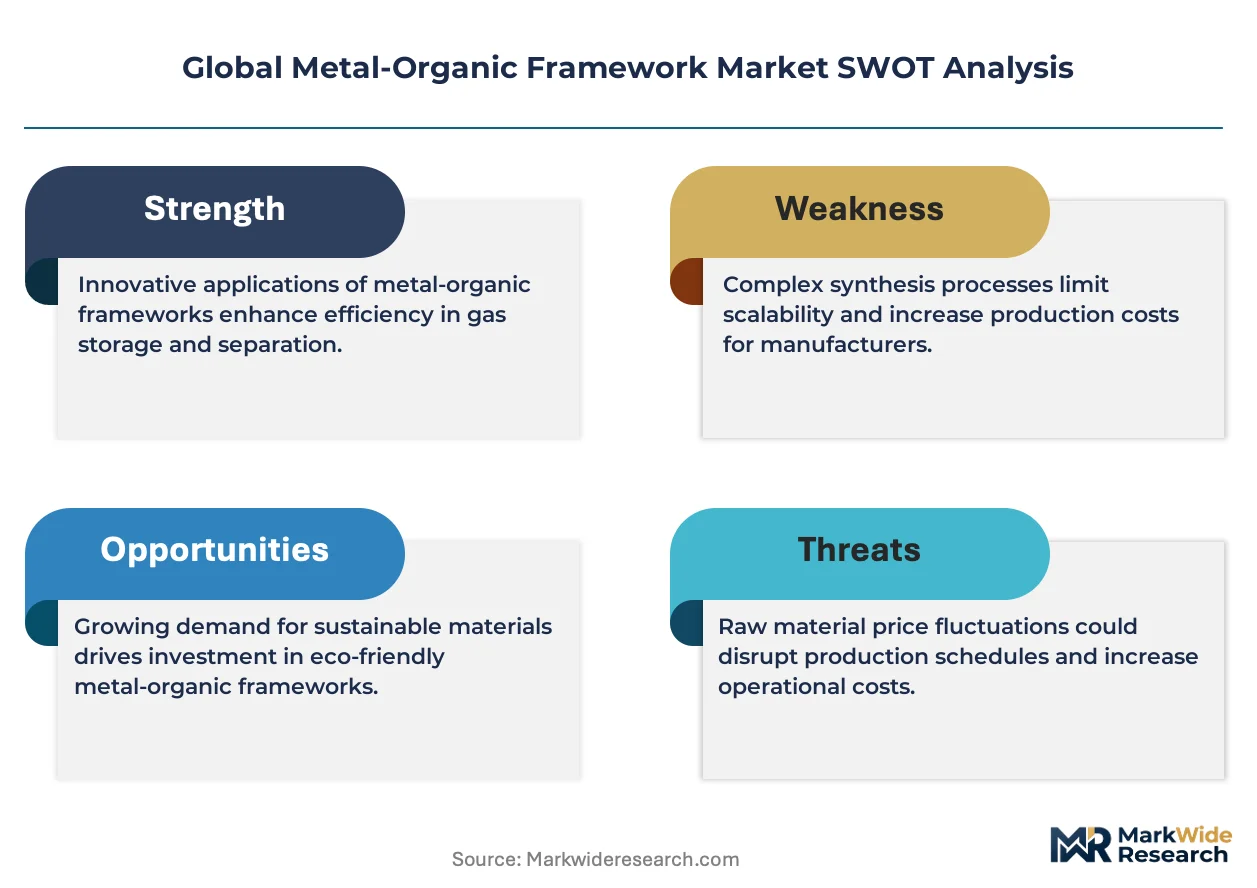
REACH is expanding the cost-of-entry calculus for metal-organic framework producers selling into European industrial gas markets. BASF SE leverages its integrated chemical manufacturing footprint to absorb compliance costs internally. Mosaic Materials anchors its position through sustained R&D partnerships with US Department of Energy laboratories. novoMOF specializes in scalable solvothermal production methods that navigate emerging purity thresholds.
Metal-organic frameworks are crystalline porous materials constructed from metal ions or clusters coordinated to organic ligands, typically exhibiting surface areas exceeding 7,000 m²/g and pore tunability down to angstrom precision for molecular sieving applications. Their primary commercial purpose centers on selective gas capture and storage in energy and environmental systems. Zeolitic imidazolate frameworks dominate current production volumes due to established synthesis protocols and thermal stability profiles. Gas storage applications command the deepest margin pools as hydrogen economy infrastructure scales, while catalysis segments compete on throughput efficiency. Microwave-assisted synthesis technology is displacing conventional solvothermal methods in pilot-scale facilities seeking reduced energy intensity and batch cycle times.
EPA regulations in the United States and REACH in Europe are forcing reformulation of framework precursors to eliminate hazardous solvent residues from manufacturing streams. China's GB standards and MIIT directives are converging with OECD chemical safety frameworks for nanomaterial classification, reshaping export qualification requirements for Asian producers. Stakeholders must monitor evolving dual carbon compliance timelines in China and emerging FDA guidance on MOF-based drug delivery carriers to anticipate certification bottlenecks before capacity commitments solidify.
Market Dynamics
Gas storage infrastructure investments are compressing commercialization timelines for metal-organic frameworks, forcing producers to scale solvothermal and microwave-assisted synthesis methods ahead of full hydrogen economy maturation.
Growth Catalysts
- Hydrogen storage mandates:Germany's national hydrogen strategy requires high-density storage media for import terminals at Wilhelmshaven and Brunsbüttel, creating immediate offtake for MOF-based tank systems.
- REACH precursor reforms:ECHA's tightening purity thresholds for metal-ligand complexes are advantaging producers with captive solvent recovery capabilities over contract manufacturers.
- Carbon capture retrofits:Post-combustion amine scrubbing facilities in the United States are piloting MOF contactors to reduce regeneration energy penalties below 2.5 GJ per tonne CO₂.
Market Restraints
- Organic ligand cost volatility:Imidazole and carboxylate precursor prices fluctuate with benzene and methanol feedstock indices, compressing gross margins for non-integrated producers.
- Chinese supply concentration:Over 60% of high-purity metal salts for framework synthesis originate from Zhejiang and Jiangsu provinces, exposing buyers to export license delays.
- Zeolite substitution in air separation:Lithium-exchanged zeolite 13X retains cost advantages for medical oxygen generation, limiting MOF penetration in portable concentrator applications.
Strategic Opportunities
- India's industrial gas expansion:Reliance Industries and Indian Oil Corporation are commissioning air separation units at Jamnagar and Paradip that specify next-generation adsorbents for argon recovery.
- EU F-Gas Regulation phase-down:Refrigerant containment standards are accelerating demand for MOF-coated heat exchangers in commercial HVAC systems across France and Italy.
- Continuous flow synthesis convergence:Integration of microreactor engineering with real-time crystallization monitoring is enabling ton-scale daily output from compact plant footprints.
Industry Challenges
- PhD-level materials chemist scarcity:Solvothermal process optimization requires expertise in coordination chemistry that outpaces university pipeline output in the United States and Germany.
- Batch-to-batch certification delays:Each production lot for pharmaceutical-grade MOF carriers requires 8-12 weeks of FDA stability testing, freezing working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metal-Organic Framework Market |
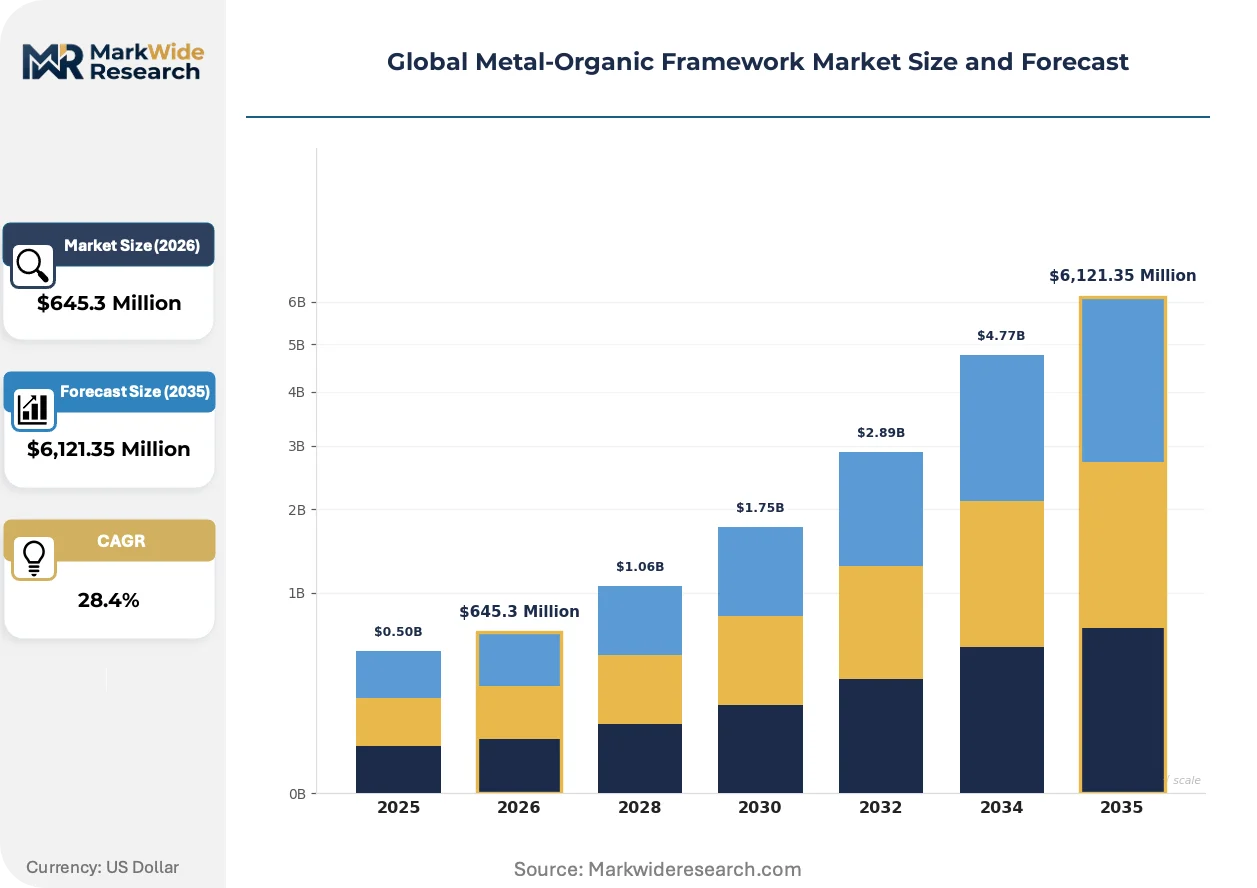
| Market Size in 2026 | $645.3 Million |
| Market Size in 2035 | $6,121.35 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zeolitic Imidazolate Frameworks, University of Oslo Frameworks, Isoreticular Metal-Organic Frameworks, Porous Coordination Polymers Application: Gas Storage, Catalysis, Drug Delivery, Chemical Separation, Sensing End User: Academic Institutions, Pharmaceutical Manufacturers, Chemical Processing Plants, Environmental Agencies Technology: Synthesis by Solvothermal, Microwave-Assisted Synthesis, Electrochemical Methods, Mechanochemical Methods |
| Companies Covered | Nuada, Nanorh, BASF SE, Mosaic Materials, novoMOF, NuMat Technologies, Inc., Framergy, Inc., ACSYNAM, MOF Technologies Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metal-Organic Framework Market Shifts & Advancements
Microwave-assisted synthesis protocols are compressing crystallization cycles from days to hours, enabling producers to respond to spot demand from hydrogen refueling station operators without carrying excessive inventory.
Continuous-flow microreactor technology is expanding into pilot-scale MOF manufacturing. BASF SE and specialty chemical producers in Ludwigshafen are installing skid-mounted units that reduce solvent consumption by 40% versus conventional autoclave methods. The technology is expanding into modular plant designs that can be relocated near hydrogen liquefaction facilities in northern Germany.
EPA's emerging standards for nanomaterial reporting under TSCA Section 8(a) are forcing framework producers to submit granular toxicity data on particle size distributions and dissolution kinetics. Formulators supplying drug delivery applications face the steepest compliance burdens, with some redirecting R&D budgets from new ligand discovery to toxicological screening. The regulation is accelerating partnerships between MOF developers and contract research organizations specializing in inhalation exposure studies.
Buyer consolidation among industrial gas majors is compressing supplier qualification timelines. Air Liquide, Linde, and Air Products International are unbundling traditional long-term adsorbent supply agreements in favor of performance-guaranteed service contracts where the MOF producer retains ownership of the material and charges per cubic meter of gas separated. This model is most visible in carbon capture projects along the US Gulf Coast, where developers prefer opex-light structures to preserve project finance capacity.
Global Metal-Organic Framework Market Segmentation
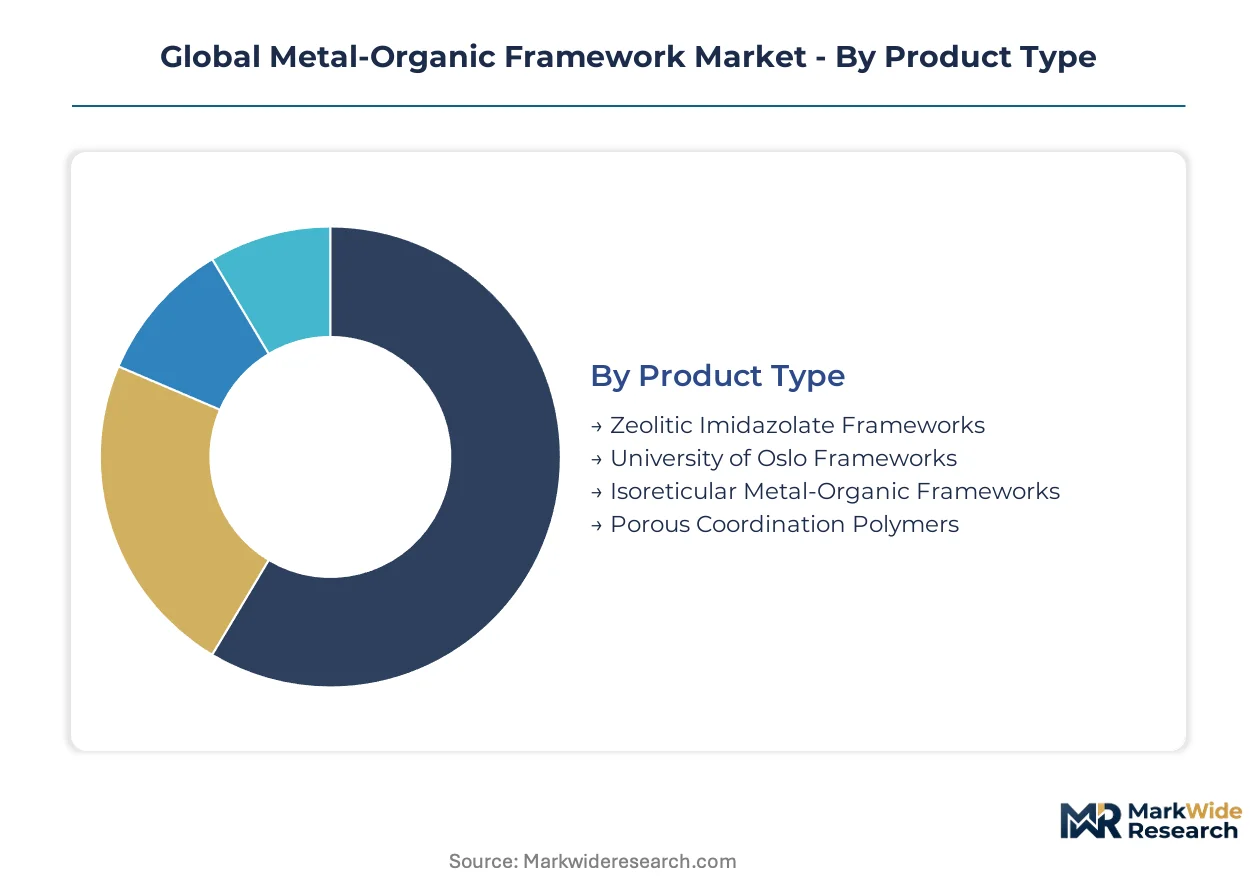
Metal-organic framework commercialization pathways diverge sharply across synthesis protocols and end-use specifications, with certification requirements determining viable market entry points for each segment. Product type selection constrains downstream application scope, while technology choices directly shape production economics and regulatory compliance burdens.
Product Type:
Zeolitic Imidazolate Frameworks and Isoreticular Metal-Organic Frameworks carry distinct REACH registration obligations under ECHA's nanomaterial classifications, while Porous Coordination Polymers face divergent FDA stability testing protocols for pharmaceutical applications.
- Zeolitic Imidazolate Frameworks:Crystalline structures built from zinc or cobalt nodes linked by imidazolate ligands deliver thermal stability above 400°C and hydrophobic pore surfaces ideal for hydrocarbon separation. Demand concentrates in German hydrogen storage terminals at Wilhelmshaven, where imidazolate frameworks meet density specifications for high-pressure tank systems under the national hydrogen strategy.
- Isoreticular Metal-Organic Frameworks:Modular architectures with tunable pore apertures ranging from 3.8 to 98 angstroms enable precise molecular sieving for carbon capture applications. Deployment is accelerating at US Gulf Coast amine scrubbing retrofits, where IR-MOF-74 variants reduce regeneration energy penalties below competing contactor materials.
- University of Oslo Frameworks:High-surface-area aluminum-based structures developed at UiO demonstrate exceptional chemical stability for catalytic applications in petrochemical crackers.
- Porous Coordination Polymers:Flexible frameworks exhibiting gate-opening adsorption behavior serve specialized sensing applications in Japanese industrial safety monitoring systems.
Leading the category by volume: Zeolitic Imidazolate Frameworks. Growing fastest: Isoreticular Metal-Organic Frameworks.
Application:
Cost tier separation divides gas storage applications commanding premium pricing from commoditized sensing segments competing on unit economics.
- Gas Storage:Hydrogen and methane containment systems for energy infrastructure represent the highest-margin application, with MOF-packed tanks achieving gravimetric capacities exceeding 10 wt% at 100 bar. German import terminals and US Department of Energy demonstration projects drive qualification timelines.
- Catalysis:Heterogeneous catalysis in fine chemical synthesis leverages open metal sites for substrate activation, with BASF SE integrating frameworks into Ludwigshafen production lines for pharmaceutical intermediates.
- Drug Delivery:Biodegradable frameworks for controlled release face extended FDA stability testing cycles that freeze working capital for 8-12 weeks per batch.
- Chemical Separation:Argon recovery units at Indian air separation facilities specify next-generation adsorbents from Reliance Industries and Indian Oil Corporation commissioning activity.
- Sensing:Explosive and toxic gas detection systems compete with semiconductor alternatives on response time and selectivity metrics.
Gas storage commands the steepest pricing tier. Drug delivery shows the steepest expansion trajectory pending regulatory harmonization.
End User:
Customer type determines procurement sophistication, with pharmaceutical manufacturers demanding batch-level certification that academic buyers rarely require.
- Chemical Processing Plants:Industrial gas majors including Air Liquide, Linde, and Air Products International are shifting from traditional supply agreements to performance-guaranteed service contracts where producers retain material ownership and charge per cubic meter separated.
- Pharmaceutical Manufacturers:Drug delivery applications require granular toxicity data on particle size distributions under emerging EPA TSCA Section 8(a) nanomaterial reporting standards.
- Academic Institutions:Research-scale procurement supports ligand discovery and structure-property correlation studies without commercial certification burdens.
- Environmental Agencies:Carbon capture pilot programs along the US Gulf Coast prefer opex-light contract structures to preserve project finance capacity.
Chemical processing plants generate the deepest revenue pools. Environmental agencies represent the fastest-climbing customer segment as carbon capture infrastructure scales.
Technology:
Volume scalability separates continuous-flow methods from batch-limited alternatives, with microwave and electrochemical approaches commanding equipment premiums that mechanochemical methods avoid.
- Microwave-Assisted Synthesis:Energy-efficient crystallization protocols compress reaction cycles from days to hours, enabling spot production for hydrogen refueling station operators without excessive inventory carrying costs. BASF SE and Ludwigshafen specialty producers are installing skid-mounted units that reduce solvent consumption by 40% versus autoclave methods.
- Synthesis by Solvothermal:Conventional high-temperature liquid-phase methods remain the production backbone for zeolitic frameworks, with novoMOF specializing in scalable protocols that navigate emerging ECHA purity thresholds through captive solvent recovery.
- Electrochemical Methods:Room-temperature synthesis through anodic dissolution of metal electrodes offers precise control over nucleation kinetics for pharmaceutical-grade frameworks.
- Mechanochemical Methods:Solvent-free ball-milling approaches minimize environmental compliance costs for commodity adsorbent applications.
Solvothermal synthesis retains the largest installed base. Microwave-assisted methods are gaining share fastest as energy intensity regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate metal-organic framework precursor manufacturing, drawing metal salt suppliers and ligand producers into clustered industrial parks. German chemical parks in Ludwigshafen and Leverkusen anchor European MOF production through integrated solvent recovery infrastructure. United States Gulf Coast hydrogen hubs are accelerating qualification timelines for storage-optimized frameworks.
United States
Hydrogen refueling station operators along the California corridor and Texas Gulf Coast are contracting for high-density storage media. EPA's emerging TSCA Section 8(a) nanomaterial reporting standards require granular toxicity data on particle size distributions. Houston-area carbon capture pilots at amine scrubbing facilities are testing MOF contactors to reduce regeneration energy penalties.
Germany
National hydrogen strategy mandates at Wilhelmshaven and Brunsbüttel import terminals are creating immediate offtake for tank-integrated frameworks. ECHA's tightening REACH purity thresholds for metal-ligand complexes favor producers with captive solvent recovery. Ludwigshafen chemical parks host BASF SE's integrated manufacturing footprint for framework production.
China
Dual carbon compliance timelines and MIIT directives on nanomaterial classification are reshaping export qualification requirements. Zhejiang and Jiangsu provinces supply over 60% of high-purity metal salts for framework synthesis. Shanghai's Yangtze River Delta industrial clusters concentrate solvothermal production capacity for domestic hydrogen infrastructure.
India
Reliance Industries and Indian Oil Corporation are commissioning air separation units at Jamnagar and Paradip specifying next-generation adsorbents. BIS standards for industrial gas equipment are converging with OECD chemical safety frameworks. Gujarat's chemical corridor is attracting MOF producers targeting argon recovery applications.
Japan
METI funding for hydrogen economy infrastructure is driving qualification of storage-optimized frameworks at Kobe and Yokohama terminals. JIS standards for high-pressure gas containment equipment are tightening material certification requirements. Osaka-Kansai industrial clusters host specialty chemical producers developing pharmaceutical-grade frameworks.
Global Metal-Organic Framework Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the metal-organic framework value chain. BASF SE leverages integrated chemical manufacturing to absorb regulatory compliance costs internally, while smaller entities anchor positions through R&D partnerships or scalable production methods. Three archetypes dominate: integrated chemical majors with captive raw material access, technology licensors with federal laboratory partnerships, and contract manufacturers specializing in solvothermal scale-up. Competitive moves concentrate on strategic partnerships with industrial gas majors and capacity expansion near hydrogen liquefaction facilities.
Among the integrated chemical majors, BASF SE exemplifies the diversified conglomerate archetype with its Ludwigshafen manufacturing footprint. Mosaic Materials and novoMOF occupy distinct specialist positions, with the former representing the federal laboratory partnership model and the latter exemplifying scalable production expertise. NuMat Technologies, Inc. anchors the technology licensing tier. These entities collectively illustrate how competitive positioning fragments across synthesis scale, regulatory compliance depth, and end-use application focus.
| Leading Market Players |
|---|
| Nuada |
| Nanorh |
| BASF SE |
| Mosaic Materials |
| novoMOF |
| NuMat Technologies, Inc. |
| Framergy, Inc. |
| ACSYNAM |
| MOF Technologies Ltd. |
| Others |
Supply & Pricing Matrix
Captive solvent recovery infrastructure anchors both supply security and margin protection for metal-organic framework producers navigating ECHA purity thresholds. BASF SE's Ludwigshafen chemical park integration demonstrates how backward control over precursor streams converts regulatory compliance burdens into pricing power over contract manufacturers lacking comparable vertical scope.
Pricing Analysis
Short lead-time premiums separate qualified suppliers from spot-market sellers in hydrogen storage offtake negotiations. Pharmaceutical-grade frameworks command premium-mid-economy pricing differentiation based on FDA stability certification tiers, while commodity adsorbents compete on volume scale. Cost compression in standard-grade ZIF production is intensifying because imidazole precursor prices track volatile benzene indices. Academic institutions exhibit the sharpest price sensitivity, whereas industrial gas majors prioritize performance guarantees over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Zhejiang and Jiangsu provinces, where over sixty percent of high-purity metal salts for framework synthesis originate. The supply chain draws from Chinese metal salt clusters, German ligand producers, and US Department of Energy laboratory partnerships. Export license delays from MIIT directives constitute the dominant structural risk. Distribution runs through direct long-term offtake agreements with industrial gas majors rather than merchant spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH precursor reforms and EPA nanomaterial reporting standards are accelerating consolidation by raising fixed compliance costs above viable scale thresholds for sub-scale producers.
For Market Incumbents: Anticipate margin compression from microwave-assisted synthesis entrants by deepening captive solvent recovery capabilities at Ludwigshafen-scale integrated sites. Secure long-term metal salt offtake from Yangtze River Delta suppliers before export license tightening. Certification investment in FDA drug-delivery stability protocols preserves access to the highest-margin application segment. For New Entrants and Emerging Players: Direct-to-researcher digital channels offer the lowest customer acquisition cost for pilot-scale MOF producers lacking industrial gas major relationships. India's Jamnagar and Paradip air separation unit commissions represent the most penetrable geography for next-generation adsorbent qualification. Target performance-guaranteed service contracts rather than traditional supply agreements to bypass incumbent qualification timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in technology licensing to industrial gas majors seeking opex-light carbon capture structures. Five-to-ten year viability hinges on hydrogen infrastructure buildout pace rather than laboratory-scale R&D milestones. Acquisition target archetype: solvothermal scale-up specialists with captive solvent recovery and existing ECHA registration dossiers. Watch for EPA TSCA Section 8(a) enforcement discretion as the signal indicating regulatory cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metal Salt Supply | Zhejiang province sourcing agreements reduce exposure to MIIT export license volatility. |
| Microwave-Assisted Synthesis Scale-Up | Skid-mounted Ludwigshafen units cut solvent consumption versus conventional autoclave methods. |
| Performance-Guaranteed Service Contracts | Air Liquide and Linde prefer opex-light structures for US Gulf Coast carbon capture projects. |
| FDA Stability Certification Investment | Drug delivery applications face eight-to-twelve week batch testing cycles that freeze working capital. |
| Joint Venture with National Laboratory | Mosaic Materials leverages Department of Energy partnerships to anchor technology licensing position. |
Research Methodology
Independent corroboration across coordination chemistry specialists, industrial gas procurement directors, and regulatory affairs consultants underwrites the qualitative findings. Primary fieldwork engaged plant managers at German chemical parks, downstream OEM procurement leads in hydrogen infrastructure, and ECHA nanomaterial classification officers. Secondary validation drew from SEC 10-K filings, customs trade data, and EPA TSCA Section 8(a) docket records. Bottom-up production capacity tallies and top-down end-use demand estimates were reconciled across the analysis window.
Comparable-period anchoring to historical solvothermal and microwave-assisted synthesis deployment rates established the forecast baseline. The quantitative framework segmented by framework type, application tier, synthesis technology, and regional regulatory cluster. CAGRs were derived from production capacity expansion schedules mapped against hydrogen storage mandate timelines. Industry-specific inputs included ECHA registration dossier progressions and FDA stability testing queue lengths.
The model holds under sustained REACH and EPA enforcement trajectories; deviation in Chinese dual carbon compliance acceleration or German hydrogen import terminal delays would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Organocatalyst Market
Organic Chemicals
Dioctyl Maleate (DOM) Market
Organic Chemicals
2-Fluorobenzotrifluoride Market
Organic Chemicals
Global Glycolic Acid Market
Organic Chemicals
Dioxolane Market
Organic Chemicals
Lithium Chemicals Market
Organic Chemicals
Absolute Ethanol Market
Organic Chemicals
Heterocyclic and Fluoro Organic Compounds Market
Organic Chemicals
Organic Matting Agent Market
Organic Chemicals
Azelaic Acid Market
Organic Chemicals
Benzyl Cyanide Market
Organic Chemicals
Mercaptopropionic Acid Market
Organic Chemicals
Europe Organic Acid Market
Organic Chemicals
Nonylphenol Market
Organic Chemicals
Global Pseudocumene Market
Organic Chemicals
Organic Rheological Modifiers Market