
 Membranes Market | 2026-2036
Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
Membranes Market Intelligence
Membrane-as-a-service contracting and performance-based maintenance agreements is repositioning how water utilities procure filtration capacity rather than capital equipment alone. DuPont leverages its fluoropolymer chemistry heritage to dominate high-pressure reverse osmosis module supply for seawater desalination. Toray Industries anchors East Asian demand through integrated hollow-fiber manufacturing from polymer to module assembly. Veolia Water Technologies competes by bundling membrane operations with long-term service contracts that lock in municipal clients.
Membranes are selective barriers engineered with pore sizes ranging from 0.1 micrometers in microfiltration to sub-nanometer dimensions in reverse osmosis, typically fabricated through phase inversion or interfacial polymerization onto woven or nonwoven supports. Their primary purpose is to separate dissolved salts, suspended solids, biological contaminants, or specific ions from water and process fluids without phase change. Reverse osmosis and nanofiltration command the deepest margin pools in water treatment applications where energy efficiency and salt rejection rates determine competitive viability. Ceramic membranes sustain premium positioning in food and beverage processing and pharmaceutical applications where thermal sterilizability and chemical resistance justify higher capital outlays against polymeric alternatives.
The EPA's Safe Drinking Water Act amendments and the EU F-Gas Regulation constrain membrane manufacturing chemistries and refrigerant-intensive production processes, while China's GB standards for industrial wastewater discharge mandate tertiary membrane treatment for heavy industries. ISO 9001 and NSF/ANSI 61 certifications function as baseline market access requirements rather than differentiators in municipal procurement. Stakeholders must monitor how evolving per- and polyfluoroalkyl substances restrictions in the United States and Europe reshape material choices for durable hydrophobic membranes previously reliant on fluorinated polymers.
Market Dynamics
Membrane-as-a-service contracting is compressing capital equipment sales cycles into recurring revenue streams, forcing manufacturers to restructure pricing models and field service organizations around performance guarantees rather than unit shipments.
Growth Catalysts
- EPA effluent standard tightening:Municipal utilities in the United States face accelerated replacement mandates for aging tertiary treatment infrastructure, driving demand for advanced membrane bioreactor systems.
- China's industrial water recycling corridors:Heavy manufacturing clusters along the Yangtze and Yellow River basins now require zero-liquid-discharge compliance, mandating membrane-based brine concentration and crystallization.
- Thin-film composite chemistry advances:Interfacial polymerization refinements are improving reverse osmosis permeability without sacrificing salt rejection, reducing energy consumption per cubic meter treated.
Market Restraints
- Fluoropolymer feedstock concentration:High-performance hydrophobic membrane production depends on concentrated fluoropolymer supply chains subject to EU F-Gas Regulation phase-down schedules.
- Energy cost volatility:Reverse osmosis operations remain electricity-intensive; tariff spikes in Germany and industrial power markets directly compress operating margin pools for membrane plant operators.
- Membrane fouling limitations:Biological and colloidal fouling in wastewater applications imposes chemical cleaning cycles that reduce effective membrane lifespan below theoretical polymer durability.
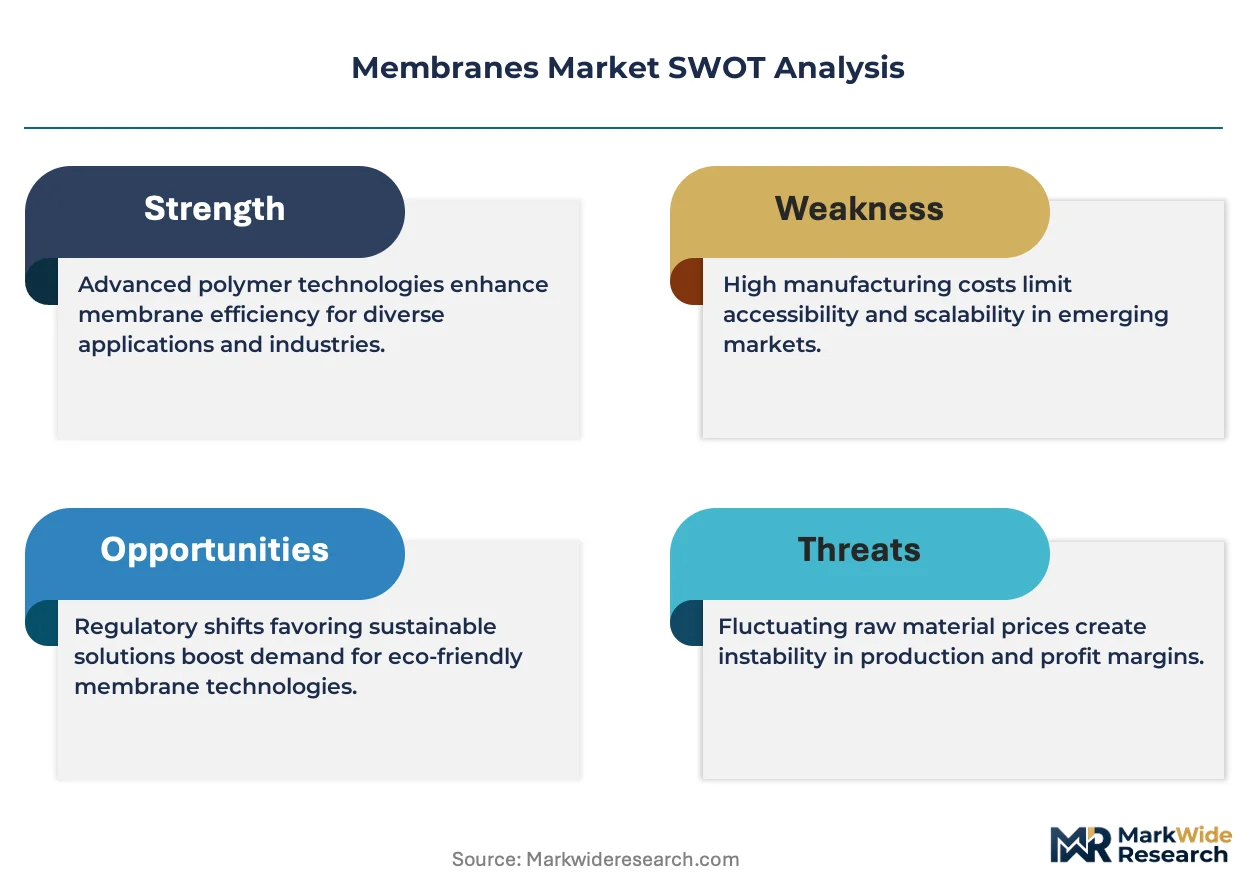
Strategic Opportunities
- India's municipal desalination programs:Coastal cities including Chennai and Mumbai are expanding public-private partnership frameworks for seawater reverse osmosis capacity.
- Food and beverage membrane bioreactors:Dairy processors and brewery operations are adopting ceramic ultrafiltration for protein fractionation and product recovery applications.
- EU Green Deal industrial water reuse mandates:The European Commission's circular economy action plan creates binding water reuse targets for steel, pulp, and chemical manufacturing facilities.
Industry Challenges
- Specialized polymer synthesis expertise:Phase inversion and interfacial polymerization process engineering requires chemists and materials scientists with decade-long training curves.
- NSF/ANSI 61 certification timelines:Drinking water contact approvals involve 18-24 month testing protocols that delay product commercialization for municipal procurement cycles.
- Legacy SCADA integration:Membrane skids with advanced sensor arrays must interface with decades-old plant control systems, requiring custom protocol translation and commissioning delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Membranes Market |
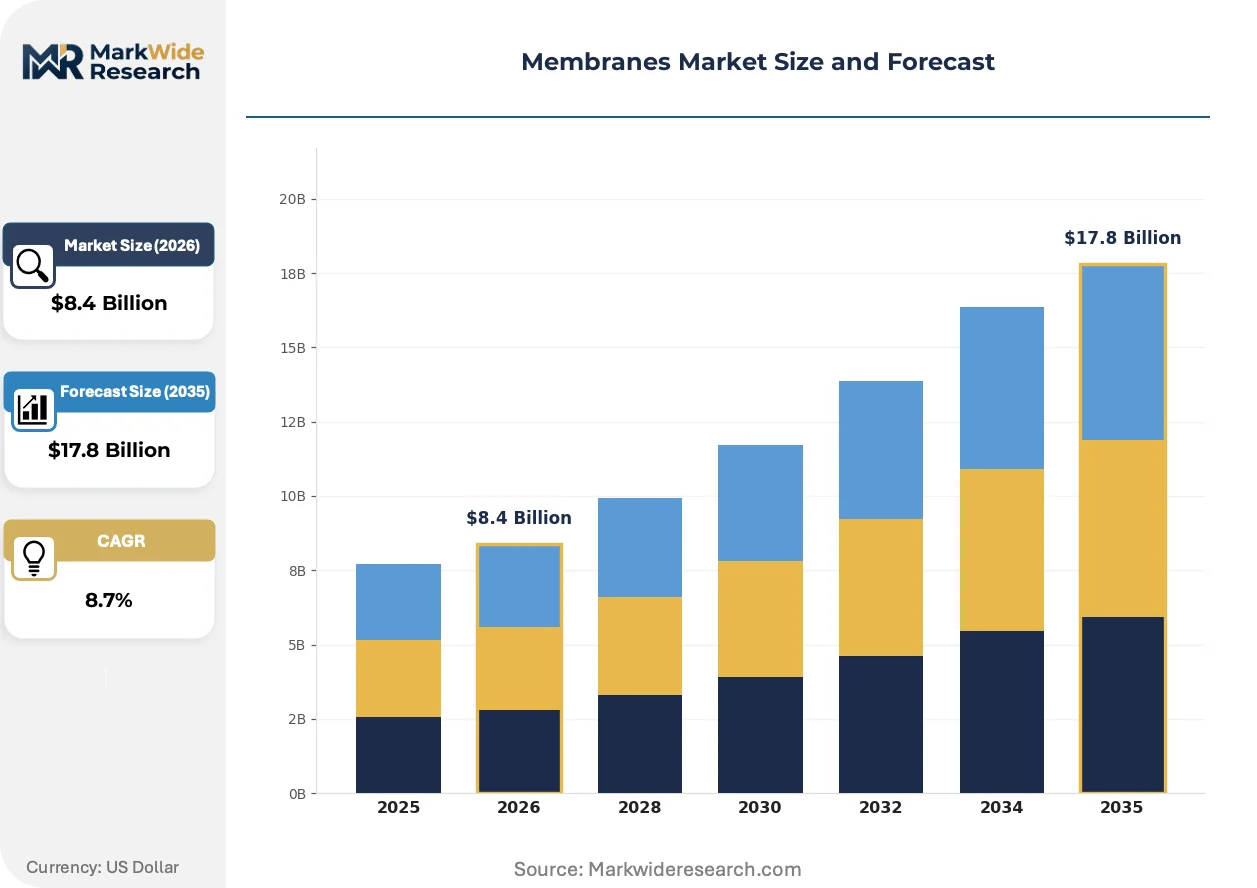
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $17.8 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Membrane Type: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis, Electrodialysis Material: Polyvinylidene Fluoride, Polyethersulfone, Cellulose Acetate, Polysulfone, Ceramic Application: Water Treatment, Food & Beverage Processing, Pharmaceutical Processing, Pulp & Paper, Chemical Processing End User Industry: Municipal Water Utilities, Beverage Manufacturers, Biopharmaceutical Companies, Paper Mills, Petrochemical Plants |
| Companies Covered | DuPont, Toray Industries, Veolia Water Technologies, Asahi Kasei Corporation, 3M Company, Hydranautics, Pall Corporation, LG Chem, Koch Membrane Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Membranes Market Strategic Shifts & Innovations
Digital twin technology and predictive fouling algorithms are transforming membrane plant operations from reactive maintenance schedules toward condition-based intervention models.
Graphene oxide laminates are automating molecular separation selectivity in nanofiltration modules. Specialty chemical manufacturers in Germany and Japan are piloting these materials for solvent recovery and pharmaceutical intermediate purification. The technology is automating quality control protocols that previously required manual sampling and laboratory analysis, compressing batch release timelines.
REACH restrictions on per- and polyfluoroalkyl substances are forcing membrane producers to reformulate durable hydrophobic surfaces. The European Chemicals Agency's 2023 PFAS restriction proposal covers fluorinated polymer processing aids and surface treatments essential to membrane module integrity. Manufacturers are responding with silicone-based and hydrocarbon alternatives, though these substitutes currently trade thermal stability and chemical resistance.
Performance-based contracting is displacing capital purchase models in municipal water treatment. Utilities in California, Texas, and Australia's major cities now procure treated water volumes rather than membrane assets, transferring operational risk to equipment suppliers and service integrators. This shift concentrates procurement authority among engineering firms with balance sheet capacity to underwrite long-term availability guarantees.
Membranes Market Segmentation
Membrane procurement patterns diverge sharply across filtration precision grades, polymer chemistries, and end-use compliance regimes. Understanding these segment boundaries reveals where margin pools concentrate and which material platforms face substitution pressure from regulatory tightening.
Membrane Type:
Supply concentration in high-pressure module manufacturing favors established interfacial polymerization specialists with captive polymer synthesis capabilities.
- Reverse Osmosis:Thin-film composite polyamide layers achieve sub-nanometer selectivity for dissolved salt rejection. Demand concentrates in Saudi Arabia's megascale desalination projects and California's agricultural groundwater remediation, where energy efficiency mandates drive module replacement cycles.
- Nanofiltration:Divalent ion-selective membranes operate at lower pressures than reverse osmosis while retaining organic micropollutants. Water utilities in the Netherlands and Belgium deploy these systems for pesticide and pharmaceutical removal from surface water sources.
- Ultrafiltration:Hollow-fiber configurations with 0.01 micrometer pores separate macromolecules and colloids. Beverage processors and tertiary wastewater plants favor this format for its lower fouling propensity.
- Microfiltration:0.1 micrometer pore structures target suspended solids and bacterial loads. Dairy processors deploy ceramic and polymeric versions for protein concentration and whey fractionation.
- Electrodialysis:Ion-exchange membranes under direct current enable selective salt transport. Brackish water desalination in Israel and Japan's coastal industrial zones relies on this electrochemical approach for partial demineralization.
Today's leader: Reverse Osmosis. Tomorrow's challenger: Nanofiltration.
Material:
Cost tier stratification separates fluoropolymer premium grades from commodity polysulfone alternatives, with ceramic occupying a defensible high-temperature niche.
- Polyvinylidene Fluoride:Hydrophobic fluoropolymer with exceptional chemical resistance and mechanical durability. Outdoor membrane bioreactor installations in Australia's municipal sector and Singapore's NEWater facilities specify PVDF for its oxidative cleaning tolerance.
- Ceramic:Aluminum oxide and titanium dioxide sintered structures withstand steam sterilization and aggressive solvents. Pharmaceutical active ingredient recovery and food protein fractionation justify the capital premium against polymeric alternatives.
- Polyethersulfone:Amorphous thermoplastic with broad pH tolerance and thermal stability. Dialysis membrane manufacturing and laboratory filtration consume significant volumes of this mid-tier material.
- Polysulfone:Cost-engineered ultrafiltration and microfiltration substrates for municipal water treatment where chemical exposure remains moderate.
- Cellulose Acetate:Legacy reverse osmosis material with asymmetric pore structure. Limited to low-pressure applications due to hydrolytic degradation and biological fouling susceptibility.
PVDF and ceramic command pricing power; polysulfone and cellulose acetate face margin compression from Asian polymer commoditization.
Application:
Volume concentration tracks regulatory enforcement intensity, with water treatment consuming module output at multiples of pharmaceutical or food processing rates.
- Water Treatment:Municipal drinking water, industrial process water, and wastewater reuse constitute the dominant demand sink. China's zero-liquid-discharge mandates and India's municipal desalination expansion are accelerating membrane installation rates.
- Food & Beverage Processing:Dairy protein concentration, juice clarification, and brewery filtration require sanitary-grade membranes with FDA and EU food contact approvals.
- Pharmaceutical Processing:Final filtration, virus removal, and active pharmaceutical ingredient purification demand validated integrity testing and batch documentation.
- Pulp & Paper:White water recycling and effluent treatment in Nordic and Canadian mills utilize high-solids-tolerant membrane configurations.
- Chemical Processing:Solvent recovery and catalyst separation in German and Japanese specialty chemical plants exploit ceramic membrane thermal stability.
Water treatment absorbs capacity; pharmaceutical processing delivers the steepest expansion trajectory per unit installed.
End User Industry:
Customer type determines procurement modality, with municipal utilities favoring performance contracts and industrial buyers emphasizing capital efficiency.
- Municipal Water Utilities:Public procurement frameworks in the United States, Germany, and Australia increasingly specify treated water volumes rather than equipment ownership, transferring operational risk to membrane service providers.
- Biopharmaceutical Companies:Single-use membrane assemblies for sterile filtration command validation documentation and supply chain security protocols that constrain vendor switching.
- Beverage Manufacturers:Quality-sensitive producers in France, Italy, and California integrate membrane filtration into brand protection strategies for premium product lines.
- Petrochemical Plants:Refinery wastewater reuse and produced water treatment in Texas and the Middle East drive demand for high-salinity-tolerant reverse osmosis systems.
- Paper Mills:Water circuit closure targets in EU ETS-regulated facilities create membrane demand for effluent polishing and fiber recovery.
Municipal utilities anchor volume; biopharmaceutical companies defend the premium pricing tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Membrane production capacity migrates toward jurisdictions with lower fluoropolymer processing costs and less stringent PFAS discharge oversight, creating regulatory arbitrage between European chemical compliance regimes and Asian manufacturing zones.
United States
California's agricultural groundwater remediation and Texas petrochemical wastewater reuse drive module demand. EPA Safe Drinking Water Act amendments tighten tertiary treatment mandates for municipal utilities. The Permian Basin and Central Valley water districts are expanding brackish water reverse osmosis capacity under state drought emergency protocols.
Germany
Industrial water reuse targets under EU Green Deal circular economy mandates accelerate membrane installation in steel and chemical corridors. REACH restrictions on fluorinated polymers constrain domestic hydrophobic membrane manufacturing. The Rhine-Ruhr industrial cluster and Bavarian chemical parks are piloting ceramic ultrafiltration for solvent recovery applications.
China
Zero-liquid-discharge compliance in Yangtze and Yellow River manufacturing basins mandates membrane-based brine concentration systems. MEE discharge rules for heavy industries enforce tertiary treatment for metallurgical and textile effluents. The Jiangsu and Shandong provincial industrial zones are deploying integrated membrane bioreactor networks for electronics manufacturing process water.
India
Municipal desalination programs in coastal cities expand public-private partnership frameworks for seawater reverse osmosis. Central Pollution Control Board standards for industrial effluent quality drive adoption in chemical processing zones. The Chennai and Mumbai metropolitan water authorities are tendering large-scale membrane capacity under 25-year availability contracts.
Saudi Arabia
Megascale desalination projects sustain demand for high-pressure reverse osmosis modules with superior energy efficiency specifications. The national water strategy prioritizes membrane technology transfer agreements for local manufacturing development. The Jubail industrial city and Riyadh metropolitan water system are integrating advanced filtration into national water security infrastructure.
Membranes Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated polymer-to-module producers commanding premium positioning in high-pressure applications while regional fabricators compete on cost-engineered ultrafiltration substrates. The market structure concentrates around three strategic archetypes: fluoropolymer chemistry specialists with captive resin synthesis, hollow-fiber manufacturing integrators controlling polymer spinning through module assembly, and service-anchored engineering firms bundling equipment with long-term operations contracts. Dominant competitive moves include backward integration into specialized polymer production and geographic expansion through licensing arrangements for thin-film composite manufacturing.
Within the chemistry-specialist tier, DuPont and Toray Industries occupy positions defined by materials science heritage and manufacturing scale. DuPont represents the fluoropolymer-centric archetype leveraging polymer expertise for high-pressure seawater desalination applications. Toray Industries exemplifies the integrated manufacturing model spanning polymer synthesis through hollow-fiber module assembly. Veolia Water Technologies anchors the service-integrated competitive vector, bundling membrane assets with long-term operational contracts that transfer performance risk from municipal clients.
| Leading Market Players |
|---|
| DuPont |
| Toray Industries |
| Veolia Water Technologies |
| Asahi Kasei Corporation |
| 3M Company |
| Hydranautics |
| Pall Corporation |
| LG Chem |
| Koch Membrane Systems |
| Others |
Cost & Logistics Intelligence
Captive polymer synthesis capabilities anchor both supply security and pricing power for membrane manufacturers, with DuPont and Toray Industries leveraging in-house fluoropolymer and polyamide production to command premium positioning in high-pressure reverse osmosis modules while regional fabricators without upstream integration compete on cost-engineered ultrafiltration substrates.
Pricing Analysis
Distributor margins compress pricing transparency for mid-tier polymeric membranes, while direct-to-OEM contracts for ceramic and fluoropolymer grades secure volume discounts and long-term offtake guarantees. Three-tier pricing structure across premium PVDF/ceramic, standard polyethersulfone, and economy polysulfone levels reflects certification intensity and thermal stability specifications. Cost compression in commodity ultrafiltration is intensifying because Asian polymer commoditization erodes margin pools for non-integrated producers. Municipal utilities exhibit highest price sensitivity due to public procurement frameworks, while biopharmaceutical companies defend premium tiers for validated single-use assemblies.
Supply Chain Analysis
Domestic-content mandates in India's municipal desalination tenders and Saudi Arabia's technology transfer agreements are reshaping sourcing patterns toward local module assembly partnerships. Fluoropolymer feedstock concentrates in the United States, Japan, and China, with interfacial polymerization expertise clustering in Germany and South Korea. Raw material dependencies rest on specialty amine monomers, woven polysulfone supports, and high-purity solvents for phase inversion processes. Single-source vulnerability in fluorinated polymer processing aids exposes manufacturers to EU F-Gas Regulation phase-down schedules. Distribution runs through engineering-procurement-construction contractors for municipal projects and direct manufacturer relationships for industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The membranes market functions as a stable compounder anchored by regulatory mandates for tertiary water treatment that sustain replacement cycles regardless of macroeconomic volatility.
For Market Incumbents: Deepen backward integration into amine monomer and fluoropolymer resin production to defend margin pools against REACH-driven material substitution threats. Lock in municipal clients through membrane-as-a-service contracts that transfer operational risk and create switching costs. Prioritize ceramic membrane capacity expansion for pharmaceutical and food processing segments where thermal sterilizability justifies capital premiums.
For New Entrants and Emerging Players: Mid-sized Indian municipal water authorities represent the most penetrable buyer archetype, with 25-year availability contracts creating entry pathways without upfront capital competition. Target Australia's outdoor membrane bioreactor installations where PVDF oxidative tolerance specifications favor new chemistry specialists. Pursue food and beverage processor segments through protein fractionation applications with lower certification barriers than pharmaceutical validation requirements.
For Investors and Strategic Acquirers: Roll-up economics work for regional hollow-fiber fabricators because municipal procurement consolidation favors engineering firms with balance sheet capacity for performance guarantees. The 5-to-10-year investment horizon rewards platforms integrating polymer spinning through module assembly with service contract capabilities. Monitor EU PFAS restriction implementation timelines as the critical inflection signal for material substitution winners and stranded fluoropolymer asset risks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Synthesis | Captive amine monomer production insulates DuPont and Toray from fluoropolymer feedstock volatility. |
| Membrane-as-a-Service Contracting | Veolia's performance guarantees transfer operational risk and lock in municipal replacement revenue streams. |
| Ceramic Capacity Expansion | Aluminum oxide sintering capabilities capture pharmaceutical sterilization premiums against polymeric alternatives. |
| Regional Manufacturing Licensing | Technology transfer agreements in Saudi Arabia satisfy domestic-content rules for megascale desalination tenders. |
| PFAS-Free Material Reformulation | Silicone-based hydrophobic surfaces respond to ECHA restrictions while trading thermal stability specifications. |
Research Approach
Coverage spans the United States, Germany, China, India, and Saudi Arabia, with primary inputs from each market combining interviews with municipal water utility procurement directors, membrane plant operations managers, fluoropolymer R&D chemists, and engineering-procurement-construction contractors. Secondary validation draws from EPA enforcement databases, EU ETS water reuse compliance filings, MEE discharge permit records, and customs trade data for membrane module imports. Bottom-up installation counts triangulate against top-down water treatment capital expenditure estimates.
Granularity-level modeling disaggregates volume and value across membrane type, material chemistry, application vertical, and end-user procurement modality throughout the forecast period. Reverse osmosis and nanofiltration segments incorporate energy efficiency specifications and salt rejection performance tiers. Municipal versus industrial buyer archetypes capture divergent contract structures and replacement cycle dynamics. CAGRs derive from regulatory mandate timelines, infrastructure investment pipelines, and technology substitution curves for graphene oxide laminates.
Underlying measurement precision varies by segment; reverse osmosis and ceramic membrane categories carry tighter precision than emerging electrodialysis applications due to established vendor reporting and project visibility. Forecasts incorporate assumptions around EPA effluent standard implementation pacing, EU F-Gas Regulation enforcement intensity, and China's zero-liquid-discharge compliance timelines that could accelerate or delay replacement demand. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Oxygen Barrier Films Market
Membrane Materials
Global Medical Membranes Market
Membrane Materials
Global Tubular Membranes Market
Membrane Materials
Inorganic Ion Exchange Materials Market
Membrane Materials
Asia-Pacific, Middle East and Africa Macrofiltration Market
Membrane Materials
Bitumen Waterproofing Membrane Market
Membrane Materials
Global Gas Separation Membranes Market
Membrane Materials
Nafion Market
Membrane Materials
Global Vapor Permeability Films Market
Membrane Materials
Membrane Skinners Market
Membrane Materials
Polyarylsulfone (PAS) Market
Membrane Materials
Hollow Fibers Membrane Market
Membrane Materials
Global Membrane Separation Technology Market
Membrane Materials
Thermoplastic Polyolefin Membranes Market
Membrane Materials
Polyvinyl Chloride Membranes Market
Membrane Materials
Membrane Chemicals Market