
 Membrane Touch Switch Material Market | 2026-2036
Membrane Touch Switch Material Market Size, Share, and Industry Trends Forecast 2026-2036
Membrane Touch Switch Material Market Analytics
Flexible printed electronics integration is narrowing the performance gap between conventional rigid PCBs and membrane touch switch assemblies in cost-sensitive applications. DuPont leverages its Kapton polyimide film heritage to anchor high-temperature membrane substrate supply for industrial HMI panels. Sabic sustains polycarbonate resin innovation for optical-grade graphic overlays requiring impact resistance and clarity. MacDermid Autotype specializes in coated polyester films with hard-surface durability for repetitive actuation environments.
Membrane touch switch materials comprise layered polymer substrates, conductive inks, and adhesive systems engineered for electrical signal transmission through mechanical deformation. Polyester films typically span 0.125 to 0.25 millimeter thickness with silver-carbon hybrid ink circuits screen-printed to achieve contact resistances below 100 ohms, serving as human-machine interfaces where sealed, low-profile input surfaces are essential. Multi-layer constructions dominate specification-driven medical and industrial segments where tactile feedback and environmental sealing command margin premiums. Silicone materials represent the fastest-expanding category due to biocompatibility certifications and sterilization tolerance in diagnostic equipment. Graphic overlays constitute a mature, volume-driven segment tied to appliance and consumer electronics branding requirements.
FDA 21 CFR Part 820 quality system regulations and EU MDR Class I-III device classifications shape material traceability and biocompatibility testing burdens for medical membrane suppliers. REACH substance restrictions and RoHS hazardous substance limits constrain adhesive and ink formulation choices across European and North American manufacturing footprints. Stakeholders must monitor evolving IEC 60601 medical electrical equipment standards for touch interface isolation requirements while evaluating backward integration into conductive ink compounding to secure supply continuity.
Market Dynamics
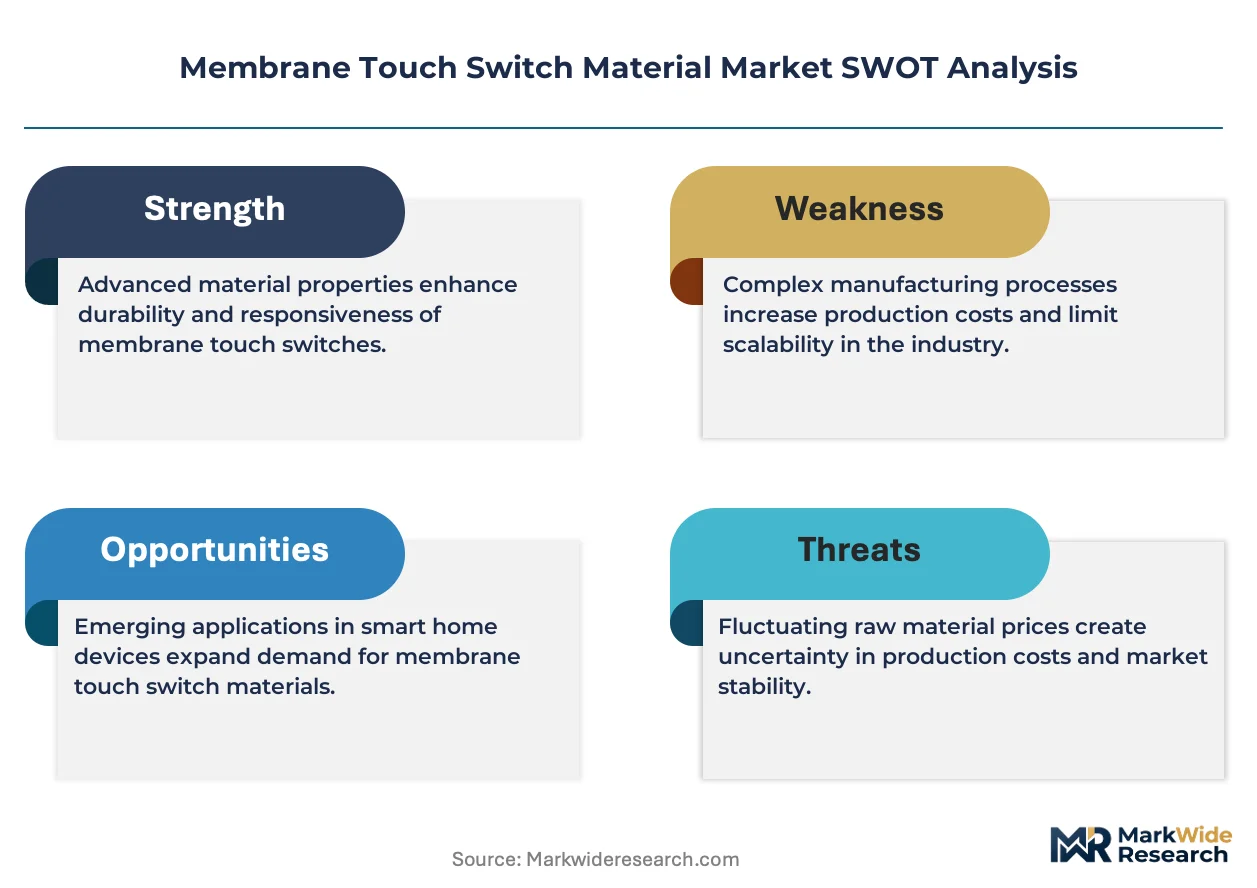
REACH restrictions on phthalate plasticizers in PVC formulations are accelerating polyester and polycarbonate substitution across European supply chains, compressing legacy material margins while medical device procurement concentrates on biocompatible silicone alternatives.
Growth Catalysts
- EU MDR biocompatibility mandates:Medical device manufacturers are expanding silicone-based membrane procurement to meet Class I-III device classification requirements under the European Union's Medical Device Regulation framework.
- Automotive HMI cluster demand:German OEMs are driving specification-grade material consumption for sealed, low-profile input surfaces in next-generation dashboard interfaces.
- Silver-carbon hybrid ink advances:Screen-printed circuit resistances below 100 ohms are enabling thinner polyester constructions without signal degradation.
Market Restraints
- Silver price volatility:Conductive ink formulations depend on precious metal inputs subject to commodity exchange fluctuations, squeezing converter margins.
- German supply concentration:Automotive and industrial automation OEM procurement clusters in Bavaria and Baden-Württemberg create geographic demand risk.
- Flexible printed electronics substitution:Cost-sensitive appliance and consumer electronics segments are migrating to integrated FPC alternatives.
Strategic Opportunities
- Diagnostic equipment sterilization tolerance:Silicone materials with gamma and autoclave resistance are penetrating surgical robotics and point-of-care testing devices.
- IEC 60601 isolation standard evolution:Touch interface dielectric requirements in medical electrical equipment are creating specification-grade material premiums.
- Industrial automation retrofit cycles:Food processing and pharmaceutical packaging machinery in the United States are replacing legacy mechanical switches with sealed membrane assemblies.
Industry Challenges
- Conductive ink compounding expertise:Formulation chemistry for low-resistance, high-flex circuits requires specialized polymer science talent scarce outside established converter hubs.
- FDA 21 CFR Part 820 traceability burdens:Medical membrane suppliers face extended documentation and testing timelines for quality system compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Membrane Touch Switch Material Market |
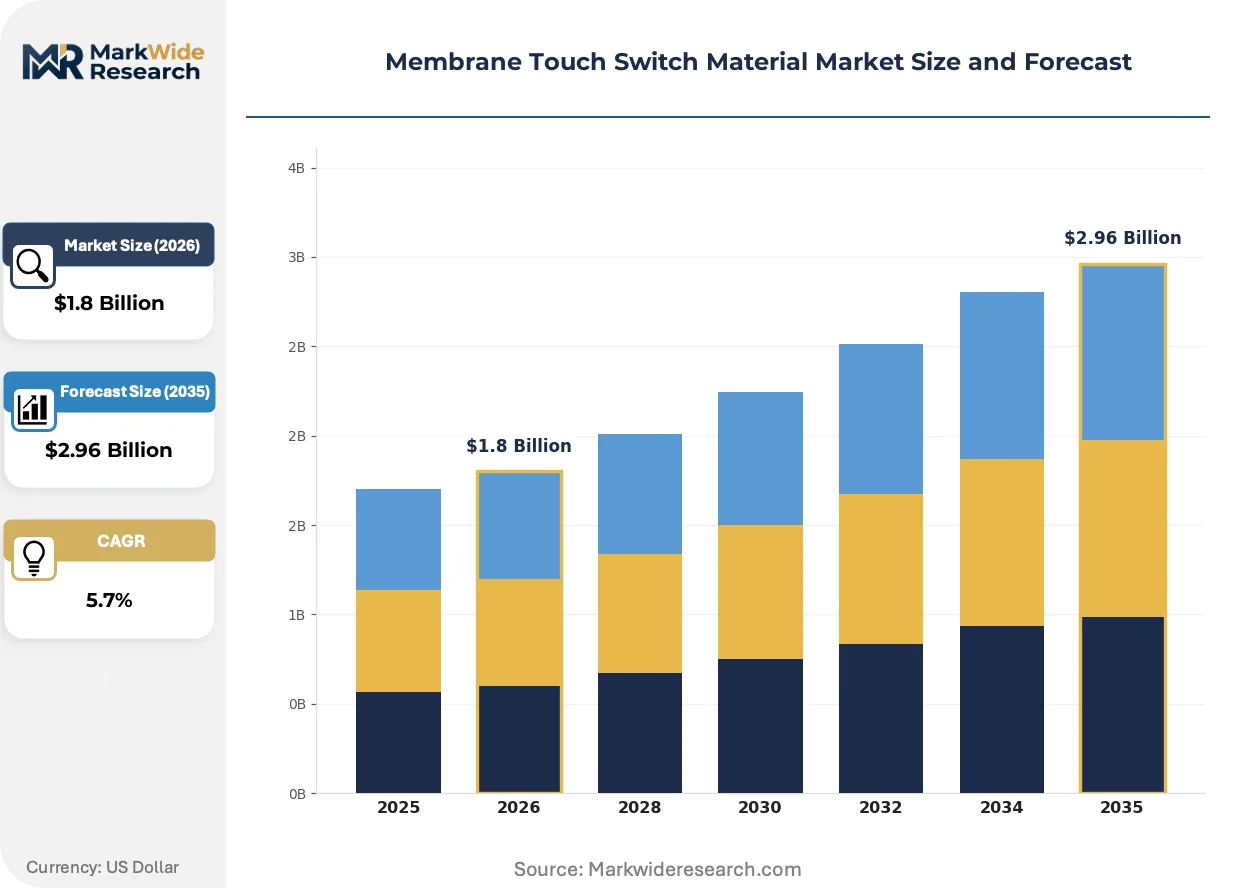
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Layer, Multi-Layer, Graphic Overlays, Keypads Material: Polyester, Polycarbonate, Silicone, PVC Application: Consumer Electronics, Industrial Equipment, Medical Devices, Home Appliances Feature: Waterproof, Dustproof, Anti-glare, Customizable |
| Companies Covered | DuPont, Sabic, MacDermid Autotype, 3M, The Cubbison Company, Design Mark Industries, Tekra, Young Ji USA, Topflight Italia Spa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Membrane Touch Switch Material Market Evolving Landscape
Flexible printed electronics integration is narrowing the performance gap between conventional rigid PCBs and membrane touch switch assemblies, compressing the addressable market for traditional layered constructions while opening hybrid material opportunities.
Printed silver nanowire circuits on polyethylene terephthalate substrates are achieving bend radii under 5 millimeters with maintained conductivity. Automotive tier-one suppliers in Germany and Japan are qualifying these constructions for curved center console applications. The technology is rendering obsolete thick-film silver-carbon inks in radius-critical HMI designs.
REACH substance restrictions continue tightening phthalate plasticizer limits in PVC formulations used for graphic overlays and flexible circuits. European converters are accelerating polyester and thermoplastic polyurethane migration to maintain CE marking eligibility. Medical device and appliance OEMs with pan-European distribution footprints are now specifying non-phthalate substrates by default.
Specification-grade procurement is consolidating around certified material suppliers capable of delivering batch-level biocompatibility documentation. Hospital equipment and diagnostic device manufacturers in the United States are shortening approved vendor lists to reduce FDA audit exposure. This concentration is most visible in Class II device segments where ISO 10993 testing certificates have become table stakes for contract consideration.
Membrane Touch Switch Material Market Segmentation
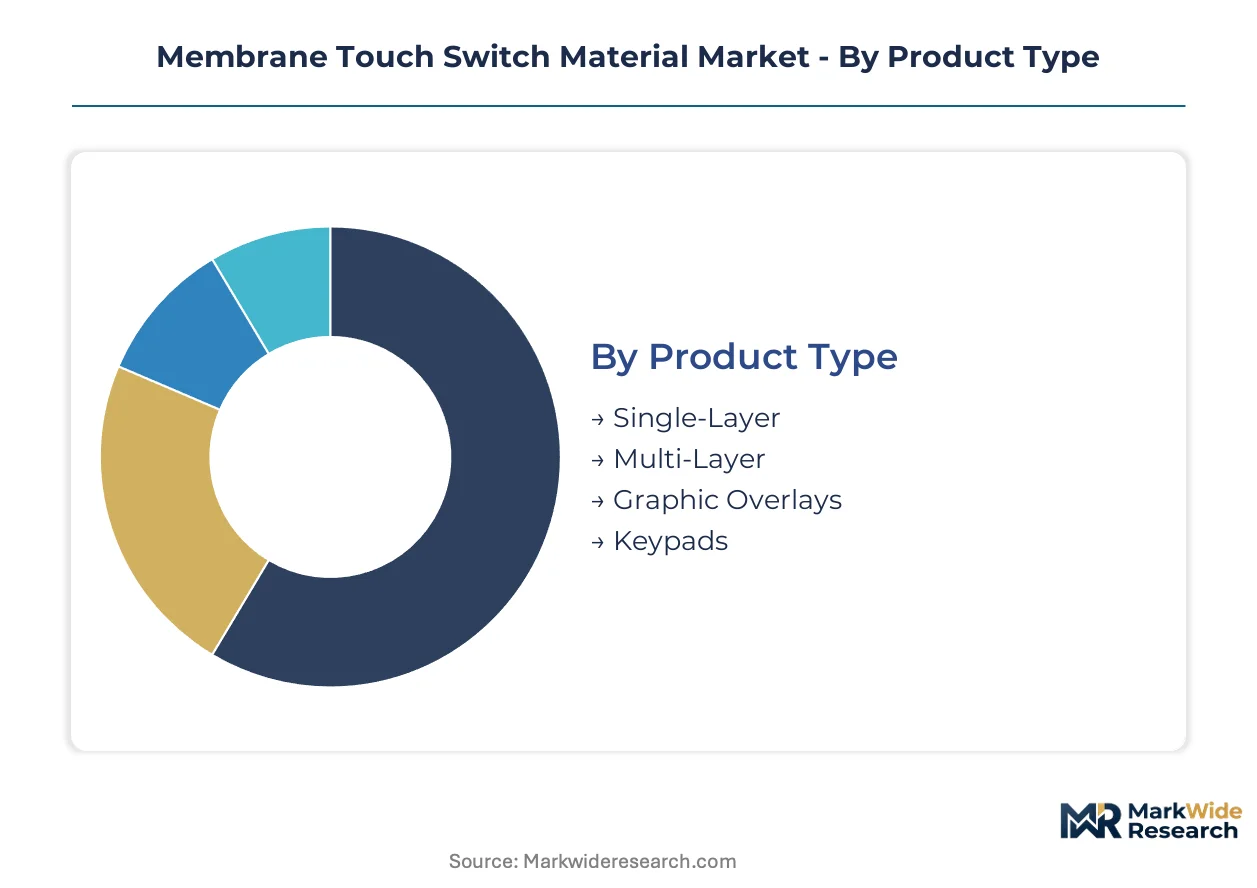
Membrane touch switch material procurement varies sharply by end-use environment, from sterile surgical suites to industrial shop floors. Specification requirements for biocompatibility, impact resistance, and sealing integrity create distinct material tiers that command different margin structures.
Product Type:
Construction complexity spans from simple single-sheet actuators to multi-layer assemblies with tactile domes and embedded electronics.
- Multi-Layer:Laminated constructions integrate spacer layers, adhesive films, and conductive circuits between substrate and overlay films. German automotive HMI clusters and FDA-regulated diagnostic equipment OEMs drive specification-grade consumption for sealed, low-profile input surfaces requiring tactile feedback.
- Graphic Overlays:Surface-printed polyester or polycarbonate films provide branding, labeling, and environmental protection without embedded circuitry. Appliance manufacturers in the United States and consumer electronics brands specify these for cost-sensitive applications where electrical function resides on separate PCBs.
- Single-Layer:Basic printed polyester constructions serve simple on-off switching in low-cycle applications.
- Keypads:Molded silicone or thermoplastic elastomer buttons integrate with membrane substrates for raised-actuation interfaces.
Established volume favors graphic overlays; emerging adoption favors multi-layer assemblies with embedded flexible electronics.
Material:
Substrate selection trades off sterilization tolerance, optical clarity, and regulatory compliance against unit cost.
- Silicone:Platinum-cured elastomer formulations achieve ISO 10993 biocompatibility certification and withstand gamma radiation and autoclave sterilization cycles. Surgical robotics OEMs and point-of-care diagnostic device manufacturers are expanding procurement to meet FDA 21 CFR Part 820 and EU MDR traceability mandates.
- Polyester:Biaxially oriented polyethylene terephthalate films in 0.125-0.25 millimeter thicknesses provide dimensional stability for screen-printed silver-carbon circuits. REACH restrictions on phthalate plasticizers in PVC are accelerating European converter migration to polyester substrates for graphic overlays and flexible circuits.
- Polycarbonate:Optical-grade resin formulations deliver impact resistance and clarity for industrial HMI panels requiring vandal resistance.
- PVC:Legacy formulations face declining specification in European supply chains due to ECHA substance restrictions on plasticizer chemistries.
Polyester dominates current procurement volumes; silicone is climbing the fastest on medical device qualification cycles.
Application:
End-use environments dictate sealing requirements, actuation cycle counts, and regulatory documentation burdens.
- Medical Devices:Class I-III equipment under EU MDR and FDA frameworks requires batch-level biocompatibility documentation and ISO 10993 testing certificates. Hospital equipment manufacturers in the United States are consolidating approved vendor lists to reduce audit exposure.
- Industrial Equipment:Food processing and pharmaceutical packaging machinery replacement cycles are driving sealed membrane adoption in the United States.
- Consumer Electronics:Cost-sensitive segments are migrating to flexible printed electronics alternatives, compressing traditional membrane addressable market.
- Home Appliances:Branding-driven graphic overlay procurement ties to volume appliance manufacturing with shorter qualification timelines.
Industrial equipment represents mature replacement demand; medical devices are gaining share fastest on regulatory-driven material upgrading.
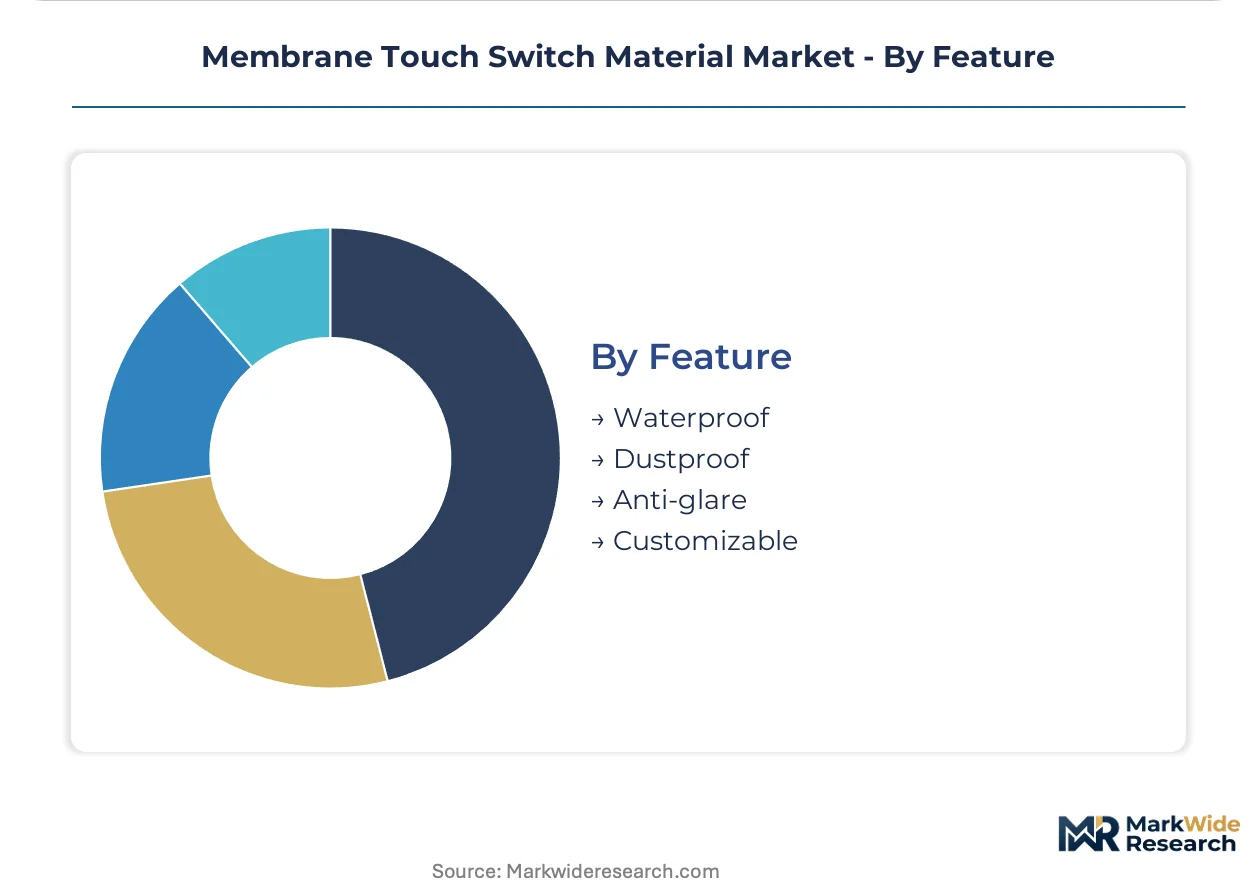
Feature:
Performance specifications differentiate commodity offerings from premium-tier membrane assemblies.
- Waterproof:IP67-rated sealing constructions prevent liquid ingress in medical sterilization environments and industrial washdown applications. IEC 60601 isolation standards for medical electrical equipment are tightening dielectric requirements for touch interfaces in diagnostic and surgical equipment.
- Dustproof:Sealed perimeter constructions protect circuit layers in agricultural machinery and outdoor industrial controls.
- Anti-glare:Surface-treated overlays reduce reflectance for outdoor and high-ambient-light HMI installations.
- Customizable:Digital printing and laser-cutting capabilities enable low-minimum-order-quantity production for specialized industrial and medical applications.
Waterproof specifications command widest application; customizable feature sets are expanding most quickly on short-run digital manufacturing capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in membrane touch switch materials tilt toward net-import positions in Western Europe and North America, while East Asian supply bases capture growing intra-regional demand from electronics manufacturing clusters.
United States
Hospital equipment manufacturers in Minnesota and Massachusetts are consolidating approved vendor lists to streamline FDA 21 CFR Part 820 audit compliance. Domestic procurement of silicone-based membranes is climbing on diagnostic device requalification cycles. Industrial automation retrofit demand concentrates in Wisconsin and Ohio food-processing machinery corridors.
Germany
Automotive HMI cluster procurement in Bavaria and Baden-Württemberg drives specification-grade polyester and polycarbonate consumption. REACH restrictions on phthalate plasticizers are accelerating PVC substitution across converter supply chains. Berlin-Brandenburg medical device startups are qualifying silicone overlays for surgical robotics interfaces.
China
Domestic appliance brands in the Yangtze River Delta are migrating graphic overlay procurement to local polyester film converters. GB standards for electrical equipment are tightening dielectric requirements for touch interfaces. Shenzhen and Dongguan electronics assemblers are integrating membrane switches into export-bound consumer devices.
Japan
Automotive tier-one suppliers in Aichi Prefecture are qualifying printed silver nanowire constructions for curved center console applications. METI industrial standards are shaping material specifications for next-generation HMI panels. Osaka-based industrial equipment OEMs are specifying sealed membrane assemblies for pharmaceutical packaging machinery.
South Korea
Display panel manufacturers in Gyeonggi Province are sourcing optical-grade polycarbonate overlays for integrated touch modules. MFDS medical device regulations are driving biocompatibility documentation requirements for diagnostic equipment exports. Busan-based converters are expanding capacity for silicone keypad integration with membrane substrates.
Membrane Touch Switch Material Market Competitive Landscape
On the supply side, the industry is structured around three tiers: multinational chemical conglomerates controlling substrate resin supply, specialized film coaters serving specification-grade applications, and regional converters handling volume graphic overlay production. Strategic archetypes include resin-integrated material suppliers, certified medical membrane specialists, and scale-driven appliance component fabricators. Dominant competitive moves center on backward integration into conductive ink compounding and geographic expansion into German automotive supply corridors.
Among resin-integrated suppliers, DuPont and Sabic occupy positions anchoring high-performance substrate supply for industrial and medical segments. MacDermid Autotype exemplifies the specialized film coater archetype, sitting within the certified supplier tier where hard-surface durability and batch-level traceability command specification premiums.
| Leading Market Players |
|---|
| DuPont |
| Sabic |
| MacDermid Autotype |
| 3M |
| The Cubbison Company |
| Design Mark Industries |
| Tekra |
| Young Ji USA |
| Topflight Italia Spa |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor's freight cost volatility feeds directly into European converter margins, amplifying price differentiation between specification-grade silicone membrane suppliers and commodity polyester graphic overlay producers while concentrating procurement leverage among Bavarian automotive HMI clusters.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command certification-grade margins through ISO 10993 biocompatibility documentation and batch-level FDA traceability, while economy segments face cost compression from flexible printed electronics substitution. Price differentiation rests on sterilization tolerance and REACH compliance status. Appliance manufacturers in cost-sensitive segments exhibit highest price sensitivity; surgical robotics OEMs show lowest.
Supply Chain Analysis
Contract manufacturing capacity concentrates among German automotive-tier converters, Yangtze River Delta appliance component fabricators, and Gyeonggi Province display panel integrators. Raw material flows draw from Saudi polycarbonate resin supply, Chinese silver nanoparticle ink production, and Japanese polyimide film heritage. Single-source vulnerability in conductive ink compounding expertise creates structural risk. Distribution runs through certified medical membrane specialists and volume graphic overlay distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise for low-resistance, high-flex circuits remains scarce outside established converter hubs, constraining supply expansion and consolidating margin capture among incumbent certified suppliers.
For Market Incumbents: Insulate specification-grade positioning through captive conductive ink compounding capabilities and accelerated EU MDR certification investments. Flexible printed electronics substitution threatens traditional layered constructions; backward integration into silver-carbon hybrid ink formulation secures supply continuity against commodity price volatility. For New Entrants and Emerging Players: Mid-market industrial automation retrofit demand in the American Midwest represents the most penetrable entry point, with food processing machinery replacement cycles shortening qualification timelines. Silicone keypad integration for point-of-care diagnostic devices offers a second white-space target. Lead with digital printing capabilities for low-minimum-order-quantity production to bypass incumbent volume advantages. For Investors and Strategic Acquirers: EU MDR Class II-III device requalification cycles reshape the acquisition landscape toward certified material suppliers with existing ISO 10993 testing infrastructure. Long-term viability favors resin-integrated conglomerates and specialized film coaters with hospital equipment approved vendor list status. Monitor FDA 21 CFR Part 820 audit enforcement intensity as an inflection signal for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Ink Compounding | Captive silver-carbon formulation supply secures margin against precious metal commodity volatility. |
| EU MDR Certification Fast-Track Investment | Accelerated ISO 10993 documentation enables Class II-III device procurement eligibility. |
| Digital Manufacturing Capability Expansion | Laser-cutting and short-run printing capture customizable-feature demand from specialized industrial applications. |
| German Automotive HMI Corridor Presence | Bavarian and Baden-Württemberg OEM proximity anchors specification-grade polyester and polycarbonate consumption. |
| Silicone Sterilization Tolerance Qualification | Gamma and autoclave resistance certifications penetrate surgical robotics and diagnostic equipment procurement. |
Research Methodology
A standing panel of membrane converter operations directors, medical device procurement managers, automotive HMI platform engineers, and industrial automation aftermarket specialists provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation from FDA 510(k) filings, ECHA REACH substance restriction updates, SEC 10-K resin supplier disclosures, and German automotive production databases. Bottom-up volume modeling triangulated against top-down chemical industry consumption estimates.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation dimensions spanning product construction complexity, substrate material chemistry, end-use regulatory environment, and geographic certification cluster. CAGRs derived from elasticity-adjusted demand curves incorporating silver price volatility indices and medical device requalification cycle frequencies. Industry-specific forecast inputs included REACH phthalate restriction implementation timelines and IEC 60601 isolation standard revision trajectories.
Practitioners should monitor silver commodity exchange movements, EU MDR audit enforcement intensity, and flexible printed electronics yield improvements for early signals of forecast revision. Quarterly review of converter capacity utilization rates and hospital equipment approved vendor list consolidation velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Thermoplastic Polyolefin Membranes Market
Membrane Materials
Polymer Electrolyte Membrane Fuel Cells (Pemfcs) Market
Membrane Materials
North America Transparent Conductive Films Market
Membrane Materials
Global Nanomembrane Market
Membrane Materials
Membrane Filter Cartridge Market
Membrane Materials
Global Track Etched Membrane Market
Membrane Materials
Global Polymer Nanomembrane Market
Membrane Materials
Reverse Osmosis Films Market
Membrane Materials
Global Gas Separation Membranes Market
Membrane Materials
North America Roofing Membranes Market
Membrane Materials
Polyarylsulfone (PAS) Market
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
Europe Gas Barrier Membrane Market
Membrane Materials
APP and SBS Modified Bitumen Membrane Market
Membrane Materials
Global Ion Exchange Membrane Market
Membrane Materials
Membrane Chemicals Market