
 Spain Respiratory Devices Market | 2026-2036
Spain Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Respiratory Devices Market Analytics
MDR is hardening the cost-of-entry calculus for manufacturers targeting Spain. GE HealthCare leverages its installed base of ventilators to sustain service revenue streams across Spanish hospital networks. Koninklijke Philips N.V. anchors its position through integrated sleep apnea diagnostics-to-therapy workflows. Medtronic plc differentiates via advanced portable oxygen concentrators designed for ambulatory patient mobility.
Respiratory devices encompass mechanical and electromechanical apparatus engineered to assist, monitor, or replace pulmonary function, with ventilators typically operating at pressure ranges of 5–40 cm H₂O and oxygen concentrators delivering 90–96% purity at flow rates up to 10 L/min. Their primary commercial purpose centers on therapeutic intervention for obstructive and restrictive lung pathologies across acute and chronic care settings. Inhalers occupy the largest volume position among device types due to ubiquity in asthma and COPD maintenance protocols, while smart devices within the technology dimension command premium positioning through remote monitoring capabilities and adherence analytics. The homecare end-user segment exhibits the steepest trajectory as Spain's regional health services expand domiciliary respiratory support programs to reduce hospital readmission burdens.
BIS-equivalent Spanish medical device standards and EU MDR conformity requirements shape product registration timelines and clinical evidence obligations for market access. Spain's national health system procurement frameworks and regional tendering authorities influence pricing negotiations and distribution channel selection across autonomous communities. Stakeholders must monitor evolving reimbursement thresholds for connected respiratory technologies as cost-effectiveness criteria tighten under decentralized purchasing mandates.
Market Dynamics
EU MDR compliance timelines are compressing product registration windows for manufacturers targeting Spain, forcing accelerated clinical evidence generation and quality management system overhauls ahead of notified body capacity constraints.
Growth Catalysts
- Regional domiciliary expansion:Catalonia and Madrid autonomous communities are scaling home-based respiratory support programs to reduce acute hospital bed utilization. This decentralization creates sustained equipment demand from regional health service procurement authorities.
- MDR transitional provisions:Extended certificate validity for legacy devices under EU MDR Article 120 allows continued market presence while manufacturers complete conformity assessments. This regulatory bridge sustains supply continuity during system strain.
- Aging respiratory burden:Spain's 65-plus demographic concentration in coastal provinces drives COPD and sleep apnea diagnostic volumes. Pulmonology service networks in Valencia and Andalusia are expanding screening capacity to match prevalence curves.
Market Restraints
- Notified body bottlenecks:Limited EU MDR-designated entities are extending technical documentation review timelines to 18-24 months. Manufacturers face launch delays and portfolio rationalization pressures.
- Semiconductor input volatility:Flow sensors and pressure transducers depend on specialized MEMS fabrication concentrated in East Asian foundries. Supply intermittency disrupts ventilator and high-flow oxygen device production schedules.
- Pneumatics supplier concentration:Precision valve and compressor subsystems source from a narrow base of German and Swiss component specialists. Geographic concentration amplifies logistics cost exposure and tariff vulnerability.
Strategic Opportunities
- Connected adherence platforms:Integration of nebulizer usage sensors with regional health information systems enables remote monitoring reimbursement under evolving SNS criteria. Data-driven therapy optimization creates service revenue streams.
- Galicia and Basque Country penetration:These northern autonomous communities show underdeveloped home respiratory infrastructure relative to central Spain. Early tender participation secures preferred supplier positioning ahead of competitive saturation.
- AI-embedded diagnostic workflows:Machine learning classification of spirometry and polysomnography data converges with cloud-based clinical decision support. Pulmonology departments in Madrid's hospital networks are piloting automated severity stratification.
Industry Challenges
- Clinical evidence generation capacity:EU MDR requires expanded post-market surveillance and PMCF studies. Contract research organizations with respiratory device specialization face booking constraints that delay submission readiness.
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization assessments for polymer-containing inhalation interfaces are queuing at accredited laboratories. Extended timelines compress product update windows.
- Legacy system integration friction:Connected respiratory devices must interface with heterogeneous hospital information systems across Spain's 17 autonomous communities. API standardization gaps force costly custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Respiratory Devices Market |
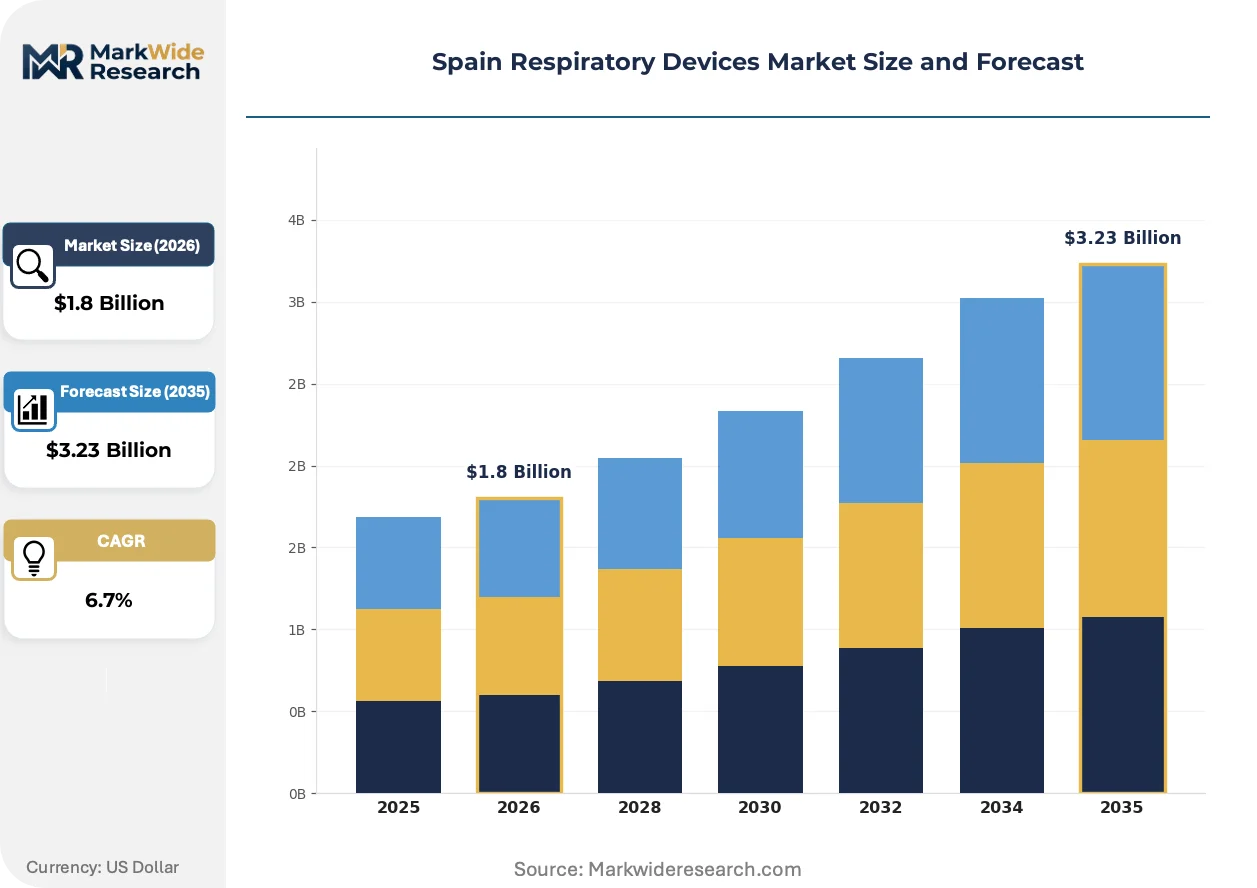
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Inhalers, Nebulizers, Ventilators, Oxygen Concentrators End User: Hospitals, Homecare, Clinics, Long-term Care Facilities Application: Asthma, COPD, Sleep Apnea, Acute Respiratory Distress Technology: Smart Devices, Portable Units, Manual Systems, Automated Systems |
| Companies Covered | GE HealthCare, Koninklijke Philips N.V., Fisher & Paykel Healthcare Ltd, Medtronic plc, ResMed, Dragerwerk AG, Breas Medical AB, GlaxoSmithKline PLC, Hamilton Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Respiratory Devices Market Evolving Landscape
Digital respiratory therapeutics are displacing conventional mechanical platforms across Spanish care settings, with software-enabled dosing and remote titration becoming baseline expectations rather than premium differentiators.
Portable oxygen concentrator technology is consolidating around lightweight lithium-ion power systems and pulse-dose delivery algorithms. Homecare providers in Andalusia and Catalonia are standardizing on sub-five-kilogram units for ambulatory patient cohorts. This specification convergence is compressing supplier margins and favoring manufacturers with captive battery cell sourcing.
EU MDR Article 10 quality management mandates are hardening post-market surveillance obligations for all risk-class respiratory devices. Spanish notified bodies are demanding systematic PMCF data collection through patient registries. Class IIa and IIb manufacturers with inhaler and sleep therapy portfolios face disproportionate clinical follow-up cost burdens.
Hospital procurement authorities are unbundling device acquisition from preventive maintenance contracts. Castile and León regional tendering bodies now separate capital expenditure and service line items, enabling multi-vendor service competition. This disaggregation pressures incumbent suppliers defending integrated pricing models and creates entry points for independent service organizations.
Spain Respiratory Devices Market Segmentation
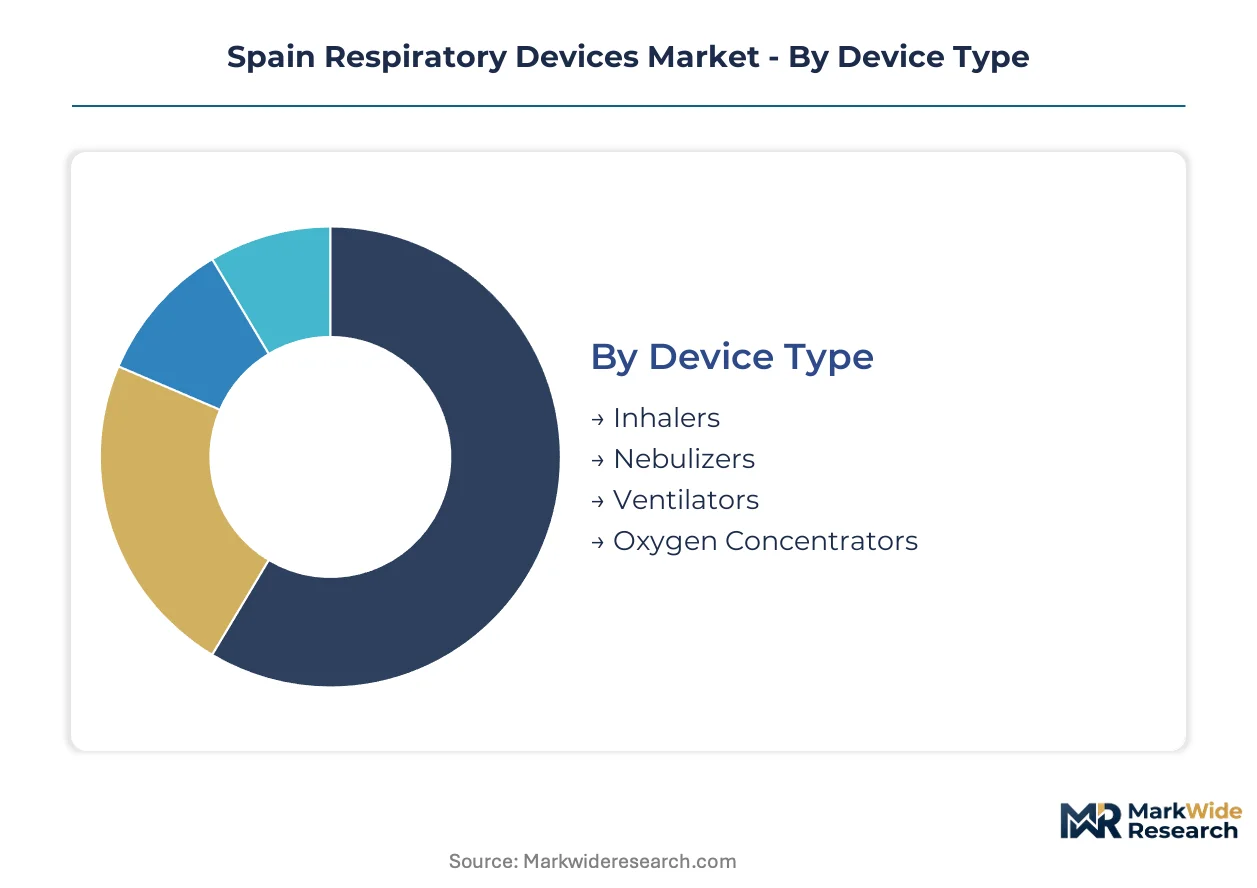
Respiratory device segmentation in Spain reflects divergent reimbursement pathways across autonomous communities and varying technical specifications demanded by hospital procurement frameworks. Understanding category boundaries enables manufacturers to align product portfolios with regional tendering priorities and evolving SNS coverage criteria.
Device Type:
Pressure ranges, flow rates, and portability specifications define competitive positioning across therapeutic modalities.
- Inhalers:Pressurized metered-dose and dry-powder inhalers deliver bronchodilators and corticosteroids through standardized canister or capsule mechanisms. Catalonia's primary care networks procure these in highest volumes for asthma maintenance protocols, with SNS reimbursement favoring generic formulations that compress device margin structures.
- Ventilators:Electromechanical systems operating at 5–40 cm H₂O pressure ranges support invasive and non-invasive ventilation across ICU and emergency settings. Madrid's hospital networks drive replacement demand as aging installed bases require technology upgrades under regional capital expenditure programs.
- Nebulizers:Compressor-driven and mesh-atomizing units convert liquid medication into respirable aerosols for patients with severe obstruction. Homecare adoption in Andalusia concentrates demand for portable ultrasonic variants.
- Oxygen Concentrators:Pressure-swing adsorption systems deliver 90–96% purity oxygen at flow rates up to 10 L/min. Valencia's domiciliary support programs prioritize lightweight pulse-dose units for ambulatory COPD cohorts.
Inhalers lead on scale; oxygen concentrators lead on momentum.
End User:
Procurement authority and reimbursement eligibility vary sharply across care settings.
- Hospitals:Acute care facilities in Madrid and Barcelona metropolitan areas concentrate high-acuity ventilator and high-flow nasal cannula demand. Regional health service tendering bodies negotiate multi-year framework agreements that lock in supplier relationships.
- Homecare:Domiciliary respiratory support programs in Catalonia and Andalusia are expanding fastest as autonomous communities seek to reduce hospital readmission metrics. SNS reimbursement for connected monitoring devices is tightening eligibility to cost-effectiveness thresholds.
- Clinics:Outpatient pulmonology centers in Valencia perform diagnostic spirometry and sleep studies, generating demand for portable screening equipment.
- Long-term Care Facilities:Nursing homes across Castile and León require basic oxygen delivery systems and suction apparatus for chronic respiratory management.
Hospitals dominate procurement value; homecare is expanding most quickly.
Application:
Disease prevalence curves and screening infrastructure penetration determine addressable patient populations.
- Asthma:Allergic and non-allergic variants affect pediatric and adult populations disproportionately in coastal provinces with higher allergen exposure. Primary care prescribing volumes in Catalonia exceed other autonomous communities.
- COPD:Tobacco-related and biomass-exposure etiologies concentrate in aging demographics across Andalusia and Galicia. Pulmonology service networks are expanding screening capacity to match prevalence.
- Sleep Apnea:Obstructive sleep-disordered breathing drives diagnostic demand in Madrid's private sleep laboratory sector. Home sleep testing devices are displacing in-lab polysomnography for initial screening.
- Acute Respiratory Distress:Viral pneumonia and sepsis-related lung injury generate episodic ventilator demand spikes. ICU surge capacity planning in Basque Country favors modular ventilator fleets.
COPD leads on scale; sleep apnea leads on momentum.
Technology:
Connectivity specifications and power architecture differentiate premium positioning from commodity supply.
- Smart Devices:Sensor-embedded inhalers and cloud-connected ventilators transmit usage data to regional health information systems. SNS pilot programs in Madrid are testing remote monitoring reimbursement for adherence analytics.
- Portable Units:Battery-powered oxygen concentrators and travel ventilators enable ambulatory patient mobility. Lithium-ion cell sourcing constraints are compressing supplier margins for sub-five-kilogram specifications.
- Manual Systems:Basic nebulizers and bag-valve-mask resuscitators serve emergency backup and resource-limited settings. Galicia's rural health posts maintain these for infrastructure redundancy.
- Automated Systems:Closed-loop oxygen titration and adaptive servo-ventilation reduce clinician intervention burden. Hospital procurement in Catalonia is standardizing on these for ICU staffing efficiency.
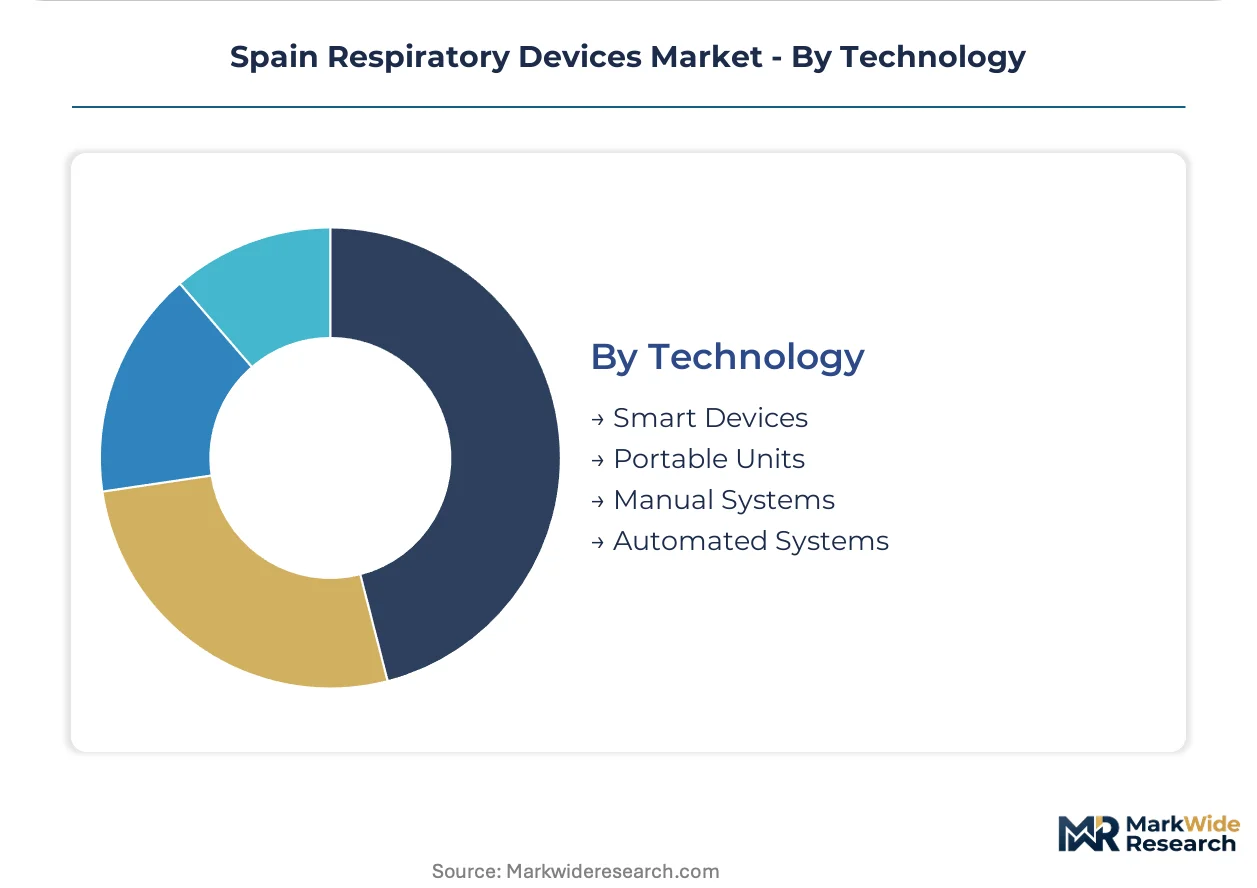
Manual systems lead on scale; smart devices lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pulmonology specialists and respiratory therapists concentrate in Spain's autonomous communities with the highest COPD and sleep apnea prevalence, creating regional demand clusters that shape procurement patterns and service infrastructure.
Catalonia
Barcelona's hospital networks drive ventilator replacement cycles while primary care centers in Girona and Tarragona generate inhaler prescription volumes exceeding other autonomous communities. The Catalan Health Service (CatSalut) expanded domiciliary oxygen reimbursement criteria in 2023. Sabadell's medical device distribution corridor anchors logistics for northeastern Spain.
Madrid
The capital's private sleep laboratory sector concentrates diagnostic demand for home sleep testing devices displacing in-lab polysomnography. Madrid's regional health service (SERMAS) pilots remote monitoring reimbursement for connected inhalers under SNS cost-effectiveness frameworks. The Alcorcón-Getafe hospital cluster standardizes on automated oxygen titration systems for ICU staffing efficiency.
Andalusia
Aging demographics in Seville and Málaga drive COPD screening expansion through pulmonology service networks. The Andalusian Health Service (SAS) scales portable ultrasonic nebulizer procurement for homecare programs reducing hospital readmissions. Córdoba's respiratory rehabilitation centers generate demand for lightweight pulse-dose oxygen concentrators.
Valencia
Coastal allergen exposure elevates pediatric asthma diagnostic volumes in Alicante and Castellón primary care networks. The Valencian Health Service (Conselleria de Sanitat) prioritizes sub-five-kilogram portable oxygen units for ambulatory COPD cohorts. Elche's manufacturing zone supplies polymer components for inhaler interfaces facing ISO 10993 biocompatibility testing queues.
Basque Country
Bilbao's hospital networks pilot modular ventilator fleets for ICU surge capacity planning against viral pneumonia demand spikes. The Basque Health Service (Osakidetza) tenders separately for device acquisition and preventive maintenance, enabling multi-vendor service competition. San Sebastián's underdeveloped home respiratory infrastructure presents early supplier positioning opportunities.
Spain Respiratory Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Spain's respiratory device procurement landscape. The market exhibits tiered consolidation with premium positioning held by integrated diagnostics-to-therapy workflow providers and commodity supply dominated by regional distributors. Three archetypes define competitive structure: multinational health technology conglomerates leveraging installed base service revenue, specialized respiratory pure-plays commanding ambulatory mobility segments, and pharmaceutical-device hybrids capturing inhaler volume through formulation-device bundling. M&A activity concentrates on connected adherence platform capabilities while geographic expansion targets underpenetrated northern autonomous communities.
Within the multinational conglomerate tier, GE HealthCare and Koninklijke Philips N.V. exemplify installed-base defense strategies across Spanish hospital networks. These entities occupy positions sustained by service revenue streams and integrated workflow offerings rather than device sales alone. Medtronic plc represents the specialized mobility archetype, with its corporate structure signaling pure-play respiratory focus distinct from diversified competitors.
| Leading Market Players |
|---|
| GE HealthCare |
| Koninklijke Philips N.V. |
| Fisher & Paykel Healthcare Ltd |
| Medtronic plc |
| ResMed |
| Dragerwerk AG |
| Breas Medical AB |
| GlaxoSmithKline PLC |
| Hamilton Medical |
| Others |
Value Network & Pricing Analysis
Family-owned German pneumatics specialists anchor precision valve and compressor sourcing for Spanish ventilator manufacturers, translating geographic supply concentration into persistent pricing power over device OEMs facing EU MDR compliance cost inflation.
Pricing Analysis
Bundled preventive maintenance contracts are unbundling from device acquisition across Castile and León regional tenders, separating capital expenditure and service line items to enable multi-vendor service competition. Pricing stratifies across premium, standard, and economy tiers based on connectivity specifications and ISO 13485 certification grade. Cost compression in standard ventilator tiers is intensifying because hospital procurement authorities now benchmark against multi-source framework agreements. Homecare providers exhibit highest price sensitivity due to SNS reimbursement tightening, while ICU departments show lowest sensitivity given staffing efficiency mandates.
Supply Chain Analysis
Direct-to-hospital channels handle high-acuity ventilator demand from Madrid and Barcelona metropolitan networks, while distributor-mediated pathways serve primary care inhaler procurement across rural autonomous communities. MEMS fabrication for flow sensors and pressure transducers draws from Taiwan, South Korea, and Japan. Lithium-ion battery cells for portable oxygen concentrators rest on Chinese and South Korean cathode supply. Single-source vulnerability concentrates in German and Swiss precision pneumatics specialists. Distribution runs through Sabadell's medical device corridor for northeastern Spain and Madrid's logistics hub for central regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's respiratory device market compounds steadily as regional health services expand domiciliary reimbursement criteria, embedding recurring equipment demand into autonomous community procurement cycles.
For Market Incumbents: Acquire connected adherence platform capabilities to defend service revenue streams as Castile and León procurement authorities unbundle maintenance from device sales. Consolidate backward integration into lithium-ion cell supply chains to offset margin pressure from sub-five-kilogram portable oxygen concentrator specification convergence. Counter emerging pure-play mobility specialists by locking in multi-year framework agreements with CatSalut and SERMAS before competitive saturation accelerates. For New Entrants and Emerging Players: Telehealth-integrated distribution partnerships offer the lowest-friction entry path into Galicia and Basque Country home respiratory infrastructure gaps. Target San Sebastián's underdeveloped domiciliary support programs ahead of competitive tender participation. Prioritize lightweight pulse-dose oxygen concentrator specifications aligned with Valencian Health Service ambulatory COPD criteria. Lead with remote monitoring reimbursement pilot eligibility under evolving SNS cost-effectiveness frameworks. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors with established CatSalut and SERMAS relationships but limited proprietary device portfolios. Five-to-ten year viability hinges on EU MDR conformity completion and connected technology integration. Target acquisition archetypes include specialized respiratory pure-plays with ambulatory mobility focus and software-enabled dosing platforms. Monitor notified body designation expansion as the critical inflection signal for registration timeline normalization.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 120 transitional provisions sustain market presence during conformity assessment completion. |
| Hospital System Partnership | Madrid's Alcorcón-Getafe cluster standardizes on automated oxygen titration for ICU staffing efficiency. |
| Software Companion Development | Connected inhaler usage sensors enable remote monitoring reimbursement under evolving SNS criteria. |
| Reimbursement Strategy | CatSalut's expanded domiciliary oxygen criteria create sustained procurement demand for portable concentrators. |
| Backward Integration | Captive lithium-ion cell sourcing compresses supplier margins for sub-five-kilogram oxygen specifications. |
Research Methodology
Coverage spans Catalonia, Madrid, Andalusia, Valencia, and Basque Country, with primary inputs from each autonomous community's health service procurement authorities. The analysis combines structured interviews with hospital biomedical engineers, regional tendering officers, GPO contracts managers, and homecare provider operations leads with secondary validation from hospital procurement databases, SNS reimbursement bulletins, and EU MDR notified body registers. Bottom-up equipment shipment tracking and top-down health expenditure allocation triangulate market sizing across device categories.
Granularity-level modeling distinguishes pressure ranges, flow rates, and portability specifications within ventilator and oxygen concentrator segments, while connectivity specifications differentiate smart device premiums from manual system commodities. CAGRs derive from autonomous community-level procurement pipeline analysis and prevalence-based patient population forecasting across COPD, sleep apnea, and asthma cohorts. EU MDR transition timelines and SNS reimbursement evolution feed scenario-weighted projections.
The model assumes a particular technology adoption path; alternative pathways for AI-embedded diagnostic workflows would alter the outlook if automated severity stratification accelerates beyond Madrid pilot programs. Forecasts reflect assumptions regarding notified body capacity expansion, semiconductor supply normalization, and regional domiciliary program scaling. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Biopsy Devices Market
Medical Devices
Arteriovenous Fistula Devices Market
Medical Devices
Below-The-Knee Implants Market
Medical Devices
Transradial Access Devices Market
Medical Devices
Intravenous Stopcock Market
Medical Devices
High Flow Oxygen Therapy Devices Market
Medical Devices
Injectable Bone Graft Substitutes Market
Medical Devices
Medical LED Headlight Market
Medical Devices
France Ophthalmic Devices Market
Medical Devices
Photomedicine Technology Market
Medical Devices
Parenteral Feeding Devices Market
Medical Devices
Wearable Cardioverter Defibrillators Market
Medical Devices
Plastic Surgery Scaffolds Market
Medical Devices
Oxygen Conservers Market
Medical Devices
Alexandrite Gemstone Lasers Market
Medical Devices
Global Self Care Medical Devices Market