
 Global Large Volume Wearable Injectors Market | 2026-2036
Global Large Volume Wearable Injectors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Large Volume Wearable Injectors Market Foresight
Contract manufacturers in Switzerland and Germany are recalibrating cleanroom capacity to accommodate the shift from prefilled syringes to large-volume on-body systems. BD leverages backward integration into needle-free transfer systems to sustain its supply chain position across North America and Europe. Ypsomed anchors its competitive stance through dedicated manufacturing scale in Solothurn, while Enable Injections specializes in disposable cassette architectures that reduce patient training burden.
Large volume wearable injectors are electromechanical or spring-driven drug delivery devices designed to administer subcutaneous doses typically exceeding 2 mL over extended periods, incorporating pressure sensors and feedback mechanisms to ensure complete dose delivery. Their primary purpose is to enable self-administration of biologics outside clinical settings, reducing healthcare utilization while maintaining therapeutic adherence. Patch injectors and on-body delivery systems occupy the dominant volume positions, with patch platforms capturing margin pools through disposable cartridge economics and on-body systems extending into oncology and immunology applications where infusion center avoidance carries measurable value. Smart injectors featuring wireless-controlled connectivity represent the fastest-expanding technology tier, though spring-driven mechanisms retain cost advantages in price-sensitive procurement environments.
The FDA regulates these devices as combination products under 21 CFR 3.2, requiring alignment between device quality systems and drug sponsor obligations that lengthen development timelines but raise barriers to commoditized competition. EMA's MDR implementation and the EU AI Act's emerging requirements for connected health devices are simultaneously expanding documentation burdens and creating differentiation opportunities for manufacturers with pre-established notified body relationships. Stakeholders must monitor how FDA's forthcoming guidance on human factors testing for large-volume wearables interacts with EMA's evolving expectations for real-world evidence from connected devices, as divergence in these frameworks will shape geographic launch sequencing and regulatory investment priorities.
Market Dynamics
The shift from hospital-based infusion to subcutaneous self-administration is compressing device development cycles and forcing sponsors to integrate human factors validation earlier in combination product pathways.
Growth Catalysts
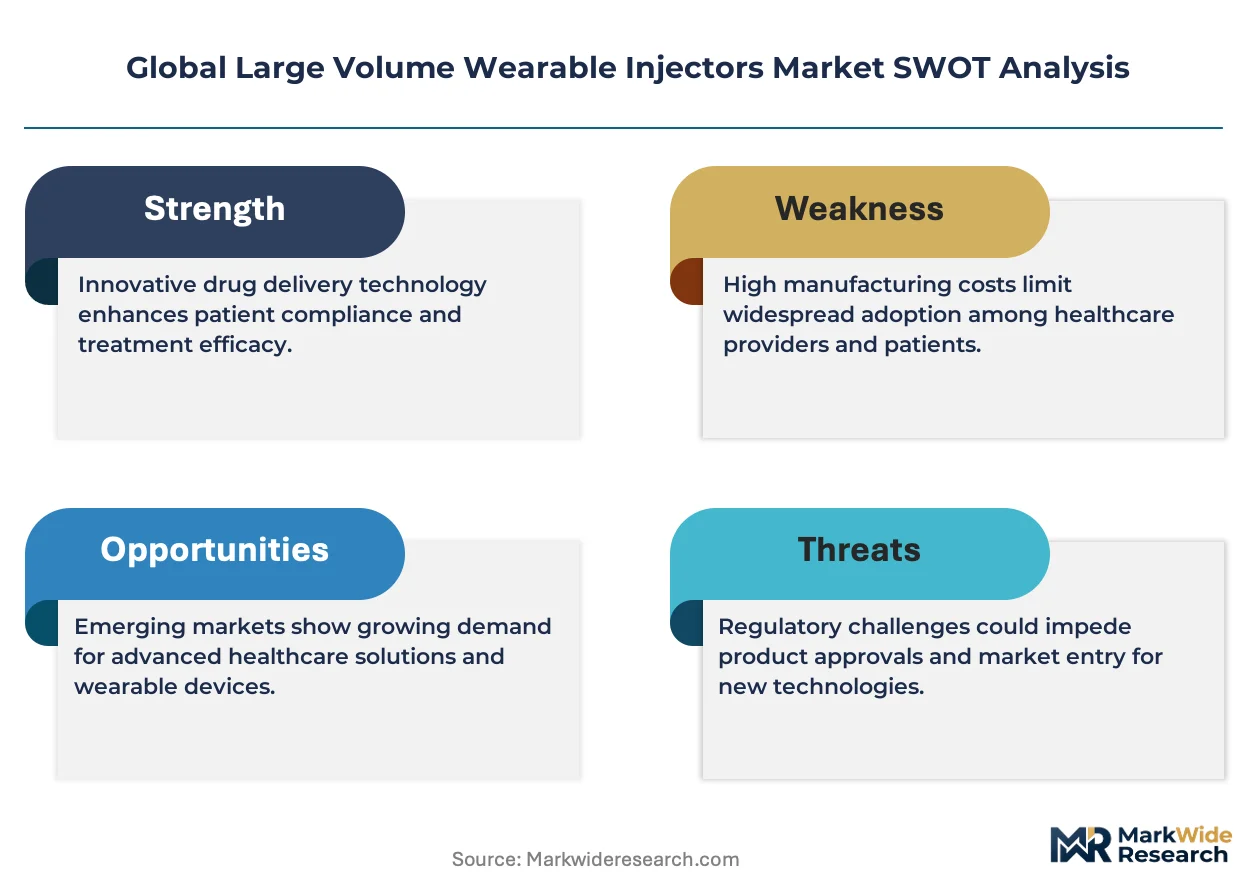
- EU MDR framework alignment:The Medical Device Regulation's enhanced clinical evidence requirements for Class III devices is accelerating notified body specialization in wearable drug delivery, creating certification scarcity that rewards early movers.
- Oncology pipeline concentration:Immuno-oncology biologics requiring volumes above 5 mL are driving sponsor demand for on-body systems that eliminate infusion center dependency.
- Spring-driven mechanism cost advantages:Electromechanical complexity in smart injectors faces price resistance from European procurement coalitions, preserving market space for simplified mechanical platforms.
Market Restraints
- Specialized polymer supply concentration:Cyclic olefin polymer and high-performance thermoplastics for cassette housings concentrate among Japanese and German chemical suppliers, exposing device makers to input cost volatility.
- FDA combination product timeline friction:The 21 CFR 3.2 requirement for synchronized device and drug sponsor quality systems extends development timelines by 12-18 months versus standalone device pathways.
- Prefilled syringe substitution in low-viscosity formulations:Standard syringe formats retain cost advantages for molecules below 2 mL, limiting wearable injector penetration in diabetes and hormone therapy segments.
Strategic Opportunities
- India CDSCO accelerated approval pathways:The country's pharmaceutical regulator has streamlined combination product reviews for devices paired with domestically manufactured biologics, opening access to a price-sensitive outpatient market.
- EU AI Act connectivity differentiation:Connected injectors with embedded algorithmic dose monitoring can leverage regulatory clarity on AI-enabled health devices to command premium positioning in German and French reimbursement frameworks.
- Home infusion channel expansion:Specialty pharmacy networks in the United States are building dedicated reimbursement codes for on-body delivery systems, bypassing traditional durable medical equipment distribution.
Industry Challenges
- Human factors engineering talent scarcity:The FDA's draft guidance on large-volume wearable usability testing requires specialized expertise in ethnographic research and failure mode analysis that outstrips current training pipeline output.
- Cleanroom capacity reconfiguration capex:Contract manufacturers must retool ISO 7-8 facilities originally designed for syringe assembly to accommodate larger-format on-body device form factors.
- Drug-device interface IP fragmentation:Patent thickets covering cassette-to-pump mechanical interfaces and pressure-sensor feedback algorithms complicate freedom-to-operate assessments for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Large Volume Wearable Injectors Market |
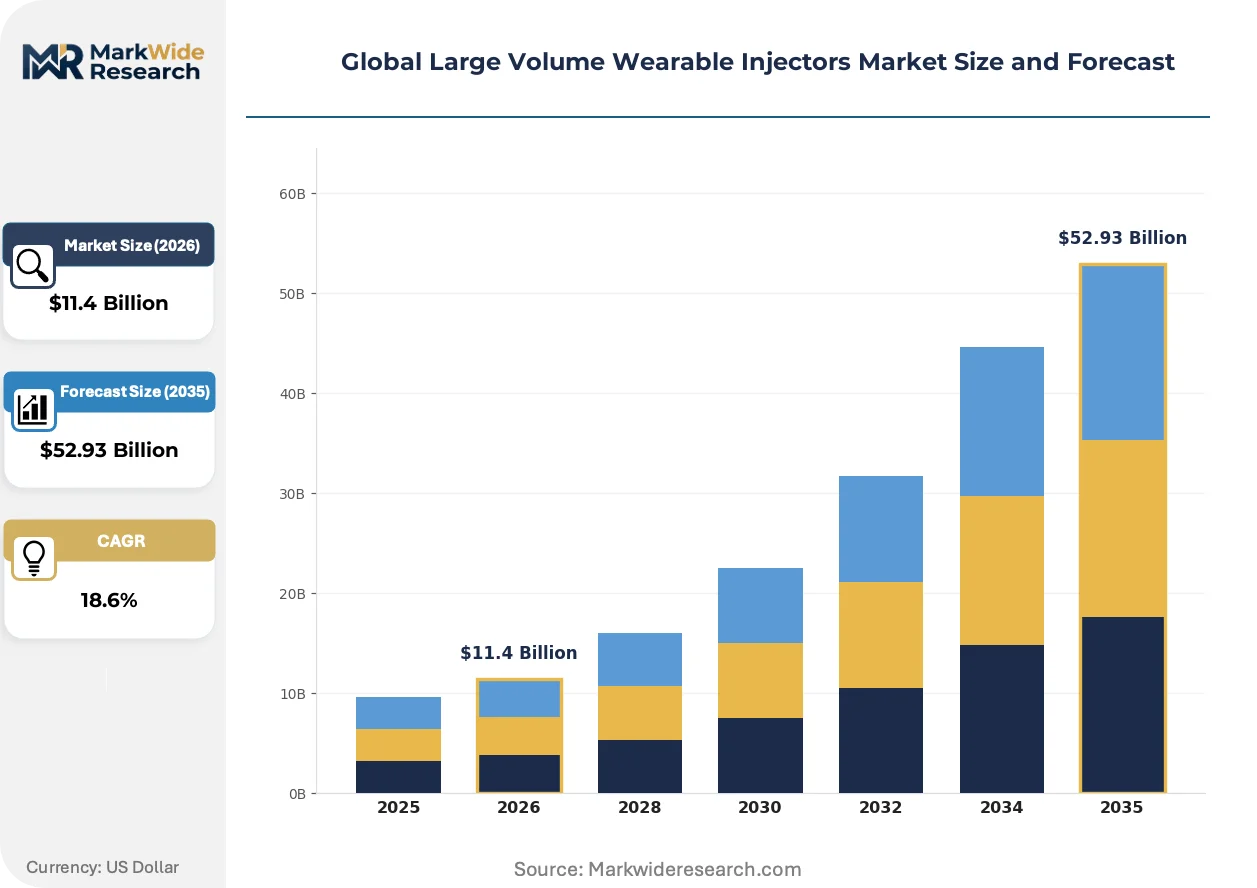
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $52.93 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patch Injectors, Belt-Worn Injectors, On-Body Delivery Systems, Portable Injectors, Smart Injectors Technology: Electromechanical, Spring-Driven, Electrochemical, Battery-Powered, Wireless-Controlled Application: Chronic Disease Management, Hormone Therapy, Insulin Delivery, Chemotherapy, Biologics Administration End User: Specialty Clinics, Home Healthcare Providers, Infusion Centers, Research Institutions |
| Companies Covered | BD, Ypsomed, Medtronic, Insulet Corporation, West Pharmaceutical Services, Amgen, Enable Injections, Sensile Medical, CeQur, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Large Volume Wearable Injectors Market Shifts & Advancements
Electromechanical connectivity, regulatory data requirements, and procurement centralization are simultaneously elevating technical complexity and consolidating vendor relationships across the wearable injector value chain.
Spring-driven disposable cassettes are overtaking reusable electromechanical bases in European oncology applications where single-use economics align with hospital infection control protocols. German and Swiss procurement coalitions have standardized on this architecture for trastuzumab and rituximab biosimilars. The shift is compressing margins for smart injector platforms while expanding addressable volume in price-sensitive therapeutic categories.
EMA's MDR implementation and the EU AI Act's emerging connectivity requirements are expanding documentation burdens for notified body submissions. Manufacturers with pre-established BSI or TÜV SÜD relationships are capturing certification queue priority. Connected injectors with real-world data capture capabilities face the steepest compliance escalation, particularly in France and Germany where digital health evidence standards are tightening fastest.
Hospital purchasing consortiums in the United States are unbundling device procurement from drug contracts, forcing wearable injector vendors to compete on standalone value rather than sponsor bundling. Specialty pharmacy networks are replacing traditional distributor relationships for patient-direct fulfillment. This channel rotation is most advanced in immunology and rare disease segments where home administration protocols are already established.
Global Large Volume Wearable Injectors Market Segmentation
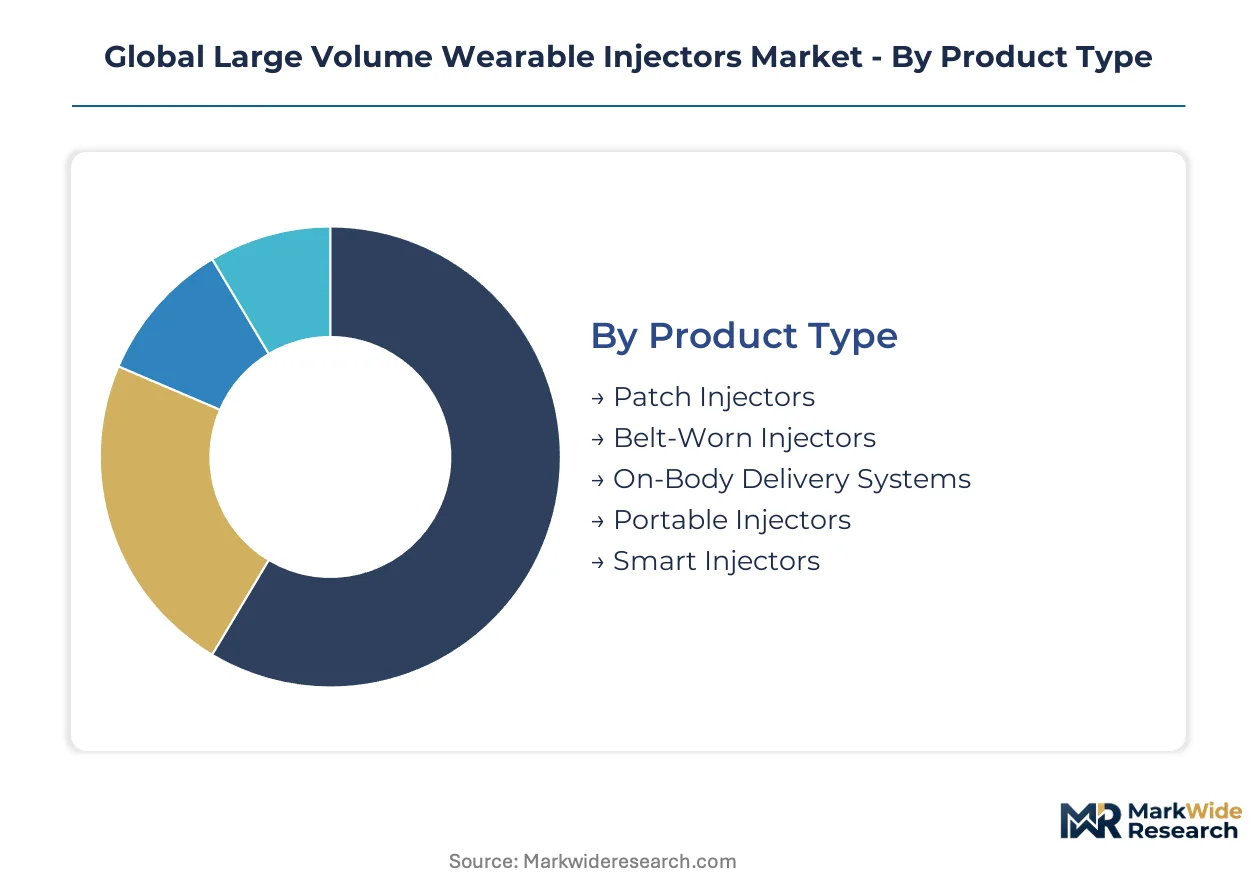
Device architecture and technology modality determine reimbursement pathways, manufacturing scale requirements, and competitive moats across the large volume wearable injector landscape. Segmentation reveals where electromechanical complexity commands premium pricing versus where simplified mechanical platforms capture volume procurement contracts.
Product Type:
Patch injectors anchor the volume tier through disposable cartridge economics, while on-body delivery systems capture premium positioning in oncology applications where infusion center avoidance justifies higher device costs.
- Patch Injectors:Adhesive-based disposable platforms integrating pre-filled drug reservoirs with passive diffusion or spring-actuated delivery mechanisms. Demand concentrates in German and Swiss hospital procurement coalitions for trastuzumab and rituximab biosimilars, where single-use infection control protocols override electromechanical feature sets.
- On-Body Delivery Systems:Electromechanical wearable pumps with programmable infusion profiles and wireless connectivity for volumes exceeding 5 mL. Adoption clusters in United States immunology and rare disease segments where specialty pharmacy reimbursement codes for home administration are expanding fastest.
- Belt-Worn Injectors:Larger-format devices accommodating reservoir volumes above 10 mL via waist-worn configurations, primarily serving chemotherapy protocols in Japanese outpatient settings.
- Portable Injectors:Handheld spring-driven systems with manual activation for intermittent dosing, penetrating price-sensitive hormone therapy markets in India.
- Smart Injectors:Connectivity-enabled platforms with embedded sensors and algorithmic dose monitoring, facing steepest compliance escalation under EU AI Act documentation requirements.
Today's leader: Patch injectors. Tomorrow's challenger: On-body delivery systems.
Technology:
Mechanical simplicity versus digital connectivity defines the cost-structure frontier, with procurement coalitions in Europe and Asia-Pacific diverging on acceptable complexity premiums.
- Spring-Driven:Compressed mechanical energy systems eliminating battery dependency and electronic failure modes. European oncology procurement has standardized on this architecture for cost containment, with German hospital purchasing consortiums driving volume scale.
- Electromechanical:Motor-driven precision dosing with programmable flow rates and pressure feedback, dominating United States immunology applications where payer reimbursement supports higher device acquisition costs.
- Electrochemical:Battery-free delivery via osmotic or chemical reaction mechanisms, emerging in glucose-responsive insulin applications.
- Battery-Powered:Rechargeable base units with disposable drug cassettes, occupying mid-tier positioning in Japanese home healthcare markets.
- Wireless-Controlled:Smartphone-integrated dosing management with real-world data capture, climbing fastest in French and German digital health reimbursement frameworks.
Spring-driven mechanisms defend volume share; wireless-controlled platforms are gaining share fastest in premium segments.
Application:
Therapeutic category determines device specification requirements, with biologics administration demanding the most sophisticated pressure-sensor feedback systems.
- Biologics Administration:High-viscosity monoclonal antibody delivery requiring extended infusion profiles and subcutaneous tissue pressure monitoring. United States specialty pharmacy networks are building dedicated reimbursement infrastructure for these devices.
- Chronic Disease Management:Long-term self-administration protocols for conditions requiring frequent dosing, with German and Japanese aging populations driving demand concentration.
- Chemotherapy:Cytotoxic drug delivery with strict occupational safety requirements, favoring closed-system on-body platforms in European hospital settings.
- Insulin Delivery:Rapid-acting and basal insulin administration, where standard pump technology limits large-volume wearable penetration below 2 mL thresholds.
- Hormone Therapy:Intermittent dosing regimens with lower viscosity requirements, retaining prefilled syringe substitution risk in cost-sensitive markets.
Biologics administration commands premium device economics; chronic disease management offers the steepest expansion trajectory across patient demographics.
End User:
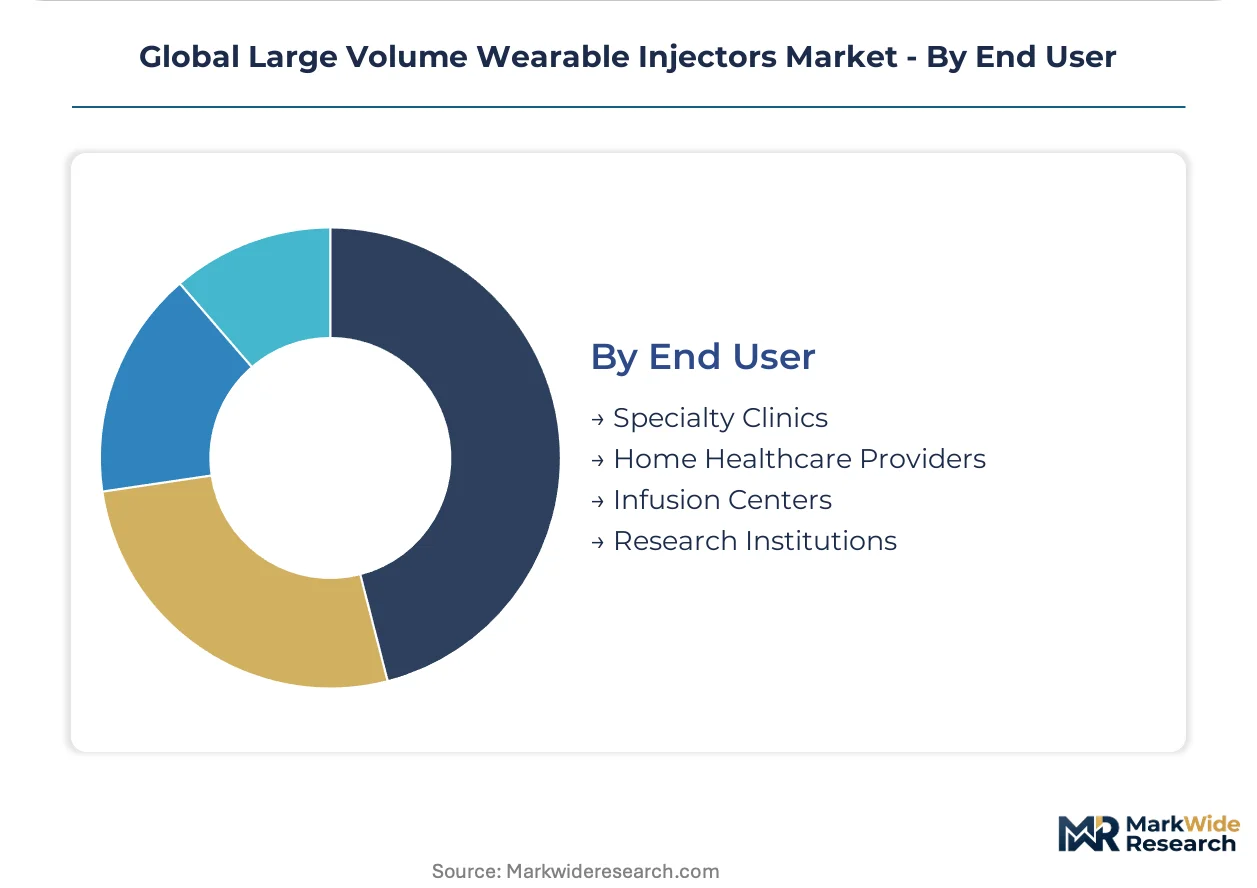
Channel configuration determines fulfillment complexity, with home healthcare providers demanding the most streamlined patient training protocols.
- Home Healthcare Providers:Patient-direct fulfillment networks requiring disposable cassette architectures that minimize training burden and support remote troubleshooting. United States specialty pharmacy consolidation is reshaping vendor relationships.
- Infusion Centers:Outpatient clinic settings transitioning from intravenous to subcutaneous administration, driving demand for on-body systems that eliminate chair time in German and Swiss facilities.
- Specialty Clinics:Physician-administered settings with staff supervision, accepting higher-complexity electromechanical platforms.
- Research Institutions:Clinical trial supply for pharmacokinetic studies and comparative effectiveness research, requiring customizable dosing profiles and data capture capabilities.
Home healthcare providers are consolidating procurement power; infusion centers are shifting fastest from legacy intravenous infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's procurement coalitions drive standardization for spring-driven patch injectors while the United States builds specialty pharmacy infrastructure for connected on-body systems at substantially higher reimbursement levels.
United States
Specialty pharmacy networks consolidate procurement power for immunology and rare disease biologics requiring volumes above 5 mL. FDA's 21 CFR 3.2 combination product pathway shapes development timelines for sponsor-device partnerships. The Greater Boston corridor concentrates contract research organizations supporting human factors validation for wearable drug delivery.
Germany
Hospital purchasing consortiums standardize on disposable cassette architectures for trastuzumab and rituximab biosimilars. EMA's MDR implementation accelerates notified body specialization in wearable drug delivery, with BSI and TÜV SÜD capturing certification queue priority. The Solothurn-Basel corridor anchors European manufacturing scale for electromechanical and spring-driven platforms.
Japan
Aging demographics and expanding biologics pipelines concentrate demand for belt-worn injectors accommodating chemotherapy volumes above 10 mL in outpatient settings. PMDA's alignment with IMDRF guidelines streamlines combination product reviews for devices paired with domestically manufactured monoclonal antibodies. The Kansai region hosts precision polymer suppliers for high-performance thermoplastic housings.
Switzerland
Contract manufacturers recalibrate ISO 7-8 cleanroom capacity from syringe assembly to large-format on-body device production. Swissmedic's notified body relationships create certification advantages for manufacturers with pre-established technical documentation. The Jura Arc clusters precision mechanics expertise serving both pharmaceutical and medical device industries.
India
Domestic biologics manufacturing expansion creates demand for cost-sensitive portable injectors in hormone therapy and chronic disease management. CDSCO's accelerated approval pathways for combination products paired with locally produced drugs open outpatient market access. The Mumbai-Pune corridor concentrates pharmaceutical formulation expertise increasingly integrated with device sourcing.
Global Large Volume Wearable Injectors Market Competitive Landscape
North American producers anchor the premium connectivity tier; Swiss and German specialists hold standardized mechanical platforms. The vendor base splits between diversified medical technology conglomerates with combination product experience and focused device developers with dedicated manufacturing scale. Three archetypes dominate: backward-integrated suppliers controlling needle-free transfer systems, pure-play wearable injector specialists with captive cleanroom capacity, and pharmaceutical sponsors vertically integrating device development. Competitive moves concentrate on notified body relationship building and specialty pharmacy channel access rather than price-based rivalry.
Among diversified medical technology conglomerates, BD exemplifies backward integration into fluid transfer components; Ypsomed represents dedicated manufacturing scale in Swiss precision mechanics; Enable Injections occupies the disposable cassette architecture specialization. These three anchors illustrate how geographic concentration of polymer supply and notified body access create defensive positioning against commoditization pressures from Asian contract manufacturers.
| Leading Market Players |
|---|
| BD |
| Ypsomed |
| Medtronic |
| Insulet Corporation |
| West Pharmaceutical Services |
| Amgen |
| Enable Injections |
| Sensile Medical |
| CeQur |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between FDA-cleared combination products and CE-marked mechanical platforms manifests in both acquisition premiums and supply chain configurations, with notified body queue position becoming a tradable asset that concentrates margin capture among early movers in Switzerland and Germany.
Pricing Analysis
Capacity additions in Swiss and German cleanroom facilities are reshaping price floors for spring-driven patch injectors while electromechanical platforms retain premium positioning through connectivity bundling. Three-tier pricing structure across premium connectivity, standard electromechanical, and economy spring-driven levels separates reimbursement-eligible on-body systems from procurement-coalition disposable cassettes. Cost compression in European oncology procurement is intensifying because German hospital purchasing consortiums have standardized on single-use architectures. European procurement coalitions exhibit highest price sensitivity; United States specialty pharmacy networks show lowest sensitivity due to separate reimbursement codes.
Supply Chain Analysis
Regional distribution centers in Basel, Solothurn, and the Greater Boston corridor maintain hub-and-spoke patterns for finished device fulfillment, with raw material flows concentrating among Japanese cyclic olefin polymer suppliers and German high-performance thermoplastic producers. Component dependencies rest on precision-machined spring mechanisms, pressure sensor arrays, and adhesive patch substrates. Single-source vulnerability in Japanese polymer feedstock exposes device makers to input cost volatility. Distribution runs through pharmaceutical sponsor bundling agreements and direct specialty pharmacy contracts, bypassing traditional durable medical equipment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Large Volume Wearable Injectors Market functions as a stable compounder anchored by irreversible healthcare decentralization, with outpatient biologics administration creating durable demand tailwinds across demographic and therapeutic segments.
For Market Incumbents: To counter Asian contract manufacturer cost advantages, BD and Ypsomed should deepen backward integration into needle-free transfer systems and expand captive cleanroom capacity in the Solothurn-Basel corridor. Priority investment in pre-established BSI and TÜV SÜD notified body relationships defends certification queue position against late entrants.
For New Entrants and Emerging Players: Enter via CDSCO's accelerated approval pathway for combination products paired with domestically manufactured biologics, targeting India's price-sensitive hormone therapy and chronic disease management segments. White-space concentration in belt-worn injectors for Japanese chemotherapy outpatient protocols and wireless-controlled platforms for French digital health reimbursement frameworks offers penetrable entry points.
For Investors and Strategic Acquirers: Consolidation pressure builds where patent thickets covering cassette-to-pump mechanical interfaces fragment freedom-to-operate assessments for new entrants. Long-term viability favors pure-play wearable injector specialists with dedicated ISO 7-8 manufacturing scale and pre-established pharmaceutical sponsor relationships. Monitor FDA draft guidance finalization on human factors testing as inflection indicator for regulatory investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Relationship Investment | BSI and TÜV SÜD queue priority accelerates EMA MDR certification timelines for Class III devices. |
| Specialty Pharmacy Channel Partnership | Direct fulfillment agreements with United States networks bypass traditional distributor margin layers. |
| Backward Integration into Fluid Transfer | Needle-free transfer system control secures supply chain position against Asian component suppliers. |
| Cleanroom Capacity Reconfiguration | ISO 7-8 facility retooling from syringe assembly accommodates large-format on-body device form factors. |
| Connectivity Platform Development | EU AI Act-compliant algorithmic dose monitoring commands premium positioning in German reimbursement. |
Research Methodology
Multiple input streams — primary interviews with regulatory affairs leads, biomedical engineers, and hospital procurement managers; secondary validation through FDA 510(k) filings, EMA MDR submission databases, and hospital GPO contract records; and bottom-up manufacturing capacity assessments — were reconciled against top-down pharmaceutical pipeline analysis across the projection horizon.
Historical volume trajectories were cross-referenced against expert panel inputs on reimbursement code expansion and procurement coalition standardization. Segmentation dimensions modeled include device architecture, technology modality, therapeutic application, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to disclosed manufacturing capacity additions and sponsor-device partnership announcements.
Inputs from notified body submission databases and pharmaceutical sponsor pipeline disclosures were available through the study window; gaps in real-world evidence from connected device deployments introduce uncertainty bands around connectivity-enabled platform adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Sweden Minimally Invasive Surgery Devices Market
Medical Devices
Medical Device Complaint Management Market
Medical Devices
Electroencephalography Systems/Devices Market
Medical Devices
Allergic Rhinitis Treatment Device Market
Medical Devices
Spinal Fusion Bone Graft Substitutes Market
Medical Devices
Electronic Smart Mask Market
Medical Devices
Asia Pacific Hearing Aids Market
Medical Devices
Medication Management System Market
Medical Devices
India Hemostats Market
Medical Devices
Global Gastrointestinal Devices Market
Medical Devices
Interventional Cardiology Devices Market
Medical Devices
Direct-Skin Wearable Medical Devices Market
Medical Devices
Intervertebral Implants Market
Medical Devices
Interatrial Shunt Market
Medical Devices
Cellular Encapsulation Market
Medical Devices
Global Catheter Stabilization Devices Market