
 Global Smart Biopsy Devices Market | 2026-2036
Global Smart Biopsy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Biopsy Devices Market Foresight
Hospital procurement departments are bifurcating from traditional imaging centers as the dominant buyer archetype for smart biopsy platforms. Becton, Dickinson and Company leverages its integrated needle and guidance portfolio to anchor North American supply contracts. Intuitive Surgical competes through robotic assistance capabilities that extend its installed base into interventional oncology workflows. Boston Scientific Corporation specializes in electromagnetic navigation systems that occupy the minimally invasive biopsy segment.
Smart biopsy devices integrate sensor-enabled instruments with real-time imaging guidance to extract tissue samples with spatial precision measured in sub-millimeter accuracy, primarily serving histopathological diagnosis and molecular profiling for treatment selection. Imaging-Guided Biopsy Systems lead product type demand as clinicians require concurrent visualization during extraction procedures. Robotic Assistance technology sustains premium positioning through reduced operator variability and improved sample adequacy rates. Oncology Diagnostics anchors application demand, while Ambulatory Surgical Centers represent the fastest-growing end user channel as same-day biopsy protocols expand.
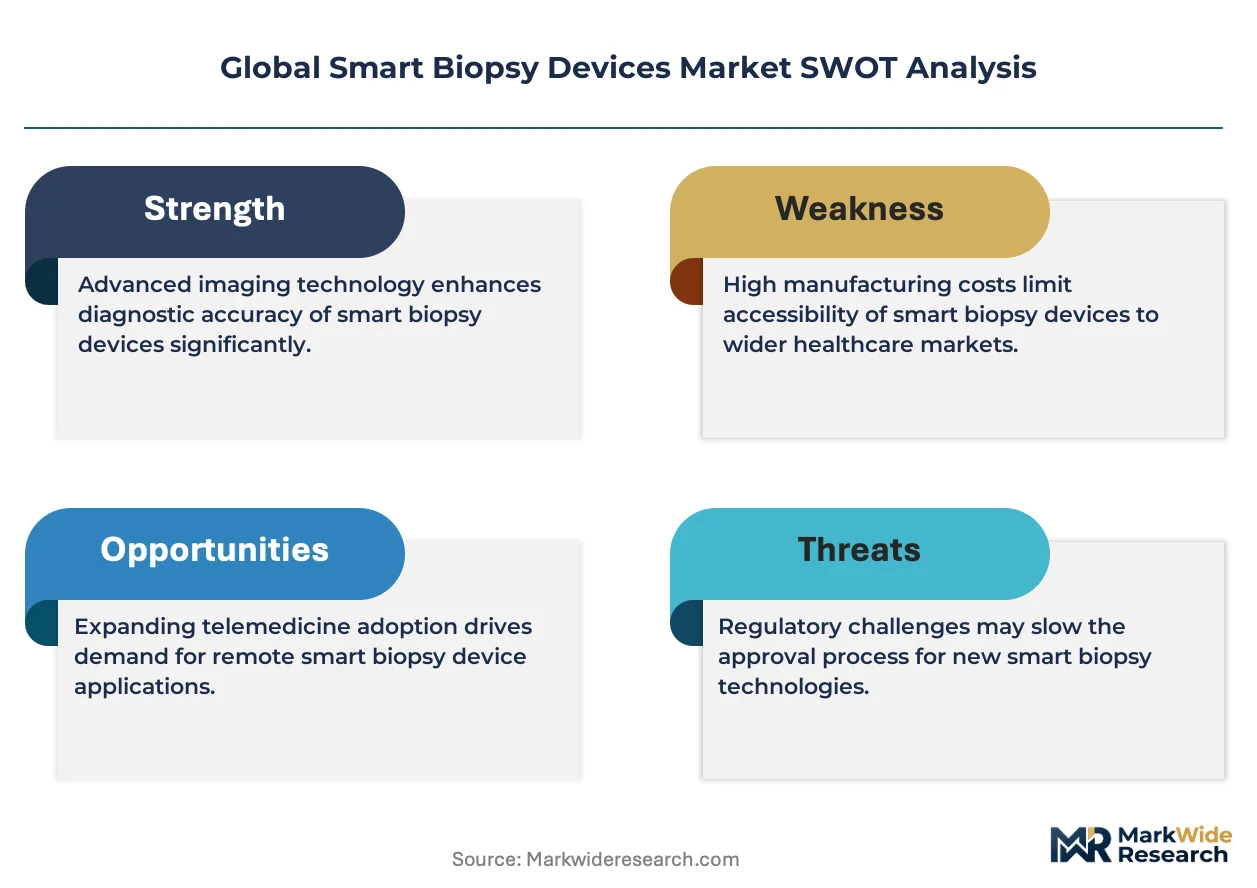
FDA premarket notification requirements shape device commercialization timelines for US manufacturers, while EMA medical device regulation and CE marking obligations govern European market access. Japan's PMDA enforces stringent clinical evidence standards for software-as-medical-device components in biopsy guidance systems. Stakeholders must monitor evolving reimbursement codes for computer-assisted navigation to anticipate which technology investments will yield sustainable procedure economics.
Market Dynamics
Hospital procurement departments are consolidating purchasing authority over smart biopsy platforms, displacing traditional distributor intermediaries and compressing vendor negotiation cycles through direct tender processes.
Growth Catalysts
- FDA 510(k) pathway streamlining:The FDA's abbreviated premarket notification process for AI-integrated imaging guidance is accelerating commercialization timelines for biopsy navigation software, reducing regulatory friction for new market entrants.
- Robotic assistance adoption:Ambulatory surgical centers are integrating robotic-assisted biopsy systems to execute same-day tissue extraction protocols, expanding addressable procedure volumes beyond hospital settings.
- Germany precision oncology expansion:German university hospitals are scaling molecular profiling programs that mandate sub-millimeter tissue sampling accuracy, creating concentrated demand for sensor-enabled biopsy instruments.
Market Restraints
- Capital intensity barrier:Robotic biopsy platforms require seven-figure capital commitments that constrain adoption among independent imaging centers and smaller hospital networks.
- PMDA software validation:Japan's PMDA enforces extensive clinical evidence requirements for software-as-medical-device components, extending time-to-revenue for biopsy guidance algorithms.
- Single-source sensor dependency:Sub-millimeter position sensors for biopsy needles concentrate supply among specialized German and Japanese component manufacturers, creating input vulnerability.
Strategic Opportunities
- India diagnostic infrastructure:India's tier-2 and tier-3 cities present underpenetrated demand for portable imaging-guided biopsy systems as the country's CDSCO streamlines medical device registration.
- AI-CT fusion navigation:Convergence of real-time CT imaging with machine learning trajectory planning is opening procedure categories previously excluded from percutaneous biopsy approaches.
- Reimbursement code expansion:CMS and private payors are establishing discrete reimbursement categories for computer-assisted navigation, improving procedure economics for technology-enhanced biopsies.
Industry Challenges
- Interventional radiologist scarcity:The specialized training pipeline for physicians capable of operating robotic biopsy platforms is constraining deployment velocity across health systems.
- EMR integration complexity:Biopsy guidance systems must achieve seamless data exchange with legacy electronic medical record architectures, extending implementation timelines and IT resource requirements.
- CE marking MDR transition:European manufacturers face recertification burdens under the EU Medical Device Regulation's heightened clinical evidence standards for active implantable accessories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Biopsy Devices Market |
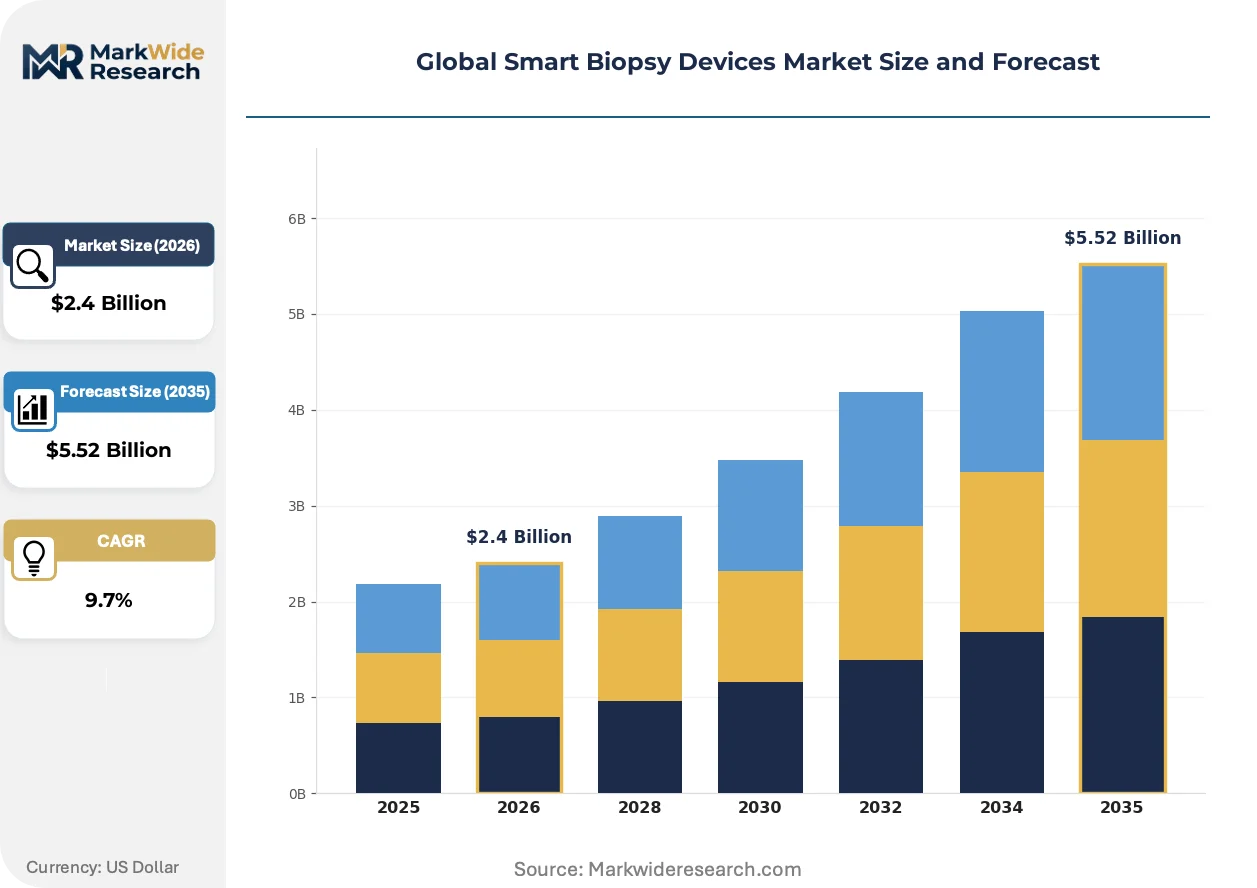
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needle Biopsy Devices, Endoscopic Biopsy Instruments, Surgical Biopsy Tools, Imaging-Guided Biopsy Systems Technology: Optical Coherence Tomography, Ultrasound Guidance, Electromagnetic Navigation, Robotic Assistance, Magnetic Resonance Imaging Application: Oncology Diagnostics, Neurological Assessment, Pulmonary Evaluation, Gastroenterology Testing, Urological Screening End User: Diagnostic Laboratories, Research Institutions, Specialized Clinics, Imaging Centers, Ambulatory Surgical Centers |
| Companies Covered | Becton, Dickinson and Company, Boston Scientific Corporation, Danaher Corporation, Medtronic, Intuitive Surgical, C. R. Bard, B. Braun Melsungen AG, Cook Medical, Canon Medical Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Biopsy Devices Market Shifts & Advancements
Electromagnetic navigation is displacing mechanical stereotactic frames as the dominant localization modality, while regulatory frameworks accelerate software validation pathways and procurement centralization reshapes vendor relationships.
Real-time electromagnetic tracking is displacing fixed-frame stereotactic guidance in brain and lung biopsy procedures. Academic medical centers in the United States and Germany are adopting these systems at replacement-cycle pace. The technology is displacing capital-intensive fixed infrastructure with portable platforms that enable intraoperative adaptability.
EMA's Medical Device Regulation and the EU AI Act are imposing concurrent compliance obligations on biopsy guidance software. Manufacturers must demonstrate clinical validity for algorithmic components alongside traditional device safety. European oncology centers are prioritizing vendors with established notified body relationships to mitigate approval uncertainty.
Hospital procurement departments are consolidating vendor contracts into multi-year enterprise agreements with performance guarantees. Independent imaging centers and ambulatory surgical facilities are losing negotiating leverage as health system purchasing coalitions aggregate demand. This concentration is most visible in the United States, where IDN procurement offices now control biopsy device selection for affiliated outpatient sites.
Global Smart Biopsy Devices Market Segmentation
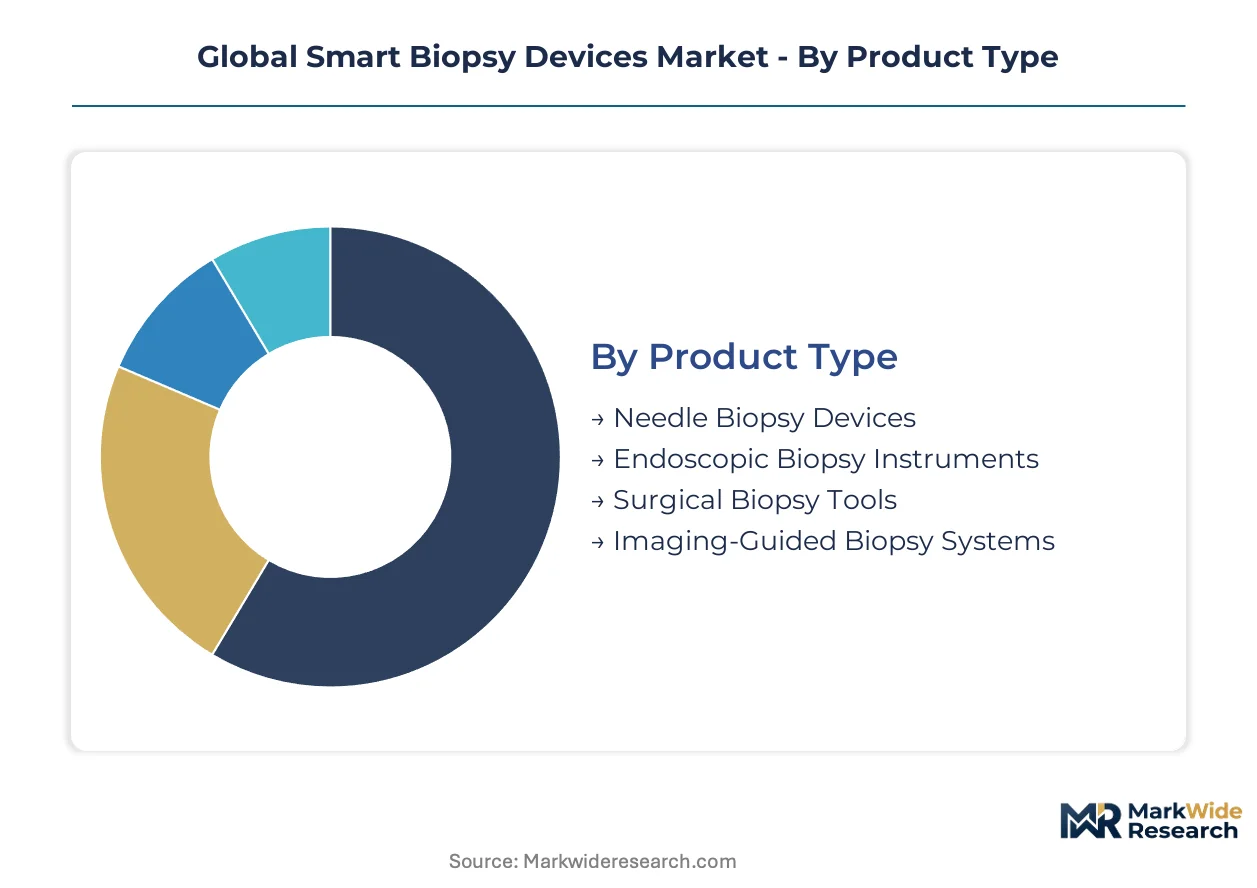
Segmentation in smart biopsy devices reveals distinct technology-product couplings that determine procurement priorities across health systems. Each category exposes different vulnerability to substitution, from imaging modalities displaced by AI fusion to end-user channels consolidating under hospital authority.
Product Type:
Substitution pressure concentrates in surgical biopsy tools as minimally invasive alternatives achieve diagnostic parity with lower morbidity.
- Needle Biopsy Devices:Spring-loaded and vacuum-assisted instruments extract core tissue samples through percutaneous access. Demand clusters in United States ambulatory surgical centers executing same-day lung and breast protocols, constrained by single-use consumable economics.
- Imaging-Guided Biopsy Systems:Integrated platforms combine real-time visualization with instrument positioning for spatial accuracy below one millimeter. German university hospitals drive procurement for these systems to support molecular profiling mandates in precision oncology programs.
- Endoscopic Biopsy Instruments:Flexible forceps and brushes retrieve tissue through natural orifices during endoluminal procedures.
- Surgical Biopsy Tools:Open and laparoscopic excisional instruments for tissue removal when percutaneous methods prove inadequate.
Imaging-Guided Biopsy Systems retain volume leadership; Needle Biopsy Devices hold the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive robotic platforms from portable guidance modalities accessible to mid-tier facilities.
- Robotic Assistance:Motorized instrument positioning with haptic feedback reduces operator variability in complex trajectories. United States integrated delivery networks concentrate purchasing for these seven-figure systems to standardize outcomes across affiliated sites.
- Electromagnetic Navigation:Real-time sensor tracking enables frameless localization for brain and lung procedures. Academic medical centers in Germany and the United States adopt these platforms at replacement-cycle pace, displacing fixed stereotactic frames.
- Ultrasound Guidance:Real-time sonographic visualization for superficial and abdominal target access.
- Magnetic Resonance Imaging:MR-compatible instruments for soft-tissue targets requiring superior contrast resolution.
- Optical Coherence Tomography:Near-infrared interferometry for microscopic-resolution surface tissue assessment.
Electromagnetic Navigation commands the premium tier; Robotic Assistance is climbing the fastest.
Application:
Application demand correlates directly with procedure reimbursement density and screening program maturity across national health systems.
- Oncology Diagnostics:Tissue acquisition for histopathological diagnosis and biomarker analysis to guide systemic therapy selection. Japan's expanded cancer screening programs and Germany's molecular profiling initiatives concentrate demand for high-adequacy sampling.
- Pulmonary Evaluation:Bronchoscopic and percutaneous biopsy for lung nodule characterization. United States lung cancer screening expansion drives volume for navigational bronchoscopy platforms in academic medical centers.
- Neurological Assessment:Brain tissue sampling for neurodegenerative and neoplastic conditions.
- Gastroenterology Testing:Mucosal biopsy for inflammatory bowel disease and neoplasia detection.
- Urological Screening:Prostate and bladder tissue acquisition for malignancy diagnosis.
Oncology Diagnostics anchors absolute volume; Pulmonary Evaluation shows the steepest upward trajectory.
End User:
Customer type concentration reflects procurement authority migration from independent operators to consolidated health system purchasing offices.
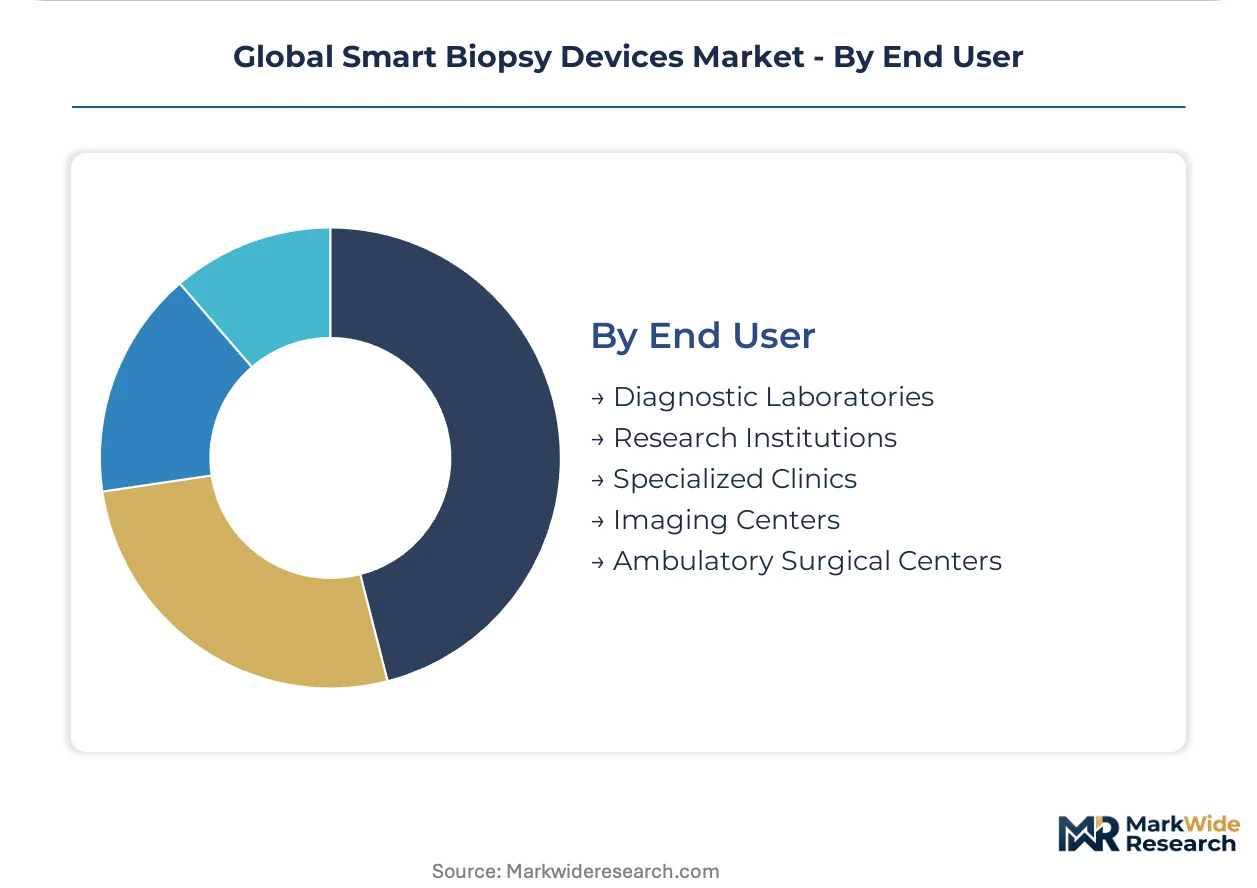
- Ambulatory Surgical Centers:Same-day facilities integrating robotic and imaging-guided platforms to execute outpatient biopsy protocols. United States site-of-service shift toward lower-acuity settings accelerates capital deployment for these channels.
- Imaging Centers:Dedicated radiology facilities performing image-guided percutaneous procedures. Independent operators in this channel face contracting leverage as hospital procurement coalitions aggregate demand.
- Diagnostic Laboratories:Pathology-focused facilities receiving and processing externally acquired specimens.
- Specialized Clinics:Disease-focused outpatient settings including urology and gastroenterology practices.
- Research Institutions:Academic centers conducting translational studies with experimental biopsy technologies.
Imaging Centers retain installed base dominance; Ambulatory Surgical Centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision sensor components to United States and Japanese manufacturers of robotic biopsy platforms, establishing a critical trade corridor in the smart biopsy device supply chain.
United States
Integrated delivery networks in Texas and California drive procurement of seven-figure robotic biopsy systems for standardized outcomes across affiliated sites. FDA 510(k) pathway streamlining accelerates commercialization timelines for AI-integrated imaging guidance software. The Mayo Clinic Rochester and MD Anderson Cancer Center anchor demand concentration for electromagnetic navigation platforms in precision oncology workflows.
Germany
University hospitals in Munich and Heidelberg scale molecular profiling programs mandating sub-millimeter tissue sampling accuracy. EMA Medical Device Regulation and CE marking obligations govern market access for biopsy guidance systems. The Baden-Württemberg medical technology cluster around Stuttgart concentrates sensor-enabled instrument manufacturing for export markets.
Japan
Expanded cancer screening programs in Tokyo and Osaka metropolitan areas concentrate demand for high-adequacy sampling instruments. PMDA enforces stringent clinical evidence standards for software-as-medical-device components in biopsy guidance systems. The Kansai region's precision manufacturing base supplies sub-millimeter position sensors to global device assemblers.
India
Tier-2 and tier-3 cities present underpenetrated demand for portable imaging-guided biopsy systems as diagnostic infrastructure expands. CDSCO streamlines medical device registration pathways for foreign manufacturers. The Maharashtra medical device manufacturing zone near Mumbai attracts assembly operations serving South Asian markets.
United Kingdom
NHS England's precision medicine initiatives drive adoption of computer-assisted navigation systems in London and Manchester academic centers. MHRA post-Brexit regulatory frameworks align with EU MDR standards for biopsy device market access. The Cambridge life sciences cluster develops AI-CT fusion navigation algorithms for next-generation platforms.
Global Smart Biopsy Devices Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with integrated imaging and instrument portfolios. Market structure concentrates around three to five global enterprises controlling robotic platform and navigation system supply. Strategic archetypes include full-stack integrators combining hardware and software, component specialists supplying position sensors and guidance algorithms, and regional distributors with localized service networks. Dominant competitive moves encompass enterprise-wide procurement contract consolidation and cross-border technology licensing for electromagnetic navigation patents.
Among United States-based technology integrators, Becton, Dickinson and Company and Boston Scientific Corporation exemplify the full-stack archetype through combined needle and guidance portfolios. Intuitive Surgical occupies a distinct position representing robotic assistance specialization. These three enterprises anchor competitive dynamics as hospital procurement departments consolidate multi-year agreements with performance guarantees.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Boston Scientific Corporation |
| Danaher Corporation |
| Medtronic |
| Intuitive Surgical |
| C. R. Bard |
| B. Braun Melsungen AG |
| Cook Medical |
| Canon Medical Systems Corporation |
| Others |
Supply & Pricing Matrix
Multi-year enterprise procurement contracts with performance guarantees lock in supply access for robotic biopsy platforms while compressing price visibility for independent imaging centers and ambulatory surgical facilities. Hospital purchasing coalitions in the United States and Germany leverage aggregated demand to extract favorable terms from electromagnetic navigation and robotic assistance vendors.
Pricing Analysis
Current-generation robotic biopsy platforms command seven-figure capital commitments against prior-generation fixed-frame stereotactic systems trading at depreciated secondary-market values. Pricing stratifies across premium, standard, and economy tiers based on navigation accuracy certification and bundled service agreements. Cost compression in the standard tier is intensifying because Japanese and German sensor manufacturers face input volatility. Independent imaging centers exhibit highest price sensitivity; academic medical centers anchored to precision oncology programs demonstrate lowest sensitivity.
Supply Chain Analysis
Sub-millimeter position sensor manufacturing concentrates in Baden-Württemberg and the Kansai region, creating single-source vulnerability for biopsy needle guidance components. Device assemblers draw from German precision optics, Japanese mechatronics, and United States software development inputs. Tariff exposure runs through cross-border component shipments between these manufacturing clusters. Distribution runs through health system procurement offices that have displaced traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart biopsy devices market is recovering from capital expenditure compression as hospital procurement departments restart precision oncology infrastructure investments. Replacement-cycle demand for electromagnetic navigation platforms signals the cyclical upswing.
For Market Incumbents: Secure multi-year enterprise agreements with integrated delivery networks before procurement consolidation peaks. Deepen backward integration into sensor manufacturing to mitigate single-source dependency on German and Japanese component suppliers. Anchor North American supply contracts through FDA-cleared AI-integrated imaging guidance portfolios.
For New Entrants and Emerging Players: Lead with portable imaging-guided biopsy systems targeting India's tier-2 and tier-3 diagnostic infrastructure expansion. Penetrate the ambulatory surgical center channel fastest by aligning with same-day biopsy protocol adoption. Pursue CDSCO registration pathways to establish South Asian market presence ahead of multinational competitors.
For Investors and Strategic Acquirers: Component specialists with captive sensor manufacturing capabilities present acquisition targets with defensible margin structures. Long-term viability hinges on software-as-medical-device revenue streams recurring across hardware replacement cycles. Monitor CMS reimbursement code expansion for computer-assisted navigation as the inflection indicator for procedure economics improvement.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Navigation | Abbreviated premarket notification accelerates commercialization timelines for AI-integrated biopsy guidance software. |
| CE Marking Under MDR | European manufacturers must recertify active implantable accessories under heightened clinical evidence standards. |
| Hospital System Partnership | Enterprise agreements with IDN procurement offices aggregate demand and displace distributor intermediaries. |
| Software Companion Development | Algorithmic trajectory planning components attract PMDA scrutiny for software-as-medical-device validation. |
| Reimbursement Strategy | CMS and private payor code expansion for computer-assisted navigation improves procedure economics. |
Research Methodology
A standing panel of interventional radiologists, hospital procurement managers, biomedical engineers, and GPO contracts managers provided ongoing calibration against primary field observations. Secondary validation drew from FDA 510(k) filings, EMA medical device registration databases, CMS Medicare reimbursement schedules, and hospital procurement contract disclosures. Bottom-up modeling of installed base replacement cycles triangulated with top-down spending forecasts from health system capital expenditure surveys.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation across product type, technology generation, application area, and end-user channel. CAGRs were derived from procedure volume trajectories and capital equipment replacement elasticity. Forecast inputs incorporated PMDA software validation timelines and EMA MDR transition compliance burdens.
Underlying assumptions cover sustained precision oncology program expansion and stable sensor component trade flows, with deviation risk concentrated in interventional radiologist training pipeline constraints and reimbursement code adoption velocity. Practitioners should keep alternative scenarios live as regulatory validation requirements and procurement consolidation patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intrapartum Monitors Market
Medical Devices
Laser Resurfacing Market
Medical Devices
Mexico Electrocardiograph (ECG) Market
Medical Devices
Global Orthopedic Surgical Robots Market
Medical Devices
Global Angiography Catheters Market
Medical Devices
Tourniquet Systems Market
Medical Devices
Toe Fixation System Market
Medical Devices
Disposable Thermometer Market
Medical Devices
Wearable Medical Technology Market
Medical Devices
Lung Preservation Systems Market
Medical Devices
Global Surgical Robotics Market
Medical Devices
Ultrasound Transducers Market
Medical Devices
Global Scleral Lens Market
Medical Devices
India Spinal Fusion Devices Market
Medical Devices
Digital Intraoral Sensors and Consumables Market
Medical Devices
Digital Slit Lamp Market