
 Peripheral Micro Catheters Market | 2026-2036
Peripheral Micro Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Peripheral Micro Catheters Market Analytics
Ireland is narrowing the manufacturing gap for micro catheter components serving European and North American OEMs. Boston Scientific Corporation leverages vertically integrated polymer extrusion capabilities in Galway to sustain cost competitiveness on PTCA catheter platforms. Terumo Corporation anchors its position through proprietary hydrophilic coating technologies applied to neurovascular micro catheter lines. Merit Medical Systems differentiates via direct hospital contracting models that control distribution across interventional radiology suites in the western United States.
Peripheral micro catheters are sub-millimeter diameter, flexible tubular devices typically constructed from braided nylon or Pebax polymer composites with distal radiopaque marker bands, designed to navigate tortuous vasculature for targeted delivery of contrast media, guidewires, or embolic agents during minimally invasive procedures. PTCA catheters and guide catheters command the largest share of current revenue as mature workhorse categories with established reimbursement, while coated polymer platforms represent the fastest-expanding material segment driven by lubricity demands in chronic total occlusion cases. Diagnostic catheters face margin compression as commoditization spreads across entry-level hospital procurement, whereas composite metal-polymer hybrids capture premium positioning in neurovascular and peripheral vascular applications requiring torque response.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and sterilization validation burdens for manufacturers seeking dual-market access. ISO 10993 biocompatibility testing and REACH substance restrictions on phthalate plasticizers further constrain material selection and supply chain qualification processes. Stakeholders must monitor evolving CMS reimbursement decisions for peripheral arterial disease interventions and EU notified body capacity constraints that could delay market entry for novel micro catheter designs.
Market Dynamics
EU MDR conformity requirements and FDA 510(k) sterility benchmarks are compressing product development timelines while concentrating qualified supplier networks around polymer extrusion and coating capabilities. Manufacturers face simultaneous pressure to accelerate innovation and validate biocompatibility across dual-market access pathways.
Growth Catalysts
- Aging demographics in Japan and Germany:Expanding patient pools for peripheral arterial disease interventions are sustaining procedural volume growth in reimbursed hospital settings.
- Hydrophilic coating technologies:Advanced polymer surface treatments are enabling navigation through chronic total occlusion cases previously deemed untreatable.
- REACH substance restrictions:Phasing out phthalate plasticizers is accelerating adoption of Pebax and bio-based polymer alternatives with superior lubricity profiles.
Market Restraints
- Specialized polymer feedstock concentration:Pebax resin supply chains cluster with Arkema and select European compounders, exposing manufacturers to input volatility.
- EU notified body capacity constraints:Technical documentation review backlogs under MDR Article 52 are extending market entry timelines by 12-18 months for novel designs.
- Commoditization pressure in diagnostic catheters:Entry-level hospital procurement tenders are compressing margins on standard contrast delivery platforms.
Strategic Opportunities
- Composite metal-polymer hybrids:Braided nitinol-reinforced platforms for neurovascular torque response command premium positioning in underserved stroke intervention segments.
- Direct hospital contracting models:Bypassing distributor markups through captive sales forces captures margin in high-volume interventional radiology suites.
- ISO 10993-18 chemical characterization:Accelerated biocompatibility testing protocols offer first-mover advantage for manufacturers with pre-validated material libraries.
Industry Challenges
- Polymer extrusion technician scarcity:Precision micro-extrusion operations require specialized skill sets concentrated in Ireland and Massachusetts medical device clusters.
- Sterilization validation complexity:EO residual limits and alternative modality qualification under ISO 11135 demand capital-intensive facility upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peripheral Micro Catheters Market |
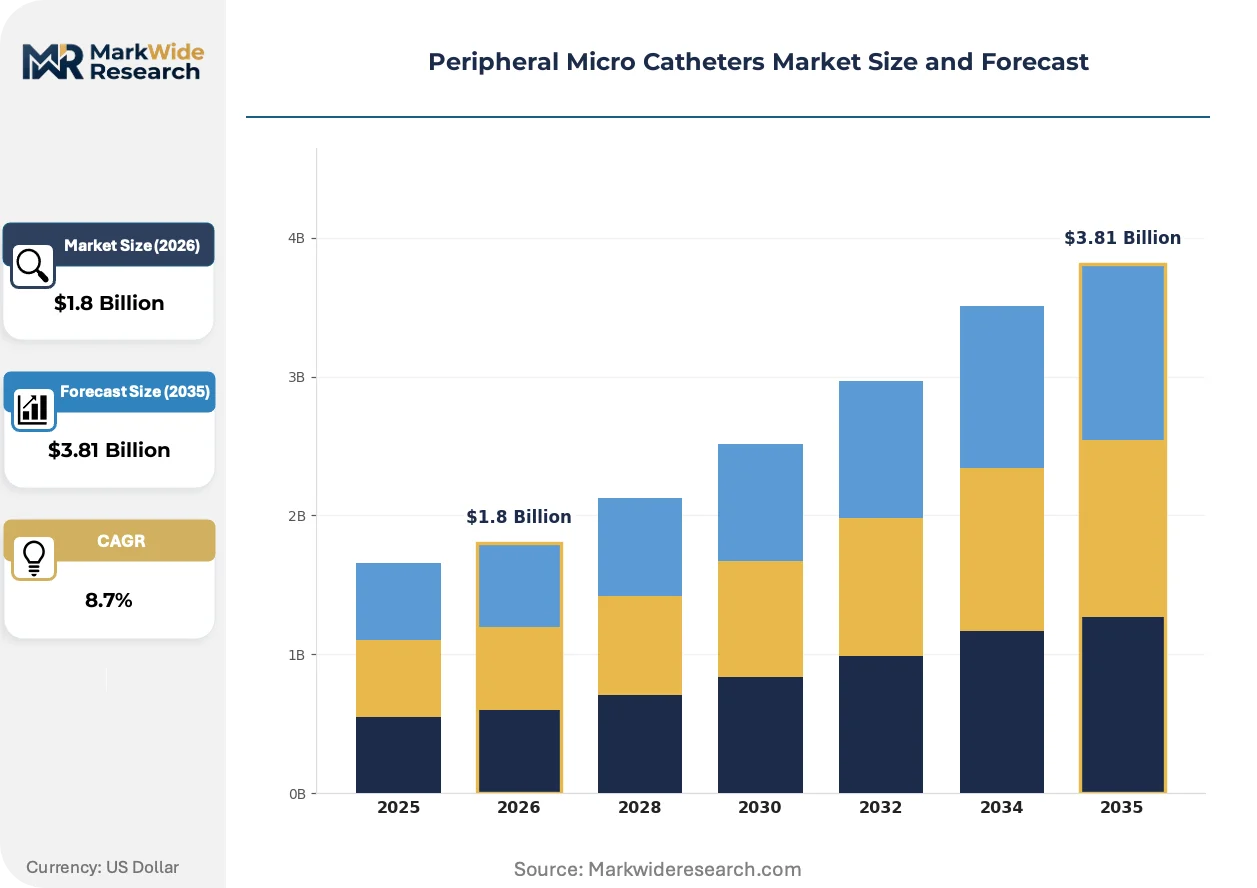
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTCA Catheters, Diagnostic Catheters, Guide Catheters, Sheath Introducers End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Material: Polymer, Metal, Composite, Coated Application: Cardiology, Oncology, Neurology, Peripheral Vascular |
| Companies Covered | Boston Scientific Corporation, Medtronic, Terumo Corporation, Merit Medical Systems, Cook Medical, Teleflex Incorporated, Stryker, Penumbra, ASAHI INTECC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peripheral Micro Catheters Market Evolving Landscape
Digital integration across catheter design workflows and manufacturing execution systems is compressing iteration cycles while tightening process control. Real-time torque sensing and navigation feedback are migrating from capital equipment into disposable catheter platforms.
Embedded fiber-optic force sensors within catheter shafts are digitizing tactile feedback during lesion crossing procedures. Interventional cardiologists in high-volume US catheterization labs are piloting these platforms to reduce vessel perforation rates. The technology is digitizing training curves and enabling remote proctoring across distributed hospital networks.
EU MDR Annex I general safety and performance requirements are mandating enhanced clinical evidence for legacy catheter designs seeking renewal. Manufacturers must retroactively compile post-market surveillance data and update risk management files. Peripheral vascular indications face particular scrutiny given the diversity of anatomical challenges and operator technique variables.
Hospital procurement committees are consolidating vendor lists around full-line suppliers capable of servicing multiple interventional specialties. Standalone micro catheter specialists without guide catheter or balloon platform breadth face exclusion from integrated supply agreements. This concentration is most pronounced in western United States health systems pursuing standardization across catheterization lab and interventional radiology service lines.
Peripheral Micro Catheters Market Segmentation
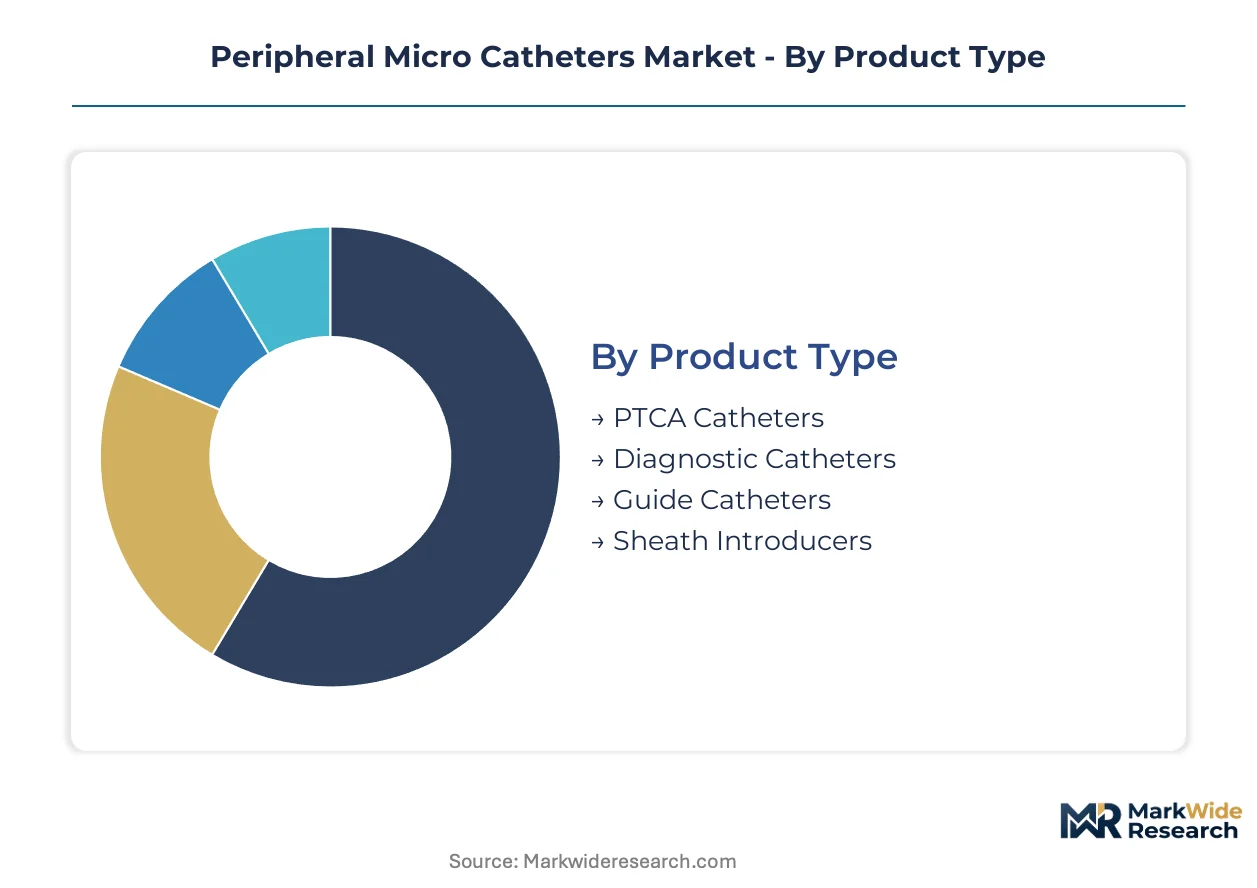
Micro catheter procurement patterns diverge sharply across clinical settings and material platforms. Hospital catheterization labs prioritize torque response and coating durability for complex interventions, while ambulatory centers emphasize single-use economics and sterility assurance. Understanding these segment-specific performance thresholds shapes both R&D allocation and distribution strategy.
Product Type:
After-sales service intensity varies dramatically across catheter categories, with PTCA and guide catheter platforms requiring field clinical support and inventory management partnerships that diagnostic lines rarely demand.
- PTCA Catheters:Balloon-expandable platforms constructed from Pebax or nylon multilayer shafts with radiopaque marker bands for precise lesion positioning. Demand concentrates in United States hospital catheterization labs where CMS reimbursement alignment for peripheral arterial disease interventions sustains procedural volume. Hydrophilic coating durability under repeated inflation cycles drives replacement rates and service contract attachment.
- Diagnostic Catheters:Contrast delivery platforms with braided nylon construction and distal side-hole configurations for angiographic visualization. Procurement committees in German hospital networks are consolidating vendor lists around full-line suppliers, compressing margins for standalone diagnostic specialists. Standardization across service lines reduces SKU complexity but limits premium positioning opportunities.
- Guide Catheters:Large-lumen platforms designed for guidewire and device delivery during interventional procedures.
- Sheath Introducers:Vascular access platforms with hemostatic valve mechanisms for catheter exchange.
By volume, diagnostic catheters lead due to procedural ubiquity. By growth pace, PTCA platforms are ahead on chronic total occlusion case expansion.
End User:
Cost tier stratification separates capital-intensive hospital installations from price-sensitive ambulatory settings, with specialty clinics occupying a hybrid procurement position.
- Hospitals:Comprehensive catheterization labs and interventional radiology suites with 24/7 procedural capability and dedicated biomedical engineering support. United States health systems in the western states are pursuing vendor consolidation across cardiology and peripheral vascular service lines. Integrated supply agreements favor full-line manufacturers with guide catheter, balloon, and micro catheter breadth.
- Ambulatory Surgical Centers:Focused procedure environments with compressed case turnaround and limited on-site sterilization infrastructure. Japanese ASC networks are expanding peripheral vascular case volumes under revised reimbursement categories. Single-use economics and disposable packaging efficiency dominate procurement criteria over technical performance differentiation.
- Specialty Clinics:Cardiology and vascular-focused outpatient facilities with selective interventional capability.
- Research Institutions:Academic medical centers and preclinical testing facilities evaluating novel catheter designs.
By volume, hospitals dominate catheter consumption. By growth pace, ambulatory surgical centers are climbing the fastest on case migration trends.
Material:
Application requirements dictate material selection, with neurology and peripheral vascular segments driving divergent performance specifications.
- Polymer:Pebax and nylon extrusions with braided reinforcement for flexibility and kink resistance. Demand concentrates in cardiology applications where trackability through tortuous coronary anatomy is paramount. REACH substance restrictions on phthalate plasticizers are accelerating compound reformulation timelines.
- Coated:Hydrophilic or hydrophobic surface treatments applied to polymer substrates for lubricity control. Neurology applications in Japan and Germany are expanding most quickly on chronic total occlusion navigation demands. Coating durability under mechanical stress determines clinical performance and regulatory biocompatibility validation burdens.
- Metal:Stainless steel or nitinol hypotube construction for proximal pushability and torque transmission.
- Composite:Braided metal-polymer hybrid platforms combining torque response with distal flexibility.
By volume, polymer platforms lead on cost efficiency. By growth pace, coated materials are gaining share fastest on lubricity requirements.
Application:
Customer type segmentation reveals divergent operator training curves and capital equipment dependencies across clinical specialties.
- Cardiology:Coronary and peripheral arterial interventions requiring sub-millimeter navigation and balloon compatibility. United States interventional cardiologists in high-volume catheterization labs are piloting force-sensing catheter platforms. Procedural volume concentration supports premium pricing for advanced coating technologies.
- Peripheral Vascular:Lower extremity and renal arterial interventions with extended catheter length requirements. German hospital networks are standardizing across peripheral and coronary platforms to reduce inventory complexity. Anatomical variability demands broader size ranges and specialized curve configurations.
- Neurology:Cerebrovascular and stroke intervention applications requiring distal flexibility and torque response.
- Oncology:Transarterial chemoembolization and radioembolization delivery platforms for targeted tumor therapy.
By volume, cardiology leads catheter deployment. By growth pace, peripheral vascular is expanding most quickly on aging demographic procedural demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer extrusion capabilities for micro catheter manufacturing concentrate in Ireland, Massachusetts, and select Japanese industrial corridors, with finished device assembly and sterilization operations distributed across hospital-proximate logistics hubs in the United States, Germany, and Japan.
United States
Interventional cardiologists in high-volume catheterization labs are expanding complex peripheral vascular procedures under CMS reimbursement alignment for arterial disease interventions. FDA 510(k) clearance pathways compress product development timelines while elevating sterility validation burdens for dual-market manufacturers. Boston Scientific Corporation anchors vertically integrated polymer extrusion operations in Galway, Ireland, to sustain cost competitiveness on PTCA catheter platforms serving North American hospital networks.
Germany
Hospital procurement committees are consolidating vendor lists around full-line suppliers capable of servicing cardiology and peripheral vascular service lines simultaneously. EU MDR technical documentation requirements under Annex I general safety and performance mandates are extending market entry timelines by 12-18 months for novel catheter designs seeking renewal. The Galway medical device cluster in Ireland supplies precision micro-extrusion components to German OEMs facing REACH substance restrictions on phthalate plasticizers.
Japan
Aging demographics are expanding patient pools for peripheral arterial disease interventions in reimbursed hospital settings, with ambulatory surgical centers climbing fastest on case migration trends. PMDA regulatory alignment with ISO 10993 biocompatibility testing protocols constrains material selection and supply chain qualification processes. Terumo Corporation anchors its market position through proprietary hydrophilic coating technologies applied to neurovascular micro catheter lines serving domestic and export demand.
Ireland
Precision micro-extrusion operations for Pebax and nylon catheter shafts concentrate in the Galway medical device cluster, narrowing the manufacturing gap for European and North American OEMs. EU MDR conformity requirements and FDA sterility benchmarks are compressing product development timelines while concentrating qualified supplier networks. Arkema resin supply chains for Pebax feedstock expose manufacturers to input volatility, driving backward integration strategies among device assemblers.
United Kingdom
Interventional radiology suites in NHS hospital networks are standardizing catheter procurement across peripheral vascular and oncology service lines, favoring full-line suppliers with guide catheter and embolic delivery platform breadth. MHRA post-Brexit regulatory divergence from EU MDR is creating parallel technical documentation requirements for manufacturers seeking UK market access. Research institutions in London and Oxford are evaluating novel force-sensing catheter designs with embedded fiber-optic sensors for digitized tactile feedback.
Peripheral Micro Catheters Market Competitive Landscape
Vertically integrated multinationals and specialized coating technology firms split the market between scale-driven cost efficiency and premium performance differentiation. Tier-one manufacturers with captive polymer extrusion capabilities command hospital contracting relationships through inventory management partnerships, while mid-tier specialists face margin compression in diagnostic catheter commoditization. Strategic archetypes include full-line platform suppliers, hydrophilic coating technology licensors, and direct-hospital contracting operators. Dominant competitive moves encompass backward integration into polymer feedstock and geographic expansion through sterilization facility qualification.
Within the full-line platform tier, Boston Scientific Corporation and Terumo Corporation exemplify divergent specialization strategies. Boston Scientific Corporation occupies a position anchored in vertically integrated polymer extrusion capabilities, while Terumo Corporation represents the hydrophilic coating technology archetype. Merit Medical Systems sits within the direct-contracting operator category, bypassing distributor markups through captive sales forces. Among Japanese manufacturers, ASAHI INTECC exemplifies the torque-response specialist archetype serving neurovascular applications.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Terumo Corporation |
| Merit Medical Systems |
| Cook Medical |
| Teleflex Incorporated |
| Stryker |
| Penumbra |
| ASAHI INTECC |
| Others |
Value Network & Pricing Analysis
Overcapacity in Irish polymer extrusion facilities is compressing supplier margins while concentrating pricing power among device assemblers with captive coating capabilities. This utilization dynamic rewards backward integration into Pebax resin sourcing and penalizes standalone component vendors lacking sterilization validation infrastructure.
Pricing Analysis
EU MDR and FDA 510(k) sterility benchmarks dictate the pricing tier structure across the Peripheral Micro Catheters Market. Three-tier pricing structure across premium, standard, and economy levels separates composite metal-polymer hybrids with embedded force sensors from braided nylon diagnostic platforms and commodity contrast delivery catheters. Price differentiation rests on ISO 10993 biocompatibility certification tier and hydrophilic coating durability under mechanical stress. Cost compression in diagnostic catheters is intensifying because German hospital procurement committees are consolidating vendor lists around full-line suppliers. Ambulatory surgical centers in Japan exhibit highest price sensitivity due to single-use economics, while United States hospital catheterization labs show lowest sensitivity on premium PTCA platforms.
Supply Chain Analysis
Extended payment terms from United States hospital networks are squeezing working capital across Irish and Massachusetts component suppliers. Geographic supply concentration centers on Ireland, Massachusetts, and Japan for precision micro-extrusion operations. Raw material dependencies draw from Arkema Pebax resin, nitinol hypotube, and radiopaque marker alloys. Single-source vulnerability in European Pebax compounders exposes manufacturers to input volatility. Distribution runs through hospital-proximate sterilization hubs in the United States, Germany, and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Peripheral Micro Catheters Market functions as a service-attach opportunity where field clinical support and inventory management partnerships expand faster than hardware unit economics. Coating durability guarantees and procedural training subscriptions represent the fastest-growing recurring-revenue layer.
For Market Incumbents: Harden polymer extrusion technician pipelines through apprenticeship partnerships with Galway and Massachusetts medical device clusters. Deepen backward integration into Pebax resin sourcing to offset Arkema supply volatility. Lock in hospital system partnerships through integrated supply agreements spanning guide catheter, balloon, and micro catheter platforms before EU MDR renewal deadlines compress vendor lists. For New Entrants and Emerging Players: Japanese ambulatory surgical centers present the most penetrable white-space target given revised reimbursement categories and limited incumbent field presence. Neurology applications with chronic total occlusion navigation demands offer premium positioning entry points. Pursue direct hospital contracting models bypassing distributor markups in western United States health systems. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hydrophilic coating technology licensors with validated material libraries and service contract attachment above hardware replacement cycles. Target acquisition archetypes include torque-response specialists serving neurovascular segments and sterilization facility operators with FDA and EU MDR dual qualification. Watch EU notified body capacity constraints as inflection indicator for market entry timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Renewal | Accelerates consolidation around full-line suppliers with post-market surveillance infrastructure. |
| Backward Integration into Pebax Resin | Reduces input volatility from Arkema and European compounder concentration. |
| Hospital System Partnership Expansion | Captures integrated supply agreements across cardiology and peripheral vascular service lines. |
| ISO 10993-18 Pre-validated Material Libraries | Compresses biocompatibility testing timelines for first-mover regulatory advantage. |
| Embedded Fiber-optic Force Sensor Development | Digitizes tactile feedback for remote proctoring and training curve reduction. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR technical documentation filings, and hospital procurement contract records preceded structured interviews with interventional cardiologists, biomedical engineers, GPO contracts managers, and polymer extrusion operations directors. Primary fieldwork with catheterization lab directors and sterilization facility operators combined with secondary validation against ISO 10993 biocompatibility testing protocols and REACH substance restriction updates. Bottom-up unit economics modeling triangulated against top-down procedural volume estimates from CMS and PMDA reimbursement datasets.
Assumptions held regulatory pathway timelines and reimbursement alignment constant across the analysis window while varying polymer feedstock cost trajectories and notified body capacity scenarios. Segmentation dimensions modeled include product type, end user, material platform, and application specialty. CAGRs derived from weighted average of historical procedural volume elasticity and projected demographic demand across United States, German, and Japanese patient populations. Forecast inputs incorporated hydrophilic coating adoption curves and chronic total occlusion case expansion rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by composite metal-polymer hybrid specialists or accelerated EU MDR enforcement would shift outcomes. Macroeconomic deviation in healthcare reimbursement, regulatory timeline compression, or breakthrough coating technology displacement would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cranial Perforator Market
Medical Devices
Medical Device Trays Market
Medical Devices
Veterinary Radiography Flat Panel Detectors Market
Medical Devices
Brachytherapy Afterloaders Market
Medical Devices
Public Access Automated External Defibrillators (Aeds) Market
Medical Devices
Facial Implant Market
Medical Devices
United Kingdom Respiratory Devices Market
Medical Devices
Digital Phoropter Market
Medical Devices
Airway Clearance Devices System Market
Medical Devices
Global Advanced Bipolar Direct Energy Device Market
Medical Devices
Electroencephalography Devices Market
Medical Devices
Wearable Blood Pressure Monitor Market
Medical Devices
Respiratory Inhaler Devices Market
Medical Devices
Global Anesthesia Gas Blender Market
Medical Devices
Skull Clamp Market
Medical Devices
US C-Arms Market