
 Global Smart Implants Market | 2026-2036
Global Smart Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Implants Market Foresight
German precision manufacturers is repositioning sensor-embedded orthopedic production toward North American hospital networks. Medtronic leverages integrated neurostimulation platforms to anchor its presence in neural modulation therapy. Abbott Laboratories differentiates through biosensor-enabled cardiovascular stents that sustain long-term patient monitoring capabilities.
Smart implants are active medical devices incorporating microelectronics, wireless transceivers, and biological sensors to enable real-time physiological monitoring and therapeutic feedback. These systems typically integrate MEMS-based pressure or motion detectors with biocompatible titanium or polymer housings to perform closed-loop intervention inside the human body. Orthopedic implants and neurostimulators currently occupy the largest addressable segments, while energy harvesting technology represents the fastest-expanding capability layer as manufacturers eliminate dependency on transcutaneous power transfer. Cardiovascular stents with embedded biosensors command premium positioning due to their capacity for post-implantation hemodynamic surveillance.
The FDA enforces Class III premarket approval pathways for smart implantable devices, while the EMA's Medical Device Regulation mandates clinical evidence thresholds that shape European market entry timelines. Japan's PMDA applies distinct quality management standards for wireless-enabled implants that influence design verification protocols. Stakeholders must monitor evolving cybersecurity requirements for connected implantables as regulators in the United States, Europe, and Japan independently tighten data integrity and patient safety mandates.
Market Dynamics
Energy harvesting architectures are displacing transcutaneous power systems across implantable device portfolios, forcing manufacturers to reconfigure entire electronics stacks around thermoelectric and piezoelectric generation modules.
Growth Catalysts
- Japan's PMDA wireless quality standards:These protocols accelerate design verification for Bluetooth-enabled cardiac monitors, creating regulatory clarity that shortens hospital procurement cycles.
- Closed-loop neurostimulation:Real-time feedback algorithms for Parkinson's and epilepsy treatment are expanding addressable patient populations beyond traditional open-loop devices.
- Titanium-polymer hybrid housings:Advanced biocompatible materials reduce inflammatory response rates, enabling longer implantation windows for chronic disease management.
Market Restraints
- Lithium primary cell supply concentration:Battery chemistry for backup power remains dependent on East Asian material processing, exposing manufacturers to input cost volatility.
- FDA Class III PMA timelines:Premarket approval pathways for novel sensor-implant combinations extend development cycles beyond typical venture capital horizons.
- Biological fouling limitations:Protein adhesion on glucose biosensors degrades signal accuracy after 14-day implantation, constraining chronic metabolic monitoring applications.
Strategic Opportunities
- German precision manufacturing clusters:Stuttgart and Munich sensor fabrication ecosystems offer partnership pathways for North American orthopedic OEMs seeking European production bases.
- AI-enabled predictive maintenance:Machine learning algorithms analyzing implant telemetry streams enable preemptive clinical intervention before device failure.
- India's CDSCO medical device rules:Streamlined registration pathways for Class C and D devices create first-mover advantages in a historically underpenetrated surgical implant market.
Industry Challenges
- MEMS fabrication talent scarcity:Cleanroom process engineering expertise concentrates in legacy semiconductor regions, complicating geographic diversification of sensor production.
- ISO 14155 clinical investigation compliance:Multi-site trial coordination across US, European, and Japanese investigative sites demands specialized regulatory project management capabilities that mid-tier manufacturers struggle to assemble.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Implants Market |
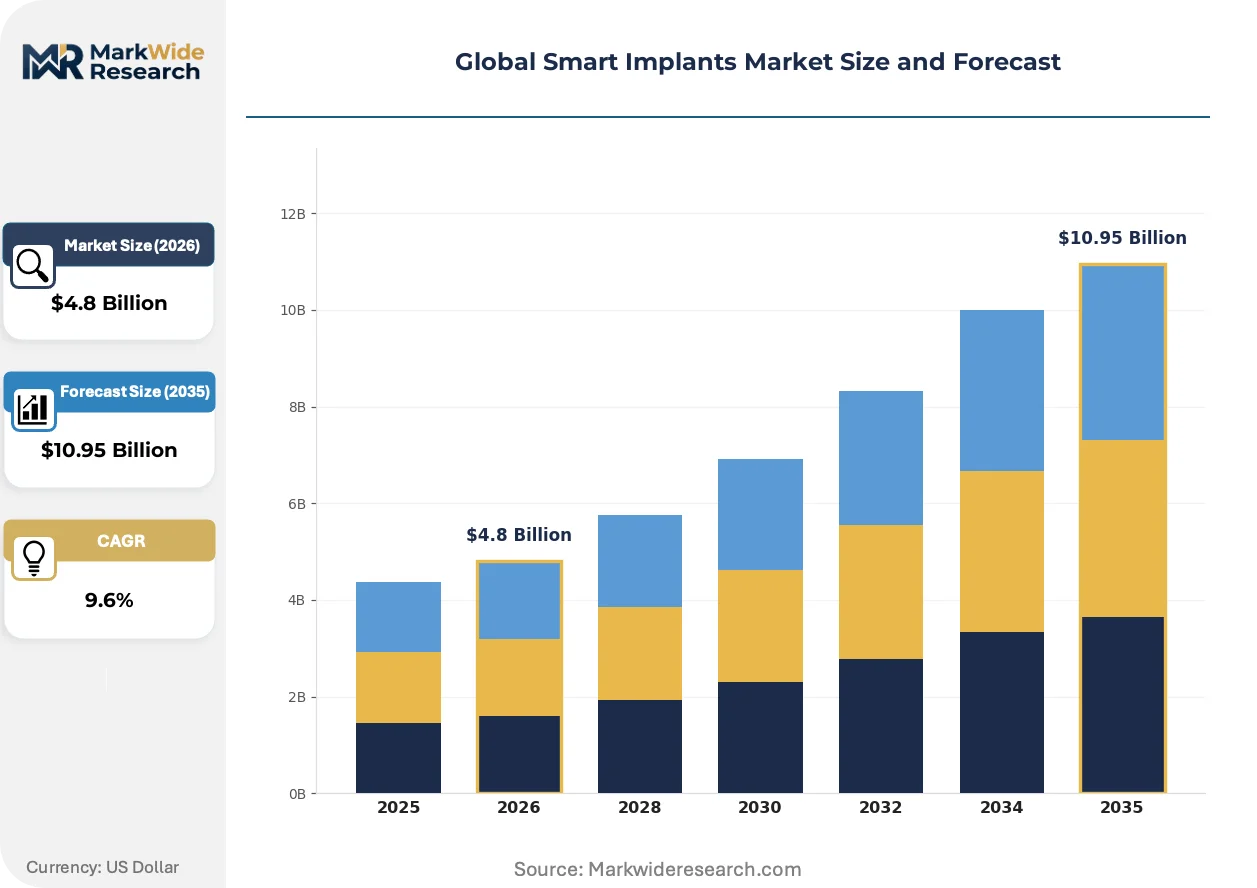
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.95 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthopedic Implants, Cardiovascular Stents, Neurostimulators, Dental Implants, Cochlear Implants Technology: Wireless Communication, Biosensors, Microelectronics, MEMS, Energy Harvesting Application: Bone Fracture Repair, Cardiac Rhythm Management, Pain Management, Hearing Restoration, Neural Modulation End User: Specialty Clinics, Ambulatory Surgery Centers, Rehabilitation Facilities, Diagnostic Laboratories, Research Institutes |
| Companies Covered | Medtronic, Abbott Laboratories, Zimmer Biomet Holdings, Stryker, Boston Scientific Corporation, BIOTRONIK SE & Co. KG, NeuroPace, Johnson & Johnson, Smith & Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Implants Market Shifts & Advancements
Wireless power transfer and edge computing architectures are converging inside implantable form factors, enabling autonomous therapeutic decision-making without external device dependency. This shift demands entirely new validation frameworks for software-as-medical-device components.
Thin-film piezoelectric energy harvesters is electrifying the power architecture of next-generation spinal cord stimulators. Boston Scientific and Nevro are integrating these generators into commercial portfolios scheduled for 2027-2028 regulatory submissions. The technology eliminates percutaneous charging ports, reducing infection vectors while compressing total cost-of-ownership calculations for hospital procurement committees.
Europe's MDR Article 10 clinical evidence requirements are tightening post-market surveillance obligations for wireless-enabled implants. Manufacturers must now submit periodic safety update reports with real-world performance data, not just pre-approval trial results. Cardiovascular stent-biosensor hybrids face the steepest compliance burden, with notified bodies demanding extended follow-up periods that delay commercial launches by 18-24 months.
Hospital value analysis committees are consolidating vendor relationships around integrated platform contracts rather than single-device purchases. This procurement compression favors suppliers offering telemetry dashboards, remote monitoring services, and predictive analytics bundled with hardware. The shift is most pronounced in US integrated delivery networks, where purchasing decisions increasingly centralize at system-wide supply chain offices rather than individual physician preference.
Global Smart Implants Market Segmentation
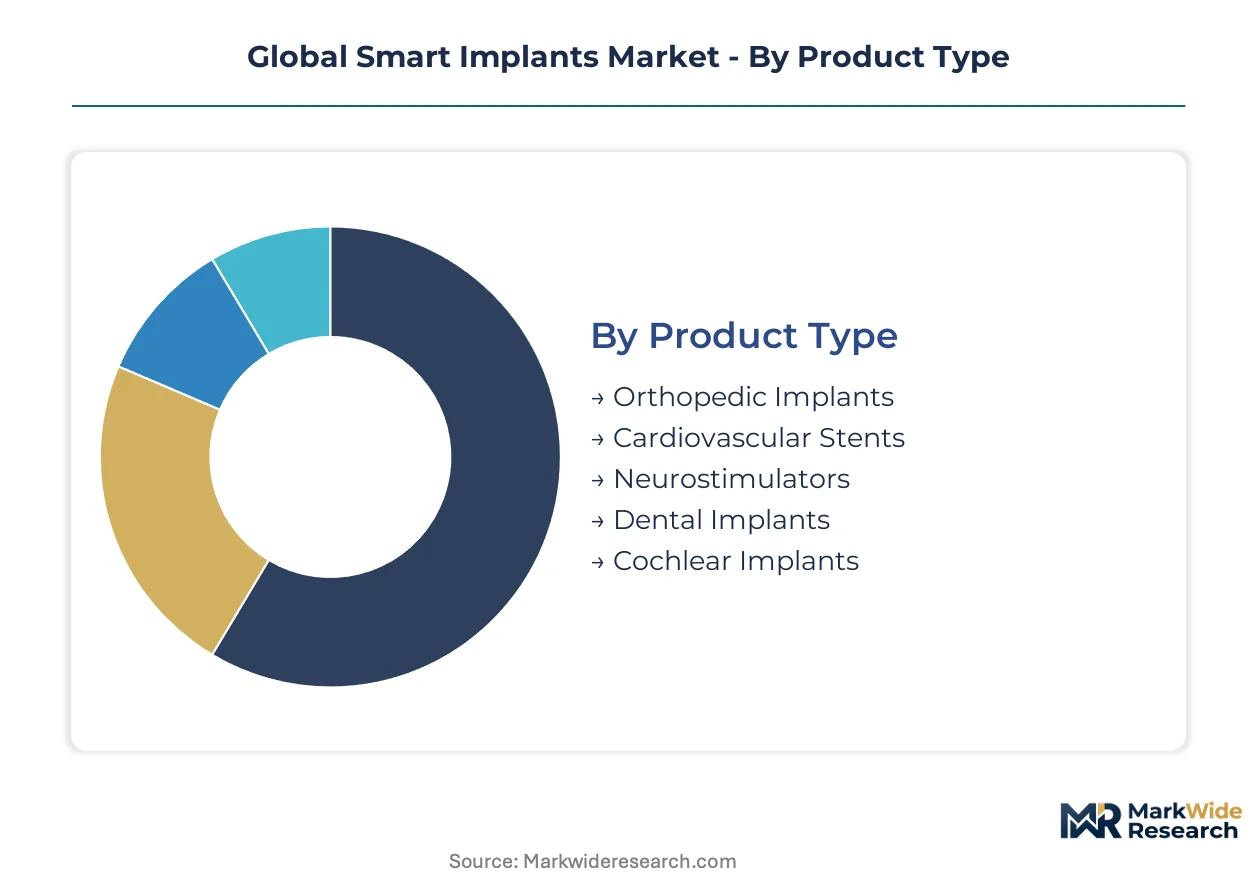
Smart implant segmentation reveals divergent capital requirements across hardware architectures. Product categories demand heavy cleanroom fabrication investment, while technology layers differentiate through R&D intensity rather than production scale.
Product Type:
Orthopedic implants absorb the heaviest upfront capital, requiring precision machining centers and biocompatible coating facilities.
- Orthopedic Implants:Sensor-embedded joint replacements integrate titanium housings with strain-gauge arrays for load-bearing monitoring. Demand concentrates in German and Japanese hospital networks seeking post-surgical mobility analytics.
- Cardiovascular Stents:Drug-eluting platforms with embedded pressure transducers enable hemodynamic surveillance after percutaneous coronary intervention. US integrated delivery networks prioritize these for reduced readmission exposure.
- Neurostimulators:Closed-loop systems for movement disorders.
- Dental Implants:Osseointegration sensors for bone density tracking.
- Cochlear Implants:Electrode arrays with wireless programming capability.
Most installed capacity flows through orthopedic implants. Expansion is steepest in cardiovascular stents.
Technology:
Wireless communication protocols command premium engineering talent pools, while energy harvesting attracts venture funding for breakthrough physics.
- Wireless Communication:Bluetooth Low Energy and proprietary RF transceivers enable telemetry without percutaneous leads. Japan's PMDA quality standards accelerate design verification for cardiac monitors.
- Biosensors:Enzymatic and affinity-based detectors measure glucose, lactate, or inflammatory markers. Protein fouling limits chronic metabolic monitoring to sub-14-day windows.
- Microelectronics:ASICs for signal processing and power management.
- MEMS:Miniaturized pressure and motion detectors.
- Energy Harvesting:Thermoelectric and piezoelectric generators eliminate transcutaneous charging.
Biosensors dominate current revenue contribution. Energy harvesting gains share fastest.
Application:
Cardiac rhythm management applications justify the steepest reimbursement codes, while neural modulation expands into psychiatric indications.
- Cardiac Rhythm Management:Pacemakers and defibrillators with remote monitoring reduce sudden cardiac death events. US Medicare bundled payment models incentivize hospital adoption.
- Neural Modulation:Deep brain stimulation for Parkinson's disease and emerging obsessive-compulsive disorder protocols. Closed-loop algorithms expand addressable populations beyond open-loop devices.
- Bone Fracture Repair:Internal fixation with strain monitoring.
- Pain Management:Spinal cord stimulation for chronic neuropathy.
- Hearing Restoration:Cochlear implant sound processing optimization.
Cardiac rhythm management commands the largest procedure volume. Neural modulation climbs the fastest.
End User:
Specialty clinics concentrate high-margin complex procedures, while ambulatory surgery centers drive volume through streamlined workflows.
- Specialty Clinics:Orthopedic and cardiology-focused facilities perform sensor-embedded implantations with dedicated remote monitoring infrastructure. German precision manufacturing clusters supply these networks directly.
- Ambulatory Surgery Centers:Same-day discharge protocols for cardiac monitors and pain stimulators. US site-of-service shifts redirect volume from inpatient settings.
- Rehabilitation Facilities:Post-implantation functional recovery programs.
- Diagnostic Laboratories:Companion testing for implant compatibility.
- Research Institutes:Clinical trial execution for novel indications.
Specialty clinics anchor current purchasing power. Ambulatory surgery centers expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates precision manufacturing capacity while the United States dominates clinical validation throughput and hospital procurement volume. Japan maintains distinct wireless quality protocols that shape design verification timelines for cardiac monitors.
United States
Integrated delivery networks centralize purchasing decisions at system-wide supply chain offices, compressing vendor relationships around bundled platform contracts. FDA Class III premarket approval pathways extend development cycles for novel sensor-implant combinations. The Greater Boston and Minneapolis-St. Paul corridors host neurostimulation and cardiac rhythm management R&D clusters.
Germany
Stuttgart and Munich sensor fabrication ecosystems supply orthopedic OEMs with MEMS-based strain-gauge arrays for load-bearing monitoring. EMA Medical Device Regulation mandates clinical evidence thresholds that shape European market entry timelines. Baden-Württemberg precision manufacturers are repositioning production toward North American hospital networks.
Japan
PMDA wireless quality standards accelerate design verification for Bluetooth-enabled cardiac monitors, shortening hospital procurement cycles. Closed-loop neurostimulation algorithms for movement disorders expand addressable patient populations beyond traditional devices. The Kanto region around Tokyo anchors domestic manufacturing and clinical trial execution.
Switzerland
Swissmedic oversight of Class III active implantable devices maintains rigorous post-market surveillance obligations for wireless-enabled systems. Biosensor-enabled cardiovascular platforms command premium positioning for hemodynamic surveillance applications. The Lake Geneva corridor concentrates microelectronics and biocompatible materials research.
India
CDSCO streamlined registration pathways for Class C and D devices create first-mover advantages in surgical implant markets historically dependent on imports. Specialty clinics in urban centers perform sensor-embedded implantations with dedicated remote monitoring infrastructure. Maharashtra and Karnataka host emerging contract manufacturing and clinical research organization clusters.
Global Smart Implants Market Competitive Landscape
German precision manufacturers anchor one tier; US-based integrated device specialists hold another. The market structures around three to five dominant platform players with full-stack capabilities, mid-tier component suppliers, and emerging energy harvesting technology ventures. Three archetypes dominate: diversified medtech conglomerates with neurostimulation portfolios, orthopedic-focused sensor integrators, and cardiovascular stent-biosensor hybrid developers. Competitive moves concentrate on strategic partnerships for MEMS fabrication access and portfolio diversification into closed-loop therapeutic systems.
Among diversified medtech conglomerates, Medtronic and Abbott Laboratories exemplify platform-scale positioning across neural modulation and cardiovascular monitoring. Boston Scientific Corporation occupies a specialist tier focused on spinal cord stimulation and piezoelectric energy harvesting integration. These three entities represent distinct competitive vectors: integrated neurostimulation platforms, biosensor-enabled cardiovascular surveillance, and next-generation power architecture elimination of transcutaneous charging ports.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Zimmer Biomet Holdings |
| Stryker |
| Boston Scientific Corporation |
| BIOTRONIK SE & Co. KG |
| NeuroPace |
| Johnson & Johnson |
| Smith & Nephew |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up orthopedic specialists concentrate procurement leverage across German and US hospital networks, compressing component supplier margins while sustaining premium positioning for closed-loop neurostimulation platforms. This ownership pattern feeds pricing discipline through volume consolidation and direct-to-manufacturer contracting that bypasses traditional distribution markups.
Pricing Analysis
Capacity additions in South Korean MEMS foundries are reshaping price floors for pressure transducers and motion detectors embedded in spinal cord stimulators. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA PMA certification status and wireless telemetry capability. Pricing pressure stems from hospital value analysis committees consolidating vendor relationships around bundled platform contracts. Ambulatory surgery centers exhibit highest price sensitivity due to Medicare site-of-service reimbursement differentials, while US integrated delivery networks prioritize total cost-of-ownership over per-unit acquisition cost.
Supply Chain Analysis
Explant recovery and refurbishment flows for cardiac rhythm management devices create secondary material streams that reduce virgin titanium dependence for housing fabrication. German precision manufacturers and Japanese sensor foundries anchor MEMS production, with Taiwan semiconductor packaging facilities feeding ASIC assembly for signal processing modules. Lithium primary cell chemistry draws from concentrated East Asian material processing, exposing manufacturers to input cost volatility. Single-source vulnerability concentrates in piezoelectric ceramic substrates for energy harvesting architectures. Distribution runs through orthopedic OEM direct sales forces and cardiovascular GPO contracts rather than independent distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Smart Implants Market functions as a stable compounder anchored by chronic disease prevalence expansion and irreversible hospital procurement centralization. Regulatory validation requirements create durable competitive moats that protect incumbent returns across multiple product cycles.
For Market Incumbents: Cement platform dominance through captive MEMS fabrication capacity in Stuttgart or Munich precision clusters, insulating against foundry allocation constraints. Defend against emerging energy harvesting ventures by accelerating piezoelectric integration timelines ahead of 2027 regulatory submissions. Prioritize ISO 14155 clinical investigation infrastructure to compress multi-site trial coordination across US, German, and Japanese investigative sites. For New Entrants and Emerging Players: Launch via CDSCO-fast-tracked Class C and D device registrations targeting Indian specialty clinics in Maharashtra and Karnataka, bypassing saturated North American procurement committees. India's historically import-dependent surgical implant market offers white-space penetration for sensor-embedded orthopedic platforms. Pursue partnership pathways with German precision manufacturing clusters to access MEMS fabrication without cleanroom talent scarcity constraints. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier component suppliers lacking closed-loop therapeutic capabilities but holding FDA master files and notified body relationships. Five-to-ten-year viability hinges on successful navigation of MDR Article 10 clinical evidence requirements and cybersecurity mandate tightening. Monitor PMDA wireless quality standard adoption velocity as inflection indicator for Bluetooth-enabled cardiac monitor procurement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Premarket approval pathways for novel sensor-implant combinations anchor US market access. |
| CE Marking Pathway | Notified body engagement under MDR Article 10 determines European commercial launch timing. |
| Hospital System Partnership | Integrated delivery network platform contracts consolidate vendor relationships and compress pricing. |
| Software Companion Development | Telemetry dashboards and predictive analytics bundles differentiate hardware procurement decisions. |
| Reimbursement Strategy | Medicare bundled payment models for cardiac rhythm management incentivize hospital adoption. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at notified bodies with secondary validation. FDA 510(k) and PMA filings, EMA MDR submission databases, PMDA approval records, hospital procurement databases, and CMS Medicare reimbursement schedules anchored supply-side and demand-side calibration. Bottom-up implant shipment modeling and top-down healthcare expenditure allocation triangulated market size estimates.
Historical reference periods spanning pre-pandemic, acute disruption, and stabilization phases anchored projection parameters across the analysis window. Segmentation dimensions modeled include product architecture, wireless communication protocol, energy harvesting capability, application indication, and end-user facility type. CAGRs derived from logistic diffusion curves fitted to adoption data, with hospital capital expenditure cycles and regulatory approval velocity as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA Class III PMA timeline extensions or lithium supply chain disruptions. Practitioners should monitor PMDA wireless quality standard harmonization progress and MDR notified body capacity constraints for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Radiofrequency-Based Aesthetic Devices Market
Medical Devices
Global Hi-Tech Medical Devices Market
Medical Devices
Balloon Inflation Devices Market
Medical Devices
Focused Ultrasound System Market
Medical Devices
Microscope Market
Medical Devices
Deflectable Catheters Market
Medical Devices
Middle East and Africa Medical Devices Market
Medical Devices
Organ Preservation & Perfusion Products Market
Medical Devices
Medication Management System Market
Medical Devices
Global Photomedicine Market
Medical Devices
United Kingdom General Surgical Devices Market
Medical Devices
Capnography Devices Market
Medical Devices
Cardioscope Market
Medical Devices
Cardiac Catheters and Guidewires Market
Medical Devices
Elderly and Disabled Assistive Devices Market
Medical Devices
Airway Management Tubes Market