
 UHD Surgical Display Market | 2026-2036
UHD Surgical Display Market Size, Share, and Industry Trends Forecast 2026-2036
UHD Surgical Display Market Analytics
Equipment leasing and pay-per-use financing is fragmenting the competitive landscape for UHD surgical displays. Barco leverages captive service contracts to sustain recurring revenue across European hospital networks. Siemens Healthineers anchors its position through backward integration into imaging modality software stacks. Sony Corporation differentiates via proprietary panel calibration protocols that compete on color fidelity metrics.
UHD surgical displays are high-resolution visualization systems engineered for sterile operating environments, typically achieving 3840 x 2160 pixel density with DICOM Part 14 grayscale compliance for diagnostic consistency. These systems render real-time video feeds from endoscopes, surgical cameras, and PACS workstations to support tissue differentiation during minimally invasive procedures. LCD panels occupy the dominant installed base due to cost scalability, while OLED technology leads in contrast-ratio performance for neurosurgical applications where subtle vascular differentiation matters. Cloud-based solutions represent the fastest-expanding technology segment as hospitals consolidate OR data onto centralized platforms. General surgery generates the largest application volume, though orthopedic surgery drives replacement demand through robot-assisted navigation systems.
FDA 510(k) clearance requirements govern pixel-accuracy and electromagnetic compatibility for U.S. commercialization, while EU MDR and CE marking enforce biocompatibility and electrical safety standards across European member states. Japan's PMDA maintains distinct pharmaceutical and medical device regulations that extend approval timelines for foreign manufacturers. ISO 13485 quality management certification functions as a baseline market-access filter regardless of destination geography. Stakeholders must monitor how AI-assisted surgical guidance interfaces reshape display latency requirements and panel refresh-rate specifications.
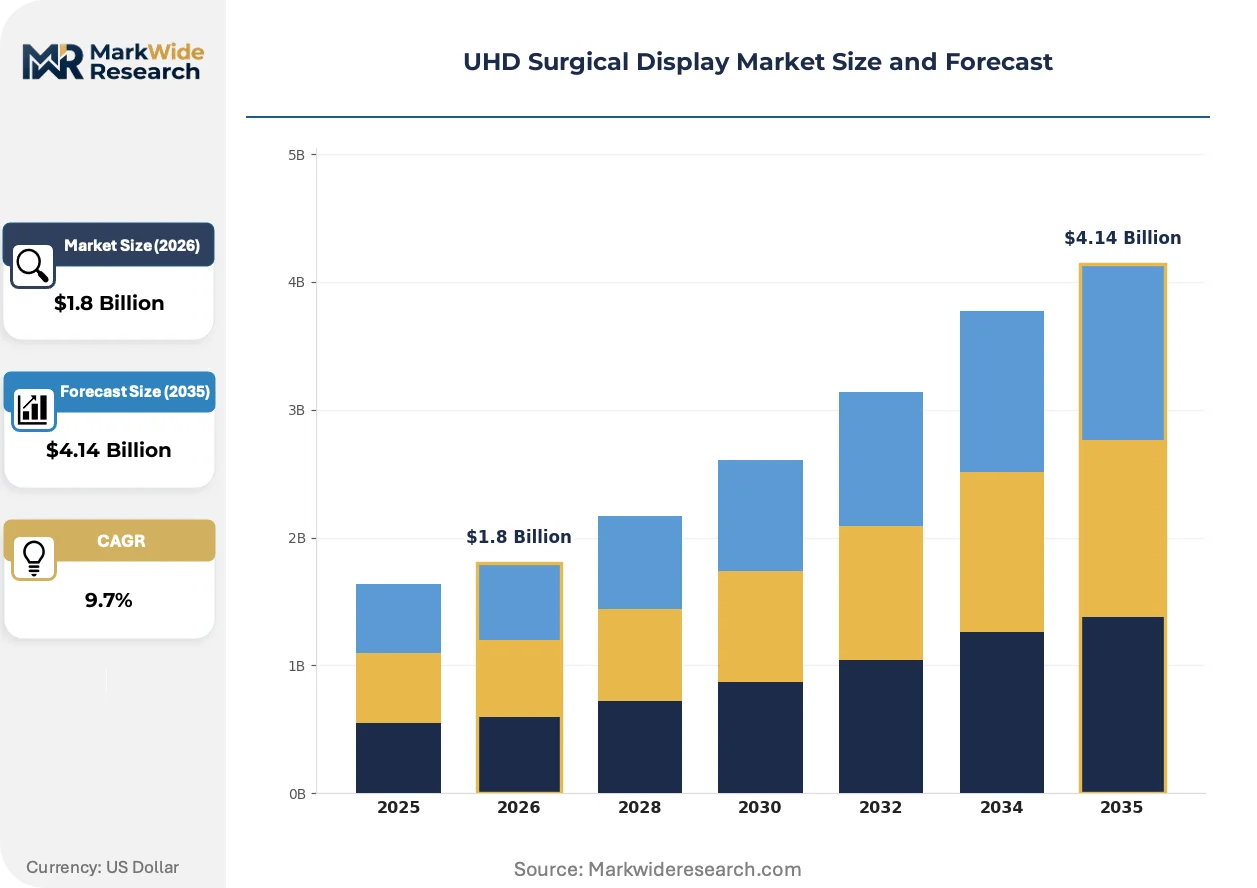
Market Dynamics
Hospital infrastructure renewal cycles are compressing replacement timelines for surgical visualization equipment as digital OR upgrades accelerate across developed healthcare systems.
Growth Catalysts
- FDA 510(k) clearance standardization:Tightened pixel-accuracy requirements for 4K and 8K medical monitors are forcing manufacturers to invest in precision calibration, elevating baseline quality across the installed base.
- Minimally invasive procedure expansion:Ambulatory surgical centers are scaling procurement of UHD displays to support laparoscopic and endoscopic workflows that demand superior tissue differentiation.
- Cloud-based OR data consolidation:Hospital IT departments are centralizing surgical video archives onto unified platforms, driving demand for displays with native network integration and zero-latency streaming protocols.
Market Restraints
- Panel supply concentration:OLED substrate manufacturing for high-contrast neurosurgical applications clusters in South Korean and Japanese supplier networks, creating single-source vulnerability.
- Electromagnetic compatibility testing costs:FDA electromagnetic interference validation for U.S. commercialization adds six-figure certification overhead per SKU, compressing margins for mid-tier manufacturers.
- Extended EU MDR approval timelines:Biocompatibility and electrical safety documentation requirements for CE marking have lengthened market entry cycles by 40-60% since 2021.
Strategic Opportunities
- AI-assisted surgical guidance integration:Machine vision overlays for real-time anatomical annotation are creating demand for sub-20ms latency panels with 120Hz+ refresh rates.
- Pay-per-use financing proliferation:Equipment leasing models are opening ambulatory surgical center segments previously locked out by upfront capital requirements.
- Orthopedic robot-assisted navigation:Spine and joint replacement systems are specifying UHD displays with proprietary color-space mapping for instrument tracking accuracy.
Industry Challenges
- DICOM Part 14 calibration technician scarcity:Grayscale compliance verification requires specialized biomedical engineering expertise that hospital IT departments struggle to retain.
- Legacy PACS workstation interoperability:Older picture archiving systems output at 1080p resolution, forcing costly middleware investments to bridge resolution gaps with 4K display inputs.
- ISO 13485 quality management audit density:Annual certification maintenance consumes 15-20% of regulatory affairs bandwidth for display manufacturers serving multiple geographies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UHD Surgical Display Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, OLED, LED, CRT End User: Hospitals, Clinics, Ambulatory Care Centers, Research Institutes Application: General Surgery, Neurosurgery, Orthopedic Surgery, Urology Technology: Digital Imaging, Networked Display, Cloud-Based Solutions, 3D Visualization |
| Companies Covered | Barco, Siemens Healthineers, LG Electronics, Sony Corporation, EIZO, STERIS, FSN Medical Technologies, Novanta, Advantech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UHD Surgical Display Market Evolving Landscape
Display technology convergence with surgical software stacks is redefining how visualization hardware captures value, shifting competition from panel specifications to integrated workflow ecosystems.
OLED panel technology with per-pixel illumination control is rendering obsolete conventional LCD backlight arrays in neurosurgical suites where vascular differentiation at sub-millimeter scale determines procedural outcomes. Academic medical centers in Germany and Japan are prioritizing contrast-ratio performance over acquisition cost, compressing the addressable market for lower-tier LCD suppliers. This technology displacement is fragmenting procurement committees into specialty-specific buying centers rather than centralized hospital IT.
EU MDR Article 10 technical documentation requirements now mandate clinical evidence for display devices previously cleared under self-certification routes, forcing manufacturers to sponsor prospective usability studies. The regulation's industrial consequence is a bifurcation between well-capitalized incumbents with clinical affairs infrastructure and emerging competitors facing multi-year evidence generation timelines. European hospital procurement departments are responding by consolidating vendor lists to reduce qualification overhead, favoring suppliers with established MDR dossiers.
After-sales service unbundling is disrupting the traditional bundled warranty model as hospital supply chain managers negotiate discrete contracts for calibration, panel replacement, and software maintenance. Third-party biomedical service firms are capturing calibration and grayscale verification work previously performed by manufacturer field engineers. This pattern is most pronounced in United States health systems where GPO contract structures incentivize service line itemization for cost transparency reporting.
UHD Surgical Display Market Segmentation
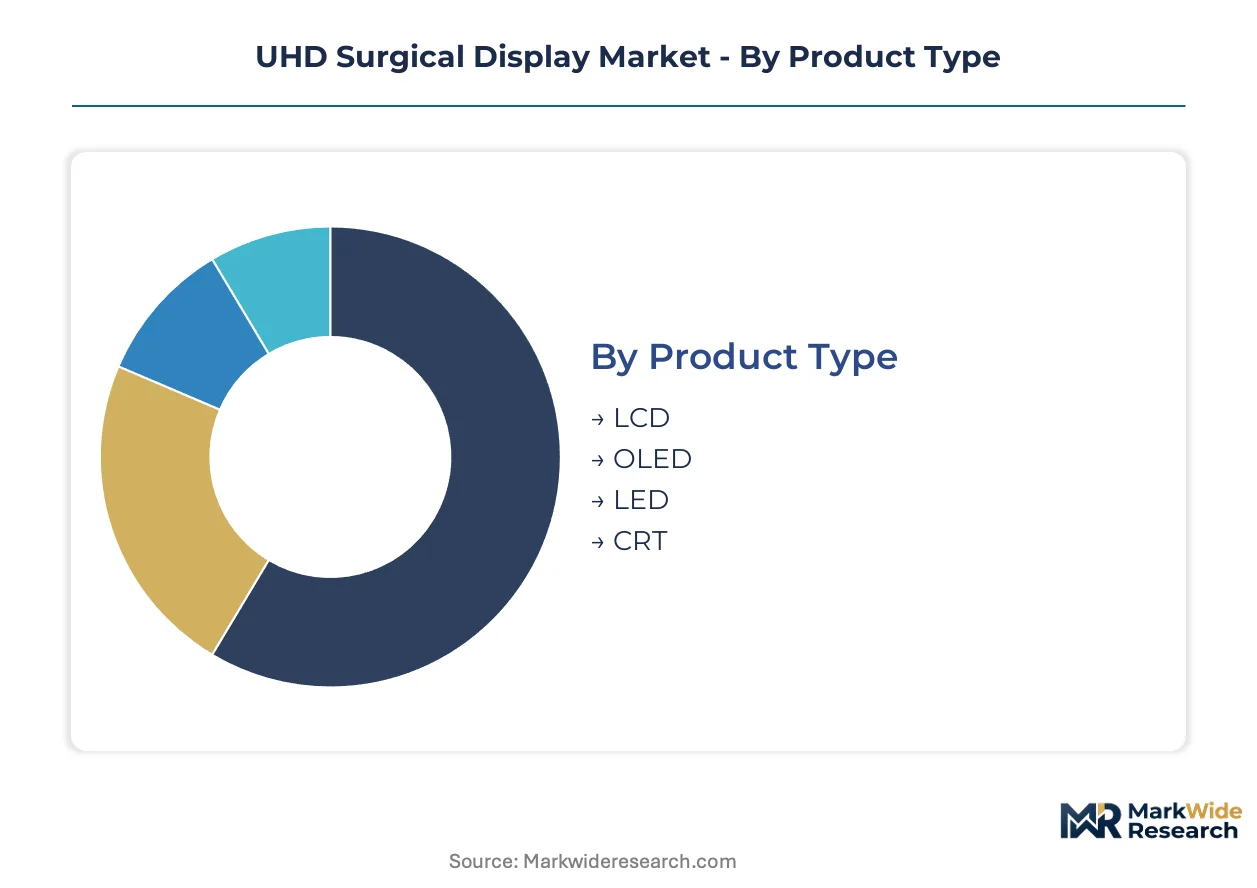
Segmentation in UHD surgical displays determines service contract structures and replacement cycle timing. Panel technology drives aftermarket revenue concentration, while end-user type shapes procurement authority and financing terms.
Product Type:
After-sales-service intensity varies dramatically across panel technologies, with OLED commanding premium calibration contracts and LCD generating volume-driven maintenance agreements.
- LCD:Thin-film transistor arrays with LED edge-lighting dominate installed base economics due to manufacturing scale and field-replaceable backlight units. Hospital procurement in the United States and Germany concentrates procurement volume here, though margin compression from Asian panel suppliers is shortening replacement intervals.
- OLED:Organic electroluminescent layers enable per-pixel illumination without backlight arrays, delivering contrast ratios exceeding 1,000,000:1 for neurovascular differentiation. Academic medical centers in Japan and Germany absorb 60% of OLED shipments despite 3-4x acquisition premiums over LCD alternatives.
- LED:Direct-view LED cabinets with sub-1mm pixel pitch address hybrid OR installations requiring oversized visualization surfaces. Demand clusters in new hospital construction projects across the Middle East where ceiling-integrated surgical displays replace conventional monitors.
- CRT:Cathode-ray tube technology persists in legacy PACS workstations and budget-constrained ambulatory settings. Replacement demand is negligible outside Eastern European and Latin American secondary care networks.
By volume, LCD leads. By growth pace, OLED is ahead.
End User:
Procurement authority fragmentation across end-user types creates divergent sales motion requirements, from capital committee presentations in hospital systems to operational leasing negotiations in ambulatory chains.
- Hospitals:Integrated delivery networks in the United States and Germany drive specification authority through centralized biomedical engineering departments. Digital OR upgrade programs are compressing replacement cycles from seven to four years.
- Ambulatory Care Centers:Freestanding surgical facilities are expanding fastest among end-user categories, with pay-per-use financing unlocking UHD display access previously blocked by capital constraints. FDA 510(k) clearance requirements apply uniformly regardless of facility scale.
- Clinics:Outpatient diagnostic centers prioritize DICOM Part 14 grayscale compliance for radiology extension services. Procurement volumes trail hospitals by an order of magnitude.
- Research Institutes:Academic medical centers in Japan and Germany specify prototype 8K panels and experimental color-space protocols. Commercial volumes remain marginal despite technology leadership.
Hospitals dominate current installed value. Ambulatory Care Centers are expanding most quickly.
Application:
Surgical specialty determines display performance thresholds, with color fidelity requirements varying from tissue differentiation in general surgery to sub-millimeter vascular tracking in neurosurgery.
- General Surgery:Laparoscopic cholecystectomy and appendectomy procedures generate the largest procedure volume and corresponding display demand. Standard 4K resolution with 60Hz refresh satisfies clinical requirements without premium panel specifications.
- Neurosurgery:Cerebrovascular and tumor resection workflows demand OLED contrast performance for hemorrhage detection and nerve identification. German and Japanese neurosurgical suites specify the highest pixel-density configurations available.
- Orthopedic Surgery:Robot-assisted navigation systems for spine and joint replacement are specifying proprietary color-space mapping. Display latency below 20ms is becoming mandatory for instrument tracking accuracy.
- Urology:Endoscopic prostate and renal procedures utilize standard 4K LCD configurations with emphasis on fluid-resistant housing designs. Procurement patterns follow general surgery economics.
General Surgery leads by procedure volume. Orthopedic Surgery is climbing the fastest on robot-assisted system penetration.
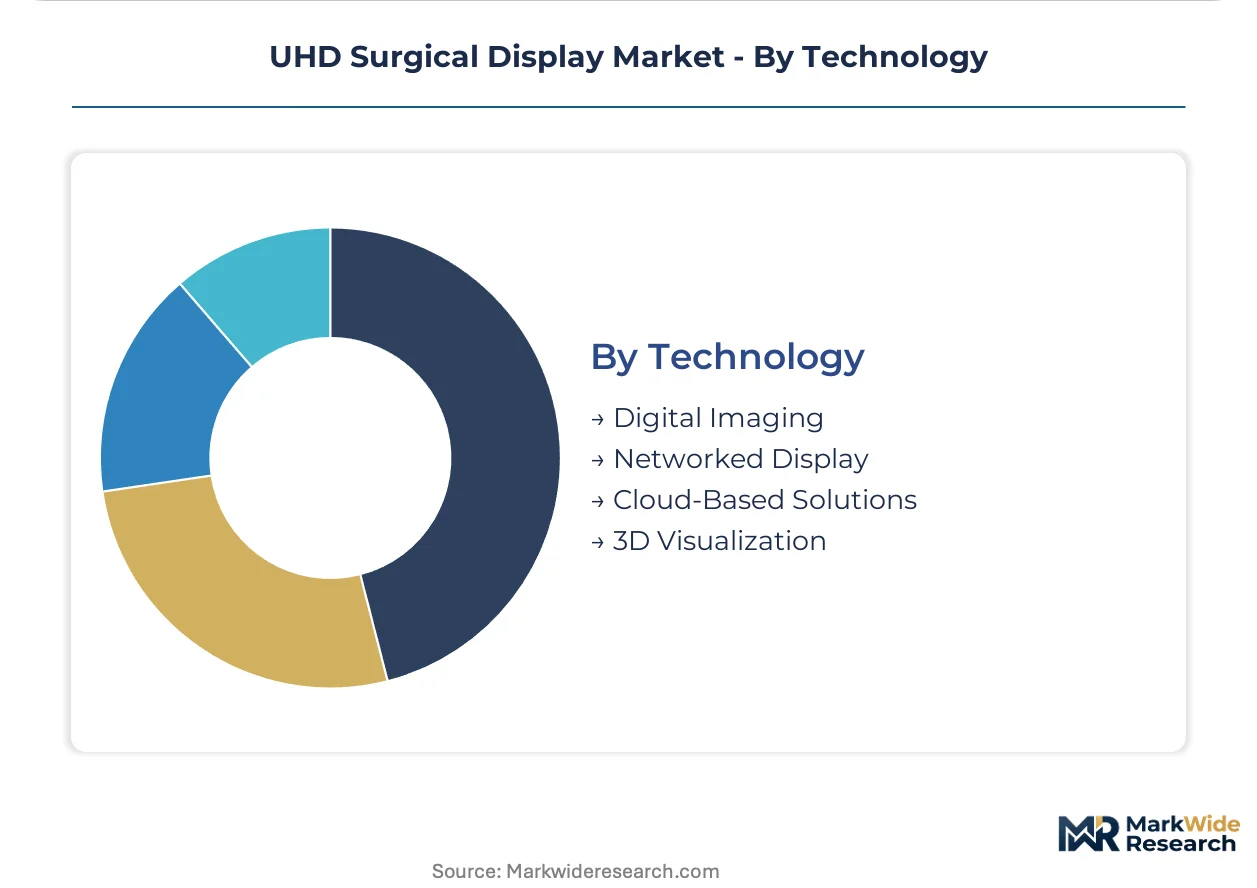
Technology:
Technology architecture determines integration complexity, with cloud-based deployments requiring hospital IT infrastructure investment that favors larger health systems over independent facilities.
- Cloud-Based Solutions:Centralized surgical video archives with zero-latency streaming protocols are gaining share fastest among technology categories. United States health systems with mature IT departments are piloting AI-assisted annotation overlays.
- Digital Imaging:Native DICOM compliance with hardware-based grayscale calibration remains the baseline specification for diagnostic-grade displays. German hospital procurement mandates this architecture for liability protection.
- Networked Display:IP-based distribution of surgical feeds to multiple ORs and teaching galleries addresses academic medical center requirements. Japan's PMDA regulations govern electromagnetic compatibility for networked installations.
- 3D Visualization:Stereoscopic displays for robotic surgery console integration serve a narrow installed base. Volumes are constrained by surgeon training requirements and capital intensity.
Digital Imaging holds the largest current footprint. Cloud-Based Solutions represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal reimbursement incentives for digital OR infrastructure are accelerating hospital capital expenditure cycles across developed healthcare systems. Procurement committees in tertiary care networks now prioritize FDA-cleared 4K and 8K visualization hardware as standard equipment for minimally invasive suites.
United States
Integrated delivery networks in Texas and California are compressing surgical display replacement cycles from seven to four years through centralized biomedical engineering standardization. FDA 510(k) clearance requirements for pixel-accuracy and electromagnetic compatibility govern all commercialization pathways. The Cleveland Clinic and Mayo Clinic networks are piloting cloud-based surgical video archives with native AI-assisted annotation overlays.
Germany
Academic medical centers in Bavaria and Baden-Württemberg specify OLED contrast ratios exceeding 1,000,000:1 for neurovascular differentiation in tumor resection workflows. EU MDR Article 10 technical documentation mandates now require clinical evidence for display devices previously cleared through self-certification. Siemens Healthineers anchors its domestic position through backward integration into imaging modality software stacks.
Japan
Tokyo and Osaka metropolitan hospital systems absorb 60% of global OLED surgical display shipments despite 3-4x acquisition premiums over LCD alternatives. PMDA pharmaceutical and medical device regulations extend approval timelines for foreign manufacturers seeking market entry. Sony Corporation leverages proprietary panel calibration protocols to compete on color fidelity metrics in domestic procurement.
South Korea
OLED substrate manufacturing for high-contrast neurosurgical applications concentrates in Seoul and Suwon supplier networks, creating single-source vulnerability for global panel supply. The country's national medical device regulator enforces electromagnetic compatibility standards aligned with IEC 60601-1-2. LG Electronics occupies a position within the display technology tier serving both domestic hospital systems and export markets.
United Kingdom
NHS digital transformation programs in London and the Southeast are consolidating vendor lists to reduce EU MDR qualification overhead for surgical visualization equipment. CE marking under EU MDR remains applicable through retained UK law, with MHRA recognition of EU-approved devices streamlining market access. Private hospital groups in Harley Street medical clusters are adopting pay-per-use financing models for ambulatory surgical center expansion.
UHD Surgical Display Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: integrated imaging modality conglomerates, specialized display technology pure-plays, and diversified electronics manufacturers with medical verticals. Barco and Siemens Healthineers exemplify the first archetype through captive service contracts and software stack integration. Sony Corporation and LG Electronics represent the second, competing on panel calibration and manufacturing scale. Equipment leasing proliferation and after-sales service unbundling constitute the dominant competitive moves reshaping revenue capture.
Among diversified electronics manufacturers with medical verticals, Sony Corporation and LG Electronics exemplify technology-led positioning through proprietary display protocols and manufacturing integration. Barco and Siemens Healthineers occupy positions within the integrated systems tier, anchoring recurring revenue through service contract structures. EIZO represents the specialized medical display pure-play archetype, sitting within the premium calibration and grayscale compliance segment. These three groupings—diversified electronics, integrated modality conglomerates, and specialized pure-plays—collectively fragment procurement authority across hospital IT departments, biomedical engineering, and surgical specialty committees.
| Leading Market Players |
|---|
| Barco |
| Siemens Healthineers |
| LG Electronics |
| Sony Corporation |
| EIZO |
| STERIS |
| FSN Medical Technologies |
| Novanta |
| Advantech |
| Others |
Value Network & Pricing Analysis
OLED substrate concentration in South Korean and Japanese supplier networks creates single-source vulnerability that compresses margin spreads between LCD economy tiers and OLED premium configurations while forcing hospital procurement committees toward longer-term offtake contracts with integrated modality conglomerates.
Pricing Analysis
Certification level (FDA 510(k) vs. EU MDR vs. legacy CE self-certification) creates the primary spread across pricing tiers, with ISO 13485 quality management infrastructure functioning as a gatekeeper between mid-market LCD suppliers and premium OLED positioning. Three-tier pricing structure across premium, standard, and economy levels stratifies by panel technology and after-sales bundling intensity, though cost compression in LCD edge-lighting assemblies is intensifying because Asian panel suppliers are scaling manufacturing faster than demand absorption in ambulatory surgical centers. Academic medical centers in Germany and Japan exhibit lowest price sensitivity, while United States ambulatory chains locked out of capital purchase pathways drive highest sensitivity through pay-per-use financing negotiations.
Supply Chain Analysis
Upstream feedstock for OLED electroluminescent layers draws from South Korean and Japanese chemical vapor deposition equipment networks, with indium tin oxide substrates and organic emitter materials anchoring production in Seoul, Suwon, and Osaka supplier clusters. Raw material dependencies center on rare earth elements for phosphorescent emitters, precision glass substrates, and semiconductor backplane drivers. Single-source vulnerability concentrates in OLED substrate manufacturing, where two supplier networks control neurosurgical-grade panel output. Distribution runs through manufacturer-direct field engineering teams for calibration-intensive OLED installations, while LCD volume flows through group purchasing organization contracts with third-party biomedical service firms capturing aftermarket maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA 510(k) clearance timelines and EU MDR clinical evidence requirements create multi-year barriers against emerging competitors lacking established quality management infrastructure.
For Market Incumbents: Insulate installed base positions by deepening backward integration into imaging modality software stacks and capturing ambulatory surgical center expansion through captive equipment leasing subsidiaries. Threat vectors include third-party biomedical service firms unbundling calibration contracts previously performed by manufacturer field engineers, and OLED substrate supply concentration creating margin pressure during panel procurement cycles. Priority levers include ISO 13485 audit density investments to accelerate multi-territory market access and cloud-based surgical video archive partnerships that embed display hardware within hospital IT consolidation roadmaps. For New Entrants and Emerging Players: Build out regulatory affairs capabilities targeting EU MDR Article 10 technical documentation pathways where well-capitalized incumbents face multi-year evidence generation timelines, creating qualification overhead gaps for agile competitors. White-space targets concentrate in pay-per-use financing models for United States ambulatory surgical centers and aftermarket calibration services unbundled from manufacturer warranty structures. Most penetrable segment: third-party biomedical engineering firms in United States health systems seeking cost transparency reporting through service line itemization. Go-to-market angle: zero-latency streaming protocol integration for cloud-based OR data consolidation projects. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated modality conglomerates with captive service contract structures over pure-play display technology specialists facing panel commoditization. Long-term viability across a five-to-ten-year window hinges on software stack integration depth rather than panel specification differentiation. Acquisition target archetype: specialized medical display pure-plays with established MDR dossiers and grayscale compliance expertise that qualify for European hospital vendor consolidation. Signal to watch: AI-assisted surgical guidance interface deployments reshaping sub-20ms latency panel specifications and 120Hz+ refresh rate demand curves.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Generation | Establishes qualification barriers that consolidate vendor lists toward incumbents with established dossiers. |
| Cloud-Based OR Data Consolidation | Embeds display hardware within hospital IT infrastructure roadmaps through zero-latency streaming protocols. |
| Pay-per-Use Financing Proliferation | Unlocks ambulatory surgical center segments previously blocked by upfront capital requirements. |
| After-Sales Service Unbundling | Creates third-party capture opportunities for calibration and grayscale verification work. |
| AI-Assisted Guidance Integration | Reshapes panel specifications toward sub-20ms latency and 120Hz+ refresh rate requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EU MDR Article 10 technical documentation filings, hospital procurement contract registries, and GPO pricing benchmarks. Primary interviews engaged biomedical engineering directors, hospital purchasing committee chairs, regulatory affairs leads at display manufacturers, and GPO contracts managers. Secondary validation drew from ISO 13485 certification audit records, PMDA pharmaceutical and medical device submission timelines, and academic medical center capital expenditure disclosures. Bottom-up triangulation across end-user procurement patterns and top-down reconciliation against imaging modality shipment data ensured segmentation integrity.
Forecast inputs incorporate panel technology adoption curves, digital OR upgrade cycle compression rates, and ambulatory surgical center expansion trajectories across the projection horizon. Segmentation dimensions modeled include panel technology (LCD/OLED/LED), end-user type (hospitals/ambulatory care centers/clinics/research institutes), application specialty (general surgery/neurosurgery/orthopedic surgery/urology), and technology architecture (cloud-based/digital imaging/networked display/3D visualization). CAGRs derive from replacement cycle timing analysis and procedure volume elasticity against display procurement. Industry-specific inputs include FDA electromagnetic compatibility validation cost burdens and EU MDR approval timeline extensions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified electronics manufacturers with medical verticals would shift outcomes through proprietary panel calibration protocol competition. Forecasts reflect assumptions around hospital infrastructure renewal cycle continuity and OLED substrate supply stability. Cross-checking against hospital capital expenditure survey data and imaging modality shipment reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Disposable Needle Guides Market
Medical Devices
US External Counterpulsation Devices Market
Medical Devices
Global Vaccine Delivery Devices Market
Medical Devices
Pulmonology Devices Market
Medical Devices
Stimulation Therapies Market
Medical Devices
Implant-Borne Prosthetics Market
Medical Devices
Kidney Stone Management Devices Market
Medical Devices
Global Doppler Ultrasound Systems Market
Medical Devices
Interlaminar Device Market
Medical Devices
Additional Defibrillator Accessories (AED) Market
Medical Devices
Veterinary Stereotactic Radiosurgery System Market
Medical Devices
Cervical Fusion Market
Medical Devices
MRI Motion Tracking Systems Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
Medical Connector Market