
 Asthma Spacers Market | 2026-2036
Asthma Spacers Market Size, Share, and Industry Trends Forecast 2026-2036
Asthma Spacers Market Intelligence
Asset-light leasing models for respiratory device fleets is rewriting competitive economics in the spacer segment, lowering capital barriers for regional distributors. Trudell Medical International leverages its North American manufacturing footprint to sustain hospital channel dominance. PARI GmbH anchors European market access through specialized pediatric spacer portfolios. Cipla Inc. competes on cost-engineered plastic chamber variants across emerging markets.
An asthma spacer is a cylindrical attachment that interfaces between a metered-dose inhaler and the patient's airway, typically constructed from anti-static polymers or polycarbonate to minimize drug deposition on interior walls and maximize pulmonary delivery of bronchodilator aerosols. Valved holding chambers command the largest product segment due to their universal compatibility with pressurized inhalers and superior drug delivery efficiency in pediatric populations. Home care settings represent the fastest-growing end-user channel as post-acute respiratory management shifts beyond hospital walls. Plastic and polycarbonate materials dominate manufacturing inputs, though silicone components are gaining share in premium reusable designs.
The FDA regulates spacer devices as Class II medical instruments under 510(k) premarket notification pathways, while the EMA's Medical Device Regulation imposes stricter biocompatibility and clinical performance documentation requirements for European market entry. Health Canada and the TGA enforce parallel standards that shape product redesign cycles and regional launch sequencing. Stakeholders must monitor evolving reimbursement codes for durable respiratory equipment and anticipate polymer supply constraints that could reshape manufacturing geography.
Market Dynamics
The FDA's renewed emphasis on valved holding chamber performance standards is compressing product development cycles while elevating quality barriers for manufacturers seeking 510(k) clearance. This regulatory tightening is reshaping competitive economics across the spacer segment.
Growth Catalysts
- Remote respiratory management protocols:Pediatricians in home care settings are expanding spacer prescriptions as post-acute monitoring shifts beyond hospital walls. Home care represents the fastest-growing end-user channel.
- EMA Medical Device Regulation:Stricter biocompatibility documentation requirements for European market entry are accelerating product redesign cycles that favor established manufacturers with robust clinical data portfolios.
- Anti-static polymer formulations:Advanced polycarbonate materials that minimize drug deposition on interior walls are improving pulmonary delivery efficiency and driving replacement demand in pediatric populations.
Market Restraints
- Polymer supply concentration:Manufacturing inputs for plastic and polycarbonate chambers face geographic concentration risks that could reshape production geography and inflate input costs.
- Reimbursement code volatility:Evolving durable medical equipment coverage policies in the United States create pricing uncertainty for distributors managing respiratory device fleets.
- Silicone component cost premiums:Premium reusable designs incorporating silicone elements face cost-structure pressures that limit mass-market penetration against disposable alternatives.
Strategic Opportunities
- Asset-light leasing models:Respiratory device fleet leasing is lowering capital barriers for regional distributors and rewriting competitive economics in the spacer segment.
- Health Canada parallel standards:Alignment with FDA quality benchmarks creates streamlined regulatory pathways for manufacturers already holding 510(k) clearance.
- Pediatric specialization:Specialized spacer portfolios targeting age-specific airway anatomy remain underdeveloped relative to adult-format dominance.
Industry Challenges
- ISO 13485 quality management certification:Medical device manufacturing standards require sustained compliance investment that strains mid-tier producers.
- Legacy inhaler compatibility testing:Ensuring universal fit across pressurized inhaler variants demands extensive validation protocols that extend time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asthma Spacers Market |
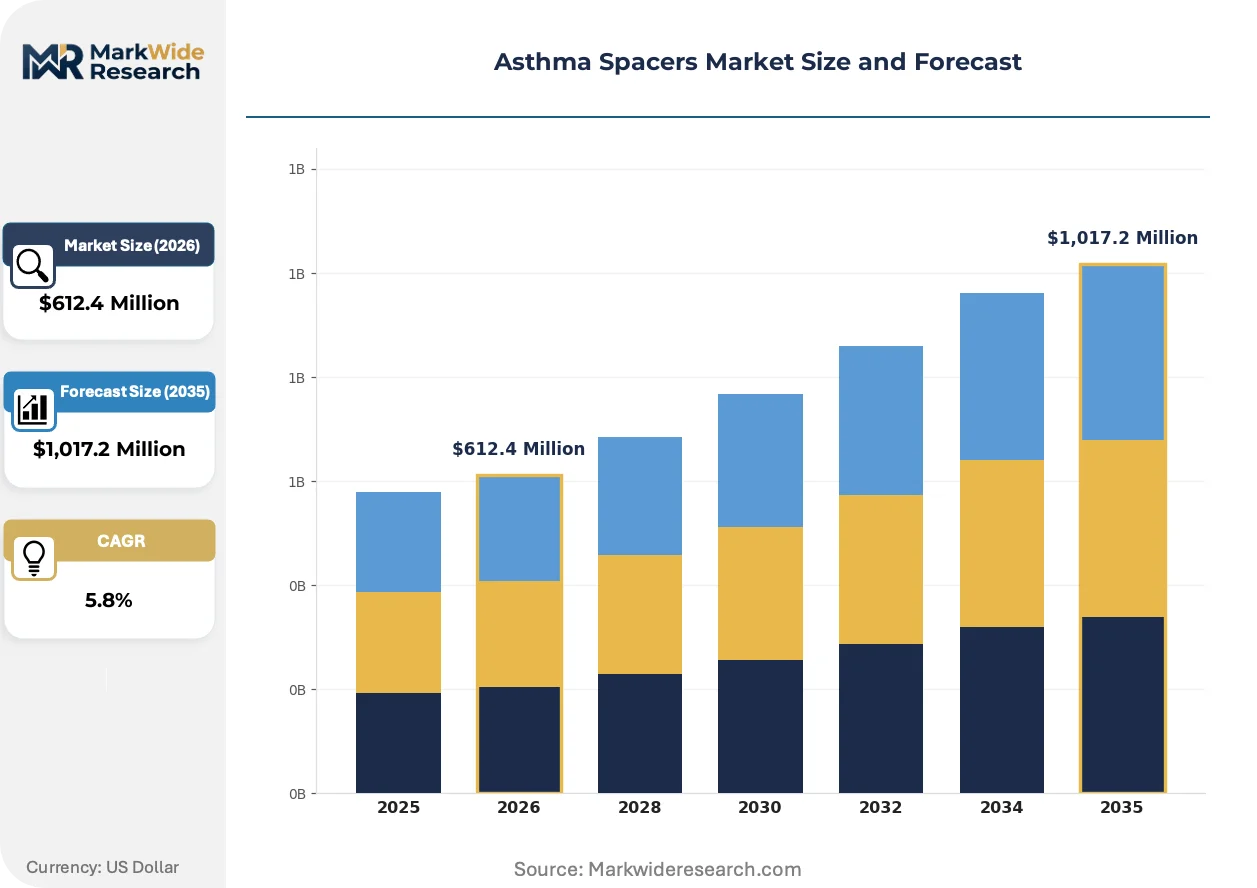
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,017.2 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Valved Holding Chamber, Non-Valved Chamber, Breath-Activated Spacer, Universal Spacer Material: Plastic, Silicone, Metal, Polycarbonate, Thermoplastic Elastomer End User: Respiratory Clinics, Pediatricians, Pulmonologists, Home Care Settings Distribution Channel: Pharmacies, Online Retail, Hospitals, Medical Device Distributors |
| Companies Covered | PARI GmbH, Trudell Medical International, GlaxoSmithKline, Koninklijke Philips N.V., Cipla Inc., Lupin Limited, Monaghan Medical Corporation, Laboratoire ProtecSom, Medical Developments International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asthma Spacers Market Strategic Shifts & Innovations
Digital integration and materials science advances are converging to transform spacer functionality from passive drug delivery chambers into connected respiratory management tools. This evolution is compressing traditional hardware margins while opening software-enabled revenue streams.
Smart spacer technology incorporating flow sensors and Bluetooth connectivity is virtualizing patient adherence monitoring for clinicians managing pediatric asthma populations. Pulmonologists in integrated health systems are piloting these devices to capture real-world usage data. The technology is virtualizing the traditional patient-clinic relationship by enabling remote dosage verification and technique correction without office visits.
The FDA's tightened 510(k) premarket notification pathways for Class II medical instruments are extending clearance timelines for novel spacer designs. Manufacturers must now submit expanded clinical performance documentation demonstrating equivalence to predicate devices. Pediatric spacer portfolios face the steepest compliance burden due to heightened safety scrutiny for vulnerable populations.
Hospital procurement departments are consolidating respiratory device purchasing through centralized durable medical equipment contracts that bundle spacers with inhalers and peak flow meters. This bundling is displacing standalone spacer sales through traditional distributor channels. The United States exhibits the most pronounced concentration, where group purchasing organizations command increasing leverage over manufacturer pricing.
Asthma Spacers Market Segmentation
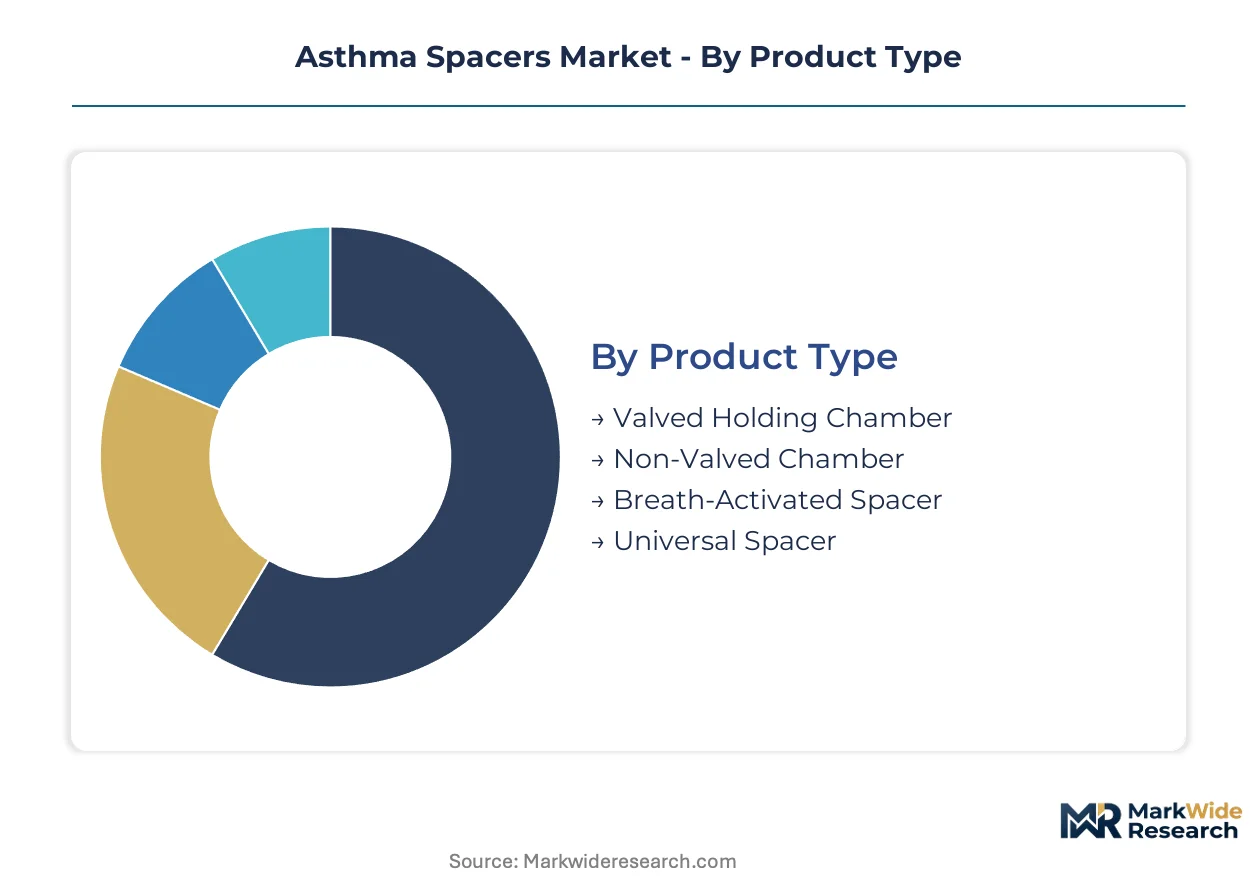
Asthma spacer purchasing decisions split across clinical performance requirements, material durability preferences, and care delivery settings. Manufacturers must align product architectures with distinct reimbursement pathways and user capability profiles that vary sharply between hospital procurement and direct-to-patient channels.
Product Type:
Use-case spectrum spans acute rescue medication delivery in emergency settings through to daily maintenance therapy in unsupervised home environments.
- Valved Holding Chamber:Incorporates one-way valves that retain aerosolized medication during exhalation, enabling coordinated breathing for young children and elderly patients with impaired hand-breath synchronization. Demand concentrates in pediatric pulmonology practices across the United States where insurance coverage for durable medical equipment remains elevated and FDA quality benchmarks favor established valved designs.
- Non-Valved Chamber:Simpler cylindrical construction without mechanical valves reduces manufacturing cost and cleaning complexity for budget-conscious health systems. Adoption favors respiratory clinics in emerging markets where cost-engineered plastic variants dominate procurement decisions and clinical staff provide direct supervision during administration.
- Breath-Activated Spacer:Flow-triggered mechanisms release medication only on detected inhalation, eliminating coordination requirements entirely.
- Universal Spacer:Modular interfaces accommodate multiple inhaler geometries through adjustable mouthpiece adapters.
Established volume favors valved holding chambers; emerging adoption favors breath-activated spacers.
Material:
Cost tier stratification separates premium reusable designs from high-volume disposable alternatives.
- Polycarbonate:Anti-static polymer formulations minimize electrostatic drug deposition on interior walls, maximizing pulmonary delivery efficiency for corticosteroid suspensions. Demand concentrates in pediatric home care settings where parents prioritize medication conservation and reusable construction justifies higher upfront expenditure against disposable alternatives.
- Plastic:Injection-molded polypropylene and ABS variants enable mass production at lowest unit cost for single-use hospital dispensing. Procurement favors group purchasing organizations in the United States bundling plastic spacers with inhaler formularies through centralized durable medical equipment contracts.
- Silicone:Flexible, autoclavable construction supports premium reusable designs with extended service life.
- Metal:Aluminum and stainless steel chambers offer durability for institutional settings with aggressive sterilization protocols.
- Thermoplastic Elastomer:Soft-touch mouthpiece components improve pediatric compliance and mask seal integrity.
Disposable economics favor plastic; clinical performance optimization favors polycarbonate.
End User:
Customer capability divides between supervised clinical administration and self-managed home therapy.
- Home Care Settings:Post-acute respiratory management protocols are expanding spacer prescriptions as remote patient monitoring platforms enable virtual adherence tracking. Pediatricians in the United States are driving fastest channel expansion through telehealth-integrated asthma action plans that substitute home spacer use for routine clinic visits.
- Pediatricians:Age-specific airway anatomy demands specialized chamber volumes and mask interfaces for infant through adolescent populations.
- Pulmonologists:Severe asthma and COPD comorbidity management requires high-fidelity drug delivery documentation for therapy optimization.
- Respiratory Clinics:High-throughput environments prioritize rapid patient turnover and standardized device training protocols.
Clinical anchoring favors pediatricians and pulmonologists; volume expansion favors home care settings.
Distribution Channel:
Supply concentration varies between regulated medical device procurement and consumer-direct retail pathways.
- Medical Device Distributors:Regional respiratory device fleets leverage asset-light leasing models that lower capital barriers for independent distributors serving community hospitals. Channel concentration in the United States reflects consolidated durable medical equipment reimbursement codes that favor established distributor relationships over direct manufacturer sales.
- Pharmacies:Retail dispensing integrates spacer counseling with inhaler prescription fulfillment, capturing walk-in replacement demand.
- Hospitals:Centralized procurement departments bundle spacers with inhalers and peak flow meters through integrated contracts.
- Online Retail:Direct-to-consumer platforms bypass prescription requirements for over-the-counter spacer sales.
Institutional volume favors medical device distributors and hospitals; patient convenience favors online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of anti-static polymer formulations concentrate in Germany and the United States, while import dependency for finished spacers shapes procurement economics in Brazil and India. Trade balances favor manufacturing economies with integrated medical device supply chains.
United States
Pediatric pulmonology practices drive spacer demand through telehealth-integrated asthma action plans that substitute home use for clinic visits. The FDA's tightened 510(k) premarket notification pathways for Class II medical instruments compress product development cycles. Minneapolis and Cleveland host respiratory device manufacturing clusters where Trudell Medical International sustains hospital channel dominance through North American production footprints.
Germany
Specialized pediatric spacer portfolios anchor European market access through precision-engineered polycarbonate designs. The EMA's Medical Device Regulation imposes stricter biocompatibility documentation requirements that accelerate redesign cycles favoring established manufacturers. Stuttgart and Munich concentrate polymer processing capabilities serving continental distribution networks.
India
Cost-engineered plastic chamber variants dominate procurement decisions across emerging market health systems with budget-constrained respiratory clinics. CDSCO medical device registration requirements shape regional launch sequencing for imported devices. Mumbai and Ahmedabad host injection-molding clusters producing high-volume disposable alternatives for domestic and export markets.
United Kingdom
Integrated health systems pilot smart spacer technology incorporating flow sensors and Bluetooth connectivity for real-world usage data capture. NHS reimbursement frameworks for durable medical equipment create pricing benchmarks that influence European procurement patterns. Cambridge and Oxford medical technology corridors attract digital respiratory device development.
Australia
TGA enforcement of parallel standards to FDA quality benchmarks streamlines regulatory pathways for manufacturers holding existing clearances. Remote patient monitoring platforms enable virtual adherence tracking in dispersed rural populations. Melbourne and Sydney concentrate respiratory device distribution serving Pacific regional markets.
Asthma Spacers Market Key Industry Players
On the supply side, the industry is tiered between premium polycarbonate specialists and mass-market plastic fabricators. Regional respiratory device fleets leverage asset-light leasing models that lower capital barriers for independent distributors. Three archetypes dominate: North American hospital channel anchors, European pediatric specialists, and emerging market cost engineers. Competitive moves concentrate on portfolio diversification into connected device platforms and strategic partnerships with group purchasing organizations.
Within the premium-tier vector, PARI GmbH exemplifies European pediatric specialization through German-engineered chamber designs. Trudell Medical International occupies a position as the North American manufacturing anchor serving consolidated hospital procurement. Cipla Inc. represents the cost-engineered archetype, with Mumbai-based production scaling plastic variants across price-sensitive health systems.
| Leading Market Players |
|---|
| PARI GmbH |
| Trudell Medical International |
| GlaxoSmithKline |
| Koninklijke Philips N.V. |
| Cipla Inc. |
| Lupin Limited |
| Monaghan Medical Corporation |
| Laboratoire ProtecSom |
| Medical Developments International |
| Others |
Cost & Logistics Intelligence
Undercapacity in German polycarbonate resin production is elevating input cost volatility for anti-static polymer formulations while simultaneously compressing margin buffers for chamber manufacturers serving FDA-regulated channels. This utilization squeeze propagates through contract structures, forcing tiered pricing separations between premium reusable designs and disposable alternatives.
Pricing Analysis
Hospital procurement committees anchor pricing negotiations through centralized durable medical equipment contracts that bundle spacers with inhaler formularies. Three-tier pricing structure across premium polycarbonate, standard plastic, and economy disposable levels reflects FDA certification grade and volume scale commitments from group purchasing organizations. Pricing pressure stems from reimbursement code volatility in United States Medicaid frameworks, with pediatric home care segments exhibiting highest price sensitivity against institutional buyers.
Supply Chain Analysis
Export-control restrictions on advanced polymer processing equipment limit capacity expansion in emerging manufacturing economies, concentrating anti-static resin supply in Germany and the United States. Raw material flows draw from polycarbonate feedstock in Stuttgart, silicone components in Michigan, and injection-molding tooling from Japan. Single-source vulnerability persists for medical-grade anti-static coatings. Distribution runs through medical device distributors leveraging asset-light leasing models for regional respiratory device fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Profitable participation in this market demands mastery of pediatric-specific regulatory pathways and polymer formulation IP that remains concentrated among established European and North American manufacturers. The capability gap separating certified chamber producers from commodity fabricators is widening.
For Market Incumbents: Pre-empt competitive erosion by deepening backward integration into anti-static polymer resin production and securing exclusive group purchasing organization contracts before reimbursement consolidation accelerates. Prioritize ISO 13485 certification maintenance as quality barriers tighten under FDA 510(k) pathway revisions. For New Entrants and Emerging Players: Pursue white-space opportunities in connected smart spacer platforms integrating Bluetooth adherence monitoring, where regulatory pathways remain unsettled and incumbent R&D lag creates penetration windows. Target telehealth-integrated pediatric home care segments through direct-to-clinic software companion development. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier manufacturers holding FDA 510(k) clearances but lacking European CE marking, where MDR compliance investments create acquisition discounts with embedded geographic expansion optionality. Watch for inflection signals in polymer supply contract renegotiations indicating input cost stabilization.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Submission | Clearance under tightened performance standards secures hospital channel access against predicate device competition. |
| CE Marking Pathway under MDR | European biocompatibility documentation creates defensible market position in German pediatric specialization clusters. |
| Hospital System Partnership | Integrated durable medical equipment contracts displace standalone distributor sales through formulary bundling leverage. |
| Software Companion Development | Bluetooth-enabled adherence platforms virtualize patient-clinic relationships for telehealth-integrated asthma management. |
| Reimbursement Strategy | CMS durable medical equipment code alignment determines pricing floor for Medicaid-covered pediatric populations. |
Research Approach
Initial hypotheses were tested against primary input from pediatric pulmonologists, hospital procurement managers, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) premarket notification databases, EMA Medical Device Regulation submission filings, hospital procurement contract repositories, and CMS durable medical equipment reimbursement schedules. Bottom-up demand modeling across patient population segments triangulated against top-down polymer consumption estimates.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeling spanning valved versus non-valved chamber architectures, polycarbonate-plastic-silicone material tiers, and home care-hospital-respiratory clinic end-user channels. CAGRs were derived from patient prevalence trajectories and replacement cycle assumptions for reusable versus disposable designs, incorporating FDA regulatory timeline impacts on product launch sequencing.
Sensitivities concentrate around polymer supply disruptions and reimbursement code revisions that could compress replacement demand timelines. Forecasts reflect assumptions regarding regulatory clearance velocity and pediatric asthma prevalence stability. Material shifts in FDA valved holding chamber performance standards or EMA biocompatibility documentation requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Germany Respiratory Devices Market
Medical Devices
Global Intragastric Balloon Market
Medical Devices
Hyperpigmentation Treatment Devices Market
Medical Devices
South Korea Drug Delivery Devices Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
Complementary Therapy Devices Market
Medical Devices
Varicose Vein Treatment Devices Market
Medical Devices
Organ Preservation & Perfusion Products Market
Medical Devices
Acute External Ventricular Drain Market
Medical Devices
3D Printing for Surgical Procedures Market
Medical Devices
Global Implantable Cardioverter Defibrillators (ICD) Market
Medical Devices
Global Thermoelectric Devices in Medical and Laboratory Offering Market
Medical Devices
Electrophysiology Market
Medical Devices
US Thrombectomy Devices Market
Medical Devices
China Respiratory Devices Market
Medical Devices
Blood Warmer Devices/Sample Warmer Market