
 Global Defibrillators Market | 2026-2036
Global Defibrillators Market Size, Share, and Industry Trends Forecast 2026-2036
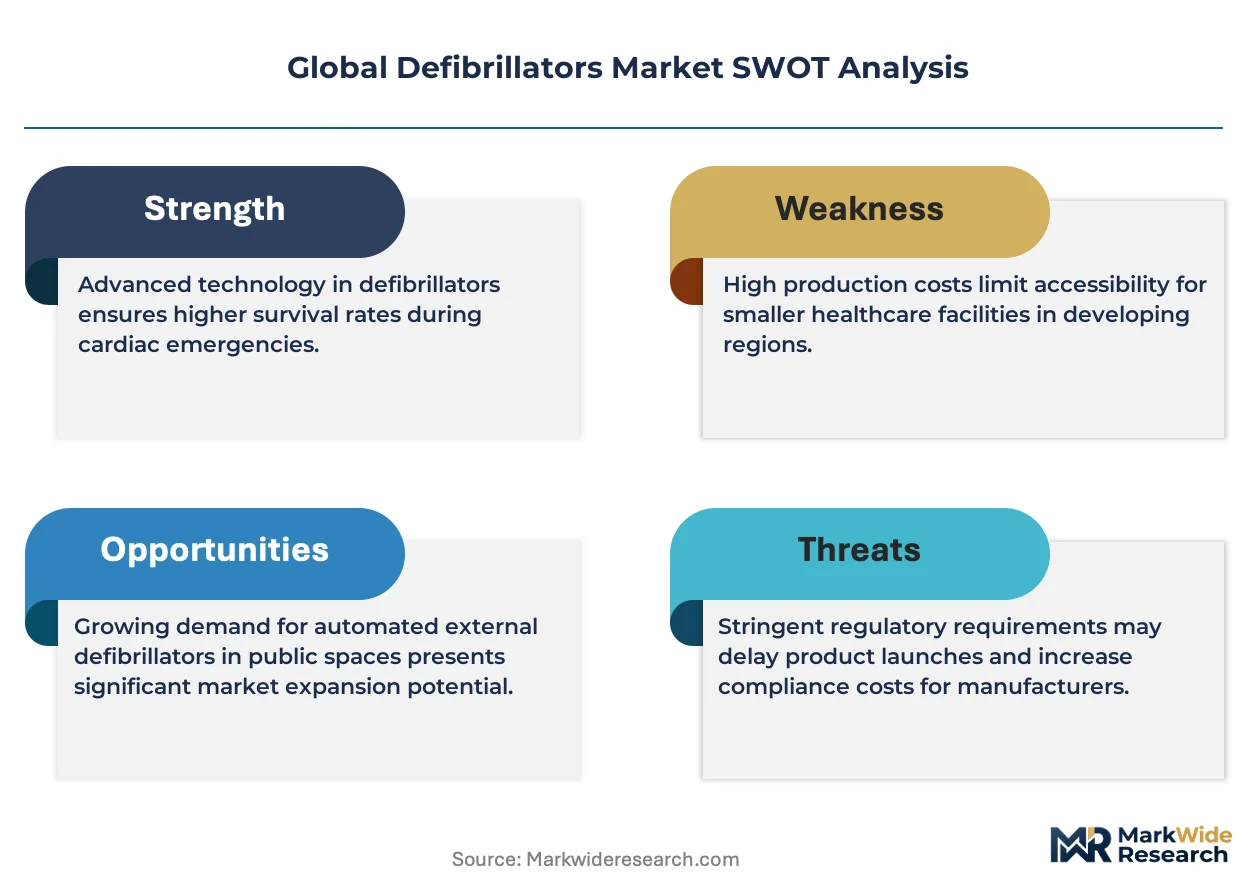
Global Defibrillators Market Analysis
Aftermarket service revenue is reshaping competitive economics in the Global Defibrillators Market. Medtronic leverages its extensive field service network to capture recurring maintenance contracts across implantable systems. Abbott anchors its position through specialized technical support for electrophysiology labs. Boston Scientific Corporation differentiates via remote monitoring subscriptions that extend patient touchpoints beyond device implantation.
Defibrillators are emergency cardiac resuscitation devices that deliver controlled electrical shocks to restore normal heart rhythm, typically operating with energy outputs ranging from 150 to 360 joules depending on waveform configuration and patient impedance. Their primary purpose is terminating life-threatening arrhythmias including ventricular fibrillation and pulseless ventricular tachycardia in both pre-hospital and clinical settings. Implantable cardioverter-defibrillators command the deepest margin pools due to surgical placement requirements and long-term follow-up protocols, while automated external defibrillators penetrate fastest through public access mandates in airports, schools, and sports venues. Wireless connectivity technology now enables real-time transmission of event data to emergency medical services and cloud-based physician dashboards.
FDA premarket notification requirements and CE marking under the EU Medical Device Regulation govern device safety, electromagnetic compatibility, and clinical evidence standards for market access. The EU AI Act and FDA software-as-medical-device guidance are converging on algorithm-driven rhythm detection systems, reshaping validation protocols for biphasic waveform analysis. Stakeholders must monitor how cybersecurity requirements for connected defibrillators interact with hospital IT procurement criteria and liability frameworks.
Market Dynamics
Wireless connectivity mandates from FDA and CE marking authorities are forcing hardware redesigns across implantable and external defibrillator portfolios, elevating R&D costs while creating service revenue anchors through remote monitoring subscriptions.
Growth Catalysts
- Public Access Mandates:Airport, school, and sports venue deployment requirements in the United States and Germany are accelerating automated external defibrillator procurement cycles.
- Aging Demographics:Japan's super-aged population structure expands the addressable patient pool for implantable cardioverter-defibrillator procedures.
- EU MDR Compliance Windows:Device recertification deadlines under the Medical Device Regulation are compressing replacement demand into concentrated purchasing waves.
Market Restraints
- Battery Supply Concentration:Lithium manganese dioxide cell sourcing depends heavily on East Asian contract manufacturers, exposing lead times to geopolitical friction.
- Electromagnetic Interference Standards:IEC 60601-1-2 testing protocols for wireless coexistence extend product development timelines by 8-14 months.
- Capital Equipment Substitution:Wearable cardioverter-defibrillator rentals are diverting high-risk patients from permanent implant procedures in select cardiac centers.
Strategic Opportunities
- Rural India Penetration:District hospital electrification programs under the National Health Mission create first-time infrastructure for external defibrillator placement.
- AI-Enabled Rhythm Analysis:Machine learning integration with biphasic waveform detection is collapsing false-positive shock rates and expanding lay-rescuer device usability.
- Subscription Service Models:Remote monitoring platforms for implantable systems are unbundling hardware from recurring physician dashboard access fees.
Industry Challenges
- Electrophysiology Talent Scarcity:Implantable device programming and troubleshooting requires specialized cardiac electrophysiology nursing credentials that remain concentrated in tertiary academic centers.
- Cybersecurity Validation Burden:FDA premarket guidance for connected devices demands penetration testing and software bill of materials documentation that extends submission preparation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Defibrillators Market |
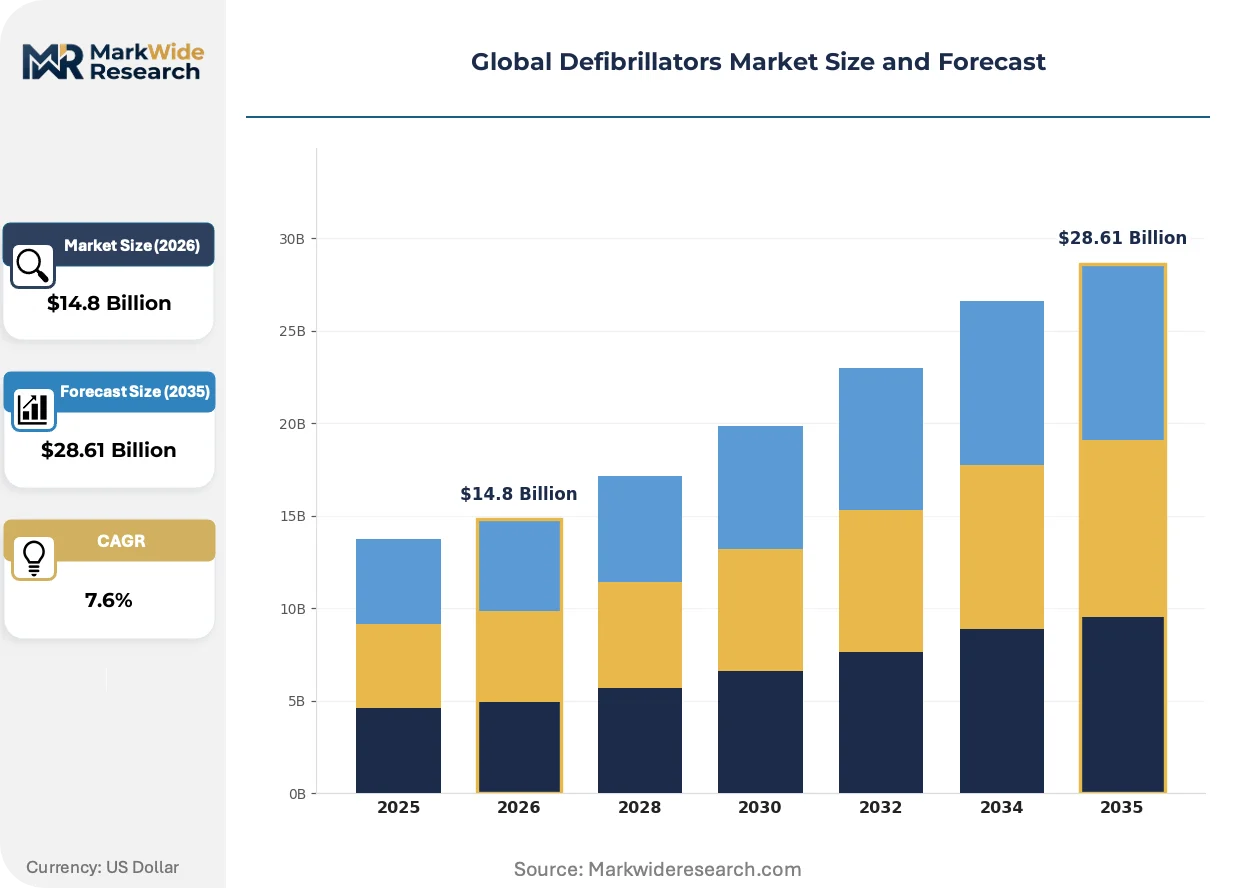
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $28.61 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Defibrillator, Automated External Defibrillator, Implantable Cardioverter-Defibrillator, Wearable Cardioverter Defibrillator End User: Hospitals, Clinics, Emergency Medical Services, Homecare Technology: Biphasic, Monophasic, CPR Feedback, Wireless Connectivity Distribution Channel: Online Retail, Direct Sales, Distributors, Others |
| Companies Covered | Medtronic, Abbott, Boston Scientific Corporation, Koninklijke Philips N.V., Stryker, Nihon Kohden Corporation, ZOLL Medical Corporation, Biotronik, MicroPort Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Defibrillators Market Emerging Trajectories
Algorithm-driven diagnostic capabilities and cloud-connected device ecosystems are redefining competitive differentiation beyond hardware specifications toward integrated care delivery platforms.
Subcutaneous implantable cardioverter-defibrillator technology is collapsing the transvenous lead placement requirement that has dominated implantable systems for three decades. Cardiac electrophysiology programs in Germany and the Netherlands are adopting these leadless architectures fastest, reducing long-term extraction complication risks while compressing the addressable market for lead repair and replacement services.
EU AI Act risk classification requirements for machine learning-enabled arrhythmia detection are forcing rhythm analysis algorithm validation protocols that exceed historical predicate device equivalence standards. Device manufacturers must now maintain post-market performance monitoring systems that feed real-world accuracy data back into notified body surveillance files, with implantable systems facing the strictest conformity assessment pathways.
Hospital procurement committees are consolidating defibrillator purchasing decisions under centralized biomedical engineering oversight rather than decentralized cardiology department authority. This shift elevates total cost of ownership metrics—including wireless infrastructure integration and cybersecurity compliance—above clinical feature differentiation in vendor selection processes, with United States health system consolidation accelerating this behavioral change fastest.
Global Defibrillators Market Segmentation
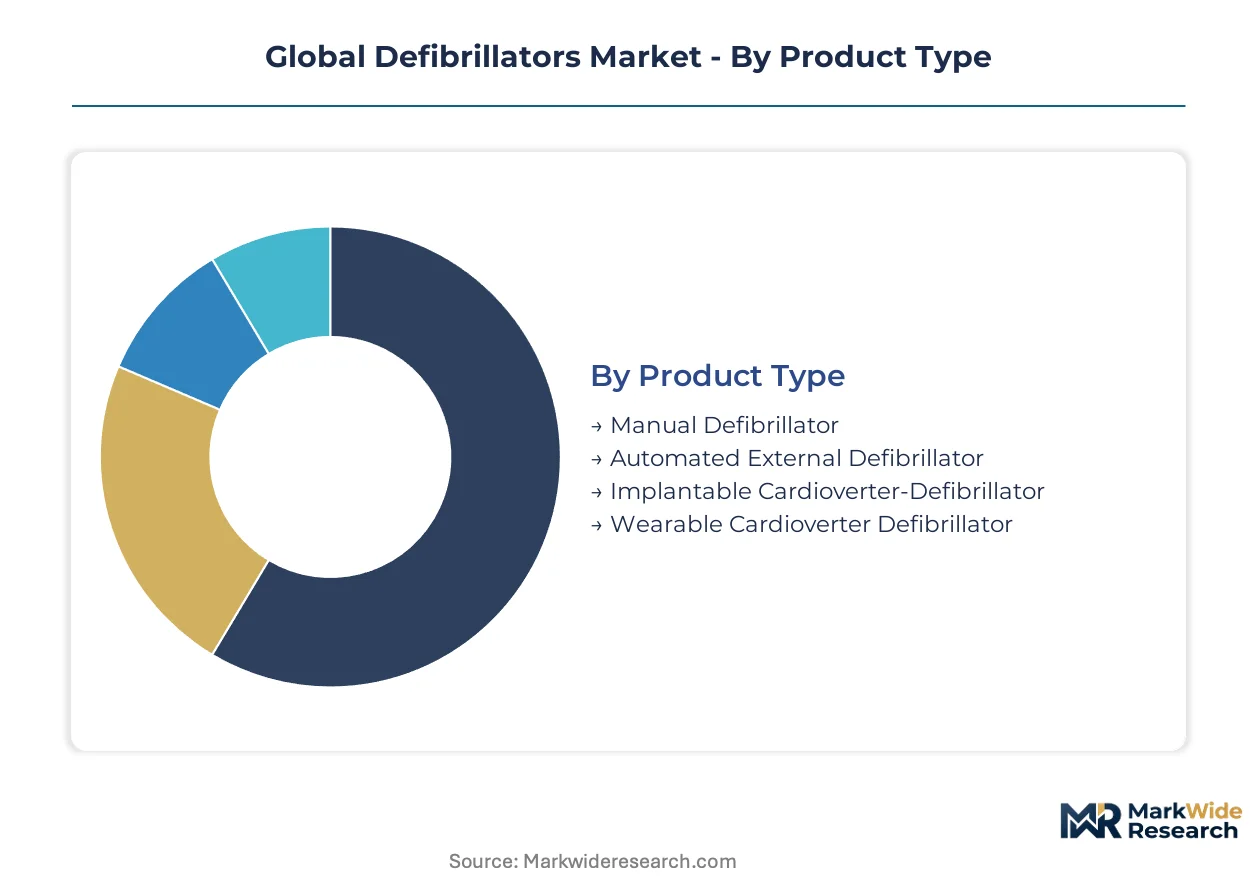
Defibrillator segmentation reveals distinct margin architectures across product categories, with implantable systems commanding premium pricing while automated external units penetrate through public access mandates. Technology differentiation and distribution channel selection determine competitive positioning more than geographic expansion alone.
Product Type:
Mature surgical implant systems coexist with emerging wearable formats, creating divergent R&D investment priorities across manufacturer portfolios.
- Manual Defibrillator:These devices require trained operator intervention for energy selection and shock delivery, typically deployed in hospital emergency departments and advanced cardiac life support teams. Demand concentrates in Germany and Japan where physician-staffed emergency response maintains strong institutional presence, constrained by training certification requirements that limit lay-rescuer adoption.
- Automated External Defibrillator:Voice-prompted systems analyze cardiac rhythm and automatically deliver shocks without operator judgment, enabling deployment in airports, schools, and sports venues across the United States. Public access mandates in California and New York accelerate procurement cycles, though battery replacement logistics create ongoing service revenue dependencies.
- Implantable Cardioverter-Defibrillator:Surgically placed devices with transvenous or subcutaneous leads provide continuous arrhythmia monitoring and automatic therapy delivery. Long-term follow-up protocols and remote monitoring subscriptions anchor recurring revenue streams.
- Wearable Cardioverter Defibrillator:External vest systems offer temporary protection for high-risk patients awaiting transplant or recovering from myocardial infarction. Rental models in select cardiac centers divert patients from permanent implant procedures.
Implantable Cardioverter-Defibrillator retains volume leadership; Wearable Cardioverter Defibrillator holds the steepest expansion curve.
End User:
Customer type segmentation maps directly to reimbursement pathways and procurement authority structures, with hospital committees consolidating purchasing decisions under biomedical engineering oversight.
- Hospitals:Tertiary cardiac centers perform implantable device procedures and maintain external defibrillator fleets across emergency departments, catheterization labs, and general wards. Centralized procurement elevates total cost of ownership metrics above clinical feature differentiation in vendor selection.
- Clinics:Outpatient cardiology practices require compact external units for diagnostic stress testing and post-implant follow-up, with space constraints favoring biphasic waveform systems. United States ambulatory surgery centers drive demand for portable manual defibrillators with CPR feedback integration.
- Emergency Medical Services:Pre-hospital response vehicles demand ruggedized automated external defibrillators with wireless transmission capabilities for real-time event data relay to receiving hospitals.
- Homecare:Post-discharge patients with wearable cardioverter defibrillators require remote monitoring infrastructure and patient education support services.
Hospitals dominate absolute unit volume; Emergency Medical Services shows the most rapid procurement acceleration.
Technology:
Waveform architecture and connectivity features now determine regulatory submission complexity more than core shock delivery functionality.
- Biphasic:Truncated exponential waveforms deliver equivalent defibrillation efficacy at lower energy levels than monophasic systems, reducing myocardial damage risk and enabling smaller device form factors. FDA premarket notifications for biphasic systems require extensive clinical evidence portfolios.
- Monophasic:Damped sinusoidal waveforms represent legacy technology with declining new product development, though installed base maintenance sustains limited replacement demand in emerging markets with constrained procurement budgets.
- CPR Feedback:Integrated accelerometers and impedance sensors provide real-time compression depth and rate guidance to rescuers, improving resuscitation quality in lay-rescuer deployments.
- Wireless Connectivity:Bluetooth and cellular-enabled devices transmit event data to emergency medical services and cloud-based physician dashboards, subject to FDA cybersecurity guidance and EU AI Act risk classification for algorithm-driven rhythm analysis.
Biphasic technology commands installed base dominance; Wireless Connectivity features gain share fastest through regulatory mandate compliance.
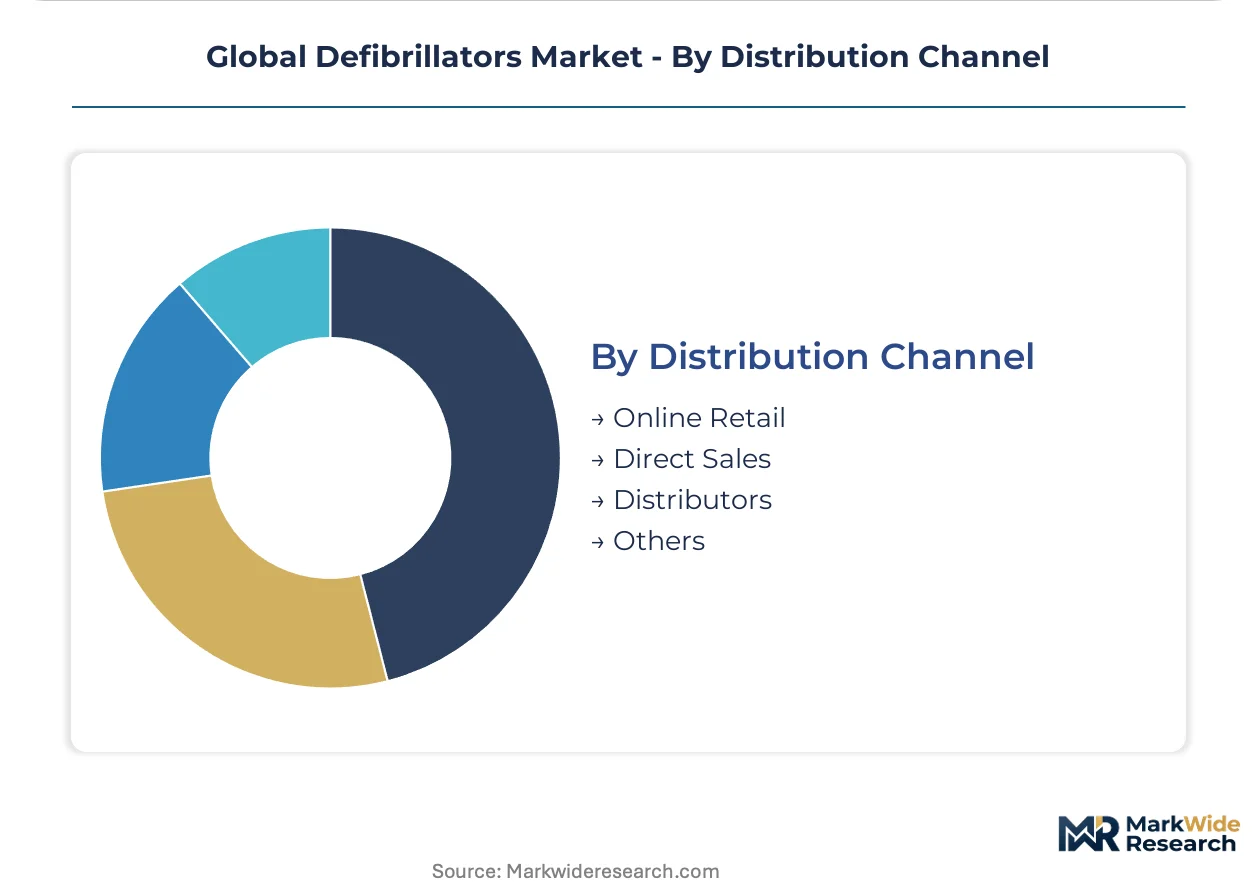
Distribution Channel:
Channel selection reflects capital equipment versus consumable purchasing patterns, with service bundling increasingly influencing route-to-market decisions.
- Direct Sales:Manufacturer field service organizations handle implantable cardioverter-defibrillator placement and long-term follow-up, capturing recurring maintenance contracts and remote monitoring subscriptions. Medtronic leverages this channel most extensively across electrophysiology labs.
- Distributors:Regional medical device distributors serve automated external defibrillator demand from schools, airports, and municipal procurement departments with localized inventory and training support.
- Online Retail:E-commerce platforms penetrate consumer-facing automated external defibrillator segments for home and small business purchase, though regulatory compliance verification creates friction.
- Others:Group purchasing organizations and hospital consortiums aggregate demand across health system networks, compressing pricing through volume commitment structures.
Direct Sales maintains revenue concentration; Online Retail climbs the fastest as consumer channel infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across procurement environments. Hospital systems in Germany and Japan absorb premium pricing for implantable systems with minimal volume sensitivity, while municipal purchasers in India and Brazil face severe budget constraints that favor basic automated external units.
United States
Public access mandates in California and New York accelerate automated external defibrillator deployment across airports, schools, and sports venues. FDA premarket notification requirements for wireless connectivity features elevate compliance costs for manufacturers. The Minneapolis-St. Paul corridor hosts concentrated electrophysiology device development activity.
Germany
Cardiac electrophysiology programs in Bavaria and North Rhine-Westphalia lead European adoption of subcutaneous implantable cardioverter-defibrillator architectures. CE marking under the EU Medical Device Regulation compresses recertification timelines into concentrated replacement waves. Berlin-based hospital procurement committees prioritize total cost of ownership metrics over clinical feature differentiation.
Japan
Super-aged demographics expand the addressable patient pool for implantable cardioverter-defibrillator procedures beyond historical saturation levels. METI reimbursement frameworks maintain premium pricing for devices with remote monitoring capabilities. The Kanto region around Tokyo concentrates cardiac device manufacturing and clinical trial infrastructure.
India
District hospital electrification programs under the National Health Mission create first-time infrastructure for external defibrillator placement in rural Maharashtra and Gujarat. CDSCO medical device regulations are converging toward international standards for electromagnetic compatibility testing. Bangalore-based biomedical engineering clusters are developing localized service networks for device maintenance.
Brazil
ANVISA regulatory pathways for automated external defibrillators remain protracted, constraining penetration despite rising cardiovascular disease prevalence. Municipal health budgets in São Paulo and Rio de Janeiro prioritize basic resuscitation equipment over connected device portfolios. Private hospital chains in the Southeast region drive demand for biphasic manual systems with CPR feedback integration.
Global Defibrillators Market Vendor Landscape
Integrated device manufacturers and specialized cardiac technology firms split the market along implantable versus external product boundaries. The competitive structure consolidates around players with established electrophysiology field service networks and regulatory submission expertise. Three archetypes dominate: diversified medical technology conglomerates with full cardiac portfolios, dedicated cardiac rhythm management specialists, and emergency care equipment manufacturers with automated external defibrillator scale. M&A activity targets remote monitoring platform capabilities, while geographic expansion concentrates on district hospital infrastructure in emerging markets.
Among diversified medical technology conglomerates, Medtronic and Abbott exemplify the integrated-service archetype through extensive field service organizations and recurring maintenance contract structures. Boston Scientific Corporation occupies a specialized position within implantable rhythm management, anchoring competitive dynamics around remote monitoring subscription models. Koninklijke Philips N.V. represents the emergency care equipment trajectory with automated external defibrillator scale and public access deployment expertise.
| Leading Market Players |
|---|
| Medtronic |
| Abbott |
| Boston Scientific Corporation |
| Koninklijke Philips N.V. |
| Stryker |
| Nihon Kohden Corporation |
| ZOLL Medical Corporation |
| Biotronik |
| MicroPort Scientific Corporation |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor channels lithium manganese dioxide cells and semiconductor components through concentrated East Asian contract manufacturers, where freight cost volatility amplifies margin pressure on automated external defibrillator producers while implantable system vendors capture pricing power through captive service networks and remote monitoring subscriptions.
Pricing Analysis
After-sales service contracts and remote monitoring subscriptions generate the majority of lifetime value in implantable cardioverter-defibrillator portfolios. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA certification tier and wireless connectivity feature depth. Cost compression in the automated external segment intensifies as municipal procurement committees in India and Brazil prioritize basic biphasic units over connected portfolios. Hospital systems in Germany and Japan exhibit minimal price sensitivity for implantable systems with METI reimbursement backing, while district health missions in rural India face severe budget constraints.
Supply Chain Analysis
Export-control restrictions on advanced semiconductors and wireless communication modules limit component flows from United States and European Union sources to Chinese contract manufacturers. Manufacturing concentration rests on China, South Korea, and Japan for lithium manganese dioxide cells, high-density capacitors, and algorithm-processing chipsets. Single-source vulnerability in battery cell supply exposes lead times to geopolitical friction. Distribution runs through manufacturer field service organizations for implantable systems and regional medical device distributors for external units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defibrillator markets are approaching a platform-economics inflection where cloud-connected device ecosystems and AI-enabled rhythm analysis algorithms are displacing hardware-centric competition, with interoperability standards for emergency medical services data transmission reshaping vendor lock-in dynamics.
For Market Incumbents: Insulate implantable system margins by deepening backward integration into leadless subcutaneous architectures and securing electrophysiology nursing talent pipelines against scarcity. Consolidate field service network density in Germany and Japan where METI and EU MDR compliance windows compress replacement cycles. Defend against wearable cardioverter-defibrillator rental substitution by bundling remote monitoring subscriptions with surgical placement protocols.
For New Entrants and Emerging Players: Rural Maharashtra and Gujarat district hospitals under India's National Health Mission electrification programs offer first-mover infrastructure for basic automated external defibrillator placement. Target municipal procurement departments in São Paulo with biphasic manual systems featuring CPR feedback integration, bypassing ANVISA protracted pathways for connected devices. Partner with Bangalore biomedical engineering clusters for localized maintenance networks.
For Investors and Strategic Acquirers: EU AI Act risk classification for machine learning-enabled arrhythmia detection reshapes the acquisition landscape toward algorithm validation capabilities and post-market surveillance infrastructure. Long-term viability centers on platforms with recurring physician dashboard revenue rather than transactional hardware sales. Monitor CDSCO electromagnetic compatibility convergence as signal for Indian market formalization.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR recertification deadlines compress replacement demand into concentrated purchasing waves across German hospital systems. |
| Hospital System Partnership | Centralized biomedical engineering procurement in United States health networks elevates total cost of ownership metrics above clinical differentiation. |
| Software Companion Development | AI-enabled rhythm analysis algorithms reduce false-positive shock rates and expand lay-rescuer device usability for public access mandates. |
| Reimbursement Strategy | METI frameworks in Japan maintain premium pricing for implantable systems with remote monitoring capabilities beyond demographic saturation. |
| FDA Submission | Premarket notification requirements for wireless connectivity features elevate compliance costs and extend submission preparation cycles. |
Methodological Framework
A spread of perspectives from cardiac electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers converged on the working assumptions underlying demand modeling. Primary interviews with device manufacturers and emergency medical services operators combined with secondary validation against FDA 510(k) filings, CE marking databases under EU MDR, CMS Medicare reimbursement schedules, and hospital procurement contract repositories. Bottom-up unit economics triangulated against top-down epidemiological projections for sudden cardiac arrest incidence.
Demand-supply balance dynamics across the analysis window incorporated patient pool expansion from aging demographics, public access mandate compliance waves, and EU MDR recertification deadlines. Segmentation dimensions spanned product type, end user category, waveform technology, wireless connectivity feature depth, and regional regulatory cluster. CAGRs derived from logistic diffusion modeling of implantable procedure penetration and replacement cycle compression. Forecast inputs included electrophysiology lab capacity constraints and battery supply lead time volatility.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure growth rates, lithium commodity pricing, and transoceanic freight costs would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline adherence and reimbursement stability. Material shifts in FDA cybersecurity guidance stringency or EU AI Act enforcement posture would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spain Contraceptive Devices Market
Medical Devices
Japan Medical Device Regulatory Affairs Market
Medical Devices
Breast Prosthesis Market
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
Medical Device Regulatory Affairs Market
Medical Devices
Bone Anchored Hearing Aids Market
Medical Devices
Snare Devices Market
Medical Devices
Neurovascular Stent Market
Medical Devices
Europe Organ-On-Chip Market
Medical Devices
Europe Electroencephalography Devices Market
Medical Devices
Spinal Fusion Bone Graft Substitutes Market
Medical Devices
External Pacemakers Market
Medical Devices
ECG Patch and Holter Monitor Market
Medical Devices
Global Portable Ultrasound Equipment Market
Medical Devices
Smart Patches Market
Medical Devices
Global Blood Transfusion Devices Market