
 UK Cyber (Liability) Insurance Market | 2026-2036
UK Cyber (Liability) Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
UK Cyber (Liability) Insurance Market Analytics
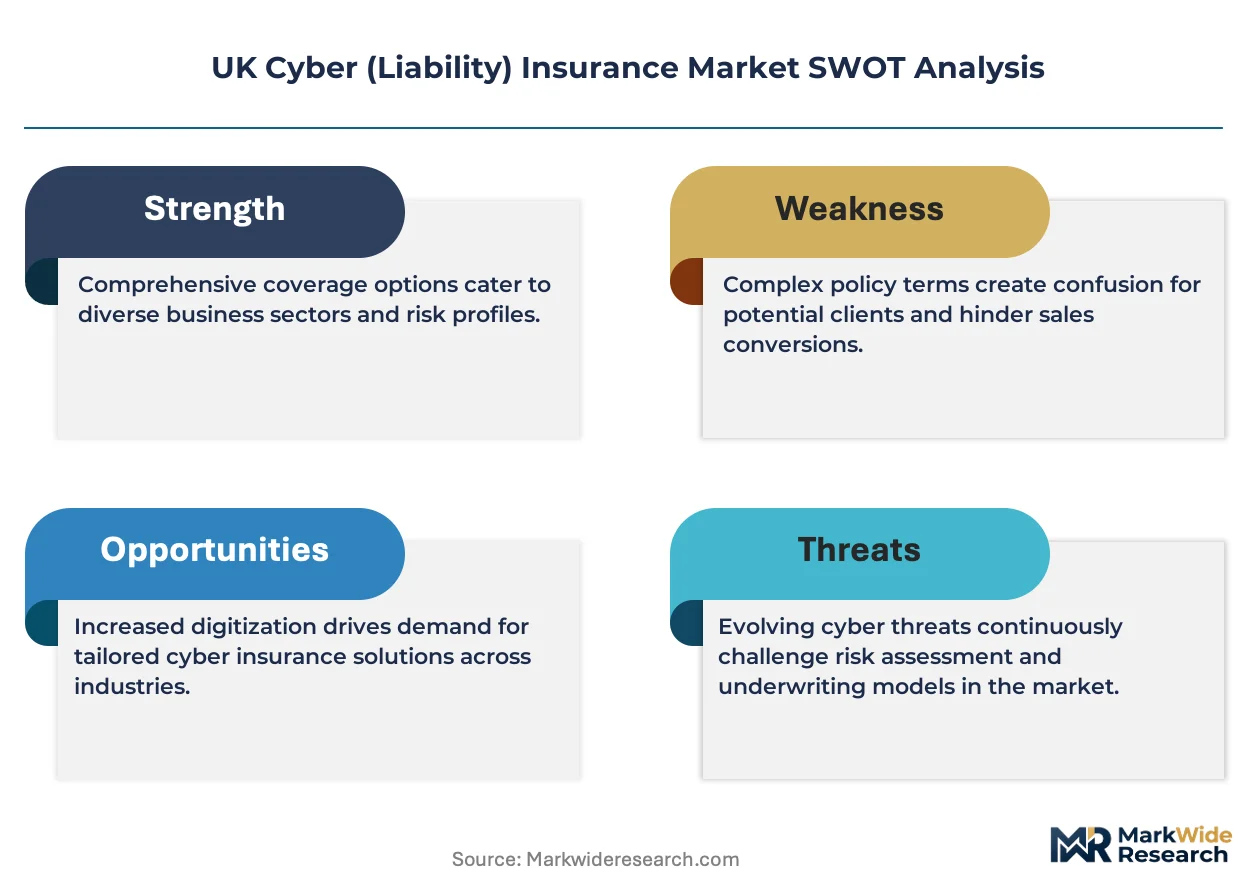
Asset-light syndication through Lloyd's of London is narrowing the capital barrier for specialist cyber underwriters. Beazley Group plc leverages its technology and cyber underwriting expertise to sustain premium pricing power in complex risk layers. Hiscox Ltd anchors its competitive position through direct-to-SME distribution that controls acquisition costs and policy customization.
Cyber liability insurance indemnifies policyholders against financial losses stemming from data breaches, network security failures, and privacy violations, typically covering legal defense costs, regulatory fines, forensic investigation expenses, and business interruption losses. The coverage triggers on unauthorized access events, malware deployment, or denial-of-service attacks that compromise confidentiality, integrity, or availability of digital assets. First-party coverage dominates premium pools as organizations prioritize direct loss recovery from ransomware and operational disruption over third-party liability transfer. Medium enterprises represent the fastest-growing business size segment as these firms cross regulatory thresholds without matching enterprise-grade security infrastructure.
The Prudential Regulation Authority and the Financial Conduct Authority jointly supervise insurer solvency and policy conduct standards, while the UK Cyber Essentials certification scheme shapes minimum security controls that carriers mandate for premium eligibility. The National Cyber Security Centre publishes threat intelligence that informs underwriting models and exclusion drafting. Stakeholders must monitor how the UK transposes evolving EU cybersecurity directives into domestic law without disrupting cross-border policy consistency.
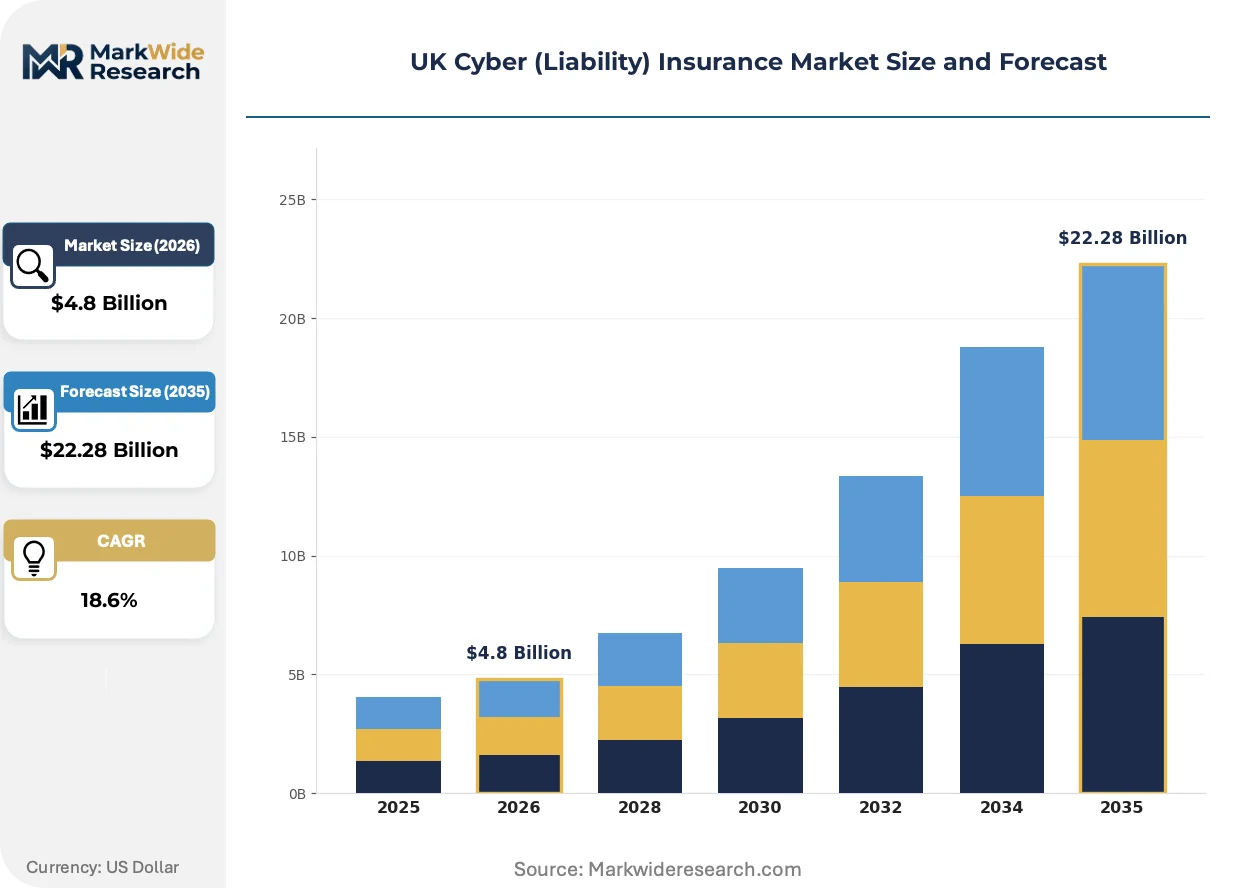
Market Dynamics
Ransomware frequency is compressing policy renewal cycles and forcing carriers to reprice risk layers mid-term, while the UK government's Cyber Essentials mandate tightens underwriting standards across SME portfolios.
Growth Catalysts
- NIS2 transposition:The Product Security and Telecommunications Infrastructure Act imposes baseline security obligations on critical infrastructure operators, expanding mandatory coverage pools for cyber liability policies.
- Financial services:Banks and asset managers face escalating regulatory scrutiny from the Prudential Regulation Authority, driving bulk purchases of standalone cyber policies beyond packaged endorsements.
- Mid-market concentration:London and South East enterprises without dedicated security teams represent an underserved risk pool seeking affordable first-party coverage.
Market Restraints
- Capacity concentration:Lloyd's of London syndicates control disproportionate specialist cyber underwriting capacity, creating supply bottlenecks during peak demand periods.
- Loss cost volatility:Ransomware payment trends and forensic investigation expenses exhibit unpredictable spikes that distort actuarial modeling.
- Retrocession pressure:Reinsurance markets have tightened terms for cyber catastrophe layers, pushing primary carriers to retain more risk.
Strategic Opportunities
- Regional expansion:Northern England and Scotland host manufacturing and logistics clusters with minimal cyber penetration but rising threat exposure.
- Parametric triggers:Index-based policies tied to National Cyber Security Centre threat level indicators could streamline claims settlement for business interruption.
- Embedded distribution:Cyber coverage bundled through managed service providers and cloud platforms reaches buyers outside traditional broker channels.
Industry Challenges
- Actuarial talent scarcity:Underwriters with combined cyber risk and insurance pricing expertise command premiums that strain mid-tier carrier budgets.
- Legacy system integration:Incumbent insurers struggle to embed real-time threat telemetry into decades-old policy administration platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Cyber (Liability) Insurance Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: First-Party Coverage, Third-Party Coverage, Data Breach Coverage, Business Interruption Coverage Industry Vertical: Financial Services, Healthcare, Retail, Technology Business Size: Small Enterprises, Medium Enterprises, Large Enterprises, Startups Risk Assessment Method: Self-Assessment, External Audit, Third-Party Consultation, Automated Risk Analysis |
| Companies Covered | AIG UK Limited, Hiscox Ltd, Beazley Group plc, Allianz Insurance plc, AXA Insurance UK plc, Chubb European Group Limited, Lloyd's of London, QBE Insurance Group Limited, Zurich Insurance plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Cyber (Liability) Insurance Market Evolving Landscape
Artificial intelligence is reconstructing underwriting workflows from static questionnaires to continuous risk monitoring, compressing the gap between threat emergence and policy response.
Security orchestration platforms are virtualizing the traditional broker-carrier relationship by feeding live vulnerability scan data directly into pricing engines. Mid-market enterprises in Manchester and Birmingham adopt these tools fastest as they seek Cyber Essentials certification. The technology is virtualizing how underwriters assess risk continuity rather than relying on annual application snapshots.
The UK Cyber Essentials scheme now mandates multi-factor authentication and patch management protocols that carriers incorporate as binding coverage conditions. Non-compliant policyholders face automatic exclusion triggers for ransomware claims. Financial services firms in the Square Mile invest most heavily in certification maintenance to preserve premium eligibility.
Buyers increasingly unbundle cyber coverage from packaged commercial policies to secure standalone terms with dedicated claims teams. This behavior concentrates premium volume with specialist underwriters who maintain 24/7 incident response capabilities. The shift is most pronounced among professional services firms in London seeking forensic investigation services bundled with indemnity.
UK Cyber (Liability) Insurance Market Segmentation
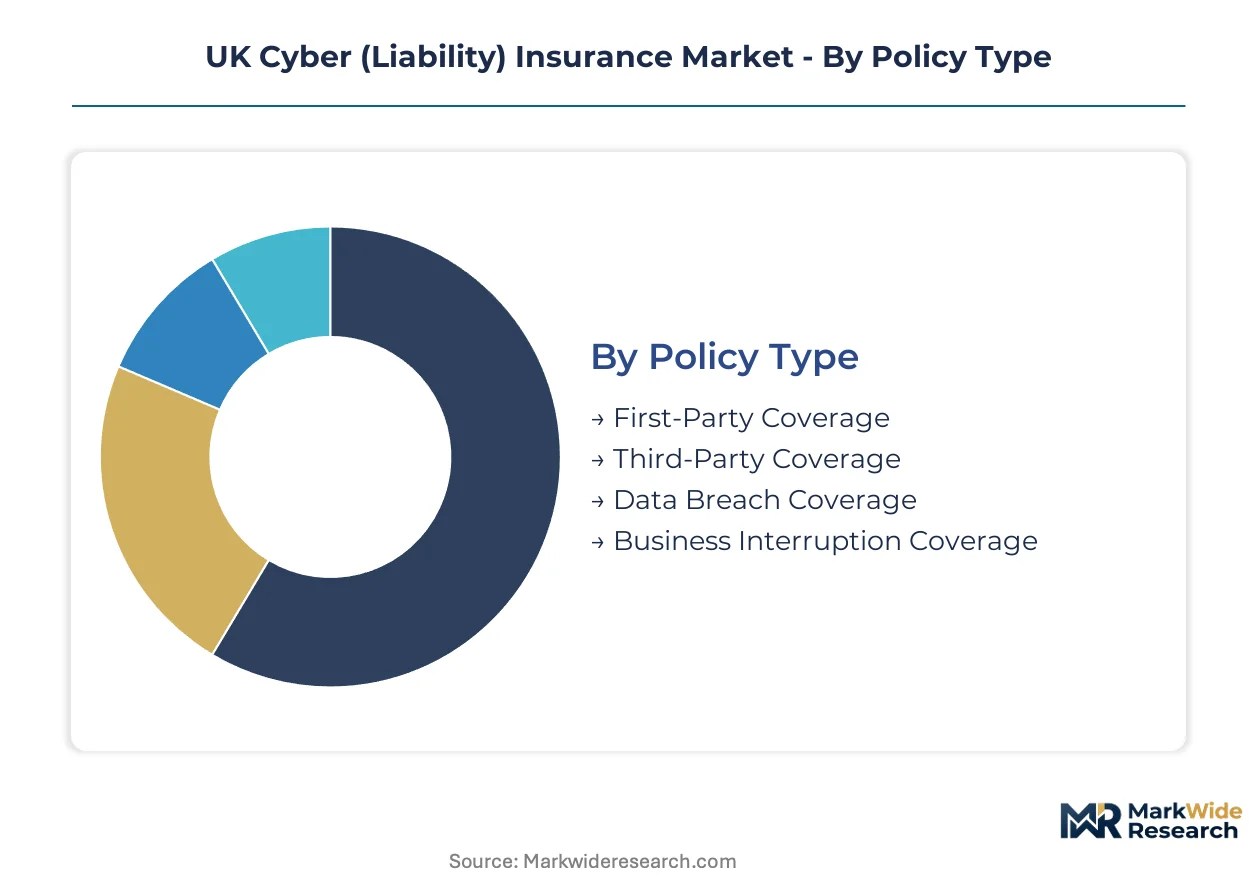
Cyber liability policies require continuous post-sale risk engineering and incident response coordination. Insurers structure coverage tiers around the intensity of these ongoing services rather than static policy limits alone.
Policy Type:
After-sales service intensity peaks with first-party coverage, where carriers deploy 24/7 incident response teams and forensic investigators.
- First-Party Coverage:Indemnifies direct losses from ransomware, operational disruption, and data restoration. Demand concentrates among mid-market enterprises in London seeking bundled incident response services alongside indemnity. The Lloyd's market dominates placement for complex first-party layers requiring dedicated claims teams.
- Third-Party Coverage:Transfers liability to policyholders for privacy breaches affecting customers, suppliers, or partners. Financial services firms in the Square Mile purchase standalone third-party policies to satisfy Prudential Regulation Authority conduct standards. Regulatory scrutiny from the Financial Conduct Authority is compressing renewal cycles for this segment.
- Data Breach Coverage:Funds notification costs, credit monitoring, and regulatory fines following unauthorized data access. Healthcare providers in the NHS supply chain prioritize this coverage amid patient record digitization.
- Business Interruption Coverage:Replaces revenue lost during system downtime from cyber events. Manufacturing clusters in Northern England are expanding purchases as operational technology networks converge with IT infrastructure.
By volume, First-Party Coverage leads. By growth pace, Business Interruption Coverage is ahead.
Industry Vertical:
Cost tier stratification separates financial services—where premiums absorb specialized breach counsel—from retail, where standardized coverage dominates.
- Financial Services:Banks, asset managers, and insurers face the highest premium tiers due to regulatory capital requirements and systemic risk exposure. The Prudential Regulation Authority mandates standalone cyber policies beyond packaged endorsements for systemically important institutions.
- Healthcare:NHS trusts and private providers purchase coverage for patient data breaches and medical device compromise. Regulatory pressure from the UK Information Commissioner's Office is accelerating adoption among regional hospital networks.
- Retail:E-commerce platforms and brick-and-mortar chains seek affordable first-party coverage for payment card breaches. Mid-market retailers in the South East represent an underserved risk pool with minimal security infrastructure.
- Technology:Software vendors and cloud service providers require errors-and-omissions extensions alongside cyber liability. Firms in Cambridge and Manchester technology clusters are expanding coverage for supply chain liability.
Financial Services commands premium pricing. Technology verticals are expanding most quickly as SaaS providers face downstream liability exposure.
Business Size:
Customer type determines whether underwriters apply standardized questionnaires or bespoke risk engineering.
- Medium Enterprises:Organizations with 50-250 employees lack dedicated security teams but face sophisticated threat exposure. Firms in London and the South East represent the fastest-expanding segment as they cross regulatory thresholds without enterprise-grade infrastructure.
- Large Enterprises:Multinationals and critical infrastructure operators purchase layered programs across multiple carriers. Lloyd's syndicates compete for lead positions on complex risks requiring international jurisdiction coordination.
- Small Enterprises:Micro-businesses and professional services firms seek Cyber Essentials-certified coverage through direct distribution. Hiscox Ltd anchors this segment with controlled acquisition costs and policy customization tools.
- Startups:Venture-backed technology firms prioritize founder-friendly coverage with minimal exclusion triggers. Embedded distribution through venture capital platforms is reaching buyers outside traditional broker channels.
Medium Enterprises generate the steepest expansion trajectory. Large Enterprises retain the largest premium pool by absolute value.
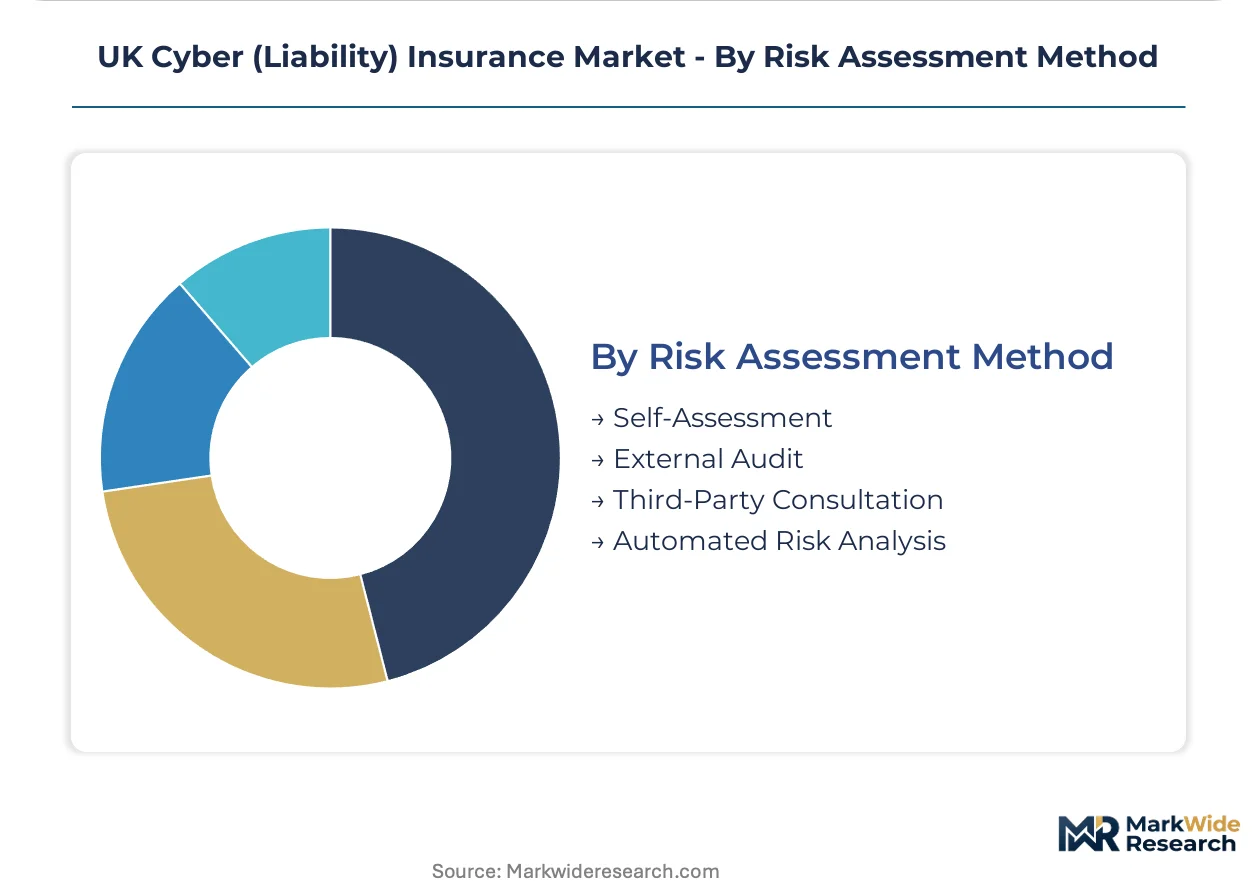
Risk Assessment Method:
Supply concentration among automated platforms is displacing traditional broker-collected questionnaires in mid-market placements.
- Automated Risk Analysis:Security orchestration platforms feed live vulnerability scan data directly into pricing engines. Manchester and Birmingham enterprises adopt these tools fastest as they seek Cyber Essentials certification.
- External Audit:Independent cybersecurity firms assess controls for large enterprise placements. Financial services firms in London invest most heavily in audit maintenance to preserve premium eligibility.
- Third-Party Consultation:Specialist brokers engage cybersecurity advisors to structure complex multi-carrier programs. Lloyd's managing agents rely on this method for catastrophe-layer placements.
- Self-Assessment:Standardized questionnaires remain common for small enterprise direct distribution. Non-compliant policyholders face automatic exclusion triggers for ransomware claims under this method.
Automated Risk Analysis is gaining share fastest. External Audit retains the highest premium attachment per policy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK cyber insurance market exhibits minimal cross-border trade in coverage itself, though London's Lloyd's market exports underwriting expertise and reinsurance capacity to international programmes. Domestic demand concentrates in financial and professional services clusters where regulatory pressure intersects with high-value data assets.
London and South East
Financial services firms in the Square Mile drive premium volume through standalone policy purchases mandated by the Prudential Regulation Authority. The UK Cyber Essentials scheme shapes minimum security controls that carriers require for premium eligibility. Mid-market professional services firms in Canary Wharf and the South East technology corridor represent the fastest-expanding buyer segment as they cross regulatory thresholds without enterprise-grade security infrastructure.
Midlands
Manufacturing and logistics enterprises in Birmingham and Manchester are accelerating cyber coverage adoption as operational technology networks converge with IT systems. The National Cyber Security Centre publishes threat intelligence that informs regional underwriting models and exclusion drafting. Security orchestration platforms feeding live vulnerability data into pricing engines see fastest uptake among Midlands enterprises seeking Cyber Essentials certification.
North England
Healthcare providers in the NHS supply chain prioritize data breach coverage amid patient record digitization and regulatory pressure from the UK Information Commissioner's Office. Regional hospital networks in Leeds and Newcastle are expanding purchases beyond basic indemnity to include forensic investigation services. The Product Security and Telecommunications Infrastructure Act imposes baseline security obligations that expand mandatory coverage pools for critical infrastructure operators.
Scotland
Financial services subsidiaries in Edinburgh and Glasgow purchase layered cyber programmes to satisfy group-level risk management standards. The Scottish Government's cyber resilience strategy aligns with UK-wide certification requirements, creating consistent underwriting standards across borders. Technology firms in Glasgow's emerging fintech cluster seek founder-friendly coverage with minimal exclusion triggers through embedded distribution channels.
Wales
Public sector bodies and small enterprises in Cardiff pursue affordable first-party coverage through direct distribution channels. The Welsh Government's digital infrastructure investments are raising baseline security awareness among regional businesses. Manufacturing clusters in South Wales are expanding business interruption coverage purchases as they modernize operational technology systems.
UK Cyber (Liability) Insurance Market Competitive Landscape
On the supply side, the industry is tiered between Lloyd's syndicate specialists with catastrophe-layer capacity and direct-distributed SME carriers with controlled acquisition costs. The market structure separates complex international risks requiring multi-jurisdictional coordination from standardized domestic coverage. Three archetypes dominate: syndicate specialists leveraging Lloyd's capital flexibility, direct-to-SME distributors with technology-enabled underwriting, and global commercial carriers with bundled enterprise programmes. Competitive moves concentrate on portfolio diversification into adjacent cyber services and strategic partnerships with security orchestration platforms.
Within the syndicate specialist tier, Beazley Group plc and Lloyd's of London occupy positions defined by capital-light syndication and complex risk-layer expertise. Hiscox Ltd anchors the direct-distributed SME segment with policy customization tools that control acquisition costs. These three entities exemplify how market positioning stratifies between international catastrophe capacity and domestic mid-market penetration.
| Leading Market Players |
|---|
| AIG UK Limited |
| Hiscox Ltd |
| Beazley Group plc |
| Allianz Insurance plc |
| AXA Insurance UK plc |
| Chubb European Group Limited |
| Lloyd's of London |
| QBE Insurance Group Limited |
| Zurich Insurance plc |
| Others |
Value Network & Pricing Analysis
The Thames-Corridor logistics spine channels Lloyd's syndicate capacity into London's financial district with freight-cost dynamics that concentrate underwriting power among catastrophe-layer specialists while forcing price differentiation across SME and enterprise tiers.
Pricing Analysis
Industrial OEM buyers anchor premium-mid-economy pricing differentiation across the UK cyber market. Pricing stratifies across first-party indemnity tiers, standalone third-party liability, and bundled incident-response packages based on Cyber Essentials certification grade and forensic service intensity. Cost compression in mid-market SME tiers is intensifying because automated risk-scoring platforms displace broker-collected questionnaires. Micro-businesses and professional services firms exhibit highest price sensitivity, while financial services institutions in the Square Mile absorb specialized breach-counsel premiums with minimal elasticity.
Supply Chain Analysis
Extended payment terms from Lloyd's managing agents to security orchestration platform vendors are restructuring working-capital flows across the underwriting value chain. Capacity draws from London, Bermuda, and Dublin reinsurance hubs, with forensic investigation services and threat-intelligence feeds as critical component inputs. Single-source vulnerability in 24/7 incident-response teams creates exposure when ransomware waves exceed specialist staffing capacity. Distribution runs through Lloyd's broker networks for complex international risks and direct digital channels for standardized SME coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK cyber insurance market represents a high-growth disruption as artificial intelligence reconstructs underwriting from annual questionnaires to continuous risk monitoring, compressing the threat-to-policy-response cycle.
For Market Incumbents: Harden competitive moats by embedding real-time threat telemetry into legacy policy administration platforms and securing exclusive partnerships with security orchestration vendors. Ransomware loss-cost volatility threatens capital adequacy; catastrophe-layer retrocession terms demand tighter risk retention discipline. For New Entrants and Emerging Players: Build out automated risk-analysis capabilities targeting Manchester and Birmingham manufacturing clusters where operational technology convergence outpaces incumbent coverage penetration. Embedded distribution through managed service providers offers the most penetrable go-to-market angle outside saturated Lloyd's broker channels. For Investors and Strategic Acquirers: Carve-out targets emerge from global commercial carriers seeking to divest non-core cyber portfolios amid actuarial talent scarcity and legacy system integration burdens. Long-term viability hinges on underwriting teams with combined cyber risk and insurance pricing expertise; monitor NIS2 transposition implementation as the signal for regulatory-driven coverage mandate expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Security orchestration platforms feeding live vulnerability data into Lloyd's pricing engines compress risk-assessment cycles. |
| Geographic Expansion | Northern England and Scotland manufacturing clusters offer underserved risk pools with rising operational technology exposure. |
| Strategic Partnership | Alliances with Cyber Essentials certification bodies create policy-eligibility gatekeeping and captive distribution channels. |
| Acquisition of Specialist Firm | Forensic investigation boutiques provide 24/7 incident-response capabilities that differentiate standalone policy offerings. |
| Product Launch | Parametric triggers tied to National Cyber Security Centre threat levels streamline business-interruption claims settlement. |
Research Methodology
The analysis maps first-party coverage, third-party liability, data breach, and business interruption policy types, each validated through underwriters at Lloyd's syndicates, broker placement specialists, security orchestration platform engineers, and mid-market enterprise risk managers. Primary interviews with these stakeholders combined secondary validation through Prudential Regulation Authority solvency disclosures, Financial Conduct Authority policy conduct filings, National Cyber Security Centre threat intelligence publications, and Cyber Essentials certification databases. Bottom-up premium volume estimates triangulated against top-down market sizing from regulatory mandate expansion trajectories.
Assumptions held fixed include NIS2 transposition timing through the Product Security and Telecommunications Infrastructure Act, ransomware frequency trends, and Lloyd's catastrophe-layer capacity availability across the projection horizon. Segmentation dimensions modeled encompass policy type, industry vertical, business size, and risk assessment method complexity. CAGRs derived from regulatory mandate-driven coverage pool expansion and threat-escalation-driven premium repricing, with inputs from forensic investigation cost inflation and retrocession market tightening.
Stress conditions across ransomware payment trends, reinsurance capacity contraction, and Cyber Essentials compliance enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Bancassurance in ASEAN Market
Insurance
Self Funded Insurance Market
Insurance
Social Media Analytics-Based Insurance Market
Insurance
Logistics Insurance Market
Insurance
Telematics-Based Auto Insurance Market
Insurance
Aviation Insurance Market
Insurance
Insurance Big Data Analytics Market
Insurance
Term Insurance Market
Insurance
Intellectual Property Liability Insurance Market
Insurance
Peer to Peer Insurance Market
Insurance
Horse Insurance Market
Insurance
Cancer Insurance Market
Insurance
Medical Claims Processing Services Market
Insurance
UK Electronic Gadgets Insurance Market
Insurance
Liability Insurance Market
Insurance
Gap Insurance Market