
 Gap Insurance Market | 2026-2036
Gap Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Gap Insurance Market Analysis
Market Context
Telematics-driven underwriting is decoupling gap insurance from traditional loan origination economics. Progressive leverages real-time vehicle depreciation data to price policies dynamically. State Farm anchors its gap offerings through captive agency distribution networks. Allstate differentiates by bundling gap coverage with its proprietary new-car replacement products.
Technical Definition and Segment Structure
Gap insurance is a financial indemnity product that covers the difference between an asset's outstanding loan balance and its actual cash value at the time of total loss, typically triggered when depreciation outpaces principal amortization. The product protects lenders and borrowers against collateral shortfalls in secured auto financing. Vehicle gap insurance dominates premium volume, while commercial gap insurance represents the fastest-expanding margin pool as fleet operators seek balance-sheet protection against accelerated commercial vehicle depreciation. Online platforms are displacing direct sales as the primary distribution channel, though insurance brokers retain pricing power in complex commercial fleet transactions.
Regulatory Environment and Outlook
The US Consumer Financial Protection Bureau enforces Truth in Lending Act disclosures for gap insurance sold at point of sale, while state insurance commissioners regulate rate adequacy and producer licensing. The National Association of Insurance Commissioners has advanced model legislation addressing gap product suitability and refund calculations. Stakeholders must monitor evolving state-level restrictions on dealership markup practices and the integration of gap coverage into digital retail platforms.
Market Dynamics
Telematics integration is compressing underwriting cycles from annual to real-time, forcing carriers to rebuild actuarial infrastructure around streaming depreciation feeds rather than static loan schedules.
Growth Catalysts
- Negative Equity Structuration:US auto loan-to-value ratios above 100% at origination create persistent collateral shortfall exposure that gap products are designed to absorb.
- CFPB Disclosure Mandates:Enhanced Truth in Lending Act requirements for add-on product transparency are professionalizing dealership sales practices and reducing post-sale cancellation rates.
- Commercial Fleet Digitization:Fleet management platforms embedding gap coverage into total cost of ownership calculators are accelerating B2B adoption among logistics operators.
Market Restraints
- Used Vehicle Price Volatility:Wholesale auction index swings of 20-30% annually distort loss reserve adequacy and compress carrier margins during depreciation spikes.
- Dealership Markup Compression:State-level restrictions on add-on product pricing flexibility in California and New York limit distribution economics for front-end gap sales.
- Direct-to-Consumer Substitution:Lender-placed insurance products offered by captive finance arms at point of origination displace standalone gap policy purchases.
Strategic Opportunities
- Embedded Insurance APIs:Integration of gap coverage into digital auto retail platforms like Carvana and Vroom enables checkout-embedded policy issuance without dealership intermediation.
- Electric Vehicle Depreciation Uncertainty:Battery residual value opacity in EVs creates demand for enhanced gap products covering powertrain-specific value collapse scenarios.
- Subscription Mobility Models:Vehicle-as-a-service fleet operators require gap structures adapted to mileage-based depreciation curves rather than time-based amortization schedules.
Industry Challenges
- Telematics Talent Scarcity:Underwriting teams lack sufficient data science capacity to operationalize real-time vehicle valuation streams into pricing engines.
- Legacy System Integration:Core policy administration platforms require expensive middleware development to connect with IoT-enabled depreciation data feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gap Insurance Market |
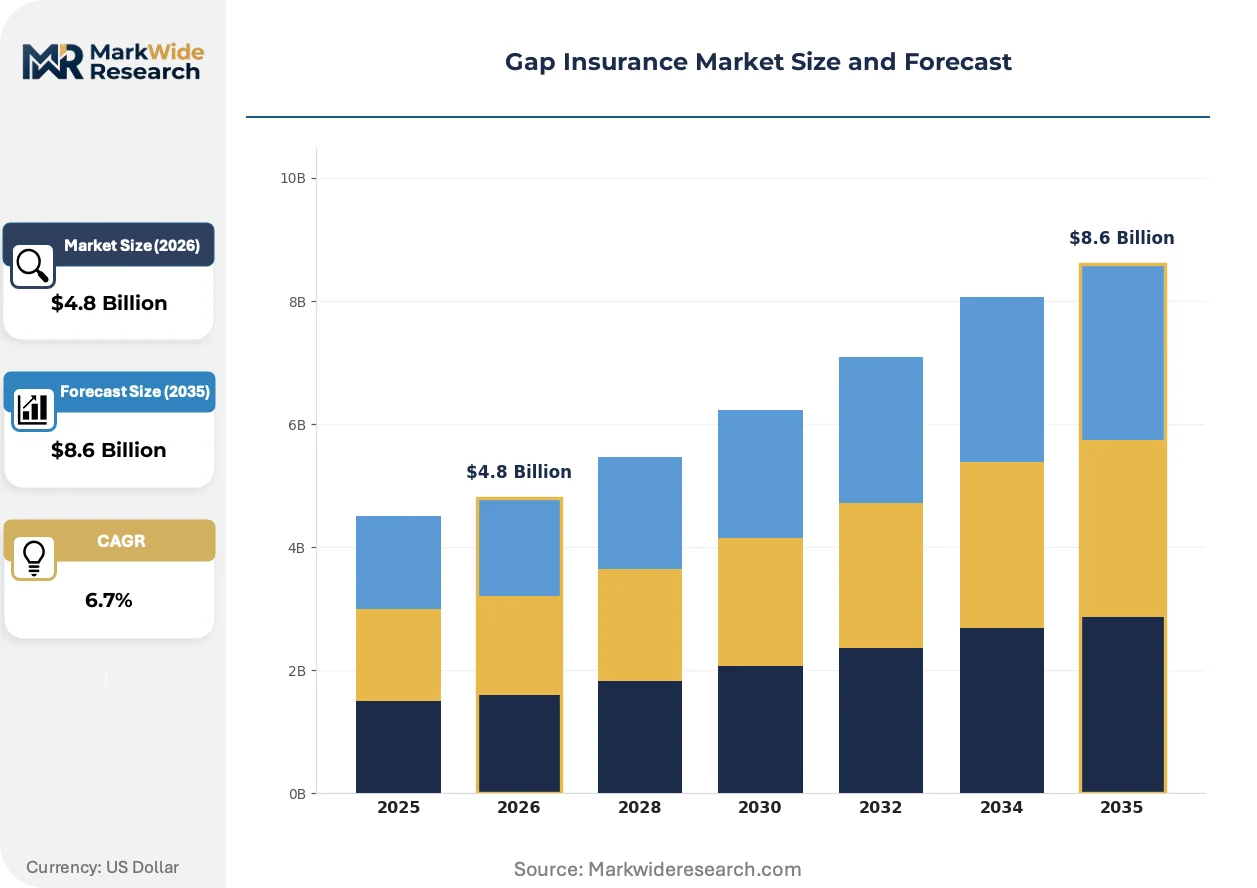
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loan Gap Insurance, Vehicle Gap Insurance, Lease Gap Insurance, Commercial Gap Insurance Distribution Channel: Direct Sales, Insurance Brokers, Online Platforms, Banks Customer Type: Individual Consumers, Auto Dealerships, Commercial Fleets, Financial Institutions Coverage Type: New Vehicles, Used Vehicles, Rental Vehicles, Others |
| Companies Covered | Nationwide, American Family, Progressive, Amica Mutual, Erie Insurance, State Farm, Allstate, Travelers, Liberty Mutual, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gap Insurance Market Emerging Trajectories
Real-time data infrastructure is displacing static actuarial tables as the foundation of gap insurance pricing, compressing the gap between loss occurrence and reserve recognition.
Connected vehicle telematics is automating the detection of total loss events and triggering immediate claims settlement workflows. Auto lenders with embedded sensor partnerships are adopting this capability fastest, reducing claims cycle times from weeks to hours. This compression is eliminating the traditional float period that carriers relied upon for investment income.
The US Consumer Financial Protection Bureau's 2022 add-on product consent order framework is mandating standalone disclosure documents and cooling-off periods for dealership-sold gap coverage. This regulatory friction is pushing volume toward direct digital channels where compliance automation is simpler. Subprime auto lenders are responding by pre-qualifying gap products outside the dealership environment.
Fleet procurement departments are unbundling gap coverage from bundled fleet management contracts and negotiating standalone policies through insurance brokers. Large logistics operators with centralized risk management functions are driving this shift, seeking transparency into premium allocation across vehicle classes. This behavior is most visible among North American last-mile delivery contractors with electric vehicle transition mandates.
Gap Insurance Market Segmentation
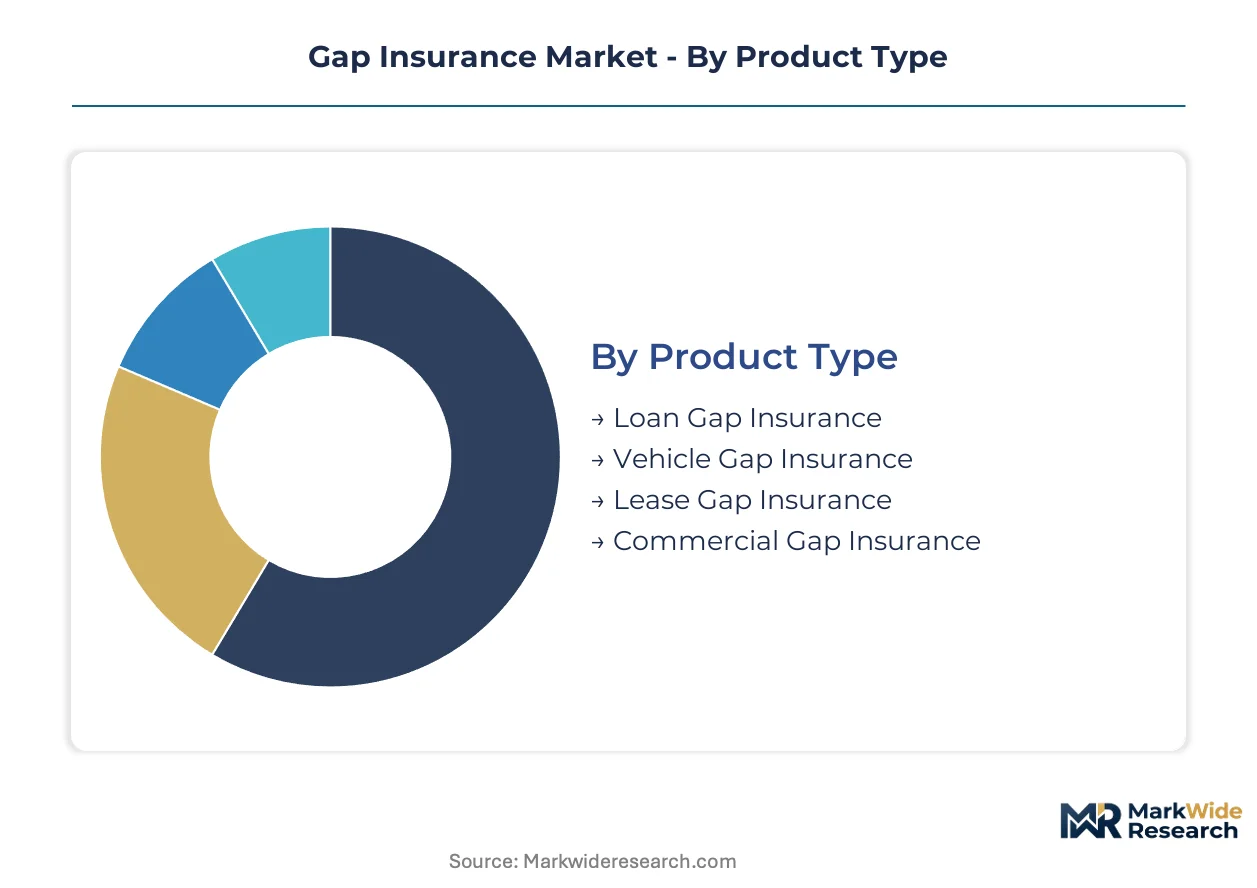
Gap insurance pricing and distribution economics vary sharply across product structures, purchase contexts, and buyer sophistication. Segmentation reveals where carrier margins concentrate and where digital disruption is displacing traditional intermediation.
Product Type:
Buyer risk exposure and policy duration differentiate demand across product categories, with collateral type and depreciation velocity driving coverage design.
- Vehicle Gap Insurance:Covers the differential between auto loan balances and actual cash value for total loss events. Demand concentrates in the United States among new car buyers at franchised dealerships, where negative equity rates on auto loans remain structurally elevated and lenders mandate coverage for high-LTV originations.
- Commercial Gap Insurance:Protects fleet operators against accelerated depreciation on commercial vehicles and specialized equipment. Logistics contractors in North America with electric vehicle transition mandates are driving fastest expansion as battery residual value uncertainty creates balance-sheet protection needs.
- Loan Gap Insurance:Tied specifically to secured financing arrangements rather than asset classes. Credit unions and regional banks embed this coverage into auto loan originations as a loss-mitigation tool.
- Lease Gap Insurance:Addresses end-of-lease residual value shortfalls when vehicles are totaled. Lessors require this coverage for lessees with minimal down payments or extended mileage allowances.
Vehicle Gap Insurance leads volumes today; Commercial Gap Insurance is gaining share fastest.
Distribution Channel:
Channel economics hinge on regulatory friction, with compliance automation favoring digital pathways over dealership-dependent sales.
- Online Platforms:Digital auto retail platforms enable checkout-embedded policy issuance without intermediation. Carvana and Vroom integrate gap coverage into their purchase workflows, capturing consumers who research financing independently before visiting dealerships.
- Insurance Brokers:Retain pricing power in complex commercial fleet transactions where coverage must align with heterogeneous vehicle classes and lease structures. Large logistics operators with centralized risk management functions drive broker channel growth.
- Direct Sales:Carrier-owned agency networks and call centers serve consumers who decline dealership add-on products. State Farm anchors gap offerings through this channel with captive agent distribution.
- Banks:Lender-placed products offered by captive finance arms at point of origination displace standalone purchases. Subprime auto lenders are pre-qualifying gap products outside dealership environments to comply with CFPB disclosure mandates.
Online Platforms are climbing the fastest; Insurance Brokers retain the highest margins per policy.
Customer Type:
Procurement sophistication and scale determine whether buyers accept standard dealership offerings or negotiate standalone coverage terms.
- Individual Consumers:Purchase gap coverage reactively at point of sale or proactively through direct channels. CFPB cooling-off period requirements are professionalizing this segment's decision-making and reducing post-sale cancellation rates.
- Commercial Fleets:Centralized procurement departments unbundle gap coverage from bundled fleet management contracts. Last-mile delivery contractors with vehicle-as-a-service models require structures adapted to mileage-based depreciation curves.
- Auto Dealerships:Act as intermediaries for front-end gap sales, though state-level markup restrictions in California and New York compress their economics. Dealerships remain the primary touchpoint for new vehicle buyers seeking immediate coverage activation.
- Financial Institutions:Auto lenders with embedded telematics partnerships automate claims settlement and reduce cycle times from weeks to hours. This capability eliminates the float period carriers traditionally relied upon for investment income.
Individual Consumers dominate policy count today; Commercial Fleets show the steepest expansion trajectory.
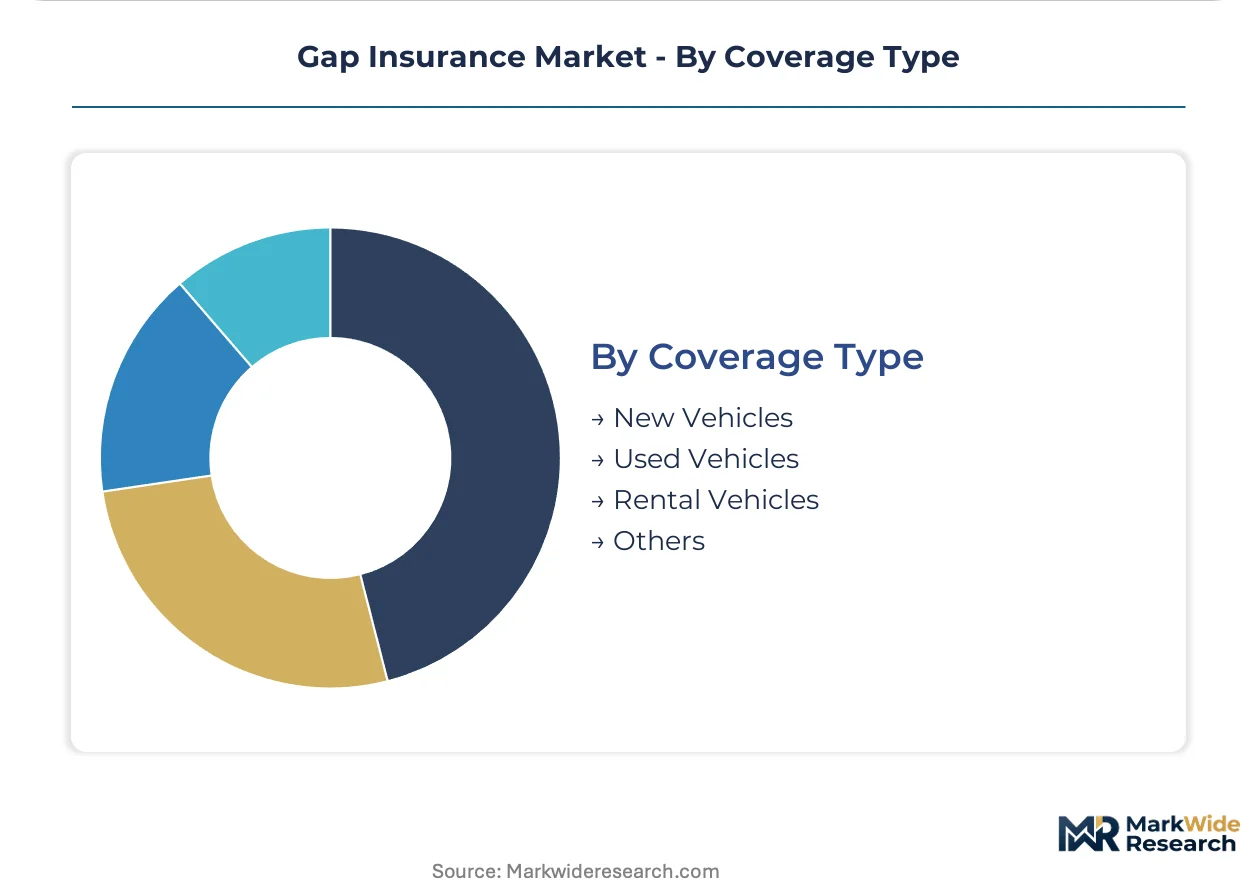
Coverage Type:
Vehicle age and prior ownership status determine depreciation patterns and thus loss severity distributions.
- New Vehicles:Steepest first-year depreciation creates maximum gap exposure. Franchised dealership sales of new cars generate the highest premium volume and carrier attachment rates.
- Used Vehicles:Depreciation curves flatten but loan-to-value ratios often exceed new car originations due to higher financing costs. Wholesale auction price volatility of 20-30% annually distorts reserve adequacy for this segment.
- Rental Vehicles:Fleet turnover schedules and high-utilization depreciation patterns require specialized coverage structures. Rental car companies self-insure or negotiate master policies rather than purchasing per-vehicle coverage.
- Others:Includes recreational vehicles, marine craft, and powersports equipment with collateral-specific depreciation profiles. Niche lenders serving these asset classes originate tailored gap products.
New Vehicles lead premium volume today; Used Vehicles are expanding most quickly as certified pre-owned financing lengthens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Franchised dealership clusters across the United States generate the highest gap insurance premium density. Negative equity rates on auto loans remain structurally elevated in this market, driving persistent demand for collateral shortfall protection.
United States
Subprime auto lenders and captive finance arms dominate origination volume here. The Consumer Financial Protection Bureau enforces Truth in Lending Act disclosures for add-on products sold at point of sale. Houston and Dallas-Fort Worth dealership corridors report the densest concentration of gap policy activations tied to high-LTV originations.
Canada
Credit unions and regional banks embed gap coverage into auto loan structures as loss-mitigation tools. Provincial insurance regulators oversee rate adequacy and producer licensing standards. The Greater Toronto Area anchors national volume, with Vancouver and Calgary serving as secondary concentration nodes for commercial fleet coverage.
United Kingdom
Personal contract purchase agreements drive demand for lease gap structures addressing end-of-lease residual shortfalls. The Financial Conduct Authority mandates product suitability assessments and cooling-off periods for dealership-sold add-ons. Birmingham and Manchester retail clusters show fastest adoption of direct digital channel alternatives to franchised dealer sales.
Germany
Commercial fleet operators unbundle gap coverage from bundled fleet management contracts to negotiate standalone terms. The Federal Financial Supervisory Authority regulates insurance product distribution and transparency requirements. The Rhine-Ruhr metropolitan region concentrates logistics contractor demand for electric vehicle transition coverage.
Australia
Online platforms displace dealership-dependent sales as primary distribution pathway for individual consumers. The Australian Securities and Investments Commission oversees add-on insurance product conduct standards. Sydney and Melbourne digital auto retail platforms embed gap coverage into checkout workflows without intermediation.
Gap Insurance Market Vendor Landscape
Strategic partnerships dominate the current landscape as carriers race to embed coverage into digital auto retail platforms. The market structure concentrates around national carriers with captive agency networks and direct-to-consumer capabilities. Three archetypes define competitive positioning: telematics-enabled underwriters leveraging real-time depreciation data, traditional carriers anchoring distribution through exclusive agent relationships, and digital-native insurers integrating API-based policy issuance. M&A activity targets telematics infrastructure providers, while portfolio diversification into commercial fleet products represents the second dominant move.
Among national carriers with captive distribution, State Farm, Allstate, and Progressive exemplify the scale-driven archetype. State Farm anchors its market position through exclusive agency networks that control the point-of-sale experience. Allstate represents the bundled-product approach, attaching gap coverage to proprietary new-car replacement offerings. Progressive occupies the telematics-forward tier, utilizing real-time vehicle depreciation feeds to compress underwriting cycles from annual to dynamic pricing intervals.
| Leading Market Players |
|---|
| Nationwide |
| American Family |
| Progressive |
| Amica Mutual |
| Erie Insurance |
| State Farm |
| Allstate |
| Travelers |
| Liberty Mutual |
| Others |
Supply Flow & Price Mechanics
The US Consumer Financial Protection Bureau's enhanced Truth in Lending Act disclosure mandates gate both qualified distribution partnerships and premium-tier pricing access for gap insurance carriers, forcing compliance investment as a prerequisite to dealership channel participation.
Pricing Analysis
Input-cost pass-through from telematics infrastructure investments and real-time data feed licensing compresses margins for carriers without scale economies. Three-tier pricing structure across premium, standard, and economy levels segments buyers by credit tier and vehicle LTV ratio at origination. Price differentiation centers on claims automation capability and telematics integration depth. Pricing pressure stems from state-level markup restrictions in California and New York that cap dealership commission flexibility. Subprime auto lenders exhibit highest price sensitivity due to thin origination spreads, while captive finance arms at OEMs show lowest sensitivity given balance-sheet integration.
Supply Chain Analysis
Warehouse-distribution layer concentration in Dallas-Fort Worth and Houston anchors US policy fulfillment infrastructure, with regional distribution centers serving franchised dealership corridors. Geographic supply concentration centers on the United States, Canada, and the United Kingdom as primary premium generation markets. Raw material dependencies include telematics hardware modules, actuarial software licenses, and cloud computing infrastructure for real-time depreciation feeds. Single-source vulnerability in telematics data providers creates concentration risk for carriers building dynamic pricing engines. Distribution runs through embedded API integrations with digital auto retail platforms, insurance broker networks, and captive agency channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gap insurance market functions as a regulatory compounder where CFPB disclosure mandates professionalize distribution and sustain demand through transparency requirements that reduce post-sale cancellations.
For Market Incumbents: Deepen telematics infrastructure partnerships to automate claims settlement and defend against direct-to-consumer substitution by captive finance arms. Invest in backward integration into real-time vehicle valuation data feeds to reduce third-party licensing costs. State-level markup compression in coastal markets threatens front-end dealership economics, making captive agency channel control the priority defensive lever. For New Entrants and Emerging Players: Capture commercial fleet gap coverage as large logistics operators unbundle from bundled fleet management contracts and negotiate standalone policies through insurance brokers. Electric vehicle depreciation uncertainty represents the most penetrable white space, with battery residual value opacity creating demand for powertrain-specific coverage structures. Target embedded insurance API integrations with vehicle-as-a-service platforms as the primary go-to-market pathway. For Investors and Strategic Acquirers: Valuations sit cheapest among regional carriers with concentrated subprime auto lender relationships and limited telematics capabilities. Long-term viability over the next decade hinges on successful transition from static actuarial tables to real-time data infrastructure. Acquisition target archetype: mid-tier carriers with captive agency footprints in Texas and Florida dealership corridors. Watch wholesale auction price volatility as the signal indicating reserve adequacy stress and potential distressed opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Infrastructure Partnership | Progressive leverages real-time depreciation feeds to compress underwriting cycles from annual to dynamic intervals. |
| Embedded Insurance API Integration | Carvana and Vroom embed gap coverage into checkout workflows, bypassing dealership intermediation entirely. |
| Commercial Fleet Unbundling | North American last-mile delivery contractors negotiate standalone policies through brokers for transparency into premium allocation. |
| Electric Vehicle Coverage Extension | Battery residual value uncertainty in EVs creates demand for powertrain-specific value collapse protection. |
| Captive Agency Network Expansion | State Farm anchors market position through exclusive agent relationships controlling point-of-sale experience. |
Methodological Framework
Direct dialogue with auto lender risk officers, dealership F&I managers, insurance broker principals, telematics platform engineers, and state insurance regulator staff grounded qualitative insights. Secondary validation drew from NAIC model legislation filings, CFPB consent orders, SEC 10-K insurance segment disclosures, vehicle registration databases, and wholesale auction price indices. Bottom-up policy volume estimates triangulated against top-down premium generation calculations across the analysis window.
Bottom-up modeling segmented volume by product type, distribution channel, customer sophistication tier, and coverage vintage, then cross-referenced against top-down macroeconomic drivers including auto loan origination trends and negative equity rate trajectories. CAGRs were derived from regression analysis of historical premium growth against explanatory variables. Industry-specific forecast inputs included loan-to-value ratio distributions at origination and telematics adoption curves among auto lenders.
Regulatory enforcement intensity, used vehicle price volatility swings, and telematics infrastructure deployment delays are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about CFPB disclosure mandate adherence rates and dealership channel persistence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Europe Embedded Insurance Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
Insurance Aggregators Market
Insurance
Austria Property and Casualty Insurance Market
Insurance
Marine Cargo Insurance Market
Insurance
Denmark Property and Casualty Insurance Market
Insurance
MENA Health and Medical Insurance Market
Insurance
UK Travel Insurance Market
Insurance
Europe EV Insurance Market
Insurance
Europe Liability Insurance Market
Insurance
UK Commercial Insurance Market
Insurance
Extended Warranty Agreement Market
Insurance
Insurance BPO Services Market
Insurance
India Electronic Gadget Insurance Market
Insurance
Asia-Pacific Travel Insurance Market
Insurance
North America Family Floater Health Insurance Market