
 Term Insurance Market | 2026-2036
Term Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Term Insurance Market Intelligence
The premium term insurance tier is consolidating around medically underwritten products with extended conversion privileges, while the commodity tier fragments into simplified-issue and guaranteed-issue policies with minimal health screening. Guardian leverages its mutual structure to sustain long-duration product competitiveness. Northwestern Mutual anchors its position through proprietary underwriting expertise and advisor-led distribution.
Term insurance provides pure mortality protection through fixed-duration contracts with no cash value accumulation, where insurers price coverage using attained-age mortality tables, risk class stratification, and reserve valuation under statutory accounting principles. Level term policies dominate premium volume due to predictable premium schedules and consumer preference for budget stability, while online platforms represent the fastest-growing distribution channel as direct-to-consumer pricing transparency reshapes customer acquisition economics. Annual renewable term retains niche appeal among transient workforce segments seeking short-term flexibility without long-term commitment.
US state insurance commissioners enforce reserve adequacy and illustration standards through the NAIC model regulations, while the SEC scrutinizes securities-linked variable term products under federal disclosure requirements. The EU's Solvency II framework imposes risk-based capital charges that elevate pricing for longer-duration guarantees. Stakeholders must monitor how algorithmic underwriting and alternative data sources redefine risk classification boundaries and regulatory acceptance.
Market Dynamics
Digital-first distribution platforms are compressing customer acquisition costs while algorithmic underwriting is compressing risk classification granularity, fundamentally restructuring how mortality coverage reaches price-sensitive demographics.
Growth Catalysts
- IRDAI Sandbox Approvals:India's insurance regulator accelerates product innovation cycles by permitting controlled testing of novel term structures and embedded wellness riders before full market release.
- Telematics-Enabled Risk Scoring:Wearable data streams and behavioral analytics enable dynamic premium adjustments for health-conscious policyholders, expanding addressable markets among younger cohorts.
- Tier-One City Concentration:China's urban middle-class households in Beijing, Shanghai, Shenzhen, and Guangzhou prioritize income protection as household leverage ratios climb, concentrating premium volume in coastal provinces.
Market Restraints
- Long-Duration Reserve Strain:Statutory valuation under NAIC principles elevates capital charges for insurers issuing level-term policies beyond twenty-year durations, compressing product economics.
- Reinsurance Capacity Concentration:Global mortality risk transfer depends on a narrow cohort of Bermuda and London-based reinsurers, creating systemic vulnerability to pandemic tail events.
- Alternative Asset Substitution:Employer-sponsored group life coverage and defined-contribution retirement balances compete for household protection budgets, particularly among salaried workers in developed economies.
Strategic Opportunities
- Micro-Term Penetration:India's semi-urban and rural districts remain dramatically underpenetrated for individual mortality coverage, presenting white-space potential for mobile-enabled, low-ticket policies.
- Solvency II Optimization:EU insurers can restructure term guarantee durations to minimize risk-based capital charges under the European framework's mortality stress parameters.
- Embedded Distribution Convergence:Partnerships with neobanks, payroll platforms, and gig-economy marketplaces enable contextual policy origination at moments of employment transition or income verification.
Industry Challenges
- Actuarial Talent Compression:Traditional mortality modeling expertise confronts scarcity as data science and machine-learning specializations divert graduate cohorts from insurance-specific career tracks.
- Legacy System Integration:Core policy administration platforms built on decades-old architectures resist API-native connectivity with digital distribution partners, delaying real-time quoting and binding capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Term Insurance Market |
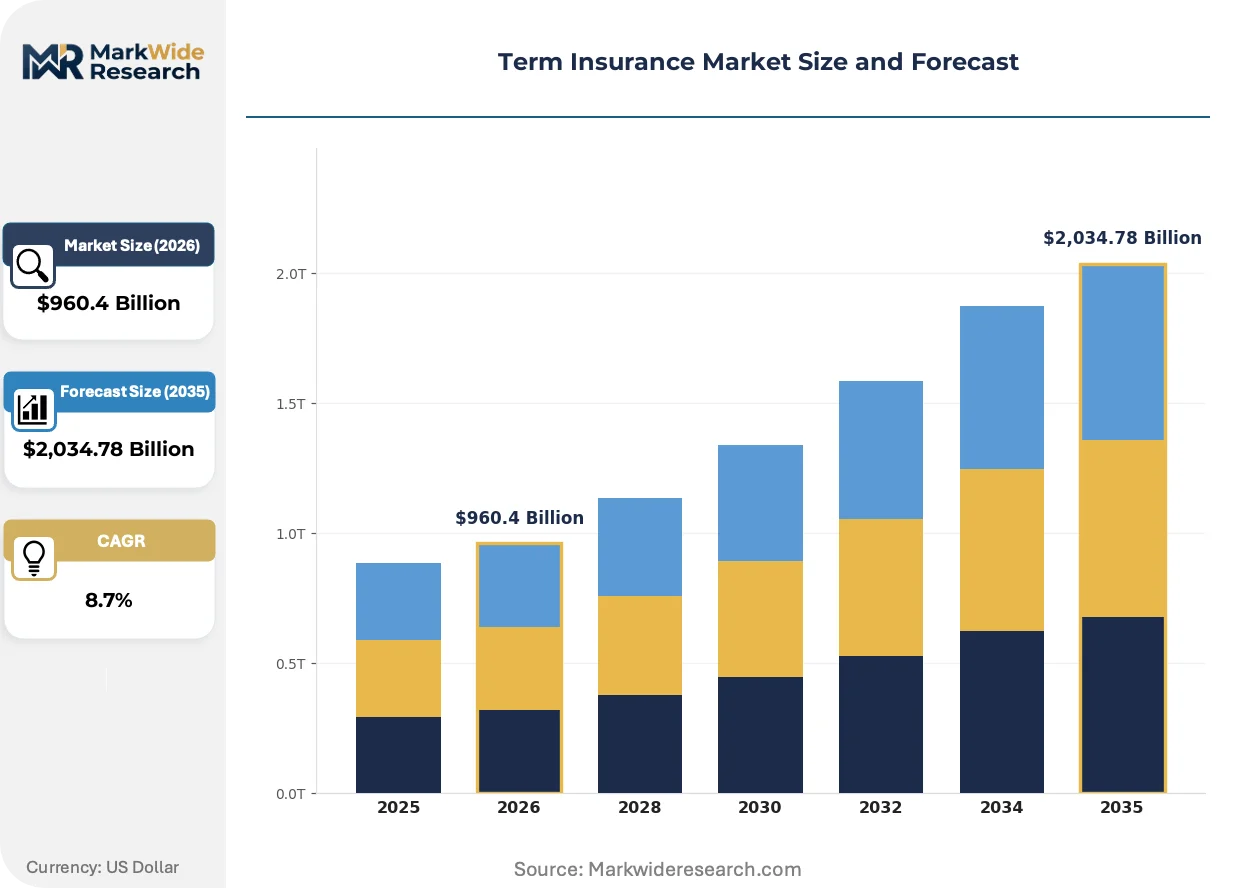
| Market Size in 2026 | $960.4 Billion |
| Market Size in 2035 | $2,034.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Level Term, Decreasing Term, Annual Renewable Term, Convertible Term Distribution Channel: Direct Sales, Insurance Agents, Brokers, Online Platforms Coverage Amount: $100K-$250K, $250K-$500K, $500K-$1M, Over $1M Customer Type: Individuals, Families, Corporates, Self-Employed |
| Companies Covered | Guardian, New York Life, USAA, Northwestern Mutual, Thrivent, State Farm, Protective Life, Pacific Life, Lincoln Financial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Term Insurance Market Strategic Shifts & Innovations
Algorithmic underwriting engines are displacing fluid-based medical exams across standard risk classes, while regulatory sandboxes in multiple jurisdictions validate accelerated underwriting models that compress issuance timelines from weeks to minutes.
Automated underwriting platforms leveraging prescription history, motor vehicle records, and credit attributes are consolidating risk assessment workflows for standard and preferred risk tiers. Direct-to-consumer carriers and insurtech distributors deploy these engines to achieve sub-48-hour policy issuance. The compression of underwriting labor is consolidating cost advantages with digitally native distributors while pressuring traditional advisor-dependent channels.
The EU's Solvency II review introduces calibrated adjustments to mortality risk capital charges that elevate pricing precision for longer-duration guarantees. Insurers operating under European supervision must recalibrate product design to optimize capital efficiency. German and French carriers are responding by shortening guarantee periods or introducing renewable structures that reset risk classification at interval boundaries.
Young professionals across Asian metropolitan centers now initiate term coverage research through mobile comparison platforms rather than agent referrals. Aggregator sites and insurer-owned direct channels capture this behavioral pivot, displacing traditional brokerage intermediaries for straightforward mortality products. This channel rotation is most pronounced in Mumbai, Singapore, and Jakarta, where smartphone penetration and financial literacy rates converge.
Term Insurance Market Segmentation
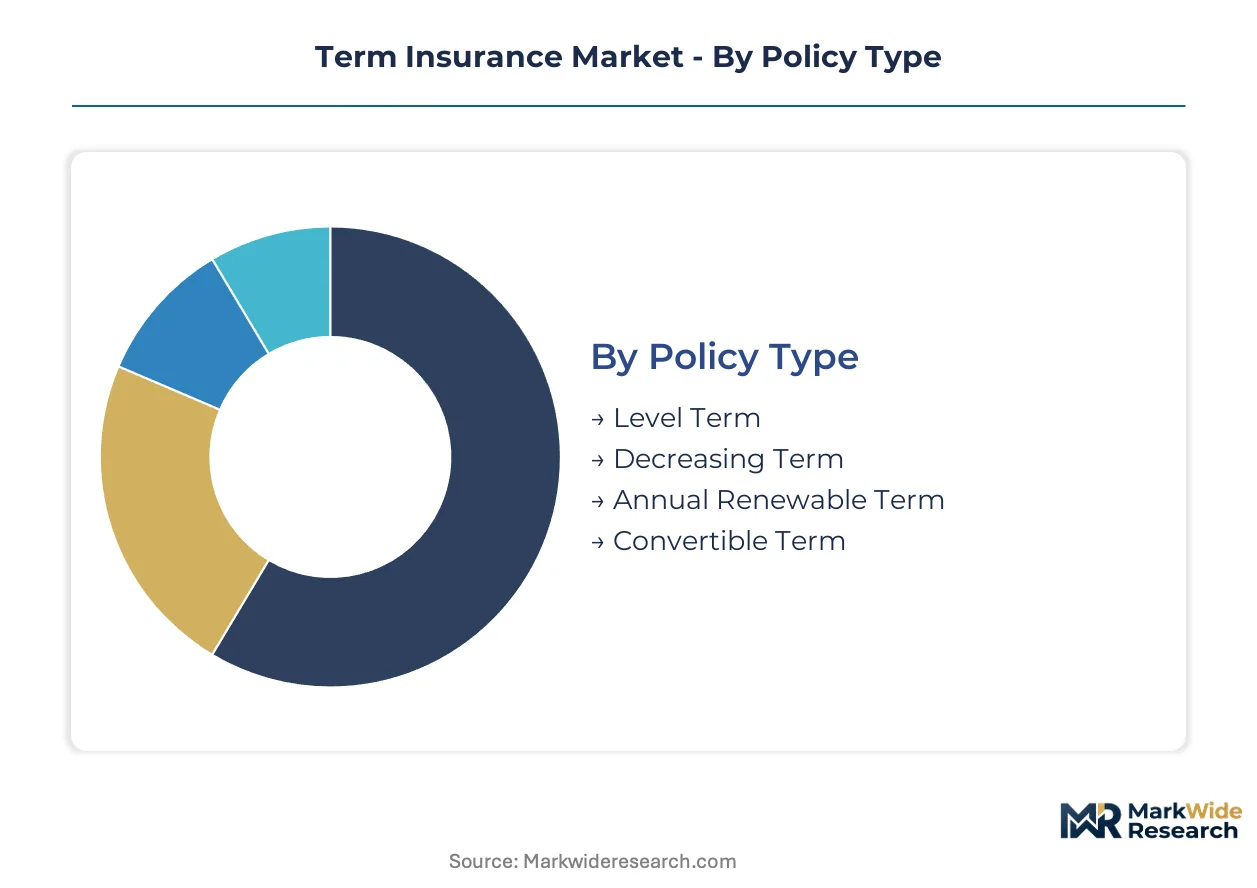
Term insurance segmentation reveals how mortality coverage stratifies across risk tolerance, purchase behavior, and household financial architecture. Policy structure and distribution pathway selection directly determine capital efficiency, customer acquisition economics, and regulatory reserve requirements for carriers.
Policy Type:
NAIC reserve valuation principles and Solvency II mortality stress parameters impose divergent capital charges across guarantee structures, shaping product economics.
- Level Term:Fixed premium schedules across 10-30 year durations dominate premium volume through budget predictability. Demand concentrates among US middle-income households seeking income replacement certainty amid mortgage obligations.
- Annual Renewable Term:Attained-age pricing with annual premium escalation serves transient workforce segments requiring short-duration flexibility without long-term capital commitment. Gig-economy platforms in India and Southeast Asia drive adoption.
- Decreasing Term:Face value amortization aligns with declining mortgage balances, offering lower initial premiums for collateral protection needs.
- Convertible Term:Embedded permanent insurance conversion privileges command higher base rates but reduce policyholder lapse risk, prized by mutual insurers for persistency metrics.
Leading the category by volume: Level Term. Growing fastest: Convertible Term.
Distribution Channel:
Customer acquisition cost structures and illustration compliance burdens fragment across intermediary types, with digital channels compressing expense ratios while advisor-led sales sustain premium persistency.
- Online Platforms:Direct-to-consumer aggregators and insurer-owned portals leverage algorithmic underwriting to achieve sub-48-hour issuance. Young professionals in Mumbai, Singapore, and Jakarta initiate coverage research through mobile comparison engines.
- Insurance Agents:Captive and independent advisor networks dominate complex household protection planning, with Northwestern Mutual and Guardian sustaining competitiveness through proprietary underwriting expertise.
- Brokers:Independent intermediaries access multiple carrier panels for risk-class optimization, particularly for impaired-risk applicants outside standard markets.
- Direct Sales:Carrier-employed sales forces target employer-sponsored group conversions and affinity marketing arrangements.
Volume leadership: Insurance Agents. Steepest expansion trajectory: Online Platforms.
Coverage Amount:
Face value bands correlate with household leverage ratios, income replacement multiples, and reinsurance treaty participation thresholds.
- $500K-$1M:Primary demand concentration among dual-income professional households in China's tier-one cities and India's metropolitan districts, where mortgage debt service drives protection adequacy calculations.
- Over $1M:High-net-worth segment requiring private placement life insurance structures and advanced estate liquidity planning, with Bermuda reinsurers providing mortality capacity.
- $250K-$500K:Mass-affluent entry tier for first-time buyers establishing baseline income protection.
- $100K-$250K:Simplified-issue and guaranteed-issue products with minimal health screening for budget-constrained segments.
Category volume leader: $500K-$1M. Climbing the fastest: Over $1M.
Customer Type:
Risk classification granularity and policy servicing intensity vary sharply across purchaser categories, from standardized individual underwriting to experience-rated group structures.
- Individuals:Medically underwritten products with extended conversion privileges consolidate around preferred risk tiers, while simplified-issue policies fragment the commodity segment.
- Families:Multi-life discount structures and dependent rider attachments concentrate demand among primary breadwinners seeking household income continuity.
- Corporates:Employer-sponsored group term arrangements compete for household protection budgets, particularly among salaried workers in developed economies with defined-contribution retirement balances.
- Self-Employed:Income verification challenges elevate pricing for gig-economy participants, driving demand for guaranteed-issue micro-term products.
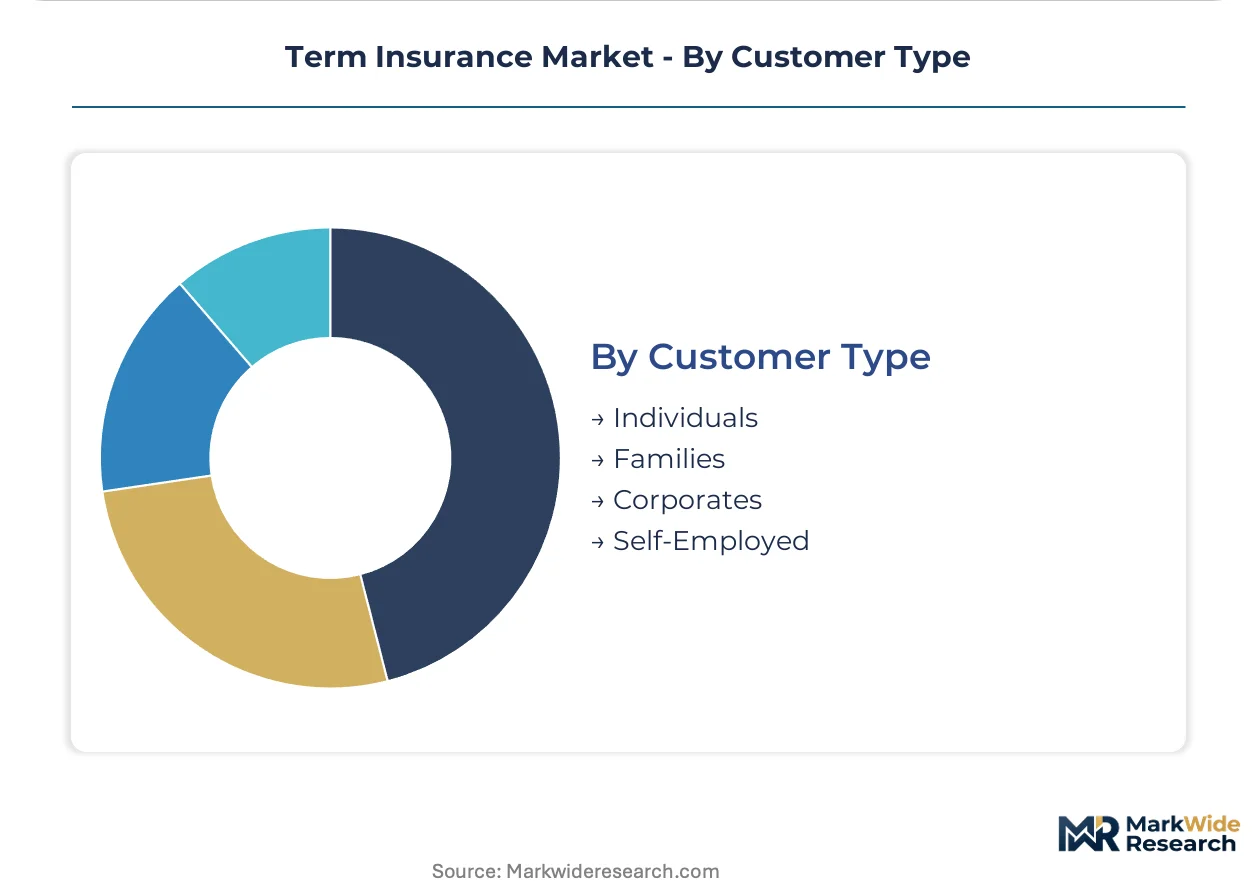
Volume concentration: Individuals. Gaining share fastest: Self-Employed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai's financial district anchors term insurance distribution innovation through mobile-first platforms targeting young professionals. India's IRDAI sandbox accelerates product testing. China's tier-one cities concentrate premium volume as middle-class households prioritize income protection.
United States
Mortgage debt service drives demand for level-term policies among dual-income households in suburban corridors. State insurance commissioners enforce NAIC reserve adequacy standards through model regulations. Texas and Florida metros exhibit elevated policy origination through direct-to-consumer channels.
China
Beijing, Shanghai, Shenzhen, and Guangzhou concentrate premium volume as household leverage ratios climb. SAMR supervises product disclosure and illustration standards. Coastal provinces dominate convertible term adoption among technology sector employees.
India
Young professionals in Mumbai, Bangalore, and Delhi-NCR initiate coverage research through mobile comparison engines. IRDAI's sandbox approvals permit controlled testing of wellness-linked riders. Semi-urban districts present white-space potential for micro-term penetration.
Germany
Solvency II mortality stress parameters elevate capital charges for longer-duration guarantees. BaFin supervises risk-based capital requirements under the European framework. Munich and Frankfurt carriers recalibrate product design toward renewable structures.
United Kingdom
London's fintech ecosystem enables embedded distribution partnerships with neobanks and payroll platforms. The Financial Conduct Authority scrutinizes algorithmic underwriting fairness. Southeast England exhibits concentrated demand for simplified-issue products among gig-economy participants.
Term Insurance Market Key Industry Players
Premium-margin players sit above commodity-margin players across underwriting sophistication and distribution economics. The market consolidates around medically underwritten products with extended conversion privileges while fragmenting into simplified-issue tiers. Mutual structures and proprietary underwriting expertise define two strategic archetypes. Competitive moves center on digital platform partnerships and algorithmic underwriting engine deployment.
Within the mutual insurer archetype, Guardian and Northwestern Mutual exemplify long-duration product competitiveness through captive capital structures. New York Life occupies a position bridging mutual heritage with modernized direct channels. These three entities represent how organizational form shapes risk capacity and persistency economics in mortality protection markets.
| Leading Market Players |
|---|
| Guardian |
| New York Life |
| USAA |
| Northwestern Mutual |
| Thrivent |
| State Farm |
| Protective Life |
| Pacific Life |
| Lincoln Financial |
| Others |
Cost & Logistics Intelligence
Mortality table reserve valuation spreads cascade through Bermuda reinsurance treaties into policyholder premium tiers across US, Chinese, and Indian markets. Long-duration guarantee structures face elevated capital charges under NAIC and Solvency II frameworks, compressing product economics for carriers while shifting price sensitivity toward digitally distributed simplified-issue tiers.
Pricing Analysis
Outcome-linked wellness scoring anchors value-based pricing for telematics-enabled term products, rewarding policyholders with wearable-verified health metrics. Premium stratification separates medically underwritten preferred risk tiers from guaranteed-issue commodity segments, with algorithmic underwriting compressing issuance costs. Pricing pressure stems from direct-to-consumer platform transparency, which exposes traditional advisor-loaded commission structures. Mass-affluent first-time buyers in India's metropolitan districts exhibit highest price sensitivity, while high-net-worth segments in China's tier-one cities prioritize conversion privileges over premium minimization.
Supply Chain Analysis
Regional reinsurance hubs in Bermuda and London concentrate mortality risk capacity through treaty-based capacity allocation to primary carriers. Ceded premium flows depend on proprietary underwriting expertise, algorithmic risk-scoring engines, and advisor network infrastructure. Single-source vulnerability concentrates in Bermuda-based mortality reinsurers, creating systemic exposure to pandemic tail events. Distribution runs through captive agent networks, direct-to-consumer platforms, and embedded neobank partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithmic underwriting engines are displacing fluid-based medical exams and legacy actuarial workflows, compressing issuance timelines from weeks to minutes across standard risk classes.
For Market Incumbents: Anticipate margin compression from insurtech distributors deploying sub-48-hour automated underwriting platforms by accelerating proprietary algorithmic engine investment and securing exclusive embedded distribution partnerships with payroll platforms. Channel control through advisor network consolidation remains critical as direct-to-consumer pricing transparency erodes traditional commission-loaded economics. For New Entrants and Emerging Players: Launch via mobile-first micro-term products targeting India's semi-urban and rural districts, where individual mortality coverage penetration remains minimal. White-space concentration exists among gig-economy participants requiring income-verification-flexible guaranteed-issue structures. Contextual policy origination at employment transition moments through neobank partnerships offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor mutual insurers with captive capital structures in US coastal corridors, where persistency economics and long-duration product competitiveness create defensive moats. Acquisition targets should demonstrate proprietary underwriting expertise and advisor-led distribution density. Watch algorithmic underwriting regulatory sandbox approvals as the inflection indicator for technology-transition viability across the analysis window.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Underwriting Engine Deployment | NAIC model regulations and IRDAI sandbox approvals validate accelerated risk-scoring models that compress issuance timelines. |
| Embedded Distribution Partnership | Neobank and payroll platform integrations enable contextual policy origination at income verification moments in Mumbai and Jakarta. |
| Wellness Rider Integration | Telematics-enabled dynamic premium adjustments expand addressable markets among health-conscious young professionals. |
| Reinsurance Treaty Restructuring | Bermuda and London-based capacity concentration demands diversified mortality risk transfer mechanisms. |
| Legacy System API Modernization | Core policy administration platforms require real-time connectivity with digital distribution partners for sub-48-hour binding. |
Research Approach
Document review covered NAIC model regulation filings, IRDAI sandbox approval records, and Solvency II mortality stress parameter documentation, complemented by interviews with chief underwriting officers, actuarial science directors, digital distribution platform executives, and reinsurance treaty specialists. Secondary validation drew from statutory insurance commissioner reports, SEC variable product disclosure filings, and EU insurance supervision authority capital adequacy assessments. Bottom-up policy origination volume estimates triangulated against top-down premium flow projections.
Segment-level outputs across policy type, distribution channel, coverage amount, and customer type dimensions were generated through mortality table application and reserve valuation modeling. CAGRs were derived from risk-class stratification trends and digital adoption curve analysis. Forecast inputs incorporated regulatory sandbox approval velocity, wearable penetration rates, and household leverage ratio trajectories across the projection horizon.
Regulatory framework revision, pandemic mortality tail event recurrence, and algorithmic underwriting fairness litigation are the dominant revision risks that could alter trajectory assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Vietnam Private Health Insurance Market
Insurance
Cybersecurity Insurance Market
Insurance
Bancassurance Market
Insurance
Digital Monetary Insurance Market
Insurance
Sri Lanka Cyber (Liability) Insurance Market
Insurance
Marine Freight Insurance Market
Insurance
Asia-Pacific Extended Warranty Market
Insurance
Norway Property and Casualty Insurance Market
Insurance
Global Mobile Phone Insurance Ecosystem Market
Insurance
Agriculture Insurance Market
Insurance
Internet of Things Insurance Market
Insurance
United Kingdom Parametric Insurance Market
Insurance
India Dental Insurance Market
Insurance
South Korea Liability Insurance Market
Insurance
UK Commercial Insurance Market
Insurance
Bancassurance in ASEAN Market