
 Logistics Insurance Market | 2026-2036
Logistics Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Logistics Insurance Market Analysis
Asset-light fleet leasing and third-party logistics outsourcing is narrowing the pool of insureds with direct insurable interest, forcing carriers to redesign policy structures for non-asset operators. Munich Re leverages captive underwriting platforms to sustain pricing power in volatile marine cargo lines. Allianz SE anchors its European logistics portfolio through specialized freight liability programs targeting contract logistics providers. Chubb Ltd. competes in high-value electronics transit with temperature-controlled coverage extensions.
Logistics insurance encompasses risk transfer instruments protecting goods, vessels, vehicles, and infrastructure against physical loss or damage during multimodal transit, with policies typically specifying per-kilogram valuation limits, deductible tiers, and Institute Cargo Clauses coverage benchmarks. Marine cargo coverage dominates premium pools due to international trade density, while freight liability policies are expanding fastest among 3PL providers assuming statutory carrier responsibility. Claims management services command elevated margins as automated port scanning and IoT telemetry generate dispute-resolution data streams.
The EU's Corporate Sustainability Reporting Directive and the International Maritime Organization's emissions protocols are elevating environmental liability exposure in logistics contracts, directly shaping coverage demand. The US Federal Maritime Commission and the UK's Financial Conduct Authority both scrutinize premium adequacy in container shipping lines, tightening capital reserving requirements. Stakeholders must monitor how parametric triggers tied to GPS-verified delays and automated warehouse robotics incidents reshape underwriting models and claims adjudication workflows.
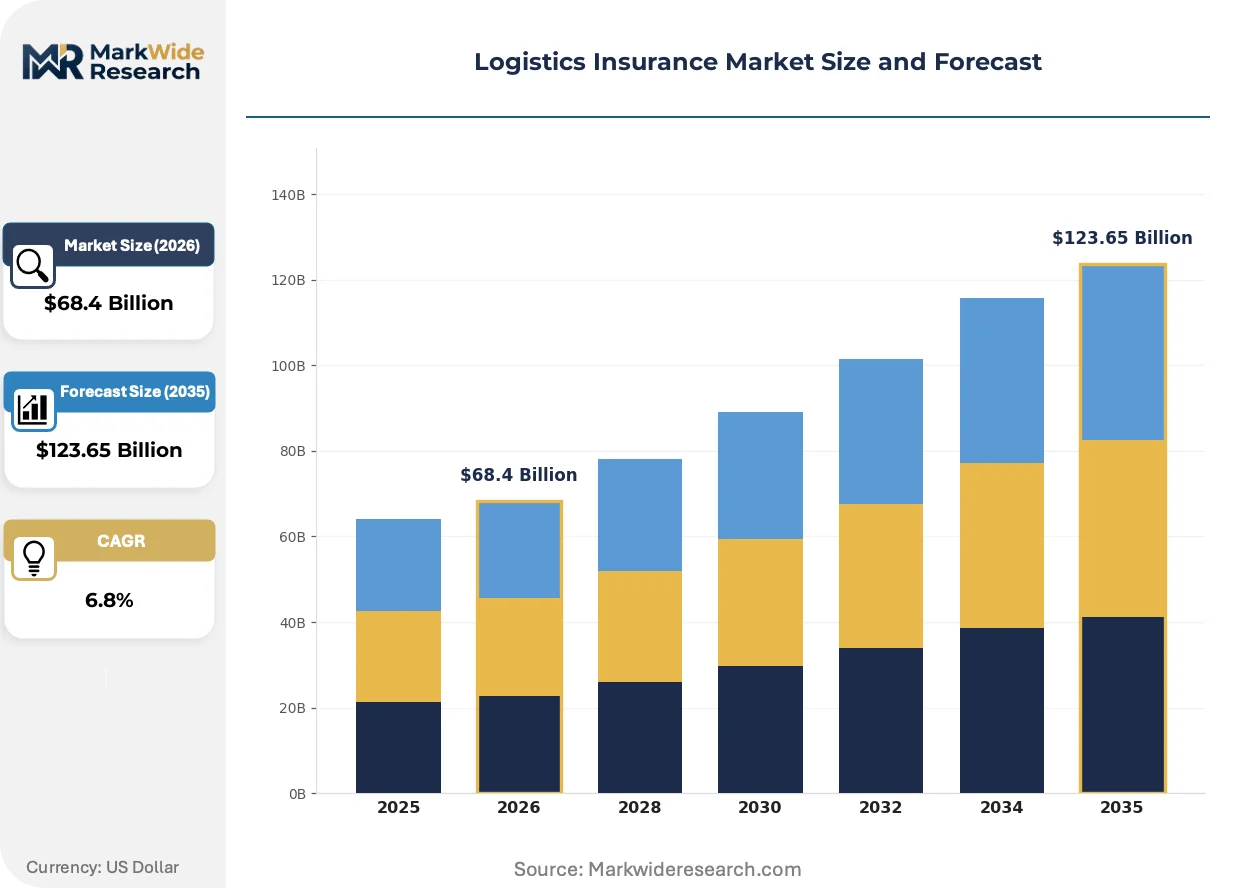
Market Dynamics
Asset-light logistics operators now dominate freight forwarding, fragmenting insurable interest across multiple contract tiers and forcing carriers to rebuild policy architectures around liability chains rather than owned-asset exposure.
Growth Catalysts
- E-commerce fulfillment density:Last-mile delivery networks in Germany, Netherlands, and Poland require specialized cargo coverage for high-value parcel flows through automated sorting hubs.
- CSRD disclosure mandates:The EU's Corporate Sustainability Reporting Directive compels logistics firms to quantify supply chain risk exposure, driving demand for verified insurance documentation.
- Parametric trigger innovation:GPS-verified delay clauses and IoT telemetry integration enable automated claims settlement for container shipping lines.
Market Restraints
- Reinsurance capacity contraction:Marine cargo lines face tightened retrocession availability after consecutive years of port congestion losses in Rotterdam and Hamburg.
- Input cost volatility:Hull and machinery repair inflation in Southeast Asian shipyards compresses technical margins on vessel coverage.
- Regulatory fragmentation:Divergent cargo liability regimes between the Hague-Visby Rules and Hamburg Rules jurisdictions create policy wording conflicts.
Strategic Opportunities
- Cold chain expansion:Temperature-controlled pharmaceutical distribution across the Rhine-Ruhr corridor demands specialized perishables coverage with real-time monitoring.
- Cyber-physical convergence:Automated warehouse robotics and port automation create new liability categories at the intersection of property and technology errors.
- India's logistics corridor development:Dedicated freight corridors under the Ministry of Railways generate demand for multimodal transit policies covering rail-road handoffs.
Industry Challenges
- Actuarial data scarcity:Emerging risk categories around autonomous trucking and drone delivery lack historical loss experience for pricing models.
- Legacy system integration:Blockchain-enabled smart contracts for parametric claims require costly middleware development at established carriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Logistics Insurance Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Marine Cargo, Freight Liability, General Liability, Warehouse Legal Liability Customer Type: 3PL Providers, Freight Forwarders, Manufacturers, Retailers Coverage Type: All Risks, Named Perils, Comprehensive, Specific Coverage Service Type: Risk Assessment, Claims Management, Underwriting, Policy Administration |
| Companies Covered | AIG, Tokio Marine Holdings, Allianz SE, Munich Re, The Travelers Companies, AXA XL, Chubb Ltd., Liberty Mutual Insurance, Zurich Insurance Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Logistics Insurance Market Emerging Trajectories
Underwriting workflows are being rebuilt around continuous data streams rather than static policy periods, with real-time cargo monitoring displacing traditional survey-based risk assessment.
Telematics-enabled cargo tracking is migrating from premium add-on to standard coverage requirement. Large retailers and automotive manufacturers now mandate GPS-verified chain-of-custody documentation as a condition of supplier qualification. This shift compresses pricing differentiation between carriers with integrated IoT platforms and those relying on manual claims investigation.
The EU's CSRD and the International Maritime Organization's emissions protocols are elevating environmental liability exposure in logistics contracts. Insurers must now model carbon-related supply chain disruption alongside traditional physical damage. Container shipping lines operating through Rotterdam and Antwerp face the earliest pressure to disclose Scope 3 exposure in coverage negotiations.
Third-party logistics providers are consolidating procurement of freight liability programs through specialized brokers rather than direct carrier relationships. Contract logistics firms in the Benelux region increasingly demand outcome-based coverage tied to delivery performance metrics rather than per-shipment premiums. This reconfigures commission structures and retention strategies across the intermediated channel.
Logistics Insurance Market Segmentation
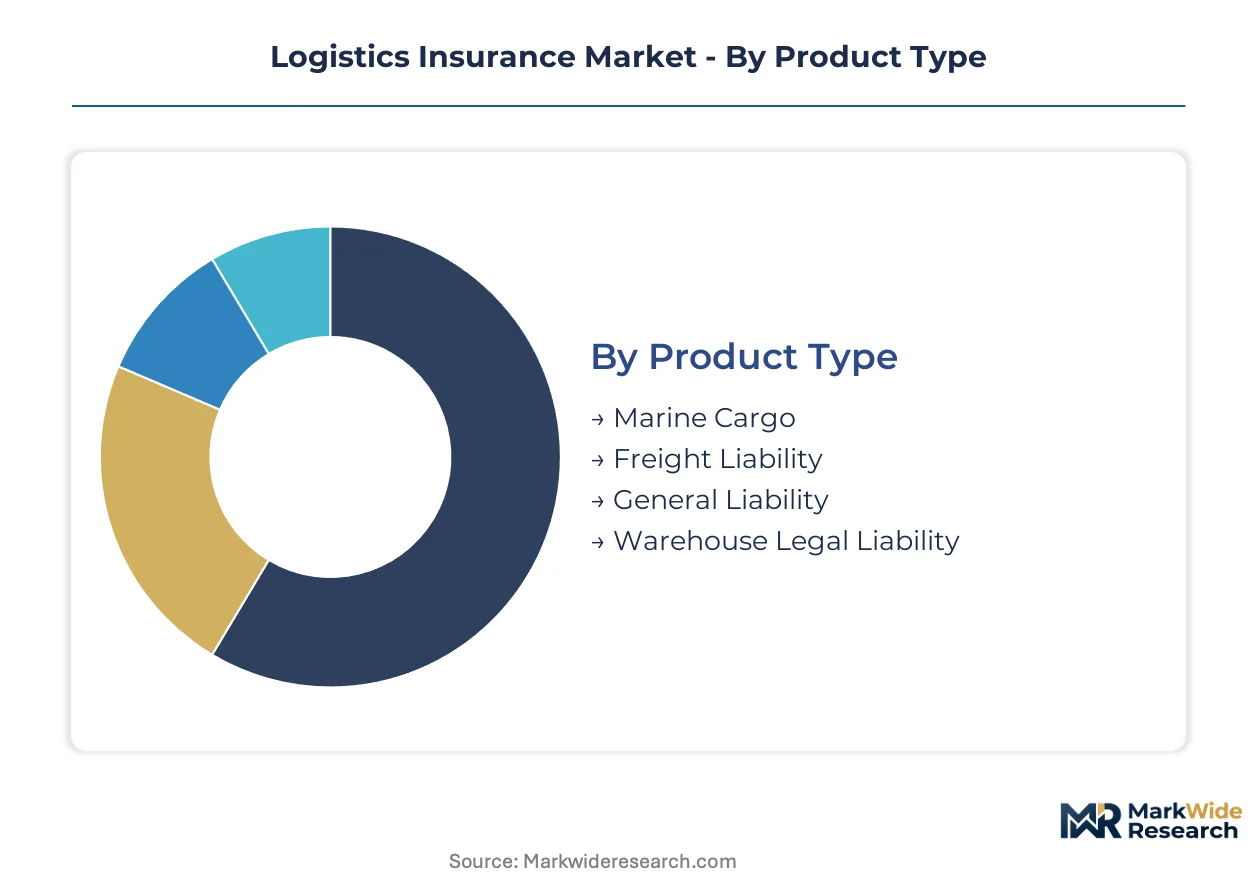
Logistics insurance carriers must architect products around divergent risk profiles across transport modes and contract structures. Each segmentation dimension reveals distinct pricing power, retention dynamics, and intermediation patterns that shape portfolio construction.
Product Type:
Cost tiers within logistics insurance correlate directly with claim severity distributions and reinsurance dependency ratios.
- Marine Cargo:Institute Cargo Clauses-based coverage protecting international goods-in-transit against perils ranging from total vessel loss to partial damage during container handling. Rotterdam and Hamburg port operators drive premium concentration through high-value container throughput and specialized project cargo requirements.
- Freight Liability:Statutory and contractual carrier responsibility coverage assuming legal liability for cargo loss under Hague-Visby and Hamburg Rules jurisdictions. 3PL providers in the Benelux region are consolidating procurement through specialized brokers, compressing direct carrier relationships.
- General Liability:Third-party bodily injury and property damage protection for logistics facility operations and vehicle fleets. Demand concentrates among mid-sized warehouse operators seeking bundled coverage alongside property policies.
- Warehouse Legal Liability:Bailee coverage protecting stored goods against fire, theft, and environmental damage while under logistics operator custody. Cold chain pharmaceutical distributors in Germany's Rhine-Ruhr corridor require temperature excursion sublimits with real-time monitoring integration.
Marine Cargo holds installed capacity. Freight Liability is rotating up the share rankings.
Customer Type:
Application-specific risk exposures fragment procurement behavior and policy architecture across the logistics value chain.
- 3PL Providers:Contract logistics firms assuming end-to-end supply chain responsibility through asset-light operating models. The EU's CSRD disclosure mandates compel these operators to document verified insurance coverage as part of sustainability reporting.
- Freight Forwarders:Intermediary NVOCCs and air cargo consolidators arranging multimodal transit without direct asset ownership. Parametric GPS-verified delay triggers are displacing traditional claims investigation for this segment.
- Manufacturers:Industrial shippers with captive risk management functions seeking controlled master policies covering inbound raw materials and outbound finished goods. Automotive manufacturers now mandate GPS chain-of-custody documentation as supplier qualification criteria.
- Retailers:E-commerce fulfillment networks and omnichannel distributors requiring last-mile delivery coverage for high-value parcel flows. Automated sorting hubs in Poland and the Netherlands generate specialized cargo coverage demand for electronics and fashion goods.
3PL Providers command the deepest policy customization. Retailers are expanding coverage limits fastest.
Coverage Type:
Volume concentration within each coverage tier reflects trade lane maturity and buyer risk sophistication.
- All Risks:Broadest Institute Cargo Clauses A protection covering external causes of loss except enumerated exclusions. High-value electronics and pharmaceutical shippers in temperature-controlled lanes default to this tier despite premium surcharge.
- Named Perils:Specified-cause coverage under Institute Cargo Clauses B and C limiting protection to fire, collision, and jettison events. Commodity bulk shippers with predictable loss patterns select this structure for rate efficiency.
- Comprehensive:Bundled property and liability protection for integrated logistics operators with owned warehouses and vehicle fleets. Mid-market 3PLs in Germany consolidate coverage through single-carrier programs.
- Specific Coverage:Tailored endorsements addressing unique exposures such as cyber-physical warehouse automation or drone delivery liability. Actuarial data scarcity constrains capacity deployment in this tier.
All Risks maintains premium share leadership. Specific Coverage is climbing the fastest.
Service Type:
Customer maturity and technology adoption rates segment service delivery models across the policy lifecycle.
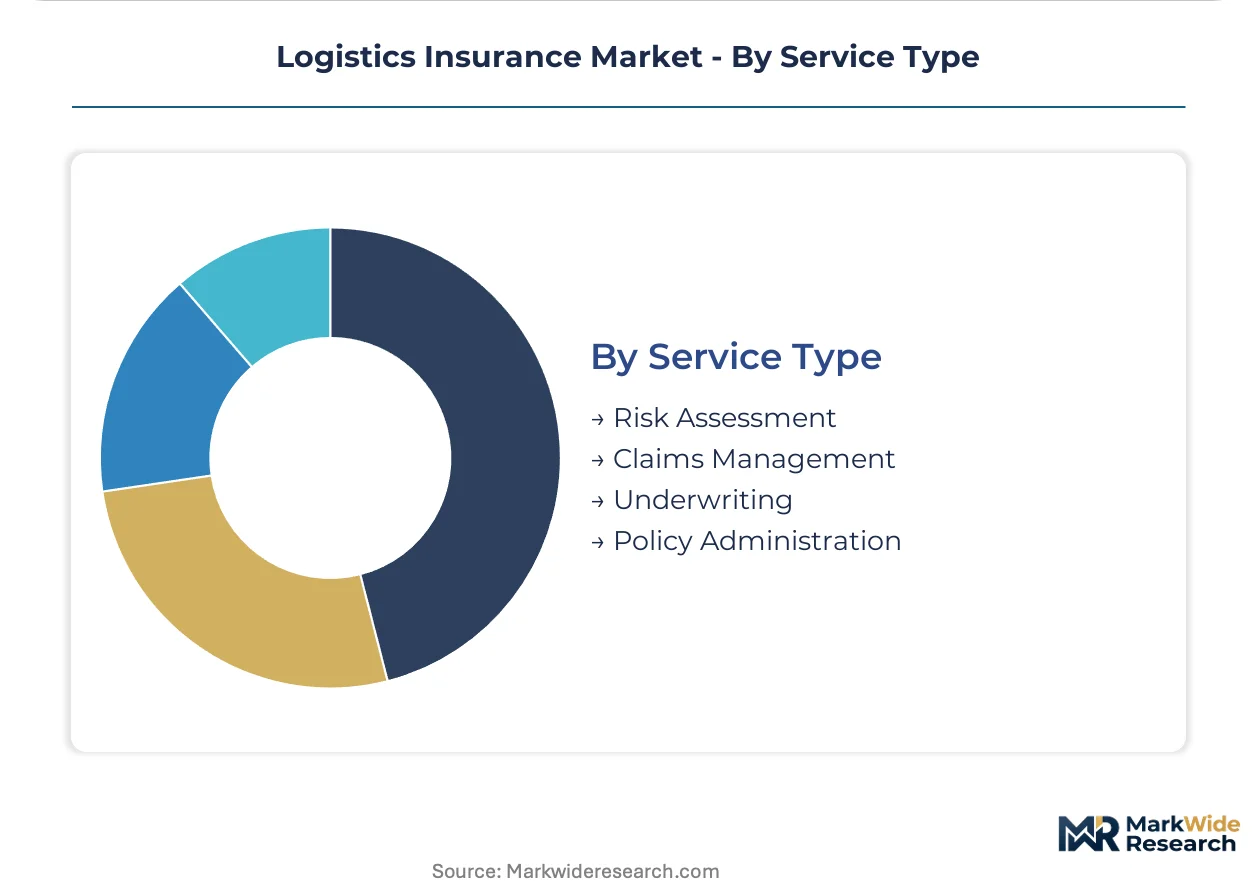
- Risk Assessment:Pre-binding survey and IoT-enabled continuous monitoring replacing static annual reviews. Telematics integration is migrating from premium add-on to standard coverage requirement among large retailers.
- Claims Management:Dispute resolution and loss adjustment services commanding elevated margins through automated port scanning data streams. Blockchain-enabled smart contracts require costly middleware development at established carriers.
- Underwriting:Risk selection and pricing authority exercised through captive platforms and specialized freight liability programs. Munich Re leverages captive structures to sustain pricing power in volatile marine cargo lines.
- Policy Administration:Endorsement processing, premium collection, and documentation management increasingly automated through broker portals. Third-party logistics providers are consolidating procurement through specialized intermediaries rather than direct carrier channels.
Underwriting captures the highest value per transaction. Claims Management is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import intensity varies sharply across major trade corridors, with container throughput volumes and customs clearance complexity driving divergent coverage demand. Germany's Rhine-Ruhr logistics cluster and Rotterdam-Antwerp port systems anchor European premium pools, while US intermodal networks and Asian manufacturing export zones concentrate specialized cargo lines.
Germany
Multimodal freight hubs along the Rhine-Ruhr corridor generate specialized cargo coverage for pharmaceutical cold chains and automotive parts. The EU's CSRD disclosure mandates compel logistics operators to document verified insurance coverage in sustainability reports. Duisburg's inland port terminal drives demand for barge-to-rail transit policies with real-time temperature monitoring.
United States
E-commerce fulfillment density across California and Texas distribution corridors requires last-mile delivery coverage for high-value electronics. The Federal Maritime Commission scrutinizes premium adequacy in container shipping lines, tightening capital reserving requirements. Chicago's intermodal rail yards concentrate freight liability programs among third-party logistics providers.
China
Manufacturing export zones in the Yangtze River Delta and Pearl River Delta sustain marine cargo premium volumes through high-value electronics shipments. The Ministry of Transport's logistics corridor development programs expand multimodal transit policy demand. Shanghai's automated container terminal generates specialized coverage for cyber-physical port automation risks.
Netherlands
Rotterdam's port congestion losses have tightened reinsurance capacity for marine cargo lines serving European trade lanes. The EU Green Deal emissions protocols elevate environmental liability exposure in logistics contracts. Venlo's distribution parks concentrate warehouse legal liability coverage for pharmaceutical perishables with GPS-verified chain-of-custody requirements.
India
Dedicated freight corridors under the Ministry of Railways generate demand for multimodal transit policies covering rail-road handoffs. The PLI scheme for logistics infrastructure attracts specialized coverage for automated warehousing investments. Gujarat's Mundra Port drives marine cargo premiums for bulk commodity exports and project cargo imports.
Logistics Insurance Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with captive underwriting structures and niche liability programs. The market consolidates around reinsurance-backed carriers with captive platforms and specialized freight liability underwriters serving contract logistics providers. Two archetypes dominate: scale-driven marine cargo specialists leveraging retrocession networks, and technology-integrated carriers embedding IoT telemetry into standard coverage. Competitive moves center on parametric trigger innovation and broker channel consolidation for third-party logistics procurement.
Among European reinsurance-backed carriers, Munich Re and Allianz SE exemplify platform-scale archetypes with captive underwriting structures sustaining pricing power in volatile marine cargo lines. Chubb Ltd. occupies a position within the technology-integrated tier, competing through specialized coverage extensions for high-value electronics transit. These three entities represent divergent strategic postures: retrocession-dependent scale, broker-anchored European portfolio construction, and premium-tier technology embedding.
| Leading Market Players |
|---|
| AIG |
| Tokio Marine Holdings |
| Allianz SE |
| Munich Re |
| The Travelers Companies |
| AXA XL |
| Chubb Ltd. |
| Liberty Mutual Insurance |
| Zurich Insurance Group |
| Others |
Supply Flow & Price Mechanics
Overcapacity in marine cargo lines serving Rotterdam and Hamburg is compressing technical margins and forcing carriers to restructure commission schedules for freight liability programs. Utilization rates below break-even thresholds are driving Munich Re and Allianz SE toward captive underwriting platforms that sustain pricing power through selective risk retention rather than volume competition.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in logistics insurance. Premium tiers attach to Institute Cargo Clauses A coverage with real-time IoT monitoring for pharmaceutical and electronics shippers, while standard tiers cover Named Perils under Clauses B and C for commodity bulk flows. Price differentiation rests on certification grade and after-sales claims service quality. Pricing pressure stems from reinsurance capacity contraction after port congestion losses, with 3PL providers in the Benelux region exhibiting highest price sensitivity due to broker-consolidated procurement, whereas captive-insured manufacturers show lowest sensitivity.
Supply Chain Analysis
Upstream reinsurance capacity draws from Munich, London, and Bermuda as primary retrocession markets for marine cargo lines. Raw material inputs include actuarial data services, IoT telemetry platforms, and blockchain-enabled smart contract middleware. Supply chain risk centers on single-source vulnerability in parametric trigger technology providers. Distribution runs through specialized brokers consolidating third-party logistics procurement rather than direct carrier relationships, with Allianz SE and Chubb Ltd. maintaining differentiated channel positions.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through 3PL provider consolidation in the Benelux region and Germany's Rhine-Ruhr corridor, with contract logistics firms demanding outcome-based coverage tied to delivery performance metrics rather than per-shipment premiums.
For Market Incumbents: Build data moats through captive IoT telemetry platforms that embed real-time cargo monitoring as standard coverage requirements. Integrate blockchain-enabled smart contract middleware to automate parametric claims settlement and defend against technology-integrated entrants. Add underwriting capacity in India's dedicated freight corridors to capture rail-road handoff policies before local carriers scale. For New Entrants and Emerging Players: Build out specialized perishables coverage for cold chain pharmaceutical distribution across Germany's Rhine-Ruhr corridor, where temperature excursion sublimits with real-time monitoring remain underpenetrated. Target drone delivery liability and autonomous trucking coverage where actuarial data scarcity constrains incumbent capacity deployment. Partner with automated warehouse robotics manufacturers to bundle cyber-physical liability at the point of equipment sale. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across parametric trigger technology providers as IoT hardware costs decline and software margins expand. Long-term viability favors carriers with integrated data platforms over retrocession-dependent marine cargo specialists. Acquire technology-integrated underwriters with proven GPS-verified delay clause deployments. Watch for inflection when the EU's CSRD disclosure mandates trigger mandatory insurance documentation requirements across mid-market logistics operators.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Trigger Integration | GPS-verified delay clauses automate claims settlement for container shipping lines through Rotterdam and Hamburg. |
| Cold Chain Coverage Expansion | Temperature-controlled pharmaceutical policies capture Rhine-Ruhr corridor demand with real-time monitoring integration. |
| Captive Underwriting Platform | Munich Re's captive structures sustain pricing power in volatile marine cargo lines amid retrocession tightening. |
| Broker Channel Consolidation | Specialized intermediaries capture 3PL procurement volume as contract logistics firms abandon direct carrier relationships. |
| Cyber-Physical Liability Development | Automated warehouse robotics coverage addresses new intersection of property and technology errors in port automation. |
Methodological Framework
Operator-level perspectives from marine cargo underwriters, freight liability program managers, 3PL procurement directors, and IoT telemetry platform engineers anchored the qualitative base. Primary interviews combined with secondary validation from Institute of London Underwriters filings, EU CSRD disclosure databases, Federal Maritime Commission dockets, and customs trade data. Bottom-up premium pool estimates triangulated against top-down reinsurance market assessments across product type, customer type, and coverage type segmentation dimensions.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific assumptions. The analytical framework modeled transport mode, contract structure, buyer sophistication tier, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from historical premium growth patterns adjusted for reinsurance capacity inflections and parametric technology adoption curves. Forecast inputs included port throughput volumes, CSRD compliance timelines, and cold chain infrastructure investment pipelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by technology-integrated entrants or captive platform specialists would shift outcomes. Cross-checking against Lloyd's List marine cargo premium benchmarks and EU insurance supervisory authority capital adequacy disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Financial Guarantee Market
Insurance
Data Analytics in Insurance Market
Insurance
Russia Property and Casualty Insurance Market
Insurance
Event Insurance Market
Insurance
Greece Property and Casualty Insurance Market
Insurance
Asia-Pacific Critical Illness Insurance Market
Insurance
Germany Reinsurance Market
Insurance
Factory and Warehouse Insurance Market
Insurance
Canada House Insurance Market
Insurance
Business Income Insurance Market
Insurance
US Travel Insurance Market
Insurance
China Property and Casualty Insurance Market
Insurance
Middle East and Africa Travel Insurance Market
Insurance
Djibouti Insurance Market
Insurance
South Africa Property and Casualty Insurance Market
Insurance
Marine Cargo Insurance Market