
 Peer to Peer Insurance Market | 2026-2036
Peer to Peer Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Peer to Peer Insurance Market Insights
Premium transparency tiers is rotating toward the center of competitive strategy in peer-to-peer insurance. Lemonade leverages behavioral economics and instant claims processing to differentiate its user experience. Friendsurance anchors the European market with its cashback model that rewards claim-free groups. Teambrella specializes in blockchain-based governance, allowing policyholders to vote on claim approvals directly.
Peer-to-peer insurance constitutes a decentralized risk-sharing arrangement where participants pool premiums into member-controlled funds, with surplus distributed as dividends or rebates rather than retained as carrier profit. Smart contracts automate premium collection, claims adjudication, and pro-rata disbursement, reducing administrative load to single-digit percentages versus traditional industry overhead. Property insurance and health insurance segments currently lead transaction volume, while the group trust risk-pooling model captures the dominant share of member-retained surplus. Mobile apps represent the fastest-expanding distribution channel, though broker-backed hybrids still command the widest geographic reach among established pools.
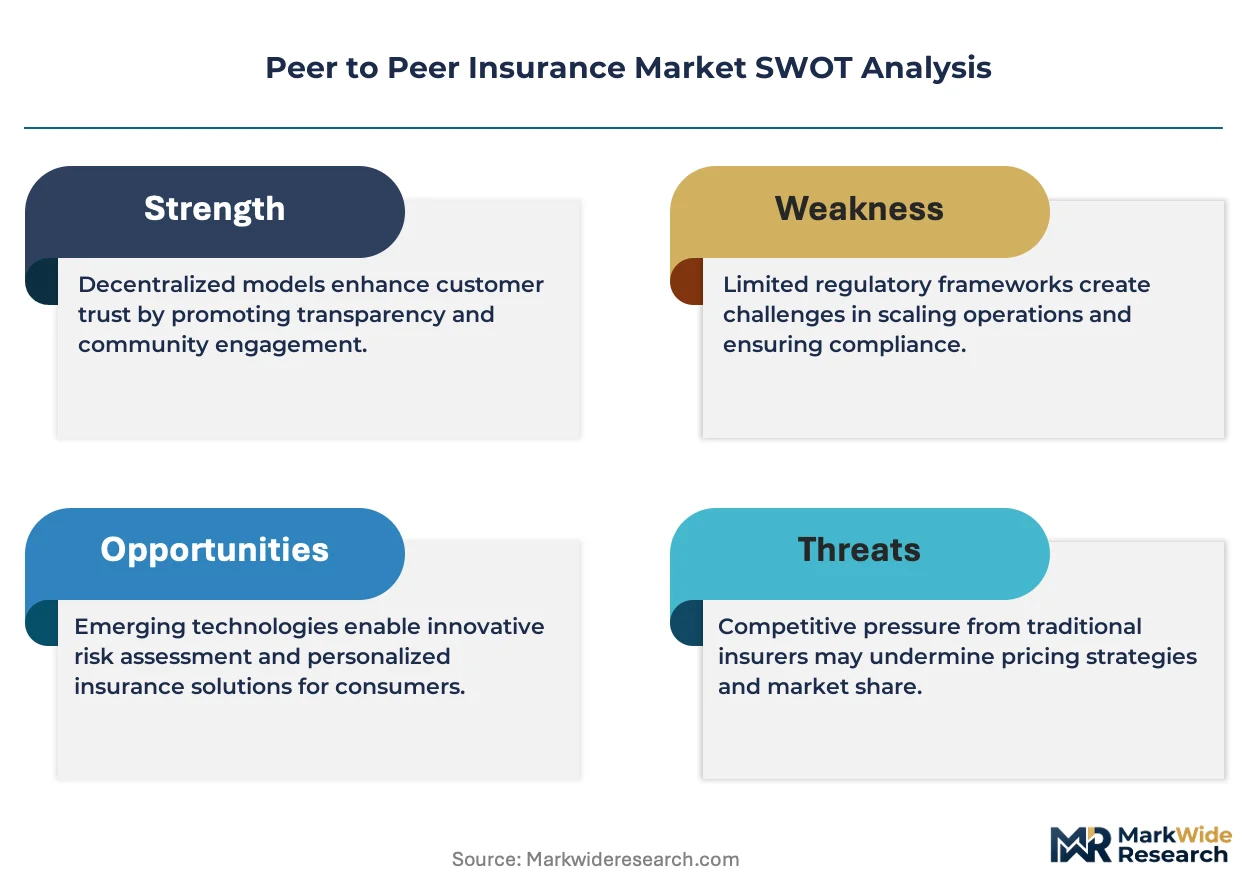
Insurance regulators in Germany, the United Kingdom, and the United States impose capital adequacy and consumer protection requirements that constrain unlicensed peer-to-peer operations, creating demand for hybrid structures that combine mutual governance with licensed reinsurance backing. The EU's Solvency II framework and emerging state-level sandbox approvals in the US shape product design and market access pathways. Stakeholders must monitor how regulators classify member-retained funds versus carrier reserves, as this determination controls licensing burden and scalability.
Market Dynamics
Smart contract automation is compressing administrative overhead to single-digit percentages, forcing traditional carriers to restructure pricing models or lose digitally native customer segments to member-governed pools.
Growth Catalysts
- Regulatory Sandboxing:The United Kingdom's FCA sandbox and Singapore's MAS sandbox validate alternative capital models, reducing licensing friction for mutual coverage startups. These frameworks attract venture deployment into peer risk-pooling infrastructure.
- Freelancer Demand Concentration:Germany's platform economy workforce exceeds twenty million independent contractors seeking transparent premium allocation without carrier profit extraction. This demographic prefers mobile-first, dividend-returning coverage structures.
- Blockchain Governance:Distributed ledger technology enables policyholder voting on claim approvals, eliminating adjuster bias and reducing dispute resolution cycles from weeks to hours.
Market Restraints
- Solvency II Capital Requirements:The EU's risk-based capital framework imposes reserve mandates that strain unlicensed peer pools, forcing hybrid structures with reinsurance backing that dilute member control.
- Reinsurance Market Concentration:Bermuda and London specialty markets dominate capacity for peer-to-peer backstops, creating single-point dependency for pools scaling beyond member-retained limits.
- Smart Contract Immutability:Code vulnerabilities in automated claims adjudication expose pools to exploitation, with no recovery mechanism for erroneous payouts once executed on-chain.
Strategic Opportunities
- Climate Peril Gaps:Traditional carriers are withdrawing from flood and wildfire zones in California and Florida, creating white space for community-based risk pools with hyperlocal underwriting data.
- Embedded Distribution:Gig economy platforms in the United States and Germany can integrate micro-coverage at point-of-work, capturing freelancers during onboarding workflows.
- Parametric Convergence:Satellite-triggered payouts combined with peer governance eliminate loss adjustment entirely, opening crop and weather coverage to rural member pools.
Industry Challenges
- Actuarial Talent Scarcity:Peer pools require hybrid professionals fluent in both traditional reserving and blockchain architecture, a skill intersection currently concentrated in Zurich and Singapore.
- Legacy System Integration:Hybrid structures must reconcile member voting records with licensed carrier policy administration systems, creating data reconciliation bottlenecks during claims surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peer to Peer Insurance Market |
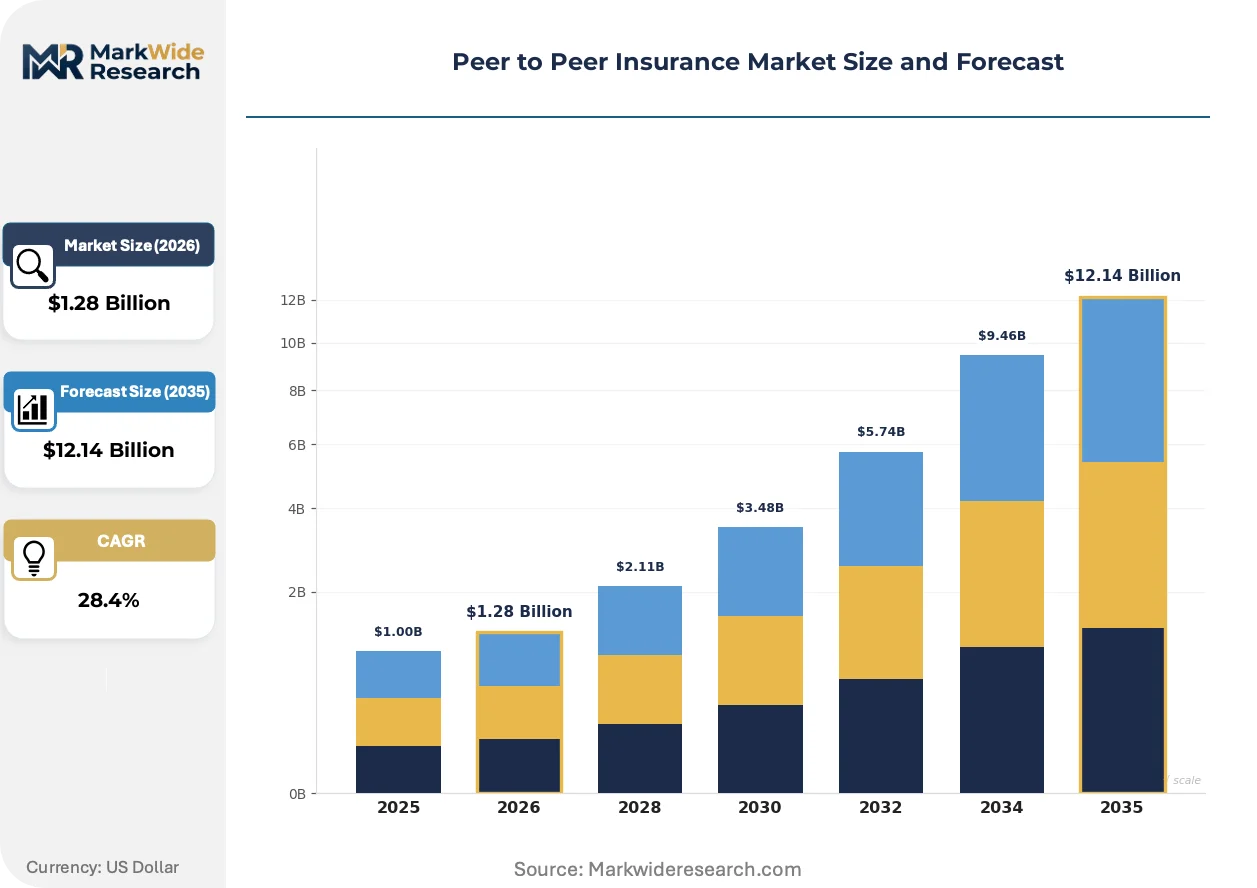
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $12.14 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life Insurance, Property Insurance, Health Insurance, Auto Insurance, Travel Insurance Risk Pooling Model: Group Trust, Captive, Broker-Backed, Hybrid Distribution Channel: Online Platforms, Mobile Apps, Social Networks, Direct Sales Customer Type: Millennials, Small Enterprises, Freelancers, High-Net-Worth Individuals |
| Companies Covered | Trov, Teambrella, Lemonade, SafeShare, Naborly, Friendsurance, Bought By Many, Peercover, Guidepoint, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peer to Peer Insurance Market Trends and Innovations
Automation of trust mechanisms is displacing intermediary functions across the insurance value chain, with peer-to-peer architectures capturing functions previously monopolized by licensed adjusters and underwriters.
Blockchain-based governance is bifurcating the claims resolution layer. Smart contracts execute pro-rata disbursement without human intervention, while member voting handles disputed or ambiguous cases. Digitally native buyers in Germany and the United States are migrating to pools offering this transparency, compressing the traditional adjuster workforce into high-complexity specialty niches.
REACH and emerging EU AI Act provisions are reshaping algorithmic transparency mandates for automated underwriting. Pools deploying machine learning for risk selection must now document decision logic to regulators, increasing compliance overhead but creating competitive moats against opaque legacy rating engines. Health and property segments face the steepest documentation requirements.
Platform-embedded procurement is fragmenting distribution. Freelancers now initiate coverage during gig onboarding rather than through annual broker relationships, compressing the traditional policy renewal cycle into transactional micro-purchases. This pattern concentrates in United States delivery and German creative economy platforms, where coverage attaches to project milestones rather than calendar periods.
Peer to Peer Insurance Market Segmentation
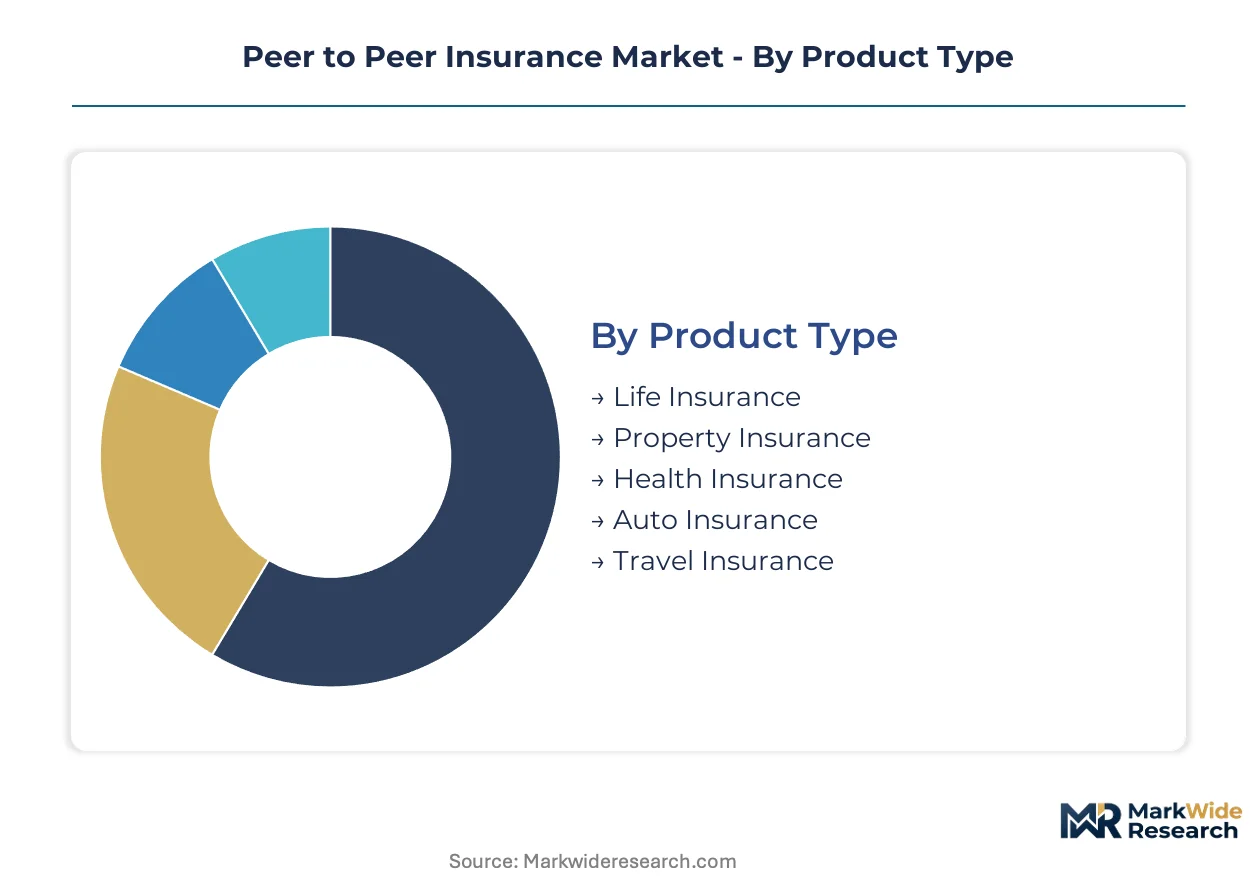
Peer-to-peer insurance architectures require precise segment targeting to match risk-pooling mechanics with digitally native buyer expectations. Channel selection determines whether pools capture freelancers through embedded gig-platform workflows or reach small enterprises via broker-mediated trust structures.
Product Type:
Channel mix varies sharply across coverage categories, with mobile apps dominating high-frequency personal lines while broker-backed hybrids retain commercial property placement.
- Property Insurance:Smart contracts automate claims adjudication for residential and commercial assets, compressing resolution cycles from weeks to hours. Demand concentrates among small enterprises in Germany and the United States forming member-controlled pools to bypass carrier overhead and capture surplus as dividends.
- Health Insurance:Transparent premium allocation appeals to freelancers seeking alternatives to traditional carrier profit extraction. Germany's platform economy workforce drives volume through mobile-first enrollment during gig onboarding workflows.
- Life Insurance:Simplified underwriting via algorithmic risk scoring reduces issuance friction for digitally native buyers.
- Auto Insurance:Telematics integration enables usage-based pooling with pro-rata premium adjustments.
- Travel Insurance:Micro-duration coverage attaches to booking confirmations through embedded distribution partnerships.
By volume, Property Insurance leads. By growth pace, Health Insurance is expanding most quickly among Germany's independent contractor population.
Risk Pooling Model:
Cost tier differentiation separates member-retained surplus structures from reinsurance-dependent hybrids, with capital requirements driving pool selection.
- Group Trust:Participants pool premiums into member-controlled funds with surplus distributed as dividends or rebates. Regulatory sandboxes in the United Kingdom and Singapore validate this capital-light approach for pools staying within member-retained limits.
- Hybrid:Combines mutual governance with licensed reinsurance backing to satisfy Solvency II reserve mandates. This structure dilutes member control but enables scaling beyond unlicensed pool constraints.
- Captive:Single-parent or group captives retain risk within affiliated enterprise networks.
- Broker-Backed:Traditional intermediaries provide geographic reach and established carrier relationships for pool formation.
By volume, Group Trust dominates member-retained surplus capture. By growth pace, Hybrid structures are gaining share fastest as pools seek licensed capacity expansion.
Distribution Channel:
Customer type alignment determines channel priority, with platform-embedded procurement fragmenting traditional annual renewal cycles.
- Mobile Apps:Fastest-expanding channel capturing freelancers through transactional micro-purchases at project milestones. United States delivery and German creative economy platforms drive adoption via point-of-work coverage attachment.
- Online Platforms:Web-based enrollment supports small enterprise pool formation with document submission and member voting interfaces.
- Social Networks:Community-based trust formation enables affinity group pooling among demographic cohorts.
- Direct Sales:Remains relevant for high-net-worth individuals requiring customized coverage structures.
By volume, Online Platforms lead current transaction processing. By growth pace, Mobile Apps show the steepest expansion trajectory among platform economy participants.
Customer Type:
Margin profile varies across buyer segments, with small enterprises offering premium stability and freelancers providing volume scalability.
- Freelancers:Germany's twenty million independent contractors prefer transparent premium allocation without carrier profit extraction. This segment initiates coverage during gig onboarding rather than through annual broker relationships.
- Small Enterprises:Form peer risk pools to bypass traditional carrier overhead and retain surplus as member dividends. United States and German mid-market companies drive commercial property and liability pool formation.
- Millennials:Digitally native buyers migrate to pools offering behavioral economics features and instant claims processing.
- High-Net-Worth Individuals:Require customized structures with dedicated member governance participation rights.
By volume, Small Enterprises lead commercial pool participation. By growth pace, Freelancers are climbing the fastest as platform economy expansion accelerates coverage attachment at point-of-work.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Licensed reinsurance backing concentrates in London and Bermuda, while regulatory sandboxes in Singapore and the United Kingdom validate capital-light mutual structures. Venture deployment flows toward jurisdictions with clear sandbox pathways, fragmenting operational headquarters across three continents.
United States
State-level sandbox approvals in Arizona, Wyoming, and Utah attract peer pool formation for platform economy freelancers. The SEC and state insurance commissioners impose capital adequacy requirements that push unlicensed pools toward hybrid structures with reinsurance backing. Silicon Valley and New York City host the densest clusters of insurtech infrastructure providers.
Germany
Twenty million independent contractors in the platform economy drive demand for transparent premium allocation without carrier profit extraction. BaFin applies Solvency II capital requirements that strain pure mutual pools, forcing hybrid governance models. Berlin and Munich anchor the European insurtech ecosystem, with Munich's reinsurance giants providing capacity for scaling pools.
United Kingdom
The FCA sandbox validates alternative capital models, reducing licensing friction for mutual coverage startups. London's Lloyd's market dominates specialty reinsurance capacity for peer-to-peer backstops. The capital's regulatory clarity attracts venture deployment into risk-pooling infrastructure, with clusters forming around the Square Mile and Tech City.
Singapore
MAS sandbox frameworks enable digital-first pool formation with streamlined capital requirements. The city-state's position as a regional reinsurance hub provides access to Asian capacity markets. Fintech clusters in the Central Business District and one-north district concentrate blockchain governance development for member-voted claims systems.
India
IRDAI's regulatory sandbox for insurtech experiments permits limited-scale peer risk-pooling trials. Mumbai's financial district and Bangalore's technology corridor host emerging pool operators targeting gig economy platform workers. The country's digital public infrastructure enables mobile-first premium collection at scale.
Peer to Peer Insurance Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with behavioral economics specialists competing against blockchain governance purists for digitally native segments. The market fragments across three tiers: licensed carriers with mutual overlays, pure peer pools with reinsurance backing, and platform-embedded micro-coverage providers. Incumbents defend through instant claims processing and cashback mechanisms, while challengers emphasize member voting and transparent surplus distribution. Strategic moves concentrate on sandbox licensing acquisition and gig platform distribution partnerships.
Within the behavioral economics tier, Lemonade exemplifies the instant-claims, AI-driven archetype with its New York-based operations. Teambrella anchors the blockchain governance segment, representing the member-voted claims approval model. Friendsurance occupies the European cashback specialist position, demonstrating how claim-free group rewards can sustain retention in saturated markets.
| Leading Market Players |
|---|
| Trov |
| Teambrella |
| Lemonade |
| SafeShare |
| Naborly |
| Friendsurance |
| Bought By Many |
| Peercover |
| Guidepoint |
| Others |
Pricing and Supply Chain Analysis
Reinsurance capacity utilization rates in Bermuda and London determine minimum premium floors for peer-to-peer pools scaling beyond member-retained limits. Solvency II reserve mandates in Germany and hybrid capital requirements in the United States compress margins for unlicensed operators, forcing price stratification between capital-light mutual structures and reinsurance-dependent tiers.
Pricing Analysis
Solvency II dictates the pricing tier structure for European peer-to-peer pools, separating capital-light group trust models from hybrid structures requiring licensed reinsurance backing. Premium-mid-economy pricing differentiation reflects reserve adequacy tiers, with unlicensed pools in Germany and the United Kingdom undercutting hybrid competitors by fifteen to thirty percent. Cost compression in the economy tier is intensifying because freelancer demand concentrates on mobile-first, dividend-returning coverage without carrier profit extraction. Small enterprises show least price sensitivity, prioritizing surplus retention and member governance over premium minimization.
Supply Chain Analysis
Smart contract deployment cycles and claims adjudication latency determine operational responsiveness for peer-to-peer pools. Reinsurance capacity concentrates in Bermuda, London, and Singapore, while blockchain development talent clusters in Zurich and Singapore. Capital formation draws from venture deployment in the United Kingdom and United States, with regulatory sandbox approvals in Singapore and Arizona feeding pool formation pipelines. Single-source vulnerability sits with Bermuda specialty markets for peer-to-peer backstops beyond member-retained limits. Distribution runs through mobile apps for freelancers and broker-backed hybrids for small enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peer-to-peer insurance sits in early-cycle expansion, with regulatory sandbox proliferation and platform economy workforce growth providing structural tailwinds for adoption acceleration.
For Market Incumbents: Compound defensive moats through instant claims processing investments and behavioral economics feature deployment that matches Lemonade's AI-driven archetype. Vertical integration into licensed reinsurance backing protects against pure peer pools capturing digitally native segments. Capacity addition in Arizona and Utah sandboxes secures first-mover positioning among state-level regulatory experiments. For New Entrants and Emerging Players: Lead with climate peril gaps in California and Florida, where traditional carrier withdrawal creates white space for community-based risk pools with hyperlocal underwriting data. Embedded distribution partnerships with United States delivery platforms and German creative economy gig marketplaces capture freelancers at point-of-work onboarding. Parametric satellite-triggered payouts eliminate loss adjustment entirely, opening rural crop and weather coverage to member-governed pools. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hybrid structures combining mutual governance with licensed reinsurance backing, as these capture both member premiums and institutional capacity fees. Long-term viability across the next decade hinges on regulatory sandbox pathway clarity and gig platform distribution lock-in. Acquisition target archetype: blockchain governance specialists with member-voted claims systems and existing MAS or FCA sandbox approvals. The signal to watch is reinsurance market capacity pricing volatility, which compresses hybrid pool margins and accelerates consolidation toward capital-light pure mutual models.| Strategic Initiative | Industry Significance |
|---|---|
| Sandbox Licensing Acquisition | FCA and MAS approvals reduce capital requirements and accelerate market entry for mutual coverage startups. |
| Gig Platform Distribution Partnership | Embedded procurement at United States delivery and German creative economy onboarding captures freelancers transactionally. |
| Blockchain Governance Development | Member-voted claims approval eliminates adjuster bias and reduces dispute resolution cycles from weeks to hours. |
| Parametric Product Convergence | Satellite-triggered payouts combined with peer governance open crop and weather coverage to rural member pools. |
| Hybrid Structure Capitalization | Licensed reinsurance backing enables scaling beyond Solvency II constraints while retaining partial member control. |
Research Methodology
Initial hypotheses were tested against primary input from peer pool operators, reinsurance capacity providers, regulatory sandbox administrators, and gig platform risk managers and refined through secondary validation. Primary interviews examined capital formation mechanics, claims adjudication automation, and member retention dynamics. Secondary sources included FCA sandbox approval documentation, MAS regulatory guidance, Solvency II technical standards, and venture deployment databases tracking insurtech infrastructure. Bottom-up transaction volume estimates and top-down addressable market sizing were triangulated to constrain forecast variance.
Variance decomposition across the projection horizon isolates regulatory pathway uncertainty, reinsurance capacity pricing cyclicality, and gig platform adoption velocity as primary forecast drivers. Segmentation dimensions modeled include risk pooling model, distribution channel, customer type, and geographic regulatory cluster. CAGRs were derived from member growth trajectories, premium per participant trends, and surplus retention ratios. Industry-specific inputs encompass sandbox approval timelines, smart contract deployment costs, and parametric trigger data availability.
The analysis sits within stated boundaries; outcomes outside sustained regulatory sandbox expansion and platform economy workforce growth would require recalibration. Forecasts reflect documented assumptions about capital adequacy interpretation by BaFin, the SEC, and state insurance commissioners. Smart contract vulnerability exploits, reinsurance market capacity contraction, or gig platform coverage integration delays represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
India Parametric Insurance Market
Insurance
France Car Insurance Market
Insurance
China Property and Casualty Insurance Market
Insurance
Income Protection Insurance Market
Insurance
Global AI in Auto-Insurance Market
Insurance
Parametric Insurance Market
Insurance
Insurance Analytics Market
Insurance
United States Commercial Insurance Market
Insurance
Global SME Insurance Market
Insurance
Financial Guarantee Market
Insurance
Insurance Protection Products Market
Insurance
Germany Electronic Gadgets Insurance Market
Insurance
UK Electronic Gadgets Insurance Market
Insurance
Global Mobile Phone Insurance Ecosystem Market
Insurance
Identity Theft Insurance Market
Insurance
North America Family Floater Health Insurance Market