
 Liability Insurance Market | 2026-2036
Liability Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Liability Insurance Market Outlook
NAIC accreditation is reorganizing competitive access for cross-state carriers. Chubb Limited leverages its global underwriting platform to dominate high-limit commercial accounts. Allianz SE anchors European liability portfolios through specialized industrial coverage. CNA Financial Corporation competes in professional liability with sector-specific policy architectures.
Liability insurance is a risk-transfer contract indemnifying policyholders against legal obligations arising from third-party bodily injury, property damage, or financial loss, with coverage limits, retention structures, and claims-made or occurrence triggers defining contractual performance. The policy term dimension shows short-term contracts capturing event-driven demand while multi-year agreements sustain insurer cash flow predictability. Coverage type segmentation reveals cyber liability as the fastest-expanding pool, though general liability retains the largest premium base. Client type distribution concentrates margin in corporate accounts, with small businesses representing the most price-sensitive expansion segment.
US state insurance commissioners, the EU's EIOPA framework, and the UK's Prudential Regulation Authority each enforce capital adequacy and consumer protection standards that directly shape product design and distribution licensing. The EU's Digital Operational Resilience Act and emerging US SEC climate disclosure rules are expanding the perimeter of insurable regulatory risk. Stakeholders must monitor how algorithmic underwriting tools interact with evolving fair-lending and anti-discrimination enforcement across multiple jurisdictions.
Market Dynamics
Litigation frequency against healthcare providers and technology firms is compressing policy renewal cycles while forcing carriers to reprice coverage tiers more aggressively than historical loss-cost models anticipate.
Growth Catalysts
- EU Digital Operational Resilience Act:Financial services firms across the European Union must now carry explicit cyber liability minimums, creating immediate coverage procurement mandates for banks, insurers, and payment processors.
- Healthcare litigation surge:Patient malpractice claims in the United States are rising faster than medical inflation, compelling hospital systems and physician groups to expand umbrella policy limits.
- Cloud infrastructure concentration:Single points of failure at hyperscale providers are generating systemic risk awareness, driving enterprise buyers toward standalone technology errors-and-omissions coverage.
Market Restraints
- Reinsurance capacity tightening:Natural catastrophe losses and social inflation are reducing retrocession availability, pushing primary carriers to retain more risk or withdraw from high-severity lines.
- Social inflation in US jurisdictions:Nuclear verdicts in Florida, Texas, and California state courts are rendering general liability pricing inadequate for commercial auto and construction accounts.
- Long-tail asbestos and environmental reserves:Legacy pollution and product liability claims continue draining capital from mature books, constraining capacity deployment into emerging cyber and climate lines.
Strategic Opportunities
- Parametric liability triggers:Index-based settlement mechanisms using verified data feeds are reducing claims adjustment friction for business interruption and cyber downtime events.
- Mid-market broker digitization:Independent agents serving small commercial accounts lack sophisticated risk quantification tools, creating white space for embedded coverage APIs.
- Climate litigation carve-outs:Directors-and-officers policies excluding fossil fuel transition exposure are opening specialized coverage products for renewable energy developers and carbon credit traders.
Industry Challenges
- Actuarial talent scarcity:Cyber risk modeling requires data science competencies that traditional casualty actuarial pipelines fail to produce, forcing carriers to compete with technology firms for quantitative analysts.
- Legacy policy administration systems:Mainframe-based claims platforms at established insurers cannot ingest real-time telemetry from IoT devices, delaying usage-based pricing deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liability Insurance Market |
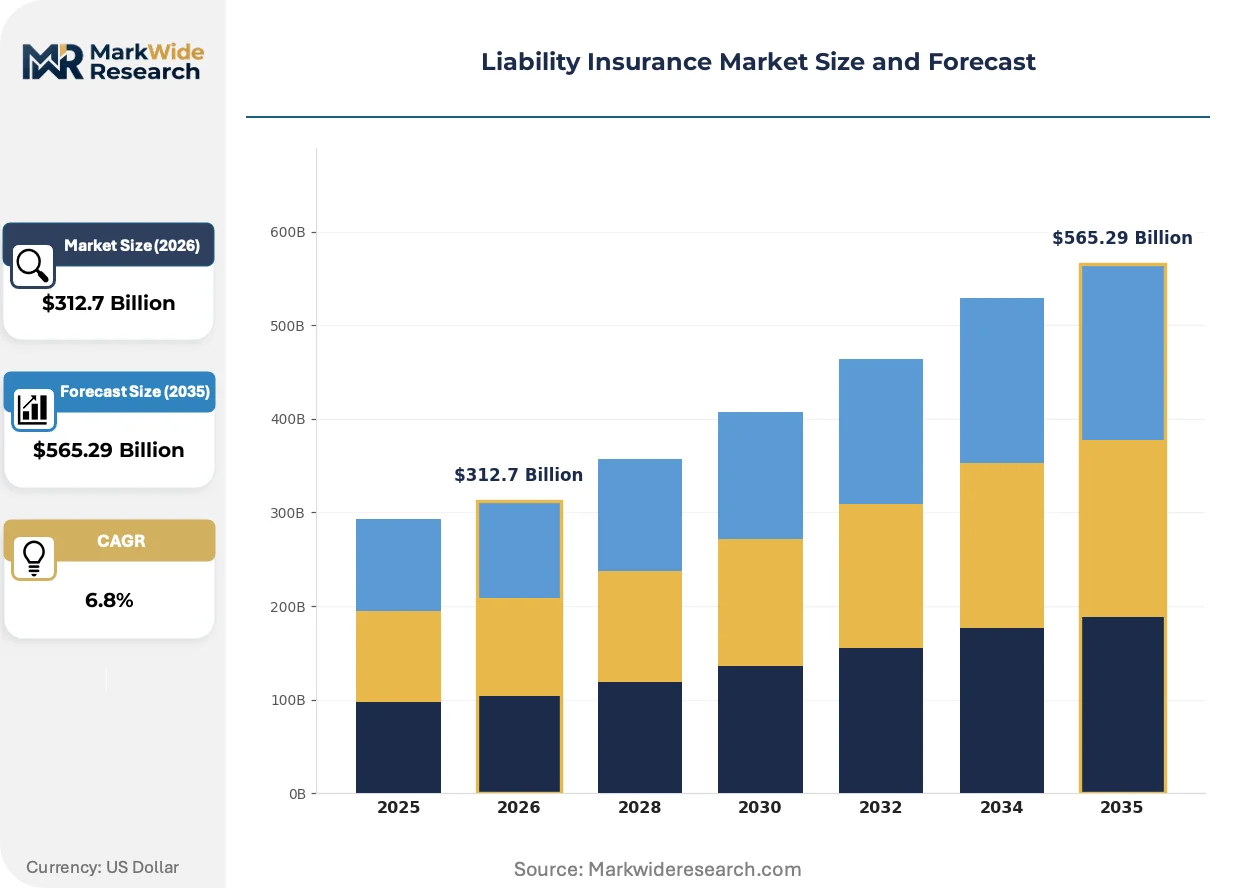
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: General Liability, Professional Liability, Product Liability, Cyber Liability Policy Term: Short-Term, Long-Term, Annual, Multi-Year Client Type: Individuals, Small Businesses, Corporations, Nonprofits Claim Type: Third-Party Claims, First-Party Claims, Class Action, Property Damage |
| Companies Covered | American International Group Inc., Allianz SE, Chubb Limited, AXA SA, CNA Financial Corporation, The Hartford Financial Services Group Inc., The Travelers Companies Inc., Zurich Insurance Group, Munich Re, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liability Insurance Market Strategic Shifts
Algorithmic underwriting and continuous risk monitoring are displacing static annual policy reviews, compressing the feedback loop between exposure accumulation and rate adjustment.
Telematics-enabled commercial auto coverage is miniaturizing risk assessment granularity to individual vehicle-hour operations. Fleet operators now transmit engine diagnostics and driver behavior data to carriers, who adjust premiums monthly rather than annually. This compression of rating periods is miniaturizing the traditional policy-year concept into rolling exposure units.
The SEC's proposed climate disclosure rules are mandating registrants to quantify and report Scope 3 liability exposures. Public companies must now model litigation risk from supply chain emissions, driving demand for specialized D&O endorsements. Manufacturing and energy extraction sectors are responding by pre-purchasing decade-long defense cost caps.
Mid-sized commercial buyers are consolidating procurement through digital brokerage platforms that disintermediate traditional agent relationships. These aggregators standardize coverage terms across competing carriers, forcing price transparency on previously opaque policy comparisons. The shift is most visible in United States metropolitan markets where small business density supports platform economics.
Liability Insurance Market Segmentation
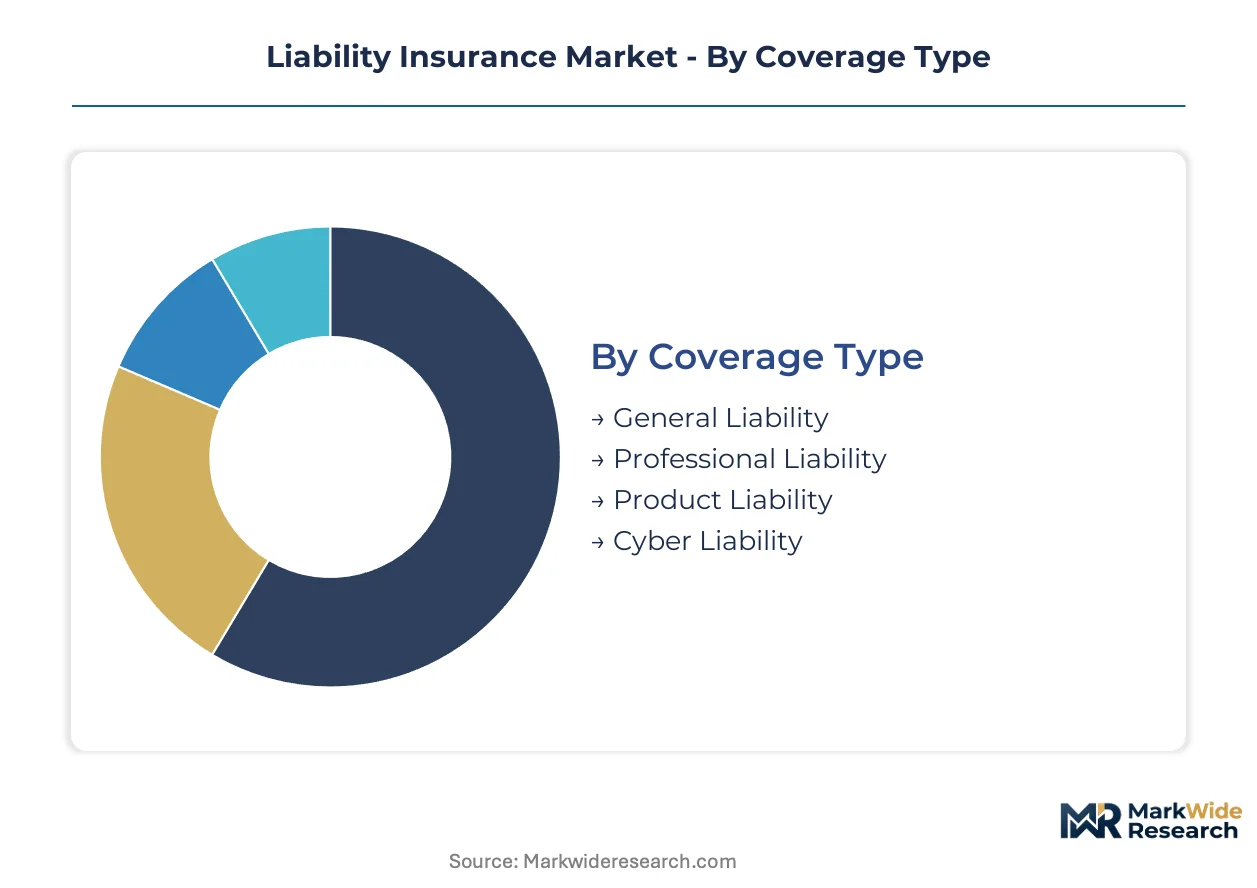
Liability insurers price risk through granular segment stratification, where coverage triggers, policy duration, and claimant categories each reshape capital allocation and underwriting margin. Segmentation precision determines whether carriers retain exposure or cede to reinsurance markets.
Coverage Type:
Regulatory mandates from the SEC, EU's Digital Operational Resilience Act, and state insurance commissioners create divergent capital requirements across coverage lines, forcing product-level reserving discipline.
- General Liability:Bodily injury and property damage protection for commercial premises and operations. Construction firms and retail chains in Texas and Florida drive volume as social inflation elevates nuclear verdict exposure. The segment absorbs the largest share of industry premium dollars.
- Professional Liability:Errors-and-omissions coverage for service providers including physicians, attorneys, and consultants. Hospital systems in California and New York expand policy limits faster than medical inflation as patient litigation accelerates. This line commands the highest rate-per-dollar of limit among traditional casualty products.
- Cyber Liability:Network security failure and data breach response coverage mandated under DORA for EU financial institutions. Regulatory procurement floors now apply to banks, insurers, and payment processors across the European Union.
- Product Liability:Manufacturing defect and failure-to-warn coverage for tangible goods. Automotive suppliers and medical device manufacturers face renewed scrutiny from FDA adverse event reporting requirements.
General Liability handles the majority of throughput; Cyber Liability is expanding most quickly on share as regulatory mandates compound.
Policy Term:
Duration selection directly impacts insurer cash flow predictability and policyholder retention economics, with longer terms locking in rate adequacy but constraining repricing flexibility.
- Annual:Standard one-year contracts with guaranteed renewable provisions. Small commercial buyers in United States metropolitan markets prefer this structure for budget certainty and competitive quoting.
- Multi-Year:Two-to-five year agreements with rate caps or inflation adjusters. Large corporations pre-purchase defense cost coverage to hedge against social inflation in California and Florida state courts.
- Short-Term:Event-specific coverage for construction projects, film productions, and special events. Project owners in Texas and New York mandate these for contract compliance.
- Long-Term:Decade-plus agreements for environmental impairment and asbestos exposure. Legacy pollution claims continue draining reserves from mature books written decades prior.
Annual policies dominate transaction count; Multi-Year agreements are climbing the fastest as risk managers seek rate stability.
Client Type:
Purchasing sophistication and price elasticity diverge sharply across client tiers, with corporate risk managers demanding bespoke coverage architectures while small businesses prioritize premium minimization.
- Corporations:Fortune 1000 entities with captive insurance subsidiaries and dedicated risk management departments. These buyers negotiate manuscript policy language and aggregate deductible structures.
- Small Businesses:Main Street enterprises with limited risk quantification capabilities. Independent agents serving this segment lack sophisticated tools, creating white space for embedded coverage APIs.
- Nonprofits:Charitable organizations and educational institutions with volunteer exposure and donor-imposed insurance requirements. Directors-and-officers coverage is typically mandatory by board charter.
- Individuals:Personal umbrella and professional liability for sole practitioners. Physicians and attorneys in high-litigation jurisdictions purchase excess limits above primary homeowners or business owners policies.
Corporations contribute the largest premium volume; Small Businesses are gaining share fastest as digital distribution platforms reduce friction.
Claim Type:
Resolution mechanics and reserve development patterns vary dramatically by claimant structure, with class actions and first-party disputes demanding specialized claims handling expertise.
- Third-Party Claims:Allegations from external parties alleging injury or damage caused by the insured. General liability and commercial auto carriers in Florida face the steepest frequency elevation from plaintiff bar advertising.
- Class Action:Aggregated litigation with hundreds or thousands of similarly situated claimants. Product liability and securities litigation in California and New York federal courts drive the largest severity outcomes.
- First-Party Claims:Direct reimbursement requests from policyholders under cyber and property-allied liability endorsements. Business interruption from cloud provider outages now triggers these provisions.
- Property Damage:Physical destruction claims often subrogated against contractors or manufacturers. Construction defect litigation in Texas and California generates the longest-tail reserve development.
Third-Party Claims absorb the greatest claims handling capacity; Class Action is the fastest mover on severity-adjusted reserve requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence across major economies is fragmenting underwriting standards and creating localized capacity shortages. State-level tort reform debates in the United States, EU-wide cyber mandates, and emerging climate disclosure requirements are each reshaping regional demand patterns.
United States
Hospital systems and physician groups in California, Texas, and Florida are expanding umbrella policy limits as patient litigation accelerates. State insurance commissioners in high-verdict jurisdictions enforce capital adequacy standards that constrain carrier participation. The New York and Boston metro corridors concentrate professional liability purchasing from law firms and consulting practices.
Germany
Industrial manufacturers in Baden-Württemberg and Bavaria are procuring specialized product liability coverage amid renewed FDA-equivalent scrutiny of automotive suppliers. The EU's Digital Operational Resilience Act mandates explicit cyber minimums for Frankfurt-based financial institutions. Munich anchors continental reinsurance capacity that retrocedes primary carrier risk.
United Kingdom
City of London brokers are structuring climate litigation carve-outs for renewable energy developers facing transition exposure. The Prudential Regulation Authority enforces capital buffers that shape D&O policy architecture for FTSE registrants. Lloyd's syndicates concentrate specialty liability underwriting for international construction and energy projects.
France
AXA SA and other Paris-based carriers anchor European liability portfolios through industrial coverage specialization. The country's national pharmaceutical regulator intensifies adverse event reporting requirements for medical device manufacturers. Île-de-France hosts the continent's densest concentration of corporate risk management departments.
Japan
Tokyo-based electronics manufacturers are purchasing standalone technology errors-and-omissions coverage as cloud concentration risks mount. METI guidelines on operational resilience influence cyber liability procurement floors for financial institutions. The Kansai corridor around Osaka concentrates manufacturing liability demand from automotive and machinery exporters.
Liability Insurance Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and geographic reach. The market structures around tiered capacity deployment, with global platforms dominating high-limit commercial accounts and regional mutuals retaining local small-business relationships. Three archetypes prevail: diversified multi-line carriers with reinsurance integration, mono-line professional liability specialists, and broker-owned managing general agents. Dominant competitive moves include portfolio diversification into cyber and climate lines and strategic partnerships with insurtech platforms for mid-market distribution.
Within the global platform tier, Chubb Limited and Allianz SE exemplify scale-driven underwriting architecture, while CNA Financial Corporation occupies a position among professional liability specialists. Chubb leverages its cross-border licensing to serve Fortune 1000 accounts with manuscript policy language. Allianz anchors European industrial portfolios through specialized coverage units. CNA competes in sector-specific architectures for healthcare and legal professionals.
| Leading Market Players |
|---|
| American International Group Inc. |
| Allianz SE |
| Chubb Limited |
| AXA SA |
| CNA Financial Corporation |
| The Hartford Financial Services Group Inc. |
| The Travelers Companies Inc. |
| Zurich Insurance Group |
| Munich Re |
| Others |
Value Chain & Pricing Dynamics
NAIC accreditation standards gate both carrier licensing across US states and the price differentiation that cross-state underwriters command against single-state mutuals. This dual-gating mechanism concentrates margin with carriers holding multi-jurisdictional capital reserves while compressing returns for regional specialists lacking scale.
Pricing Analysis
Certification level (NAIC accreditation versus state-only licensing) creates the primary spread between premium tiers. The market operates on a contract-based long-term structure with annual renewable provisions dominating small commercial accounts and multi-year agreements locking in rates for Fortune 1000 captives. Price differentiation rests on reinsurance access quality and claims-made versus occurrence trigger selection, with cyber liability endorsements commanding the steepest quality premium. Pricing pressure stems from social inflation in Florida and California state courts, where nuclear verdicts outpace historical loss-cost models. Small businesses exhibit the highest price sensitivity, while corporate risk managers prioritize coverage architecture over premium minimization.
Supply Chain Analysis
The United States and Germany anchor primary carrier capital formation, while Bermuda and London supply retrocession capacity for catastrophe-exposed lines. Raw material dependencies include actuarial talent pipelines from university programs, proprietary risk models from insurtech vendors, and legal defense networks in high-litigation jurisdictions. Supply chain risk centers on single-source vulnerability in cyber risk modeling expertise, where carriers compete with technology firms for quantitative analysts. Distribution runs through independent agency networks for small commercial accounts and direct brokerage relationships for corporate placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liability insurance market rewards carriers possessing both legacy claims data reservoirs and real-time telemetry ingestion capabilities, yet few incumbents bridge this dual competency gap. Underwriting sophistication now separates viable competitors from capacity-constrained followers.
For Market Incumbents: Secure exclusive data partnerships with telematics providers and IoT platform operators to compress rating cycles before insurtech challengers achieve scale. Defend against algorithmic underwriting entrants by accelerating mainframe migration to cloud-native policy administration systems. Prioritize captive supply of actuarial talent through university pipeline investments rather than competing with technology firms for lateral hires.
For New Entrants and Emerging Players: Lead with embedded coverage APIs targeting independent agents serving price-sensitive small commercial accounts in United States metropolitan markets. The mid-market broker digitization gap offers the most penetrable white space, with standardized coverage terms forcing transparency on previously opaque policy comparisons. Deploy parametric liability triggers using verified data feeds to reduce claims adjustment friction and differentiate against legacy carriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cyber liability lines as regulatory procurement floors expand under EU DORA and emerging US SEC climate disclosure rules. Target acquisition archetypes include mono-line professional liability specialists with healthcare sector concentration and insurtech platforms possessing mid-market distribution infrastructure. The signal to watch is reinsurance capacity tightening in natural catastrophe-exposed lines, which will force primary carrier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Reinsurance Partnership Structuring | Munich Re and London syndicates retrocede primary carrier risk amid capacity constraints. |
| Cyber Liability Portfolio Buildout | EU DORA mandates explicit minimums for Frankfurt-based financial institutions. |
| Parametric Trigger Development | Index-based settlements reduce adjustment friction for cloud downtime events. |
| Mid-Market Broker Digitization | Embedded coverage APIs capture price-sensitive small commercial expansion. |
| Climate Litigation Carve-Out Design | Specialized D&O products address renewable energy transition exposure. |
Study Parameters
The analysis maps general liability, professional liability, cyber liability, and product liability segments, each validated through underwriters, claims executives, reinsurance brokers, and regulatory affairs specialists. Primary interviews with carrier actuarial directors and independent agency principals combined with secondary validation from NAIC financial statement databases, SEC 10-K insurance disclosures, Lloyd's market returns, and EU EIOPA regulatory filings. Bottom-up policy-level data triangulated against top-down premium aggregation across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including reinsurance broker market sizing and regulatory premium tax filings. The analytical framework modeled coverage type, policy term duration, client tier, and claim structure dimensions throughout the forecast period. CAGRs derived from loss-cost trend analysis, regulatory mandate timing, and litigation frequency projections. Industry-specific inputs included social inflation indices for high-verdict US jurisdictions and cyber incident frequency curves from financial services reporting.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of cyber minimums or tort reform passage in high-verdict states would require recalibration. Forecasts reflect documented assumptions about litigation frequency, reinsurance capacity availability, and actuarial talent supply elasticity. Recalibration cycles align with material shifts in EU DORA implementation timelines and US state-level nuclear verdict trends.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Event Insurance Market
Insurance
United Kingdom Car Insurance Market
Insurance
Self Funded Insurance Market
Insurance
Embedded Insurance Market
Insurance
France Car Insurance Market
Insurance
Marine Cargo Insurance Market
Insurance
Marine Crew Insurance Market
Insurance
Netherlands Property and Casualty Insurance Market
Insurance
Social Media Analytics-Based Insurance Market
Insurance
United States Dental Insurance Market
Insurance
Australia Parametric Insurance Market
Insurance
Norway Property and Casualty Insurance Market
Insurance
Data Analytics in Insurance Market
Insurance
Specialty Insurance Market
Insurance
India Online Insurance Market
Insurance
Global Healthcare Claims Management Market