
 UK Electronic Gadgets Insurance Market | 2026-2036
UK Electronic Gadgets Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
UK Electronic Gadgets Insurance Market Analytics
Market Context with Strategic Players
FCA authorisation under the Consumer Duty regime is rotating the competitive set toward firms with stronger compliance infrastructure. Axa (Inter Partner Assistance SA) leverages its pan-European claims network to sustain pricing power across multi-device household policies. Aviva Insurance Ltd anchors its position through direct distribution dominance and proprietary risk-scoring algorithms. Assurant General Insurance Limited differentiates via embedded partnerships with mobile network operators, controlling the point-of-sale insurance attachment rate.
Technical Definition and Structural Segments
UK electronic gadgets insurance constitutes a regulated non-life product covering repair, replacement, or indemnity for portable electronic devices against named perils, with policies typically specifying excess thresholds between £25 and £150 and claim limits tied to original device retail value. The primary commercial purpose is to transfer residual value risk from consumers to underwriters while smoothing lifetime ownership costs across high-depreciation technology assets. Smartphones command the largest premium pool within product type segmentation, though wearables represent the fastest-growing risk category as health-integrated devices proliferate. Annual policy duration structures dominate volume, yet monthly subscriptions capture younger demographics through lower entry barriers and app-based claims servicing.
Regulatory Framework and Forward Outlook
The Financial Conduct Authority enforces Consumer Duty standards requiring fair value demonstration, while the Financial Ombudsman Service adjudicates disputes that shape precedent on claims handling practices. The Prudential Regulation Authority's capital reserving rules for general insurers directly influence pricing floors and market entry feasibility for new underwriting entrants. Stakeholders must monitor how the FCA's forthcoming guidance on embedded insurance distribution reshapes commission structures and partner channel economics.
Market Dynamics
The Financial Conduct Authority's Consumer Duty regime is compressing profit margins while forcing infrastructure investment across underwriting operations, fundamentally restructuring how insurers demonstrate fair value to policyholders.
Growth Catalysts
- Student device dependency:University coursework now requires persistent connectivity, expanding the addressable pool of young policyholders seeking affordable coverage for laptops, tablets, and smartphones.
- FCA Consumer Duty implementation:Enhanced transparency requirements are accelerating consumer trust rebuilding, reducing policy cancellation rates among previously skeptical demographics.
- London gadget density concentration:The capital's professional workforce carries multiple high-value devices daily, sustaining premium pricing power for multi-device household policies.
Market Restraints
- Component supply volatility:Semiconductor fabrication constraints in East Asia create repair cost uncertainty that undermines actuarial pricing precision for screen replacement claims.
- Embedded distribution lock-in:Mobile network operators control point-of-sale attachment through exclusive partnerships, limiting direct-to-consumer channel expansion for independent underwriters.
- Depreciation curve steepness:Rapid smartphone obsolescence compresses the viable policy duration window, constraining lifetime customer value calculations.
Strategic Opportunities
- Wearables health integration:Fitness trackers and medical monitoring devices present untapped premium pools as users seek coverage for health-critical technology investments.
- Monthly subscription models:App-based policy management and lower entry barriers capture younger demographics previously excluded by annual commitment requirements.
- South East regional expansion:Affluent commuter belts surrounding London show elevated gadget ownership rates with underdeveloped specialist insurance penetration.
Industry Challenges
- Claims fraud detection capability:Sophisticated staged damage schemes strain verification systems, requiring investment in AI-powered image authentication.
- Legacy core system integration:Established insurers struggle to embed real-time policy adjustments and instant claims settlement within decades-old policy administration platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Electronic Gadgets Insurance Market |
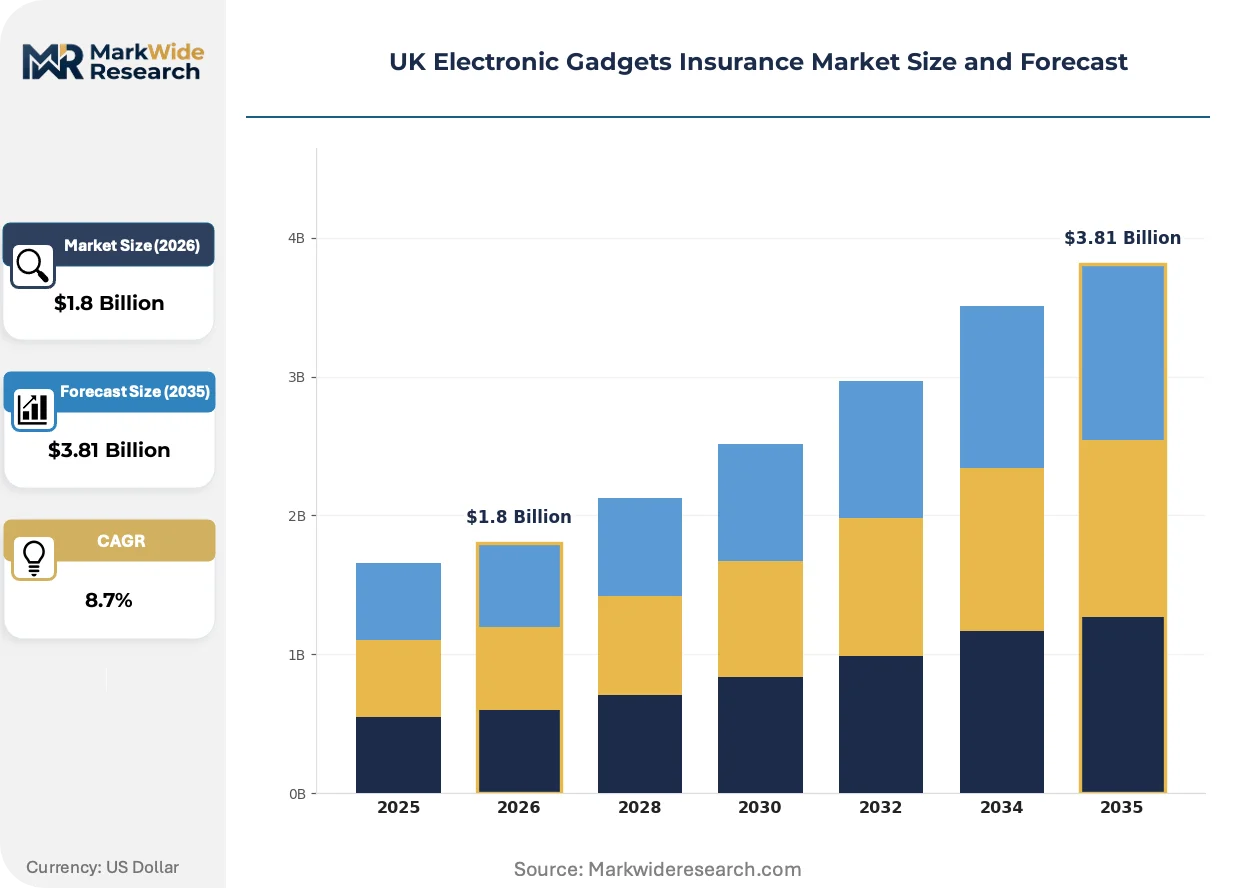
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Laptops, Tablets, Wearables Policy Duration: Annual, Monthly, Multi-Year, Lifetime Coverage Type: Theft, Accidental Damage, Liquid Damage, Mechanical Failure Target Audience: Students, Professionals, Families, Seniors |
| Companies Covered | Axa (Inter Partner Assistance SA), Aviva Insurance Ltd, Assurant General Insurance Limited, AmTrust Europe Limited, American International Group UK Limited, Better Buy Insurance, Acumen Insurance Services Ltd, Pier Insurance Managed Services Limited, EE Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Electronic Gadgets Insurance Market Evolving Landscape
Digital-first distribution models are displacing traditional broker channels while artificial intelligence compresses claims processing timelines from days to minutes.
Telematics-style risk assessment is miniaturizing into gadget insurance through device health monitoring APIs. Smartphone operating systems now expose battery degradation, drop detection, and usage intensity data. Insurers leverage this telemetry to price policies dynamically, rewarding careful handling with reduced premiums and compressing adverse selection pools.
The FCA's forthcoming guidance on embedded insurance distribution is tightening commission disclosure requirements for mobile network operator partnerships. This regulatory pressure forces renegotiation of revenue-sharing agreements. Point-of-sale attachment economics face structural compression as transparency mandates expose previously hidden markup structures.
Subscription fatigue among younger consumers is fragmenting purchasing patterns away from annual commitments. Monthly rolling contracts with instant cancellation flexibility now dominate student and early-career segments. App-based self-service claims, including automated screen damage verification through photo upload, displace telephone helpline dependency in London and the South East metropolitan corridors.
UK Electronic Gadgets Insurance Market Segmentation
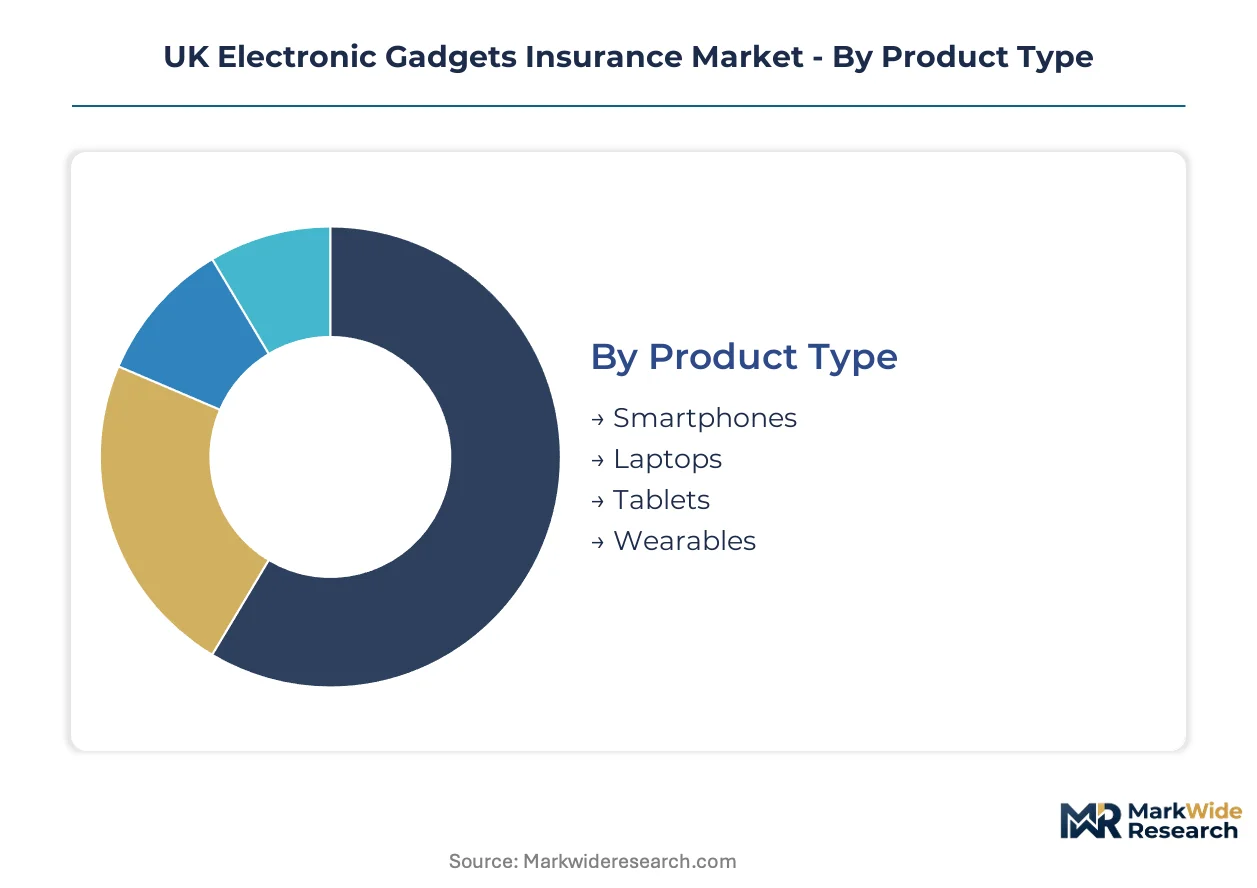
Segmentation in UK electronic gadgets insurance determines pricing precision, distribution channel selection, and reserve adequacy. Underwriters calibrate risk pools by device depreciation curves, policy commitment length, and claimant behavioral profiles to sustain loss ratios.
Product Type:
Smartphones face the most acute substitution pressure as manufacturer self-insurance programs and extended warranty bundles erode standalone policy attachment.
- Smartphones:High-frequency claims for screen and liquid damage dominate loss experience. London professionals sustain premium pricing for multi-device household bundles tied to flagship handsets.
- Laptops:University coursework dependency drives student segment penetration, though remote repair logistics complicate claims fulfillment outside metropolitan corridors.
- Tablets:Hybrid work patterns sustain demand among families seeking shared device coverage with lower per-unit premiums than smartphone equivalents.
- Wearables:Health-integrated devices attract premium pools from fitness-focused demographics, with claim limits typically capped below handset valuations.
Smartphones retain volume leadership; wearables hold the steepest expansion curve.
Policy Duration:
Cost tier stratification separates annual commitments from flexible subscriptions, reshaping customer lifetime value calculations and churn exposure.
- Annual:Dominant volume structure with upfront premium collection smoothing insurer cash flow. South East households show strongest renewal loyalty.
- Monthly:Rolling contracts capture students and early-career professionals through app-based management and instant cancellation flexibility.
- Multi-Year:Device refresh cycles rarely align with extended terms, constraining uptake despite theoretical premium discounts.
- Lifetime:Obsolescence risk and manufacturer trade-in programs render this structure commercially marginal for most device categories.
Annual policies anchor revenue stability; monthly subscriptions are climbing the fastest.
Coverage Type:
Application-specific peril selection allows granular risk transfer tailored to usage intensity and environmental exposure patterns.
- Theft:Urban concentration in London drives geographic rating differentials, with claims verification requiring police report documentation.
- Accidental Damage:Screen replacement frequency generates highest claim volume, with repair cost volatility tied to component supply constraints from East Asian fabrication.
- Liquid Damage:Corrosion assessment complexity extends claims settlement timelines compared to visible physical damage.
- Mechanical Failure:Overlaps with manufacturer warranty periods, creating adverse selection as consumers delay coverage purchase until warranty expiry approaches.
Accidental damage commands the largest premium pool; liquid damage claims gain share fastest.
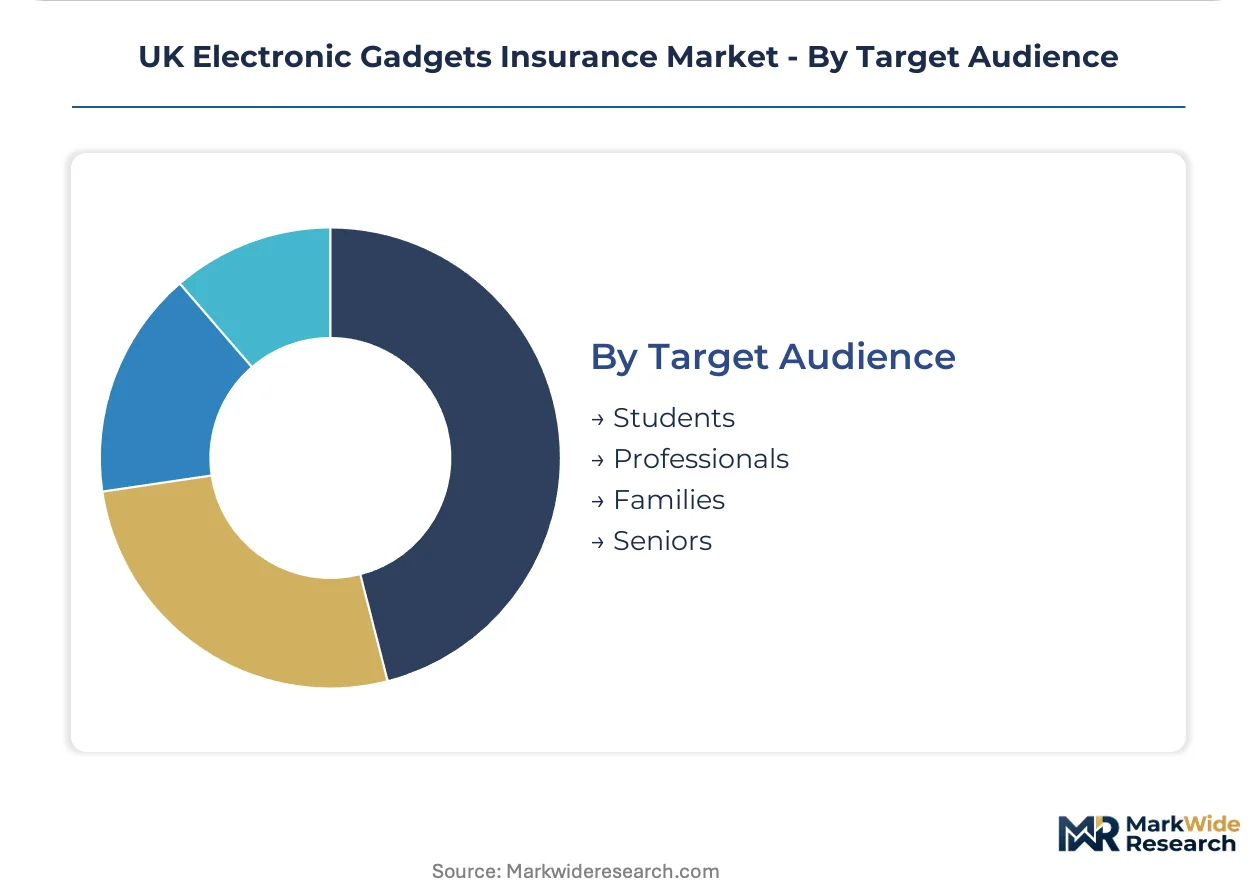
Target Audience:
Customer type segmentation aligns distribution channel investment with demographic media consumption and purchase decision autonomy.
- Students:Device dependency for coursework sustains addressable market expansion, with price sensitivity favoring monthly subscription structures.
- Professionals:London-centric workforce carries multiple high-value devices, supporting multi-policy household penetration and reduced price elasticity.
- Families:Shared coverage for children's devices concentrates demand in commuter belt postcodes with elevated gadget ownership density.
- Seniors:Simplified claims processes and telephone helpline access sustain modest penetration despite lower device replacement frequency.
Professionals retain margin leadership; students represent the steepest volume expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The London orbital motorway and high-speed rail links to the South East commuter belt concentrate gadget ownership density and insurance purchasing power within England's economic core.
London and the South East
Financial services professionals and technology workers carry multiple high-value devices, sustaining premium pricing for multi-policy household bundles. The Financial Conduct Authority's Consumer Duty rules mandate enhanced transparency disclosures from insurers headquartered in the capital. Canary Wharf and the City of London host the densest concentration of gadget insurance policyholders, with monthly subscription models capturing younger professionals.
Midlands
University cities including Birmingham, Nottingham, and Coventry drive student segment expansion as coursework dependency on connected devices intensifies. The Prudential Regulation Authority's capital reserving requirements shape pricing floors for regional underwriters operating from Birmingham's financial district. Leicester's manufacturing heritage supports a secondary market for refurbished device coverage with lower premium tiers.
North England
Remote repair logistics and lower population density compress margins for traditional annual policy structures across Manchester and Leeds metropolitan areas. The Financial Ombudsman Service adjudicates higher dispute volumes per capita here, shaping precedent on claims handling verification standards. Sheffield's emerging technology corridor shows elevated wearable device adoption among health-conscious demographics.
Scotland
Edinburgh's insurance sector presence anchors specialist gadget coverage distribution through established broker networks. Scottish university cities including Glasgow and Aberdeen mirror English student segment dynamics with pronounced price sensitivity. The Scottish Government's digital inclusion programs accelerate device penetration in rural Highlands, expanding addressable market boundaries.
Wales and Northern Ireland
Lower gadget ownership density per household constrains standalone policy viability, favoring embedded distribution through mobile network operators. Regulatory alignment with UK-wide FCA standards ensures product consistency, though local broker capacity remains thinner than in England. Belfast's emerging fintech cluster presents nascent demand for professional multi-device coverage.
UK Electronic Gadgets Insurance Market Competitive Landscape
Listed leaders compete with private specialists across distribution channel access, with publicly traded insurers leveraging balance sheet scale against agile private underwriters exploiting embedded partnership agility. The market exhibits moderate consolidation, with three to five dominant players controlling the majority of direct and affinity channel volume. Strategic archetypes include pan-European generalists with claims network advantages, direct distribution specialists with proprietary pricing algorithms, and embedded partnership operators controlling point-of-sale attachment. Competitive moves center on M&A activity targeting digital-first distribution platforms and strategic partnerships with mobile network operators seeking exclusive attachment rights.
Within the embedded partnership tier, Assurant General Insurance Limited and EE Insurance exemplify operators leveraging point-of-sale control through mobile network operator exclusivity. Axa (Inter Partner Assistance SA) occupies a position representing pan-European generalist scale with cross-border claims infrastructure. Aviva Insurance Ltd anchors the direct distribution archetype through proprietary digital platforms and risk-scoring capabilities. These three company structures illustrate the competitive segmentation between partnership-dependent, scale-driven, and direct-channel strategic positions.
| Leading Market Players |
|---|
| Axa (Inter Partner Assistance SA) |
| Aviva Insurance Ltd |
| Assurant General Insurance Limited |
| AmTrust Europe Limited |
| American International Group UK Limited |
| Better Buy Insurance |
| Acumen Insurance Services Ltd |
| Pier Insurance Managed Services Limited |
| EE Insurance |
| Others |
Value Network & Pricing Analysis
Repair-part substitution from third-party components to manufacturer-authorized parts simultaneously shifts supply geography toward East Asian fabrication hubs and compresses pricing economics for independent underwriters facing higher authorized-part cost bases.
Pricing Analysis
Volume-discount tiering structures separate multi-device household bundles from single-item coverage, with premium differentiation resting on claim limit thresholds and excess levels. Price differentiation hinges on geographic delivery cost for remote repair logistics and brand premium attached to pan-European claims networks. Pricing pressure stems from FCA Consumer Duty compliance investment requirements. Students exhibit highest price sensitivity, while London professionals show reduced elasticity for bundled household policies.
Supply Chain Analysis
Inventory lead-times for replacement screens and semiconductor components extend claims settlement timelines when East Asian fabrication capacity faces constraint. Component sourcing concentrates in China, South Korea, and Taiwan for display panels and memory chips. Supply chains draw from specialized glass substrate suppliers and precision assembly facilities. Single-source vulnerability around OLED panel production creates fulfillment risk. Distribution runs through mobile network operator point-of-sale channels and direct digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK electronic gadgets insurance market functions as a defensive-moat industry where regulatory entrenchment through FCA authorization creates substantial switching costs for policyholders and barriers for new underwriting entrants.
For Market Incumbents: Secure embedded partnership exclusivity with mobile network operators before FCA guidance on commission disclosure reshapes point-of-sale economics. Consolidate claims infrastructure investment in AI-powered image authentication to counter staged damage fraud. Vertical integration into proprietary risk-scoring algorithms defends margin position against algorithmic pricing pressure from direct-channel specialists. For New Entrants and Emerging Players: Lead with monthly subscription app-based models targeting university cities in the Midlands and North England where annual policy penetration remains underdeveloped. The student segment offers lowest competitive density and highest volume expansion trajectory. White-label partnerships with refurbished device retailers provide alternative channel access outside MNO-controlled distribution. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed digital distribution platforms lacking proprietary underwriting licenses. Long-term viability centers on regulatory compliance infrastructure as a durable competitive advantage. Watch FCA embedded insurance guidance implementation as inflection indicator for partnership economics compression.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Claims Authentication | Reduces fraud leakage while accelerating settlement timelines for screen damage verification. |
| Embedded MNO Partnership Expansion | Controls point-of-sale attachment rates before FCA transparency mandates reshape commission structures. |
| Monthly Subscription Platform Launch | Captures student and early-career demographics through app-based policy management flexibility. |
| Wearables Coverage Portfolio Extension | Accesses health-integrated device premium pools as fitness tracker adoption accelerates. |
| South East Regional Distribution Buildout | Penetrates affluent commuter belts surrounding London with elevated gadget ownership density. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with underwriting executives, claims operations directors, mobile network operator partnership managers, and FCA regulatory specialists; and secondary validation against Prudential Regulation Authority capital reserving disclosures, Financial Ombudsman Service adjudication statistics, and insurer Solvency II filings. Bottom-up policy volume estimates triangulated against top-down premium pool calculations.
Across the analysis window, forecasts modeled device type segmentation, policy duration structures, coverage peril selection, and claimant demographic profiles. CAGRs derived from historical premium growth trajectories adjusted for regulatory intervention effects and student segment expansion rates. Forecast inputs incorporated smartphone depreciation curves, semiconductor supply volatility indices, and embedded distribution attachment rate assumptions.
The analysis sits within stated boundaries; outcomes outside sustained FCA regulatory stability or extreme component supply disruption would require recalibration. Forecasts reflect documented assumptions around Consumer Duty implementation pace and student device dependency trends. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
India Liability Insurance Market
Insurance
China Liability Insurance Market
Insurance
Canada House Insurance Market
Insurance
Insurance Analytics Market
Insurance
Jewelry Insurance Market
Insurance
Europe Liability Insurance Market
Insurance
Sri Lanka Cyber (Liability) Insurance Market
Insurance
Compulsory Third Party (CTP) Insurance Market
Insurance
Extended Warranty Agreement Market
Insurance
Term Insurance Market
Insurance
Germany Reinsurance Market
Insurance
UK Dental Insurance Market
Insurance
China Business Income Insurance Market
Insurance
Telecommunication Insurance Market
Insurance
Peer to Peer Insurance Market
Insurance
US Extended Warranty Market