
 Insurance Big Data Analytics Market | 2026-2036
Insurance Big Data Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Insurance Big Data Analytics Market Insights
Multi-source data integration is broadening as carriers move beyond traditional actuarial tables toward real-time ingestion of telematics, satellite imagery, and open-source records. IBM Corporation leverages its Watson platform to anchor predictive modeling for life underwriting workflows. Microsoft Corporation competes through Azure-based analytics suites that sustain enterprise-scale deployments across national insurer networks. Oracle Corporation dominates core policy administration systems, extending its footprint into adjacent data lakes that feed downstream analytics engines.
Insurance big data analytics encompasses the systematic extraction, processing, and modeling of structured and unstructured information to quantify risk exposure, detect anomalous claims patterns, and optimize portfolio profitability. The discipline relies on distributed computing frameworks, machine learning pipelines, and API-connected data fabrics that process batch and streaming inputs with sub-second latency for time-critical decisions. Predictive analytics leads in commercial deployment maturity, with prescriptive analytics representing the fastest-expanding margin pool as carriers seek automated decision recommendations rather than retrospective scorecards. Claims data remains the most voluminous input source, though sensor data from connected devices is displacing static questionnaires in usage-based insurance programs.
The National Association of Insurance Commissioners in the United States, the European Insurance and Occupational Pensions Authority, and China's National Financial Regulatory Administration each impose distinct algorithmic accountability and data residency requirements that shape vendor product roadmaps and carrier procurement criteria. GDPR in Europe and emerging state-level privacy statutes in the United States restrict cross-border data flows, forcing regional infrastructure duplication and elevating compliance costs for multinational platforms. Stakeholders must monitor evolving model explainability mandates and determine whether to build captive data science teams or deepen reliance on specialized third-party providers as regulatory granularity intensifies.
Market Dynamics
Cloud-native data architectures are compressing deployment timelines for predictive models while state insurance commissioners impose algorithmic transparency mandates that force carriers to re-engineer governance workflows.
Growth Catalysts
- Telematics penetration in auto underwriting:Real-time driver behavior data from connected vehicles enables usage-based pricing models that improve loss ratios for property and casualty carriers.
- National Association of Insurance Commissioners model governance guidelines:Standardized documentation requirements for algorithmic decision-making create procurement pull for compliant analytics platforms.
- API-connected data fabrics:Distributed computing frameworks reduce latency for claims fraud detection from batch overnight cycles to sub-second scoring.
Market Restraints
- Cross-border data residency requirements:GDPR in Europe and emerging US state privacy statutes force infrastructure duplication that elevates operational costs for multinational deployments.
- Legacy core system technical debt:Oracle-dominated policy administration systems resist seamless integration with modern data lakes, constraining analytics pipeline throughput.
- Specialized actuarial-data science hybrid talent scarcity:Carriers face recruitment friction for professionals fluent in both traditional reserving methods and machine learning model development.
Strategic Opportunities
- Parametric insurance expansion in climate-vulnerable regions:Satellite imagery analytics enable automated payouts based on objective weather triggers rather than loss adjustment expenses.
- Embedded insurance distribution through digital platforms:Point-of-sale analytics integration at e-commerce checkout creates new premium volume without traditional agent channel costs.
- EU AI Act algorithmic accountability requirements:Mandatory risk classification for automated underwriting systems generates demand for explainable AI tooling and audit services.
Industry Challenges
- Model drift monitoring at scale:Production machine learning pipelines require continuous validation against training data distributions, demanding specialized MLOps infrastructure investment.
- Third-party data vendor consolidation risk:Reliance on concentrated telematics and satellite imagery suppliers creates single-point-of-failure exposure for real-time underwriting engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insurance Big Data Analytics Market |
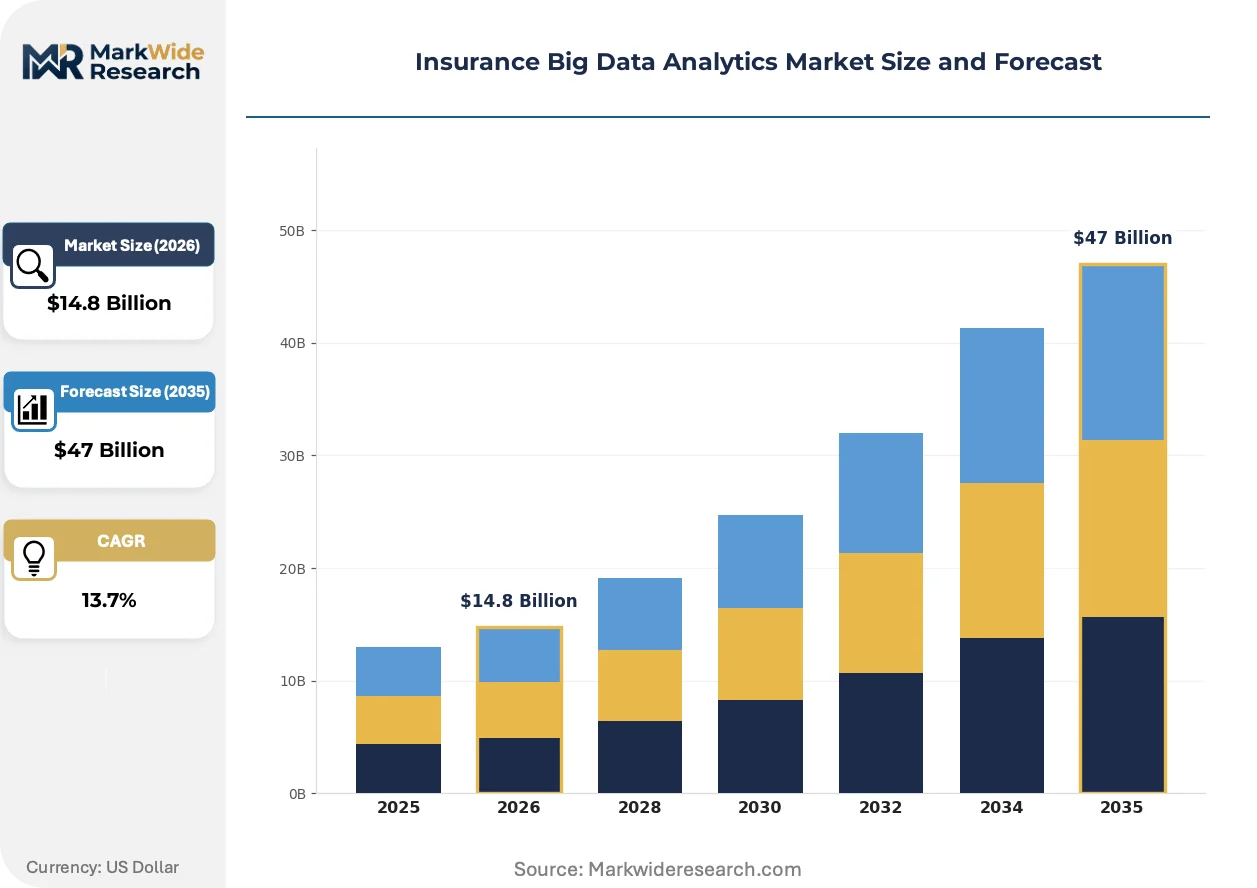
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $47 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Data Source: Claims Data, Customer Behavior Data, Social Media Data, Sensor Data, Market Data Analytics Type: Descriptive Analytics, Predictive Analytics, Prescriptive Analytics, Diagnostic Analytics, Streaming Analytics Application: Fraud Detection, Risk Assessment, Customer Segmentation, Pricing Optimization, Claims Management End User: Life Insurers, Property & Casualty Insurers, Health Insurers, Reinsurers, Brokers |
| Companies Covered | IBM Corporation, Microsoft Corporation, Salesforce, Inc., Oracle Corporation, SAP SE, LexisNexis Risk Solutions, Guidewire Software Inc., SAS Institute Inc., Verisk Analytics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insurance Big Data Analytics Market Trends and Innovations
Generative AI tools are penetrating actuarial documentation and customer communication workflows while regulatory pressure intensifies around model explainability. These forces are reshaping vendor roadmaps and carrier procurement priorities simultaneously.
Federated learning architectures are expanding into multi-carrier data collaboration scenarios. Consortia of regional insurers in Germany and the United States deploy privacy-preserving techniques to train shared fraud detection models without exposing proprietary claims records. This approach is expanding into competitive markets previously blocked by data siloing.
The EU AI Act's risk-based classification system imposes documentation and human oversight mandates on automated underwriting engines. Life and health carriers in France and Germany must now maintain model cards detailing training data provenance and performance metrics across demographic subgroups. Medium-sized insurers are responding by outsourcing governance tooling to specialized compliance-as-a-service providers.
Subscription-based analytics procurement is displacing perpetual license models among mid-tier carriers. Chief data officers in US regional markets now favor consumption-priced cloud deployments that align vendor fees with actual query volume rather than upfront capital commitments. This shift is most visible among mutual insurers with constrained IT budgets and cyclical premium income patterns.
Insurance Big Data Analytics Market Segmentation
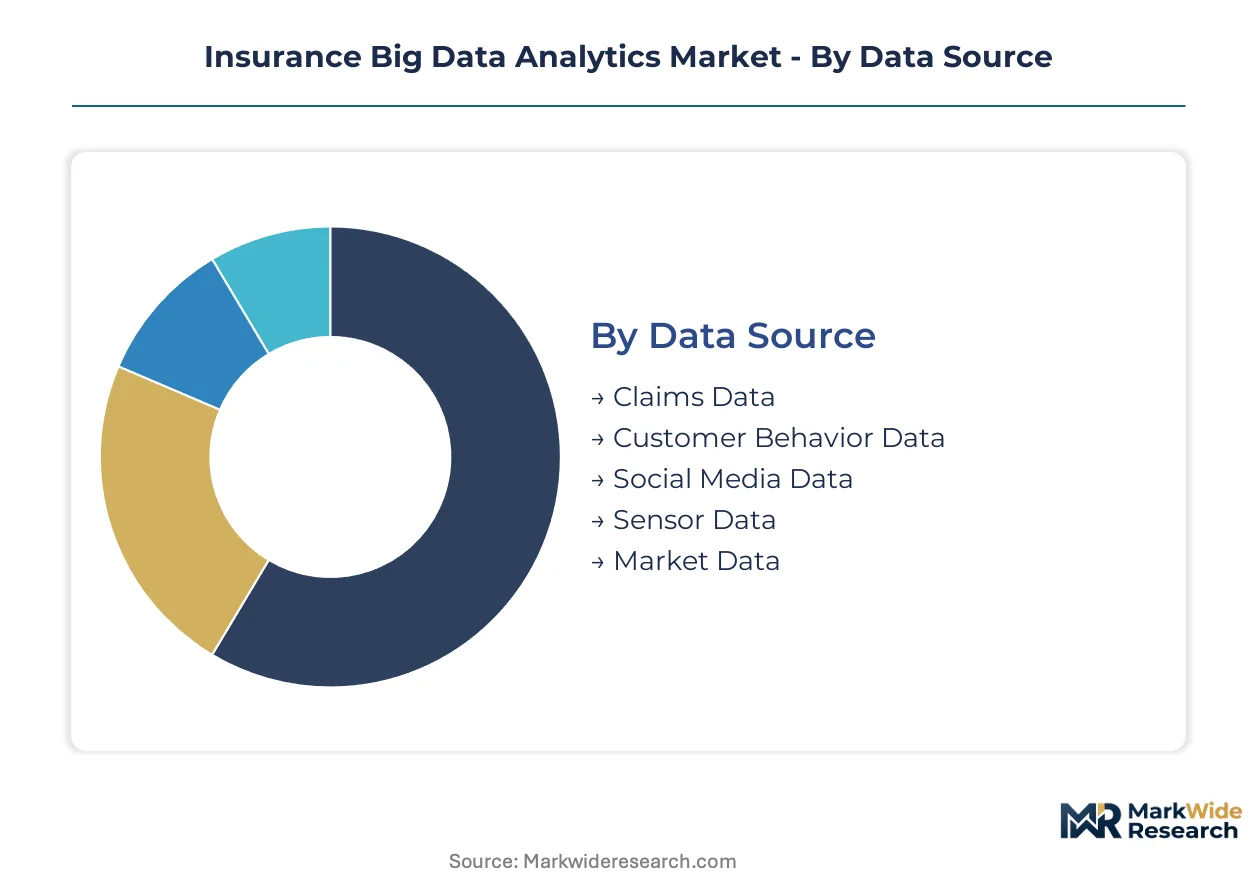
Segmentation in insurance big data analytics reveals how data infrastructure investments align with carrier risk profiles and regulatory exposure. Distinct technology stacks serve life underwriting versus property claims, while deployment depth varies from standalone dashboards to embedded policy administration modules.
Data Source:
Integration depth varies sharply: claims and customer behavior data flow through embedded core systems, while social media and sensor streams require standalone ingestion pipelines with specialized governance layers.
- Claims Data:Structured records of loss events, reserve estimates, and settlement outcomes form the foundational training corpus for fraud detection algorithms. Property and casualty carriers in the United States concentrate procurement here, driven by state commissioner mandates for algorithmic documentation.
- Sensor Data:Telematics devices, wearables, and IoT endpoints generate high-velocity streams demanding sub-second processing latency. Usage-based auto insurers deploy this as embedded pricing inputs, though GDPR restrictions in Europe force regional infrastructure duplication.
- Customer Behavior Data:Policy interaction logs and channel preference signals.
- Social Media Data:Public sentiment and lifestyle indicators scraped under consent frameworks.
- Market Data:External economic indicators and competitor pricing benchmarks.
Volume placements concentrate in Claims Data; the faster expansion belongs to Sensor Data.
Analytics Type:
Cost tier structures the competitive landscape: descriptive tools command lower per-seat pricing while prescriptive platforms extract premium fees for automated decision recommendations.
- Predictive Analytics:Machine learning models forecast loss ratios, lapse probabilities, and claim severity using historical pattern recognition. Life insurers in France and Germany prioritize this segment under EU AI Act documentation requirements for automated underwriting.
- Prescriptive Analytics:Optimization engines recommend specific pricing adjustments, reserve allocations, or fraud investigation priorities. Reinsurers deploy these as high-margin embedded services, capitalizing on their aggregated portfolio visibility across multiple cedents.
- Descriptive Analytics:Retrospective dashboards and regulatory reporting tools.
- Diagnostic Analytics:Root-cause analysis for claims anomalies and portfolio drift.
- Streaming Analytics:Real-time processing for telematics and parametric triggers.
Descriptive Analytics holds the largest installed base; Prescriptive Analytics is gaining share fastest.
Application:
Application maturity correlates with data infrastructure age: fraud detection and claims management leverage decades of structured records, while pricing optimization requires newer API-connected data fabrics.
- Fraud Detection:Anomaly detection algorithms flag suspicious claims patterns across provider networks, staged accidents, and identity manipulation. Health insurers in the United States anchor demand here, responding to HIPAA breach notification pressures and federal false claims enforcement.
- Risk Assessment:Underwriting engines evaluate mortality, morbidity, and property exposure using multi-source data fusion. Property and casualty carriers embed these directly into quoting workflows, shortening bind-to-issue cycles from days to minutes.
- Customer Segmentation:Cohort analysis for retention and cross-sell targeting.
- Pricing Optimization:Dynamic rate refinement using competitive and behavioral signals.
- Claims Management:Workflow automation and adjuster allocation optimization.
Fraud Detection commands the deepest analytics penetration; Pricing Optimization shows the steepest expansion trajectory.
End User:
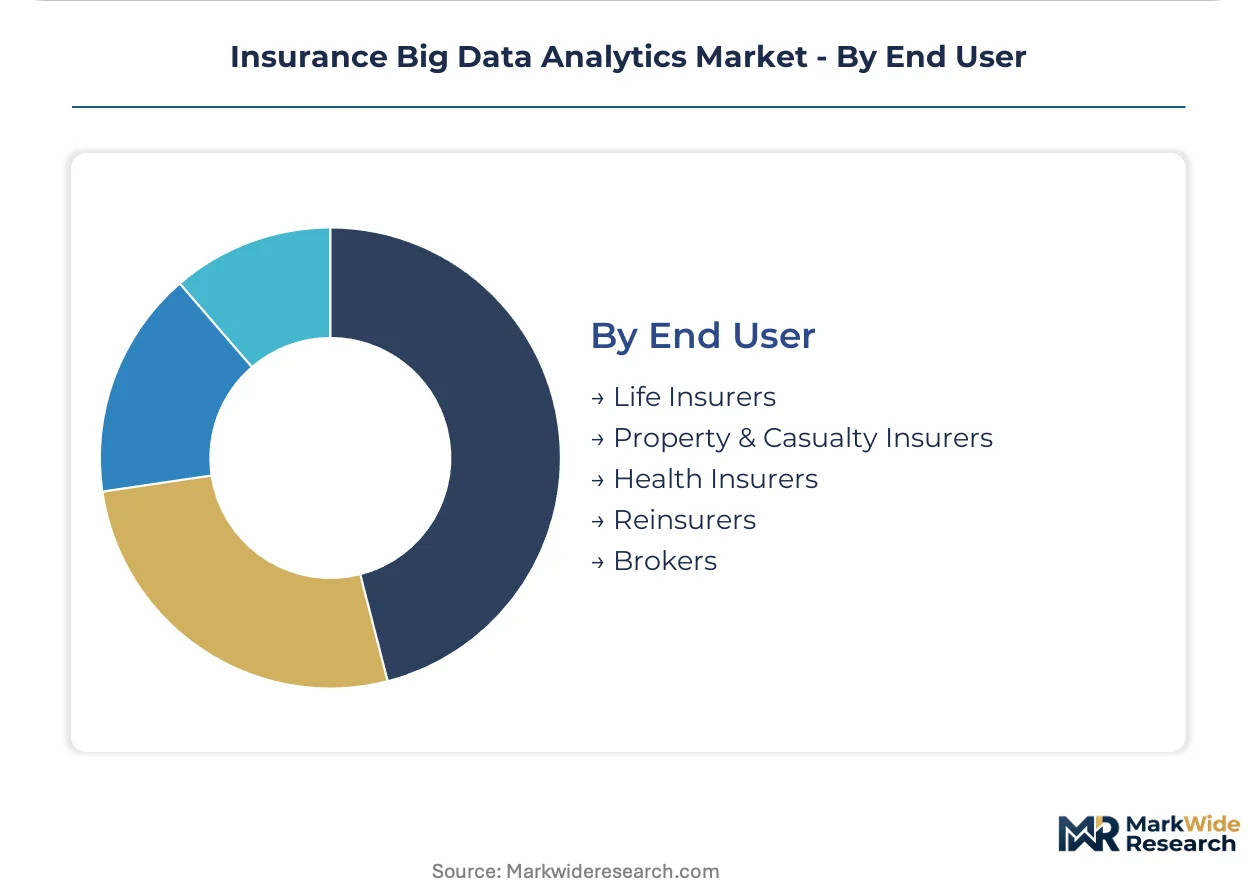
Customer type determines procurement authority and integration complexity: large multiline carriers build captive data science teams while regional mutuals rely on third-party platforms.
- Property & Casualty Insurers:Auto, home, and commercial lines carriers deploy analytics across underwriting, claims, and catastrophe modeling. Telematics integration and satellite imagery for parametric products drive technology refresh cycles in this segment.
- Life Insurers:Mortality risk quantification and in-force policy management dominate use cases. Accelerated underwriting programs using electronic health records and predictive models are displacing traditional fluid-based assessments.
- Health Insurers:Population health analytics and provider network optimization.
- Reinsurers:Portfolio aggregation and retrocession pricing intelligence.
- Brokers:Client risk profiling and coverage gap analysis tools.
Property & Casualty Insurers generate the heaviest query volumes; Life Insurers are climbing fastest as accelerated underwriting programs scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center infrastructure for insurance analytics clusters heavily in jurisdictions with mature cloud ecosystems and stringent regulatory frameworks. The United States anchors carrier spending through state-level commissioner mandates, while European markets respond to algorithmic accountability requirements under the EU AI Act.
United States
Property and casualty carriers dominate analytics procurement as NAIC model governance guidelines force documentation standardization. State insurance commissioners in California and New York impose the strictest algorithmic transparency requirements. The Hartford-to-Boston corridor hosts dense concentrations of actuarial-data science hybrid talent pools.
Germany
Regional insurer consortia deploy federated learning for fraud detection without exposing proprietary claims data. The EU AI Act's risk classification system mandates human oversight for automated underwriting engines. Munich and Frankfurt sustain competing clusters of InsurTech infrastructure providers.
United Kingdom
Lloyd's syndicates drive demand for real-time catastrophe modeling using satellite imagery analytics. The Financial Conduct Authority's consumer duty rules compel explainable AI for pricing decisions. London's Square Mile concentrates reinsurance analytics vendors serving global cedent networks.
France
Life insurers accelerate underwriting programs using electronic health records under CNIL data protection oversight. Mandatory model cards detailing training data provenance reshape procurement criteria for governance tooling. Paris hosts the continental headquarters of major cloud providers serving southern European carriers.
Japan
Non-life insurers integrate telematics for usage-based auto coverage as METI promotes data-driven risk assessment standards. The country's national financial regulator imposes strict data residency requirements for cross-border model training. Tokyo's Marunouchi district clusters domestic system integrators modernizing legacy core platforms.
Insurance Big Data Analytics Market Competitive Landscape
Global majors compete with regional champions across cloud infrastructure and specialized compliance tooling. The vendor base stratifies into three tiers: hyperscale cloud providers, core system incumbents with analytics extensions, and niche governance-as-a-service specialists. Dominant competitive moves include API partnership ecosystems and consumption-based pricing pivots to capture mid-tier carrier budgets.
Within the hyperscale tier, IBM Corporation and Microsoft Corporation exemplify platform-centric strategies anchored in Watson and Azure ecosystems respectively. Oracle Corporation occupies a position bridging legacy policy administration with adjacent data lake infrastructure. Salesforce, Inc. represents the CRM-native archetype embedding analytics directly into customer-facing workflows.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Salesforce, Inc. |
| Oracle Corporation |
| SAP SE |
| LexisNexis Risk Solutions |
| Guidewire Software Inc. |
| SAS Institute Inc. |
| Verisk Analytics, Inc. |
| Others |
Pricing and Supply Chain Analysis
Cloud-native consumption models are compressing deployment economics while concentrating procurement authority among hyperscale platform providers. This shift simultaneously reduces upfront capital barriers for mid-tier carriers and elevates switching costs through embedded data pipeline dependencies.
Pricing Analysis
Service bundling distinguishes vendor tiers: premium contracts embed dedicated model governance tooling and compliance audit support, while economy tiers unbundle these for self-managed implementations. Pricing stratifies across enterprise, mid-market, and entry-level tiers based on query volume commitments and SLA guarantees. Cost compression in the mid-market tier is intensifying because consumption-based cloud deployments align fees with actual utilization. Regional mutual insurers exhibit the highest price sensitivity; national multiline carriers with captive data science teams demonstrate the lowest.
Supply Chain Analysis
Actuarial-data science hybrid talent shortages in the United States, Germany, and United Kingdom constrain implementation velocity for advanced analytics deployments. The supply chain draws from three critical input streams: cloud compute infrastructure, specialized third-party data feeds (telematics, satellite imagery, electronic health records), and compliance-as-a-service governance tooling. Single-source vulnerability concentrates in telematics data providers, where carrier reliance on concentrated suppliers creates operational continuity exposure. Distribution runs through direct vendor relationships for large carriers and channel partners serving regional mutuals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where EU AI Act documentation mandates and NAIC model governance guidelines erect substantial barrier-to-entry moats for vendors lacking pre-built governance tooling.
For Market Incumbents: Anticipate margin compression from subscription pricing pivots by reinforcing API partnership ecosystems that embed analytics into adjacent policy administration workflows. Prioritize MLOps infrastructure investment to address model drift monitoring demands from enterprise carriers. Defensive consolidation around specialized compliance-as-a-service providers will preempt new entrant challenges in the governance tooling segment. For New Entrants and Emerging Players: Begin with white-space targeting of mid-tier mutual insurers in US regional markets, where consumption-priced cloud deployments align with cyclical premium income patterns. The most penetrable segment lies in federated learning consortia for fraud detection, where privacy-preserving techniques enable multi-carrier collaboration without proprietary data exposure. A channel partnership strategy with legacy core system modernizers accelerates initial footprint. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by hyperscale cloud providers seeking vertical insurance expertise. Long-term viability hinges on regulatory tailwinds persisting across the analysis window, with algorithmic accountability mandates deepening carrier dependence on specialized tooling. Watch for EU AI Act enforcement granularity as the critical inflection signal for governance-as-a-service valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Consortium Formation | Privacy-preserving collaboration enables German and US regional insurers to share fraud detection models without exposing proprietary claims records. |
| Consumption-Based Pricing Pivot | Cloud-native deployments align vendor fees with actual query volume, capturing mid-tier mutual insurers with constrained IT budgets. |
| Compliance-as-a-Service Integration | Pre-built EU AI Act documentation tooling reduces implementation friction for French and German life insurers facing model card mandates. |
| API Ecosystem Expansion | Embedded analytics partnerships with legacy core system providers overcome Oracle-dominated policy administration integration constraints. |
| MLOps Infrastructure Investment | Continuous model validation pipelines address production drift monitoring demands from enterprise-scale carrier deployments. |
Research Methodology
Independent corroboration across chief data officers at US regional insurers, EU compliance officers at French and German carriers, and platform engineering leads at major cloud providers underwrites the qualitative findings. Primary interviews with actuarial-data science hybrid practitioners, NAIC working group participants, and InsurTech procurement executives were validated against secondary sources including NAIC model governance guideline filings, EU AI Act implementation documentation, and SEC 10-K disclosures from publicly traded analytics vendors. Bottom-up deployment sizing and top-down carrier IT spending analysis were triangulated to establish market boundaries.
Rate-of-change decomposition across the analysis window isolates telematics penetration curves, cloud migration velocity, and regulatory enforcement intensity as distinct growth drivers. Segmentation modeling incorporated data source type (claims, sensor, behavior), analytics maturity tier (descriptive through prescriptive), application domain (fraud detection through pricing optimization), and end-user carrier archetype (property and casualty, life, health, reinsurance). CAGRs were derived from carrier analytics budget trajectories and vendor booking patterns, with cross-validation against hyperscaler vertical revenue disclosures and insurance-specific SaaS benchmarking.
Regulatory enforcement delays, carrier legacy system modernization stalls, and third-party data vendor consolidation are the dominant revision risks to the projection framework. Forecasts embed assumptions regarding NAIC guideline adoption velocity and EU AI Act implementation consistency across member states. Material deviation in these triggers warrants pause and re-evaluation of segment-level growth trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Parametric Insurance Market
Insurance
Workers Compensation Insurance Market
Insurance
Asia-Pacific Mobile Phone Insurance Market
Insurance
Property Insurance Market
Insurance
Asia-Pacific Usage-Based Insurance Market
Insurance
Takaful Market
Insurance
US Insurance Third-Party Administrator Market
Insurance
Engineering Insurance Market
Insurance
Umbrella Insurance Market
Insurance
Slovenia Property and Casualty Insurance Market
Insurance
Asia-Pacific Electronic Gadgets Insurance Market
Insurance
Marine Cargo Insurance Market
Insurance
Title Insurance Market
Insurance
India Life and Non-Life Insurance Market
Insurance
Cargo Insurance Market
Insurance
Boiler Insurance Market