
 Cyber Insurance Market | 2026-2036
Cyber Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Cyber Insurance Market Intelligence
The scarcity of experienced cyber risk actuaries is reorganizing how carriers approach underwriting, pricing, and portfolio management across the industry. Global carrier Chubb leverages its extensive historical claims data and dedicated cyber units to refine complex risk models. Specialist insurer Beazley differentiates its offerings by bundling pre-breach consulting and post-incident response services with its policies. AIG sustains its market position by providing high-capacity coverage tailored to the complex needs of large multinational corporations.
Cyber insurance is a specialty insurance product designed to protect businesses from internet-based risks and the financial losses resulting from cyber incidents like ransomware. Policies typically cover a range of costs, including data recovery, business interruption, regulatory fines, and third-party liability claims. Demand from financial institutions and technology providers constitutes the largest share of the market by industry vertical due to high-value data assets. Within policy types, coverage for business interruption and data breach response represents the fastest-growing segments.
A complex web of regulations, including Europe's GDPR, the US HIPAA, and China's Cybersecurity Law, mandates robust data protection. These frameworks influence policy demand by creating significant financial penalties for non-compliance, making insurance a key risk transfer tool. Insurers must now decide whether to focus on standardized products for small businesses or develop customized solutions for complex enterprise risks.
Market Dynamics
The increasing frequency and sophistication of state-sponsored cyber attacks is the central force reshaping the market. This pressure is forcing a re-evaluation of risk models beyond simple criminal activity, influencing policy pricing and coverage limits for critical infrastructure sectors.
Growth Catalysts
- Regulatory Mandates:The EU's GDPR and new US SEC disclosure rules compel public companies to secure coverage, treating insurance as a component of compliance and risk management.
- Financial Sector Adoption:Financial institutions, driven by high-value data assets and stringent oversight, are expanding policies to cover sophisticated threats like systemic financial fraud and business email compromise.
- Supply Chain Interdependencies:Attacks targeting software supply chains are prompting large enterprises to mandate cyber insurance for their smaller vendors, creating downstream demand and expanding the insured business pool.
Market Restraints
- Systemic Risk Aggregation:The potential for a single widespread event, such as a major cloud provider outage, to trigger catastrophic losses across thousands of policies creates unmanageable risk aggregation for insurers, limiting capacity.
- Ambiguous Policy Language:A lack of standardized definitions for terms like "cyber warfare" or "nation-state attack" leads to coverage disputes and legal challenges, creating uncertainty for both insurers and policyholders.
- Actuarial Talent Scarcity:A global shortage of actuaries with specialized expertise in cyber risk modeling constrains the ability of carriers to accurately price complex policies and innovate new products, slowing market development.
Strategic Opportunities
- SME Market in Southeast Asia:Small and medium-sized enterprises in emerging economies like Vietnam and Indonesia represent a largely untapped market, offering opportunities for standardized, lower-cost policy products.
- Operational Technology (OT) Coverage:Developing specialized policies for industrial control systems in manufacturing and energy sectors addresses a critical, underinsured risk vector distinct from traditional IT threats.
- China's Cybersecurity Law:China's data localization and security requirements create a captive market for domestic and joint-venture insurers who can offer compliant policies tailored to the country's unique regulatory landscape.
Industry Challenges
- Incident Response Expertise Gap:A shortage of qualified cybersecurity professionals for post-breach response and forensic analysis, often bundled with policies, strains carrier resources and impacts service quality during a crisis.
- Lack of Loss Data Standards:The absence of a universal standard for collecting and sharing cyber incident data across the industry hinders the development of reliable actuarial models, making risk assessment difficult.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyber Insurance Market |
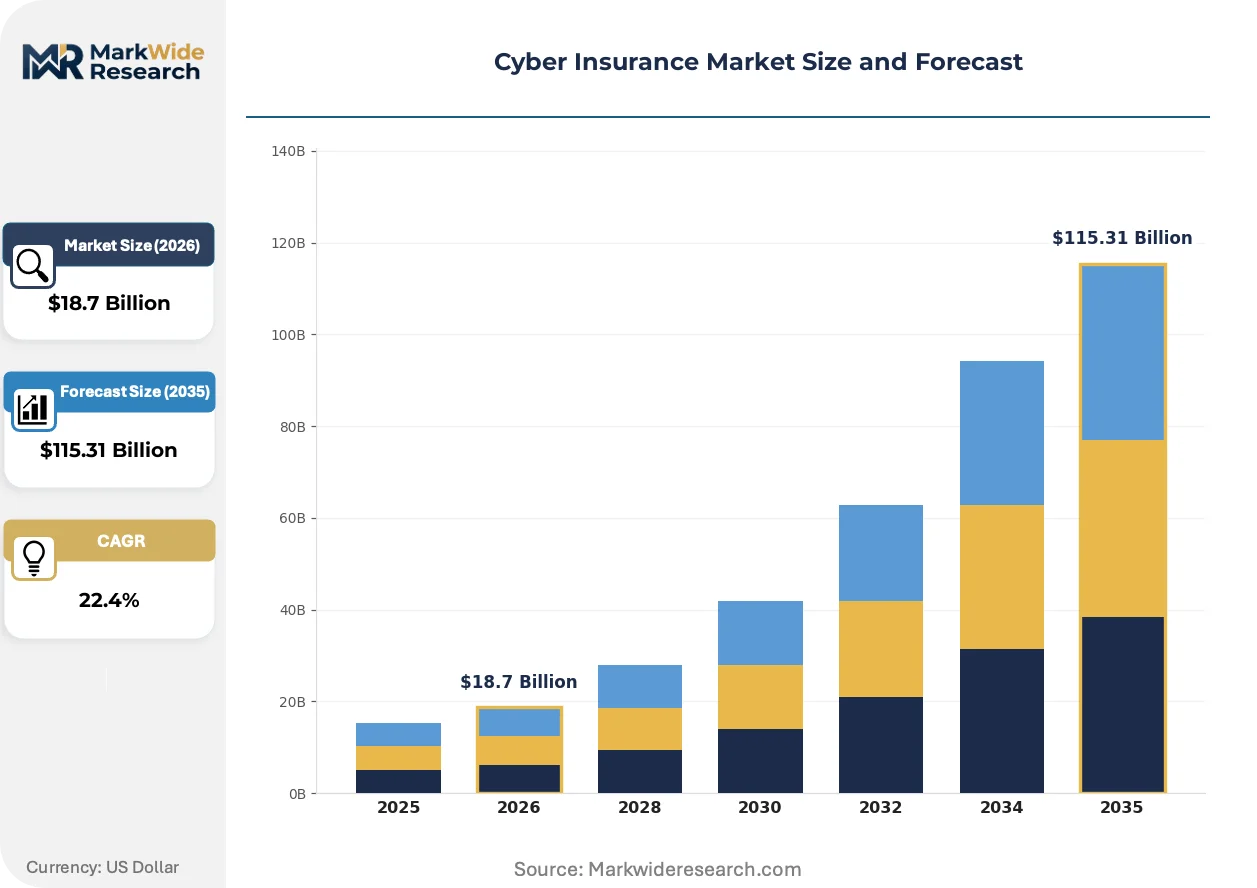
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: First-Party, Third-Party Liability, Network Security, Data Breach, Business Interruption Industry Vertical: Technology Providers, Financial Institutions, Manufacturing Firms, Media Agencies, Educational Institutions Application: Risk Management, Regulatory Compliance, Incident Response, Loss Recovery, Crisis Communication Distribution Channel: Direct Sales, Brokers, Online Marketplaces, Bancassurance, Partnership Programs |
| Companies Covered | Chubb, AXA XL, Travelers, Fairfax Financial, AIG, Beazley, Zurich Insurance, AXIS Capital, Hiscox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyber Insurance Market Strategic Shifts & Innovations
The market is evolving from a transactional product to an integrated service model. Carriers now embed proactive security services and incident response capabilities directly into policy frameworks to mitigate losses before they occur.
Artificial intelligence is integrated into underwriting platforms for risk assessment. Insurers are adopting these tools to automate evaluation of a client's security posture. This technology adoption is bifurcating the market between carriers using data-driven pricing and those relying on traditional questionnaires.
New disclosure rules from the US Securities and Exchange Commission (SEC) mandate rapid public reporting of material cybersecurity incidents. This regulation forces public companies to re-evaluate incident response plans and insurance adequacy. The financial services and technology sectors are most affected, seeking higher liability limits and crisis management support.
A shift towards embedded insurance models is gaining traction, where coverage is bundled into other business software platforms. This disrupts the traditional broker-led channel by offering insurance at the point of need. The trend is most visible among small businesses in North America and Europe seeking simplified procurement.
Cyber Insurance Market Segmentation
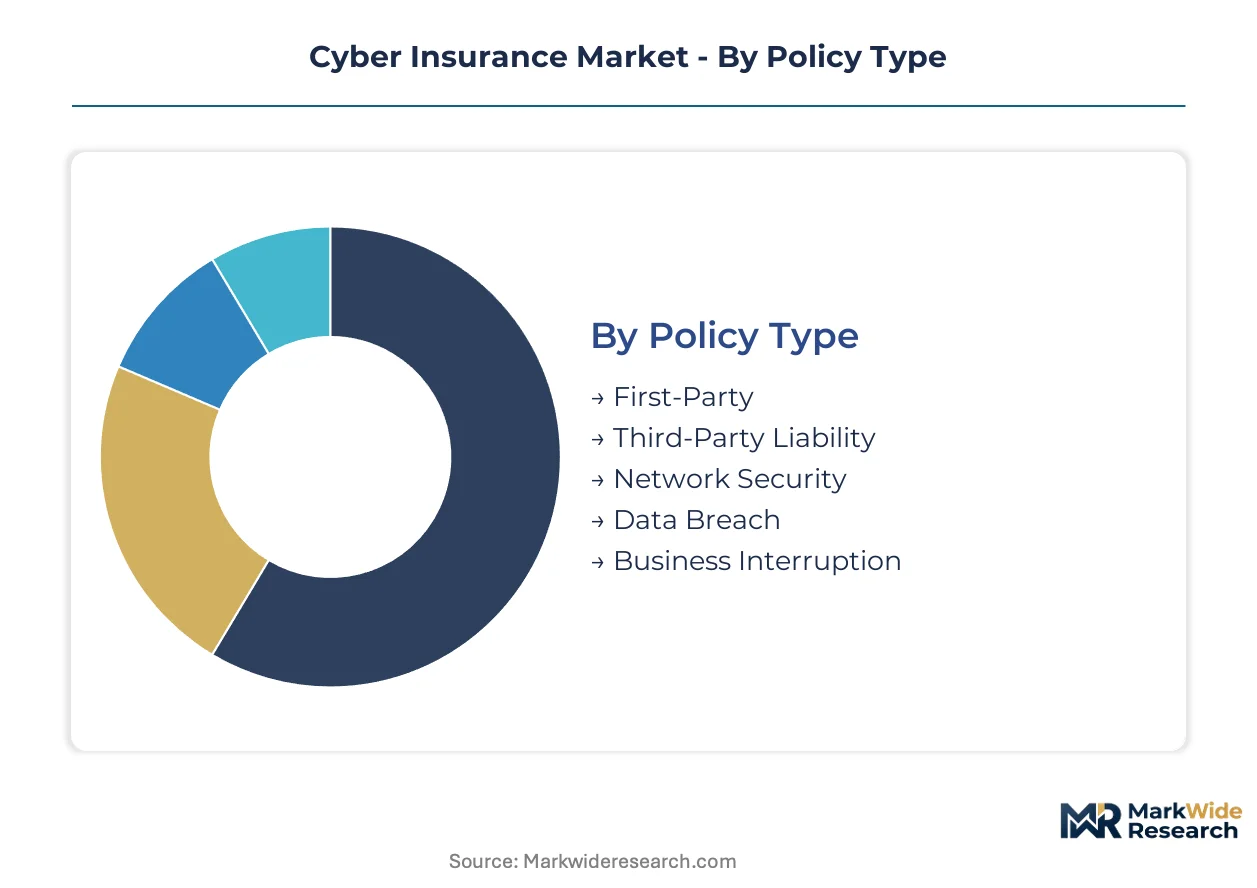
The cyber insurance market segmentations reveal distinct patterns in risk exposure, regulatory influence, and purchasing behavior among policyholders. Understanding these divisions allows insurers to tailor products, price risks accurately, and allocate capital efficiently across diverse client needs. The market's complexity necessitates granular analysis to identify areas of significant growth and emerging demand.
Policy Type:
Margin pools within policy types often concentrate where risk quantification is most complex, such as advanced data recovery and business interruption scenarios.
- Business Interruption:These policies cover financial losses arising from cyber-related operational disruptions, including lost profits and extra expenses. Demand from critical infrastructure sectors in Germany and the US is expanding due to potential systemic impacts.
- Data Breach:This coverage addresses expenses associated with unauthorized access to sensitive information, including notification costs, credit monitoring, and forensic investigations. Financial institutions and healthcare providers in Europe seek these policies due to stringent GDPR and HIPAA mandates.
- First-Party:This segment covers direct losses incurred by the policyholder, such as data restoration, forensic analysis, and public relations costs.
- Third-Party Liability:These policies protect against legal claims from customers or other entities impacted by a cyber incident originating from the policyholder.
- Network Security:This coverage typically addresses costs associated with network security failures, including incident response and legal defense for related claims.
First-Party coverage holds installed capacity. Business Interruption policies are rotating up the share rankings.
Industry Vertical:
The market for cyber insurance stratifies significantly based on the volume and sensitivity of data assets held by different industry verticals.
- Financial Institutions:These organizations require extensive protection for high-value transactional data and customer information, covering systemic fraud and business email compromise. US banks and European investment firms consistently purchase high-capacity policies.
- Technology Providers:Companies in this sector manage vast amounts of intellectual property and client data, often necessitating coverage for software supply chain vulnerabilities and intellectual property theft. North American cloud service providers and European software developers are major policyholders.
- Manufacturing Firms:Industrial control systems and intellectual property are key assets for these companies, driving demand for specialized operational technology coverage.
- Media Agencies:These entities manage sensitive client data and intellectual property, requiring protection against content theft and reputational damage.
- Educational Institutions:Universities and schools hold extensive personal data for students and staff, making them targets for data breaches and ransomware attacks.
Demand from Financial Institutions remains robust, while Manufacturing Firms are expanding quickly.
Application:
Cyber insurance applications primarily serve distinct functional utilities for businesses, ranging from proactive risk mitigation to reactive crisis management.
- Risk Management:This application integrates insurance as a strategic tool to identify, assess, and mitigate cyber threats, complementing internal security controls. Large multinational corporations leverage these policies for comprehensive enterprise risk frameworks.
- Regulatory Compliance:Policies designed for this application help organizations meet specific legal mandates, such as data breach notification requirements under GDPR or SEC disclosure rules. Public companies in the US and EU seek this coverage to avoid significant penalties.
- Incident Response:This application focuses on providing resources and expertise immediately following a cyber attack, including forensic analysis and data recovery services.
- Loss Recovery:This application directly addresses the financial restitution for losses incurred due to cyber incidents, including business interruption and data restoration costs.
- Crisis Communication:This application provides expert public relations support to manage reputational damage and stakeholder messaging after a significant cyber event.
Effective Incident Response tools are becoming critical for insurers to differentiate offerings.
Distribution Channel:
Supply concentration within distribution channels reflects the evolving preferences of policyholders, from traditional advisory models to digital procurement.
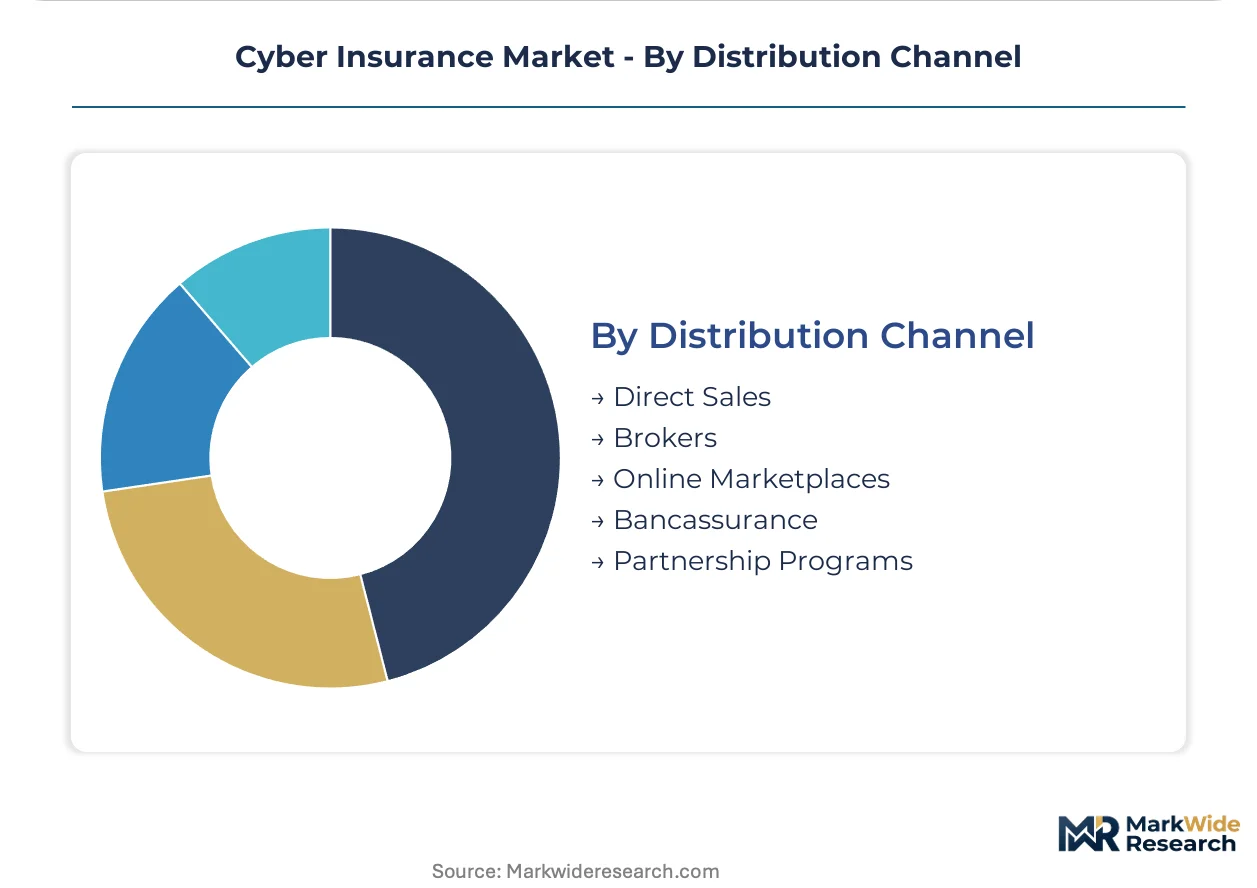
- Brokers:These intermediaries provide expert advice and access to a wide range of carrier products, often handling complex risk placements for large enterprises. Specialist brokers in London and New York facilitate bespoke policy design.
- Online Marketplaces:Digital platforms offer simplified policy comparison and purchase, primarily targeting small and medium-sized enterprises seeking standardized coverage. North American and European SMEs increasingly utilize these platforms for efficiency.
- Direct Sales:Insurers engage directly with clients to offer customized policies, particularly for large corporations with unique risk profiles.
- Bancassurance:Financial institutions partner with insurers to offer cyber policies to their existing business clientele, leveraging established customer relationships.
- Partnership Programs:Insurers collaborate with cybersecurity vendors or technology providers to embed coverage within their service offerings, creating new sales avenues.
The shift towards Online Marketplaces platforms is altering traditional procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the United States dominates cyber insurance consumption through its sophisticated financial sector, European and Asian markets are rapidly evolving with distinct purchasing behaviors. Germany's manufacturing firms prioritize operational technology coverage, whereas China's demand is shaped by its unique data localization mandates. India's burgeoning SME sector presents opportunities for standardized policy products.
United States
Financial institutions and technology providers in the United States drive significant demand for high-capacity cyber insurance. New SEC disclosure rules compel public companies to secure robust coverage, treating insurance as a key compliance component. Major tech hubs like Silicon Valley and financial centers such as New York City consistently seek higher liability limits and crisis management support.
Germany
German manufacturing firms are expanding their cyber insurance policies, particularly for industrial control systems. The EU's GDPR mandates strong data protection, influencing policy uptake across all sectors. Industrial regions like Bavaria and North Rhine-Westphalia show concentrated demand for specialized operational technology coverage.
China
China's Cybersecurity Law and data localization requirements create a captive market for cyber insurance, emphasizing compliance-driven policies. Domestic and joint-venture insurers are tailoring offerings to meet specific regulatory demands. Major tech and financial centers such as Beijing and Shanghai are key policy-purchasing hubs.
United Kingdom
Financial services and technology firms in the United Kingdom exhibit strong demand for data breach and business interruption coverage. The UK's implementation of GDPR principles continues to drive policy uptake for regulatory compliance. London's financial district and technology clusters in cities like Manchester are major centers for cyber insurance procurement.
India
India's small and medium-sized enterprises (SMEs) represent a largely untapped market for standardized, lower-cost cyber insurance policies. The country's evolving data protection framework, while still developing, is beginning to influence corporate risk management strategies. Technology hubs such as Bengaluru and Hyderabad are experiencing early-stage adoption among their growing tech ecosystems.
Cyber Insurance Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive landscape in cyber insurance. Strategic archetypes include large diversified insurers, specialist cyber underwriters, and technology-focused solution providers. Dominant competitive moves involve expanding service bundles to include pre-breach consulting and leveraging extensive historical claims data for refined risk models.
On the premium-tier vector, Chubb exemplifies a large diversified insurer, leveraging its extensive historical claims data and dedicated cyber units to refine complex risk models. Specialist insurer Beazley differentiates its offerings by bundling pre-breach consulting and post-incident response services with its policies. AIG sustains its market position through high-capacity coverage tailored to the complex needs of large multinational corporations.
| Leading Market Players |
|---|
| Chubb |
| AXA XL |
| Travelers |
| Fairfax Financial |
| AIG |
| Beazley |
| Zurich Insurance |
| AXIS Capital |
| Hiscox |
| Others |
Cost & Logistics Intelligence
Data-driven risk modeling is reshaping underwriting practices, simultaneously shifting the geography of expertise and influencing policy premium structures. This transition from traditional assessment methods to analytical platforms impacts how insurers quantify complex cyber risks across industries.
Pricing Analysis
Long-term contract-based policies dominate the cyber insurance market, reflecting the continuous nature of cyber threats. Pricing differentiates based on a client's security posture, assessed through AI underwriting tools, and the customization level required for complex enterprise risks. Pricing pressure stems from the increasing frequency and sophistication of state-sponsored cyberattacks, driving up potential claim costs. Small and medium-sized enterprises (SMEs) exhibit higher price sensitivity, while large multinational corporations prioritize comprehensive coverage and higher liability limits.
Supply Chain Analysis
Short lead times for incident response services are critical for effective cyber policy delivery, necessitating localized expertise. Geographic concentration of supply for specialized services centers on major financial hubs like New York City, London, and Munich, where skilled cybersecurity professionals are abundant. The supply chain draws from a diverse pool of cybersecurity professionals, historical claims data, and advanced AI underwriting platforms. Single-source vulnerability for niche forensic expertise represents a structural risk. Distribution runs through a hybrid model, combining specialist brokers for complex risks with online marketplaces for standardized SME products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cyber insurance market is entering a recovery phase, driven by the cyclical nature of cyber threat sophistication and regulatory responses. This dynamic environment creates opportunities for strategic positioning.
For Market Incumbents: Consolidate market share through strategic acquisitions of specialist cybersecurity firms, integrating their incident response expertise. Invest heavily in AI-driven underwriting platforms to refine complex risk models, mitigating the threat from emerging technology-focused solution providers. Deepen vertical integration into pre-breach consulting services, enhancing client security and reducing future claims. Expand high-capacity coverage offerings, particularly for critical infrastructure sectors, leveraging extensive historical claims data.
For New Entrants and Emerging Players: Rapid certification pathways for new AI-powered underwriting tools could enable faster market entry for technology-focused insurers. Target the underpenetrated SME market in Southeast Asia with standardized, lower-cost policy products. Focus on operational technology (OT) coverage for industrial sectors, addressing a distinct, critical risk vector. A potent go-to-market angle involves bundling insurance with existing cybersecurity software platforms, disrupting traditional broker-led channels.
For Investors and Strategic Acquirers: The market sits at a growth acceleration phase that favors specialist cyber underwriters with deep technical expertise. Long-term viability is strong, sustained by persistent cyber threats and evolving regulatory mandates across the analysis window. Target acquisition profiles include agile technology-focused solution providers or specialist insurers with established pre-breach and incident response capabilities. The signal to watch is the standardization of loss data across the industry, which will enhance actuarial modeling accuracy.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI-driven Underwriting Platforms | Automates risk assessment, enabling carriers like Chubb to refine complex models for diverse client needs. |
| Expand Pre-breach Consulting Services | Differentiates offerings by mitigating losses before they occur, improving client security posture for Beazley. |
| Target Operational Technology Coverage | Addresses critical underinsured risk vectors in manufacturing and energy sectors, expanding market reach. |
| Develop Embedded Insurance Models | Disrupts traditional distribution channels, offering simplified procurement for SMEs in North America and Europe. |
| Invest in Cybersecurity Talent Development | Mitigates actuarial talent scarcity and incident response expertise gaps, enhancing service quality for AIG. |
Research Approach
Initial hypotheses were tested against primary input from insurance executives, cybersecurity experts, corporate risk managers, and specialist brokers, and refined through iterative feedback. This involved combining insights from direct interviews with rigorous secondary validation using publicly available data. Secondary sources included SEC filings, industry association reports, and regulatory body publications from GDPR, HIPAA, and China's Cybersecurity Law. The analysis employed both bottom-up and top-down triangulation to ensure data consistency.
Variance decomposition identified key drivers impacting market growth, segment shifts, and regional adoption patterns across the analysis window. The analytical framework modeled segmentation dimensions including policy type, industry vertical, application, distribution channel, and regional regulatory frameworks. Compound annual growth rates (CAGRs) were derived from historical growth trends and projected future demand. Industry-specific forecast inputs included cyber incident frequency rates and evolving regulatory compliance costs.
Underlying assumptions cover evolving threat landscapes, regulatory stability, and technological advancements, with deviation risk concentrated in geopolitical events or unforeseen systemic cyberattacks. Forecasts reflect these assumptions, acknowledging the dynamic nature of the cyber threat environment. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Middle East and Africa Travel Insurance Market
Insurance
India Liability Insurance Market
Insurance
Social Media Analytics-Based Insurance Market
Insurance
Travel Insurance Market
Insurance
Aerial Imaging in Insurance Service Market
Insurance
USA Travelers Insurance Market
Insurance
Asia-Pacific EV Insurance Market
Insurance
Agricultural Insurance Market
Insurance
Aviation Insurance Market
Insurance
Germany Car Insurance Market
Insurance
Gap Insurance Market
Insurance
Europe Electronic Gadgets Insurance Market
Insurance
Business Travel Insurance Market
Insurance
Germany Reinsurance Market
Insurance
Djibouti Insurance Market
Insurance
Insurance Big Data Analytics Market