
 Self Funded Insurance Market | 2026-2036
Self Funded Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Self Funded Insurance Market Outlook
ERISA fiduciary rule evolution is rebalancing the cost-of-entry calculus for new self-funded plan sponsors. UnitedHealth Group leverages its captive PBM infrastructure to control medical spend volatility for large employers. Cigna anchors its competitive position through integrated stop-loss and behavioral health carve-outs. Elevance Health specializes in regional provider network density that sustains per-employee-per-month predictability.
Self funded insurance denotes employer-sponsored health benefit arrangements where the sponsoring organization assumes direct financial responsibility for claims payment, typically capping exposure through specific and aggregate stop-loss policies with attachment points calibrated to group size and experience. Its primary commercial purpose centers on eliminating insurer risk margins and state premium taxes while retaining claims data ownership for population health intervention. The plan type dimension shows self-insured plans dominating mid-market and large employer segments, while stop-loss plans capture expanding margin pools as attachment points compress and coverage terms lengthen. Across client size, medium enterprises represent the fastest structural expansion as third-party administrators reduce minimum enrollment thresholds and level-funded products blur the self-funded boundary.
The US Department of Labor enforces ERISA reporting and fiduciary standards that shape plan sponsor liability and third-party administrator selection criteria, while state insurance commissioners regulate stop-loss policy forms and minimum attachment point rules that determine market access for smaller groups. The NAIC model stop-loss law is gaining adoption across multiple states, creating uneven regulatory terrain that advantages multi-state employers with centralized benefits administration. Stakeholders must monitor state-level stop-loss regulatory convergence and the emerging interplay between federal transparency mandates and employer claims data strategies.
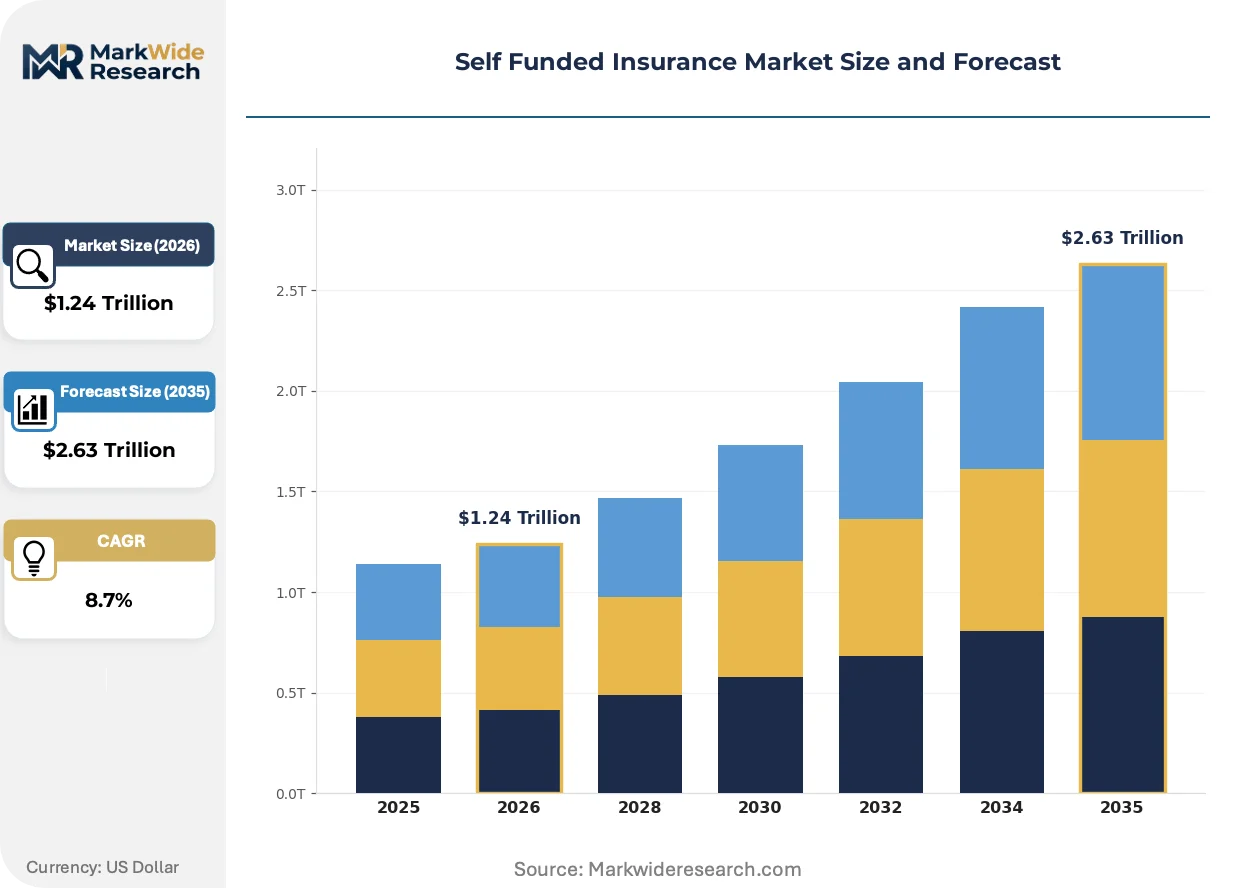
Market Dynamics
ERISA fiduciary rule evolution is compressing the risk-adjusted return threshold for new self-funded plan sponsors, forcing third-party administrators to recalibrate minimum enrollment thresholds and attachment point structures.
Growth Catalysts
- Texas regulatory environment:The state's permissive stop-loss policy framework and absence of premium taxes attract mid-sized manufacturing employers seeking cost containment alternatives.
- Level-funded product innovation:Hybrid arrangements blending self-funded flexibility with fully-insured predictability lower entry barriers for groups below 100 lives.
- OSHA workplace health integration:Self-funded sponsors leverage claims data ownership to align occupational health programming with medical spend intervention.
Market Restraints
- Stop-loss carrier concentration:Reinsurance capacity for specific policies below $50,000 attachment points concentrates among a narrow tier of specialty underwriters.
- HIPAA interoperability friction:Claims data extraction from legacy payer systems imposes technical and legal barriers on plan sponsors seeking population health analytics.
- State premium tax arbitrage limits:Fully-insured plan conversion economics narrow as several states impose assessment mechanisms on self-funded arrangements.
Strategic Opportunities
- Ohio manufacturing corridor:Industrial employers in the Great Lakes region demonstrate elevated self-funding penetration potential due to union-negotiated benefit structures.
- Behavioral health carve-out convergence:Integration of mental health utilization management with stop-loss coverage creates differentiated product positioning.
- IRA transparency mandate alignment:Federal price disclosure requirements enable plan sponsors to deploy reference-based pricing with legal cover.
Industry Challenges
- Actuarial talent scarcity:Pricing expertise for small-group stop-loss sits concentrated among retiring specialists with limited knowledge transfer pathways.
- TPA system integration complexity:Legacy claims administration platforms resist seamless data exchange with modern analytics and member engagement tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self Funded Insurance Market |
| Market Size in 2026 | $1.24 Trillion |
| Market Size in 2035 | $2.63 Trillion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Plan Type: Self-Insured Plans, Fully Funded Plans, Stop-Loss Plans, Hybrid Plans Industry Vertical: Manufacturing, Technology, Retail, Healthcare Client Size: Small Businesses, Medium Enterprises, Large Corporations, Non-Profits Service Offering: Claims Administration, Risk Assessment, Employee Benefits, Wellness Programs |
| Companies Covered | Humana, Kaiser Permanente, UnitedHealth Group, Cigna, Health Care Service Corporation, Elevance Health, CVS Health, Molina Healthcare, Centene Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self Funded Insurance Market Strategic Shifts
Artificial intelligence deployment in claims adjudication and predictive modeling is restructuring how plan sponsors manage medical spend volatility and intervene on emerging high-cost claimants.
Machine learning algorithms trained on historical claims patterns is rewriting the speed and precision of stop-loss renewal pricing. Large employers with multi-year experience data deploy these tools to negotiate attachment point reductions. The compression of underwriting cycle time from quarterly to monthly is enabling dynamic benefit adjustments.
The NAIC model stop-loss law is generating uneven regulatory terrain across state insurance departments. Multi-state employers face conflicting minimum attachment point rules and policy form requirements. Organizations with centralized benefits administration capabilities capture structural advantages in this fragmented compliance environment.
Reference-based pricing models are displacing traditional PPO network arrangements among cost-sensitive mid-market sponsors. Employers in Texas and Florida lead this transition, contracting directly with health systems at Medicare-plus-percentage benchmarks. The unbundling of network access from claims administration is reshaping third-party administrator value propositions.
Self Funded Insurance Market Segmentation
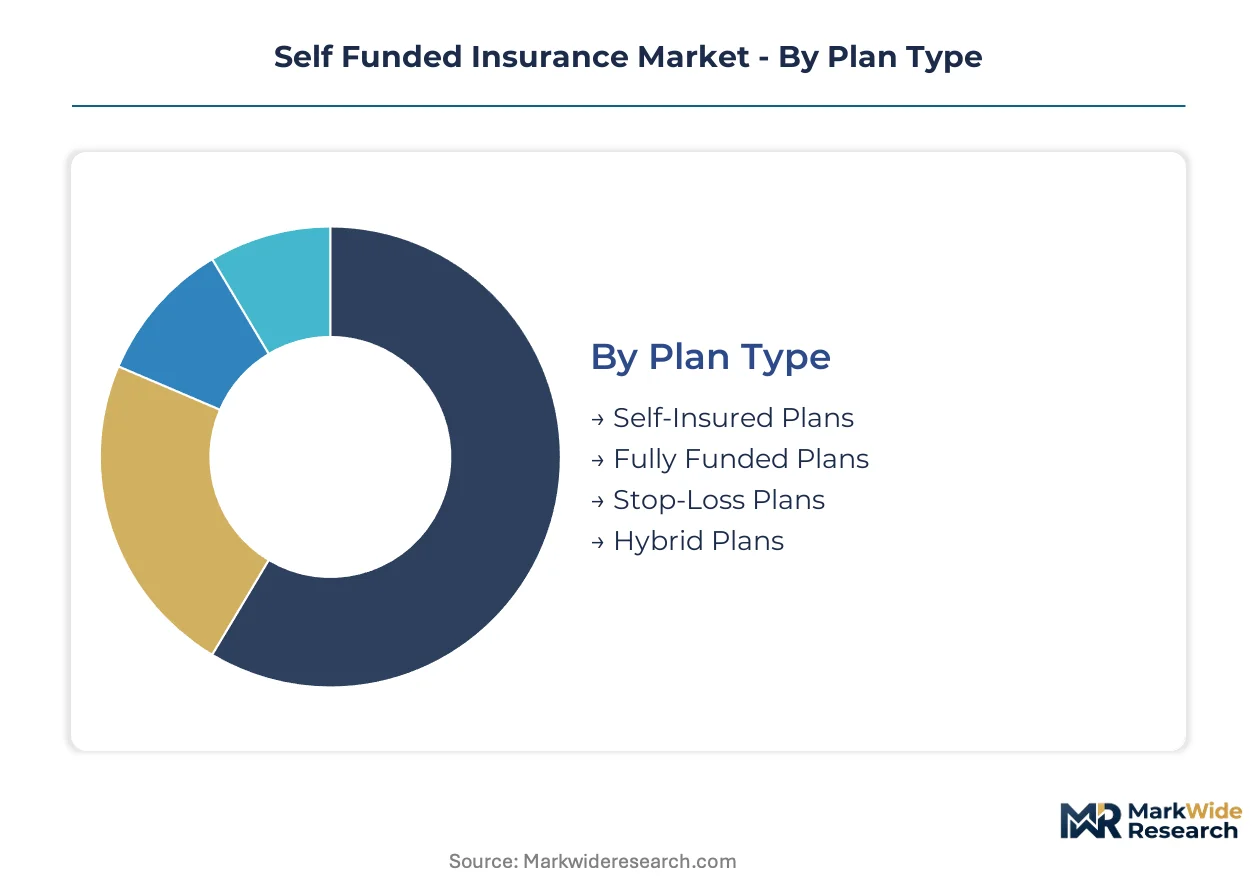
Self-funded insurance segmentation reveals how plan sponsors calibrate risk retention against administrative complexity. Each axis—plan structure, industry exposure, organizational scale, and service bundling—determines stop-loss attachment strategies and third-party administrator selection criteria.
Plan Type:
Plan architecture governs capital reserve requirements and regulatory filing obligations.
- Self-Insured Plans:Employers assume direct claims liability while purchasing specific and aggregate stop-loss coverage to cap catastrophic exposure. Large manufacturers in Ohio and Texas dominate this segment due to predictable workforce demographics and union-negotiated benefit structures that accommodate experience-rated pricing.
- Stop-Loss Plans:Reinsurance mechanisms that transfer excess risk above calibrated attachment points, with specific policies covering individual catastrophic claims and aggregate policies covering total plan exposure. Demand concentrates among mid-sized employers seeking to self-fund without bearing unlimited tail risk, particularly in Florida's permissive regulatory environment.
- Fully Funded Plans:Traditional insurance arrangements where carriers assume complete claims risk and administrative burden.
- Hybrid Plans:Level-funded structures blending self-funded flexibility with fully-insured premium predictability for groups below traditional self-funding thresholds.
Mature deployment sits with Self-Insured Plans. Newer deployment is concentrated in Hybrid Plans.
Industry Vertical:
Occupational risk profiles and workforce density shape claims experience predictability.
- Manufacturing:Industrial employers with unionized workforces and elevated occupational health exposure leverage self-funding to integrate OSHA compliance with medical spend management. The Great Lakes corridor demonstrates concentrated adoption due to legacy benefit structures and centralized plant locations.
- Technology:Younger, healthier employee populations with lower per-employee-per-month volatility attract self-funding for claims data ownership and personalized wellness intervention.
- Retail:High-turnover workforces with seasonal employment patterns create challenges for experience rating stability.
- Healthcare:Hospital systems and provider organizations self-fund to capture internal clinical cost advantages and steer employees to owned facilities.
Manufacturing anchors established self-funding penetration. Technology employers are climbing the fastest as workforce demographics favor predictable risk pools.
Client Size:
Enrollment scale determines stop-loss market access and administrative cost efficiency.
- Medium Enterprises:Organizations with 100-999 employees represent the steepest expansion trajectory as TPAs compress minimum enrollment thresholds and level-funded products blur entry barriers. Third-party administrators now serve groups below 50 lives in Texas and Florida.
- Large Corporations:Multi-state employers with centralized benefits administration capture structural advantages from fragmented state stop-loss regulation.
- Small Businesses:Groups below 100 lives face narrow reinsurance capacity and elevated specific attachment points.
- Non-Profits:Mission-driven organizations with limited capital reserves gravitate toward hybrid arrangements preserving budget predictability.
Large Corporations dominate claims volume. Medium Enterprises are gaining share fastest as product innovation democratizes access.
Service Offering:
Administrative bundling intensity shapes sponsor control over medical spend intervention.
- Claims Administration:Core TPA function encompassing adjudication, provider payment, and regulatory reporting under ERISA fiduciary standards.
- Risk Assessment:Actuarial services calibrating stop-loss attachment points and renewal pricing based on historical experience.
- Employee Benefits:Enrollment, eligibility management, and member communication infrastructure.
- Wellness Programs:Population health interventions leveraging claims data ownership to target high-cost claimant identification and chronic disease management.
Claims Administration captures the deepest market penetration. Wellness Programs are expanding most quickly as sponsors seek return on data ownership investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas Enterprise Zones and Florida Opportunity Zones concentrate self-funded insurance formation through premium tax abatements and permissive stop-loss regulatory frameworks. These designated areas attract mid-sized manufacturing employers seeking cost containment alternatives to fully-insured arrangements.
United States
The US Department of Labor's evolving ERISA fiduciary posture reshapes sponsor liability calculations and TPA selection criteria across the country. The NAIC model stop-loss law generates uneven regulatory terrain across state insurance departments, complicating multi-state employer compliance. Ohio's manufacturing corridor demonstrates concentrated adoption where union-negotiated benefit structures accommodate experience-rated pricing and centralized plant locations enable administrative efficiency.
Canada
Provincial health system variations create demand for supplemental self-funded arrangements among large employers seeking drug and dental benefit control. Health Canada's pharmaceutical pricing regulations indirectly shape stop-loss attachment strategies for catastrophic drug claims. Ontario's automotive manufacturing cluster anchors regional penetration as industrial employers leverage claims data ownership for occupational health integration.
United Kingdom
The Financial Conduct Authority's conduct standards influence employer-sponsored healthcare trust structures and fiduciary governance expectations. Post-Brexit regulatory divergence from EU insurance frameworks creates complexity for multinational employers with UK operations. London's financial services concentration drives demand for executive medical self-funding among investment banks and insurance firms seeking benefit differentiation.
Germany
Betriebskrankenkassen competition and statutory health insurance contribution structures create pressure for large employers to explore self-funded alternatives for supplementary benefits. The Federal Financial Supervisory Authority (BaFin) regulates captive insurance arrangements that employers use to manage healthcare exposure. Baden-Württemberg's automotive engineering cluster shows emerging interest as industrial employers seek population health data control for workforce productivity management.
Australia
The Australian Prudential Regulation Authority's private health insurance reforms reshape employer-sponsored healthcare arrangements and self-funding feasibility assessments. Medicare levy surcharge thresholds influence employer decisions to self-fund supplementary benefits rather than direct employees to individual coverage. New South Wales and Victoria's professional services concentrations drive demand among law firms and consulting practices seeking claims data ownership for wellness program targeting.
Self Funded Insurance Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the self-funded insurance value chain, creating a tiered market structure where scale advantages clash with service customization capabilities. UnitedHealth Group, Cigna, and Elevance Health anchor the diversified tier with integrated PBM, stop-loss, and network infrastructure. Pure-play third-party administrators and specialty stop-loss underwriters occupy the mid-market with targeted enrollment thresholds and attachment point flexibility. Competitive moves concentrate on vertical integration into pharmacy benefit management and strategic partnerships with behavioral health carve-out specialists.
Within the integrated payer tier, UnitedHealth Group exemplifies diversification through captive PBM infrastructure that controls medical spend volatility for large employers. Cigna occupies a position emphasizing integrated stop-loss and behavioral health carve-outs as competitive differentiators. Elevance Health represents regional network density specialization that sustains per-employee-per-month predictability for mid-market sponsors. These three entities anchor distinct strategic archetypes—pharmacy-centric, mental-health-integrated, and regionally-focused—shaping how competitors position alternative value propositions.
| Leading Market Players |
|---|
| Humana |
| Kaiser Permanente |
| UnitedHealth Group |
| Cigna |
| Health Care Service Corporation |
| Elevance Health |
| CVS Health |
| Molina Healthcare |
| Centene Corporation |
| Others |
Value Chain & Pricing Dynamics
Stop-loss reinsurance capacity flows through a concentrated underwriting layer where attachment point calibration determines pricing tiers downstream. Specific policy pricing for mid-sized employers in Texas and Florida compresses as specialty underwriters compete for premium dollars, while aggregate coverage retains margin in the catastrophic tail.
Pricing Analysis
Short lead-time pricing premiums attach to stop-loss policies with expedited underwriting cycles, while annual renewal contracts trade at standard rates. Three-tier pricing structure across premium, standard, and economy levels separates large employers with multi-year experience data from mid-market sponsors with limited claims history and small groups below 100 lives. Pricing pressure stems from carrier concentration in specific attachment points below $50,000, where narrow reinsurance capacity forces sponsors toward higher retentions. Small businesses demonstrate the highest price sensitivity, while large corporations with captive bargaining power capture the most favorable terms.
Supply Chain Analysis
Regional distribution of third-party administrator infrastructure follows hub-and-spoke patterns centered on Dallas, Miami, and Columbus to serve manufacturing corridors. Claims administration capacity concentrates in the United States, with emerging nodes in Ontario and London serving multinational employers. Raw material dependencies include actuarial talent pools, legacy system integration expertise, and stop-loss reinsurance treaties. Single-source vulnerability sits with retiring actuarial specialists whose pricing knowledge lacks transfer pathways. Distribution runs through direct employer-TPA relationships, with stop-loss coverage layered through specialty underwriters and reinsurance markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stop-loss reinsurance capacity constraints prop pricing across the mid-market, as specialty underwriter concentration limits supply response to sponsor demand growth.
For Market Incumbents: Cement market position through captive PBM infrastructure that controls pharmaceutical spend volatility, and deepen backward integration into behavioral health carve-out capabilities. The threat of level-funded product erosion from fully-insured carriers demands defensive moves. Capacity addition in Texas and Florida represents the priority lever for geographic defense. For New Entrants and Emerging Players: Launch via level-funded distribution partnerships targeting manufacturing employers in Ohio's Great Lakes corridor. The most penetrable segment sits with medium enterprises of 100-500 employees currently priced out of traditional self-funding by elevated attachment points. Reference-based pricing enablement offers a distinct go-to-market angle against legacy PPO-dependent competitors. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional TPA specialists with dense provider network relationships in underserved manufacturing geographies. Long-term viability hinges on data infrastructure that converts claims ownership into population health intervention revenue. The signal to watch is NAIC model stop-loss law adoption velocity across state insurance departments as regulatory fragmentation arbiter.| Strategic Initiative | Industry Significance |
|---|---|
| Captive PBM Infrastructure | UnitedHealth Group's pharmacy-centric model demonstrates how drug spend control anchors large employer retention. |
| Behavioral Health Carve-out Integration | Cigna's mental health bundling with stop-loss creates differentiated positioning against pure-play administrators. |
| Regional Provider Network Density | Elevance Health's local concentration strategy sustains per-employee-per-month predictability for mid-market sponsors. |
| Level-Funded Product Expansion | TPA compression of minimum enrollment thresholds below 50 lives democratizes self-funding access in Texas and Florida. |
| Reference-Based Pricing Enablement | Direct Medicare-plus contracting with Texas health systems displaces traditional PPO network economics. |
Study Parameters
Document review covered ERISA fiduciary guidance, NAIC model stop-loss law filings, and state insurance department regulatory bulletins, complemented by interviews with third-party administrator executives, stop-loss underwriters, and employer benefits directors. Primary fieldwork included discussions with manufacturing HR leaders in Ohio, Texas, and Florida regarding plan sponsor decision criteria. Secondary validation drew from US Department of Labor enforcement data, CMS Medicare cost reports, and state premium tax assessment records. Bottom-up enrollment data triangulated against top-down market size estimates from payer financial disclosures.
Segmentation outputs reflect employer size tiers, plan architecture categories, and industry vertical exposure modeled across the projection horizon. The analytical framework incorporated stop-loss attachment point trends, TPA market entry thresholds, and regulatory adoption patterns for the NAIC model law. CAGRs derived from historical self-funding penetration rates, employer premium cost trends, and reinsurance capacity expansion trajectories. Forecast inputs included manufacturing employment density by state, union-negotiated benefit structure prevalence, and level-funded product innovation cycles.
Regulatory enforcement shifts, stop-loss carrier consolidation, and ERISA litigation trends are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions regarding state regulatory convergence and employer risk tolerance stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Embedded Insurance Market
Insurance
India Travel Insurance Market
Insurance
Europe Road Assistance Insurance Market
Insurance
India Electronic Gadget Insurance Market
Insurance
Logistics Insurance Market
Insurance
Reinsurance Market
Insurance
United Kingdom Parametric Insurance Market
Insurance
AI in Insurance Market
Insurance
Marine Freight Insurance Market
Insurance
Asia-Pacific Livestock Insurance Market
Insurance
Global Property and Casualty Reinsurance Market
Insurance
China Property and Casualty Insurance Market
Insurance
Europe Extended Warranty Market
Insurance
UK Electronic Gadgets Insurance Market
Insurance
United States Commercial Insurance Market
Insurance
Insurance Protection Products Market