
 Cyber Liability Insurance Market | 2026-2036
Cyber Liability Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Cyber Liability Insurance Market Insights
Market Context
Software-defined risk scoring is decoupling premium calculation from static policy templates, enabling dynamic pricing that adjusts to real-time threat intelligence. Travelers Group leverages proprietary telemetry platforms to refine underwriting precision across mid-market accounts. Chubb INA Group anchors its competitive stance through dedicated cyber claims units staffed with forensic specialists. American International Group competes by extending capacity limits for Fortune 500 clients facing systemic exposure.
Technical Definition and Segment Structure
Cyber liability insurance is a specialized risk transfer instrument that indemnifies organizations against financial losses stemming from data breaches, network intrusions, and privacy violations, with policies typically specifying sub-limits for forensic investigation, legal defense, and regulatory fines. Coverage type segmentation shows network security liability commanding the largest premium pool due to ransomware frequency, while privacy liability exhibits the fastest expansion trajectory as biometric and health data regulations proliferate. Policy structure insights reveal claims-made forms dominating commercial placements because occurrence-based alternatives carry prohibitively expensive tail coverage, and dedicated limits attract enterprises seeking clean protection from shared-limit contagion in tower programs.
Regulatory Framework
SEC disclosure mandates, state-level biometric privacy statutes in Illinois and Texas, and the EU's GDPR enforcement through supervisory authorities across Germany, France, and Ireland are elevating mandatory coverage minimums for publicly traded entities. These frameworks shape demand by converting ambiguous cyber risk into quantifiable compliance liabilities that boards must address through insurance rather than retained reserves. Stakeholders should monitor how regulators synchronize incident reporting timelines with policy notification clauses to avoid coverage disputes.
Market Dynamics
Real-time telemetry integration is compressing underwriting cycles from annual to continuous, forcing carriers to rebuild actuarial infrastructure around streaming threat intelligence feeds rather than static risk questionnaires.
Growth Catalysts
- Ransomware frequency:Financial institutions in the United States are expanding coverage purchases as attack volumes strain retained loss reserves. Board-level risk committees now mandate standalone cyber limits.
- SEC disclosure mandates:The SEC's cybersecurity disclosure rules compel publicly traded entities to formalize risk transfer strategies, converting compliance gaps into quantifiable insurance demand.
- Biometric data proliferation:State-level privacy statutes in Illinois and Texas are elevating mandatory coverage minimums for organizations handling fingerprint and facial recognition data.
Market Restraints
- Capacity concentration:Reinsurance treaty renewals in Bermuda and London are tightening retrocession availability, constraining primary carrier deployment limits for systemic exposures.
- Claims volatility:The absence of standardized cyber incident taxonomy produces reserve development uncertainty, deterring long-tail capital commitment from institutional investors.
- Regulatory fragmentation:Divergent notification timelines between EU GDPR supervisory authorities and US state breach laws create coverage trigger ambiguity in multinational programs.
Strategic Opportunities
- Mid-market penetration:Small and medium enterprises in Germany and France remain underinsured relative to their data asset values, presenting white space for modular policy construction.
- Parametric triggers:Index-based settlement mechanisms using third-party threat intelligence are emerging as alternatives to traditional loss-adjustment protocols.
- Managed detection bundling:Carriers are embedding endpoint monitoring services into policy terms, capturing premium-equivalent revenue through risk control subscriptions.
Industry Challenges
- Forensic talent scarcity:Incident response firms face recruitment bottlenecks for certified breach investigators, extending claim resolution timelines beyond policyholder cash-flow tolerance.
- Legacy system integration:Insurers' core policy administration platforms require middleware development to ingest real-time telemetry, inflating technology modernization budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyber Liability Insurance Market |
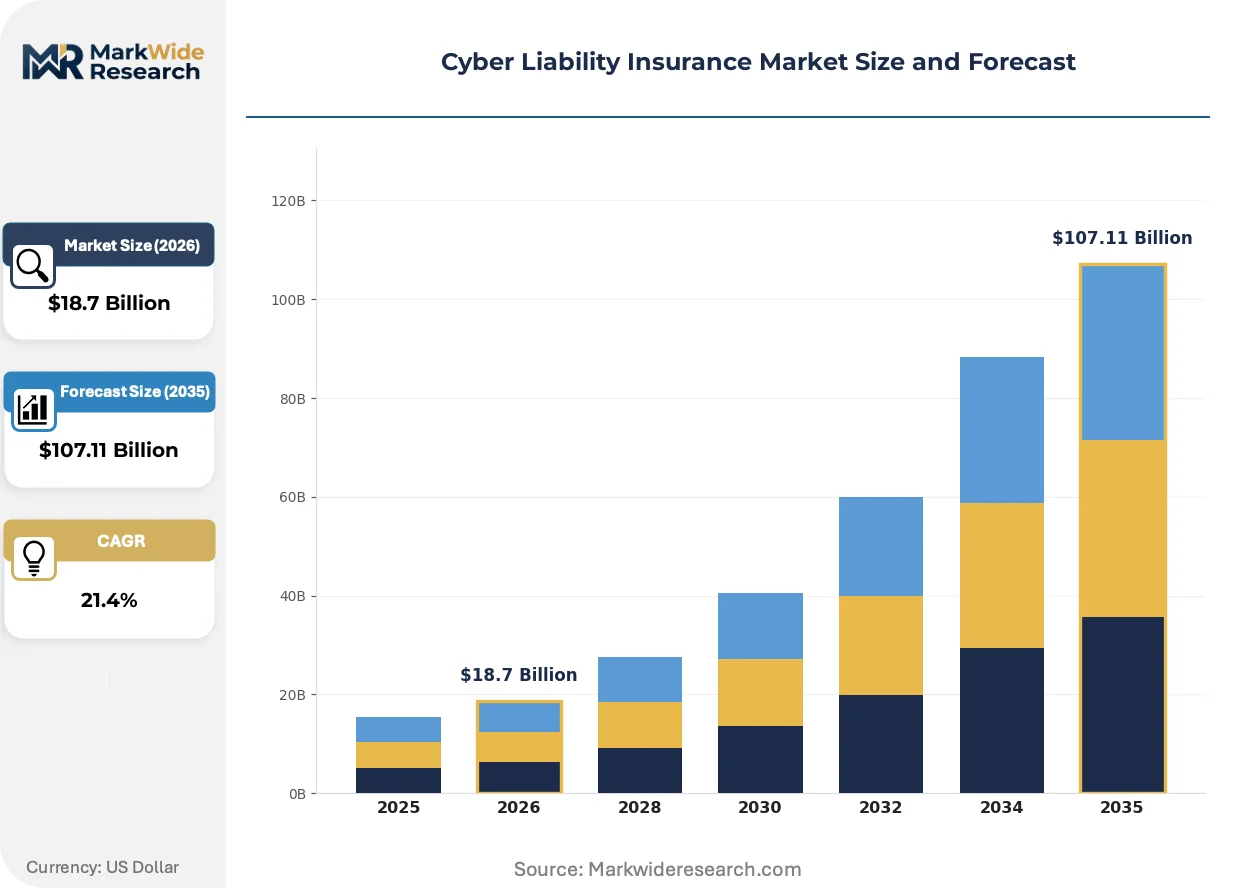
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $107.11 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Data Breach, Network Security Liability, Privacy Liability, Media Liability, Regulatory Defense End User: Financial Institutions, Technology Providers, Telecommunications Firms, Legal Services, Manufacturing Entities Policy Structure: Claims-Made, Occurrence-Based, Dedicated Limits, Shared Limits, Multi-Year Coverage Distribution Channel: Brokers, Direct Sales, Online Platforms, Agents, Bancassurance |
| Companies Covered | Travelers Group, Berkshire Hathaway Insurance Group, Chubb INA Group, American International Group, Arch Insurance Group, XL Reinsurance America Group, Tokio Marine US PC Group, Sompo Holdings US Group, Fairfax Financial Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyber Liability Insurance Market Trends and Innovations
Continuous risk scoring is displacing static underwriting, with carriers embedding telemetry-driven pricing engines that adjust premiums quarterly based on observed security control effectiveness.
Artificial intelligence-powered claims triage is electrifying forensic investigation workflows. Mid-market policyholders are adopting these platforms fastest, compressing breach response initiation from days to hours. This acceleration is enabling carriers to reserve less capital for business interruption tail exposure.
The EU's Digital Operational Resilience Act is mandating financial entities to demonstrate recoverability testing. Insurers are responding by embedding resilience certification requirements into policy eligibility criteria. German and Irish banking supervisors are already synchronizing examination schedules with carrier renewal dates.
Buyers are unbundling cyber coverage from packaged management liability programs. Risk managers at Fortune 500 manufacturing firms are negotiating dedicated towers with clean limits, rejecting shared-limit structures that expose cyber losses to exhaust directors and officers capacity. This procurement rotation is most visible in United States industrial conglomerates with complex international subsidiary networks.
Cyber Liability Insurance Market Segmentation
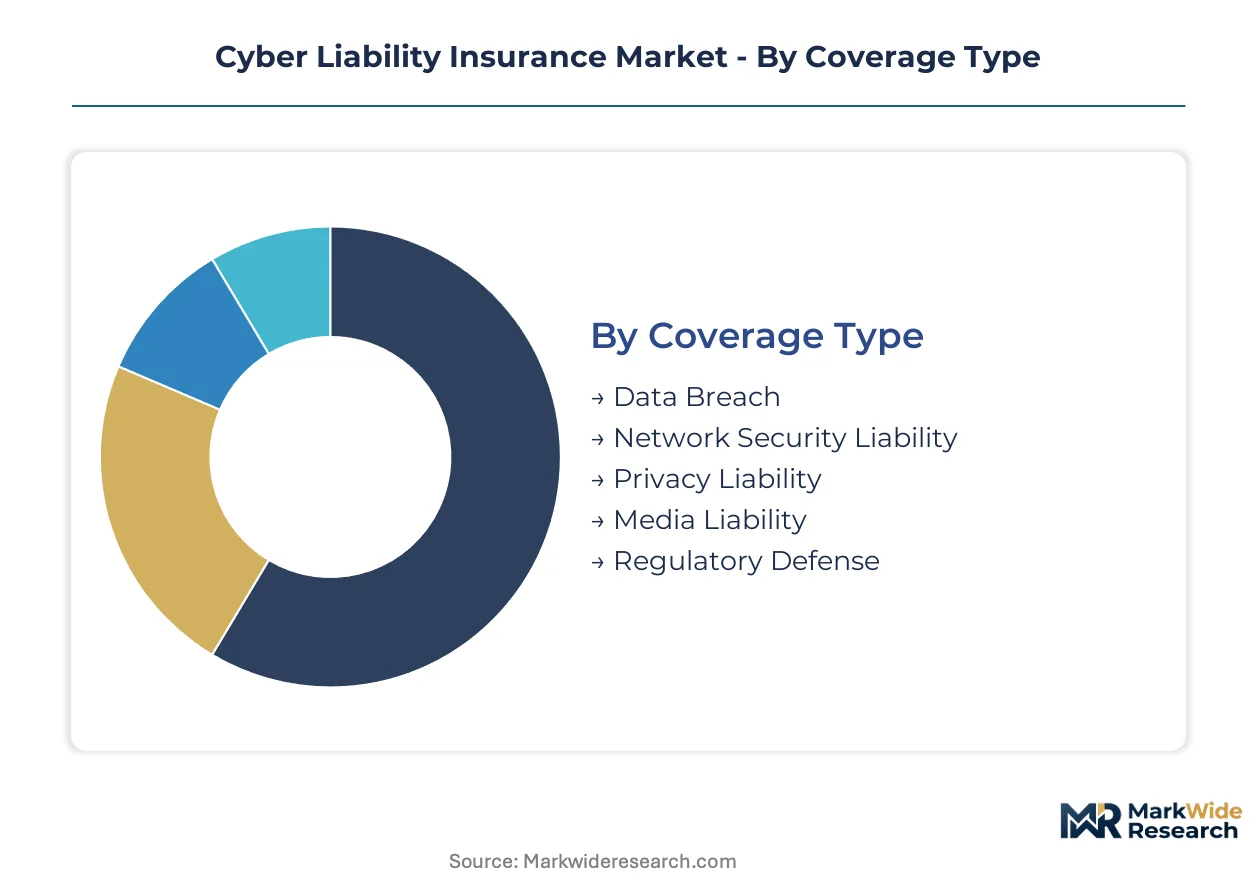
Segmentation in cyber liability insurance determines how carriers allocate capital reserves and price systemic exposure. Each category reflects distinct risk transfer mechanics that shape underwriting precision and policyholder matching.
Coverage Type:
SEC disclosure mandates and state biometric statutes impose divergent certification burdens across coverage types, with privacy liability facing the steepest compliance escalation.
- Data Breach:Indemnifies first-party costs including notification, credit monitoring, and forensic investigation. Financial institutions in the United States concentrate purchases here as ransomware strains retained loss reserves and board committees mandate standalone limits.
- Network Security Liability:Covers third-party claims arising from unauthorized network access or malware propagation. This segment commands the largest premium pool due to ransomware frequency, with mid-market manufacturing entities driving volume in industrial corridors.
- Privacy Liability:Addresses wrongful collection or exposure of personally identifiable information. Illinois and Texas biometric statutes are elevating mandatory coverage minimums for fingerprint and facial recognition handlers.
- Media Liability:Protects against defamation, copyright infringement, and intellectual property disputes in digital content. Technology providers in California and New York represent core demand.
- Regulatory Defense:Reimburses legal costs and fines from supervisory enforcement actions. EU GDPR supervisory authorities across Germany, France, and Ireland are expanding procurement among multinationals.
Network Security Liability sits at the top of the volume ranking, with Privacy Liability climbing the fastest.
End User:
Cost tier segmentation separates Fortune 500 tower programs from modular SME constructions, with premium concentration scaling to data asset value and litigation exposure.
- Financial Institutions:Banks, insurers, and asset managers facing systemic exposure from payment networks and customer data repositories. These entities are expanding coverage purchases as attack volumes strain reserves and SEC rules compel formalized risk transfer.
- Technology Providers:Cloud infrastructure and software vendors with concentration risk across client bases. SaaS platforms in Silicon Valley and Seattle drive demand for dedicated limits.
- Telecommunications Firms:Network operators managing critical infrastructure with national security implications. German and French carriers face EU Digital Operational Resilience Act mandates.
- Legal Services:Law firms holding privileged client information and facing professional liability overlap. London and New York partnerships are unbundling cyber from packaged management liability.
- Manufacturing Entities:Industrial firms with operational technology convergence and international subsidiary complexity. United States conglomerates are negotiating clean-limit towers rejecting shared structures.
Financial Institutions anchor premium concentration, while Manufacturing Entities are gaining share fastest as operational technology risks proliferate.
Policy Structure:
Application-driven segmentation distinguishes transactional commercial placements from strategic multi-year commitments, with claims-made forms dominating due to tail coverage economics.
- Claims-Made:Covers incidents reported during the policy period regardless of when they occurred. This structure dominates commercial placements because occurrence-based alternatives carry prohibitively expensive tail coverage.
- Occurrence-Based:Triggers coverage based on when the wrongful act happened, not when discovered. Long-tail capital commitment constraints limit availability to Fortune 500 clients with captive retention vehicles.
- Dedicated Limits:Provides clean cyber protection without contamination from other liability lines. Risk managers at industrial conglomerates are negotiating these structures to isolate cyber exposure from directors and officers capacity.
- Shared Limits:Pools cyber coverage with management liability or professional liability in combined towers. Mid-market professional services firms accept this structure for premium efficiency.
- Multi-Year Coverage:Locks premium rates across 24-36 month terms for budgeting certainty. Healthcare systems in Illinois and Texas use this structure to match capital planning cycles.
Claims-Made structures dominate placement volume, with Dedicated Limits expanding most quickly as procurement sophistication advances.
Distribution Channel:
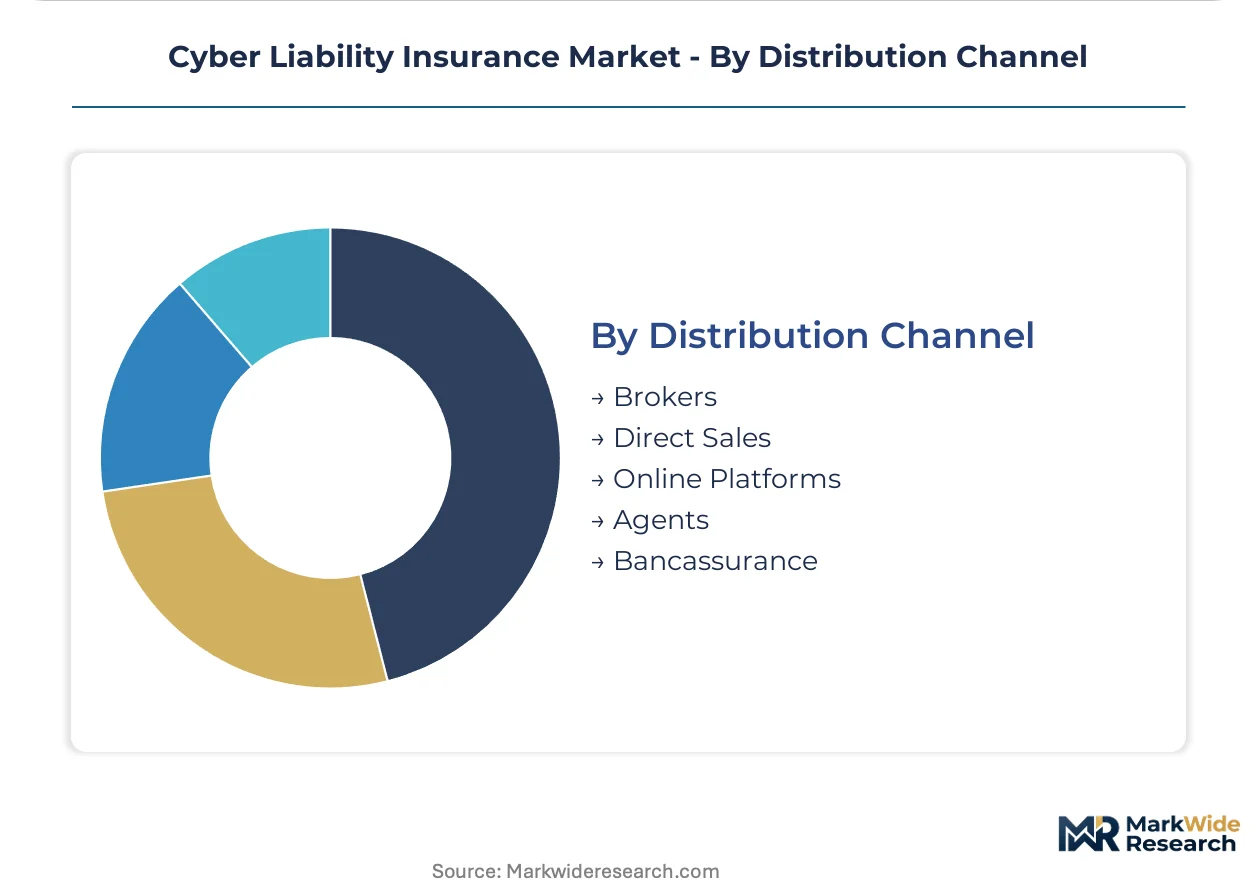
Geography shapes channel effectiveness, with broker dominance in complex tower markets and direct platforms penetrating standardized SME segments.
- Brokers:Independent intermediaries structuring multi-carrier towers and negotiating manuscript endorsements. Marsh, Aon, and Willis Towers Watson control placement flow in London and New York.
- Direct Sales:Carrier-employed underwriters engaging Fortune 500 risk managers on bespoke terms. Chubb and AIG deploy dedicated cyber units for this segment.
- Online Platforms:Digital quoting engines with algorithmic risk scoring for standardized coverage. Next Insurance and Coalition target technology startups and professional services firms.
- Agents:Captive or independent producers binding admitted market paper. State Farm and Allstate agents handle SME commercial package endorsements.
- Bancassurance:Bank-distributed products bundled with commercial lending relationships. German Sparkassen and French mutual banks embed cyber riders into credit facilities.
Brokers command placement volume leadership, while Online Platforms are climbing fastest as telemetry integration compresses underwriting cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting cyber liability capacity toward jurisdictions with clearer claims adjudication frameworks. Bermuda and London reinsurance markets attract cessions from US primary carriers seeking retrocession clarity, while EU supervisory convergence is consolidating placement flow into Frankfurt and Dublin.
United States
Financial institutions in New York and Chicago are expanding tower purchases as ransomware strains retained reserves. SEC disclosure mandates compel publicly traded entities to formalize risk transfer strategies with standalone cyber limits. Silicon Valley technology providers drive demand for dedicated limits rejecting shared management liability structures.
United Kingdom
London market brokers structure multi-carrier towers for multinational manufacturing conglomerates with complex subsidiary networks. Lloyd's syndicates are tightening cyber wording to address systemic exposure accumulation. The Prudential Regulation Authority's operational resilience expectations are synchronizing examination schedules with carrier renewal dates.
Germany
Sparkassen and cooperative banks embed cyber riders into commercial credit facilities through bancassurance channels. The Federal Financial Supervisory Authority enforces Digital Operational Resilience Act recoverability testing mandates. Munich and Frankfurt insurance clusters are embedding resilience certification into policy eligibility criteria.
France
Mutual banks and industrial insurers in Paris are bundling endpoint monitoring services into policy terms. The French Prudential Supervision and Resolution Authority coordinates with carriers on incident reporting timeline synchronization. Auvergne-Rhône-Alpes manufacturing entities are negotiating clean-limit towers to isolate cyber exposure.
Bermuda
Reinsurance treaty renewals are tightening retrocession availability for systemic cyber exposures. The Bermuda Monetary Authority's regulatory clarity on catastrophe bond structures attracts alternative capital. Hamilton-based carriers are developing parametric trigger mechanisms using third-party threat intelligence indices.
Cyber Liability Insurance Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with dedicated cyber carriers commanding premium pricing in Fortune 500 towers while composite insurers penetrate mid-market modular constructions. The vendor base concentrates around three strategic archetypes: telemetry-integrated underwriters leveraging proprietary risk scoring, forensic-specialist claims units with dedicated investigation capabilities, and capacity-extension players offering elevated limits for systemic exposures. Dominant competitive moves include embedding managed detection services into policy terms and constructing multi-year rate-lock structures for healthcare and financial institution accounts.
Within the telemetry-integrated tier, Travelers Group and Chubb INA Group exemplify carriers rebuilding actuarial infrastructure around streaming threat intelligence rather than static questionnaires. American International Group occupies a position at the capacity-extension end, anchoring placement flow for industrial conglomerates with complex international subsidiary networks requiring dedicated clean-limit towers. These three entities represent divergent strategic postures within a market where underwriting precision and claims resolution velocity increasingly determine broker preference.
| Leading Market Players |
|---|
| Travelers Group |
| Berkshire Hathaway Insurance Group |
| Chubb INA Group |
| American International Group |
| Arch Insurance Group |
| XL Reinsurance America Group |
| Tokio Marine US PC Group |
| Sompo Holdings US Group |
| Fairfax Financial Group |
| Others |
Pricing and Supply Chain Analysis
Reinsurance treaty costs flow from Bermuda and London retrocession markets through to primary carrier pricing tiers, with capacity scarcity in retrocession layers compressing margins for Fortune 500 tower programs while mid-market modular constructions retain more pricing flexibility.
Pricing Analysis
Broker placement fees and manuscript endorsement margins stratify pricing across distribution channels, with Marsh, Aon, and Willis Towers Watson commanding premium placement economics for complex multi-carrier towers. Three-tier pricing structure across premium, standard, and economy levels separates dedicated clean-limit programs from shared-limit bundled coverage and modular SME endorsements. Cost compression in mid-market segments is intensifying because online platforms with algorithmic underwriting are compressing acquisition expenses. Small and medium enterprises exhibit highest price sensitivity, while financial institutions facing SEC disclosure mandates demonstrate lowest elasticity.
Supply Chain Analysis
Dual-sourcing requirements for forensic investigation capacity mandate that primary carriers qualify multiple incident response firms, extending claim resolution timelines when certified breach investigators face recruitment bottlenecks. Capital provision concentrates in Bermuda, London, and New York, with reinsurance capacity feeding from Hamilton and Lloyd's into domestic US primary markets. Raw material dependencies include actuarial talent pools, threat intelligence data feeds, and regulatory compliance infrastructure. Single-source vulnerability sits with concentrated forensic specialist firms in London and New York. Distribution runs through broker intermediaries for complex placements and direct carrier engagement for Fortune 500 accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
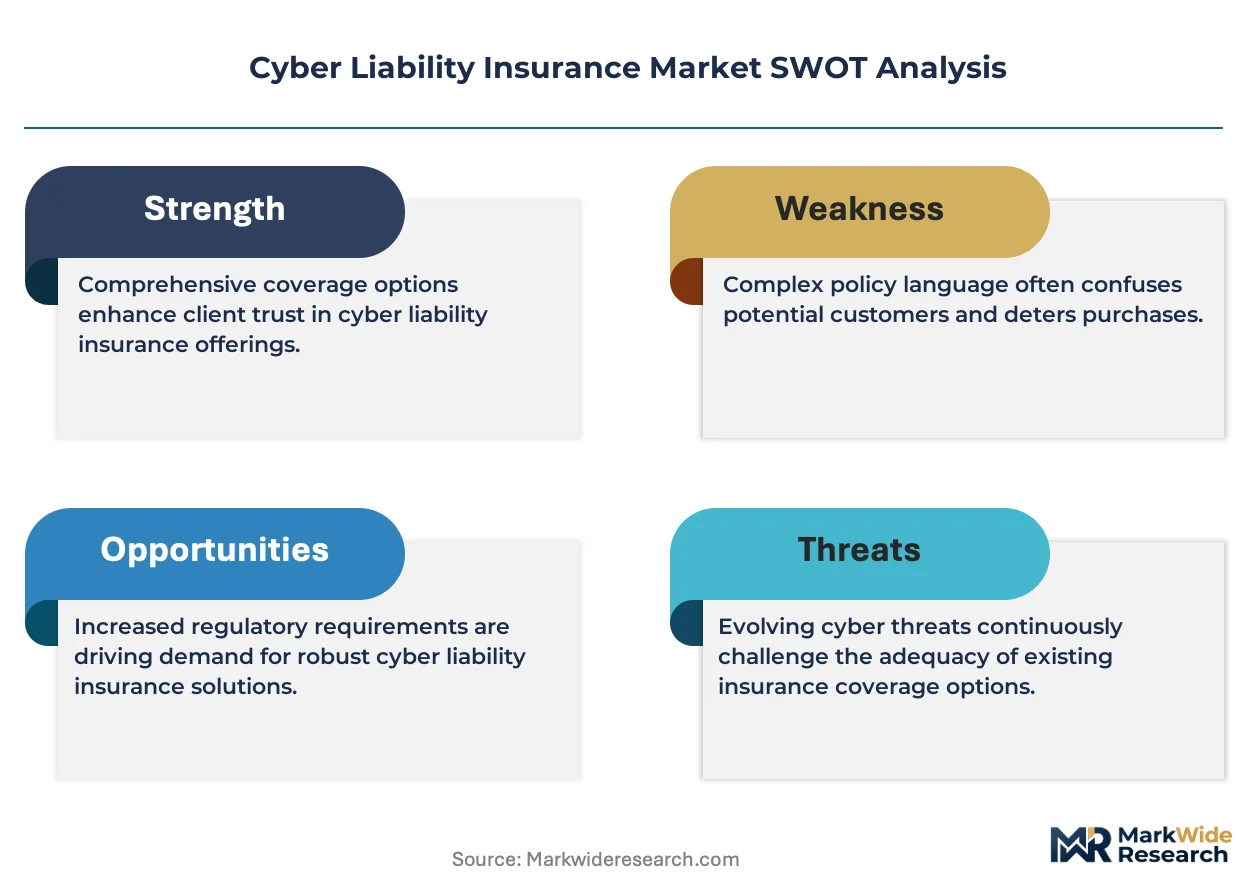
The cyber liability insurance market reads as a late-cycle quality story where board-level procurement committees are shifting demand toward standalone dedicated limits with forensic-specialist claims units.
For Market Incumbents: Deepen telemetry integration investments to defend against algorithmic underwriting platforms compressing mid-market pricing. Chubb and Travelers Group have demonstrated that proprietary risk scoring engines anchored in streaming threat intelligence create retention advantages. Capacity addition in Bermuda retrocession layers addresses systemic exposure accumulation threatening tower program viability.
For New Entrants and Emerging Players: Independent cyber MGAs represent the most penetrable channel partner type for white-space entry, particularly in German and French SME segments where bancassurance distribution remains underdeveloped. Parametric trigger products using third-party threat intelligence indices offer differentiation from traditional loss-adjustment protocols. Managed detection service bundling captures premium-equivalent revenue through risk control subscriptions.
For Investors and Strategic Acquirers: Consolidation pressure builds where forensic talent scarcity extends claim resolution timelines beyond policyholder cash-flow tolerance. Long-term viability centers on carriers with demonstrated integration of continuous risk scoring and dedicated claims units. Acquisition target archetype: telemetry-integrated underwriters with mid-market penetration in underinsured European jurisdictions. Signal to watch: synchronization of EU Digital Operational Resilience Act examination schedules with carrier renewal dates as inflection indicator for regulatory-driven demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Platform Integration | Travelers Group and Chubb leverage proprietary streaming threat intelligence to refine underwriting precision. |
| Forensic Claims Unit Development | Chubb INA Group anchors competitive stance through dedicated cyber claims units staffed with certified investigators. |
| Capacity Limit Extension | American International Group competes by elevating deployment limits for Fortune 500 systemic exposures. |
| Parametric Trigger Product Launch | Bermuda carriers develop index-based settlement mechanisms using third-party threat intelligence as alternative protocols. |
| Managed Detection Bundling | Carriers embed endpoint monitoring services into policy terms, capturing premium-equivalent subscription revenue. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with chief underwriting officers, cyber claims directors, broker placement specialists, and risk managers at Fortune 500 financial institutions with secondary validation. SEC cybersecurity disclosure filings, Lloyd's market returns, NAIC statutory financial data, and EU supervisory authority enforcement records anchored the evidence base. Bottom-up policy count and premium volume estimates triangulated against top-down market sizing from reinsurance treaty disclosures.
Segment-weighting approaches distributed value and volume across coverage type, end user industry, policy structure, and distribution channel dimensions throughout the forecast period. CAGRs derived from fitted growth curves applied to base-year observations, with trajectory adjustments for regulatory mandate implementation timelines and ransomware frequency trends. Threat intelligence platform adoption curves and forensic talent supply constraints entered as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory fragmentation across GDPR supervisory authorities and US state breach laws, reinsurance treaty renewal conditions in Bermuda and London, and the pace of AI-powered claims triage adoption. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Norway Cyber (Liability) Insurance Market
Insurance
Cyber Insurance Market
Insurance
Dental Insurance Market
Insurance
United Kingdom Parametric Insurance Market
Insurance
GCC Health Insurance Market
Insurance
China Group Health Insurance Market
Insurance
India Property & Casualty Insurance Market
Insurance
Norway Property and Casualty Insurance Market
Insurance
Workers Compensation Insurance Market
Insurance
Endowment Insurances Market
Insurance
Telecommunication Insurance Market
Insurance
India Life and Non-Life Insurance Market
Insurance
UK Dental Insurance Market
Insurance
India Health and Medical Insurance Market
Insurance
Directors and Officers (Dando) Insurance Market
Insurance
Data Analytics in Insurance Market