
 Horse Insurance Market | 2026-2036
Horse Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Horse Insurance Market Foresight
Specialized equine veterinary actuaries is rotating from general livestock pools into dedicated horse mortality teams. American Equine Insurance Group leverages this talent migration to sustain its dominance in Thoroughbred mortality underwriting. Blue Bridle Insurance anchors its competitive position through exclusive focus on high-value Warmblood surgical coverage. Petplan Equine differentiates via direct veterinary payment networks that eliminate owner reimbursement delays.
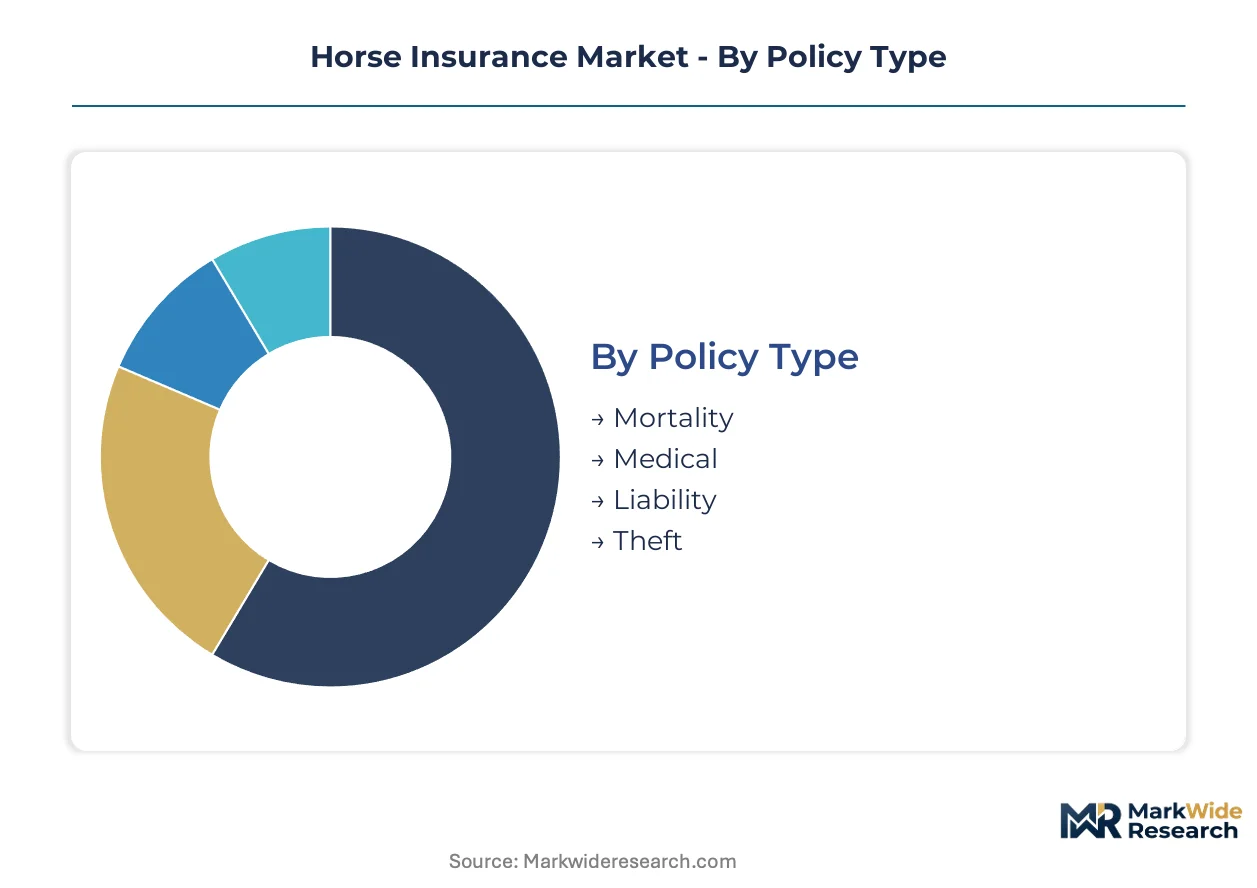
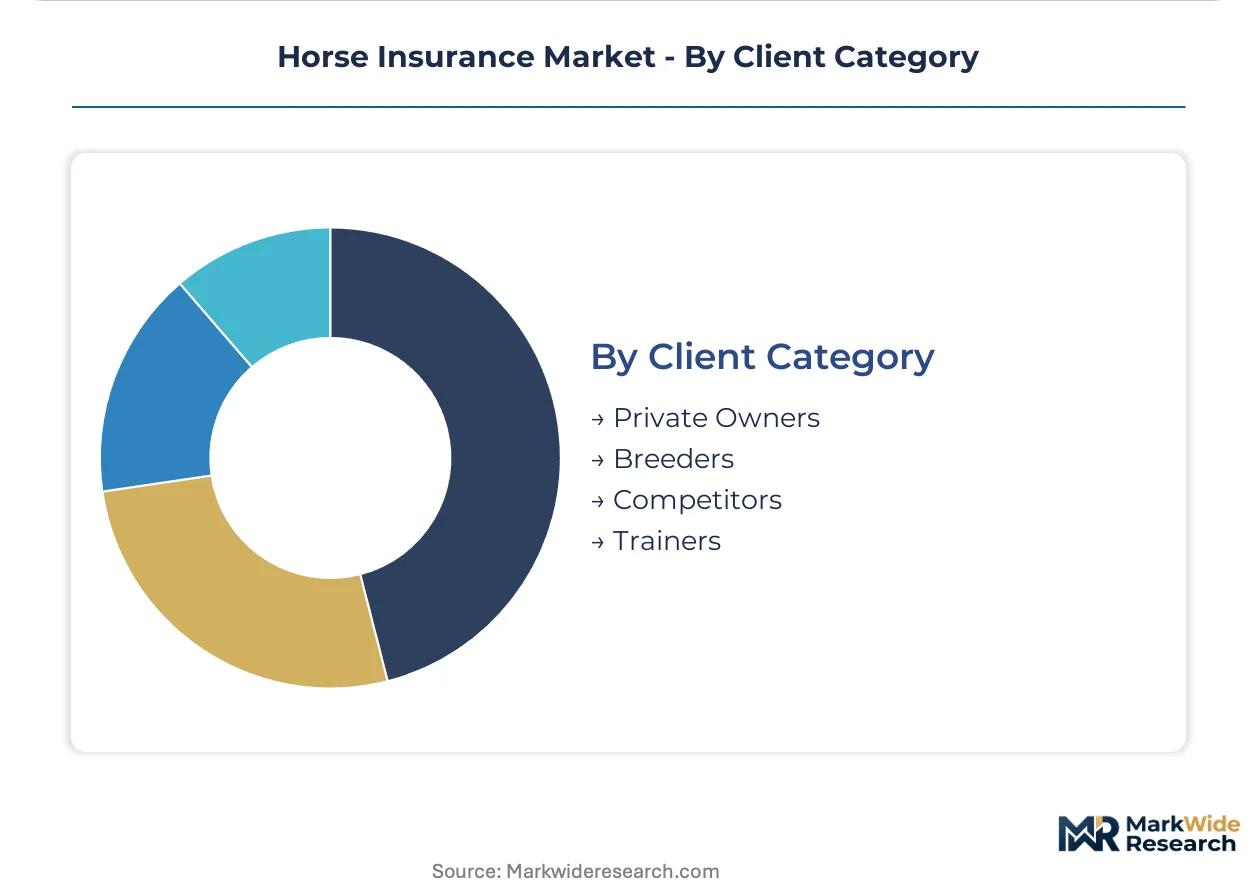
Horse insurance constitutes risk-transfer instruments covering mortality, medical expense, liability, and theft exposures for equids valued across sporting, breeding, and companion purposes. Policies incorporate pre-purchase veterinary examination protocols, bloodstock valuation methodologies, and named-peril exclusions for pre-existing degenerative conditions. Mortality coverage commands the deepest premium pool due to high-value bloodstock concentration, while medical and surgical riders exhibit the fastest expansion as veterinary intervention costs escalate. Client category segmentation reveals private owners as the volume base, though competitors and trainers generate disproportionate loss-adjustment complexity.
US state insurance commissioners enforce NAIC model laws on equine policy disclosures, while the EU's Animal Health Law mandates traceable welfare documentation that insurers increasingly embed as coverage conditions. The UK's Financial Conduct Authority scrutinizes pet and equine policy transparency under consumer duty rules. Stakeholders must monitor how climate-driven disease vector expansion reshapes regional mortality tables and veterinary capacity constraints.
Market Dynamics
Veterinary capacity constraints in Kentucky's Bluegrass region and Ireland's County Kildare are forcing insurers to embed telemedicine protocols into standard coverage terms, fundamentally restructuring how mortality risk gets assessed and priced.
Growth Catalysts
- EU Animal Health Law:Mandatory welfare documentation requirements create coverage conditions that expand policy attachment rates among breeding operations seeking compliant risk transfer instruments.
- Warmblood surgical riders:Rising veterinary intervention costs for dressage and show jumping disciplines accelerate premium growth in medical expense coverage segments.
- Thoroughbred racing stables:Expanded liability coverage for veterinary malpractice exposure drives demand concentration in high-value bloodstock corridors.
Market Restraints
- Actuarial talent scarcity:Specialized equine veterinary actuaries rotating from general livestock pools create underwriting capacity bottlenecks in mortality teams.
- Veterinary cost inflation:Surgical and diagnostic procedure escalation compresses loss ratios for medical riders, forcing repricing cycles.
- Regional capacity limits:Concentration of accredited equine hospitals in Kentucky and Kildare restricts claims servicing geography for remote policyholders.
Strategic Opportunities
- Direct veterinary payment networks:Channel innovation eliminating owner reimbursement delays captures loyalty among private owner segments.
- Telemedicine triage protocols:Technology convergence between remote diagnostics and mortality assessment enables real-time underwriting adjustments.
- UK consumer duty rules:FCA transparency mandates create competitive openings for insurers with simplified policy language and clear exclusion definitions.
Industry Challenges
- Bloodstock valuation methodology disputes:Pre-purchase examination protocols generate claims complexity when market values diverge from insured values.
- Climate-driven disease vector expansion:Regional mortality table obsolescence requires continuous recalibration of eastern equine encephalitis and West Nile risk factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Horse Insurance Market |
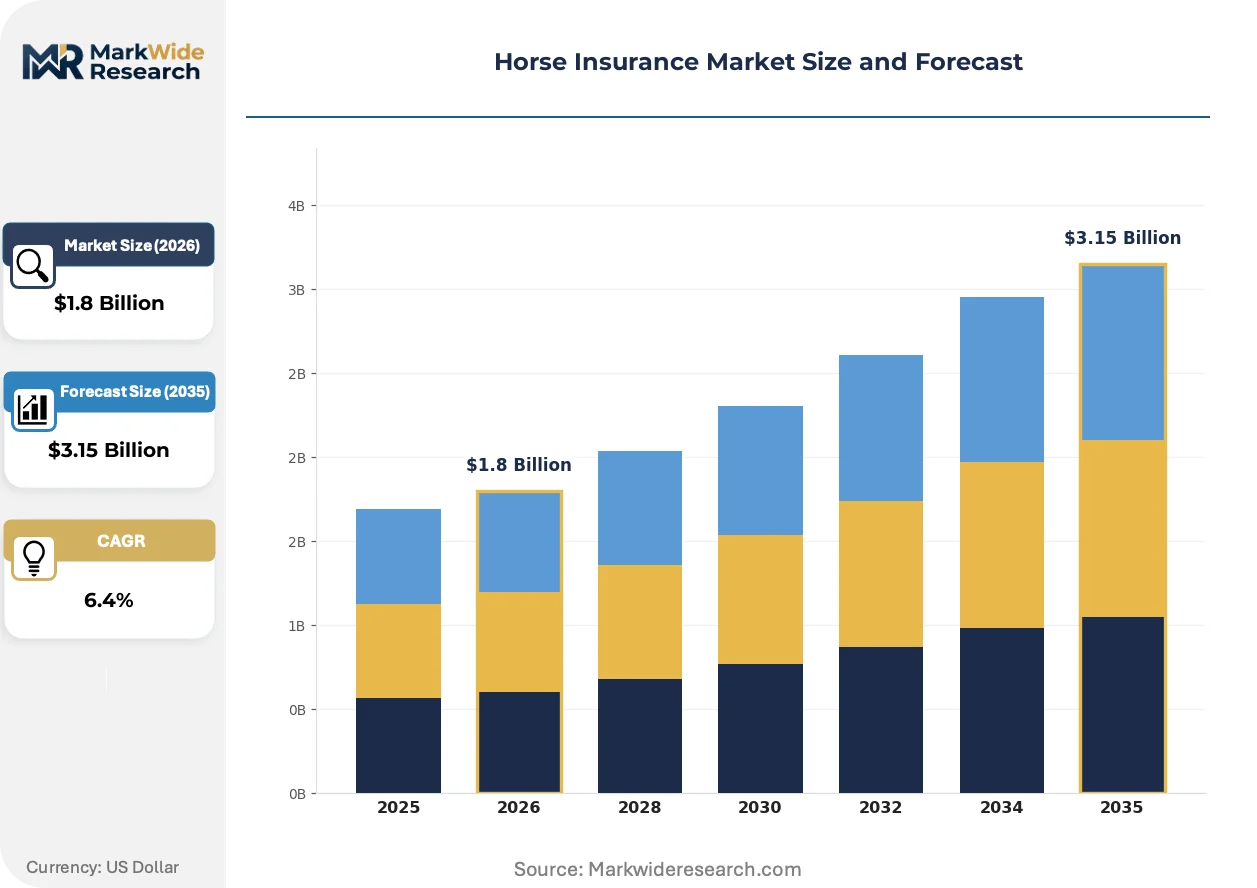
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Mortality, Medical, Liability, Theft Coverage Options: Life, Major Medical, Surgical, Loss of Use Equine Type: Thoroughbred, Warmblood, Quarter Horse, Pony Client Category: Private Owners, Breeders, Competitors, Trainers |
| Companies Covered | American Equine Insurance Group, Agria Pet Insurance, Blue Bridle Insurance, Berkley Equine and Cattle, Kay Cassell Equine Insurance, ASPCA Horse Insurance, Petplan Equine, Equisure, Broadstone Equine Insurance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Horse Insurance Market Shifts & Advancements
Digital underwriting infrastructure is compressing policy issuance timelines from weeks to days, while regulatory documentation mandates and shifting buyer expectations around payment friction are simultaneously reshaping product architecture and distribution economics.
Telematics-enabled biometrics is displacing traditional veterinary examination protocols for mortality coverage renewals. High-value Warmblood owners in Germany and the Netherlands now submit continuous heart-rate, temperature, and movement data through wearable sensors. This real-time health monitoring is displacing scheduled veterinary inspections as the primary risk assessment input, enabling dynamic premium adjustments and accelerating underwriting decisions.
The EU's Animal Health Law mandates traceable welfare documentation across breeding and sporting operations. Insurers increasingly embed compliance verification as a coverage condition, with policy language now requiring digital health passports for cross-border equine movement. Thoroughbred operations in Ireland face the steepest adaptation burden, with brokers reporting extended onboarding timelines for new clients lacking existing documentation infrastructure.
Direct payment networks between insurers and veterinary clinics are eliminating reimbursement friction for policyholders. Petplan Equine and comparable specialists now settle surgical invoices at point-of-service, capturing preference among time-constrained professional trainers and competitors. This channel innovation is most visible in the UK and Ireland, where consolidated veterinary practice groups enable streamlined billing integration. Private owners increasingly select carriers based on network breadth rather than premium price alone.
Horse Insurance Market Segmentation
Segmentation in horse insurance determines pricing precision and loss ratio performance. Policy architecture varies dramatically across equine disciplines, with Thoroughbred mortality commanding fundamentally different actuarial treatment than companion pony medical coverage.
Policy Type:
NAIC model laws in the US and the EU's Animal Health Law create divergent disclosure and documentation obligations that reshape how each policy type gets structured and sold across jurisdictions.
- Mortality:Covers death from accident, illness, or humane destruction with named-peril exclusions for pre-existing degenerative conditions. Bloodstock valuation methodologies generate disputes when market values diverge from insured values, particularly in Kentucky's Bluegrass breeding corridor where high-value Thoroughbreds concentrate.
- Medical:Reimburses veterinary examination, diagnostic, and treatment expenses excluding routine preventive care. Veterinary cost inflation in surgical and diagnostic procedures compresses loss ratios, forcing repricing cycles that vary by regional hospital capacity.
- Liability:Protects against third-party bodily injury or property damage caused by insured equids. Thoroughbred racing stables are expanding this coverage for veterinary malpractice exposure as litigation frequency rises in high-value bloodstock corridors.
- Theft:Covers illegal taking with recovery reward provisions and forensic investigation cost reimbursement. Demand concentrates in regions with documented livestock crime rings.
Mortality handles the majority of throughput; Medical is the fastest mover on share.
Coverage Options:
Premium tiering follows intervention cost escalation, with surgical riders now separating standard from premium positioning across all major markets.
- Life:Lump-sum mortality benefit tied to agreed-value or market-value valuation protocols. Pre-purchase veterinary examination requirements vary by insured value thresholds.
- Major Medical:Annual limit structures with per-incident sublimits and coinsurance provisions. Direct payment networks between insurers and veterinary clinics are eliminating reimbursement friction for this coverage tier.
- Surgical:Standalone or rider coverage for operative procedures with facility accreditation requirements. Rising intervention costs for dressage and show jumping disciplines accelerate premium growth in this segment.
- Loss of Use:Permanent disability coverage triggered by specific performance-impairing conditions. Valuation disputes arise when partial functionality remains.
Major Medical anchors volume placement; Surgical is climbing the fastest on premium contribution.
Equine Type:
Discipline-specific risk profiles and veterinary infrastructure access create divergent underwriting economics across breed categories.
- Thoroughbred:Racing and breeding bloodstock with the highest insured values and most complex mortality table construction. Veterinary capacity constraints in Kentucky and Ireland's County Kildare force telemedicine protocol embedding.
- Warmblood:Dressage, show jumping, and eventing specialists with escalating surgical intervention costs. High-value owners in Germany and the Netherlands now submit continuous biometric data through wearable sensors for dynamic premium adjustments.
- Quarter Horse:Western performance and ranch work breeds with mortality coverage focused on working value rather than bloodstock appreciation.
- Pony:Companion and youth competition animals with lower insured values but higher policy count density.
Thoroughbred dominates premium pool concentration; Warmblood is gaining share fastest on surgical rider attachment.
Client Category:
Loss adjustment complexity and documentation compliance burdens vary sharply across owner-operator profiles.
- Private Owners:Individual companion and amateur sport horse keepers forming the policy volume base. Selection criteria increasingly favor direct veterinary payment network breadth over premium price alone.
- Breeders:Commercial reproduction operations with herd-level coverage and foal mortality exposure. The EU's Animal Health Law mandates traceable welfare documentation that embeds as coverage conditions, with Irish Thoroughbred operations facing steepest adaptation burden.
- Competitors:Professional riders with loss-of-use criticality and international transport coverage needs. Time constraints drive preference for point-of-service claim settlement.
- Trainers:Commercial conditioning operations with liability concentration and multiple-horse fleet coverage. Generate disproportionate loss-adjustment complexity relative to premium contribution.
Private Owners provide the count foundation; Competitors are expanding most quickly on value per policy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Horse insurance consumption patterns diverge sharply by geography. The United States concentrates mortality coverage around Thoroughbred bloodstock corridors. European markets emphasize welfare compliance and surgical riders. Ireland anchors transnational breeding documentation standards.
United States
Kentucky's Bluegrass region and Florida's Ocala corridor drive mortality premium concentration for racing and breeding operations. State insurance commissioners enforce NAIC model laws on equine policy disclosures. Veterinary capacity constraints in Lexington force telemedicine protocol embedding into standard coverage terms.
Ireland
County Kildare breeding operations generate disproportionate policy complexity under EU Animal Health Law welfare documentation mandates. The national agricultural regulator embeds traceable health passport requirements as coverage conditions. Thoroughbred exporters face extended onboarding timelines without existing digital documentation infrastructure.
United Kingdom
Private owner segments in England and Wales select carriers based on direct veterinary payment network breadth. The Financial Conduct Authority scrutinizes policy transparency under consumer duty rules. Consolidated veterinary practice groups in Surrey and Gloucestershire enable streamlined billing integration for point-of-service claim settlement.
Germany
High-value Warmblood owners in Lower Saxony and North Rhine-Westphalia submit continuous biometric data through wearable sensors. The national financial supervisory authority oversees pet and equine insurance product standards. Hanover's dressage concentration accelerates premium growth in surgical rider segments.
Netherlands
Show jumping disciplines in Limburg and North Brabant drive medical expense coverage expansion. The Dutch central bank regulates insurer solvency for specialty livestock underwriting. Equestrian clusters around 's-Hertogenbosch anchor demand for dynamic premium adjustment protocols based on real-time health monitoring.
Horse Insurance Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in horse insurance market structure. American Equine Insurance Group and Petplan Equine occupy positions with scale advantages in mortality underwriting and direct payment networks respectively. Blue Bridle Insurance exemplifies the focused specialist archetype anchoring competitive position through surgical coverage concentration. Competitive moves concentrate on telemedicine protocol development and veterinary clinic billing integration rather than traditional geographic expansion.
Among US-based underwriters, American Equine Insurance Group represents the integrated mortality leader archetype. Blue Bridle Insurance occupies the high-value surgical specialist position. Petplan Equine exemplifies the direct payment network innovator within UK and Irish market penetration. These three anchors illustrate how talent migration from general livestock pools into dedicated equine teams separates tier-one underwriting capacity from commodity competitors.
| Leading Market Players |
|---|
| American Equine Insurance Group |
| Agria Pet Insurance |
| Blue Bridle Insurance |
| Berkley Equine and Cattle |
| Kay Cassell Equine Insurance |
| ASPCA Horse Insurance |
| Petplan Equine |
| Equisure |
| Broadstone Equine Insurance |
| Others |
Supply & Pricing Matrix
Telemedicine triage protocols displacing traditional veterinary examinations are restructuring supply geography toward remote diagnostics platforms while simultaneously compressing pricing premiums for mortality coverage in Kentucky and Ireland. This substitution dynamic concentrates underwriting capacity in technology-enabled carriers and fragments pricing power among legacy exam-dependent incumbents.
Pricing Analysis
Long-term mortality contracts with agreed-value valuation protocols dominate Thoroughbred bloodstock segments, while spot-priced surgical riders attach to medical coverage for Warmblood disciplines. Price differentiation separates mortality coverage with telemedicine-enabled dynamic adjustments from standard veterinary-exam-dependent policies. Cost compression in medical riders is intensifying because veterinary capacity constraints in Lexington and Kildare force premium repricing. Private owners exhibit highest price sensitivity, selecting carriers based on direct payment network breadth rather than premium levels, while high-value competitors prioritize claim settlement speed over cost.
Supply Chain Analysis
Veterinary capacity chokepoints in Kentucky's Bluegrass region and Ireland's County Kildare constrain claims servicing geography and force telemedicine protocol embedding. Underwriting capacity draws from specialized equine veterinary actuaries migrating from general livestock pools, with talent concentration in American Equine Insurance Group and Petplan Equine operations. Single-source vulnerability in accredited equine hospital networks creates regional service gaps for remote policyholders. Distribution runs through broker intermediaries with veterinary clinic billing integration capturing preference among professional trainers and competitors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Horse insurance operates as a defensive-moat market where regulatory entrenchment through EU Animal Health Law compliance documentation creates switching costs that embed carriers within breeding operations. Network effects in direct veterinary payment systems compound this structural advantage.
For Market Incumbents: Compound underwriting capacity advantages by acquiring specialized equine veterinary actuary teams from general livestock pools before competitors secure talent. Embed telemedicine protocols as standard coverage terms to defend against technology-enabled entrants threatening mortality pricing premiums. Extend digital health passport infrastructure to capture EU Animal Health Law compliance burdens as a retention mechanism for Irish Thoroughbred breeding operations.
For New Entrants and Emerging Players: Anchor in direct veterinary payment network gaps among consolidated practice groups in UK counties lacking streamlined billing integration. Target private owner segments in Germany and the Netherlands where wearable biometric submission protocols remain underpenetrated among mid-value Warmblood keepers. Pursue white-label telemedicine platform partnerships with veterinary clinic chains to bypass incumbent broker networks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed veterinary practice consolidators seeking captive insurance distribution channels across Surrey and Gloucestershire clusters. Five-to-ten year viability hinges on telemedicine protocol standardization and regulatory documentation automation. Monitor biometric data submission penetration rates in Hanover dressage concentrations as inflection indicator for dynamic pricing model adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Protocol Integration | Remote diagnostics embedding enables real-time mortality risk assessment and premium adjustments for Kentucky bloodstock. |
| Direct Veterinary Payment Network Expansion | Point-of-service claim settlement captures loyalty among time-constrained professional trainers in UK consolidated practice clusters. |
| Digital Health Passport Infrastructure | EU Animal Health Law compliance verification embeds coverage conditions and extends onboarding timelines for Irish exporters. |
| Specialized Actuary Team Acquisition | Equine veterinary talent migration from general livestock pools concentrates underwriting capacity in dedicated mortality teams. |
| Wearable Biometric Platform Partnership | Continuous health monitoring data submission enables dynamic premium adjustments for high-value Warmblood owners in Germany. |
Research Methodology
Desk research of regulatory filings from NAIC state insurance commissioners and EU Animal Health Law documentation preceded structured interviews with equine insurance underwriters, veterinary clinic network managers, and Thoroughbred breeding operation risk managers. Secondary validation drew from bloodstock valuation databases, veterinary capacity reports for Kentucky and Kildare regions, and FCA consumer duty transparency assessments. Bottom-up policy issuance data triangulated against top-down premium pool estimates across mortality, medical, and liability coverage segments.
Variance decomposition across policy type, equine discipline, and client category dimensions shaped analytical framework construction over the projection horizon. CAGRs derived from premium growth trajectories in surgical riders and telemedicine-enabled mortality coverage, with inputs from veterinary cost inflation indices and regional hospital capacity constraints. Modeled outputs incorporated bloodstock valuation methodology disputes and climate-driven disease vector expansion as structural uncertainty factors.
Underlying assumptions cover sustained veterinary cost inflation and regulatory documentation mandate enforcement, with deviation risk concentrated in telemedicine protocol adoption rates and biometric data submission penetration among Warmblood owners. Practitioners should keep alternative scenarios live as EU Animal Health Law implementation timelines and veterinary capacity expansion in Kentucky evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Digital Insurance Market
Insurance
Marine Freight Insurance Market
Insurance
Data Analytics in Insurance Market
Insurance
Business Travel Insurance Market
Insurance
Social Media Analytics-Based Insurance Market
Insurance
United States Bancassurance Market
Insurance
Asia-Pacific Family Floater Health Insurance Market
Insurance
Musical Instrument Insurance Market
Insurance
Boiler Insurance Market
Insurance
B2B2C Insurance Market
Insurance
South Africa Property and Casualty Insurance Market
Insurance
Event Insurance Market
Insurance
UK Cyber (Liability) Insurance Market
Insurance
Drone Insurance Market
Insurance
Canada Health and Medical Insurance Market
Insurance
Germany Reinsurance Market